
 Fruit Beverages Market | 2026-2036
Fruit Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Beverages Market Analysis
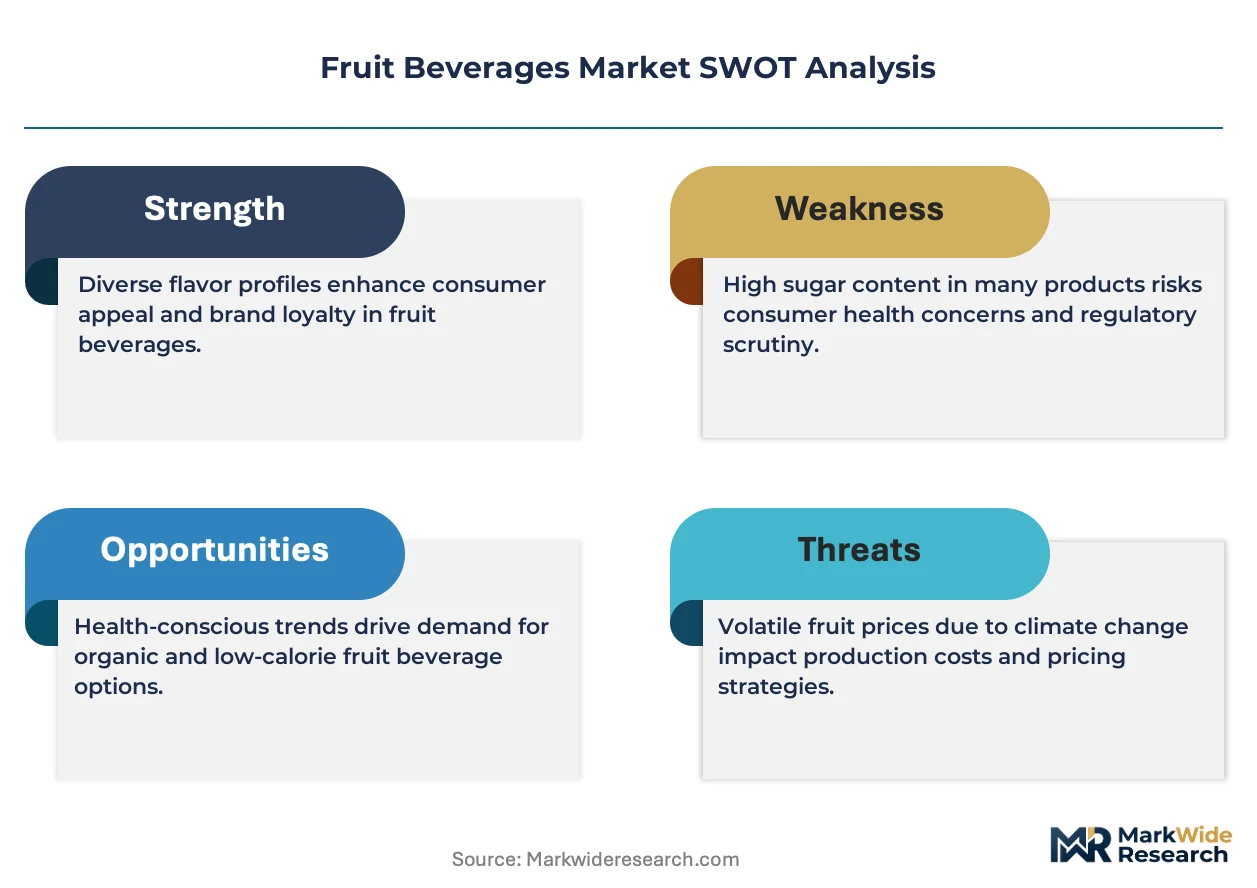
EU F-Gas Regulation is repositioning cold-chain economics for aseptic fruit juice processing. Coca-Cola Company leverages captive concentrate sourcing across multiple climate zones to buffer raw material volatility. The Wonderful Company anchors its margin structure through integrated pomegranate orchards in California's Central Valley. Döhler Group competes on formulation technology leadership for reduced-sugar nectar applications.
Fruit beverages comprise aqueous extracts, purees, or suspensions derived from edible fruits, typically standardized to specific Brix levels and pasteurized for shelf stability. The category serves commercial refreshment, nutritional supplementation, and ingredient supply functions across retail and food manufacturing channels. Juice maintains the largest revenue footprint among product types, though smoothie formulations command premium positioning in urban supermarkets. Nectar segments face margin compression from sugar-content reformulation mandates, while concentrate volumes track food-service procurement cycles closely.
FDA juice HACCP rules, EU MDR-adjacent food contact material standards, and BIS certification requirements for packaged beverages collectively shape formulation compliance costs and cross-border market access protocols. These frameworks elevate testing expenditure for new entrants while rewarding incumbents with established laboratory infrastructure. Stakeholders must calibrate portfolio renovation speed against diverging regional sweetener and labeling thresholds.
Market Dynamics
The EU's Farm to Fork Strategy is tightening permissible additive thresholds while Brazil's São Paulo corridor concentrates tropical fruit processing capacity. Cold-chain economics are repositioning under F-Gas Regulation compliance costs. Health-conscious retail consumers are shifting toward no-added-sugar formulations across multiple climate zones.
Growth Catalysts
- EU Green Deal alignment:The Farm to Fork Strategy mandates sugar-content reductions that accelerate clean-label innovation. Reformulation investment is concentrating in facilities serving German and French retail channels.
- Aseptic processing advancement:Cold-chain infrastructure upgrades under F-Gas Regulation compliance are enabling extended shelf-life products. Food-service procurement cycles are expanding concentrate volumes.
- Brazil's processing corridor:Tropical fruit clusters in São Paulo state are scaling puree and suspension capacity. Integrated orchard-to-bottle operations are compressing logistics expenditure.
Market Restraints
- Input cost volatility:Concentrate sourcing across multiple climate zones exposes margins to weather-driven raw material swings. Pomegranate and tropical fruit harvest variability is particularly acute.
- Regulatory friction:FDA juice HACCP rules and EU MDR-adjacent food contact standards elevate testing expenditure. New entrants face laboratory infrastructure barriers that reward established compliance systems.
- Substitution threat:Flavored functional waters and plant-based milk alternatives are capturing refreshment occasions. Nectar segments face particular displacement pressure in urban supermarkets.
Strategic Opportunities
- Reduced-sugar formulation white space:Clean-label nectar applications command premium positioning where Brix standardization meets natural sweetness. Technology licensing for enzyme-based sugar reduction is expanding.
- India BIS certification pathway:Packaged beverage standards create first-mover advantage for compliant exporters. Domestic cold-chain gaps present partnership openings for aseptic technology providers.
- Smoothie channel innovation:Urban supermarket premium positioning is shifting toward grab-and-go formats. On-premise blending equipment is creating new food-service attachment points.
Industry Challenges
- Reformulation talent scarcity:Food chemists specializing in natural sweetener systems and stability testing are in short supply. Compensation inflation is compressing R&D budgets.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and BIS approval processes extend product launch windows. Divergent labeling thresholds require portfolio fragmentation.
- Legacy pasteurization asset stranding:High-temperature short-time systems face displacement by aseptic cold-fill alternatives. Retooling decisions are complicated by residual book values.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Beverages Market |
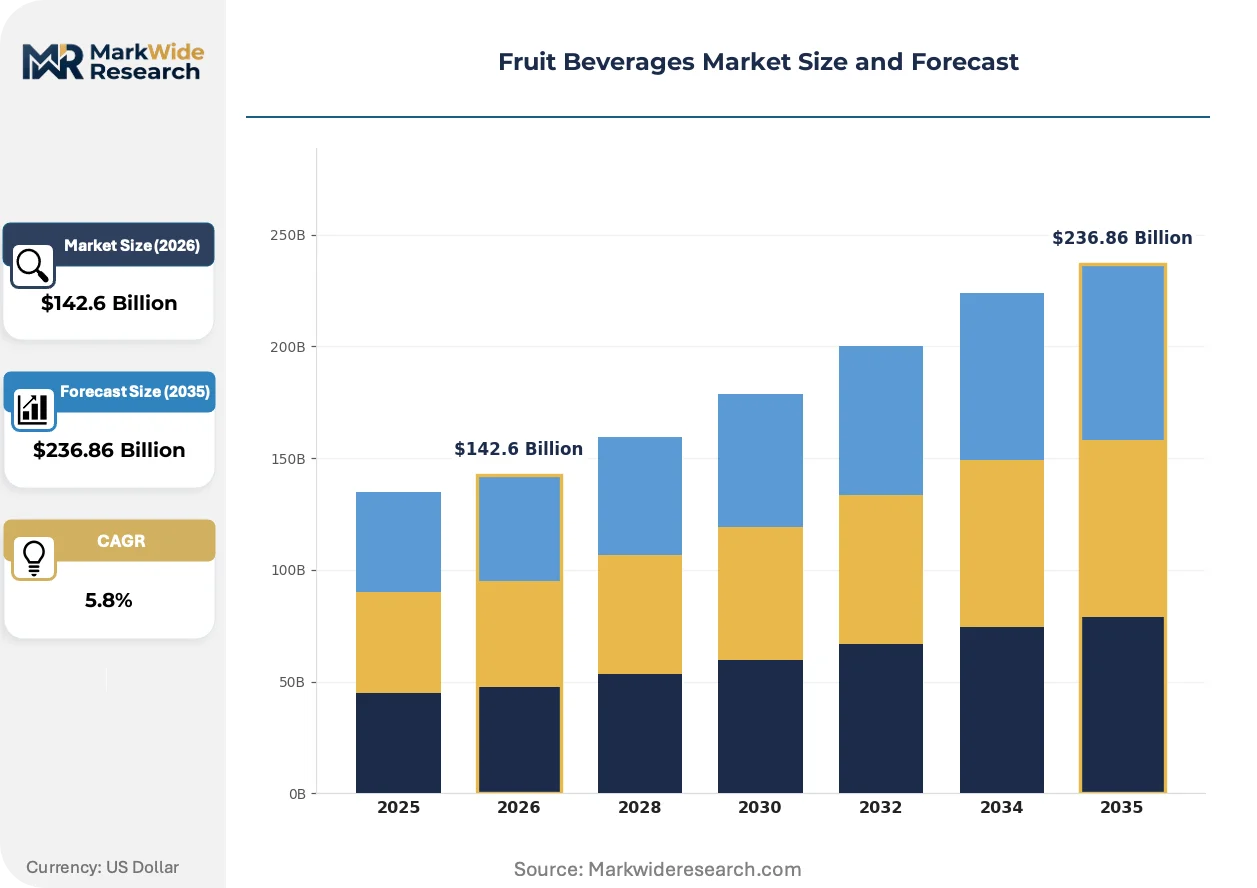
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $236.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juice, Nectar, Smoothie, Concentrate End User: Retail Consumers, Food Service, Catering, Institutions Packaging Type: Bottles, Cans, Cartons, Pouches Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Wholesalers |
| Companies Covered | Tropicana Products, Döhler Group, Coca-Cola Company, The Wonderful Company, Welch Foods, PepsiCo, Ocean Spray, Tree Top, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Beverages Market Emerging Trajectories
High-pressure processing is electrifying preservation economics while regulatory convergence around sugar disclosure is rewriting formulation priorities. Channel fragmentation between direct-to-consumer subscription models and automated retail is redrawing distribution maps.
Pulsed electric field technology is electrifying microbial inactivation at ambient temperatures. Premium smoothie brands in California and Germany are adopting PEF systems to preserve heat-sensitive vitamins and enzymes. This shift is compressing energy expenditure relative to thermal pasteurization while extending clean-label claims.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants across cold-chain infrastructure. Aseptic juice processors in Italy and Spain are retrofitting facilities with natural refrigerant systems. Nectar and concentrate segments face disproportionate capex burdens where temperature-controlled storage dominates cost structures.
Urban consumers are fragmenting their beverage occasions across functional, indulgent, and hydration states. Subscription smoothie delivery in London and New York is displacing conventional supermarket bulk purchasing. This pattern is most visible among millennial and Gen-Z demographics with premium willingness-to-pay thresholds.
Fruit Beverages Market Segmentation
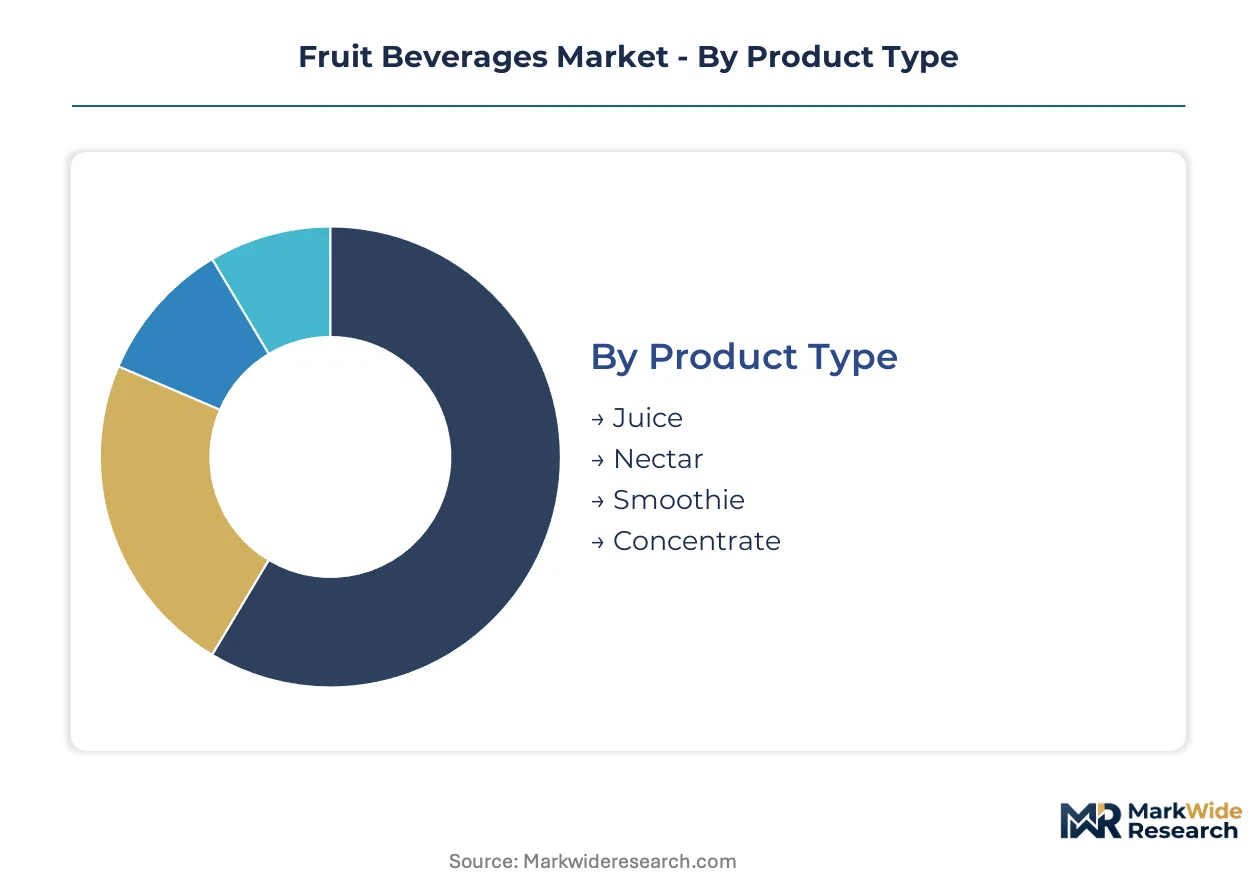
Fruit beverage segmentation reveals distinct margin profiles across formulation intensity and channel access. Product architecture determines cold-chain requirements, while packaging and distribution choices shape working capital intensity and geographic reach.
Product Type:
Standalone consumption formats compete against embedded ingredient systems for food manufacturing applications.
- Juice:Aqueous extracts standardized to specific Brix levels and pasteurized for ambient shelf stability. Demand concentrates in German and French retail channels where the EU Farm to Fork Strategy's sugar reduction mandates are accelerating clean-label reformulation investment.
- Smoothie:Fruit puree suspensions with intact fiber matrices, typically high-pressure processed to preserve enzyme activity. Urban supermarkets in London and New York are displacing conventional bulk purchasing through subscription delivery models targeting millennial demographics.
- Nectar:Diluted fruit bases with restored pulp content, facing margin compression from sugar-content reformulation mandates.
- Concentrate:Volume-reduced extracts for food-service reconstitution, tracking procurement cycles closely.
Juice leads volumes today; smoothie is gaining share fastest.
End User:
Cost tier stratification separates premium direct-to-consumer positioning from bulk institutional supply contracts.
- Retail Consumers:Individual purchasers through supermarkets and online channels, commanding highest per-unit margins. No-added-sugar formulations are shifting health-conscious demand toward premium price bands in São Paulo corridor supermarkets.
- Food Service:Restaurants, cafes, and hospitality operators procuring concentrate and ready-to-serve formats. Aseptic processing advancement under F-Gas Regulation compliance is extending shelf-life for ambient distribution to smaller operators.
- Catering:Event and contract food providers with volume procurement and seasonal demand spikes.
- Institutions:Schools, hospitals, and corporate cafeterias with standardized nutritional specifications and bid-based purchasing.
Retail consumers anchor revenue contribution; food service is climbing the fastest.
Packaging Type:
Application requirements dictate barrier properties, with aseptic cold-fill formats displacing legacy pasteurization systems.
- Bottles:PET and glass formats for premium juice and smoothie positioning. Pulsed electric field technology adoption in California and Germany is preserving heat-sensitive vitamins while enabling extended ambient distribution.
- Cartons:Aseptic brick packs for ambient-stable juice and nectar, dominating Brazilian tropical fruit exports.
- Cans:Aluminum formats for on-premise and convenience channel refreshment occasions.
- Pouches:Flexible formats for children's portions and food-service portion control.
Cartons dominate export volumes; bottles show steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation separates planned pantry stocking from impulse refreshment purchasing.
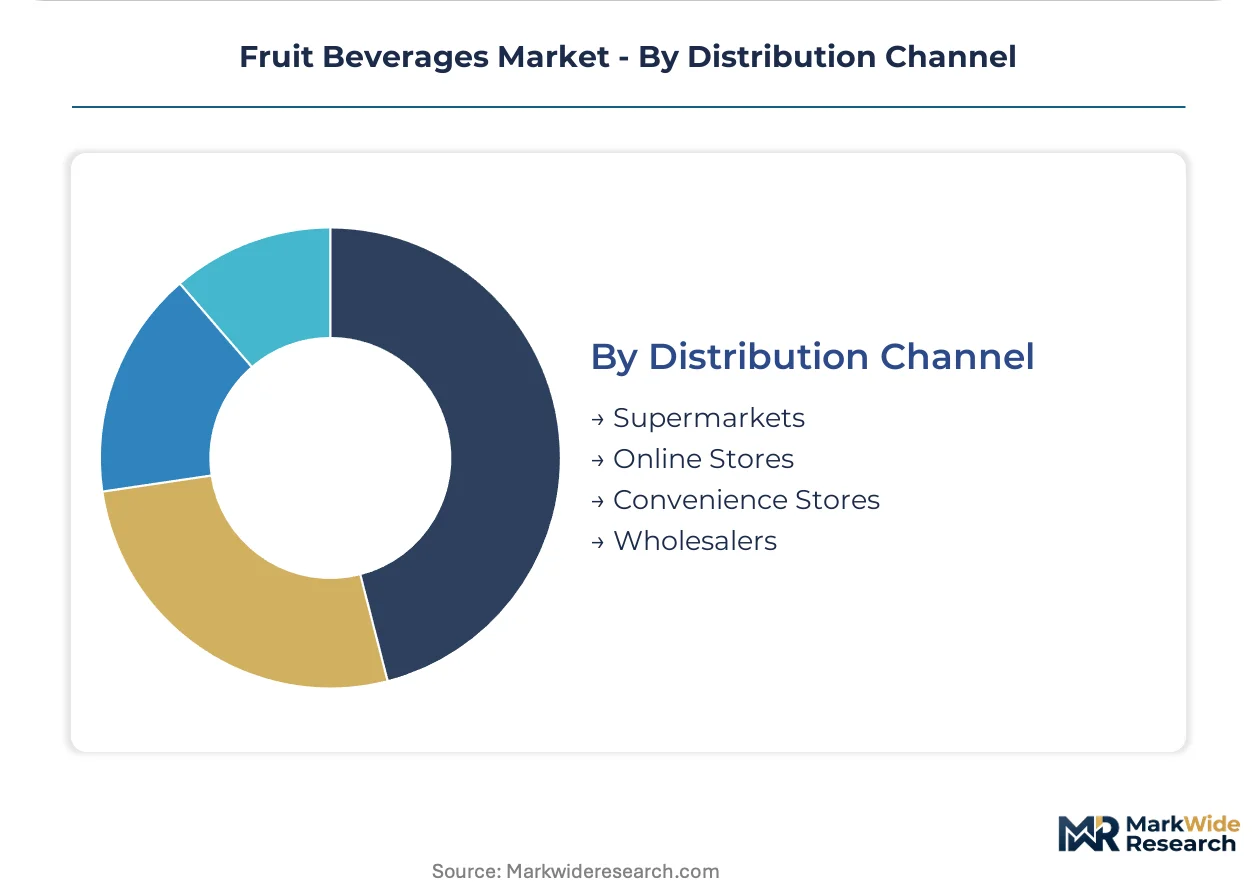
- Supermarkets:Planned purchase environment with premium-mid-economy pricing differentiation across shelf positioning. EU Green Deal alignment is concentrating reformulation investment in facilities serving German and French retail channels.
- Online Stores:Direct-to-consumer subscription models with cold-chain last-mile requirements. Subscription smoothie delivery is creating new attachment points for on-premise blending equipment.
- Convenience Stores:Impulse channel for single-serve formats with higher per-unit pricing.
- Wholesalers:Bulk distribution to food service, catering, and institutional accounts with negotiated contract terms.
Supermarkets retain volume leadership; online stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food chemists specializing in natural sweetener systems anchor the competitive workforce in Germany and California, while tropical fruit processing talent clusters in São Paulo state and Southeast Asian export hubs.
Germany
Clean-label reformulation investment concentrates in facilities serving German retail channels where EU Farm to Fork Strategy mandates accelerate sugar-content reductions. EFSA labeling thresholds and BfR food contact material standards elevate testing expenditure for new entrants. The Rhine-Main corridor hosts multiple aseptic processing technology providers retrofitting cold-chain infrastructure under F-Gas Regulation compliance.
Brazil
Tropical fruit puree and suspension capacity scales in São Paulo state as integrated orchard-to-bottle operations compress logistics expenditure. ANVISA packaged beverage standards create certification barriers that reward established laboratory infrastructure. The São Paulo corridor concentrates processing clusters serving export markets with aseptic carton formats dominating shipment volumes.
United States
Premium smoothie brands in California adopt pulsed electric field systems to preserve heat-sensitive vitamins while extending clean-label claims. FDA juice HACCP rules and EPA F-Gas phase-down timelines reposition cold-chain economics for aseptic processors. The Central Valley anchors captive pomegranate orchard operations that buffer raw material volatility through backward integration.
India
Domestic cold-chain gaps present partnership openings for aseptic technology providers as BIS certification requirements for packaged beverages create first-mover advantage for compliant exporters. FSSAI food safety standards and state-level agricultural marketing board programs shape procurement patterns. Maharashtra and Karnataka concentrate emerging processing capacity for tropical fruit nectars targeting urban supermarket channels.
France
Reformulation investment serving French retail channels accelerates under EU Green Deal alignment with sugar-reduction mandates driving clean-label nectar innovation. ANSM-adjacent food contact oversight and DGCCRF market surveillance elevate compliance costs. The Île-de-France region hosts headquarters operations for multiple beverage formulation technology licensors.
Fruit Beverages Market Vendor Landscape
The competitive structure tilts toward integrated orchard operators and formulation technology specialists rather than pure-brand marketers. Tiered concentration separates multinational concentrate sourcers from regional puree processors and niche clean-label innovators. Three archetypes dominate: captive agricultural integrators, aseptic processing technology licensors, and multi-climate concentrate blenders. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players reposition under regulatory compliance cost pressures.
Among captive agricultural integrators, The Wonderful Company and Tropicana Products exemplify backward integration strategies that buffer margin exposure to harvest variability. The Döhler Group occupies a position within the formulation technology tier, representing specialists that compete on reduced-sugar application development rather than brand equity. These three anchors illustrate how competitive positioning diverges between agricultural asset control and intellectual property licensing in a market where input cost volatility and regulatory fragmentation simultaneously reshape strategic priorities.
| Leading Market Players |
|---|
| Tropicana Products |
| Döhler Group |
| Coca-Cola Company |
| The Wonderful Company |
| Welch Foods |
| PepsiCo |
| Ocean Spray |
| Tree Top |
| Keurig Dr Pepper |
| Others |
Supply Flow & Price Mechanics
EU Farm to Fork Strategy sugar-reduction mandates are forcing reformulation investments that compress nectar margins while premium smoothie tiers capture willingness-to-pay for intact-fiber positioning. Supply response concentrates in German and French retail-serving facilities where clean-label certification costs feed into three-tier pricing stratification.
Pricing Analysis
Bundled orchard-to-bottle operations command premium positioning against unbundled concentrate sourcing models. Three-tier pricing structure across premium, standard, and economy levels separates aseptic cold-fill smoothie formats from heat-pasteurized juice and private-label nectar. Cost compression in mid-tier nectar segments is intensifying because sugar-content reformulation requires enzyme-based sweetness restoration. Food-service concentrate buyers exhibit highest price sensitivity; direct-to-consumer subscription smoothie purchasers show lowest.
Supply Chain Analysis
Domestic-content mandates in India's BIS certification pathway and Brazil's ANVISA standards are reshaping sourcing toward integrated local processing. Raw material flows center on São Paulo state tropical fruit clusters, California Central Valley pomegranate operations, and Southeast Asian puree export hubs. Pomegranate and tropical fruit harvest variability creates single-source vulnerability for non-integrated processors. Distribution runs through aseptic carton bulk export for concentrate, cold-chain last-mile for subscription smoothie delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fruit beverages rests on reformulation technology licensing fees and captive orchard throughput efficiency. Premium-tier shift toward high-pressure processed smoothie formats widens spreads against commodity juice.
For Market Incumbents: Anchor margin structure through backward integration into orchard operations that buffer harvest variability, as The Wonderful Company demonstrates in California. Accelerate aseptic cold-fill capacity additions in São Paulo corridor facilities to capture Brazilian export growth. Defend against substitution threat from functional waters by locking urban supermarket premium shelf positioning.
For New Entrants and Emerging Players: Begin with India BIS certification pathway where domestic cold-chain gaps create partnership openings for aseptic technology providers. Target reduced-sugar nectar white space in German and French retail channels where EU Green Deal alignment accelerates clean-label demand. Pursue direct-to-consumer subscription model with on-premise blending equipment attachment.
For Investors and Strategic Acquirers: Asymmetric upside sits with formulation technology specialists holding enzyme-based sugar reduction IP. Five-to-ten year viability favors licensors over brand-dependent marketers as regulatory fragmentation persists. Watch F-Gas Regulation compliance capex burdens as inflection indicator for facility acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captive pomegranate supply in California's Central Valley buffers raw material volatility. |
| Aseptic Cold-Fill Capacity Expansion | São Paulo corridor facilities capture Brazilian tropical fruit export growth under ANVISA standards. |
| Enzyme-Based Sugar Reduction Licensing | Döhler Group technology leadership commands premium fees for clean-label nectar reformulation. |
| Direct-to-Consumer Subscription Launch | London and New York urban millennial targeting displaces conventional supermarket bulk purchasing. |
| BIS Certification Compliance Investment | First-mover advantage in India packaged beverage standards rewards established laboratory infrastructure. |
Methodological Framework
Direct dialogue with fruit beverage plant managers, retail category buyers, food-service procurement directors, and formulation technology R&D leads grounded qualitative findings. Secondary validation drew from FDA juice HACCP filings, EU F-Gas Regulation implementation reports, ANVISA packaged beverage standards, and BIS certification documentation. Bottom-up facility capacity assessments and top-down retail channel revenue estimates were triangulated.
Top-down macroeconomic drivers and bottom-up segment-level volume builds converged across the analysis window. Segmentation dimensions modeled include product type, end-user tier, packaging format, and distribution channel. CAGRs were derived from slope analysis of historical trajectory and forward projection of regulatory compliance cost absorption. Forecast inputs incorporated EU Farm to Fork Strategy implementation pace and F-Gas Regulation cold-chain retrofit timelines.
Caveats apply where harvest volatility, regulatory timeline slippage, or substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about reformulation technology adoption curves and certification pathway completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Botanical Infused Beverages Market
Beverages
Commercial Drink Mixers Market
Beverages
NFC JUICE Market
Beverages
Europe Bottled Water Processing Market
Beverages
North America Yerba Mate Market
Beverages
GCC Fruit Juice Market
Beverages
Apple Cider Vinegar Market
Beverages
Semillon Market
Beverages
Morocco Bottled Water Market
Beverages
Global Squash Drinks Market
Beverages
India Cafes & Bars Market
Beverages
GCC Coconut Water Market
Beverages
Plant-Based Energy Drink Market
Beverages
Relaxation Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
Soft Serve Premix Market