
 Carbonated Soft Drinks Market | 2026-2036
Carbonated Soft Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonated Soft Drinks Market Intelligence
Direct-to-consumer subscription models are shifting the traditional retail purchase dynamic for carbonated soft drinks. This channel allows brands to bypass conventional retail gatekeepers and build direct customer relationships. The Coca-Cola Company leverages its extensive global distribution network to maintain market presence across all channels. In contrast, PepsiCo competes through a diversified portfolio that includes both beverages and snack foods, creating significant cross-promotional opportunities.
Carbonated soft drinks are non-alcoholic beverages containing dissolved carbon dioxide gas, which creates effervescence. These drinks are typically composed of water, a sweetener such as sucrose or a high-intensity alternative, and natural or artificial flavorings to provide refreshment. The cola segment remains a mature and dominant category by volume, though flavor innovation in areas like ginger ale and orange is gaining traction. While supermarkets and convenience stores command the largest share of distribution, online retailers represent the fastest-growing channel for consumer purchases.
Regulatory frameworks increasingly influence product formulation and marketing. In the United States, the FDA mandates strict nutritional labeling, while Europe's EFSA scrutinizes sweeteners and additives. Similarly, India's FSSAI has implemented standards regarding sugar content and advertising to children, shaping market access. Key strategic decisions for manufacturers will revolve around balancing consumer demand for traditional flavors with the need for healthier, lower-sugar product innovations.
Market Dynamics
The fundamental dynamic shaping the carbonated soft drinks market is the conflict between consumer demand for indulgent, traditional flavors and mounting public health pressure, particularly through sugar taxation policies, which mandates product reformulation toward lower-calorie alternatives.
Growth Catalysts
- Flavor Innovation:Sophisticated flavor profiles like botanical-infused ginger ale and artisanal orange sodas attract adult consumers, supporting premiumization in mature economies.
- Foodservice Channel Growth:Expansion within fast-casual restaurants creates a key channel for introducing customized beverages and driving trial for new formulations.
- Demographics in Brazil:The country's large, youthful consumer base provides a significant source of demand for traditional cola and fruit-flavored soft drinks.
Market Restraints
- Sugar Taxation:Taxes on sweetened beverages in markets like the United Kingdom and Mexico increase consumer prices, depressing volume for traditional full-sugar products.
- Input Cost Volatility:Price fluctuations for commodities like aluminum and sweeteners create margin pressure and complicate financial planning for manufacturers.
- Competition from Substitutes:Healthier beverage categories, including functional waters and ready-to-drink teas, compete for consumer share by appealing to wellness trends.
Strategic Opportunities
- Direct-to-Consumer Channels:Subscription models allow brands to bypass retail gatekeepers, build direct customer relationships, and gather data on consumption patterns.
- Functional Formulations:Incorporating ingredients like vitamins or nootropics into carbonated drinks creates a hybrid category that appeals to health-oriented consumers.
- Southeast Asia Expansion:Markets in Vietnam and Indonesia offer significant growth potential, driven by a rising middle class and an appetite for novel beverages.
Industry Challenges
- Supply Chain Complexity:SKU proliferation from flavor diversification demands more agile supply chains, increasing logistical costs and inventory management challenges.
- Divergent Regulations:Navigating disparate labeling rules from regulators like the US FDA and Europe's EFSA complicates global product launches and adds compliance overhead.
- Brand Messaging:Promoting lower-sugar reformulations without alienating a core consumer base loyal to original taste profiles presents a significant marketing hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonated Soft Drinks Market |
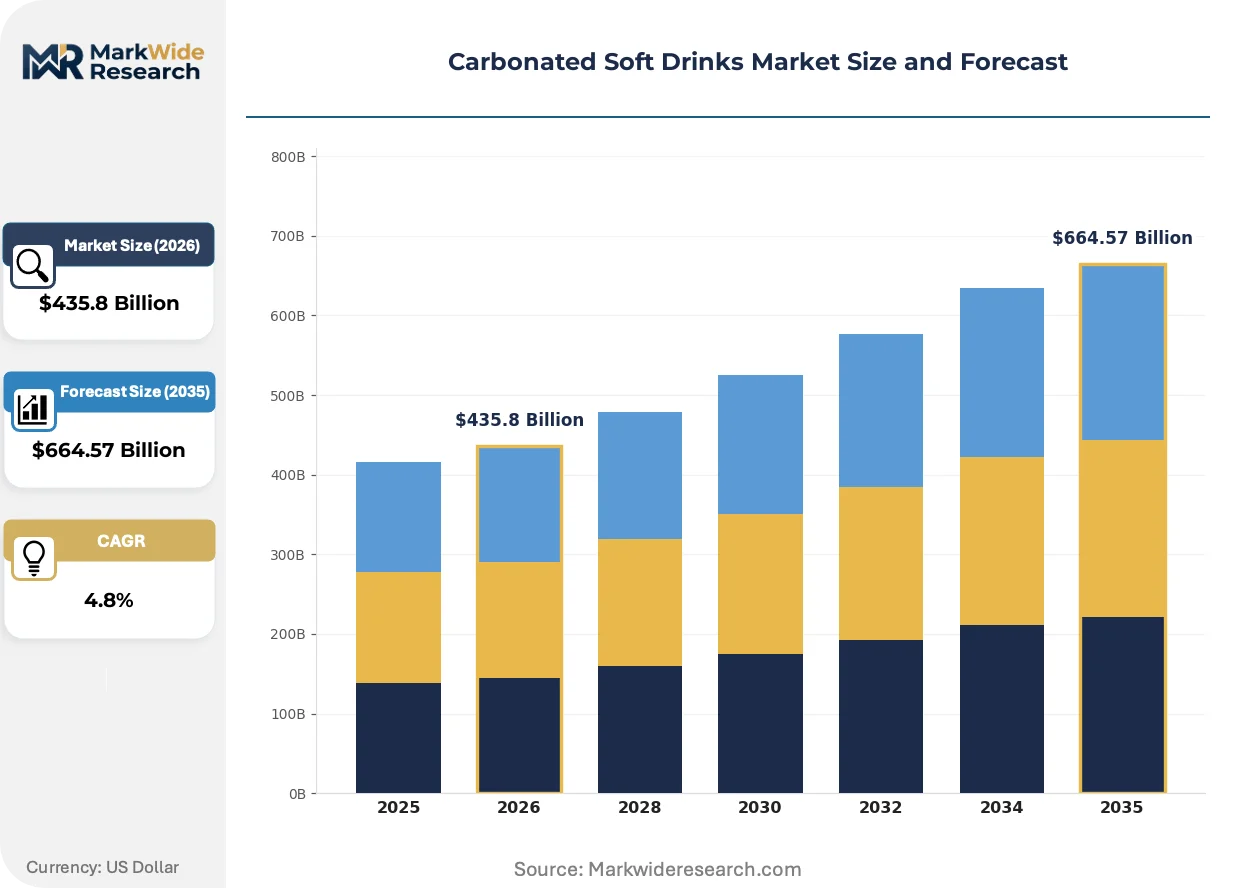
| Market Size in 2026 | $435.8 Billion |
| Market Size in 2035 | $664.57 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cola, Lemon-Lime, Root Beer, Ginger Ale, Orange, Tonic Water Packaging Type: Bottle, Can, Carton, PET, Glass Bottle, Box Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines, Foodservice Outlets, Specialty Stores End User: Restaurants, Cafes, Hotels, Institutions, Entertainment Venues, Retail Consumers |
| Companies Covered | Suntory Holdings, Nongfu Spring, The Coca-Cola Company, Monster Beverage, Yili Group, PepsiCo, Refresco Group, Red Bull, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonated Soft Drinks Market Strategic Shifts & Innovations
Product development is reshaping around the concept of permissible indulgence. This involves leveraging formulation science to deliver healthier beverage options that do not compromise on the taste and refreshment consumers expect from traditional carbonated soft drinks.
Advanced sugar reduction technology, including high-intensity sweeteners and enzymatic modification, provides the core mechanism for lowering calorie content. Beverage formulators are rapidly adopting these tools to meet new regulatory standards and shifting consumer preferences. This formulation capability is expanding into iconic, full-sugar product lines, enabling the launch of zero-sugar or reduced-sugar flankers that maintain brand equity.
Regulatory frameworks targeting marketing are becoming more stringent, as seen with India's FSSAI standards that restrict advertising to children. This policy directly impacts media planning and promotional strategies for brands with high youth appeal. Consequently, the cola and sweetened fruit soda segments are most affected, forcing a pivot in marketing campaigns toward adult consumers and family-oriented occasions.
Consumer behavior is shifting toward a preference for customization, particularly within foodservice environments. This trend disrupts the traditional pre-packaged retail model, as interactive fountain machines offering flavor shots and adjustable carbonation levels gain traction. This demand for personalized beverages is most prominent in quick-service restaurants and cinema chains across North America and parts of Europe.
Carbonated Soft Drinks Market Segmentation
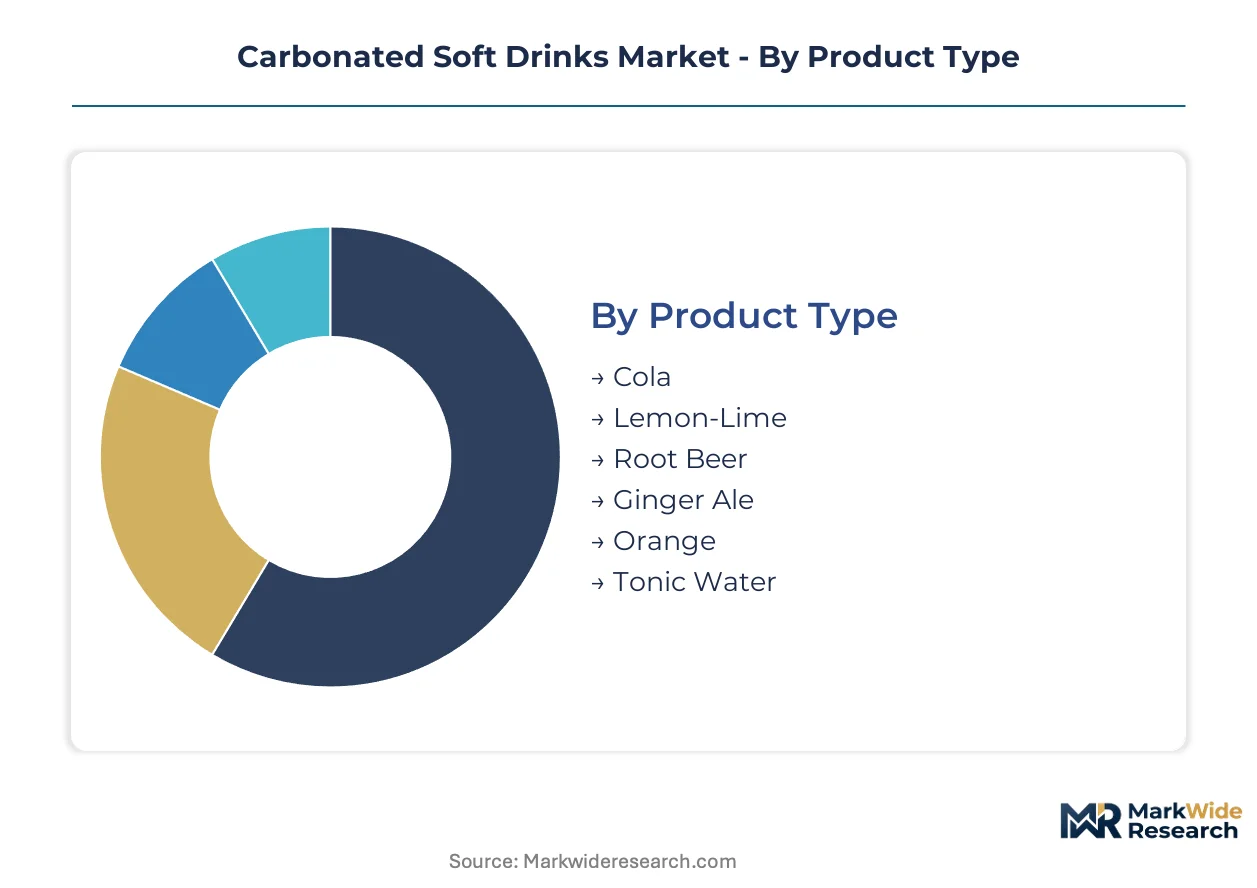
Understanding the Carbonated Soft Drinks Market's segmentation provides clarity on consumer preferences and operational dynamics. Manufacturers tailor products and distribution strategies to meet diverse demands across various categories. This granular view helps stakeholders identify growth pockets and optimize resource allocation.
Product Type:
Consumer choice in carbonated soft drinks is primarily driven by taste preference and established brand loyalty, which strongly influences product type selection.
- Cola:This segment encompasses beverages characterized by their distinctive caramel color and flavor, often derived from kola nuts and other spices. Demand remains concentrated in Brazil due to a large youthful demographic, favoring traditional and full-sugar formulations.
- Ginger Ale:Ginger ale features a carbonated beverage flavored with ginger, offering a spicier, often more sophisticated profile than traditional sodas. Flavor innovation, including botanical infusions, attracts adult consumers in mature economies like the United States and Europe.
- Lemon-Lime:This category includes clear, citrus-flavored sodas offering a crisp and refreshing taste, popular across all age groups.
- Root Beer:Root beer is a sweet, carbonated beverage traditionally flavored with sassafras root bark, enjoying niche popularity in North America.
- Orange:Orange sodas provide a sweet and tangy citrus profile, with flavor innovation gaining traction in markets like India and Southeast Asia.
- Tonic Water:Tonic water contains quinine, giving it a distinctive bitter taste, primarily consumed as a mixer for alcoholic beverages.
Cola leads on scale; ginger ale leads on momentum.
Packaging Type:
The choice of packaging type directly impacts supply chain logistics and cost efficiency for manufacturers.
- PET:PET (Polyethylene Terephthalate) bottles are lightweight, shatter-resistant plastic containers widely used for their cost-effectiveness and versatility. This packaging dominates retail shelves globally due to its convenience for both consumers and distributors.
- Can:Aluminum cans offer excellent barrier properties and are highly recyclable, providing a convenient and portable option for single-serve carbonated drinks. Demand for cans is particularly strong in entertainment venues and vending machines across Europe and North America.
- Bottle:This general category encompasses various rigid containers, often chosen for their resealability and perceived premium aesthetic.
- Carton:Carton packaging is less common for carbonated soft drinks due to pressure build-up, primarily used for still beverages or specific niche products.
- Glass Bottle:Glass bottles are favored for premium carbonated soft drinks, preserving taste integrity and offering a high-quality presentation, especially in foodservice.
- Box:Box packaging, often containing multiple cans or bottles, facilitates bulk purchases and convenient transport for retail consumers.
PET packaging captures significant volume; cans offer superior convenience for on-the-go consumption.
Distribution Channel:
Effective distribution channels are critical for ensuring product accessibility and maximizing market penetration across diverse consumer touchpoints.
- Supermarkets:Large retail chains provide extensive product selection and competitive pricing, making them the primary distribution channel for household purchases of carbonated soft drinks. These outlets command the largest share of distribution globally for packaged beverages.
- Online Retailers:E-commerce platforms offer unparalleled convenience for consumers, enabling direct-to-home delivery and subscription models for carbonated soft drinks. This channel represents the fastest-growing segment for consumer purchases, particularly in urban areas.
- Convenience Stores:These smaller retail formats cater to immediate consumption needs, offering quick access to single-serve carbonated drinks.
- Vending Machines:Automated vending machines provide instant access to chilled beverages in public spaces, offices, and entertainment venues.
- Foodservice Outlets:Restaurants and cafes integrate carbonated soft drinks into their menus, often offering customized beverage options and driving trial for new formulations.
- Specialty Stores:These niche retailers focus on imported or artisanal carbonated soft drinks, appealing to consumers seeking unique flavor profiles.
Supermarkets maintain high volume sales; online retailers are accelerating market expansion.
End User:
End-user segments define the consumption context for carbonated soft drinks, influencing product formats and marketing strategies.
- Retail Consumers:Individual consumers purchasing carbonated soft drinks for home consumption or personal immediate use form the largest end-user segment. This segment drives demand for diverse packaging sizes and flavor varieties available through retail channels.
- Restaurants:Foodservice establishments integrate carbonated soft drinks as a staple beverage offering, often through fountain systems that allow for customized drink options. This channel is pivotal for introducing new formulations and driving beverage trial.
- Cafes:Cafes offer carbonated soft drinks as part of their beverage menu, complementing coffee and snack offerings for patrons.
- Hotels:Hotels provide carbonated soft drinks through minibars, room service, and dining facilities, catering to guest refreshment needs.
- Institutions:Educational and healthcare institutions offer carbonated soft drinks in cafeterias and vending machines, serving a captive audience.
- Entertainment Venues:Theaters, stadiums, and concert halls are significant points of sale for carbonated soft drinks, catering to event attendees.
Retail consumers generate the highest sales volume; entertainment venues drive significant impulse purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Brazil's youthful population fuels demand for traditional carbonated soft drinks, the United Kingdom faces significant volume depression from sugar taxation policies. These divergent market pressures shape product development and marketing strategies across regions. Consumer preferences vary significantly by geography, impacting product formulation and distribution.
Brazil
Demand for traditional cola and fruit-flavored sodas remains strong among young consumers in Brazil. ANVISA regulations influence product labeling and ingredient use for local manufacturers. The São Paulo metropolitan area drives significant consumption volume for both established and emerging brands.
United States
Adult consumers seek sophisticated flavor profiles like botanical ginger ale and artisanal orange sodas. The US FDA mandates strict nutritional labeling on beverage products. New York City's diverse foodservice outlets serve as innovation hubs for customized drink options.
United Kingdom
Sugar taxation policies increase consumer prices, shifting demand towards lower-calorie alternatives. The EFSA provides guidelines for sweetener and additive use across the European market. London's urban centers show increased adoption of premium, reduced-sugar carbonated beverages.
India
Flavor innovation in orange sodas attracts a broad consumer base, particularly in urban areas. The FSSAI implements standards regarding sugar content and advertising to children. Mumbai's rapidly expanding retail sector supports new product launches and distribution.
Vietnam
A rising middle class and appetite for novel beverages drive significant growth potential for carbonated soft drinks. The country's national food safety regulator oversees ingredient and labeling compliance. Ho Chi Minh City's vibrant consumer market offers opportunities for new product entry.
Carbonated Soft Drinks Market Key Industry Players
Top-tier vendors anchor the global carbonated soft drinks market, while regional specialists and niche innovators carve out specific segments. The market structure exhibits a tiered consolidation, with a few multinational giants dominating volume. Key strategic archetypes include global beverage powerhouses, diversified food and beverage conglomerates, and specialized energy drink producers. These players engage in continuous portfolio diversification and geographic expansion to maintain market share.
Global beverage powerhouses like The Coca-Cola Company and PepsiCo exemplify broad market reach and extensive distribution networks across diverse geographies. These multinational corporations leverage their established brand portfolios to navigate evolving consumer preferences and stringent regulatory landscapes, often through significant reformulation efforts. Monster Beverage, in contrast, represents a specialized energy drink producer, focusing on a distinct consumer segment with targeted product offerings and marketing strategies. This differentiation highlights the varied approaches to market penetration, from mass-market dominance to niche specialization, reflecting the diverse consumer base for carbonated beverages.
| Leading Market Players |
|---|
| Suntory Holdings |
| Nongfu Spring |
| The Coca-Cola Company |
| Monster Beverage |
| Yili Group |
| PepsiCo |
| Refresco Group |
| Red Bull |
| Keurig Dr Pepper |
Cost & Logistics Intelligence
Advanced sugar reduction technology, including high-intensity sweeteners, simultaneously reshapes cost economics and supply concentration in carbonated soft drinks. This shift influences both ingredient sourcing and manufacturing processes, impacting overall market pricing.
Pricing Analysis
Capacity additions in India are reshaping price floors for fruit-flavored sodas, particularly in the orange segment. Per-unit transactional pricing dominates across most retail channels. Brand premium and volume scale drive significant price differentiation for major players. Pricing pressure stems from sugar taxation policies in markets like the United Kingdom, depressing full-sugar product margins. Retail consumers exhibit higher price sensitivity for standard products, while foodservice outlets are less sensitive to marginal price increases for customized options.
Supply Chain Analysis
Direct-to-retailer distribution channels manage high-volume delivery for packaged carbonated soft drinks, ensuring broad market accessibility. Geographic supply concentration for key inputs exists in China for high-intensity sweeteners and in the Middle East for PET resin. Key dependencies include purified water, sugar or alternative sweeteners, and aluminum for cans. Commodity price volatility for aluminum and sugar creates a structural supply chain risk. The dominant downstream distribution model relies heavily on established supermarket and convenience store networks for consumer reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbonated soft drinks market presents a geographic-arbitrage play, leveraging lower production costs in Southeast Asia compared to mature Western markets.
For Market Incumbents:
To counter market share erosion from healthier beverage categories, incumbents must accelerate product reformulation efforts. Invest in advanced sugar reduction R&D and deepen vertical integration into flavor innovation to maintain taste profiles. This strategy addresses consumer demand for wellness, maintaining brand relevance in health-conscious markets. Secure exclusive partnerships with fast-casual restaurants to control foodservice distribution and drive trial for new formulations.
For New Entrants and Emerging Players:
Begin with targeting underserved adult consumer segments seeking sophisticated, functional beverages. Focus on premium ginger ale and botanical-infused sodas in urban centers across the United States. A direct-to-consumer subscription model provides a strong go-to-market angle, building direct relationships and gathering consumption data. This approach bypasses traditional retail gatekeepers effectively.
For Investors and Strategic Acquirers:
Valuations sit cheapest among regional specialists with strong local distribution networks in emerging markets, particularly Southeast Asia. Long-term viability hinges on companies demonstrating agility in adapting to regulatory changes and shifting consumer health preferences. The ideal acquisition target is a mid-sized player with proprietary flavor formulations or unique functional ingredients. A signal to watch is the sustained growth of zero-sugar flanker brands in established cola segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Flavor Portfolio Diversification | Expands consumer appeal beyond traditional cola, capturing adult and premium segments. |
| Direct-to-Consumer Channel Launch | Builds direct customer relationships and gathers valuable consumption data for product development. |
| Advanced Sugar Reduction R&D | Enables compliance with health regulations and meets consumer demand for lower-calorie options. |
| Southeast Asia Market Entry | Captures growth from rising middle-class populations with an appetite for novel beverages. |
| Sustainable Packaging Adoption | Addresses environmental concerns and enhances brand image among eco-conscious consumers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing market dynamics and future projections. Primary interviews with brand managers, procurement leads, flavor scientists, and retail category buyers provided critical insights. Secondary validation drew from US FDA filings, Europe's EFSA reports, India's FSSAI standards, and beverage trade association publications. This approach ensured robust bottom-up and top-down triangulation of market data.
Historical market performance across comparable periods anchored the forecast framework, ensuring trend consistency over the projection horizon. The analytical model segmented the market by product type, packaging type, distribution channel, and end-user, with a specific focus on regional regulatory impact. Compound annual growth rates were derived from historical data extrapolation and expert consensus. Key forecast inputs included sweetener prices and consumer health trend adoption rates across the modeling period.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid technological disruptions in beverage production. Forecasts reflect assumptions regarding stable regulatory environments and consistent consumer purchasing power. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit Water Market
Beverages
India Bottled Water Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
United States and Australia Coconut Water Market
Beverages
Spring Water Market
Beverages
Powdered Beverages Market
Beverages
US Bubble Tea Market
Beverages
Europe Beverage Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Asia-Pacific Juices Market
Beverages
Growlers Market
Beverages
Low Fat Drinks Market
Beverages
Fruit Beverages Market