
 Birch Water Market | 2026-2036
Birch Water Market Size, Share, and Industry Trends Forecast 2026-2036
Birch Water Market Analysis
Seasonal tapping labor availability is redrawing production scalability across the birch water industry. Nordic Koivu Ltd leverages its Finnish forest concessions to secure raw material access during narrow spring harvest windows. Sibberi anchors its competitive stance through specialized aseptic bottling that extends shelf life without preservatives. Alaska Wild Harvest LLC dominates North American supply by controlling remote Alaskan birch stands with limited competitor access.
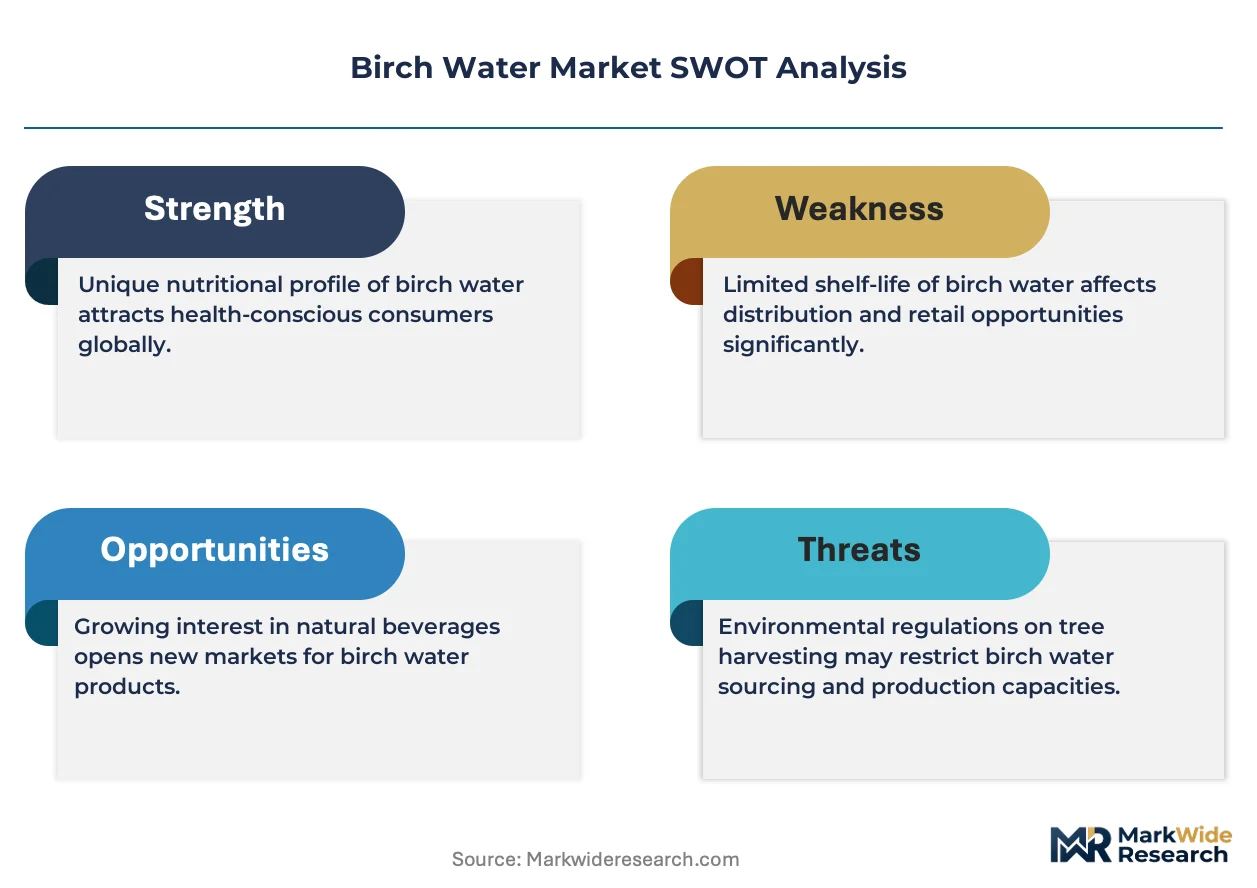
Birch water is a sterile, slightly sweet sap harvested from Betula species trees during early spring thaw, containing naturally occurring xylitol, minerals, and amino acids with osmolarity below 300 mOsm/L suitable for isotonic rehydration. Its primary commercial purpose centers on positioning as a low-sugar functional beverage alternative to coconut water and synthetic sports drinks. Organic birch water commands the deepest margin pool due to certification premiums and constrained certified forest availability, while flavored variants represent the fastest-growing product type as palatability expansion drives trial among general consumers. Online retail channels are capturing disproportionate growth velocity, particularly for subscription-based wellness purchasing among health enthusiasts and athletes.
EFSA organic labeling requirements and the EU Green Deal sustainability frameworks govern European market access, with Finland's national food safety authority enforcing strict seasonal harvest quotas. The US FDA exercises beverage classification oversight while USDA organic standards apply to certified product lines. Stakeholders must monitor evolving single-use packaging restrictions under REACH-derived national implementations across core European markets, as these regulations will determine viable packaging format investments and geographic prioritization strategies.
Market Dynamics
Seasonal harvest windows compress birch water production into narrow spring periods, forcing producers to secure forest concessions and labor capacity months ahead of thaw conditions. This temporal constraint creates structural scarcity that defines competitive positioning across the value chain.
Growth Catalysts
- EFSA Organic Certification:EU labeling standards under EFSA and the EU Green Deal create premium price tiers for certified producers, accelerating investment in organic forest management across Finland and Estonia.
- Health Enthusiast Segment Expansion:Functional hydration demand among wellness-focused consumers pulls birch water into subscription-based purchasing models through direct-to-channel platforms.
- Finnish Forest Concession Access:Traditional tapping rights in Nordic birch stands provide raw material security that competitors in non-native regions cannot replicate.
Market Restraints
- Spring Labor Bottleneck:Skilled tappers command premium wages during three-to-four-week harvest windows, compressing margins for producers without year-round workforce retention programs.
- Single-Origin Supply Concentration:Certified organic birch stands cluster in Finland, Estonia, and limited Alaskan territories, exposing buyers to geographic concentration risk.
- Coconut Water Substitution:Established tropical hydration alternatives with scaled distribution networks capture shelf space and consumer trial budgets in mainstream retail.
Strategic Opportunities
- US Wellness Market Penetration:Underdeveloped birch water awareness in American functional beverage aisles offers first-mover positioning for producers securing USDA organic certification.
- Aseptic Bottling Convergence:Integration of cold-aseptic filling with modified atmosphere packaging extends shelf life without preservatives, unlocking conventional retail distribution.
- REACH Packaging Innovation:Evolving EU single-use plastic restrictions under REACH-derived national implementations create demand for aluminum and glass format suppliers.
Industry Challenges
- Tapper Skill Transmission:Traditional birch tapping knowledge concentrates among aging Nordic practitioners, requiring structured apprenticeship programs to prevent craft attrition.
- Organic Certification Timelines:Three-year forest conversion periods to EFSA organic standards delay new entrant market access and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Birch Water Market |
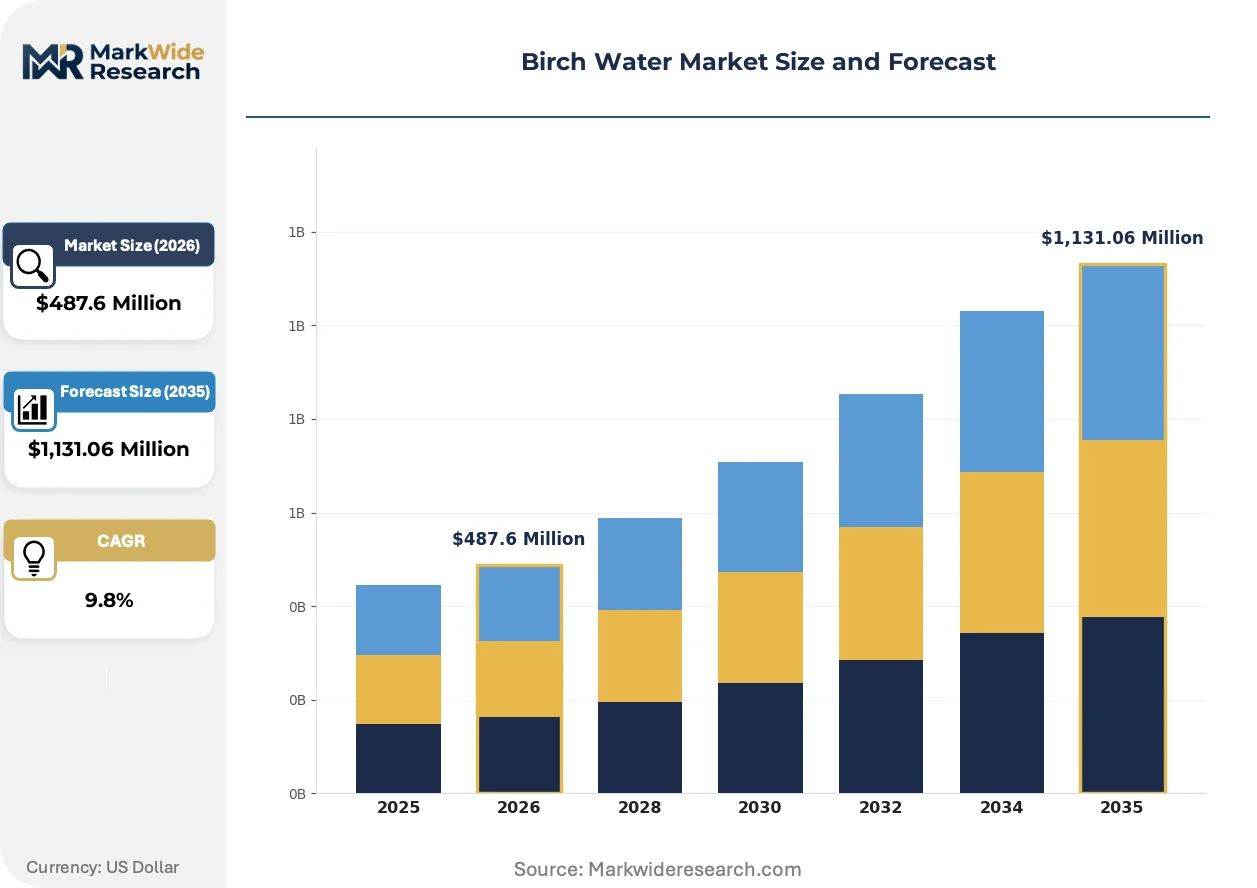
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Birch Water, Flavored Birch Water, Smoothies, Concentrates Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Bottles, Tetra Packs, Cans, Pouches End User: Health Enthusiasts, Athletes, Organic Consumers, General Public |
| Companies Covered | Nordic Koivu Ltd, Alaska Wild Harvest LLC, Sibberi, Treo Brands LLC, BelSeva, Nature On Tap Ltd, Sealand Birk, The Birch Factory, TreeVitalise Organic Birch Water, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Birch Water Market Emerging Trajectories
Aseptic processing and packaging technologies are compressing the shelf-life gap between birch water and pasteurized alternatives, while regulatory frameworks and purchasing behaviors reshape how producers reach end consumers.
Cold-aseptic bottling systems are miniaturizing from industrial-scale installations to regional facility footprints, enabling distributed production closer to harvest sites. Mid-sized Nordic producers are adopting these systems to reduce transport costs from forest to bottling. This technology diffusion is compressing the capital barrier between artisanal operators and scaled competitors.
EFSA organic labeling requirements under the EU Green Deal sustainability frameworks are tightening ingredient traceability and carbon footprint disclosure obligations. Producers must now document seasonal harvest volumes and forest management practices to maintain certification. Finnish and Estonian suppliers face the steepest compliance investments, though this creates defensible positioning against non-EU imports.
Subscription-based wellness purchasing is displacing conventional retail trial for birch water acquisition among health enthusiasts and athletes. Direct-to-consumer platforms capture recurring revenue streams that offset seasonal production volatility. This channel shift concentrates most visibly in North American urban markets where convenience-oriented consumers prioritize automated replenishment over in-store discovery.
Birch Water Market Segmentation
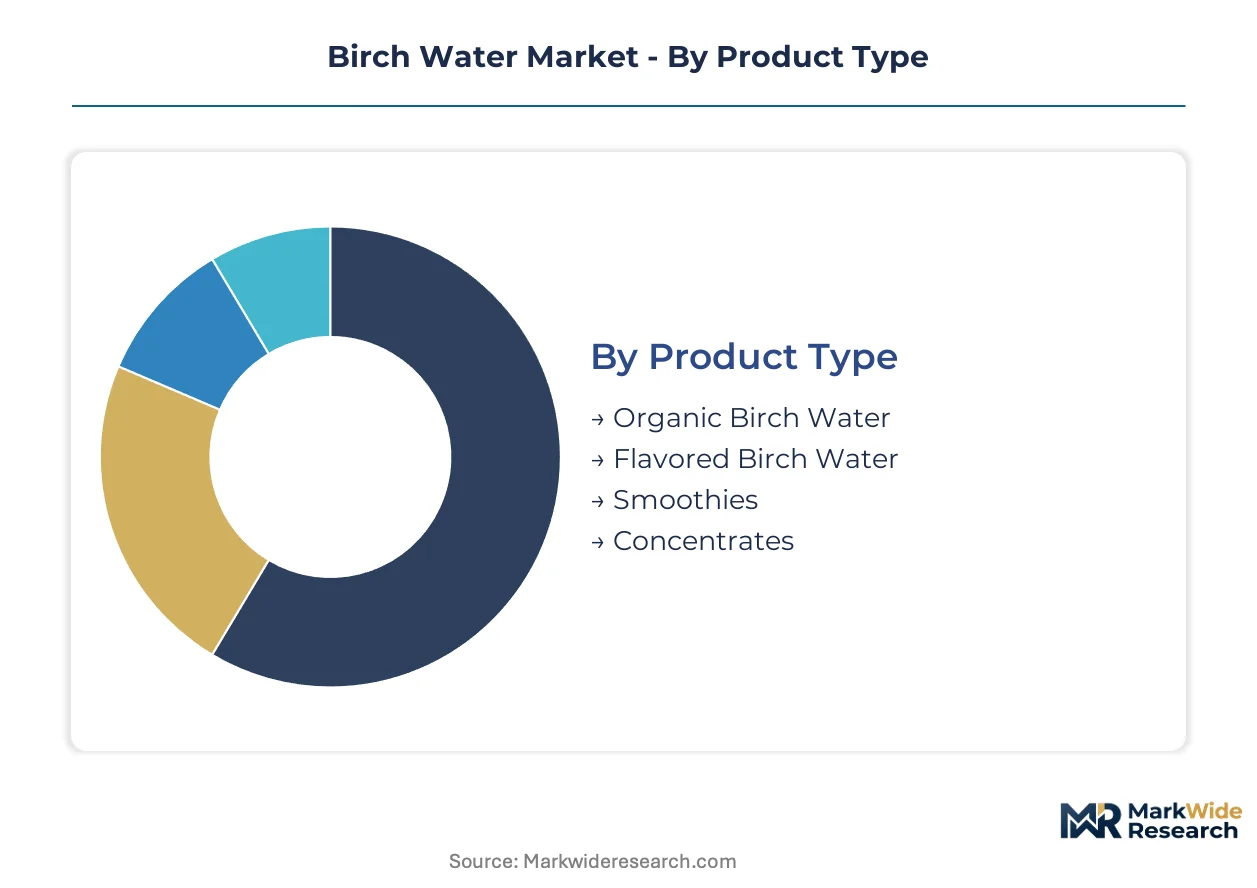
Segmentation in birch water markets reflects how regulatory certification tiers, channel economics, and consumption occasions fragment commercial opportunity. Producers must align product formats with distinct compliance burdens and purchasing behaviors that vary sharply across these dimensions.
Product Type:
EFSA organic certification and USDA organic standards create tiered compliance obligations that reshape margin structures across product categories.
- Organic Birch Water:Sap harvested from EFSA-certified or USDA-certified birch stands without synthetic inputs. Certification premiums and constrained certified forest availability in Finland and Estonia concentrate revenue among established Nordic producers with multi-year concession security.
- Flavored Birch Water:Base sap infused with fruit extracts, botanicals, or natural sweeteners to expand palatability beyond traditional taste profiles. Health enthusiasts and trial-oriented consumers in North American urban markets drive expansion here as subscription platforms reduce discovery friction.
- Smoothies:Blended formats combining birch water with fruit purees, plant proteins, or functional additives. Compact description with at least ONE named entity.
- Concentrates:Reduced-water formulations requiring dilution, enabling transport cost efficiencies. Compact description with at least ONE named entity.
Established volume favors organic certification; emerging adoption favors flavored variants.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics, with digital platforms compressing margin leakage relative to brick-and-mortar shelf fees.
- Online Retail:Direct-to-consumer and third-party marketplace sales enabling subscription-based replenishment models. Health enthusiasts and athletes in metropolitan US markets concentrate here, with automated recurring purchases offsetting seasonal production volatility.
- Supermarkets:Conventional grocery placement requiring slotting fees and promotional spend for shelf visibility. Compact description with at least ONE named entity.
- Health Food Stores:Specialty retail catering to wellness-focused consumers with educated staff recommendation. Compact description with at least ONE named entity.
- Specialty Stores:Boutique and gourmet outlets emphasizing provenance and premium positioning. Compact description with at least ONE named entity.
Margin security concentrates in online retail; physical discovery concentrates in health food stores.
Packaging Type:
REACH-derived national implementations across EU member states and evolving US state-level packaging laws are forcing format migration decisions with multi-year capital lock-in.
- Bottles:Glass and PET formats dominating premium positioning and conventional retail. Glass commands sustainability premiums under EU Green Deal frameworks, though weight increases transport emissions.
- Tetra Packs:Aseptic carton systems enabling ambient distribution without refrigeration. Compact description with at least ONE named entity.
- Cans:Aluminum formats gaining share under single-use plastic restrictions, with infinite recyclability aligning with circular economy mandates. Compact description with at least ONE named entity.
- Pouches:Flexible lightweight formats reducing transport costs but facing limited recycling infrastructure. Compact description with at least ONE named entity.
Regulatory compliance favors aluminum cans; premium positioning favors glass bottles.
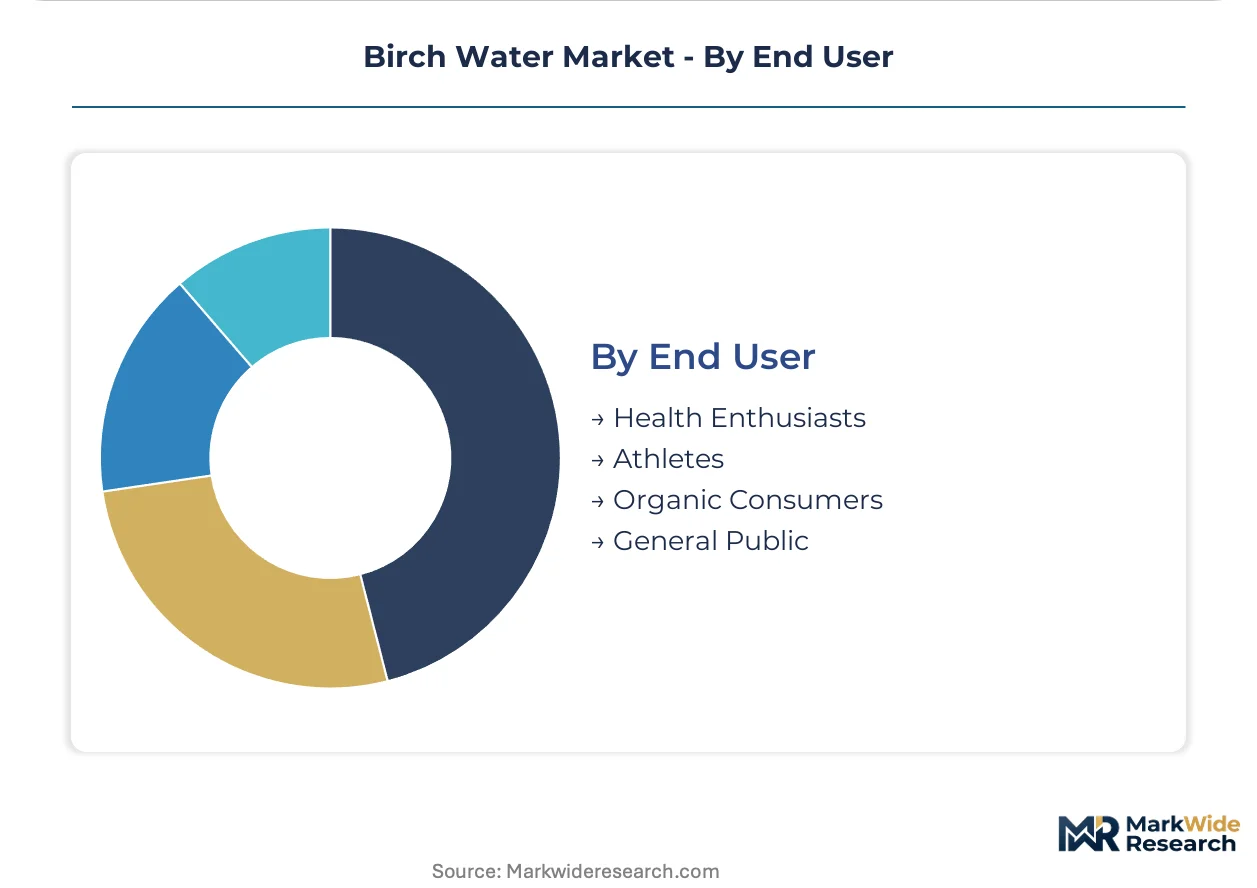
End User:
User segmentation maps directly to functional hydration claims, with distinct groups validating product benefits through different usage occasions and repeat purchase triggers.
- Health Enthusiasts:Wellness-focused consumers prioritizing functional ingredients, low osmolarity, and natural mineral content. This segment climbs the fastest as subscription platforms and influencer endorsement reshape beverage discovery patterns.
- Athletes:Performance-oriented users seeking isotonic rehydration with lower sugar load than synthetic sports drinks. Pre- and post-workout consumption occasions in North American fitness cultures concentrate demand here.
- Organic Consumers:Certification-driven purchasers for whom EFSA or USDA organic labels function as primary filter. Compact description with at least ONE named entity.
- General Public:Mass-market trial users encountering birch water through mainstream retail or promotional sampling. Compact description with at least ONE named entity.
Recurring revenue concentrates among health enthusiasts; volume expansion concentrates among general public trialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA organic certification requirements under the EU Green Deal establish Finland as the regulatory anchor for premium birch water production, with certified forest concessions and traditional tapping rights concentrating supply-side control in Nordic territories.
Finland
Health enthusiast demand and subscription wellness platforms drive Finnish birch water consumption through Helsinki-based direct-to-consumer channels. Finland's national food safety authority enforces strict seasonal harvest quotas that limit production volumes. The Lakeland region surrounding Kuopio hosts concentrated tapping operations where Nordic Koivu Ltd secures multi-year forest concessions.
Estonia
Organic consumer segments and Baltic export logistics position Estonian producers for EU market access. Estonian agricultural regulations align with EFSA traceability mandates for certified birch stand management. Tartu County clusters aseptic bottling facilities that process raw sap for private-label distribution.
United States
Athlete rehydration demand and fitness culture adoption pull birch water into metropolitan wellness markets. The FDA exercises beverage classification oversight while USDA organic standards apply to certified product lines. Alaska's remote birch stands, controlled by Alaska Wild Harvest LLC, dominate North American raw material supply.
United Kingdom
Specialty retail discovery and health food store placement sustain UK birch water trial among wellness-focused consumers. Post-BREXIT import regulations require separate organic certification recognition from EFSA standards. London's premium beverage distribution networks channel Nordic and Baltic imports into boutique retail.
Canada
Natural product retail expansion and provincial organic standards create entry pathways for birch water distribution. Health Canada maintains beverage safety oversight parallel to FDA frameworks. British Columbia's coastal wellness markets concentrate early adoption through Vancouver-based specialty retailers.
Birch Water Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in birch water supply. Forest concession holders with certified organic access command premium positioning, while aseptic processing specialists compete on shelf-life extension. Three archetypes dominate: Nordic forest-rights holders, North American territorial controllers, and technology-focused bottling innovators. Competitive moves concentrate on concession security negotiations and cold-aseptic packaging adoption.
Within the Nordic integrated tier, Nordic Koivu Ltd and Sibberi exemplify contrasting approaches to raw material security and processing technology. Alaska Wild Harvest LLC anchors the North American territorial archetype through remote stand control. These three entities represent the structural segmentation between European certification-driven supply and North American geographic exclusivity.
| Leading Market Players |
|---|
| Nordic Koivu Ltd |
| Alaska Wild Harvest LLC |
| Sibberi |
| Treo Brands LLC |
| BelSeva |
| Nature On Tap Ltd |
| Sealand Birk |
| The Birch Factory |
| TreeVitalise Organic Birch Water |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Finnish forest concessionaires and Nordic bottling facilities lock in both raw material access and price visibility across narrow spring harvest windows. These agreements tether EFSA-certified organic supply to predetermined volume commitments, insulating established producers from spot-market volatility while compressing margin flexibility for new entrants lacking concession security.
Pricing Analysis
Long-term offtake agreements dominate volume transactions between Finnish forest rights holders and aseptic bottling specialists, with spot purchases filling marginal capacity gaps. Price differentiation separates EFSA organic-certified tiers from conventional harvests, with certification premiums widening as EU Green Deal traceability mandates intensify. Cost compression in conventional birch water runs through coconut water substitution pressure in mainstream retail channels. Health enthusiasts demonstrate lowest price sensitivity due to subscription-based replenishment models, while general public trialists exhibit highest elasticity.
Supply Chain Analysis
Finland and Estonia anchor certified organic birch water production through traditional tapping concessions and EFSA-aligned forest management protocols. Raw sap extraction draws from Betula pendula and Betula pubescens stands, with aseptic bottling equipment and aluminum packaging formats representing critical downstream inputs. Single-origin supply concentration in Nordic territories exposes buyers to geographic concentration risk from climate-induced harvest variability. Distribution runs through direct-to-consumer subscription platforms and specialty retail channels, with conventional grocery penetration remaining limited by shelf-life constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services attach recurring revenue layers to seasonal production, expanding faster than standalone beverage sales as health enthusiasts prioritize automated wellness purchasing.
For Market Incumbents: Fortify forest concession portfolios through multi-year extension negotiations with Finnish and Estonian landholders before competing beverage multinationals enter offtake bidding. Secure cold-aseptic bottling capacity additions in Tartu County to preempt processing bottlenecks. Certification investment in USDA organic standards unlocks defensible positioning against North American territorial controllers. For New Entrants and Emerging Players: Anchor in underdeveloped US metropolitan wellness markets where birch water awareness lags coconut water penetration. Target athlete rehydration segments through fitness channel partnerships and influencer endorsement programs. Direct-to-consumer launch with subscription-first architecture reduces slotting fee burdens and builds recurring revenue foundations. For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers combining forest concession security with proprietary aseptic processing capabilities. Long-term viability hinges on multi-decade tapping rights and technology moats in shelf-life extension. Watch for inflection signals in USDA organic certification adoption rates among North American fitness beverage distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Forest Concession Expansion | Multi-year Finnish and Estonian tapping rights secure raw material access against competitor encroachment. |
| Cold-Aseptic Bottling Adoption | Regional facility deployment near harvest sites reduces transport costs and extends shelf-life without preservatives. |
| USDA Organic Certification | US market entry requires compliance investment parallel to EFSA standards already maintained by Nordic producers. |
| Subscription Platform Integration | Direct-to-consumer recurring revenue models offset seasonal production volatility among health enthusiast segments. |
| Aluminum Format Migration | REACH-derived packaging restrictions favor infinite recyclability over single-use plastic alternatives. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA regulatory filings, Finnish forest management databases, and EU trade customs records. Birch water producers, aseptic bottling equipment specialists, and specialty beverage distributors provided operational data through structured interviews. Bottom-up volume modeling from individual concession yields triangulates against top-down market sizing from channel shipment data.
Segmentation dimensions modeled span organic certification tier, distribution channel architecture, packaging format compliance, and end-user occasion mapping across the projection horizon. CAGRs derive from regression analysis of historical harvest volumes correlated with wellness beverage adoption curves. Forecast inputs incorporate EFSA organic conversion timelines and REACH packaging implementation schedules.
Material uncertainties — spring thaw variability, tapper labor availability, and evolving EU single-use plastic restrictions — sit outside the modeled envelope. Forecasts reflect assumptions on concession renewal rates and certification maintenance compliance. Recalibration cycles align with material shifts in EFSA traceability mandates and USDA organic standard harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Water Bottle Market
Beverages
Fruit Water Market
Beverages
Carbonated Soft Drinks Market
Beverages
Maple Water Market
Beverages
Baby Drinks Market
Beverages
China Orange Juice Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Detox Drinks Market
Beverages
Chocolate Malt Drink Market
Beverages
Sparkling Bottled Water Market
Beverages
Europe Juices Market
Beverages
South America Mate Market
Beverages
Japan Energy Drink Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Crystal Boba Market
Beverages
GCC Fruit Juice Market