
 India Cafes & Bars Market | 2026-2036
India Cafes & Bars Market Size, Share, and Industry Trends Forecast 2026-2036
India Cafes & Bars Market Insights
Aftermarket service revenue from loyalty programs and subscription-based beverage passes is fragmenting as chains compete for recurring spend. Tata Starbucks Private Limited leverages its joint-venture structure to sustain premium positioning in Mumbai and Delhi. Café Coffee Day anchors mass-market penetration through its extensive kiosk network. Blue Tokai Coffee Roasters differentiates via in-house roasting and direct-trade sourcing relationships.
Cafes and bars constitute licensed foodservice establishments preparing and serving beverages, baked goods, and alcoholic drinks on-premises, with equipment specifications ranging from espresso machines operating at 9-bar pressure to cold-brew systems requiring 12-24 hour extraction cycles. Full-service formats capture the deepest margin pools through extended dwell times and attach rates for food pairings. Quick-service and takeaway segments lead volume throughput during morning commuter windows. Artisan concept types attract the fastest-growing customer segment among professionals seeking origin-specific coffee experiences.
The Food Safety and Standards Authority of India mandates licensing under FSSAI registration for all beverage preparation outlets, while state excise departments regulate alcohol service permissions under separate frameworks. BIS certification requirements for commercial kitchen equipment shape capital expenditure planning for new entrants. Municipal corporations in Bengaluru, Hyderabad, and Pune enforce varying signage and operating-hour restrictions that fragment compliance costs. Stakeholders must monitor evolving state-level excise policies and municipal zoning amendments that determine viable locations for bar-format expansions.
Market Dynamics
Urban young adults in Mumbai, Delhi, and Bengaluru are compressing repeat-visit cycles from monthly to weekly, forcing chains to redesign loyalty mechanics and subscription passes around frequency rather than spend depth.
Growth Catalysts
- FSSAI hygiene protocols:Standardized beverage preparation mandates elevate consumer trust in organized chains over unlicensed competitors.
- Metro density economics:Maharashtra and Karnataka concentrate premium outlet viability through commuter footfall patterns.
- Cold-brew extraction systems:Extended 12-24 hour cycles enable product differentiation and margin expansion in artisan formats.
Market Restraints
- Arabica bean price volatility:Global commodity swings compress gross margins for roasters lacking forward contracts.
- Equipment import dependence:Commercial espresso machines and grinders concentrate supply among Italian and German manufacturers.
- State excise fragmentation:Alcohol service permissions vary across Maharashtra, Karnataka, and Telangana, complicating bar-format expansion planning.
Strategic Opportunities
- Tier-II city penetration:Pune, Hyderabad, and Ahmedabad present underdeveloped demand for premium cafe formats.
- Direct-trade sourcing models:Roasters building farmer relationships in Chikmagalur and Coorg capture traceability premiums.
- Subscription beverage passes:Prepaid consumption models lock recurring revenue ahead of competitor loyalty programs.
Industry Challenges
- Barista skill scarcity:Latte art and manual brewing expertise remains concentrated in metro labor pools.
- BIS certification timelines:Commercial kitchen equipment approvals delay outlet openings by 8-12 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cafes & Bars Market |
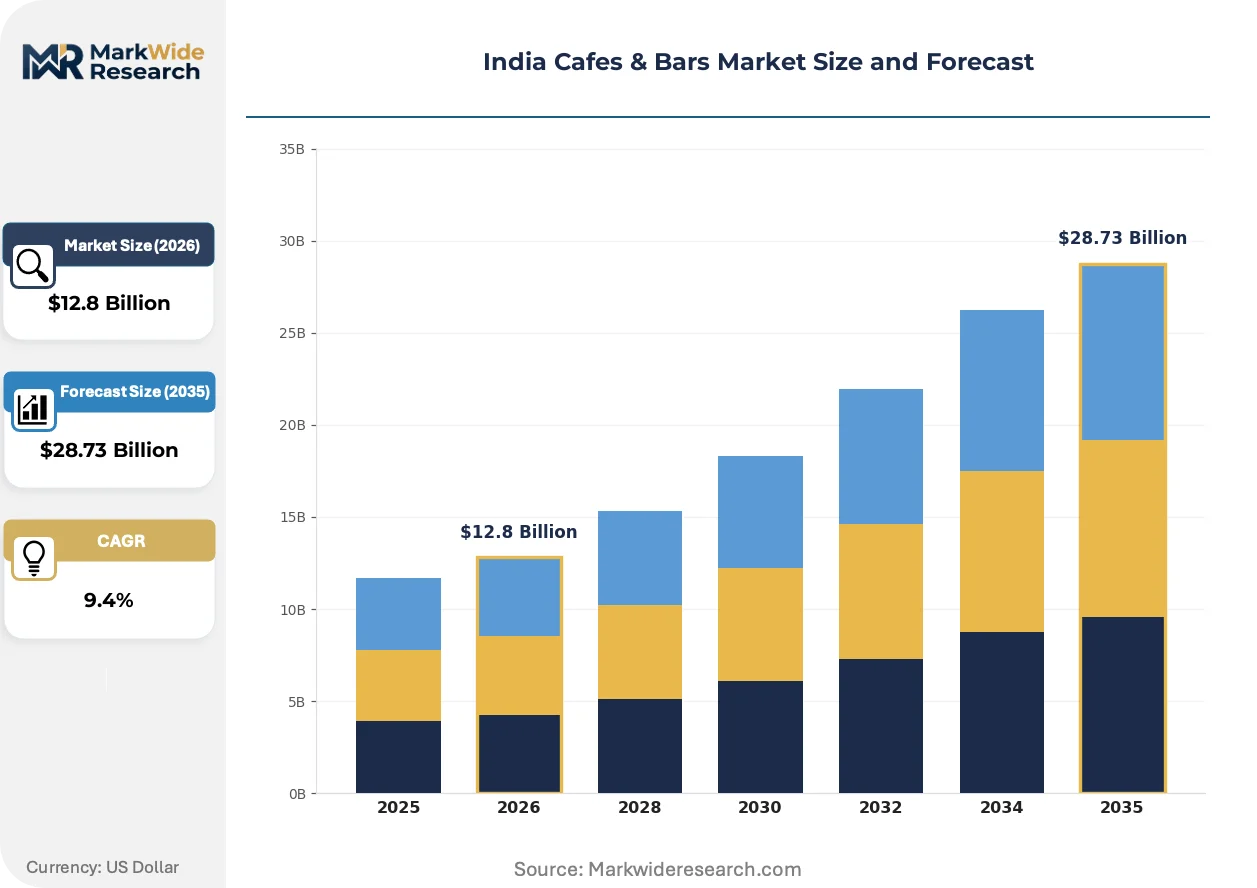
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Service, Quick Service, Drive-thru, Takeaway Customer Type: Families, Young Adults, Professionals, Students Concept Type: Themed, Health-focused, Artisan, Casual Dining Price Tier: Premium, Mid-range, Budget, Affordable |
| Companies Covered | Tata Starbucks Private Limited, Barista Coffee Company Limited, Café Coffee Day, Dunkin, Impresa Hospitality Pvt. Ltd., Speciality Restaurants Ltd., Devyani International Ltd., Blue Tokai Coffee Roasters, Third Wave Coffee Roasters, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cafes & Bars Market Trends and Innovations
Automation and provenance transparency are restructuring how beverages are produced, certified, and consumed across Indian urban centers.
Automated espresso workstations integrating grind-by-weight and pressure-profiling are collapsing the skill barrier between specialty and commodity preparation. Quick-service chains in Delhi and Mumbai deploy these systems to maintain consistency across high-turnout locations. The technology compresses training cycles from months to days while narrowing quality variance.
FSSAI licensing mandates for all beverage preparation outlets tightened documentation requirements for ingredient sourcing and storage temperature logs. Organized chains absorb compliance costs more efficiently than independent operators. The regulation accelerates informal-to-formal conversion in Bengaluru and Hyderabad municipal jurisdictions.
Origin-specific consumption preferences now drive menu architecture for professionals in Mumbai and Delhi. Single-estate pour-overs and micro-lot cold brews displace blended house coffees in premium formats. Chikmagalur and Coorg estate names appear on menus as prominently as roast profiles, reflecting farmer-direct storytelling.
India Cafes & Bars Market Segmentation
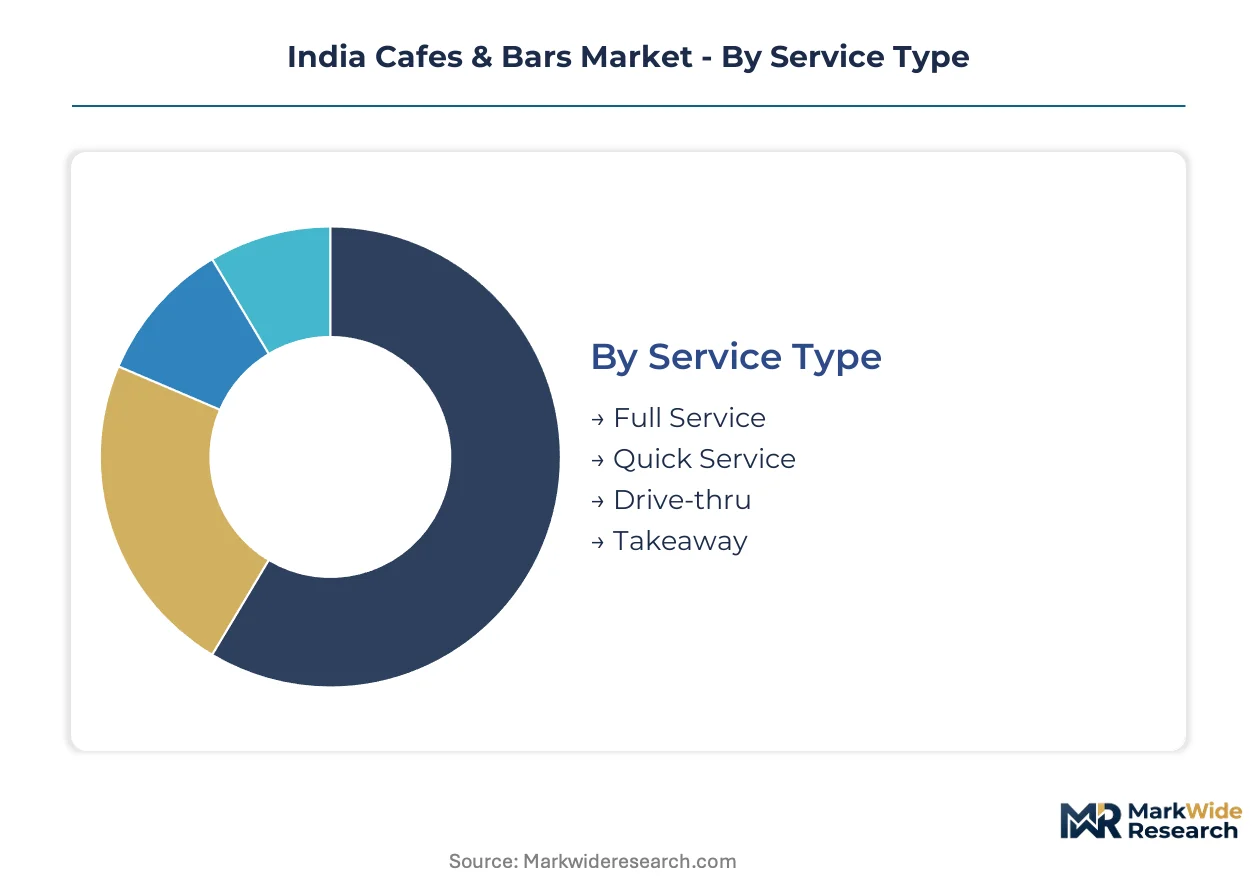
Segmentation in the India cafes and bars market reveals distinct operational economics and customer acquisition strategies. Format choice determines capital intensity, while customer demographics shape loyalty mechanics and pricing architecture.
Service Type:
Use-case spectrum spans extended dwell occasions to commuter convenience, with format selection dictating real estate footprint and labor deployment.
- Full Service:Table-side beverage preparation and extended seating configurations support food pairing attach rates. Demand concentrates in Mumbai and Delhi premium districts where professionals conduct informal meetings; FSSAI compliance documentation absorbs smaller independents.
- Quick Service:Counter-based ordering with limited seating maximizes throughput during morning commuter windows. Bengaluru and Hyderabad tech corridors generate repeat frequency; standardized preparation protocols enable rapid outlet replication.
- Drive-thru:Vehicle-accessible service lanes target highway-adjacent and suburban locations with parking constraints. Emerging presence along Mumbai-Pune and Delhi-Gurgaon corridors.
- Takeaway:Minimal footprint kiosks and mobile carts capture impulse consumption near transit nodes. Café Coffee Day's extensive network demonstrates viability in Tier-II city railway stations.
Established volume favors Quick Service; emerging adoption favors Full Service.
Customer Type:
Demographic concentration shapes menu architecture and promotional calendar timing across metropolitan markets.
- Young Adults:Weekly visitation frequency in Mumbai and Bengaluru drives subscription pass adoption and social media engagement metrics.
- Professionals:Origin-specific coffee experiences and single-estate pour-overs attract this fastest-expanding segment in Delhi and Mumbai business districts.
- Families:Weekend occasion clustering demands expanded food menus and child-friendly seating configurations.
- Students:Price-sensitive trial behavior and extended laptop-based dwell times influence seating design and WiFi infrastructure investment.
Young Adults anchor current revenue; Professionals climb the fastest as origin transparency preferences deepen.
Concept Type:
Positioning strategy differentiates through narrative depth, with capital requirements scaling dramatically across the spectrum.
- Artisan:In-house roasting equipment and direct-trade sourcing relationships with Chikmagalur and Coorg estates enable traceability premiums. Blue Tokai's model demonstrates farmer-direct storytelling viability.
- Themed:Immersive interior design and experiential programming command extended visit durations in Delhi and Mumbai entertainment districts.
- Health-focused:Alternative milk integration, low-sugar formulations, and functional beverage additions attract wellness-oriented consumers.
- Casual Dining:Expanded kitchen facilities and full meal service broaden daypart capture but increase operational complexity.
Artisan concepts gain share fastest; Casual Dining retains broadest demographic reach.
Price Tier:
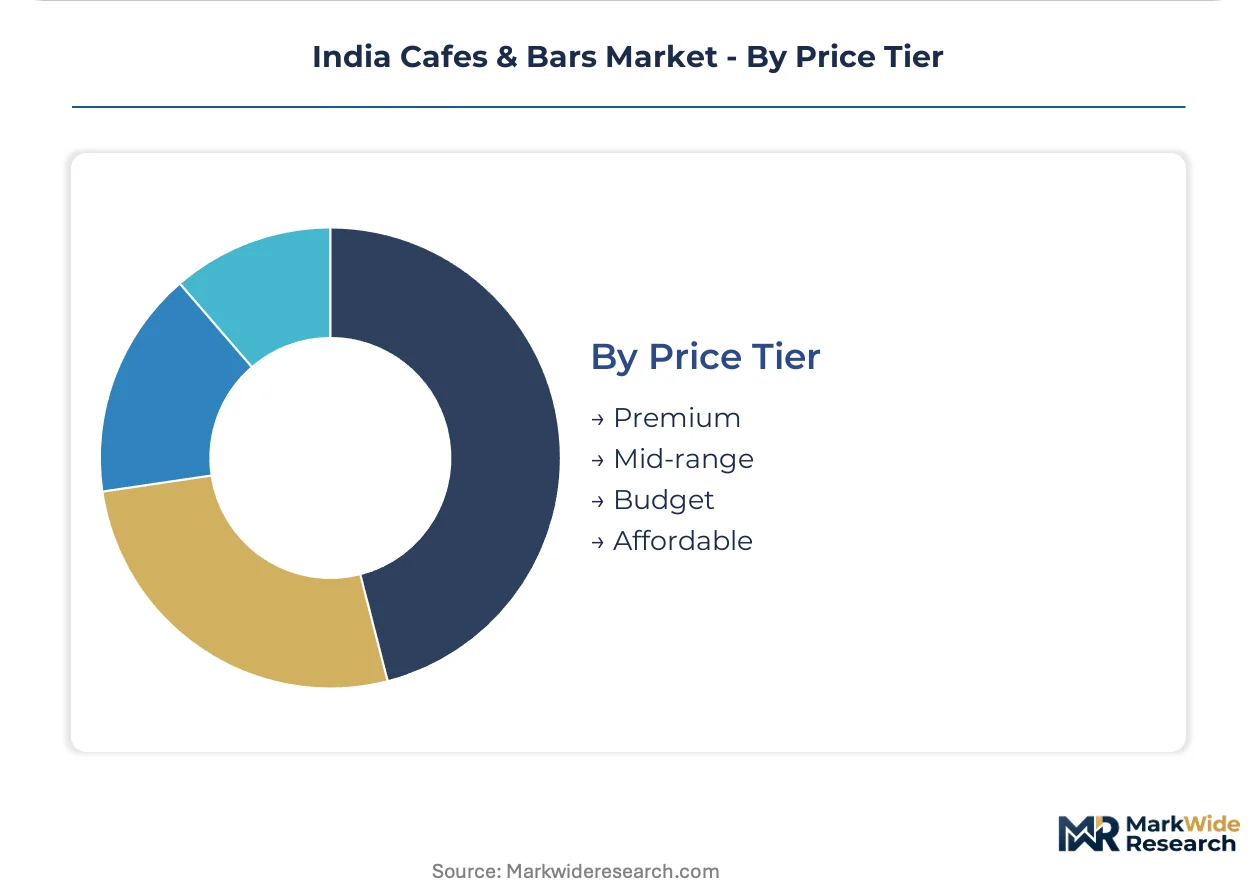
Three-tier pricing structure across premium, standard, and economy levels aligns with real estate costs and equipment specifications.
- Premium:9-bar pressure espresso systems and certified barista training support per-beverage economics in Mumbai and Delhi luxury retail locations.
- Mid-range:Automated workstations balance consistency requirements with labor cost management across Bengaluru and Hyderabad.
- Budget:Simplified equipment configurations and pre-ground coffee inputs target student and commuter price thresholds.
- Affordable:Kiosk formats and minimal service layers penetrate Tier-II city railway stations and bus terminals.
Mid-range captures widest outlet distribution; Premium exhibits steepest expansion trajectory in Maharashtra and Karnataka metro clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian metros, with Mumbai and Delhi consumers accepting premium pricing for origin-specific experiences while Tier-II city buyers remain highly price-sensitive toward standardized formats.
Maharashtra
Mumbai's dense commuter corridors generate sustained morning throughput for quick-service formats, while Pune's emerging tech workforce drives weekly visitation frequency. FSSAI licensing mandates for all beverage preparation outlets tighten compliance documentation for new entrants. Premium artisan clusters concentrate in Mumbai's Bandra-Kurla Complex and Lower Parel districts where professionals seek single-estate pour-overs.
Karnataka
Bengaluru's technology corridors anchor the fastest-growing professional segment demanding traceability-transparent coffee experiences. State excise department frameworks for alcohol service permissions remain more permissive than neighboring Telangana, enabling bar-format experimentation. Chikmagalur and Coorg estate sourcing relationships concentrate roasting operations in the city's Koramangala and Indiranagar micro-markets.
Delhi-NCR
Gurgaon's corporate campuses and Noida's media clusters sustain extended-dwell full-service demand for informal business meetings. Municipal corporation signage and operating-hour restrictions fragment compliance costs across Delhi, Gurgaon, and Noida jurisdictions. Premium positioning concentrates in Select Citywalk and Cyber Hub retail locations where joint-venture structures sustain international brand presence.
Telangana
Hyderabad's pharmaceutical and IT corridors generate emerging demand for automated espresso workstations balancing consistency with high turnover. State excise policies on alcohol service permissions remain more restrictive than Maharashtra and Karnataka, limiting bar-format expansion. Quick-service penetration targets HITEC City and Gachibowli commuter nodes with standardized preparation protocols.
Gujarat
Ahmedabad's manufacturing and diamond trading communities present underdeveloped terrain for premium cafe formats, with price sensitivity favoring budget-tier kiosk configurations. BIS certification requirements for commercial kitchen equipment shape capital expenditure planning for entrants testing market viability. Emerging clusters concentrate in SG Highway and Prahlad Nagar commercial districts.
India Cafes & Bars Market Competitive Landscape
Joint-venture premium operators and mass-market domestic chains split the market into distinct strategic territories with minimal direct overlap. The vendor base organizes around three archetypes: international joint ventures leveraging global brand equity, domestic multi-format chains optimizing kiosk density, and artisan roasters building direct-trade sourcing moats. Consolidation pressure intensifies as FSSAI hygiene protocols raise compliance costs that favor organized players. Dominant competitive moves include subscription-based loyalty program launches and Tier-II city franchise expansion.
Within the joint-venture premium tier, Tata Starbucks Private Limited occupies a position exemplifying global-local partnership structures. Among mass-market domestic chains, Café Coffee Day anchors extensive kiosk network penetration. At the artisan roaster vector, Blue Tokai Coffee Roasters and Third Wave Coffee Roasters represent farmer-direct sourcing archetypes. These named entities illustrate competitive positioning without constituting exhaustive market coverage.
| Leading Market Players |
|---|
| Tata Starbucks Private Limited |
| Barista Coffee Company Limited |
| Café Coffee Day |
| Dunkin |
| Impresa Hospitality Pvt. Ltd. |
| Speciality Restaurants Ltd. |
| Devyani International Ltd. |
| Blue Tokai Coffee Roasters |
| Third Wave Coffee Roasters |
| Others |
Pricing and Supply Chain Analysis
Chikmagalur and Coorg estate clusters in Karnataka anchor Arabica bean availability, concentrating roasting capacity in Bengaluru's Koramangala micro-market and amplifying pricing power for traceability-transparent formats. This upstream density shapes downstream tier architecture across Maharashtra and Karnataka metros.
Pricing Analysis
Subscription beverage passes and loyalty program tiers drive lifetime value capture as chains compete for recurring spend. Three-tier pricing structure across premium, standard, and economy levels aligns with FSSAI compliance costs and equipment specifications. Cost compression in budget-tier kiosk formats is intensifying because Café Coffee Day's extensive network sets reference pricing. Students and commuters exhibit highest price sensitivity; professionals in Mumbai's Bandra-Kurla Complex accept origin-specific premiums.
Supply Chain Analysis
Arabica bean sourcing draws from Karnataka's Chikmagalur and Coorg estates, with Robusta supplementation from Kerala's Wayanad district. Commercial espresso machines and precision grinders feed from Italian and German manufacturers, creating import dependence. Single-source vulnerability concentrates in European equipment suppliers subject to extended BIS certification timelines. Distribution runs through organized cold-chain networks to metro roasting hubs, then last-mile to franchise and company-operated outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FSSAI licensing entrenchment and compliance cost absorption favor organized chains over informal competitors.
For Market Incumbents: Harden subscription pass mechanics around weekly visitation frequency rather than spend depth to lock recurring revenue ahead of artisan roaster loyalty programs. Deepen direct-trade sourcing relationships with Chikmagalur estates to defend margin position against Arabica price volatility. Expand automated espresso workstation deployment to compress training cycles and maintain consistency across high-turnout Bengaluru and Mumbai locations.
For New Entrants and Emerging Players: Pursue Tier-II city white space in Pune, Hyderabad, and Ahmedabad where premium cafe penetration remains underdeveloped and price sensitivity favors differentiated format economics. Target quick-service configurations in tech corridor commuter nodes with standardized preparation protocols enabling rapid replication. Anchor go-to-market strategy around FSSAI compliance documentation as competitive differentiator against unlicensed independent operators.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because FSSAI hygiene protocol tightening accelerates informal-to-formal conversion and consolidates market share toward organized chains. Acquisition target archetype: artisan roasters with captive estate relationships and in-house roasting infrastructure. Watch state excise policy liberalization in Telangana and Gujarat as signal for bar-format expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Estate Sourcing | Captures traceability premiums from Chikmagalur and Coorg farmer relationships. |
| Automated Espresso Workstation Deployment | Collapses skill barriers between specialty and commodity preparation in high-turnout locations. |
| Subscription Beverage Pass Launch | Locks recurring revenue ahead of competitor loyalty programs among young adult segments. |
| Tier-II City Franchise Expansion | Accesses underdeveloped demand in Pune, Hyderabad, and Ahmedabad corridor markets. |
| FSSAI Compliance Infrastructure Investment | Absorbs documentation costs that fragment independent operator economics. |
Research Methodology
Operator-level perspectives from cafe chain operations directors, FSSAI compliance officers, estate sourcing managers, and municipal licensing administrators anchored the qualitative base. Secondary validation drew from FSSAI licensing databases, state excise department filings, BIS certification records, and municipal corporation zoning amendments. Bottom-up outlet economics modeling triangulated against top-down metropolitan consumption estimates.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, customer demographic, concept positioning, and price tier, with regional regulatory cluster as industry-specific overlay. CAGRs derived from outlet expansion run-rates, visitation frequency compression patterns, and per-capita beverage spend trajectories. Forecast inputs incorporated Arabica futures volatility bands and equipment import duty sensitivity.
Sensitivities concentrate around state excise policy shifts, Arabica commodity price spikes, and BIS certification timeline extensions. Forecasts reflect documented assumptions on urban young adult demographic growth and metro density economics. Cross-checking against municipal corporation licensing issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
GCC Fruit Juice Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Sports and Energy Drinks Market
Beverages
Ready to Drink Premixes Market
Beverages
GCC Coconut Water Market
Beverages
Detox Drinks Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Soft Serve Premix Market
Beverages
Probiotic Beverage Market
Beverages
North America Energy Drink Market
Beverages
Packaged Cactus Water Market
Beverages
Pineapple Juice Market
Beverages
Sparkling Water Machine Market
Beverages
Hot Cocoa Mix Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Saudi Arabia Food & Beverage Market