
 Fiber-Optic Filters Market | 2026-2036
Fiber-Optic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber-Optic Filters Market Analytics
Data center operators is reorganizing procurement priorities toward wavelength-selective components as coherent transmission architectures scale across hyperscale facilities. Thorlabs leverages vertical integration across coating chambers and fiber assembly to sustain margin control in bandpass filter production. Newport Corporation anchors North American supply through specialized thin-film deposition capabilities serving research institutions and telecom providers. DiCon Fiberoptics, Inc. competes on microstructure photonic designs that differentiate its product line in sensing applications.
Fiber-optic filters are wavelength-selective devices manufactured through thin-film coating, grating inscription, or microstructure photonic fabrication, typically specified by center wavelength, bandwidth, and insertion loss parameters, designed to isolate, block, or polarize specific optical signals in guided-wave systems. Bandpass filters command the largest revenue pool due to their ubiquity in dense wavelength division multiplexing networks, while notch filters represent the fastest-growing category as Raman amplification and sensing architectures expand. Thin-film coating technology dominates manufacturing throughput, though microstructure photonic approaches are gaining traction where thermal stability and miniaturization drive specification requirements in medical devices and industrial sensing.
FDA device clearance pathways shape demand specifications for fiber-optic filters integrated into surgical laser systems and diagnostic equipment, while FCC spectrum management rules directly influence filter performance requirements in telecommunications infrastructure. The EPA regulates hazardous material use in coating processes, pushing manufacturers toward environmentally compliant deposition chemistries. Stakeholders must monitor evolving IEEE standards for data center optical interconnects and NIST measurement protocols that redefine filter qualification benchmarks for next-generation coherent transceivers.
Market Dynamics
Coherent transmission scaling in hyperscale data centers is compressing wavelength tolerance specifications and forcing filter manufacturers to requalify products for 400G/800G line rates, creating a structural bottleneck in thin-film coating capacity.
Growth Catalysts
- China MIIT infrastructure mandates:State-backed 5G backhaul programs and cloud hyperscaler buildouts in Beijing and Shenzhen are driving volume procurement of DWDM filter arrays with tight center-wavelength stability.
- Raman amplification architectures:Long-haul submarine and terrestrial links are expanding notch filter deployment to suppress amplified spontaneous emission noise, particularly across transpacific cable systems.
- Thin-film coating throughput:Advances in ion-assisted deposition are reducing layer count requirements while maintaining thermal drift specifications, enabling faster production cycles for bandpass filters.
Market Restraints
- Specialized substrate volatility:Synthetic fused silica and silicon dioxide wafer supply concentrates among Japanese and German suppliers, exposing coaters to input cost swings.
- DWDM channel density limits:Physical constraints on thin-film stack complexity create hard boundaries on achievable bandwidth-narrowing for next-generation C+L band systems.
- EPA hazardous chemistry restrictions:Traditional electron-beam deposition precursors face phase-out timelines, forcing capital-intensive retooling toward environmentally compliant chemistries.
Strategic Opportunities
- India PLI scheme leverage:Domestic manufacturing incentives for telecom equipment are creating localized filter assembly demand that bypasses import tariff structures.
- Medical device convergence:Surgical laser systems and diagnostic imaging platforms are adopting fiber-optic filtering for precise wavelength isolation, opening FDA 510(k) pathways outside traditional telecom.
- Silicon photonics hybrid integration:Microstructure photonic filters bonded to CMOS platforms are enabling chip-scale coherent transceivers with on-board wavelength selection.
Industry Challenges
- Thin-film process engineer scarcity:Deposition chamber optimization and stress-compensation design require specialized expertise that outpaces university photonics program output.
- IEEE 802.3 requalification cycles:Data center interconnect standards revisions compress filter validation timelines, forcing parallel rather than sequential testing workflows.
- Multi-jurisdiction certification stacking:Products serving both telecom infrastructure and medical devices must satisfy FCC, FDA, and ISO 13485 protocols simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber-Optic Filters Market |
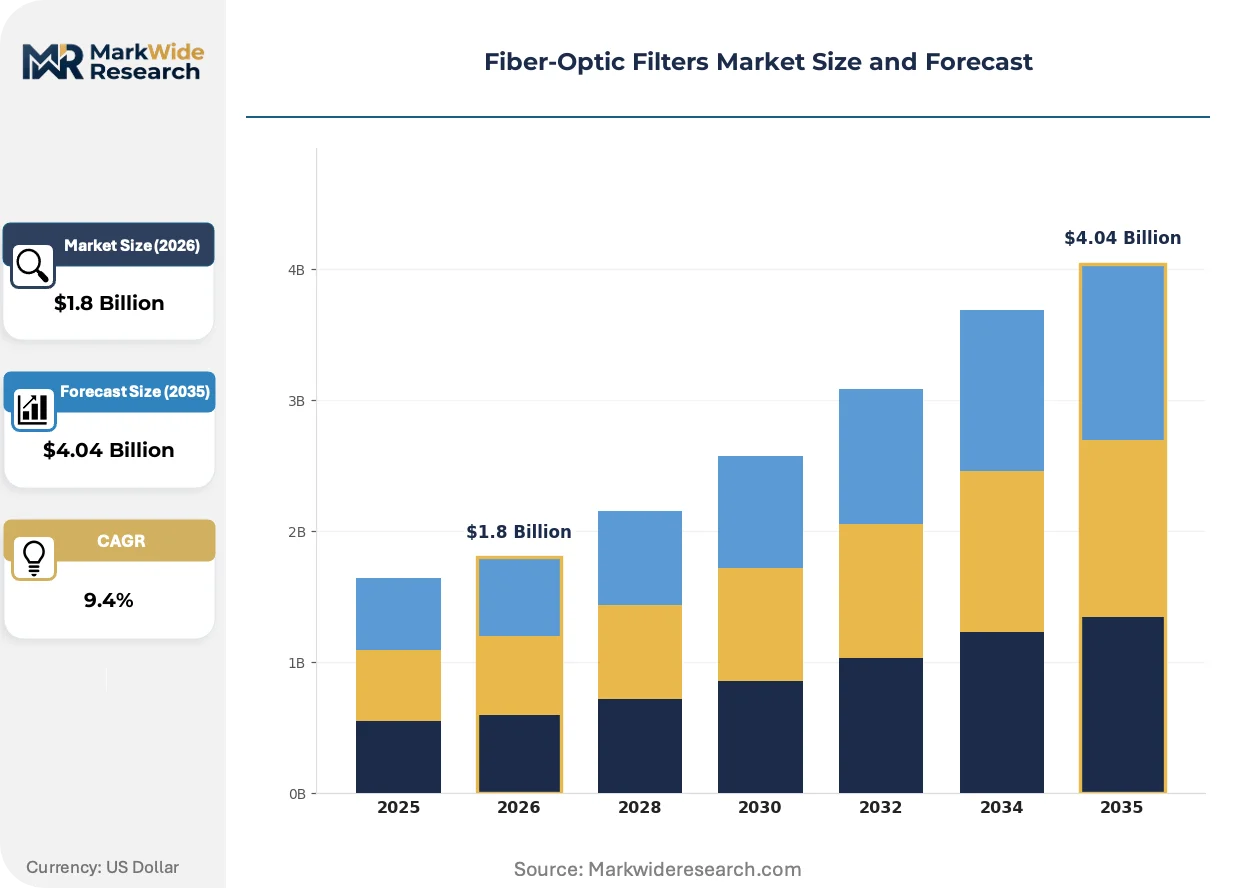
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bandpass Filter, Notch Filter, Polarizing Filter, Reflective Filter Application: Telecommunications, Sensing Applications, Medical Devices, Data Centers Technology: Thin-Film Coating, Fabrication Techniques, Microstructure Photonic, Grating End User: Telecom Providers, Research Institutions, Healthcare Facilities, Industrial Users |
| Companies Covered | Newport Corporation, DiCon Fiberoptics, Inc., WL Photonics, Inc., Agiltron Inc., Thorlabs, Edmund Optics, Alluxa Inc., Spectrogon, Reynard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber-Optic Filters Market Evolving Landscape
Photonic integration and environmental compliance mandates are rewriting manufacturing footprints and procurement specifications across fiber-optic filter supply chains.
Microstructure photonic filters fabricated through femtosecond laser inscription are displacing conventional thin-film stacks in sensing and medical applications where thermal cycling resistance and miniaturization outweigh absolute insertion loss performance. Industrial LiDAR manufacturers and surgical device OEMs are qualifying these designs for volume production. This displacement is compressing addressable market share for coating-dependent suppliers in non-telecom segments.
EU REACH and RoHS restrictions on hexavalent chromium and cadmium compounds in optical coatings are forcing deposition chemistry reformulation across European manufacturing facilities. The industrial consequence is extended qualification timelines as new layer materials undergo reliability testing. Telecom filter producers serving EU markets are responding by dual-sourcing compliant and non-compliant coating lines to maintain supply continuity during transition periods.
Hyperscale data center operators are consolidating wavelength-selective component purchasing through direct OEM partnerships rather than distributor channels, compressing margin capture for intermediaries. This channel compression is most visible in North American and Chinese cloud markets where procurement teams maintain dedicated optical component engineering staff. Distributors are pivoting toward technical support and inventory financing services to retain relevance in high-volume transactions.
Fiber-Optic Filters Market Segmentation
Fiber-optic filter procurement splits sharply between domestic infrastructure programs and export-driven specialty manufacturing. Segment boundaries increasingly blur as telecom-grade specifications migrate into medical and sensing applications.
Product Type:
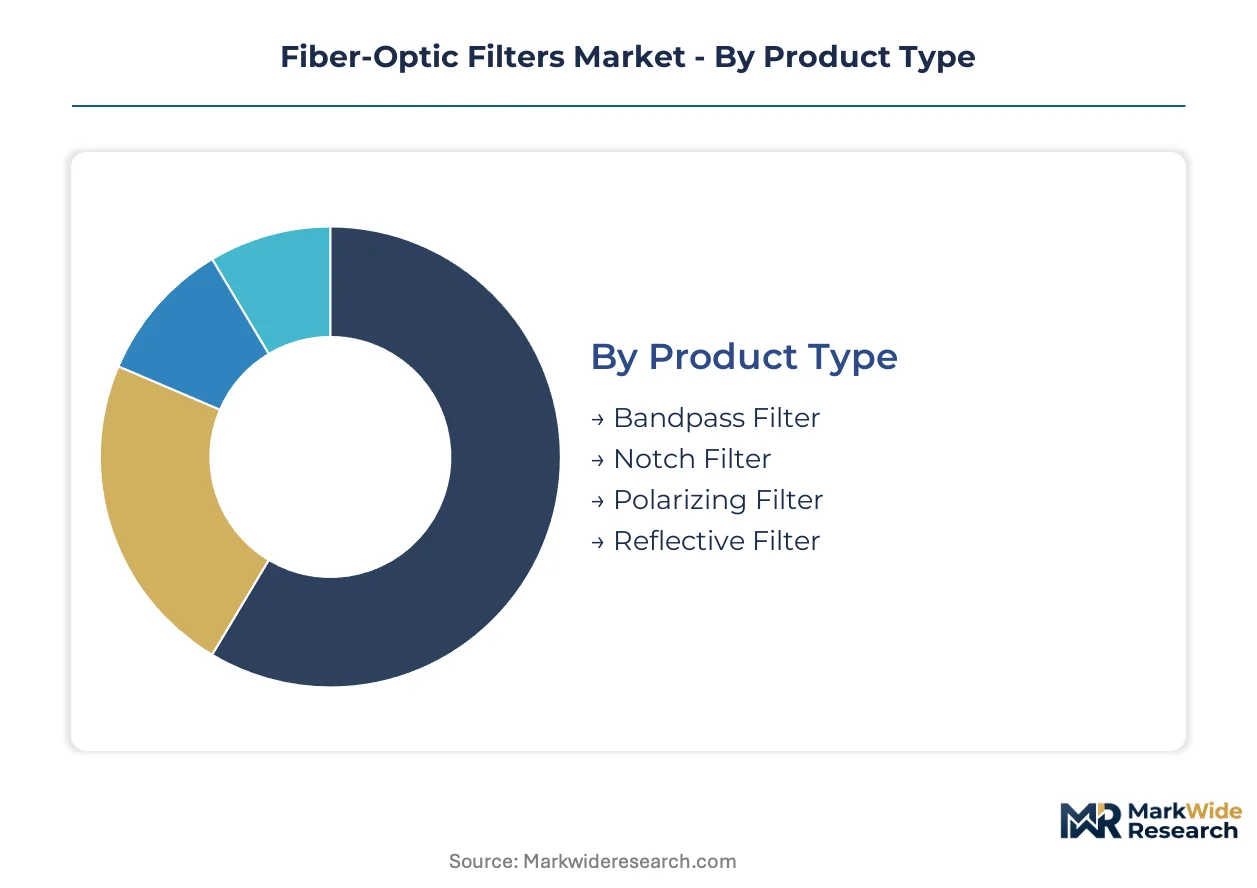
Bandpass and notch variants dominate volume production for domestic Chinese and North American hyperscaler contracts, while polarizing and reflective designs serve export-specialty markets in European medical device and Japanese industrial sensing sectors.
- Bandpass Filter:Thin-film interference stacks isolate specific wavelength channels with center-wavelength tolerances tightening to ±0.02 nanometers for 800G coherent transceivers. Chinese MIIT-mandated 5G backhaul programs in Beijing and Shenzhen absorb the majority of volume output from domestic coating facilities.
- Notch Filter:Grating-based or thin-film designs suppress narrow wavelength bands to block amplified spontaneous emission in Raman amplification chains. Transpacific submarine cable operators are expanding deployment to manage noise floors across 10,000+ kilometer spans.
- Polarizing Filter:Birefringent crystal assemblies separate orthogonal polarization states for coherent detection architectures.
- Reflective Filter:Dielectric mirror stacks redirect specific bands while transmitting others in multi-path sensing interferometers.
Bandpass variants command the established base. The steepest expansion runs through notch filter deployment in submarine and long-haul terrestrial links.
Application:
Cost-tier stratification separates high-volume telecommunications procurement from premium-priced medical and sensing segments where FDA 510(k) pathways and custom specification cycles extend lead times.
- Telecommunications:DWDM network infrastructure consumes standardized bandpass arrays in 40-channel and 80-channel configurations. Chinese cloud hyperscalers and state-owned carriers drive procurement consolidation through direct OEM partnerships.
- Data Centers:Coherent transceiver modules integrate wavelength-selective elements for 400G/800G line rates. North American hyperscale facilities in Ashburn and Prineville are requalifying filter specifications for OSFP and QSFP-DD form factors.
- Sensing Applications:Fiber Bragg grating and microstructure designs enable distributed temperature and strain monitoring.
- Medical Devices:Surgical laser systems require precise wavelength isolation for tissue ablation and diagnostic imaging platforms.
Telecommunications anchors volume procurement. Medical device integration is climbing the fastest as surgical laser OEMs qualify fiber-optic filtering for FDA-cleared systems.
Technology:
Manufacturing maturity divides thin-film coating's established throughput from emerging microstructure photonic approaches where thermal stability and miniaturization justify premium positioning.
- Thin-Film Coating:Ion-assisted electron-beam deposition builds interference stacks with 50-200 layers on synthetic fused silica substrates. Japanese and German wafer suppliers concentrate input supply, exposing coaters to price volatility.
- Microstructure Photonic:Femtosecond laser inscription creates refractive index modulations directly in fiber cores. Industrial LiDAR manufacturers and surgical device OEMs are qualifying these designs for thermal cycling resistance.
- Fabrication Techniques:Hybrid processes combine coating and etching for specialized polarization control.
- Grating:Phase-mask or point-by-point inscription generates periodic refractive index structures for narrowband filtering.
Thin-film coating holds the production base. Microstructure photonic methods are gaining share fastest in medical and sensing segments where insertion loss tradeoffs are acceptable.
End User:
Customer-type concentration shapes channel strategy: telecom providers consolidate through direct procurement while research institutions and healthcare facilities rely on distributor technical support.
- Telecom Providers:State-owned carriers and cloud hyperscalers specify DWDM filter arrays with dedicated optical component engineering staff. Chinese operators in Beijing and Shanghai bypass distributor channels for volume transactions.
- Research Institutions:Universities and national laboratories require custom wavelength specifications and extended characterization data. North American facilities maintain specialized thin-film deposition partnerships for prototype volumes.
- Healthcare Facilities:Hospital systems and surgical centers integrate filters into laser systems through OEM device manufacturers.
- Industrial Users:Manufacturing and energy sector operators deploy fiber-optic sensing for structural health monitoring.
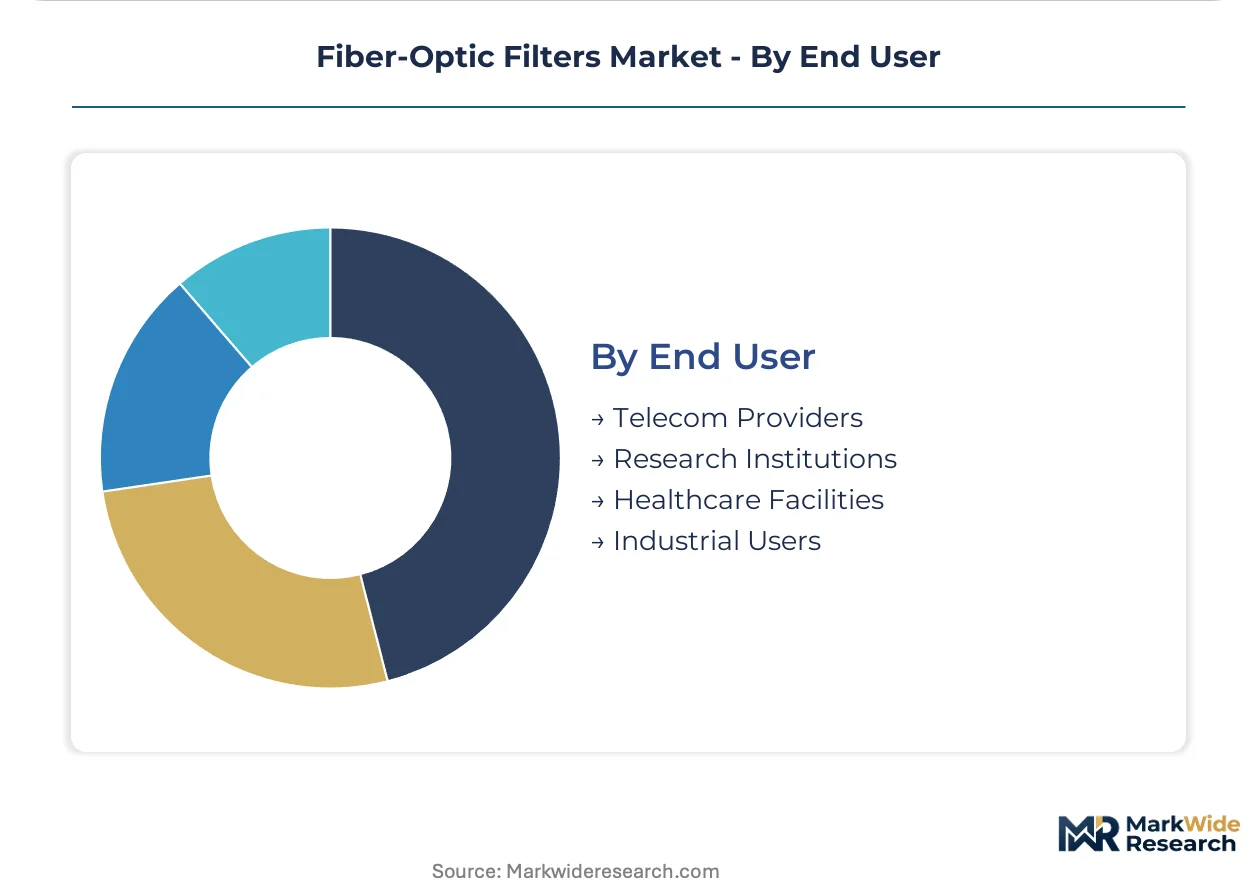
Telecom providers dominate order volumes. Healthcare facility adoption is expanding most quickly as surgical laser platforms proliferate through hospital procurement networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese coating facilities export bandpass filter arrays to North American hyperscale data centers while Japanese substrate suppliers feed thin-film deposition chambers worldwide. This trade corridor concentrates procurement leverage in Beijing and Shenzhen while creating input dependencies for coaters in Germany and the United States.
China
MIIT-mandated 5G backhaul programs and cloud hyperscaler buildouts in Beijing and Shenzhen absorb the majority of domestic bandpass filter output. SAMR oversight of telecom equipment certification tightens wavelength stability specifications for state-owned carrier procurement. The Yangtze River Delta coating cluster around Shanghai supplies DWDM arrays for both domestic infrastructure and export markets.
United States
FCC spectrum management rules for C-band and L-band allocations directly shape filter performance requirements for terrestrial and submarine cable operators. FDA 510(k) clearance pathways enable surgical laser OEMs to integrate fiber-optic filtering into diagnostic and therapeutic devices. The Pacific Northwest photonics corridor hosts thin-film deposition partnerships serving national laboratories and research institutions.
Germany
EU REACH restrictions on hexavalent chromium and cadmium compounds force deposition chemistry reformulation across Baden-Württemberg coating facilities. ECHA compliance timelines extend qualification cycles for new layer materials. The Munich-Stuttgart industrial belt concentrates specialized thin-film suppliers serving European telecom providers and medical device manufacturers.
Japan
METI industrial policy supports synthetic fused silica substrate production that concentrates supply among Osaka and Nagoya suppliers. JIS standards for optical component reliability set benchmarks for thermal drift specifications. The Chubu region wafer fabrication cluster exposes global coaters to input cost volatility when yen-denominated contracts reprice.
India
PLI scheme incentives for domestic telecom equipment manufacturing create localized filter assembly demand that bypasses import tariff structures. TRAI spectrum allocation frameworks shape wavelength planning for 5G backhaul networks. The Bengaluru-Chennai corridor attracts coating facility investments targeting hyperscaler data center procurement in South Asia.
Fiber-Optic Filters Market Competitive Landscape
Listed leaders compete with private specialists across thin-film coating capacity and microstructure photonic design capabilities. The vendor base separates into three tiers: integrated photonics conglomerates with captive deposition chambers, independent coating houses serving research and telecom markets, and femtosecond laser inscription specialists targeting medical and sensing niches. Dominant competitive moves include backward integration into substrate supply and strategic partnerships with CMOS foundries for silicon photonics hybrid integration.
Within the integrated photonics tier, Thorlabs exemplifies vertical control across coating chambers and fiber assembly operations. Newport Corporation anchors North American supply relationships through specialized deposition capabilities. DiCon Fiberoptics, Inc. occupies a distinct position in microstructure photonic designs that address sensing application requirements outside traditional telecom specifications.
| Leading Market Players |
|---|
| Newport Corporation |
| DiCon Fiberoptics, Inc. |
| WL Photonics, Inc. |
| Agiltron Inc. |
| Thorlabs |
| Edmund Optics |
| Alluxa Inc. |
| Spectrogon |
| Reynard |
| Others |
Value Network & Pricing Analysis
Femtosecond laser inscription of microstructure photonic filters is displacing conventional thin-film coating in medical and sensing segments, simultaneously shifting production geography toward precision laser fabrication clusters in Germany and Japan while compressing pricing premiums for thermal-stability-specified components.
Pricing Analysis
400G-to-800G coherent transceiver generation pricing gaps separate legacy DWDM filter arrays from next-generation center-wavelength-stabilized designs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA 510(k)-cleared medical tiers commanding substantial premiums over telecom-standard volumes. Price erosion runs through bandpass filter commoditization as Chinese coating facilities expand ion-assisted deposition throughput. Data center procurement teams exhibit lowest price sensitivity due to direct OEM partnerships, while research institutions face tightening grant-funded budgets.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Yokohama and Busan to Long Beach elevate inbound logistics costs for synthetic fused silica substrate shipments. Coating chamber supply concentrates in China, Germany, and the United States, drawing from Japanese and German wafer fabrication for fused silica and silicon dioxide inputs. Single-source vulnerability concentrates among Osaka and Nagoya substrate suppliers when yen-denominated contracts reprice. Distribution runs through direct procurement channels for telecom hyperscalers and technical distributors serving research and medical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in fiber-optic filters stems from coherent transmission scaling forcing requalification waves across 400G/800G line rate migrations.
For Market Incumbents: Compound wavelength-selective component portfolios through backward integration into substrate supply and captive ion-assisted deposition capacity additions in the Yangtze River Delta. Microstructure photonic entrants threaten thin-film margin pools in medical sensing; defend through FDA 510(k) pathway acceleration and SAMR certification stacking for Chinese state carrier procurement. For New Entrants and Emerging Players: FDA 510(k) fast-track qualification for surgical laser filter integration offers penetrable white space outside telecom consolidation. Target industrial LiDAR sensing architectures where thermal cycling specifications justify premium positioning against coating-dependent incumbents. Go-to-market leverage rests on femtosecond laser fabrication partnerships with CMOS foundries for silicon photonics hybrid integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thin-film coating houses in Baden-Württemberg facing EU REACH chemistry reformulation capital demands. Five-to-ten year viability favors microstructure photonic specialists with medical device qualification pipelines and silicon photonics bonding capabilities. Signal to watch: IEEE 802.3 requalification cycle compression forcing parallel validation workflows that strain incumbent testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Ion-Assisted Deposition Scale-Up | Thorlabs and Newport Corporation expand chamber throughput to serve MIIT-mandated Chinese 5G backhaul programs. |
| FDA 510(k) Pathway Acceleration | Medical device OEMs integrate fiber-optic filtering into surgical laser systems through streamlined clearance protocols. |
| Silicon Photonics Hybrid Integration | Microstructure photonic filters bond to CMOS platforms enabling chip-scale coherent transceivers with on-board wavelength selection. |
| EU REACH Chemistry Reformulation | Baden-Württemberg coating facilities retool deposition processes to eliminate hexavalent chromium and cadmium compounds. |
| Direct OEM Partnership Consolidation | North American and Chinese hyperscalers bypass distributor channels for wavelength-selective component procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade data, IEEE standards documentation, and SAMR certification records. Interviews with thin-film deposition engineers, data center optical component procurement leads, FDA regulatory affairs specialists, and telecom infrastructure planners inform demand specification trajectories. Bottom-up coating facility capacity modeling triangulates against top-down hyperscaler capex disclosure analysis.
Segmentation dimensions modeled span filter product type, application vertical, manufacturing technology, and end-user archetype across the projection horizon. CAGRs derive from wavelength channel density expansion rates and coherent transceiver shipment trajectories. Forecast inputs incorporate MIIT infrastructure mandate timelines and EPA hazardous chemistry phase-out schedules.
Underlying assumptions cover ion-assisted deposition throughput scaling and femtosecond laser fabrication yield maturation, with deviation risk concentrated in synthetic fused silica substrate supply disruptions and IEEE 802.3 standard revision timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
3D Optical Microscope Market
Optics
Global Enhanced Vision System Market
Optics
Fiber Optic Amplifier Market
Optics
Tunable Laser Market
Optics
Smartphone Camera Lenses Market
Optics
Asia Pacific Fiber Optics Market
Optics
Fiber Optic Development Tools Market
Optics
Liquid Crystal on Silicon Market
Optics
Optical Fiber Market
Optics
Photonics Market
Optics
Optical Telescope Market
Optics
Latin America Optical Imaging Market
Optics
Collimating Lens Market
Optics
Picosecond Lasers Market
Optics
Electro Optics Market
Optics
Germanium Lens Market