
 Liquid Cooling Connector Market | 2026-2036
Liquid Cooling Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Cooling Connector Market Insights
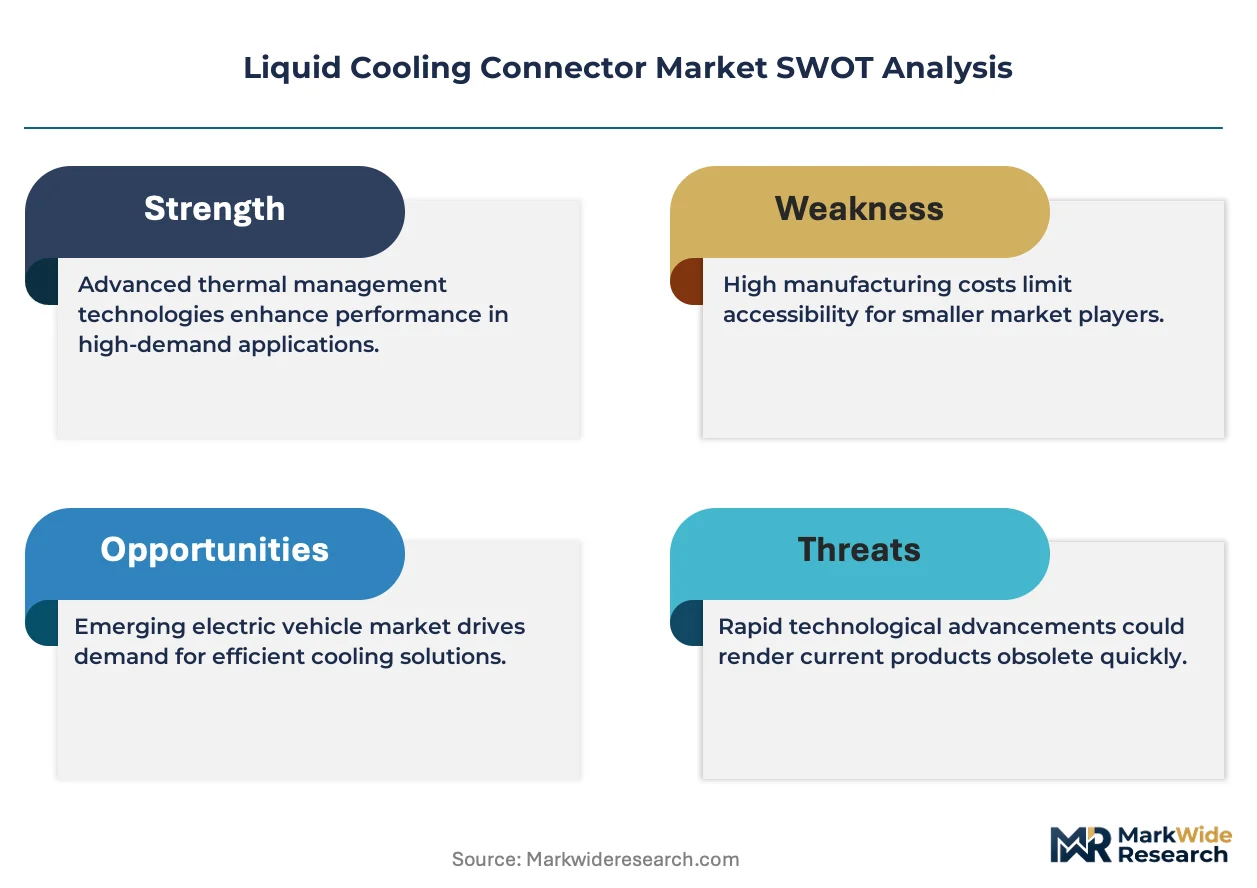
Software-defined thermal management is rebalancing what data center operators purchase, shifting capital toward connector systems that integrate with intelligent monitoring platforms. Parker Hannifin Corporation leverages its fluid power heritage to dominate high-pressure quick disconnect portfolios for hyperscale facilities. TE Connectivity Ltd. anchors its position through R&D intensity in miniature interconnect solutions that serve edge computing enclosures.
Liquid cooling connectors are precision fluid couplings engineered to maintain seal integrity across pressure differentials up to 500 psi while enabling rapid serviceability in dense thermal management loops; they route coolant between cold plates, manifolds, and heat exchangers to sustain processor operating temperatures below thermal throttling thresholds. Quick disconnects command the largest volume share within product type segmentation due to their hot-swappable design reducing server downtime during maintenance cycles. Stainless steel material grades capture premium margin pools as operators prioritize corrosion resistance for long-life coolant loops in mission-critical deployments.
FDA oversight of medical device cooling and EPA energy efficiency mandates for data center infrastructure shape product certification requirements in the United States, while REACH compliance in Europe restricts certain plating chemistries used in brass connector finishes. The EU F-Gas Regulation directly accelerates connector demand by phasing down hydrofluorocarbon-based cooling systems that rely on different sealing architectures. Stakeholders must monitor how ISO thermal management standards evolve to address direct-to-chip cooling densities before committing to next-generation connector form factors.
Market Dynamics
Software-defined thermal management is compressing connector procurement cycles as data center operators prioritize intelligent monitoring integration over standalone hardware specifications. This architectural shift concentrates purchasing power among hyperscale deployers who bundle connector selection with broader thermal infrastructure contracts.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based cooling systems forces operators toward water-based architectures that demand specialized sealing technologies and quick-disconnect compatibility.
- AI training cluster density:Thermal loads exceeding 100 kW per rack in GPU-intensive deployments mandate direct-to-chip liquid cooling loops with precision connector tolerances.
- Northern Virginia corridor concentration:Hyperscale facility construction in this data center cluster generates concentrated demand for high-pressure stainless steel quick disconnects rated for 500 psi service.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings compress margin pools for corrosion-resistant connector grades specified in mission-critical loops.
- Precision machining concentration:Swiss and German specialty manufacturers control tight-tolerance quick-disconnect production, creating supply vulnerability for North American deployers.
- Legacy air-cooling substitution:Immersion cooling architectures eliminate connector-intensive cold plate manifolds entirely in select high-density deployments.
Strategic Opportunities
- Edge computing enclosures:Miniaturized interconnect solutions for distributed AI inference nodes outside hyperscale facilities remain underpenetrated relative to central training clusters.
- India PLI scheme:Domestic data center manufacturing incentives create localized connector demand as operators establish captive production for regional cloud services.
- ISO thermal management standards evolution:Anticipated direct-to-chip cooling density specifications will obsolete current form factors, rewarding early design alignment.
Industry Challenges
- Fluoropolymer seal certification timelines:FDA and EPA parallel review processes for medical device and data center cooling applications extend product qualification cycles.
- Multi-physics simulation expertise:Computational fluid dynamics and finite element analysis skill gaps constrain OEMs optimizing connector geometries for turbulent flow regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Cooling Connector Market |
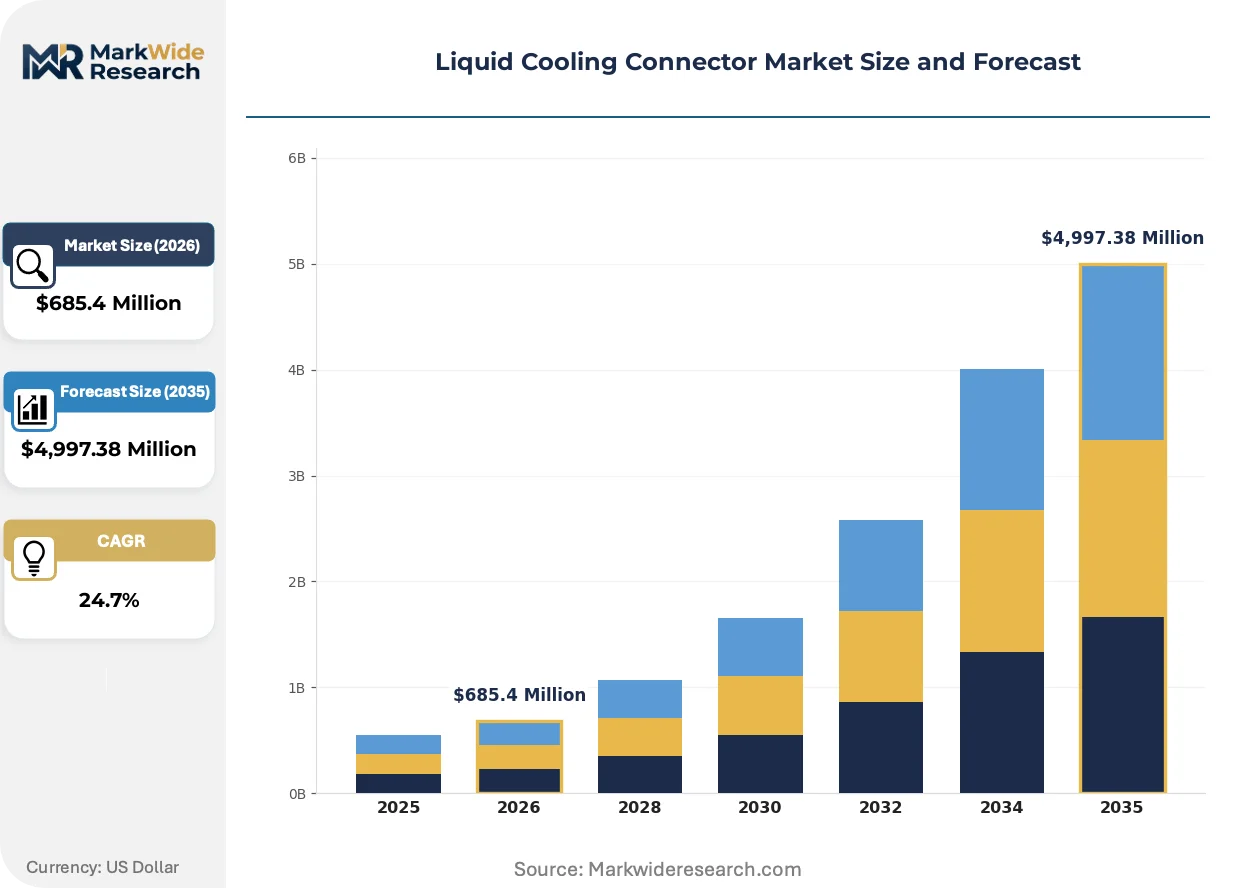
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,997.38 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quick Disconnects, Compression Fittings, Hose Connectors, Bulkhead Fittings Material: Brass, Aluminum, Plastic, Stainless Steel Industry Vertical: Data Centers, Automotive, Aerospace, Electronics Installation Type: On-Premise, Modular, Integrated, Portable |
| Companies Covered | Parker Hannifin Corporation, Aptiv PLC, TE Connectivity Ltd., Eaton Corporation PLC, IDEX Corporation, CEJN AB, Staubli, Colder Product Company, Jonhon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Cooling Connector Market Trends and Innovations
Connector engineering is converging with sensor integration and predictive maintenance platforms, transforming hardware procurement into thermal ecosystem contracting. This integration imperative favors suppliers with software development capabilities alongside precision manufacturing heritage.
Polymer-composite quick disconnects with embedded pressure and temperature sensing is rewriting how operators monitor coolant loop health in real time. Hyperscale deployers in Phoenix and Northern Virginia are specifying these intelligent connectors in new construction. The technology is rewriting service interval economics by enabling condition-based maintenance rather than calendar-driven replacement.
REACH compliance restrictions on hexavalent chromium plating chemistries are forcing brass connector manufacturers toward trivalent alternatives with inferior wear characteristics. European suppliers face reformulation costs and accelerated qualification testing. Stainless steel grades with native corrosion resistance capture preference in REACH-regulated markets despite 40-60% cost premiums.
Specification consolidation among hyperscale buyers is compressing vendor diversity as thermal infrastructure contracts bundle connector procurement with chiller and manifold supply. Traditional distribution channels serving tier-two data center operators face disintermediation. This concentration is most visible in the United States, where Northern Virginia and Phoenix corridor operators negotiate enterprise-wide connector standards across multi-year deployment pipelines.
Liquid Cooling Connector Market Segmentation
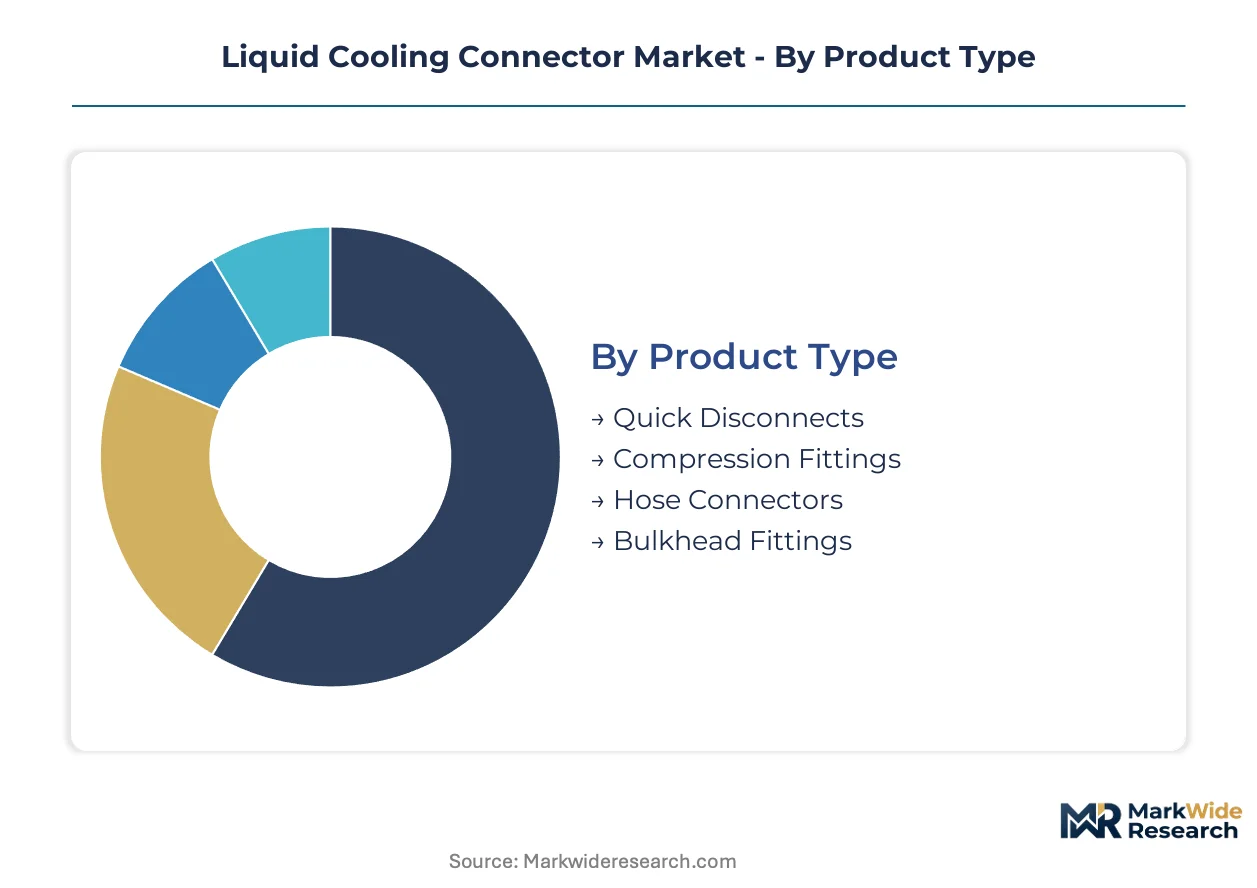
Liquid cooling connector procurement splits along thermal load intensity, coolant chemistry compatibility, and serviceability requirements. Specification choices cascade through pressure ratings, material corrosion resistance, and form factor miniaturization.
Product Type:
Pressure tolerance and hot-swap capability define the specification hierarchy across connector architectures.
- Quick Disconnects:Spring-loaded coupling mechanisms enable tool-free separation under residual pressure up to 500 psi without coolant loss. Hyperscale data centers in Northern Virginia specify these for GPU rack maintenance cycles. AI training cluster density mandates their hot-swappable design.
- Compression Fittings:Ferrule-based sealing systems create permanent, vibration-resistant joints for stationary manifold-to-chiller plumbing. Operators in Phoenix data center corridors favor these for primary distribution loops where disassembly is infrequent. Their zero-leakage reliability offsets longer installation times.
- Hose Connectors:Barbed or push-fit interfaces attach flexible tubing to rigid distribution networks.
- Bulkhead Fittings:Panel-mount designs penetrate server chassis and enclosure walls while maintaining seal integrity.
Mature deployment sits with Compression Fittings. Newer deployment is concentrated in Quick Disconnects.
Material:
Corrosion resistance versus cost tradeoffs segment procurement across coolant chemistry and deployment lifetime expectations.
- Stainless Steel:Austenitic grades 316 and 316L deliver native resistance to glycol-water mixtures and deionized water without protective plating. REACH-regulated European markets absorb 40-60% cost premiums to avoid hexavalent chromium compliance burdens. Mission-critical data center loops specify these for 15-20 year service life.
- Brass:Copper-zinc alloys with trivalent chromium or nickel plating dominate cost-sensitive volume applications. Reformulation costs from REACH restrictions are compressing margin pools for European manufacturers. Edge computing enclosures with shorter depreciation cycles favor this grade.
- Aluminum:Anodized 6061-T6 variants reduce weight in aerospace thermal management systems.
- Plastic:PEEK and polyphenylene sulfide compounds insulate against galvanic corrosion in mixed-metal loops.
Stainless Steel commands premium positioning. Brass retains volume leadership in cost-optimized installations.
Industry Vertical:
Thermal load density and regulatory scrutiny differentiate end-use specification stringency.
- Data Centers:Direct-to-chip cooling architectures demand quick disconnects rated for turbulent flow regimes and frequent service cycles. EU F-Gas Regulation phaseout of hydrofluorocarbon systems is accelerating water-based connector deployments. Northern Virginia and Phoenix corridor construction concentrates procurement volume.
- Automotive:Battery thermal management systems for electric vehicles specify vibration-resistant compression fittings with automotive-grade sealing. OEMs integrate these into powertrain cooling loops for fast-charge thermal stability.
- Aerospace:SWaP-constrained avionics cooling uses miniature stainless steel interconnects with redundant sealing.
- Electronics:Semiconductor manufacturing equipment employs ultra-high-purity connectors for process cooling.
Data Centers drive specification innovation. Automotive applications are expanding most quickly as EV thermal architectures mature.
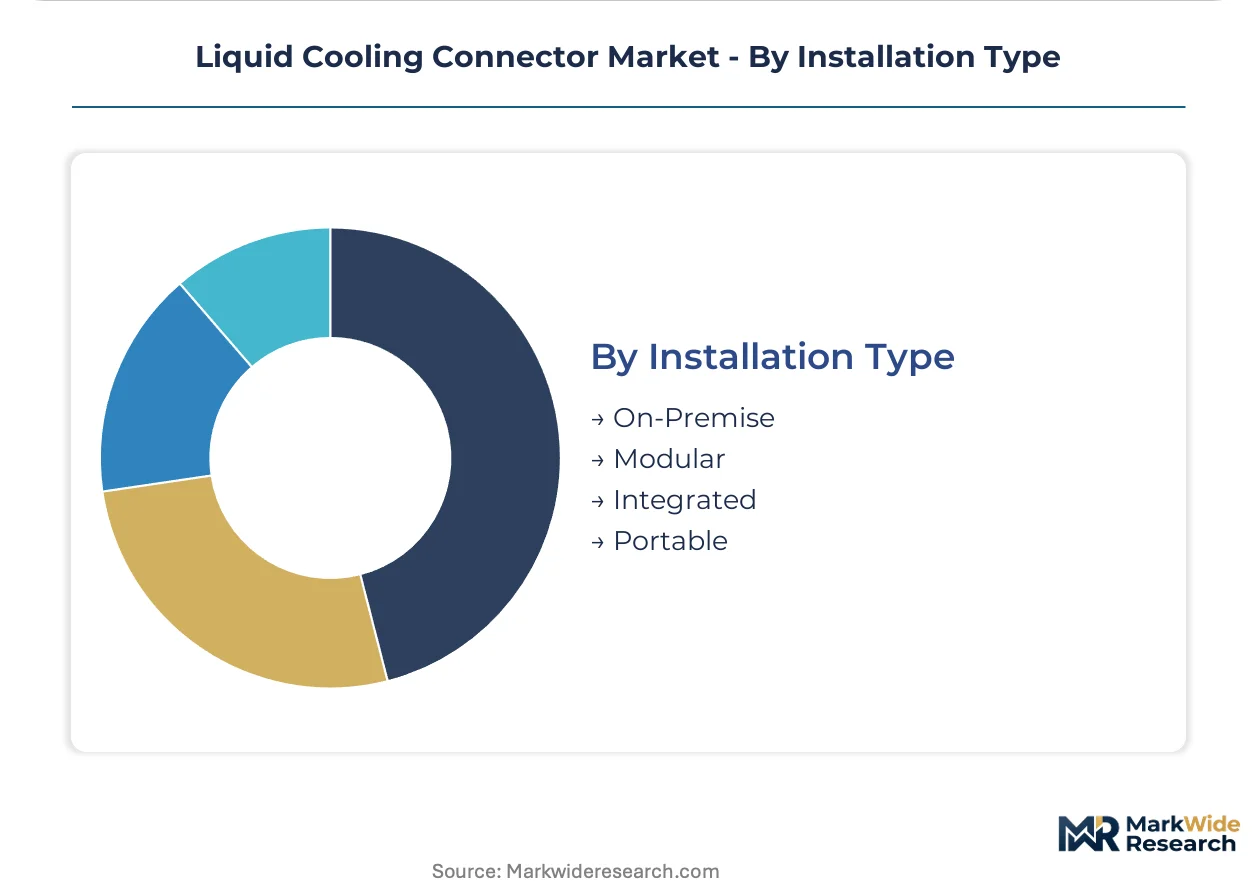
Installation Type:
Capital deployment model and facility lifecycle expectations determine connector integration approach.
- On-Premise:Permanent brazed or welded installations suit enterprise-owned facilities with 20-year depreciation horizons. Custom manifold fabrication accommodates non-standard rack configurations. Financial services and government data centers favor this capital-intensive approach.
- Modular:Pre-assembled skid-mounted cooling units with standardized quick disconnect interfaces enable rapid capacity scaling. Colocation operators in Phoenix deploy these for tenant-specific thermal provisioning. Factory-tested assemblies reduce field commissioning risk.
- Integrated:OEM-supplied server-embedded cooling loops with captive connector specifications.
- Portable:Mobile cooling carts for emergency thermal management and maintenance bypass.
On-Premise installations anchor legacy infrastructure. Modular systems are gaining share fastest among multi-tenant facility operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for precision-machined liquid cooling connectors concentrates in German and Swiss specialty manufacturers, while consumption gravity pulls toward data center construction corridors in the United States, Northern Europe, and East Asia. This geographic split creates supply chain exposure for operators deploying AI training clusters on accelerated timelines.
United States
Hyperscale facility construction in Northern Virginia and Phoenix corridors generates concentrated demand for stainless steel quick disconnects rated for 500 psi service. EPA energy efficiency mandates for data center infrastructure shape product certification requirements. FDA oversight of medical device cooling creates parallel qualification pathways for dual-use connector specifications.
Germany
Swiss and German specialty manufacturers control tight-tolerance quick-disconnect production for European data center operators. REACH compliance restricts hexavalent chromium plating chemistries used in brass connector finishes, forcing reformulation toward trivalent alternatives. Industrial clusters in Baden-Württemberg and Bavaria anchor precision machining capacity for mission-critical thermal management loops.
China
Domestic cloud service providers are expanding liquid cooling deployments to manage thermal loads from AI training clusters. MIIT standards for data center energy efficiency accelerate water-based cooling architecture adoption. Yangtze River Delta and Pearl River Delta manufacturing zones supply cost-optimized connector grades for regional hyperscale construction.
India
The PLI scheme for domestic data center manufacturing creates localized connector demand as operators establish captive production for regional cloud services. CEA regulations on power usage effectiveness drive liquid cooling specification in new facility builds. Maharashtra and Karnataka data center clusters are emerging as procurement concentration points for quick disconnect systems.
Japan
METI carbon neutrality targets for data centers are displacing traditional air-cooling architectures in favor of direct-to-chip liquid loops. JIS standards for thermal management equipment shape connector procurement specifications. Tokyo and Osaka metropolitan areas concentrate demand for miniature interconnect solutions serving edge computing enclosures.
Liquid Cooling Connector Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the liquid cooling connector market. The vendor base separates into three tiers: diversified industrial conglomerates with fluid power heritage, specialized quick-disconnect manufacturers with Swiss-German machining expertise, and regional fabricators serving cost-optimized installations. Strategic moves concentrate on backward integration into fluoropolymer seal production and geographic expansion through distribution partnerships in high-growth data center corridors.
Within the diversified industrial tier, Parker Hannifin Corporation and Eaton Corporation PLC exemplify scale-driven positioning through fluid power heritage. TE Connectivity Ltd. anchors the specialized interconnect segment with R&D intensity in miniature solutions. Among precision machining specialists, CEJN AB and Staubli represent European manufacturing excellence for high-pressure applications.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Aptiv PLC |
| TE Connectivity Ltd. |
| Eaton Corporation PLC |
| IDEX Corporation |
| CEJN AB |
| Staubli |
| Colder Product Company |
| Jonhon |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up Swiss and German machining specialists concentrate tight-tolerance quick-disconnect production, creating supply scarcity that sustains premium pricing for stainless steel grades while compressing margins for brass connector manufacturers facing REACH reformulation costs. This ownership pattern links geographic supply concentration directly to pricing power asymmetries across material tiers.
Pricing Analysis
Margin tightening in brass connector tiers reflects REACH-driven plating chemistry reformulation and trivalent chromium qualification expenses. Three-tier pricing structure across premium stainless steel, standard brass, and economy aluminum grades differentiates by corrosion resistance certification and mission-critical deployment suitability. Cost-down pressure on brass accelerates because European operators absorb native corrosion resistance premiums to avoid hexavalent chromium compliance burdens. Hyperscale data center operators in Northern Virginia and Phoenix corridors show least price sensitivity for 500 psi-rated stainless steel quick disconnects, while edge computing enclosure deployers drive volume through cost-optimized brass specifications.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German specialty manufacturers controlling sub-50-micron tolerance machining for high-pressure quick disconnects. Production gravity centers on Baden-Württemberg and Bavaria industrial clusters, with secondary capacity in China's Yangtze River Delta supplying cost-optimized grades. Raw material dependencies span nickel and chromium for austenitic stainless steel grades, fluoropolymer elastomers for FDA-compliant seals, and precision bar stock for Swiss-style CNC machining. Tariff exposure on European-sourced precision components creates supply risk for North American hyperscale deployers with accelerated AI cluster timelines. Distribution runs through direct thermal infrastructure contracts with chiller and manifold OEMs, disintermediating traditional component distributors serving tier-two operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU F-Gas Regulation creates a barrier-to-entry moat for connector suppliers with pre-qualified water-based cooling architectures and REACH-compliant material formulations.
For Market Incumbents: Anchor market position through backward integration into fluoropolymer seal production and captive precision machining capacity in Baden-Württemberg or Bavaria. Defend against immersion cooling substitution by embedding sensor intelligence into quick disconnect portfolios for condition-based maintenance contracts. Certification investment in parallel FDA and EPA review pathways for medical device cooling applications creates switching costs for dual-use specifications. For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for specialized quick-disconnect suppliers with native REACH-compliant stainless steel offerings and water-based cooling expertise. Target India's PLI scheme corridors in Maharashtra and Karnataka where domestic data center manufacturing incentives create localized demand without established incumbent relationships. Go-to-market through modular cooling skid OEM partnerships bypasses direct hyperscale certification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining specialists with Swiss-German heritage and stranded capacity from automotive thermal management contract losses. Long-term viability hinges on direct-to-chip cooling density specifications in evolving ISO thermal management standards. Watch for F-Gas Regulation phase-down acceleration as inflection signal for water-based connector demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Seal Production | Captive seal supply compresses FDA/EPA qualification timelines for medical and data center cooling applications. |
| Sensor-Embedded Quick Disconnect Development | Polymer-composite designs with pressure and temperature sensing enable condition-based maintenance contracts with hyperscale operators. |
| REACH-Compliant Stainless Steel Grade Expansion | Native corrosion resistance formulations capture European market share as hexavalent chromium plating faces regulatory phaseout. |
| Modular Cooling Skid OEM Partnership | Factory-tested assemblies with standardized interfaces penetrate colocation and edge computing deployment channels. |
| India PLI Scheme Localization | Maharashtra and Karnataka manufacturing presence qualifies for domestic data center production incentives and regional cloud service demand. |
Research Methodology
Document review covered SEC 10-K filings from diversified industrial conglomerates, EU F-Gas Regulation implementation guidance, and REACH compliance documentation for plating chemistry restrictions, complemented by interviews with thermal infrastructure procurement leads at hyperscale data center operators, precision machining plant managers in German industrial clusters, and fluoropolymer seal qualification specialists. Secondary validation drew from customs trade data for stainless steel connector imports, EPA energy efficiency mandate filings, and ISO thermal management standards committee drafts. Bottom-up deployment modeling across Northern Virginia and Phoenix construction pipelines triangulated against top-down hyperscale capex disclosures.
Market size and growth outputs trace to a structured analytical framework spanning product type, material grade, industry vertical, and installation configuration across the projection horizon. CAGRs derive from deployment velocity modeling for AI training cluster density thresholds and F-Gas Regulation phase-down compliance timelines. Industry-specific forecast inputs include GPU rack thermal load trajectories and direct-to-chip cooling penetration assumptions for mission-critical data center loops.
Caveats apply where ISO thermal management standards evolution, nickel and chromium commodity price volatility, or immersion cooling architecture adoption could materially shift the outlook for connector-intensive cold plate deployments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Wire-To-Board Connector Market
Connectors
SATA Connector Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
AS-Interface Market
Connectors
Mexico Connector Market
Connectors
Press Fit Connector Market
Connectors
Cable Connectors and Adapters Market
Connectors
PCI-E Connectors Market
Connectors
USB Type-C Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Middle East Connector Market
Connectors
Underwater Connectors Market
Connectors
Power Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Asia-Pacific Connector Market
Connectors
China Connector Market