
 Fiber Optic Cables for Military & Aerospace Market | 2026-2036
Fiber Optic Cables for Military & Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Cables for Military & Aerospace Market Insights
The EU Green Deal is hardening environmental compliance requirements for defense procurement across European member states, pushing manufacturers toward low-smoke zero halogen cable technologies. Corning Optical Communications LLC leverages its vertically integrated glass manufacturing to sustain cost advantages in polarization-maintaining fiber production. Prysmian Group anchors its competitive position through deep relationships with NATO-aligned defense contractors across Italy and Germany.
Fiber optic cables for military and aerospace applications are thin glass or plastic filaments, typically 125 microns in diameter with specialized coatings, engineered to transmit data via modulated light signals across wavelengths from 850 nm to 1550 nm while withstanding temperature extremes from minus 65°C to 200°C and mechanical stress in tactical deployments. Their primary purpose is to enable high-bandwidth, electromagnetic-interference-immune communication in mission-critical defense and aviation systems where copper cabling fails. Single-mode fiber dominates long-haul secure data transmission applications due to its minimal signal attenuation of 0.2 dB per kilometer, while multi-mode fiber competes aggressively in avionics backplanes where shorter distances and easier termination offset bandwidth limitations. Armored technology leads procurement volumes for battlefield-deployed systems, whereas ultra bend insensitive variants represent the fastest-growing technology segment as unmanned aerial vehicle designers demand tighter cable routing in constrained airframes.
The U.S. Department of Defense mandates MIL-PRF-49291 qualification for all tactical fiber deployments, while the FAA enforces DO-160G environmental standards for commercial-military hybrid aircraft, and NATO's STANAG 4754 governs interoperability requirements for coalition force communications equipment. These frameworks shape everything from raw material selection to testing protocols, effectively creating a two-tier market split between qualified suppliers and commercial-grade producers. Stakeholders must monitor how emerging quantum encryption standards will redefine fiber security specifications before retrofit cycles commence.
Market Dynamics
Defense procurement officers are consolidating vendor pools around qualified suppliers capable of delivering polarization-maintaining fiber with MIL-PRF-49291 traceability, compressing the competitive landscape into a two-tier structure split between certified military-grade producers and commercial fiber houses.
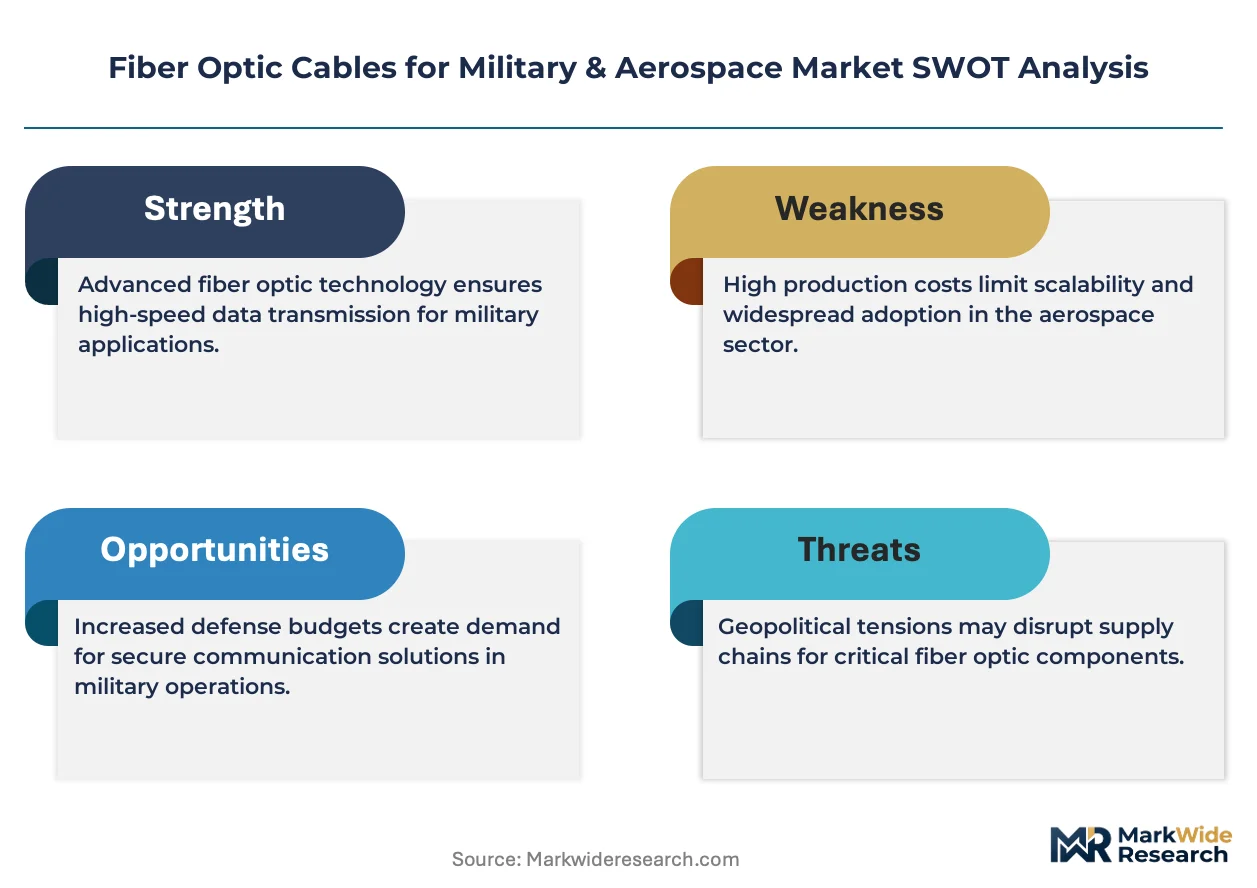
Growth Catalysts
- Unmanned Aerial Vehicle Proliferation:Defense contractors in the United States are specifying ultra bend insensitive fiber for constrained drone airframes where tight cable routing is essential.
- EU Green Deal Procurement Mandates:European defense ministries are hardening material specifications to favor low-smoke zero halogen cable technologies in sustainable supply chain frameworks.
- Satellite Communications Modernization:Japan and Germany are deploying single-mode fiber infrastructure for next-generation radar and secure data transmission systems.
Market Restraints
- Raw Material Concentration:High-purity silica sand and specialized germanium doping precursors concentrate among limited specialty chemical suppliers.
- Qualification Timeline Friction:MIL-PRF-49291 and DO-160G certification cycles extend 18-36 months, freezing out commercial-grade producers from tactical procurement streams.
- Copper-Cable Substitution in Cost-Constrained Segments:Legacy avionics retrofits in non-mission-critical zones retain shielded twisted pair for budget compliance.
Strategic Opportunities
- Quantum Encryption Infrastructure:Emerging quantum key distribution standards are creating specification white space for fiber manufacturers with photon-loss engineering capabilities.
- NATO Interoperability Procurement:STANAG 4754-aligned coalition force communications equipment is opening standardized volume contracts across Italy, Germany, and Poland.
- Commercial-Military Hybrid Aircraft:FAA DO-160G certification pathways are enabling dual-use fiber suppliers to bridge civil aviation and defense procurement channels.
Industry Challenges
- Specialized Splicing Technician Scarcity:Field termination of armored tactical fiber in minus 65°C conditions requires certified personnel pools that defense contractors struggle to maintain.
- Legacy System Integration Complexity:Hybrid fiber-copper architectures in upgraded platforms demand protocol converters and signal conditioning hardware that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Cables for Military & Aerospace Market |
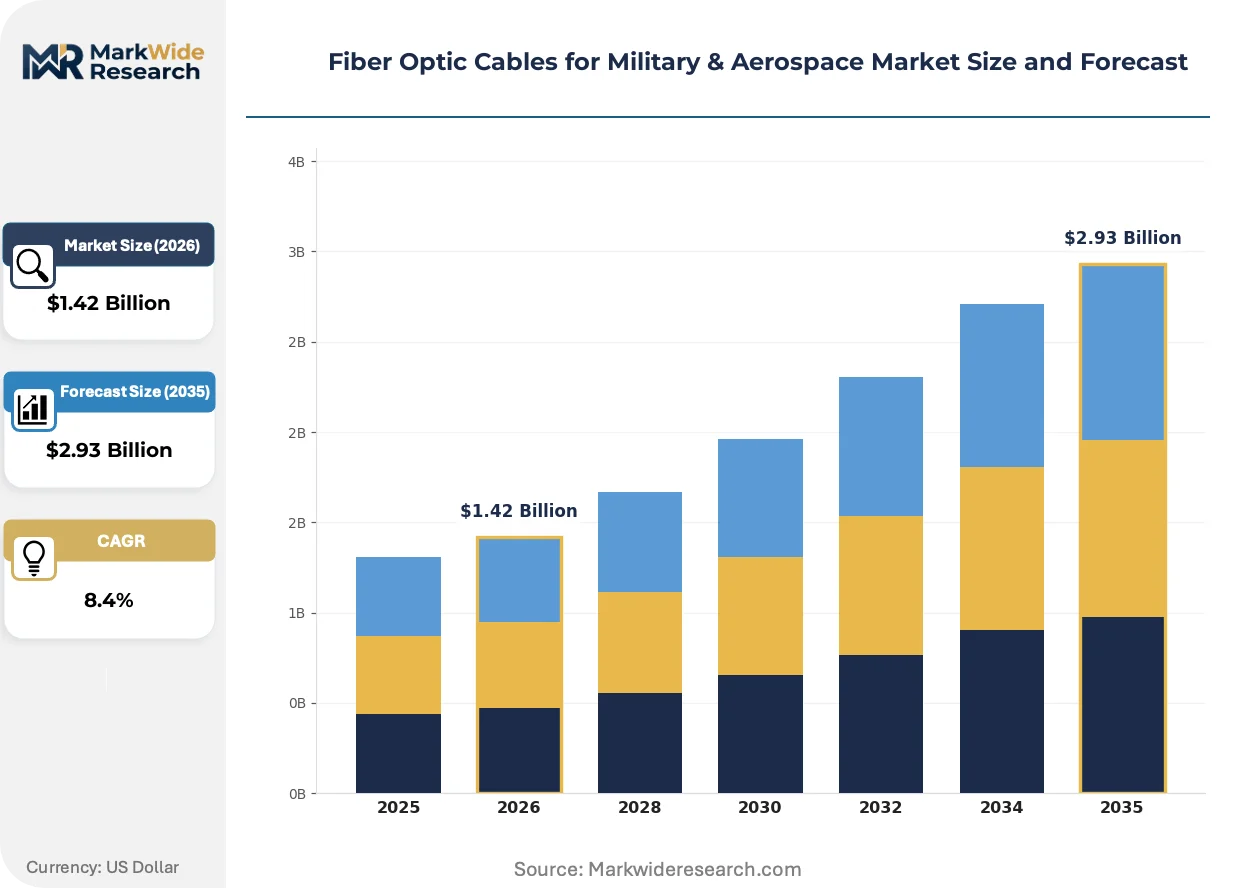
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Polarization Maintaining, Photonic Crystal, Loose Tube Technology: Armored, Non-Armored, Hydrocarbon Resistant, Low Smoke Zero Halogen, Ultra Bend Insensitive Application: Satellite Communications, Avionics, Secure Data Transmission, Radar Systems, Navigation End User: Defense Contractors, Aircraft Manufacturers, Space Agencies, System Integrators |
| Companies Covered | Corning Optical Communications LLC, Prysmian Group, Amphenol FSI, Optical Cable Corporation, W.L. Gore & Associates, Carlisle Interconnect Technologies, TE Connectivity, AFL, Radiall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Cables for Military & Aerospace Market Trends and Innovations
Photonic integration and hardened environmental specifications are compressing product development cycles while regulatory frameworks harden material compliance requirements across defense procurement channels.
Ultra bend insensitive fiber is integrating tight-radius routing capabilities into unmanned aerial vehicle airframes where mechanical space constraints previously forced copper compromises. UAV designers at defense primes in the United States and Japan are specifying 5-millimeter bend radius tolerances for flight control harnesses. This fiber variant is integrating into platform architectures that previously accepted signal attenuation trade-offs, eliminating electromagnetic interference vulnerabilities in tactical deployments.
REACH and RoHS material restrictions are forcing reformulation of cable jacket compounds and flame retardant additives across European defense supply chains. The EU Green Deal's sustainable procurement criteria are hardening into binding technical specifications for low-smoke zero halogen alternatives to traditional PVC sheathing. German and Italian defense ministries are responding by qualifying new material platforms ahead of retrofit cycles for naval and ground vehicle communications.
Defense procurement officers are consolidating vendor relationships around qualified suppliers with captive fiber drawing and in-house polarization-maintaining preform manufacturing. Long-term framework agreements with NATO-aligned contractors are displacing spot purchasing for tactical fiber deployments. This concentration is most visible in United States Department of Defense programs where sole-source justification thresholds have risen for qualified cable assemblies.
Fiber Optic Cables for Military & Aerospace Market Segmentation
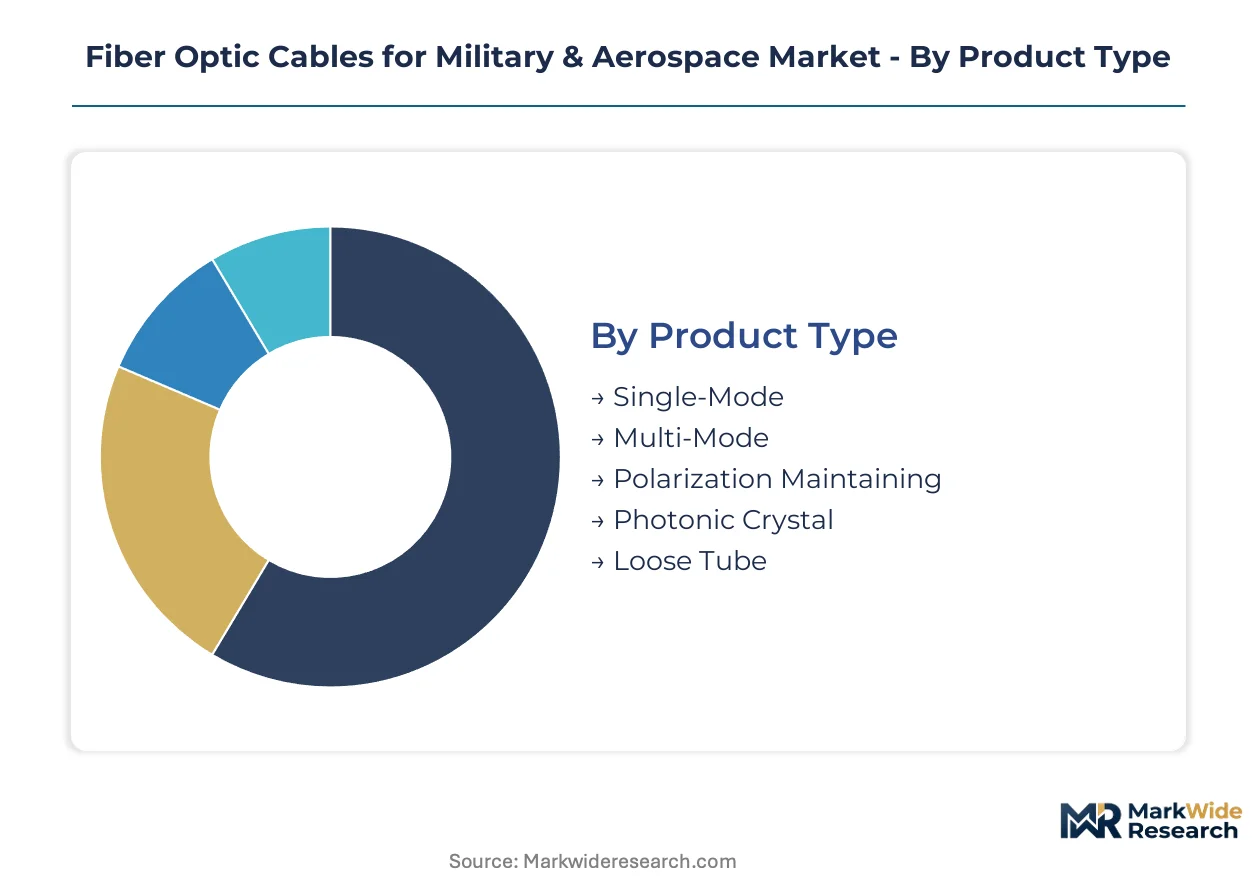
Segmentation in military and aerospace fiber optics reveals how qualification requirements and mission-critical performance tiers fragment procurement channels. Each dimension—product type, technology, application, and end user—carries distinct certification burdens and supply chain concentration patterns that shape vendor selection and pricing architecture.
Product Type:
Supply concentration in specialty fiber drawing favors producers with captive preform manufacturing and in-house polarization-maintaining capabilities.
- Single-Mode:Engineered with 8-10 micron core diameters and 0.2 dB/km attenuation specifications, this fiber dominates long-haul secure data transmission between fixed installations and satellite ground stations in the United States and Germany where signal integrity over distance is paramount.
- Polarization Maintaining:Built on Panda or Bow-Tie stress-rod geometries that preserve linear polarization states, this segment concentrates procurement for interferometric sensors and gyroscopic navigation systems aboard Japanese maritime patrol aircraft where phase stability determines targeting accuracy.
- Multi-Mode:Deploys 50-62.5 micron cores for shorter-reach avionics backplanes where easier field termination offsets bandwidth-distance limitations.
- Photonic Crystal:Structures air-hole lattices around solid cores for extreme bend tolerance in constrained unmanned vehicle architectures.
- Loose Tube:Encapsulates fibers in gel-filled buffer tubes for environmental protection in outdoor tactical deployments across varied terrain.
Single-Mode absorbs the bulk of installed capacity; Photonic Crystal is expanding most quickly.
Technology:
Cost tier differentiation separates battlefield-proven armored assemblies from commercial-grade alternatives that fail MIL-PRF-49291 environmental qualification.
- Armored:Integrates stainless steel interlock or corrugated aluminum sheathing over Kevlar strength members, this technology leads procurement volumes for ground vehicle and dismounted soldier communications in NATO expeditionary forces where crush resistance and rodent protection extend service life in harsh terrain.
- Ultra Bend Insensitive:Deploys trench-assisted refractive index profiles enabling 5-millimeter bend radii without macro-bending loss, this segment is gaining share fastest in UAV flight control harnesses at U.S. defense primes where mechanical space constraints previously forced copper compromises.
- Low Smoke Zero Halogen:Replaces halogenated flame retardants with metal hydroxide fillers to meet EU Green Deal procurement mandates for reduced toxicity in enclosed naval compartments.
- Hydrocarbon Resistant:Formulates jacket compounds with enhanced chemical stability for fuel-exposed aerospace engine nacelle routing.
- Non-Armored:Serves benign-environment installations in fixed command centers where mechanical protection is provided by conduit infrastructure.
Armored technology commands the largest qualified supplier base; Ultra Bend Insensitive is climbing the fastest as drone architectures proliferate.
Application:
Application-driven segmentation reflects how electromagnetic threat environments and bandwidth requirements concentrate procurement around specific platform types.
- Satellite Communications:Demands single-mode infrastructure with radiation-hardened coatings for geostationary and low-earth orbit ground segment links, concentrating investment in Germany and Japan as both nations modernize military satellite constellations for sovereign secure communications.
- Avionics:Requires multi-mode and bend-insensitive fiber for flight deck, engine monitoring, and in-flight entertainment backbones where weight reduction and EMI immunity justify premium pricing over copper in commercial-military hybrid aircraft certified to FAA DO-160G.
- Secure Data Transmission:Encompasses tactical fiber optic networks for command post and forward operating base communications where tap-proof optical signaling replaces copper vulnerabilities.
- Radar Systems:Deploys polarization-maintaining fiber for phased array antenna beamforming networks requiring phase coherence.
- Navigation:Integrates fiber optic gyroscopes into inertial measurement units for GPS-denied positioning aboard submarines and strategic aircraft.
Satellite Communications anchors current procurement volumes; Avionics is gaining share fastest as commercial-military hybrid platforms multiply.
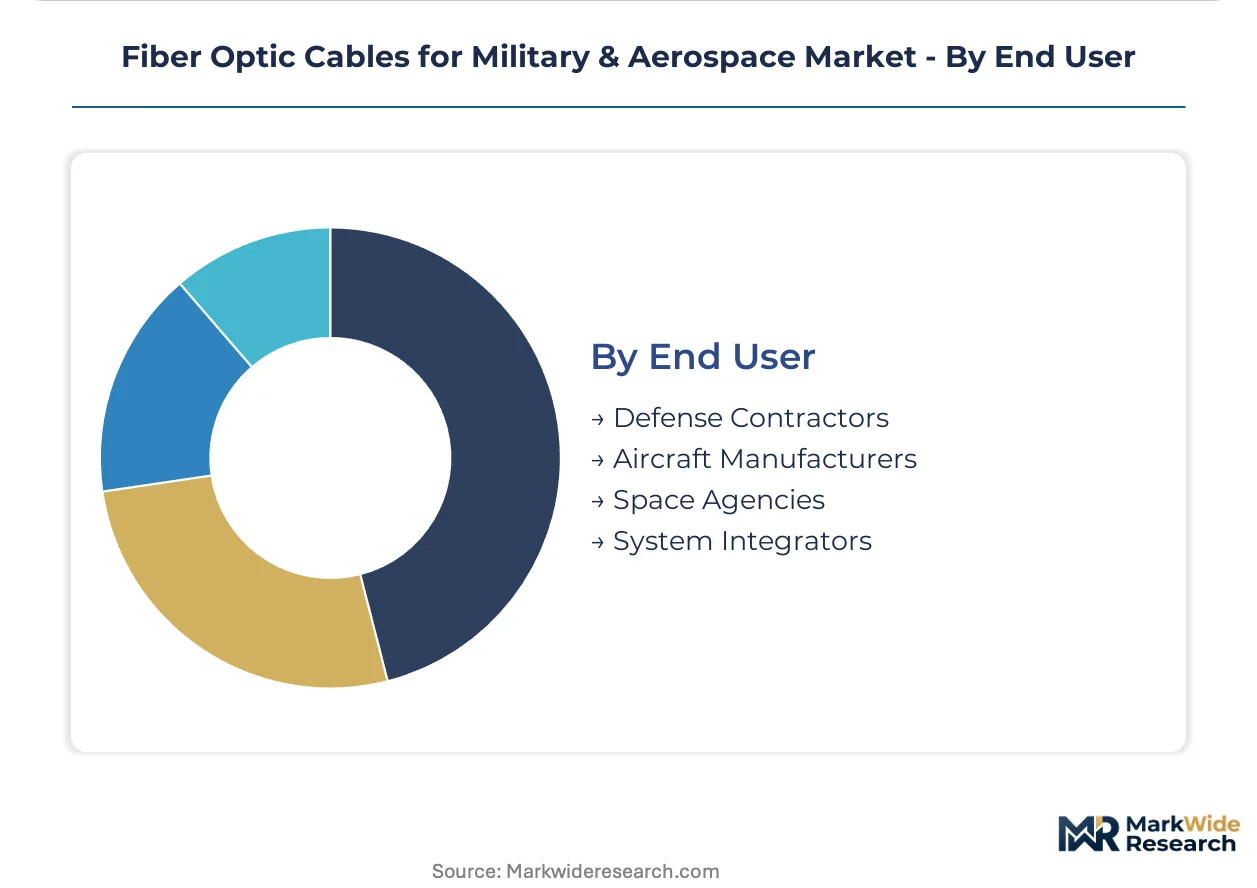
End User:
Customer type segmentation reveals how procurement consolidation around qualified suppliers has compressed vendor pools for each buyer category.
- Defense Contractors:Prime systems integrators in the United States—Lockheed Martin, Raytheon, Northrop Grumman—drive polarization-maintaining and armored fiber specifications through sole-source framework agreements that freeze out commercial-grade producers lacking MIL-PRF-49291 traceability.
- Aircraft Manufacturers:Boeing and Airbus Defense and Space divisions specify DO-160G-qualified fiber for dual-use platforms serving NATO and allied air forces, creating bridge opportunities for civil aviation suppliers with defense certification pathways.
- Space Agencies:NASA, ESA, and JAXA procure radiation-tolerant fiber for satellite bus and payload applications where orbital lifetime requirements exceed terrestrial standards.
- System Integrators:Mid-tier contractors aggregate fiber assemblies for vehicle retrofit and base infrastructure programs where spot purchasing persists.
Defense Contractors absorb the bulk of qualified supplier capacity; Aircraft Manufacturers are expanding most quickly as dual-use certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in North American and European facilities serving defense primes, while consumption patterns track modernization cycles across NATO-aligned militaries and allied Pacific nations. Qualified suppliers cluster near major aerospace manufacturing corridors to satisfy MIL-PRF-49291 traceability requirements.
United States
Defense contractors at Lockheed Martin, Raytheon, and Northrop Grumman drive armored fiber procurement for next-generation avionics platforms. The FAA enforces DO-160G environmental standards for commercial-military hybrid aircraft, hardening qualification pathways. Manufacturing concentrates in California's aerospace corridor and Texas defense clusters where sole-source framework agreements dominate tactical procurement.
Germany
Single-mode fiber demand accelerates for satellite ground station modernization and secure radar infrastructure under sovereign communications initiatives. The EU Green Deal mandates low-smoke zero halogen cable specifications for naval and ground vehicle programs. Production centers in Bavaria and North Rhine-Westphalia serve NATO-aligned defense contractors with STANAG 4754-qualified assemblies.
Japan
Maritime patrol aircraft programs specify polarization-maintaining fiber for interferometric navigation systems requiring phase stability. METI coordinates domestic supplier qualification for radiation-hardened satellite communications infrastructure. Industrial concentration in the Chubu region around Nagoya supports precision fiber drawing for aerospace gyroscopic applications.
United Kingdom
BAE Systems and Airbus Defence and Space drive dual-use fiber procurement bridging civil aviation and military certification pathways. Ministry of Defence procurement frameworks emphasize supply chain resilience for tactical communications equipment. Manufacturing clusters in the Midlands and Southwest England focus on armored cable assemblies for expeditionary force deployments.
Italy
Naval modernization programs under NATO interoperability standards create standardized volume contracts for low-smoke zero halogen fiber systems. Prysmian Group anchors domestic production capacity with deep relationships across European defense ministries. Procurement concentrates in Rome and Milan corridors serving Mediterranean fleet communications infrastructure.
Fiber Optic Cables for Military & Aerospace Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive preform manufacturing and in-house polarization-maintaining capabilities. Defense procurement consolidation has compressed vendor pools around qualified suppliers holding MIL-PRF-49291 traceability, creating a two-tier market split between certified military-grade producers and commercial fiber houses. Three archetypes dominate: glass science specialists with backward integration into silica purification, cable assembly integrators with NATO-aligned defense relationships, and precision photonics engineers serving navigation and sensor applications. Competitive moves center on sole-source framework agreements with U.S. Department of Defense programs and capacity expansion for ultra bend insensitive fiber targeting UAV architectures.
Among North American specialists, Corning Optical Communications LLC and W.L. Gore & Associates exemplify the glass science and materials engineering archetypes respectively, while Prysmian Group represents European cable integration capabilities. These three occupy positions defined by their underlying technical capabilities rather than scale alone. Corning's captive fiber drawing and preform manufacturing anchor its cost position in polarization-maintaining production. Gore's materials science heritage situates it within performance polymer jacketing for extreme environments. Prysmian's NATO-aligned relationships across Italy and Germany exemplify the defense contractor integration model. Each represents a distinct path to qualification in a market where certification timelines freeze out commercial-grade competitors.
| Leading Market Players |
|---|
| Corning Optical Communications LLC |
| Prysmian Group |
| Amphenol FSI |
| Optical Cable Corporation |
| W.L. Gore & Associates |
| Carlisle Interconnect Technologies |
| TE Connectivity |
| AFL |
| Radiall |
| Others |
Pricing and Supply Chain Analysis
Certified splicing technician pools in the United States and Germany drive labor-cost differentials that widen pricing-tier spreads between MIL-PRF-49291-qualified assemblies and commercial-grade alternatives. Defense contractors absorb premium field-service costs for armored tactical deployments, while aircraft manufacturers negotiate volume discounts on DO-160G-certified harnesses for dual-use platforms.
Pricing Analysis
Cost-down pressure on standard-grade multi-mode fiber accelerates because commercial avionics retrofits retain copper in budget-constrained segments. Contract-based long-term offtake agreements dominate procurement, with price differentiation resting on certification grade and volume scale. Premium polarization-maintaining fiber commands widest spreads due to captive preform manufacturing scarcity. System integrators exhibit highest price sensitivity; defense primes show lowest.
Supply Chain Analysis
Freight cost volatility from high-purity silica sand origins in the United States and specialized germanium doping precursor shipments from Germany shapes landed cost structures for fiber drawing facilities. Supply concentrates in the United States, Germany, and Japan, drawing from specialty chemical feedstocks, precision glass preforms, and armored cable jacket compounds. Single-source vulnerability in qualified polarization-maintaining preform manufacturing elevates disruption risk. Distribution runs through sole-source framework agreements with NATO-aligned defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained qualified vendor pools prop pricing power for certified military-grade producers, with MIL-PRF-49291 traceability timelines creating durable capacity bottlenecks that freeze commercial-grade competitors from tactical procurement streams.
For Market Incumbents: Deploy sole-source framework agreement extensions to lock NATO-aligned defense contractors into multi-year polarization-maintaining fiber commitments before emerging photonic crystal specialists achieve qualification. Deepen backward integration into captive silica purification to defend margin position against raw material concentration risks from limited germanium doping precursor suppliers. For New Entrants and Emerging Players: Digital-channel qualification support platforms offer lowest-friction entry vectors for mid-tier system integrators seeking spot-purchased fiber assemblies for vehicle retrofit programs. Target commercial-military hybrid aircraft manufacturers in Italy and the United Kingdom where FAA DO-160G certification pathways bridge civil aviation suppliers into defense procurement channels with shorter timeline friction than pure tactical qualification. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated glass science specialists given quantum encryption infrastructure specification white space opening before retrofit cycles commence. Acquisition target archetype: precision photonics engineers with in-house polarization-maintaining capabilities and existing METI or ESA radiation-hardened fiber relationships. Signal to watch: emerging quantum key distribution standards redefining fiber security specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Investment Acceleration | MIL-PRF-49291 traceability compresses vendor pools around certified producers. |
| Backward Integration into Silica Purification | Captive high-purity sand processing defends cost position against specialty chemical supplier concentration. |
| Ultra Bend Insensitive Capacity Expansion | 5-millimeter bend radius tolerance meets UAV flight control harness demand from U.S. defense primes. |
| EU Green Deal Material Reformulation | Low-smoke zero halogen alternatives to PVC sheathing qualify for German and Italian naval procurement. |
| Quantum Encryption Engineering Partnership | Photon-loss capabilities position suppliers for emerging quantum key distribution infrastructure standards. |
Research Methodology
Defense procurement databases, FAA certification registries, and NATO STANAG qualification records formed the secondary backbone, cross-referenced with primary interviews with fiber optic cable program managers, defense contractor procurement officers, and specialized splicing technician certification bodies. Bottom-up volume builds across product type, technology, application, and end-user segments triangulated against top-down defense budget allocation analysis.
Historical trendline analysis of satellite communications modernization cycles and unmanned aerial vehicle procurement trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include fiber mode type, armor technology grade, platform application, and customer qualification tier. CAGRs derived from elasticity-adjusted deployment curves incorporating EU Green Deal compliance timelines and quantum encryption specification emergence.
The model holds under sustained defense modernization spending and stable qualification timeline structures; deviation in tariff exposure on germanium doping precursors or accelerated quantum cryptography standardization would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Power and Signal Cables Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
UK Cables Market
Cables
Sensing Cable Market
Cables
HVDC Cables Market
Cables
High-Temperature Superconducting Cables Market
Cables
Copper Stranded Wire Market
Cables
Europe Wire and Cable Market
Cables
Sensor Cable Market
Cables
Aluminium Battery Cable Market
Cables
Medium Voltage Cables Market
Cables
Global Ethernet Cable Market
Cables
Ethernet Converters Market
Cables
Cable Management System Market
Cables
Active Optical Cable Market
Cables
Copper Cable Market