
 EDM Wires Market | 2026-2036
EDM Wires Market Size, Share, and Industry Trends Forecast 2026-2036
EDM Wires Market Analysis
The EU Green Deal is realigning material sourcing priorities across European EDM wire supply chains. Mitsubishi Electric Corporation leverages captive metallurgy expertise to control brass and copper wire purity grades. Sumitomo Electric Industries Ltd. anchors Asian supply through integrated drawn-wire operations spanning parent metal to finished spool. Berkenhoff GmbH dominates European coated-wire segments with specialized diffusion-annealing capabilities.
EDM wires are consumable metallic electrodes—typically brass, copper, or zinc-coated compositions ranging from 0.05 mm to 0.30 mm diameter—delivered on precision-wound spools for CNC wire electrical discharge machining. The wire functions as a moving electrode that erodes conductive workpiece material through controlled spark erosion, enabling sub-5-micron accuracy in hardened steels and exotic alloys. Brass wires occupy the mature volume tier where commodity pricing compresses margin pools across standard mold-making applications. Copper wires lead aerospace and medical device segments where conductivity optimization reduces machining time per part. Wire EDM technology sustains the largest installed base, though fast hole EDM grows fastest in turbine blade and cooling channel drilling.
REACH in Europe and EPA guidelines in the United States restrict heavy-metal content in wire coatings and spent-wire disposal streams. Japan's METI oversees JIS standards that define tensile strength and elongation tolerances for precision-grade consumables. Stakeholders must monitor evolving substance restrictions and recycling infrastructure investments as sustainability compliance becomes inseparable from supplier qualification criteria.
Market Dynamics
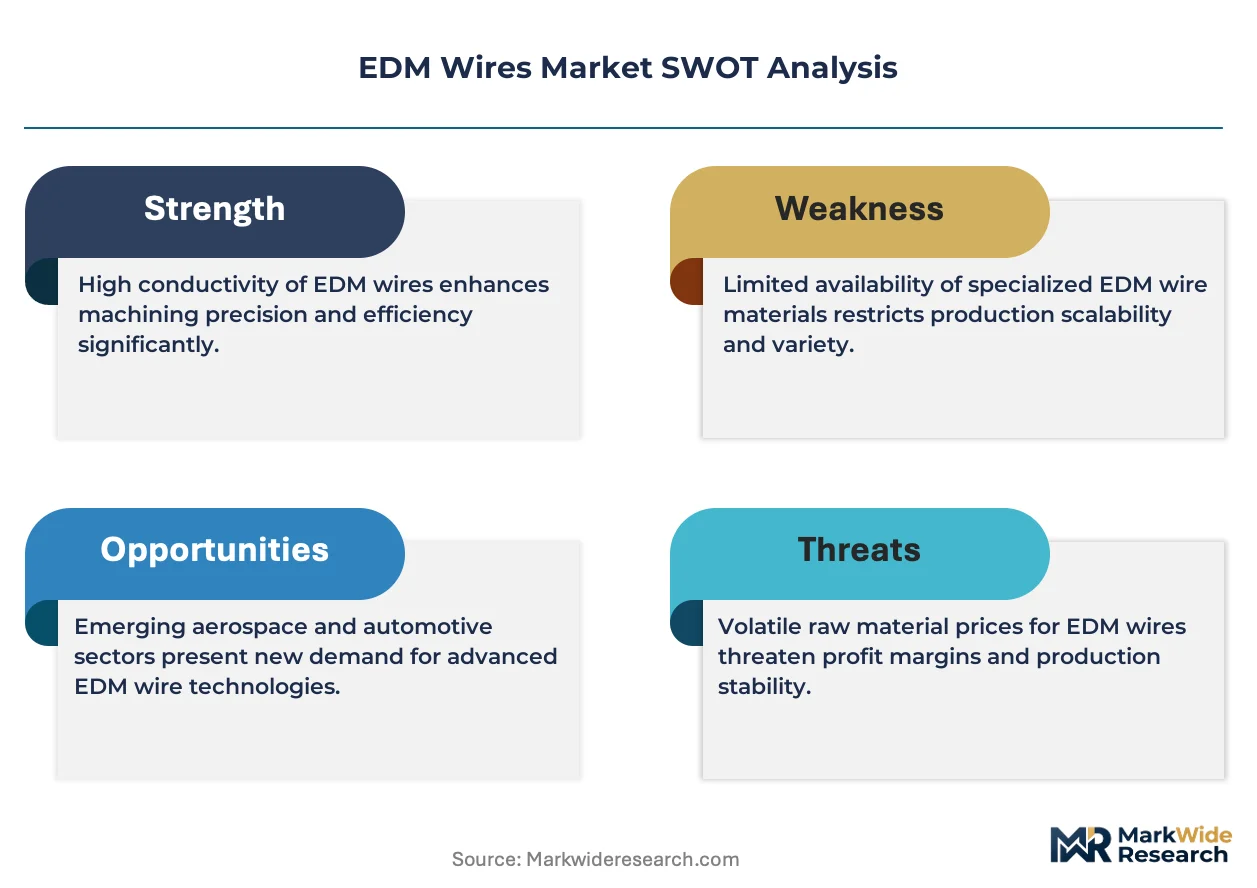
REACH compliance is forcing European wire manufacturers to reformulate zinc coatings and brass alloys away from cobalt-bearing compositions, compressing margin pools while opening premium positioning for certified low-heavy-metal alternatives.
Growth Catalysts
- Aerospace component complexity:Turbine blade cooling channels and fuel injector nozzles demand sub-5-micron tolerances achievable only through wire EDM processes, expanding consumption of high-conductivity copper wires.
- EU Green Deal material mandates:The framework's circular economy requirements accelerate investment in closed-loop wire recycling infrastructure across Germany and the Netherlands.
- Medical device miniaturization:Orthopedic implant manufacturers in Switzerland and the United States deploy precision-grade brass wires for machining cobalt-chrome and titanium alloys.
Market Restraints
- Copper price volatility:LME copper futures swings above 15% annually compress wire producer hedging effectiveness and destabilize contract pricing.
- Supply concentration in Asian drawn-wire capacity:Parent metal refining and intermediate wire drawing cluster in China's Jiangsu and Zhejiang provinces, creating single-source vulnerability.
- Technical ceiling on ultra-fine diameters:Sub-0.05 mm brass wires exhibit tensile strength degradation and spool winding defects that limit deployment in micro-EDM applications.
Strategic Opportunities
- Underpenetrated Indian precision engineering:Bangalore and Pune tool rooms remain dependent on imported coated wires, creating local manufacturing partnership openings.
- Hybrid additive-subtractive workflows:Convergence of directed energy deposition with wire EDM finishing creates demand for specialized annealed wires that withstand thermal cycling.
- Japan's METI green procurement guidelines:Public-sector manufacturing incentives favor suppliers with verified carbon footprints and domestic recycling partnerships.
Industry Challenges
- Electrode wire metallurgy expertise gap:Fewer than twelve European facilities maintain diffusion-annealing capabilities for coated-wire production, constraining capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous REACH, RoHS, and JIS compliance testing extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EDM Wires Market |
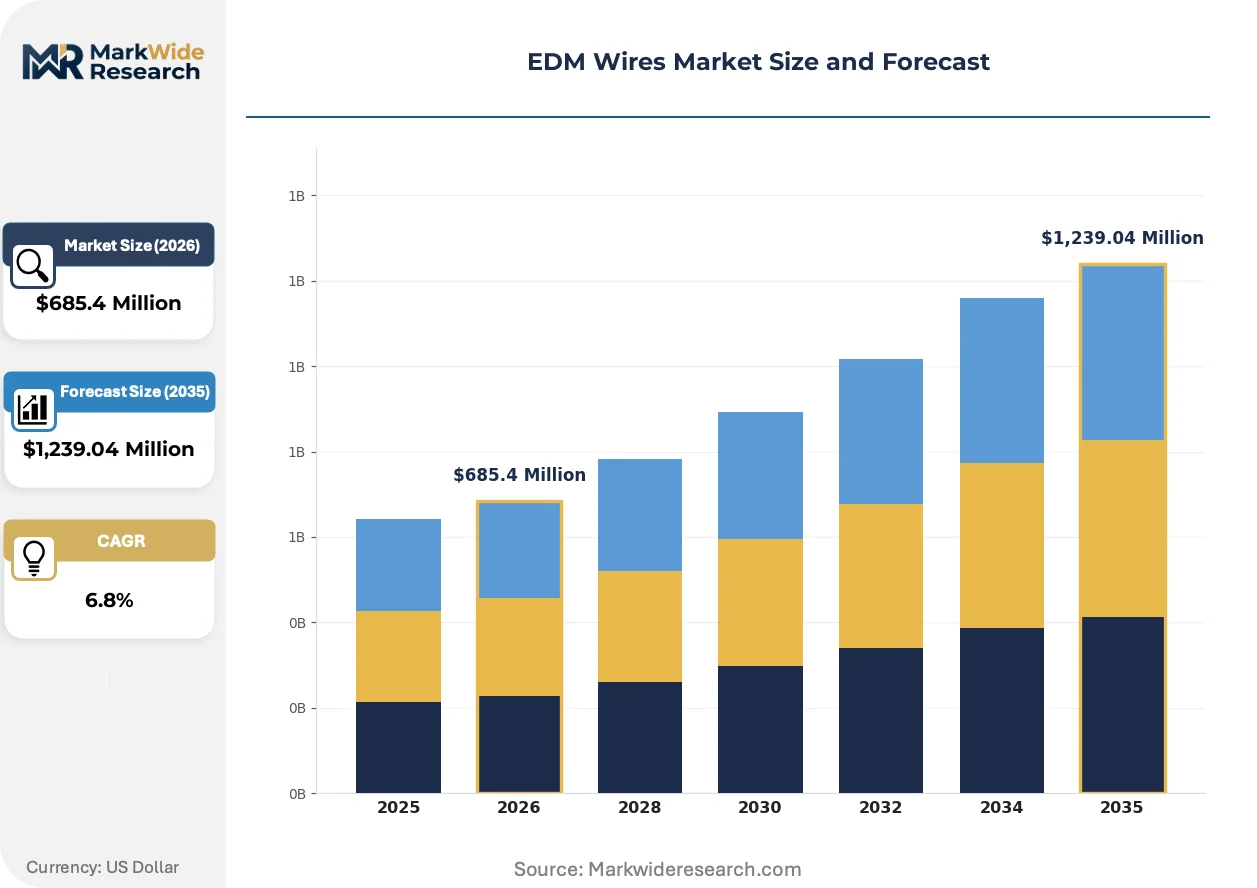
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Wires, Copper Wires, Brass Wires, Steel Wires Application: Mold Making, Tool Making, Aerospace Component, Automotive Parts End User: Manufacturing, Aerospace, Electronics, Medical Device Technology: Wire EDM, Sink EDM, Fast Hole EDM, Laser EDM |
| Companies Covered | Mitsubishi Electric Corporation, Sumitomo Electric Industries Ltd., Sodick Co., Ltd., Makino Milling Machine Co., Ltd., Oki Electric Cable Co., Ltd., Hitachi Metals Ltd., Novotec BV, Berkenhoff GmbH, Powerway Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EDM Wires Market Emerging Trajectories
Wire surface engineering and digital process monitoring are compressing machining cycle times while regulatory substance restrictions are redefining alloy permissible limits across major manufacturing jurisdictions.
Diffusion-annealed coated wires with gradient zinc layers are integrating into high-speed EDM systems to reduce electrode wear rates and stabilize spark gap conditions. Aerospace tier-one suppliers in Germany and France adopt these formulations for Inconel and titanium alloy machining. The technology is integrating quality control functions previously requiring offline measurement, collapsing inspection bottlenecks in automated cell configurations.
REACH Annex XVII restrictions on nickel and cobalt compounds in consumer-facing applications are extending to industrial consumables through ECHA guidance documents issued in 2023-2024. Wire producers reformulate brass master alloys and zinc coating baths to eliminate restricted substance thresholds. Medical device and food-contact mold segments in Italy and Spain face accelerated compliance deadlines, pushing qualified suppliers toward premium pricing tiers.
Consolidated procurement through integrated die-mold service providers is displacing spot purchasing from individual job shops across the Aachen-Stuttgart corridor. Large automotive stamping houses now contract directly with wire manufacturers for annual volume commitments, bypassing traditional distributor networks. This concentration is most visible in Germany, where three precision engineering clusters account for disproportionate European EDM wire consumption.
EDM Wires Market Segmentation
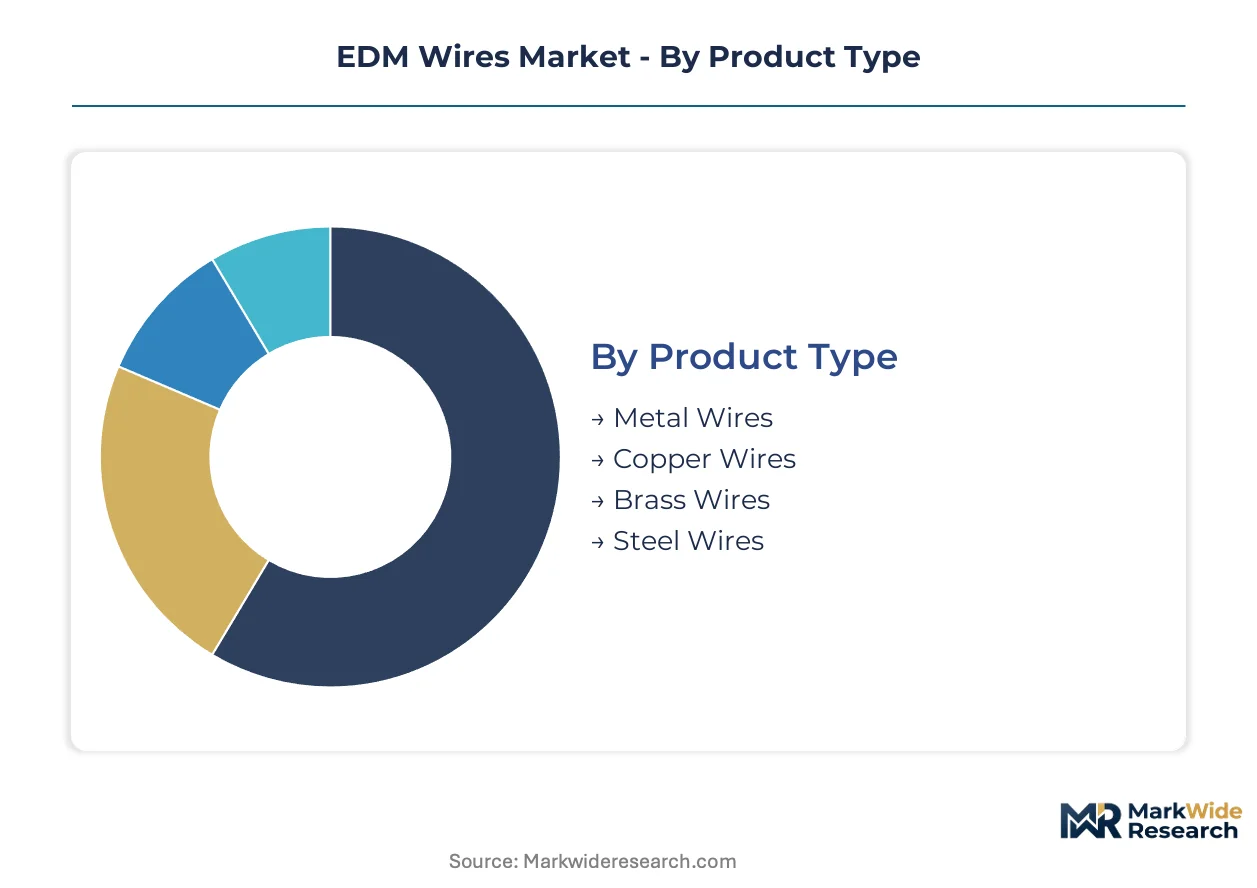
EDM wire selection hinges on conductivity requirements, workpiece hardness, and spark gap stability. Upgrade cycles vary dramatically across product tiers, with high-performance coated wires displacing commodity brass on shorter replacement intervals in precision applications.
Product Type:
Replacement cycles compress at the premium tier as diffusion-annealed formulations demonstrate measurable throughput gains over standard brass in high-speed EDM cells.
- Brass Wires:Zinc-copper alloys between 60/40 and 65/35 composition dominate volume consumption across general-purpose mold making. German tool rooms in the Aachen-Stuttgart corridor consume disproportionate tonnage for automotive stamping die production, though margin compression from commodity pricing limits producer profitability.
- Copper Wires:Pure copper electrodes deliver superior conductivity for reduced machining time in aerospace turbine blade and medical implant applications. Swiss orthopedic manufacturers and French aerospace tier-one suppliers specify oxygen-free grades for sub-5-micron tolerance work in titanium and Inconel alloys.
- Metal Wires:Specialty compositions including molybdenum and tungsten variants serve niche applications requiring extreme tensile strength for fine-diameter spooling.
- Steel Wires:Ferrous electrodes address specific rust-resistant requirements and magnetic workpiece compatibility in select European tool-making environments.
Brass wires sit at the top of the volume ranking, with copper wires climbing the fastest as aerospace and medical device specifications tighten.
Application:
Cost tier separation intensifies as automotive stamping houses consolidate procurement through direct manufacturer contracts, bypassing distributor markups.
- Mold Making:Injection mold cavity machining consumes the largest wire tonnage across plastic and die-cast tooling segments. Italian and Spanish food-contact mold producers face accelerated REACH compliance deadlines, pushing qualified suppliers toward premium pricing tiers for low-cobalt formulations.
- Aerospace Component:Turbine blade cooling channels and fuel injector nozzles demand sub-5-micron tolerances achievable only through wire EDM processes. German and French aerospace tier-one suppliers specify high-conductivity copper and diffusion-annealed coated wires for Inconel and titanium alloy machining.
- Tool Making:Precision cutting tool and die production relies on standard brass and coated wire formulations for hardened steel workpieces.
- Automotive Parts:Stamping die and powertrain component manufacturing drives volume consumption across integrated die-mold service providers.
Mold making commands the highest absolute wire consumption, with aerospace component applications expanding most quickly as cooling channel complexity multiplies.
End User:
Customer type stratification sharpens as medical device manufacturers impose carbon footprint verification requirements absent from general manufacturing procurement.
- Manufacturing:General industrial tool and die shops represent the broadest installed base of wire EDM equipment. Bangalore and Pune precision engineering clusters in India remain dependent on imported coated wires, creating local manufacturing partnership openings.
- Medical Device:Orthopedic implant and surgical instrument producers in Switzerland and the United States deploy precision-grade brass wires for machining cobalt-chrome and titanium alloys. Japan's METI green procurement guidelines favor suppliers with verified carbon footprints and domestic recycling partnerships.
- Aerospace:Tier-one suppliers and engine manufacturers drive specification of high-performance wire formulations.
- Electronics:Connector and micro-component producers utilize fine-diameter wires for precision metal removal in miniaturized parts.
Manufacturing end users generate the largest wire volume, with medical device segments gaining share fastest as miniaturization and biocompatibility requirements intensify.
Technology:
Technology maturity curves diverge as fast hole EDM penetrates turbine blade applications while wire EDM sustains its installed base dominance.
- Wire EDM:CNC-controlled traveling wire electrodes sustain the largest installed equipment base across precision machining operations. The technology enables sub-5-micron accuracy in hardened steels and exotic alloys, with diffusion-annealed coated wires integrating into high-speed systems to reduce electrode wear rates.
- Fast Hole EDM:High-speed drilling of cooling channels in turbine blades and injection nozzles represents the steepest expansion trajectory. Aerospace applications in Germany and France adopt specialized tubular electrode configurations for deep-hole precision.
- Sink EDM:Sinker electrode machining utilizes solid electrodes rather than wire, occupying adjacent but distinct consumable demand pools.
- Laser EDM:Hybrid thermal-electric processes remain experimental with minimal commercial wire consumption.
Wire EDM maintains the largest installed base, with fast hole EDM climbing the fastest in turbine blade and cooling channel drilling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wire EDM technology originated in the Soviet Union during the 1940s before commercial scaling transferred to Japan and Switzerland in the 1960s-70s. Germany subsequently emerged as the precision engineering epicenter where coated-wire metallurgy advanced most rapidly. Contemporary demand geography reflects this industrial lineage, with manufacturing clusters concentrated in historically metalworking-intensive regions.
Japan
Domestic machine tool builders and integrated wire producers sustain captive demand for precision-grade consumables. METI green procurement guidelines favor suppliers with verified carbon footprints and domestic recycling partnerships. The Chubu region around Nagoya hosts dense concentrations of die-mold manufacturers deploying high-speed wire EDM systems.
Germany
Automotive stamping die production and aerospace component machining drive premium wire consumption across Baden-Württemberg and North Rhine-Westphalia. REACH compliance deadlines force reformulation of zinc coatings away from cobalt-bearing compositions. The Aachen-Stuttgart corridor concentrates European mold-making demand, with large automotive houses now contracting directly with wire manufacturers.
United States
Medical device manufacturers in Massachusetts and Minnesota impose carbon footprint verification requirements absent from general industrial procurement. EPA guidelines restrict heavy-metal content in spent-wire disposal streams. Aerospace tier-one suppliers across the Pacific Northwest and Southeast specify high-conductivity copper formulations for turbine blade production.
Switzerland
Orthopedic implant producers in the Jura Arc and Lake Geneva region deploy precision-grade brass wires for machining cobalt-chrome and titanium alloys. Swissmedic regulations align with EU MDR for biocompatibility traceability. The country's watchmaking heritage translates into sub-micron tolerance capabilities that permeate adjacent medical device tooling.
China
Parent metal refining and intermediate wire drawing cluster in Jiangsu and Zhejiang provinces, creating single-source vulnerability for global supply chains. MIIT oversees GB standards for tensile strength tolerances in precision-grade consumables. Yangtze River Delta tool rooms consume expanding tonnage as domestic aerospace and automotive stamping capacity scales.
EDM Wires Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the EDM wire value chain, with integrated metallurgy operations holding structural advantages in purity control and coating consistency. The vendor base separates into three distinct tiers: diversified electrical equipment conglomerates with captive wire divisions, specialized drawn-wire manufacturers with diffusion-annealing capabilities, and regional distributors serving fragmented job-shop demand. Dominant competitive moves include backward integration into parent metal refining and strategic partnerships with machine tool OEMs for co-development of process-optimized formulations.
Among diversified Japanese electrical equipment producers, Mitsubishi Electric Corporation and Sumitomo Electric Industries Ltd. exemplify the integrated conglomerate archetype with metallurgy expertise spanning parent metal to finished spool. Berkenhoff GmbH anchors the European specialist tier with coated-wire production capabilities concentrated in Germany. These three entities occupy positions that reflect the industry's geographic segmentation between Asian scale production and European precision engineering.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Sumitomo Electric Industries Ltd. |
| Sodick Co., Ltd. |
| Makino Milling Machine Co., Ltd. |
| Oki Electric Cable Co., Ltd. |
| Hitachi Metals Ltd. |
| Novotec BV |
| Berkenhoff GmbH |
| Powerway Group |
| Others |
Supply Flow & Price Mechanics
Diffusion-annealing metallurgists concentrated in Germany's Aachen-Stuttgart corridor command wage premiums that widen spreads between certified coated-wire tiers and commodity brass alternatives. REACH compliance investments and cobalt-free reformulation costs cascade through producer margins, compressing economy-tier returns while insulating premium pricing for qualified suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs EDM wire transactions, with certification grade and volume scale driving differentiation. Diffusion-annealed coated wires certified for aerospace applications command substantial premiums over standard brass for mold-making. Pricing pressure stems from copper price volatility and commodity brass oversupply in Asian markets. Automotive stamping houses exhibit highest price sensitivity through consolidated direct procurement, while medical device manufacturers prioritize traceability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle consolidated demand from German automotive stamping houses and aerospace tier-one suppliers, while distributor networks serve fragmented job shops across Europe and North America. Parent metal refining and intermediate wire drawing concentrate in China, Japan, and Germany, with Jiangsu and Zhejiang provinces anchoring global brass and copper wire capacity. Raw material dependencies center on LME-grade copper cathodes, zinc ingots for coating baths, and specialized brass master alloys. Single-source vulnerability in Chinese drawn-wire capacity exposes supply chains to logistics chokepoints and regulatory restriction risks. Distribution runs through integrated die-mold service providers displacing traditional spot purchasing in precision engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EDM Wires Market represents a late-cycle quality story as aerospace and medical device specifications tighten toward sub-5-micron tolerances and biocompatibility traceability. Premium-grade diffusion-annealed wires displace commodity alternatives on accelerated replacement cycles in precision applications.
For Market Incumbents: Anticipate cobalt-free reformulation mandates expanding beyond REACH into Asian regulatory frameworks, compressing margin pools for non-compliant inventory. Defend positioning by deepening backward integration into parent metal refining and securing JIS certification for Japanese medical device supply. Prioritize diffusion-annealing capacity expansion in Germany to capture aerospace tier-one demand consolidation. For New Entrants and Emerging Players: The 40-60% price-point gap between premium coated wires and economy brass creates entry space for mid-tier certified alternatives. Target India's Bangalore and Pune precision engineering clusters, where imported coated-wire dependency meets expanding domestic aerospace and automotive stamping capacity. Pursue local manufacturing partnerships with established distributors to bypass incumbent direct-contract lockups. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with captive customer relationships but lacking metallurgy capabilities. Long-term viability favors acquisition targets with verified REACH compliance and diffusion-annealing assets in European regulatory jurisdictions. Watch for ECHA guidance document expansions restricting additional heavy-metal compounds as inflection indicators for qualified-supplier premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parent Metal Refining | Mitsubishi Electric and Sumitomo Electric control copper purity grades through captive metallurgy operations. |
| REACH-Compliant Coating Reformulation | Berkenhoff GmbH dominates European coated-wire segments through specialized diffusion-annealing capabilities. |
| Direct OEM Contracting Bypass | German automotive stamping houses now contract annually with wire manufacturers, displacing distributor networks. |
| Closed-Loop Recycling Infrastructure | EU Green Deal circular economy requirements accelerate investment across Germany and the Netherlands. |
| JIS Certification for Medical Device Supply | Japan's METI green procurement guidelines favor suppliers with verified carbon footprints and domestic recycling partnerships. |
Methodological Framework
Multiple input streams — primary interviews with wire EDM equipment operators, procurement leads at aerospace tier-one suppliers, and technical directors at precision mold shops; secondary validation through JIS standards documentation, ECHA guidance publications, and customs trade data; plus SEC filings from diversified electrical equipment conglomerates — were reconciled through bottom-up and top-down triangulation.
Historical shipment data from machine tool OEMs was cross-referenced against panel input from wire producers and distributor channels to construct segmentation models across product type, application, end user, and technology dimensions. CAGRs were derived from curve-fitting approaches applied to installed base expansion, replacement cycle compression, and specification upgrade trajectories. Copper price volatility assumptions and REACH compliance cost pass-through rates informed margin sensitivity testing.
Caveats apply where raw material price spikes, regulatory timeline accelerations, or machine tool technology substitutions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Global Cable Gland Market
Cables
Water Leak Sensing Cable Market
Cables
Middle East Cable Market
Cables
Cable Tags Market
Cables
Medium Voltage Cables Accessories Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Usb Data Cable Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Fiber Optic Cable Accessories Market
Cables
Audio and Video Cables Market
Cables
Aluminium Battery Cable Market
Cables
Electric Submersible Cable Sales Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Cable Trunking Market
Cables
Electric Submersible Cables (ESP) Market