
 Global Cable Gland Market | 2026-2036
Global Cable Gland Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cable Gland Market Analysis
Market Context
REACH compliance is pivoting material sourcing strategies across the supply chain as restricted substance lists expand. ABB Ltd leverages integrated electrification portfolios to anchor large-scale industrial contracts across Europe. Eaton Corporation sustains channel dominance through specification-grade product lines targeting oil and gas infrastructure. TE Connectivity differentiates via advanced polymer science for extreme temperature cable sealing applications.
Technical Definition and Segment Structure
A cable gland is a mechanical sealing and retention device that terminates electrical cables into enclosures, equipment, or bulkheads, typically specified by thread standard, ingress protection rating, and material compatibility with the operating environment. Brass and stainless steel variants command premium positioning due to corrosion resistance demands in chemical processing and offshore installations, while plastic formulations compete on cost-sensitive indoor telecommunications deployments. Industrial Equipment and Electrical Enclosures represent the most mature application pools with established specification channels, whereas Automotive applications are gaining velocity from high-voltage cable management requirements in electric vehicle platforms.
Regulatory Framework
EU ATEX directives, IECEx international certification, and US OSHA electrical safety standards collectively mandate explosion-proof sealing integrity for hazardous location installations. India's BIS certification and China's GB standards add national conformity layers that extend product development cycles but raise barriers against uncertified competitors. Stakeholders must monitor evolving material restrictions and harmonization gaps between regional approval regimes when allocating R&D and manufacturing footprint decisions.
Market Dynamics
Marine-grade sealing specifications from offshore wind developers are compressing product development cycles while IECEx certification requirements fragment supplier qualification pools across hazardous area markets.
Growth Catalysts
- EU F-Gas Regulation:Phasedown mandates for fluorinated gases are accelerating demand for alternative sealing materials in industrial refrigeration and HVAC cable entry systems.
- Offshore wind installation:Developers in Germany and China are specifying corrosion-resistant stainless steel glands for subsea array cabling in floating wind platforms.
- Electric vehicle manufacturing:High-voltage cable management requirements in battery pack enclosures are pulling shielded EMC glands into automotive supply chains.
Market Restraints
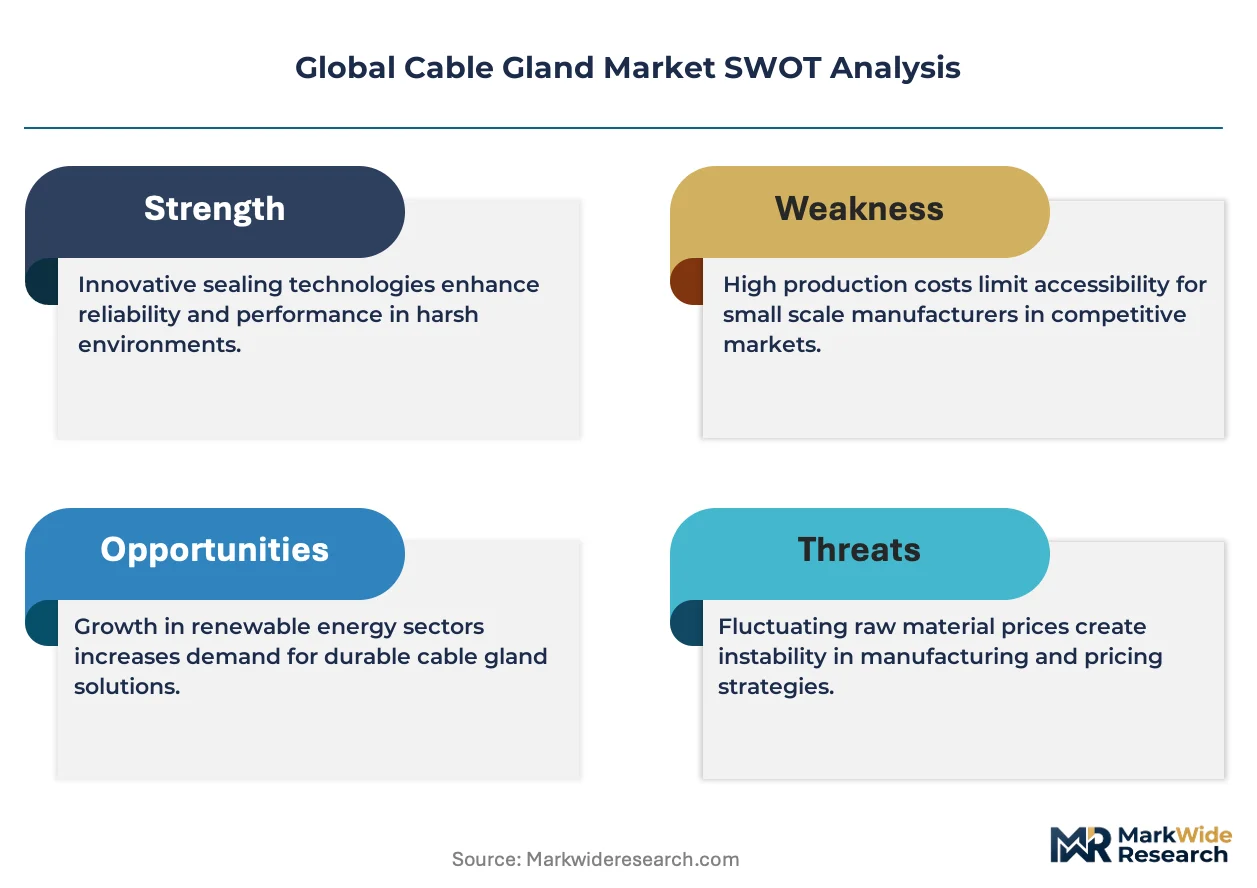
- Copper and nickel price volatility:Brass alloy feedstock costs swing with London Metal Exchange pricing, compressing margin buffers for mid-tier manufacturers.
- Supply concentration in Zhejiang province:Die-cast brass component sourcing clusters in eastern China create single-point vulnerability for European assemblers.
- Technical limitation in extreme cryogenics:Standard elastomer seals fail below minus 60 degrees Celsius, excluding cable glands from LNG liquefaction train applications without costly custom engineering.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for semiconductor and electronics manufacturing are building demand for IP-rated enclosure sealing in greenfield fabs near Ahmedabad and Chennai.
- Digital twin integration:Convergence of RFID-enabled smart glands with asset management software creates recurring revenue streams through predictive maintenance subscriptions.
- REACH material restrictions:Expanding substance restrictions are opening substitution windows for bio-based polymer formulations that bypass legacy compound supply chains.
Industry Challenges
- IECEx certification timeline:Third-party testing and factory audit queues stretch 14-18 months, delaying market entry for new product variants.
- Polymer formulation expertise gap:Compound chemistry specialization for extreme temperature ratings concentrates among a narrow pool of European and Japanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cable Gland Market |
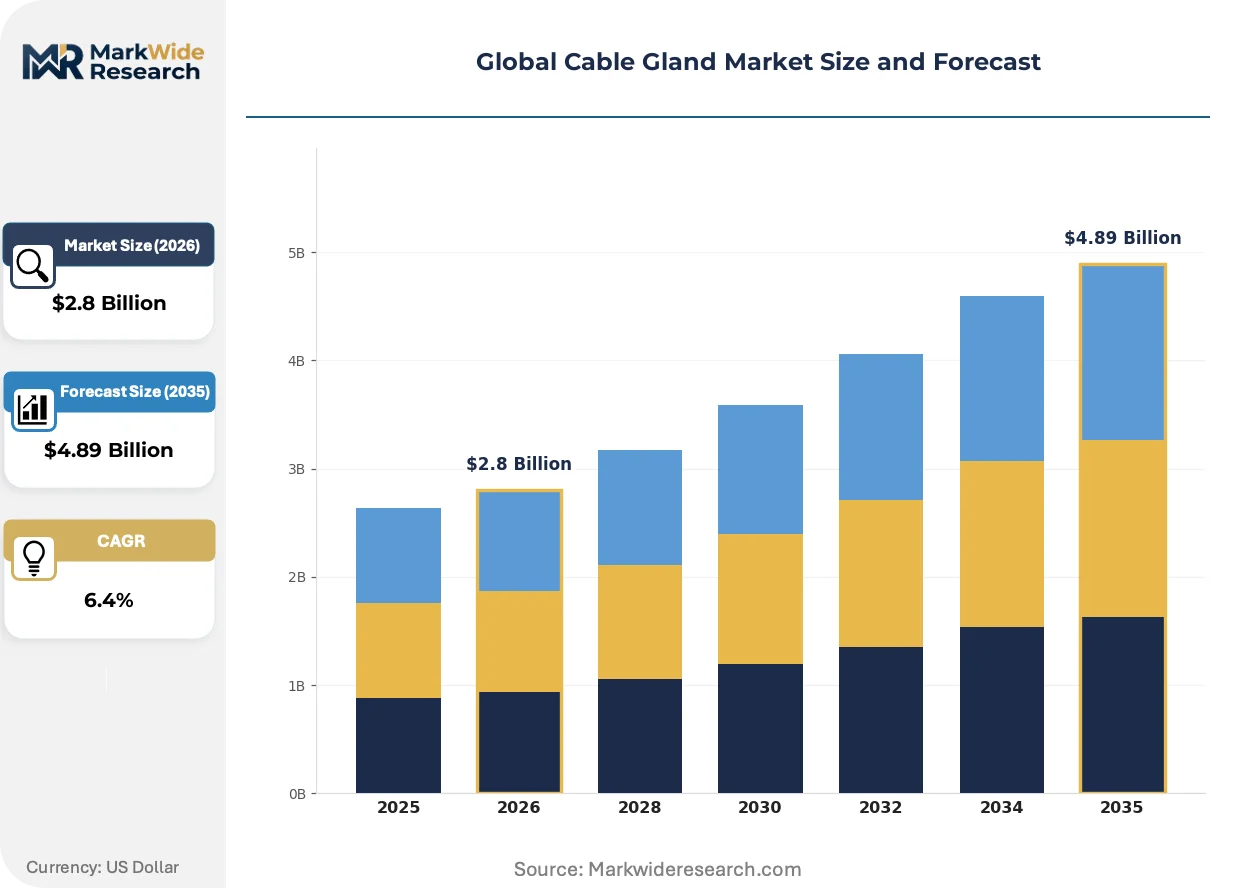
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Non-metallic, Ex d, Ex e Application: Industrial Equipment, Telecommunications, Electrical Enclosures, Automotive Material: Brass, Plastic, Stainless Steel, Aluminum Installation Type: Indoor, Outdoor, Flush Mount, Wall Mount |
| Companies Covered | ABB Ltd, Eaton Corporation, Amphenol Corporation, CMP Products Limited, Bartec Group, Hubbell Incorporated, TE Connectivity, Cortem Group, Emerson Electric Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cable Gland Market Emerging Trajectories
Material science advances and certification digitization are compressing traditional specification barriers while rewiring how industrial buyers evaluate sealing performance.
Self-healing polymer compounds with embedded microcapsule repair agents are rewriting lifecycle economics for cable glands in vibration-heavy environments. Mining operators in Western Australia and Chilean copper concentrators are piloting these formulations to extend maintenance intervals. The technology is compressing total cost-of-ownership calculations that previously favored metal-to-metal sealing architectures.
REACH substance restriction expansions are forcing reformulation of nitrile and fluorocarbon elastomer stocks across European supply chains. Compounders must now validate alternatives against IEC 60079-7 increased safety standards before ATEX certification renewal. German chemical processors and Dutch offshore fabricators are absorbing premium pricing for compliant pre-certified assemblies rather than qualifying new materials in-house.
Specification-grade buyers are unbundling engineering support from hardware procurement, contracting directly with application specialists for hazardous area compliance documentation. Distributors in the US Gulf Coast and Singapore trading houses are losing margin capture to manufacturer-direct technical sales teams. This channel compression is most visible in oil and gas project engineering where front-end loading requirements now mandate early supplier engagement.
Global Cable Gland Market Segmentation
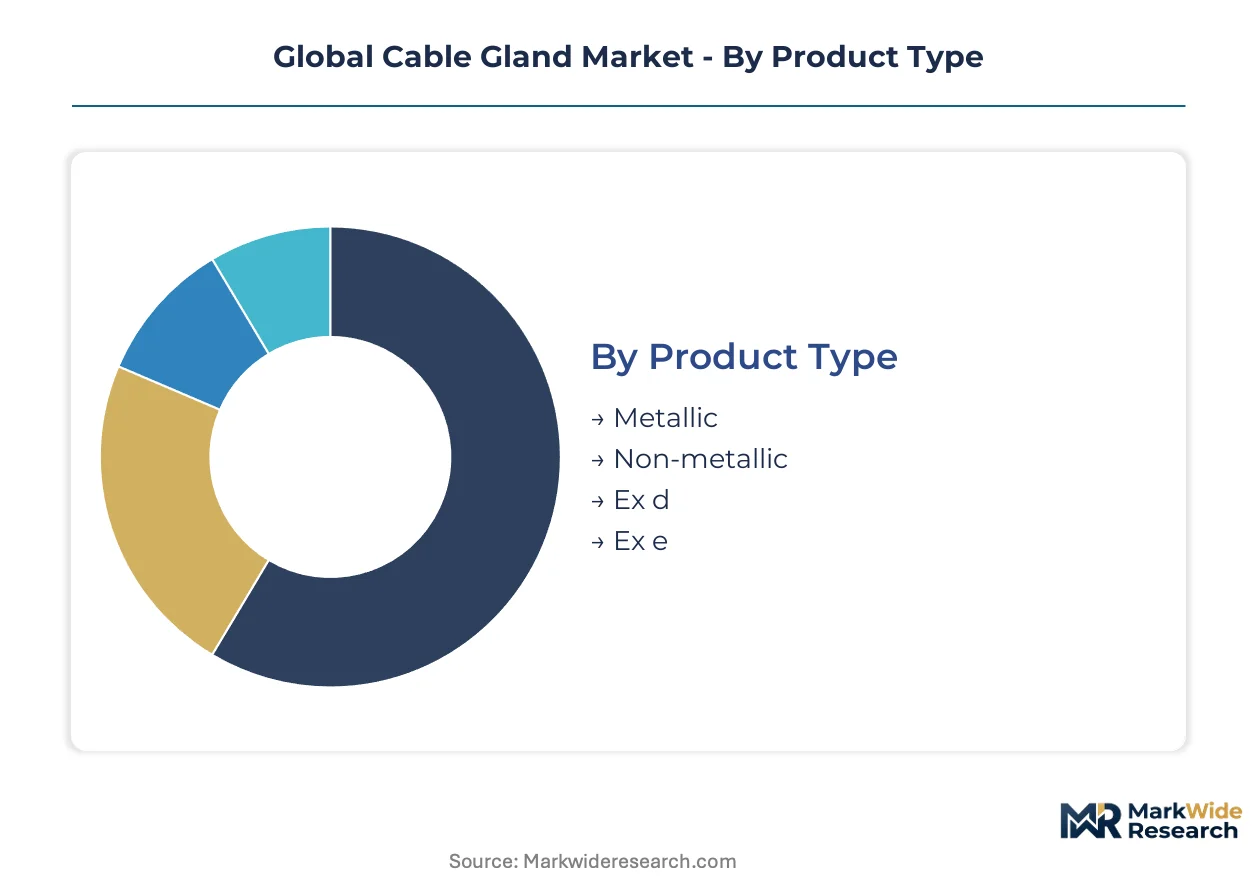
Segmentation in the cable gland market reflects divergent certification burdens and material sourcing strategies across hazardous and non-hazardous environments. Procurement teams weight ATEX/IECEx compliance costs against total lifecycle sealing performance when allocating specification budgets across product categories.
Product Type:
ATEX and IECEx certification requirements fragment supplier pools unevenly across this category, with explosion-proof variants demanding 14-18 month third-party validation timelines.
- Metallic:Brass and stainless steel constructions dominate chemical processing and offshore installations where corrosion resistance mandates alloy-grade specifications. German wind farm developers and Singapore marine fabricators specify these for subsea array cabling in floating platforms.
- Ex d:Flameproof enclosures containing internal explosions require precision-machined metal-to-metal sealing surfaces validated under IEC 60079-1 pressure testing protocols. Oil and gas project engineers in the US Gulf Coast and Middle East procurement offices specify these for zone 1 hazardous locations.
- Non-metallic:Polyamide and polypropylene formulations compete on cost for indoor telecommunications and light industrial applications without explosion-risk requirements.
- Ex e:Increased safety designs prevent ignition through enhanced construction rather than containment, common in zone 2 areas with lower ignition probability.
Leading the category by volume: Metallic. Growing fastest: Ex d.
Application:
End-use concentration shapes margin structures, with automotive and offshore energy applications pulling premium pricing through specialized EMC and marine-grade specifications.
- Industrial Equipment:Motor control centers, switchgear, and process automation enclosures constitute the most mature specification channel with established distributor relationships. German chemical processors and Indian semiconductor fabs near Ahmedabad specify IP66+ rated assemblies for washdown environments.
- Automotive:High-voltage cable management in battery pack enclosures and electric powertrain systems is pulling shielded EMC glands into automotive supply chains. Chinese EV manufacturers and German OEMs specify these for electromagnetic compatibility compliance.
- Telecommunications:Data center and 5G infrastructure deployments favor cost-optimized plastic glands for indoor fiber and copper cable entry.
- Electrical Enclosures:Panel builders and OEMs specify standard industrial grades across building automation and machinery applications with moderate environmental exposure.
Dominating current procurement spend: Industrial Equipment. Expanding most quickly: Automotive.
Material:
REACH substance restrictions and London Metal Exchange volatility are forcing reformulation and sourcing recalibration across alloy and polymer supply chains.
- Brass:Copper-zinc alloys face margin compression from nickel and copper price volatility, with die-cast component sourcing concentrated in Zhejiang province creating supply vulnerability for European assemblers.
- Stainless Steel:Marine-grade 316L specifications command premium positioning for offshore wind and subsea applications where chloride resistance is non-negotiable.
- Plastic:Polyamide formulations compete on cost for indoor telecommunications, though REACH-compliant bio-based alternatives are gaining traction as nitrile and fluorocarbon elastomer stocks face restriction.
- Aluminum:Lightweight specifications serve aerospace and weight-sensitive transportation applications with moderate corrosion exposure.
Highest volume material: Brass. Steepest expansion trajectory: Stainless Steel.
Installation Type:
Environmental exposure ratings determine IP and NEMA specification tiers, with outdoor and flush-mount variants requiring enhanced sealing geometry and gasket materials.
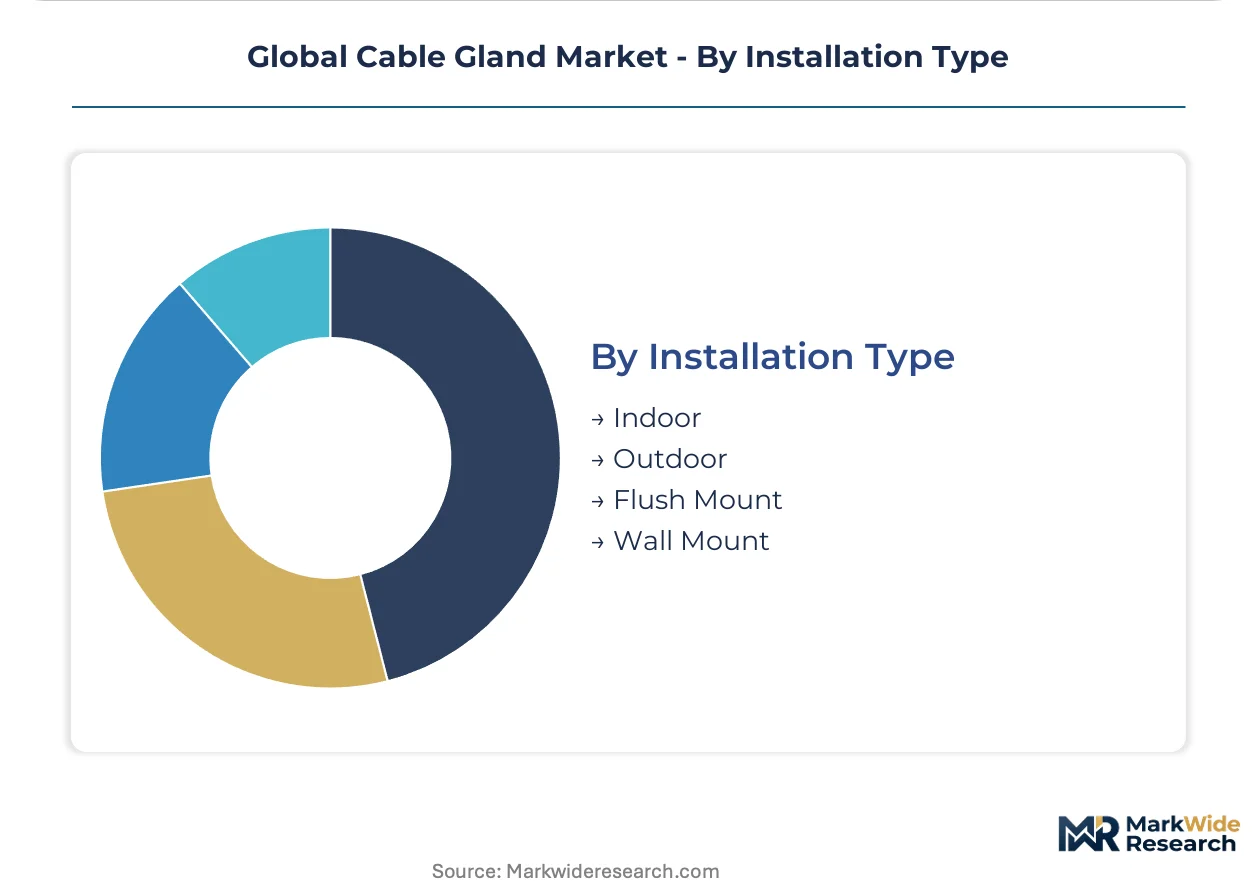
- Outdoor:UV-stabilized polymers and marine-grade metals with drainage features prevent water ingress across temperature cycling. Dutch offshore fabricators and Australian mining operators specify these for extreme environmental exposure.
- Indoor:Standard IP54-rated assemblies serve climate-controlled electrical rooms and telecommunications facilities with minimal environmental stress.
- Flush Mount:Recessed installation profiles protect against mechanical damage in high-traffic industrial corridors and mobile equipment.
- Wall Mount:Surface-mounted variants simplify retrofit installations in existing infrastructure with accessible cable routing.
Largest installed base: Indoor. Gaining share fastest: Outdoor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's Special Investment Regions and Tamil Nadu's industrial corridors are concentrating cable gland demand from semiconductor fabs and automotive electrification clusters.
United States
Offshore wind lease auctions in the Gulf of Mexico and Atlantic seaboard are pulling marine-grade stainless steel specifications into procurement pipelines. OSHA electrical safety standards and NEC hazardous location classifications mandate explosion-proof sealing for petrochemical installations along the Texas-Louisiana corridor. Houston-based engineering firms are front-loading supplier engagement for LNG export terminal expansions.
Germany
Floating wind platform developers in the North Sea and Baltic are specifying 316L marine-grade glands for subsea array cabling. The EU F-Gas Regulation is accelerating material transitions in industrial refrigeration cable entry systems. Hamburg and Bremerhaven fabrication yards are consolidating supplier qualification pools for offshore export cable installations.
China
GB standards compliance and dual carbon policy targets are reshaping material sourcing for electric vehicle battery pack enclosures. Die-cast brass component clusters in Zhejiang province supply European assemblers despite concentration risk. Shanghai and Shenzhen EV manufacturers are pulling shielded EMC glands into high-voltage cable management specifications.
India
PLI scheme incentives for semiconductor manufacturing are building demand for IP-rated enclosure sealing in greenfield fabs near Ahmedabad and Chennai. BIS certification requirements extend product development cycles but raise barriers against uncertified competitors. Tamil Nadu's electronics manufacturing clusters are specifying washdown-rated assemblies for cleanroom environments.
Singapore
Marine fabrication yards serving Southeast Asian offshore energy projects are consolidating procurement of corrosion-resistant sealing solutions. The city-state's trading houses are losing margin capture to manufacturer-direct technical sales teams for hazardous area compliance documentation. Jurong Island petrochemical complexes are mandating early supplier engagement for front-end engineering packages.
Global Cable Gland Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification and material competency vectors. The vendor base stratifies between integrated electrification portfolios and specification-grade product lines targeting hazardous area installations. Three archetypes dominate: diversified industrial conglomerates with cross-selling leverage, mid-cap specialists with deep certification expertise, and regional fabricators competing on die-cast component economics. Capacity expansion in polymer formulation and strategic partnerships for IECEx testing access represent the dominant competitive moves.
Among diversified industrial conglomerates, ABB Ltd and Eaton Corporation exemplify archetypes with integrated electrification portfolios anchoring large-scale industrial contracts. TE Connectivity occupies a position within the specialty polymer science tier, representing advanced material competency for extreme temperature applications. These three companies illustrate the competitive tension between breadth-driven cross-selling and depth-driven technical specification capture.
| Leading Market Players |
|---|
| ABB Ltd |
| Eaton Corporation |
| Amphenol Corporation |
| CMP Products Limited |
| Bartec Group |
| Hubbell Incorporated |
| TE Connectivity |
| Cortem Group |
| Emerson Electric Co |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating alternative sealing materials that only compounders with validated IEC 60079-7 formulations can deliver. German chemical processors and Dutch offshore fabricators now absorb premium pricing for pre-certified assemblies rather than qualifying new materials in-house, compressing margin buffers for uncertified competitors.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to IECEx-certified stock held in European distribution hubs, while spot inventory from Zhejiang die-casters trades at discounts for standard brass variants. Pricing stratifies across ATEX-certified premium tiers, IECEx-validated standard tiers, and uncertified economy tiers with differentiation driven by certification level and volume scale. Cost compression in mid-tier brass glands is intensifying because London Metal Exchange copper and nickel volatility feeds directly into alloy feedstock costs. Automotive OEMs exhibit the least price sensitivity due to electromagnetic compatibility compliance mandates, while telecommunications deployers drive hard volume negotiations for polyamide indoor grades.
Supply Chain Analysis
Freight cost differentials between air and sea lanes from Ningbo and Shanghai to Hamburg and Rotterdam determine competitive positioning for European assemblers sourcing die-cast brass components. Supply concentrates in China, Germany, and India, with raw material dependencies on copper-zinc alloy feedstock, marine-grade 316L stainless steel, and REACH-compliant polymer formulations. Single-source vulnerability in Zhejiang province die-casting clusters creates disruption risk for brass variant availability. Distribution runs through specification-grade distributors in the US Gulf Coast and Singapore trading houses, though manufacturer-direct technical sales teams are compressing channel margins for hazardous area compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable gland market is becoming a vertical-integration race as players pursue captive control over polymer formulation expertise to bypass the narrow European and Japanese supplier pool for extreme temperature compounds.
For Market Incumbents: Hedge against Zhejiang supply concentration by qualifying secondary die-casting sources in India or establishing in-house brass component production. Defend specification-grade positioning by embedding application engineers directly with Hamburg and Bremerhaven offshore fabricators during front-end engineering phases, compressing distributor margin capture. For New Entrants and Emerging Players: Capture white space in Indian semiconductor fab construction by pre-certifying IP66+ washdown-rated assemblies for BIS compliance before Ahmedabad and Chennai greenfield projects lock in incumbent specifications. Target bio-based polymer formulations that bypass restricted nitrile and fluorocarbon elastomer supply chains under expanding REACH substance lists. For Investors and Strategic Acquirers: IECEx certification queue lengthening beyond fourteen months is the leading indicator that compound chemistry specialization assets will command scarcity premiums. Long-term viability over the next decade rests on securing formulation expertise or testing access partnerships rather than hardware assembly scale. Acquisition targets should profile mid-cap specialists with existing ATEX/IECEx certification portfolios and established relationships with German wind farm developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captures margin from European and Japanese compounders while securing REACH compliance pathways. |
| IECEx Testing Partnership | Compresses 14-18 month certification queues that currently delay product launches for hazardous area markets. |
| Digital Twin Integration | Creates recurring revenue streams through predictive maintenance subscriptions for Australian mining operators. |
| Marine-Grade 316L Capacity Expansion | Supplies German floating wind platforms and Singapore Jurong Island petrochemical complexes with chloride-resistant sealing. |
| India BIS Pre-Certification Program | Locks in supplier status for PLI scheme semiconductor fabs near Ahmedabad and Chennai before construction completes. |
Methodological Framework
Trade databases, SEC 10-K filings, and IECEx certification registries formed the secondary backbone, supplemented by customs records tracking brass component flows from Ningbo and Shanghai to European assemblers. Primary fieldwork engaged plant engineers at German chemical processors, procurement leads at Chinese EV manufacturers, offshore fabrication managers in Singapore, and aftermarket service heads at Australian mining operators. Bottom-up volume estimates from application-level deployment data were triangulated against top-down macro indicators including offshore wind installation pipelines and semiconductor fab construction permits.
Historical trendline analysis across metallic, Ex d, non-metallic, and Ex e product categories established baseline growth patterns, with projections built through segmentation by material grade, installation environment, and regional regulatory cluster. CAGRs were derived from elasticity modeling against industrial automation capital expenditure cycles and electric vehicle platform ramp schedules. Forecast inputs incorporated London Metal Exchange pricing volatility assumptions and REACH substance restriction phase-in timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IECEx harmonization gaps, F-Gas Regulation enforcement intensity, and copper-nickel alloy price swings. Stakeholders should weight assumptions against their own operating context and certification renewal schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Instrumentation Cables Market
Cables
Power Cable Accessories Market
Cables
High-Temperature Superconducting Cables Market
Cables
Fiber Optic Cable Accessories Market
Cables
Magnetic Charging Cable Market
Cables
Ethernet Converters Market
Cables
Submarine Cabling Systems Market
Cables
Submarine Optical Fiber Cables Market
Cables
Military Fiber Optic Cables Market
Cables
Usb Data Cable Market
Cables
Cable Testing Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Low-Temperature Cable Market
Cables
Europe Wire and Cable Market
Cables
Copper Cabling Systems Market
Cables
High-Speed Interconnects Market