
 France Digital Thermometer Market | 2026-2036
France Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital Thermometer Market Insights
Pharmacy distribution networks in France is reconfiguring around direct-to-consumer digital channels and telemedicine partnerships. Omron Healthcare leverages its long-standing relationships with French pharmacy chains to sustain shelf dominance in suburban and rural markets. Braun competes through precision engineering heritage and strong brand recognition among paediatric segments. Microlife specializes in connected thermometer ecosystems that integrate with French telehealth platforms.
A digital thermometer is an electronic temperature measurement instrument employing thermistors or infrared sensors to quantify body heat with readings typically resolving to 0.1 degrees Celsius, designed for clinical accuracy without mercury. Its primary commercial purpose spans home health monitoring, clinical diagnostics, and veterinary applications where speed and hygiene matter. Forehead thermometers lead the product mix due to non-contact convenience in paediatric and public health settings, while smart thermometers represent the fastest-expanding segment as Bluetooth-enabled units feed data into patient management apps. Infrared technology anchors the installed base across French healthcare facilities, though wireless technology is capturing margin pools in premium connected devices sold through pharmacy networks.
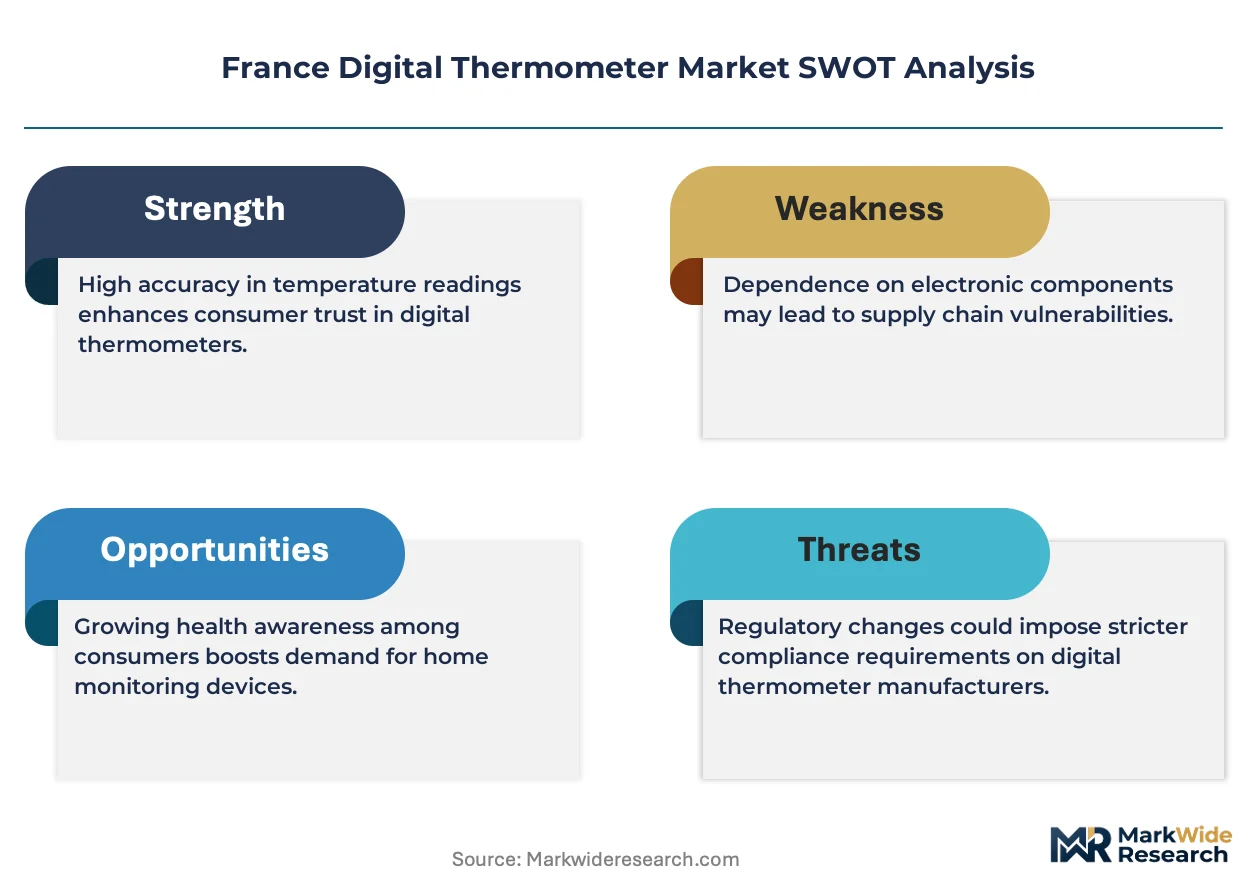
ANSM enforces Medical Device Regulation compliance for all thermometer classes sold in France, while CE marking under the EU MDR governs technical conformity and post-market surveillance obligations. GDPR constraints shape how connected thermometer vendors handle biometric data flows to cloud health platforms. Stakeholders must weigh regulatory certification timelines against the pace of sensor miniaturisation and connectivity integration when allocating R&D budgets.
Market Dynamics
The French digital thermometer market is being restructured by ANSM's Medical Device Regulation enforcement, which compresses certification timelines while elevating technical barriers for connected devices handling biometric data.
Growth Catalysts
- Chronic disease management protocols:French households managing diabetes and cardiovascular conditions now integrate daily temperature tracking into home health routines, expanding the addressable base beyond acute illness detection.
- EU MDR CE marking alignment:Harmonized technical conformity requirements across European markets enable French manufacturers to scale production for cross-border distribution without duplicative testing.
- Telemedicine platform integration:Bluetooth-enabled thermometers feeding directly into patient management apps reduce friction for remote consultations, particularly within Ile-de-France's dense healthcare corridor.
Market Restraints
- Sensor component concentration:Infrared thermopile manufacturing clusters in East Asian supply chains expose French assemblers to shipping volatility and input cost swings.
- Mercury thermometer residual stock:Legacy mercury devices persist in price-sensitive rural pharmacies, delaying full category conversion despite ANSM phase-out mandates.
- GDPR compliance overhead:Connected device vendors face biometric data handling restrictions that lengthen software development cycles and elevate legal review costs before cloud platform integration.
Strategic Opportunities
- Veterinary application expansion:Precision livestock farming in Brittany and Normandy creates demand for ruggedized infrared thermometers capable of herd-scale screening.
- Pharmacy network digitization:Direct-to-consumer channels and telemedicine partnerships enable bypass of traditional wholesale markups in suburban markets.
- EU Green Deal circularity requirements:Battery recycling mandates and repairability standards favor modular thermometer designs that extend product lifecycles and differentiate premium tiers.
Industry Challenges
- Embedded firmware talent scarcity:French medical device firms compete with automotive and aerospace sectors for engineers skilled in low-power Bluetooth stack optimization and sensor fusion algorithms.
- Post-market surveillance documentation:ANSM's strengthened vigilance reporting demands continuous adverse event tracking that strains quality management systems at mid-scale manufacturers.
- Legacy hospital IT integration:Connected thermometer data formats often conflict with proprietary electronic health record architectures in Parisian public hospital networks, requiring costly interface customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital Thermometer Market |
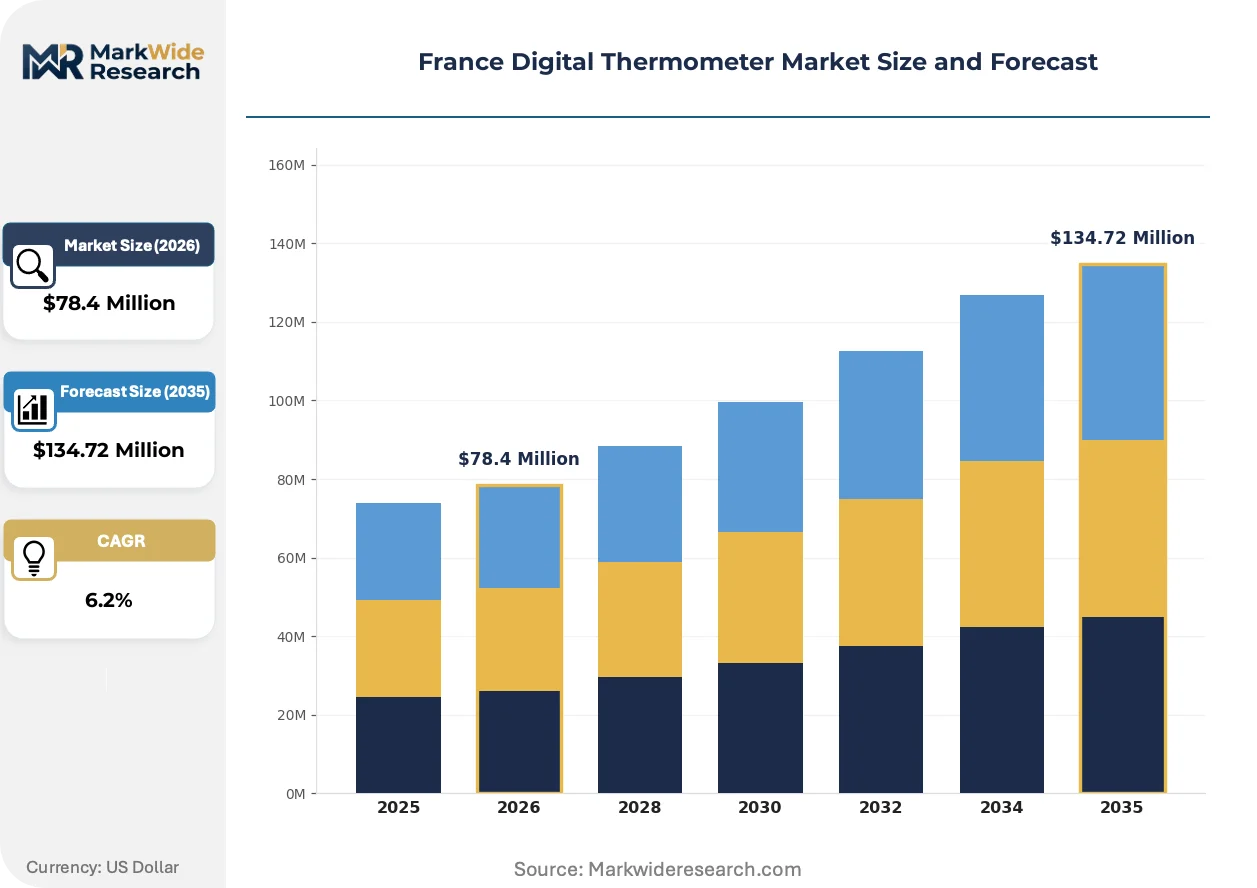
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forehead Thermometers, Ear Thermometers, Oral Thermometers, Smart Thermometers Application: Home Use, Clinical Use, Veterinary Use, Industrial Use End User: Households, Healthcare Facilities, Laboratories, Pharmacies Technology: Infrared Technology, Bluetooth Technology, Digital Display Technology, Wireless Technology |
| Companies Covered | Omron Healthcare, Braun, Philips, Microlife, Geratherm Medical AG, Terumo Corporation, AMETEK, A&D Medical, PCE Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital Thermometer Market Trends and Innovations
Thermistor-based contact measurement is yielding to infrared and multisensor arrays as French healthcare facilities prioritize speed and hygiene. This shift compresses development timelines for vendors while elevating accuracy calibration requirements.
Multisensor fusion arrays combining infrared, ambient temperature, and distance sensors are migrating from clinical settings into premium home-use devices. French paediatric practices adopted these configurations first to reduce measurement anxiety in infant patients. The technology is migrating from hospital procurement specifications into pharmacy-sold consumer units, collapsing the traditional performance gap between professional and domestic segments.
ANSM's alignment with EU MDR post-market surveillance obligations now requires real-world performance data collection from connected thermometers. French distributors must maintain digital vigilance infrastructure that flags temperature reading anomalies across installed device fleets. Connected product lines face the steepest compliance burden, with vendors restructuring warranty terms to accommodate mandatory feedback loops.
Hospital procurement committees in Lyon and Marseille now unbundle thermometer purchases from broader diagnostic equipment tenders, enabling specialized vendors to compete against diversified incumbents. This fragmentation of buying authority shifts negotiation leverage toward clinical engineering departments and away from centralized supply chain offices. The pattern is most pronounced in university hospital networks undergoing digital transformation programs.
France Digital Thermometer Market Segmentation
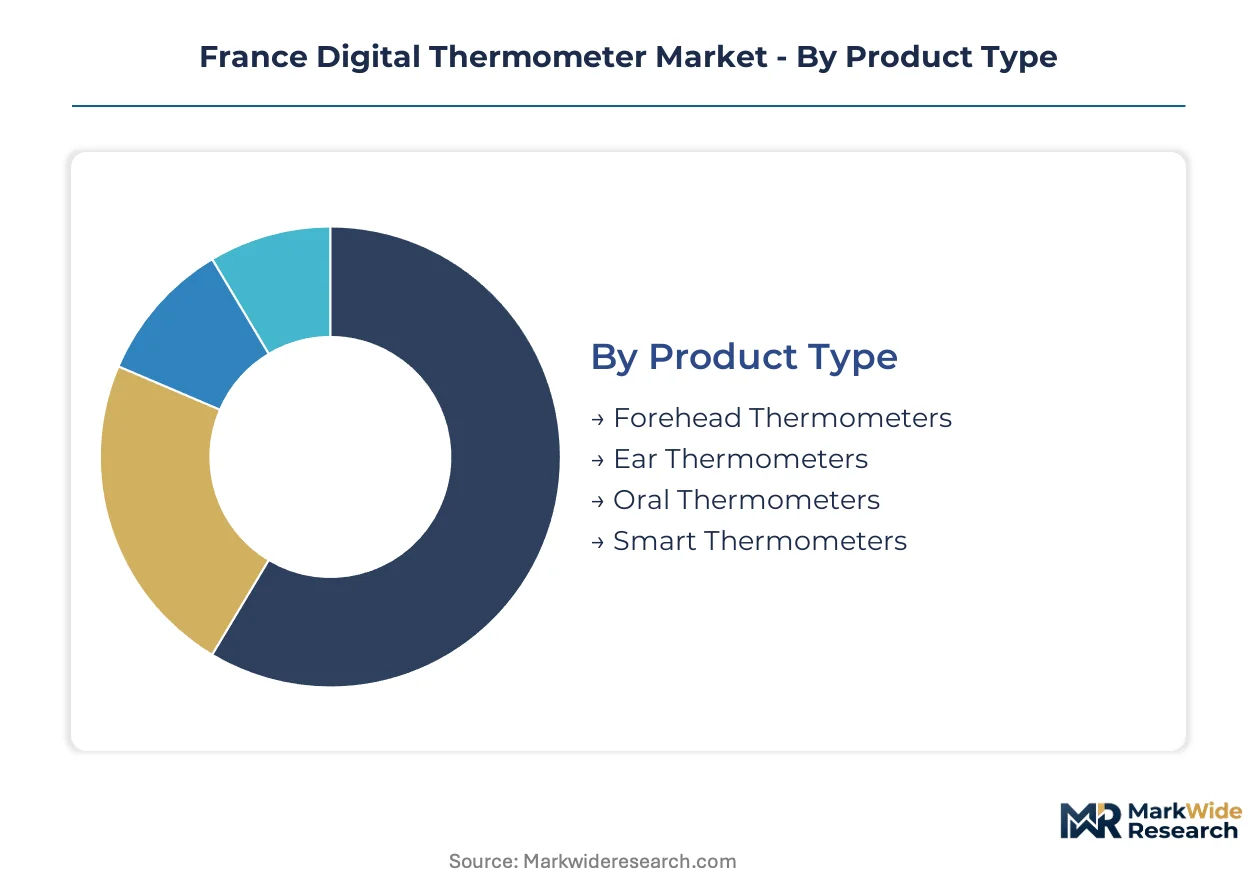
Segmentation in the France digital thermometer market reveals how technical specifications, use environments, and connectivity requirements reshape procurement patterns across pharmacy networks and healthcare systems. Distinct performance thresholds separate clinical-grade devices from household units, while regulatory compliance obligations vary sharply by end-user category.
Product Type:
Use-case spectrum spans rapid screening in public health settings through precision home monitoring, with each form factor optimizing for speed, accuracy, or data integration.
- Forehead Thermometers:Non-contact infrared sensors capture temporal artery temperature without skin contact, resolving to 0.1°C within seconds. French paediatric practices in Paris and Lyon prioritize these units to reduce infant distress during acute illness episodes. ANSM's hygiene protocols for hospital triage stations reinforce demand in Ile-de-France emergency departments.
- Smart Thermometers:Bluetooth-enabled devices stream encrypted temperature logs to patient management platforms, enabling longitudinal tracking for chronic condition management. Connected units face GDPR compliance overhead that extends software development cycles before cloud integration approval. Adoption concentrates among tech-forward households in urban centres managing multi-generational health data.
- Ear Thermometers:Tympanic membrane measurement via infrared thermopiles delivers core body temperature approximation in under two seconds. Compact designs suit home medicine cabinets and school nurse stations.
- Oral Thermometers:Thermistor-based contact measurement remains the reference standard for basal body temperature tracking in fertility monitoring applications.
Established volume favors forehead thermometers; emerging adoption favors smart thermometers.
Application:
Cost tier stratification separates disposable units for mass screening from capital equipment integrated into diagnostic workflows.
- Home Use:Consumer-grade devices prioritize intuitive interfaces and rapid readout over calibration precision, with French households purchasing primarily through pharmacy chains and direct-to-consumer platforms. Price sensitivity in rural Bretagne and Normandy sustains demand for basic digital units without connectivity features.
- Clinical Use:Hospital procurement specifications mandate IEC 60601-1 compliance, traceable calibration certificates, and electromagnetic immunity testing for deployment in critical care environments. University hospital networks in Marseille and Toulouse unbundle thermometer purchases from broader diagnostic tenders, enabling specialized vendors to compete.
- Veterinary Use:Ruggedized infrared units withstand barn environments and accommodate variable animal positioning for herd-scale screening in livestock-dense regions.
- Industrial Use:Food safety and manufacturing quality control applications require HACCP-compliant documentation and extended temperature ranges beyond physiological norms.
Clinical procurement sustains premium pricing; home use drives unit volume expansion.
End User:
Customer type determines regulatory burden, with healthcare facilities facing ANSM vigilance reporting that household purchasers avoid entirely.
- Healthcare Facilities:Public hospital networks and private clinics operate under EU MDR post-market surveillance obligations requiring adverse event tracking across installed device fleets. Procurement committees in Lyon and Marseille now delegate thermometer selection to clinical engineering departments rather than centralized supply offices.
- Households:Individual purchasers prioritize speed, display clarity, and pharmacy availability over calibration documentation, with suburban and rural markets showing persistent preference for established brand recognition.
- Laboratories:Research and reference applications demand NIST-traceable calibration and data logging capabilities for regulatory submission support.
- Pharmacies:Retail dispensaries function as both sales channel and clinical advice point, with staff training influencing device recommendation patterns.
Healthcare facilities anchor professional-grade revenue; households represent the broadest addressable base.
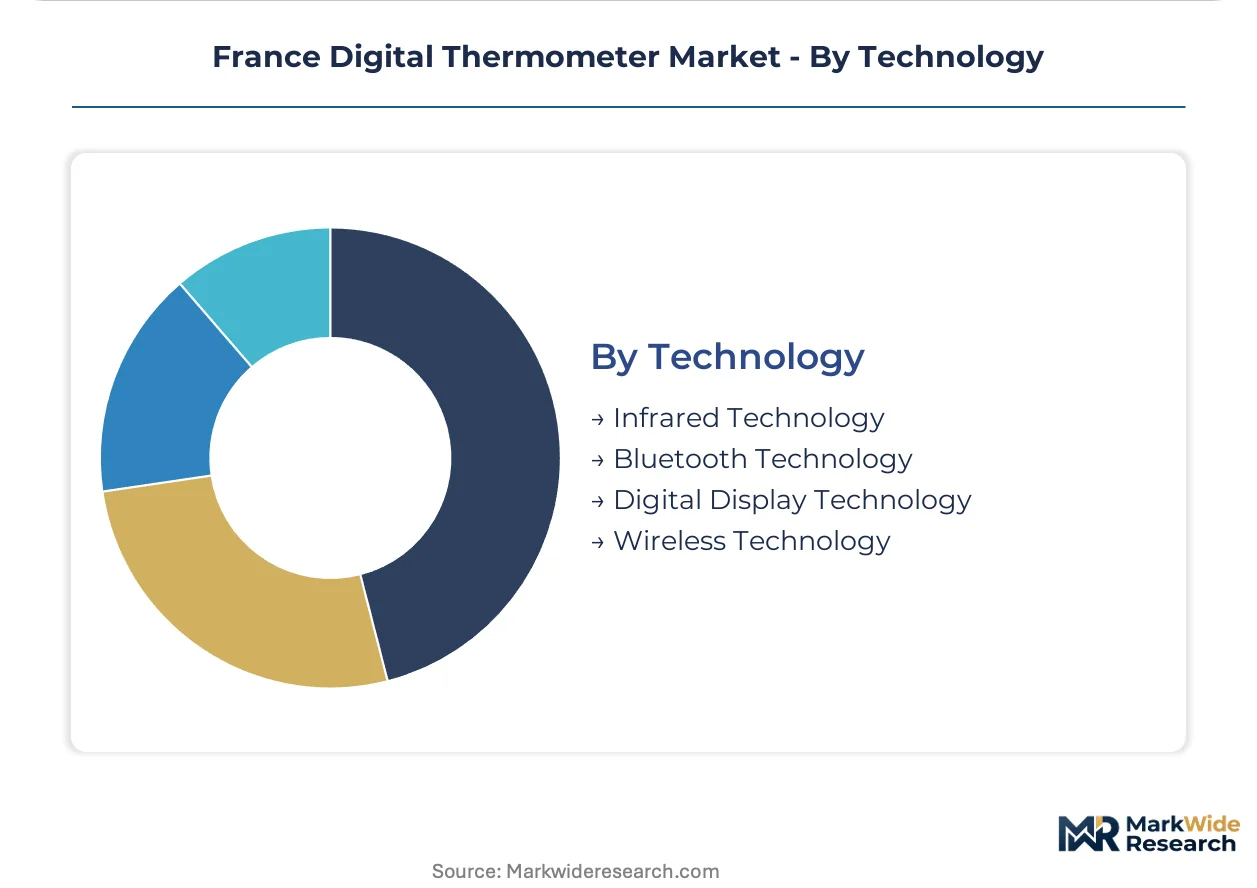
Technology:
Supply concentration in East Asian sensor manufacturing shapes margin structure across connectivity tiers.
- Infrared Technology:Thermopile arrays and infrared detectors enable non-contact measurement with millisecond response times, dominating both clinical and consumer installed bases in France. Calibration drift concerns require periodic verification against reference standards in hospital settings.
- Bluetooth Technology:Low-energy wireless stacks enable smartphone pairing and telemedicine platform integration, though firmware development competes with automotive and aerospace sectors for embedded engineering talent in France.
- Digital Display Technology:LCD and LED readout systems with backlighting accommodate low-light clinical environments and aging-user accessibility requirements.
- Wireless Technology:Wi-Fi and proprietary radio protocols support enterprise fleet management in large hospital networks, enabling centralized device monitoring and automated inventory tracking.
Infrared technology commands current installed base; Bluetooth connectivity gains share fastest in replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France commands premium pricing power through its dense hospital corridor, while rural Bretagne and Normandy markets absorb entry-tier units through pharmacy chains. This pricing asymmetry reflects divergent procurement sophistication between metropolitan healthcare networks and price-sensitive peripheral regions.
Île-de-France
Paris and its surrounding healthcare corridor concentrate demand for Bluetooth-enabled thermometers feeding telemedicine platforms. ANSM's Medical Device Regulation enforcement accelerates certification timelines for connected devices entering this market. Public hospital networks in Paris unbundle thermometer procurement from broader diagnostic tenders, enabling specialized vendors to compete against diversified suppliers.
Auvergne-Rhône-Alpes
Lyon's university hospital networks drive clinical-grade infrared thermometer adoption for triage and critical care applications. EU MDR CE marking alignment enables local distributors to source cross-border without duplicative testing. The Lyon-Grenoble medical technology cluster hosts procurement committees delegating device selection to clinical engineering departments rather than centralized supply offices.
Provence-Alpes-Côte d'Azur
Marseille's hospital procurement fragmentation creates openings for specialized thermometer vendors against incumbent diversified suppliers. GDPR constraints shape how connected device vendors handle biometric data flows to cloud health platforms from this coastal population center. The region's aging demographic sustains demand for large-display thermometers through pharmacy retail channels.
Hauts-de-France
Lille's proximity to Belgian and Dutch distribution hubs exposes this market to cross-border pricing pressure on standard digital units. Legacy mercury thermometer stock persists in rural pharmacies despite ANSM phase-out mandates, delaying full category conversion. The region's industrial heritage supports subcontracting relationships for thermometer assembly and component sourcing.
Bretagne and Normandy
Precision livestock farming in these western regions generates veterinary infrared thermometer demand for herd-scale fever screening. Price-sensitive rural households prioritize basic digital units without connectivity features through established pharmacy chains. Veterinary applications here favor ruggedized designs capable of barn environments and variable animal positioning.
France Digital Thermometer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and calibration services. The French market exhibits moderate consolidation around diversified health technology conglomerates with established pharmacy relationships, while mid-scale specialists compete on connectivity integration and veterinary applications. Three archetypes dominate: diversified health technology conglomerates leveraging pharmacy shelf presence, connected-device specialists targeting telemedicine integration, and precision-engineering heritage brands commanding pediatric segments. Competitive moves center on telemedicine platform partnerships and modular design strategies addressing EU Green Deal circularity requirements.
Among diversified health technology conglomerates, Omron Healthcare and Braun exemplify archetypes leveraging long-standing pharmacy chain relationships and precision-engineering heritage respectively. Microlife occupies a position within the connected-device specialist tier, representing vendors building thermometer ecosystems that integrate with French telehealth platforms. These three anchors illustrate how competitive positioning stratifies across pharmacy shelf dominance, pediatric brand recognition, and digital health integration vectors.
| Leading Market Players |
|---|
| Omron Healthcare |
| Braun |
| Philips |
| Microlife |
| Geratherm Medical AG |
| Terumo Corporation |
| AMETEK |
| A&D Medical |
| PCE Holding GmbH |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's thermopile manufacturing clusters anchor global infrared sensor capacity, and their output fluctuations transmit directly into French assembler margins and end-user pricing tiers. ANSM certification timelines compress procurement windows, forcing distributors to absorb inventory carrying costs or pass them downstream.
Pricing Analysis
The customization-premium spread separates Bluetooth-enabled connected thermometers from basic digital units, with firmware development and GDPR compliance architecture commanding substantial markups over standard infrared devices. Three-tier pricing structure across premium, standard, and economy levels reflects calibration precision, CE marking tier under EU MDR, and after-sales service bundling. Cost compression in entry-tier segments is intensifying because legacy mercury stock clearance in rural pharmacies delays full category conversion. Household purchasers in Bretagne and Normandy exhibit highest price sensitivity, while hospital procurement committees in Paris and Lyon prioritize traceable calibration certificates over unit cost.
Supply Chain Analysis
Supplier-financing arrangements through extended payment terms and supply-chain finance facilities have become critical liquidity tools for French distributors managing ANSM certification inventory. Component sourcing draws from China, Taiwan, and South Korea for infrared thermopiles, thermistors, and Bluetooth low-energy modules. Raw material dependencies span germanium substrates, lithium coin cells, and medical-grade ABS housings. Single-source vulnerability in East Asian thermopile manufacturing exposes French assemblers to shipping volatility and input cost swings. Distribution runs through pharmacy wholesale networks and direct-to-consumer digital channels, with telemedicine partnerships emerging as alternative pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected thermometer integration with French telehealth platforms represents high-growth disruption, justified by ANSM's EU MDR alignment compressing certification timelines for biometric data-handling devices.
For Market Incumbents: Build regulatory moats through early EU MDR CE marking investment and post-market surveillance infrastructure that mid-scale competitors cannot replicate. Deepen pharmacy chain relationships to defend shelf dominance against direct-to-consumer entrants. Prioritize backward integration into sensor calibration services to capture margin pools fleeing hardware commoditization. For New Entrants and Emerging Players: Veterinary applications in Brittany and Normandy offer underpenetrated white space, with ruggedized infrared designs for livestock screening commanding premium positioning absent entrenched competition. Target precision livestock farming cooperatives through agricultural supply distributors rather than human-health pharmacy networks. Develop modular hardware architectures that satisfy EU Green Deal circularity requirements as differentiation lever. For Investors and Strategic Acquirers: Long-term, this sits as a platform-integration play because thermometer data streams anchor broader remote patient monitoring ecosystems. Acquisition targets should exhibit embedded firmware capabilities for low-power Bluetooth optimization and existing hospital IT integration credentials. Watch ANSM adverse event reporting frequency as signal for quality management system maturity and post-market surveillance readiness.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR alignment enables cross-border scaling without duplicative testing across member states. |
| Hospital System Partnership | Unbundled procurement in Lyon and Marseille creates entry points for specialized vendors. |
| Software Companion Development | GDPR-compliant patient management apps reduce friction for Ile-de-France telemedicine integration. |
| Backward Integration | Captive sensor calibration services defend margin pools against hardware commoditization. |
| Sustainability Repositioning | Modular designs addressing EU Green Deal circularity requirements differentiate premium tiers. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and commercial databases. Primary interviews encompassed hospital procurement committee members, biomedical engineers in university hospital networks, pharmacy chain category managers, and connected device firmware architects. Secondary sources included ANSM medical device registration databases, EU MDR CE marking directories, hospital procurement contract disclosures, and trade flow records for infrared sensor components. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the forecast period.
Forecast inputs considered technology adoption curves, regulatory certification timelines, and channel shift dynamics across the projection horizon. Segmentation dimensions modeled encompassed product form factor, connectivity tier, end-use environment, and regional healthcare infrastructure maturity. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-referencing against analogous medical device category trajectories. Specific inputs included ANSM enforcement intensity indices and telemedicine platform partnership velocity.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth, sensor component pricing, or shipping cost volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and technology diffusion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Global Tactile Sensor Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Europe Proximity Sensors Market