
 Europe Bancassurance Market | 2026-2036
Europe Bancassurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bancassurance Market Intelligence
Capital-intensity divergence between integrated banking-insurance conglomerates and standalone distributors is rotating competitive advantage toward firms with captive balance sheets. Crédit Agricole Assurances leverages its mutual banking roots to sustain exclusive distribution across rural France. Allianz SE anchors its position through proprietary risk models that differentiate pricing in German-speaking markets. AXA Group competes via digital platform investments that extend reach beyond traditional branch networks.
Bancassurance denotes the distribution of insurance products through banking channels, combining credit underwriting data with actuarial risk assessment to price policies embedded within savings, lending, and retirement products. Life insurance dominates premium flows due to long-duration liabilities matching bank deposit bases, while health insurance grows fastest among retail customers seeking supplementary coverage beyond public systems. Online platforms capture rising share among SMEs purchasing general insurance, though financial advisors retain margin concentration in high net worth investment-linked policies.
Solvency II, the EU Insurance Distribution Directive, and national conduct regulators including France's Autorité de Contrôle Prudentiel et de Résolution shape capital reserves, commission disclosure, and product governance requirements across European jurisdictions. EIOPA stress-testing protocols force alignment between bank liquidity frameworks and insurance liability durations. Stakeholders must monitor evolving digital conduct standards and embedded finance regulations that could redraw permissible distribution mechanics.
Market Dynamics
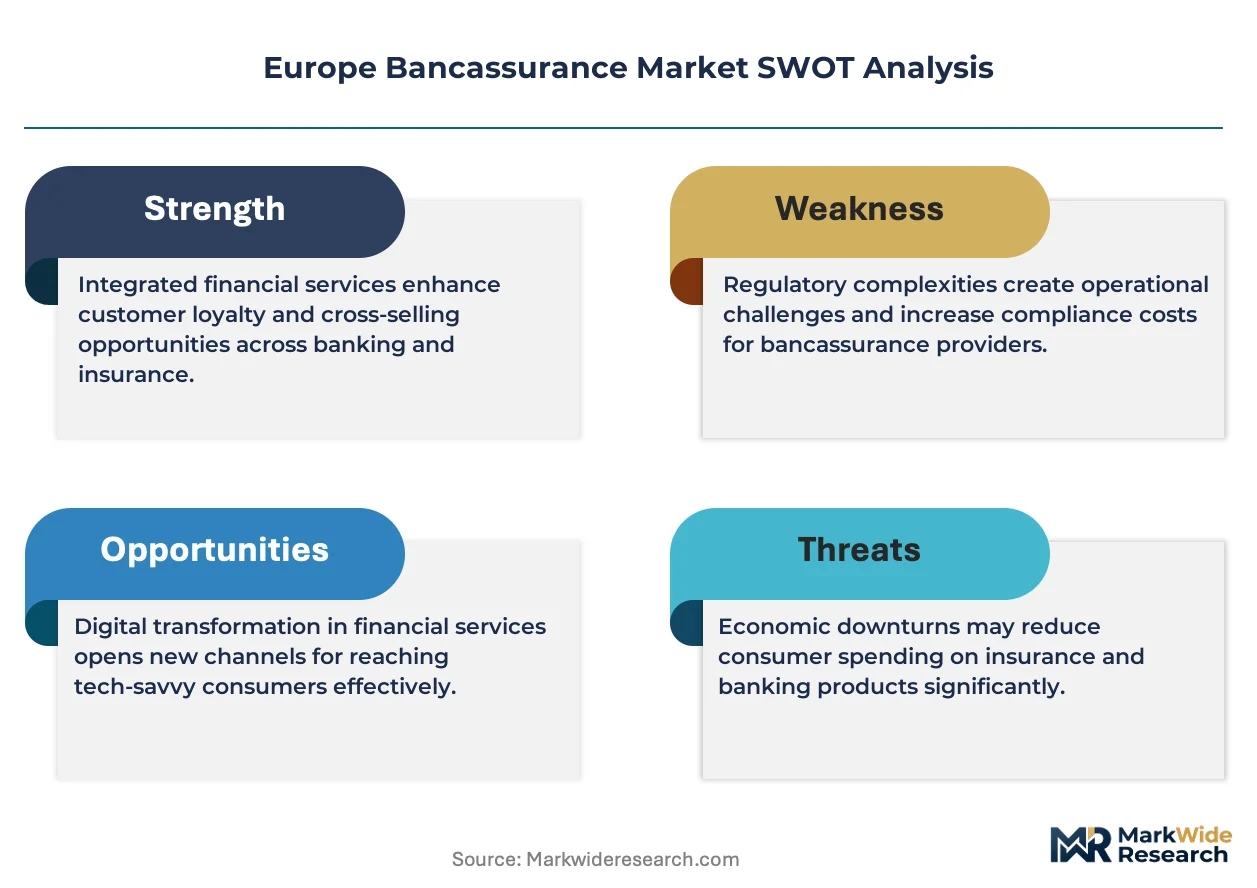
Solvency II capital requirements and the EU Insurance Distribution Directive are compressing product margins while forcing distributors to rebuild compliance architectures around customer-centric disclosure standards.
Growth Catalysts
- Embedded finance integration:Banking APIs now embed insurance quotes directly into mortgage and savings account workflows, collapsing purchase friction for retail customers in France and Italy.
- EIOPA stress-testing alignment:Harmonized liquidity frameworks between bank and insurance balance sheets reduce capital arbitrage costs for integrated conglomerates operating across eurozone jurisdictions.
- Rural branch density:Mutual banking networks in Southern France and Northern Spain sustain exclusive distribution access where digital penetration remains structurally lower than urban corridors.
Market Restraints
- Commission disclosure compression:The EU Insurance Distribution Directive mandates explicit fee breakdowns that erode opaque pricing power historically embedded in bundled products.
- Legacy IT integration costs:Core banking systems running on decades-old architectures require multimillion-euro modernization to support real-time policy issuance and claims processing.
- Long-duration liability mismatch:Life insurance reserves tied to guaranteed minimum returns strain against persistently low eurozone sovereign yields, squeezing spread income.
Strategic Opportunities
- SME general insurance digitization:Online platforms capture underserved small business segments in Portugal and Greece where traditional branch economics fail to justify dedicated advisor coverage.
- Supplementary health coverage:Public system gaps in Italy and Spain create white space for private hospital cash and dental riders distributed through payroll-linked banking channels.
- Open finance convergence:PSD2 data sharing combined with insurance scoring algorithms enables dynamic premium pricing tied to actual account behavior rather than static risk pools.
Industry Challenges
- Actuarial-data science hybrid talent:Firms struggle to recruit professionals fluent in both traditional liability modeling and machine-learning underwriting automation.
- Multi-jurisdiction product governance:National conduct regulators in France, Germany, and Italy impose divergent pre-approval timelines for identical policy structures, fragmenting launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bancassurance Market |
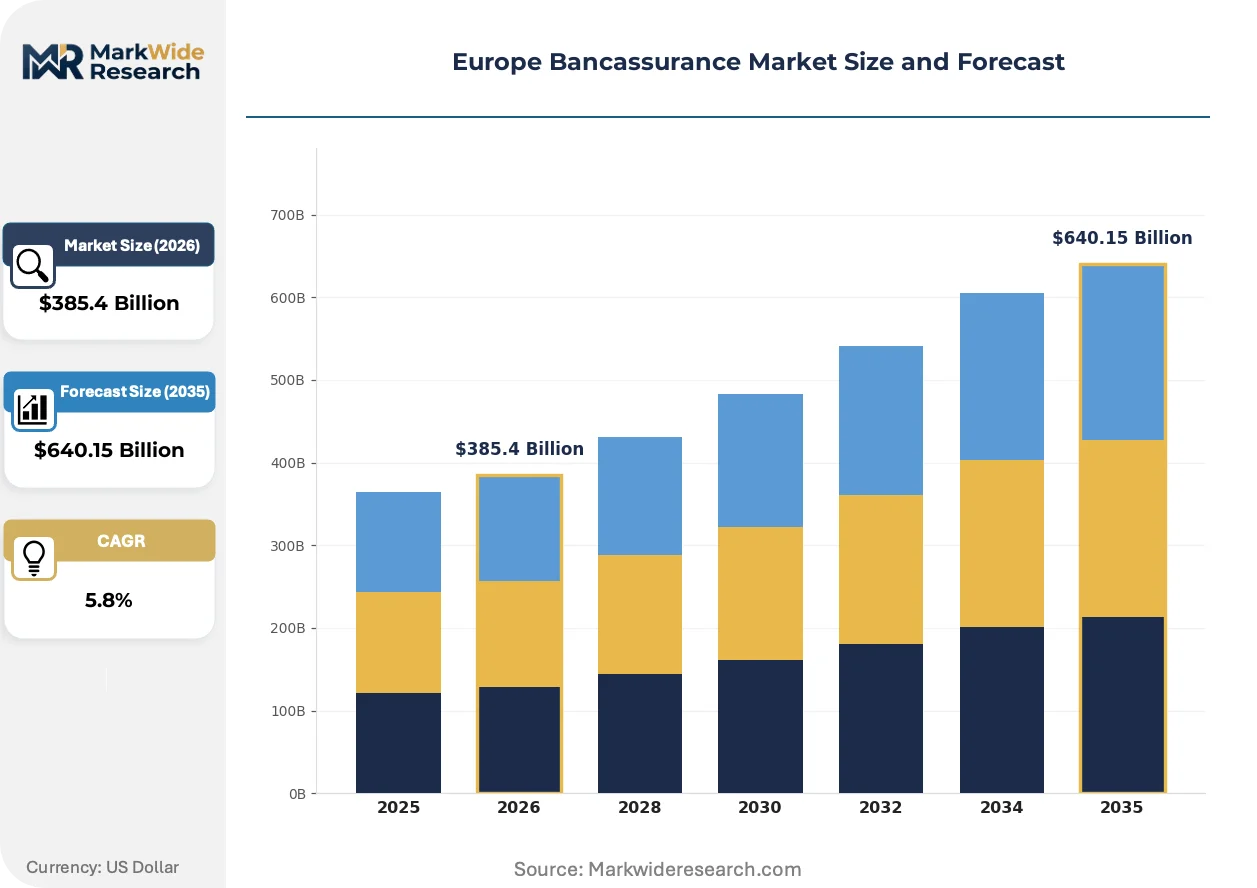
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $640.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, General Insurance, Investment Products Distribution Channel: Direct Sales, Financial Advisors, Online Platforms, Telephone Sales Customer Segment: Retail Customers, Corporates, SMEs, High Net Worth Individuals Service Type: Wealth Management, Risk Management, Claims Management, Policy Servicing |
| Companies Covered | Intesa Sanpaolo Vita, Santander Mapfre, Crédit Agricole Assurances, Allianz SE, Generali Group, BNP Paribas Cardif, CNP Assurances, AXA Group, CaixaBank / SegurCaixa Adeslas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bancassurance Market Strategic Shifts & Innovations
Digital infrastructure investments are dissolving the traditional boundary between banking transaction data and insurance risk assessment, enabling real-time product personalization that static application forms cannot replicate.
Application programming interfaces connecting core banking systems to insurance policy administration platforms are decomposing the traditional bancassurance value chain. Mid-tier banks in Spain and Portugal now white-label insurer technology stacks rather than building proprietary distribution layers. This compression favors technology vendors with modular, cloud-native architectures over legacy mainframe-dependent incumbents.
The EU Insurance Distribution Directive's product governance requirements are forcing manufacturers to document target market assessments before any distribution agreement. French and German regulators now conduct thematic reviews of remuneration structures, pushing banks toward fee-based advisory models that decouple compensation from premium volume. Southern European markets lag this transition by approximately two implementation cycles.
Retail customers increasingly initiate insurance research through mobile banking apps rather than branch appointments or independent broker consultations. This channel migration concentrates purchase influence among user experience designers and data analytics teams rather than traditional financial advisors. Italian banking groups report the steepest channel shift, with digital origination shares doubling across life and non-life categories within three years.
Europe Bancassurance Market Segmentation
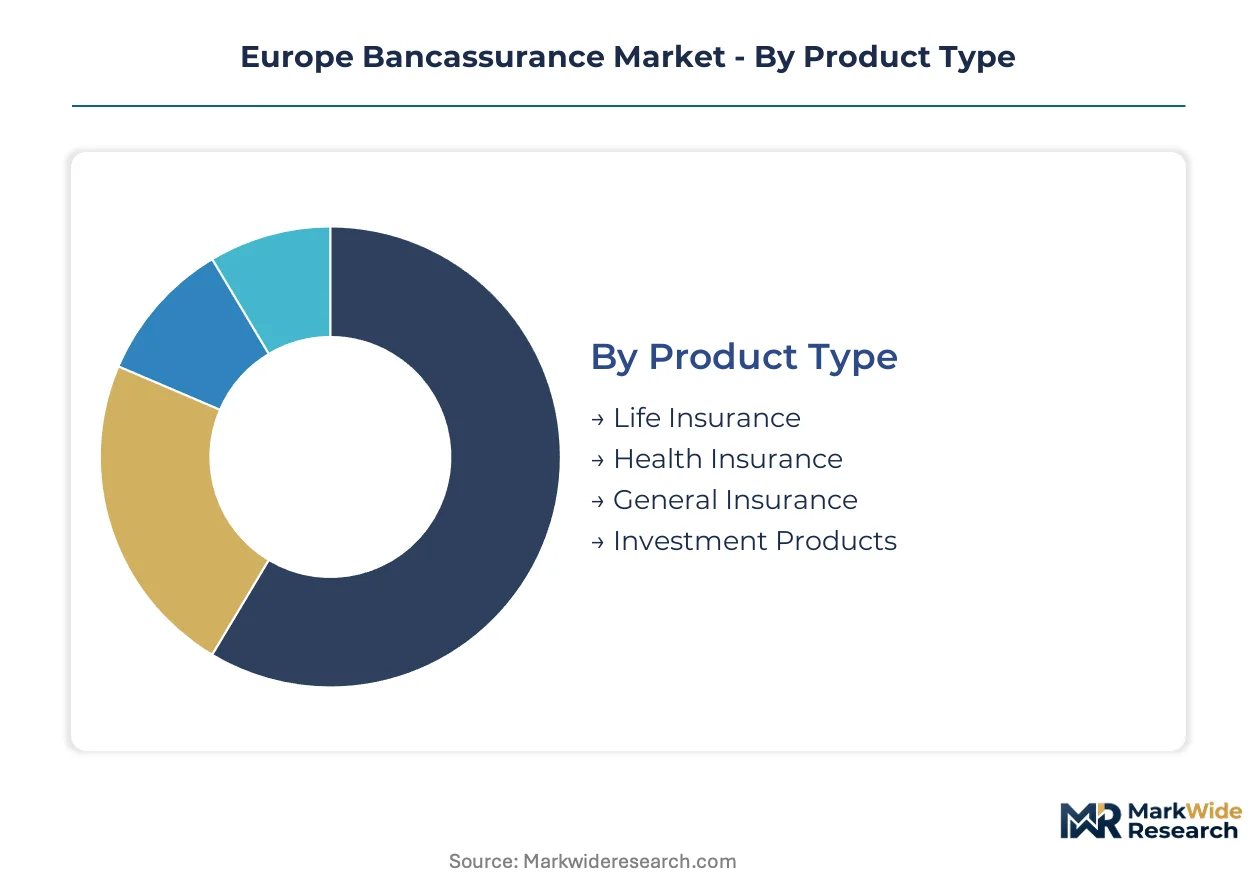
Segmentation in bancassurance determines capital allocation between long-duration liabilities and short-tail general insurance products. Solvency II reporting requirements force insurers to track segment-level risk concentrations across banking distribution networks.
Product Type:
Solvency II capital charges vary sharply between guaranteed life products and unit-linked policies, reshaping manufacturer priorities across European jurisdictions.
- Life Insurance:Long-duration contracts with guaranteed minimum returns dominate premium flows in France and Italy. EIOPA stress-testing forces alignment between these liabilities and bank deposit durations, compressing spread income in low-yield environments.
- Health Insurance:Supplementary hospital cash and dental riders address coverage gaps in Spain and Italy's public systems. Payroll-linked distribution through banking channels captures employed retail segments seeking tax-advantaged protection products.
- General Insurance:Property and motor policies distributed via banking networks serve mortgage customers requiring mandatory coverage.
- Investment Products:Unit-linked life wrappers combine insurance tax treatment with mutual fund exposure, popular in Germany's private pension market.
Established volume favors Life Insurance; emerging adoption favors Health Insurance.
Distribution Channel:
Cost-to-serve economics diverge fourfold between branch-based advice and automated digital origination, concentrating investment in hybrid models.
- Direct Sales:Branch employees at mutual banking networks in rural France maintain exclusive access where digital penetration lags urban corridors.
- Financial Advisors:Fee-based models decoupling compensation from premium volume gain regulatory favor under EU Insurance Distribution Directive disclosure mandates.
- Online Platforms:API-embedded quote engines now initiate policy research for Italian retail customers through mobile banking apps.
- Telephone Sales:Remains relevant for complex product explanations where regulatory script requirements demand human interaction.
Margin concentration sits with Financial Advisors; volume expansion concentrates in Online Platforms.
Customer Segment:
Balance sheet scale determines product access, with HNW individuals capturing bespoke investment-linked structures unavailable to mass retail.
- Retail Customers:Mass-market savings-linked life policies dominate branch network throughput in Southern Europe.
- Corporates:Group risk and pension arrangements require dedicated relationship management separate from retail banking infrastructure.
- SMEs:Underserved by traditional branch economics, Portuguese and Greek small businesses migrate to digitized general insurance platforms.
- High Net Worth Individuals:Investment-linked policies with discretionary asset allocation command dedicated advisor coverage and specialized underwriting.
Policy count concentrates among Retail Customers; premium per contract peaks with High Net Worth Individuals.
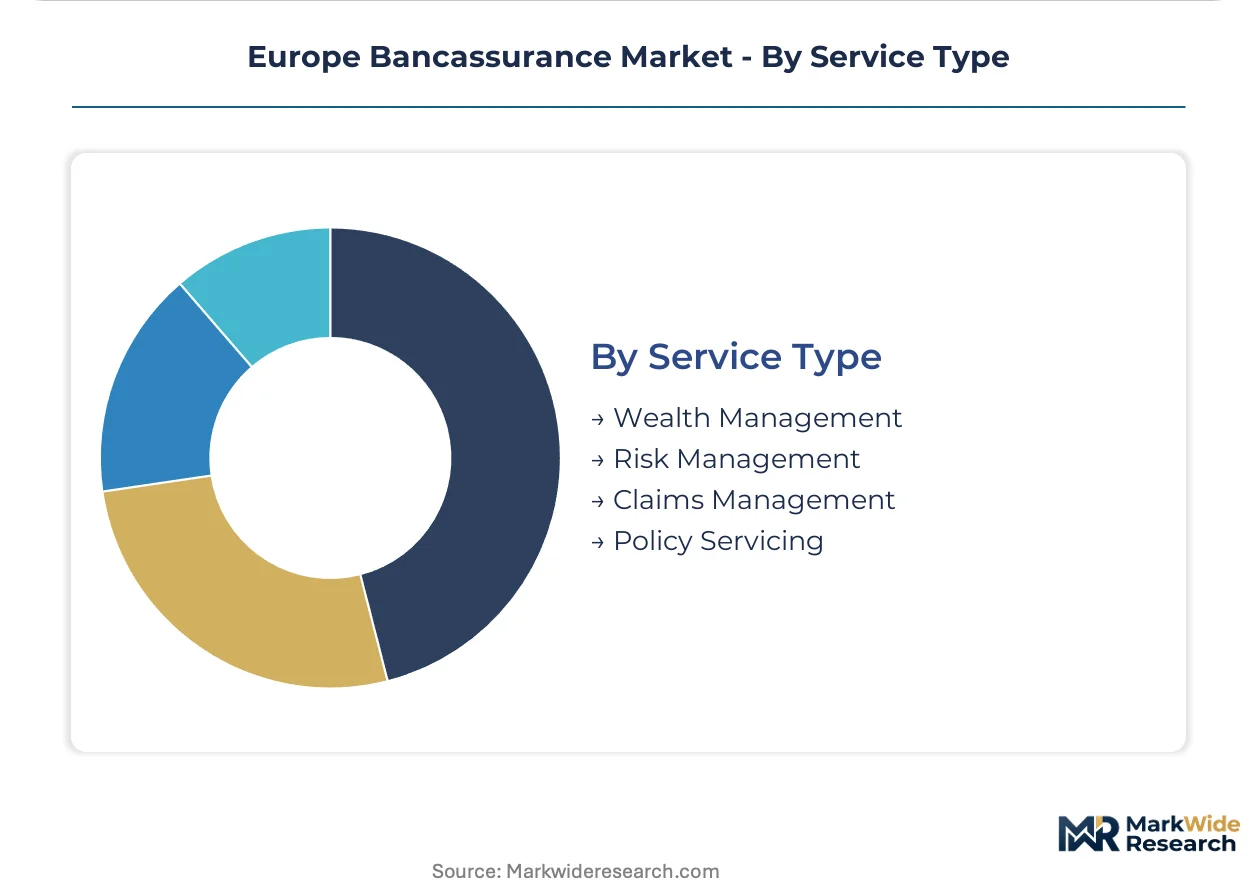
Service Type:
Regulatory conduct standards now extend to post-sale servicing, forcing documentation of claims handling timelines across all touchpoints.
- Wealth Management:Integrated insurance-investment advisory captures recurring fee income from long-duration savings products.
- Risk Management:Corporate bancassurance partnerships embed property and liability coverage within lending covenants.
- Claims Management:Real-time processing capabilities differentiate digital-native distributors from legacy mainframe-dependent incumbents.
- Policy Servicing:Premium collection and beneficiary updates sustain ongoing banking relationship touchpoints.
Revenue stability favors Wealth Management; operational differentiation concentrates in Claims Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian retail customers demonstrate the highest price elasticity in life insurance selection, while French mutual banking members show markedly lower sensitivity due to embedded relationship structures. German-speaking markets occupy a middle ground where digital comparison tools compress margins without displacing branch loyalty.
France
Rural mutual banking networks sustain exclusive distribution access across Brittany and Normandy where digital penetration trails Paris by fifteen percentage points. France's Autorité de Contrôle Prudentiel et de Résolution enforces strict commission disclosure timelines that compress product bundling economics. Lyon-based Crédit Agricole regional federations maintain captive insurance penetration above national averages through payroll-linked savings products.
Italy
Mobile-first policy origination has doubled digital share across Intesa Sanpaolo and UniCredit networks within thirty-six months. Italy's IVASS conduct regulator mandates explicit fee breakdowns that erode historical opaque pricing in bundled bancassurance products. Milan and Turin banking clusters concentrate unit-linked life insurance distribution where affluent retail segments seek tax-advantaged wrappers.
Germany
Allianz and Commerzbank partnerships anchor proprietary risk pricing through integrated data pools spanning credit and actuarial histories. BaFin supervision aligns bank liquidity frameworks with insurance liability durations under EIOPA stress-testing protocols. Frankfurt and Munich financial centers host captive bancassurance operations where investment-linked products capture private pension demand.
Spain
Santander-Mapfre and CaixaBank-SegurCaixa alliances dominate branch-based distribution across Catalonia and Madrid metropolitan corridors. Spain's DGSFP conduct authority enforces product governance documentation that delays launch schedules relative to Northern European peers. Barcelona and Valencia banking clusters drive supplementary health insurance growth through payroll-deducted hospital cash products.
Portugal
SME general insurance digitization accelerates as traditional branch economics fail to justify dedicated advisor coverage for sub-million-euro enterprises. Portugal's ASF insurance supervisor applies EU Insurance Distribution Directive standards with shorter pre-approval timelines than Spanish or Italian counterparts. Lisbon and Porto fintech clusters incubate API-embedded quote engines that white-label insurer technology stacks.
Europe Bancassurance Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in European bancassurance, with mutual banking groups and global insurers occupying distinct competitive positions. The integrated tier commands captive balance sheet advantages that reduce capital arbitrage costs across eurozone jurisdictions. Three archetypes define the competitive set: mutual banking-insurance conglomerates with exclusive rural distribution, global insurers with proprietary risk models, and digital platform specialists. Consolidation through exclusive distribution renewals and technology stack partnerships represents the dominant competitive trajectory.
Within the mutual banking tier, Crédit Agricole Assurances exemplifies exclusive rural distribution anchored in cooperative ownership structures. Among global diversified insurers, Allianz SE and AXA Group occupy positions differentiated by Germanic risk modeling capabilities and digital platform investments respectively. These three entities represent the archetype spectrum spanning cooperative embeddedness, technical underwriting specialization, and channel modernization.
| Leading Market Players |
|---|
| Intesa Sanpaolo Vita |
| Santander Mapfre |
| Crédit Agricole Assurances |
| Allianz SE |
| Generali Group |
| BNP Paribas Cardif |
| CNP Assurances |
| AXA Group |
| CaixaBank / SegurCaixa Adeslas |
| Others |
Cost & Logistics Intelligence
Solvency II capital requirements gate both manufacturer qualification and product price differentiation across European bancassurance markets. EIOPA stress-testing protocols force alignment between bank liquidity frameworks and insurance liability durations, compressing spread income for guaranteed life products while rewarding unit-linked structures with lower capital charges.
Pricing Analysis
Policy servicing and claims management fees drive lifetime customer value beyond initial premium collection. Three-tier pricing structure across premium, standard, and economy levels stratifies by advisor involvement and digital origination channel. Price differentiation rests on Solvency II capital efficiency and embedded finance API integration depth. Cost compression in mass-market life products is intensifying because mobile-first customers bypass branch advisory fees. SMEs purchasing general insurance through online platforms exhibit highest price sensitivity; high net worth individuals seeking investment-linked wrappers show lowest elasticity.
Supply Chain Analysis
Just-in-time policy issuance through API-embedded banking workflows dominates over strategic reserve-building of legacy IT capacity. Technology concentration sits with cloud-native vendors in Ireland and Estonia, while proprietary risk modeling capabilities anchor in Germany and France. Raw material dependencies include actuarial software licenses, core banking system integration modules, and regulatory reporting infrastructure. Single-source vulnerability runs through legacy mainframe-dependent incumbents unable to modernize claims processing. Distribution runs through exclusive mutual banking networks in rural France and Northern Spain alongside digital platforms capturing Italian retail migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency gaps in actuarial-data science hybrid talent constrain expansion velocity for integrated bancassurance conglomerates and standalone distributors alike. Firms fluent in both traditional liability modeling and machine-learning underwriting automation command disproportionate pricing power in product personalization.
For Market Incumbents: Compound captive balance sheet advantages through deeper EIOPA stress-testing alignment across eurozone jurisdictions. Acquire cloud-native policy administration platforms to collapse legacy IT integration timelines. Defend against white-label technology vendors by embedding proprietary risk scoring directly into core banking APIs. For New Entrants and Emerging Players: Anchor in SME general insurance digitization across Portugal and Greece where traditional branch economics fail. Target supplementary health coverage gaps in Spain and Italy's public systems through payroll-linked banking channels. Pursue open finance convergence combining PSD2 data sharing with dynamic premium pricing algorithms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital platform specialists requiring multimillion-euro modernization spend. Long-term viability favors firms with mutual banking roots sustaining exclusive rural distribution or global insurers with proprietary risk models. Watch EIOPA digital conduct standards as inflection signal for permissible distribution mechanics redraw.| Strategic Initiative | Industry Significance |
|---|---|
| API-embedded Policy Issuance | Collapses purchase friction for Italian retail customers initiating research through mobile banking apps. |
| Cloud-native Technology Stack Migration | Replaces decades-old mainframe architectures supporting real-time claims processing across Spanish banking networks. |
| Fee-based Advisory Model Transition | Aligns French and German distributor compensation with EU Insurance Distribution Directive disclosure mandates. |
| Supplementary Health Product Launch | Captures tax-advantaged protection demand from employed retail segments in Barcelona and Valencia banking clusters. |
| Open Finance Data Partnership | Enables dynamic premium pricing tied to actual account behavior rather than static risk pools across PSD2 frameworks. |
Research Approach
Initial hypotheses were tested against primary input from bancassurance product heads, regulatory affairs directors, digital channel strategists, and mutual banking network executives and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including EIOPA stress-testing disclosures, national conduct regulator thematic reviews, SEC filings of listed insurers, and eurozone banking sector liquidity reports. Bottom-up policy origination data triangulated against top-down premium flow estimates across the analysis window.
Variance decomposition separated volume drivers from price-mix effects across segmentation dimensions including product type, distribution channel, customer segment, and service type. CAGRs were derived from modeled liability duration alignment with bank deposit bases and projected digital origination share shifts. Forecast inputs incorporated Solvency II capital charge trajectories and embedded finance regulatory evolution.
Material uncertainties — EIOPA digital conduct standard revisions, eurozone sovereign yield persistence, and mutual banking consolidation waves — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation timelines and technology adoption curves. Revision becomes warranted when EIOPA stress-testing protocols materially alter capital charge differentials between guaranteed and unit-linked products.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Djibouti Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Embedded Insurance Market
Insurance
North America Liability Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
GCC Health Insurance Market
Insurance
Travel Insurance Market
Insurance
Peru Insurance Market
Insurance
Green Insurance Market
Insurance
Digital Monetary Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market