
 Europe Online Insurance Market | 2026-2036
Europe Online Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Insurance Market Foresight
Market Dynamics and Competitive Landscape
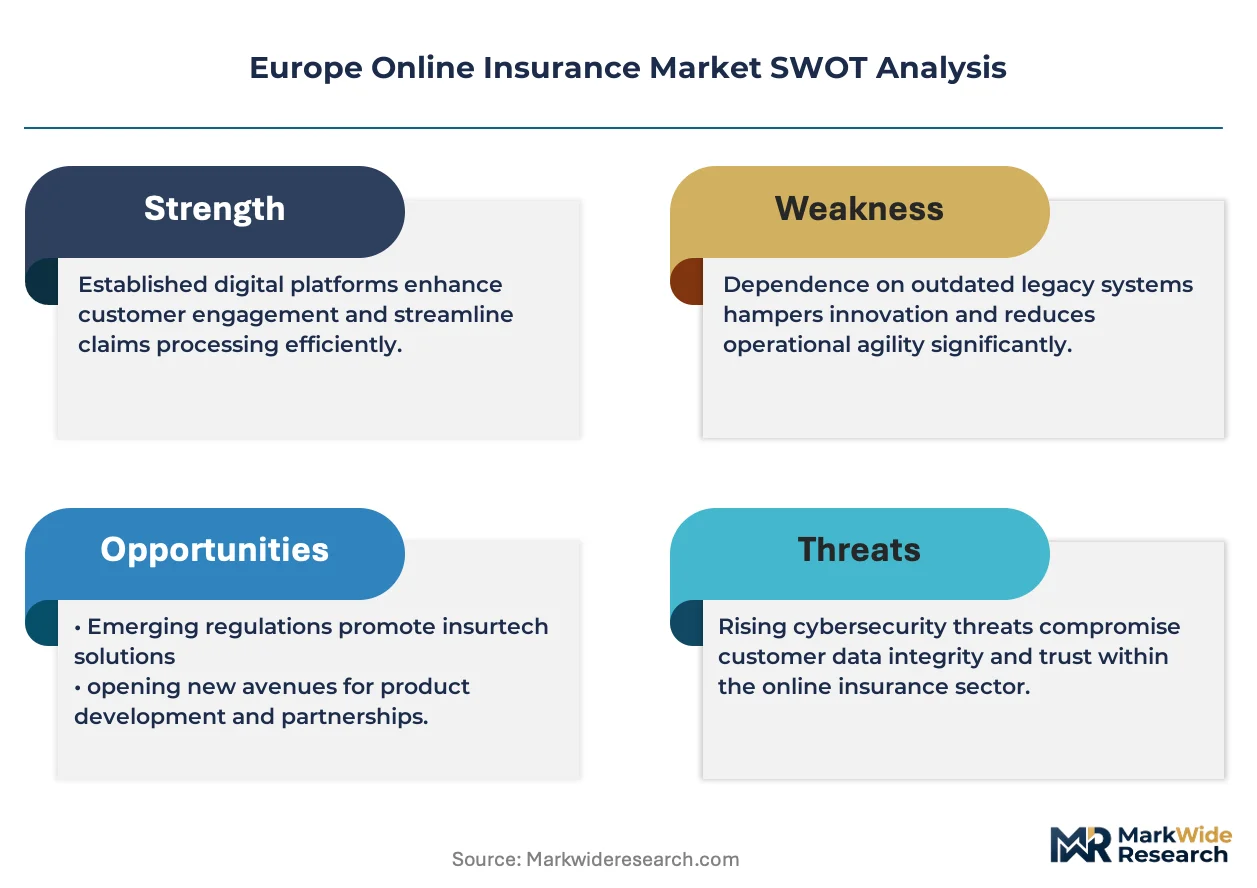
CE marking for digital insurance platforms is bifurcating the competitive landscape between established carriers and insurtech entrants. Generali Group leverages its captive agency network to sustain distribution control across Southern Europe. Wefox Insurance AG differentiates through its hybrid broker-aggregator model that anchors revenue in Germany and Austria. Allianz Direct competes on price transparency via its direct-to-consumer portal, while Getsafe specializes in app-first micro-policies targeting mobile-native demographics.
Technical Definition and Segment Architecture
Europe online insurance denotes risk-transfer contracts distributed, underwritten, and serviced through internet-enabled channels without mandatory physical agent involvement, typically integrating APIs for real-time pricing and claims adjudication. The primary commercial purpose is reducing acquisition costs while expanding addressable risk pools through automated eligibility screening and instant policy issuance. Auto insurance within the Insurance Type segment dominates premium volume due to regulatory compulsory coverage requirements across EU member states. Direct Sales within the Delivery Model segment captures the fastest expansion as carriers bypass aggregator commissions. Partner Networks, including embedded offerings at automotive dealerships and travel booking platforms, concentrate margin pools through contextual purchase-triggered conversions.
Regulatory Environment and Strategic Outlook
GDPR governs policyholder data processing across all EU jurisdictions, while the EU AI Act imposes conformity obligations on automated claims decisions and risk-scoring algorithms. EIOPA's conduct standards shape product transparency and digital disclosure requirements, directly influencing platform architecture and customer onboarding flows. National regulators such as BaFin in Germany and the FCA in the UK enforce supplementary licensing conditions for cross-border digital distribution. Stakeholders must monitor whether upcoming EU Digital Operational Resilience Act implementation will force infrastructure redundancy investments that alter cost structures for cloud-native entrants.
Market Dynamics
Embedded insurance APIs are decomposing traditional distribution hierarchies by inserting coverage at the point of transaction rather than through standalone policy purchases. This structural shift compresses customer acquisition costs while fragmenting premium pools across non-traditional intermediaries.
Growth Catalysts
- EU AI Act compliance pathways:Automated underwriting algorithms gaining regulatory clearance accelerate deployment of real-time risk scoring across digital platforms. Insurers invest in explainable AI architectures to satisfy conformity assessment requirements.
- Automotive embedded partnerships:Dealerships and mobility platforms integrate compulsory auto coverage into vehicle financing workflows. Germany's KBA registration data feeds directly into policy issuance systems.
- Cloud-native core systems:API-first policy administration platforms replace legacy mainframe infrastructure. Carriers reduce per-policy servicing costs through containerized microservices architectures.
Market Restraints
- GDPR data localization:Cross-border policyholder data transfers face adequacy decision dependencies. UK-EU data flows require supplementary contractual clauses that delay platform rollouts.
- Legacy system integration costs:Mainframe policy administration systems resist real-time API connectivity. Migration capex absorbs 18-24 months of digital channel revenue.
- Aggregator commission compression:Price comparison sites extract 15-25% of premium value. Direct channel investments struggle to offset established traffic dependencies.
Strategic Opportunities
- Poland and Romania digital penetration:Underdeveloped agency networks create first-mover advantages for app-first distribution. Smartphone-native demographics bypass traditional intermediation entirely.
- Parametric climate coverage:Satellite-indexed crop and property policies trigger automatic payouts without loss adjustment. EIOPA's sandbox frameworks enable pilot programs.
- Open Insurance data standards:PSD2-inspired account information sharing extends to policy and claims data. Consent-based portability reduces switching friction.
Industry Challenges
- Actuarial-technologist translation gaps:Underwriting teams lack fluency in machine learning model validation. Model risk management functions struggle to document algorithmic decision trees for BaFin examinations.
- Legacy core system entanglement:Policy administration platforms from the 1990s resist microservices decomposition. Greenfield digital insurers bypass this constraint entirely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Insurance Market |
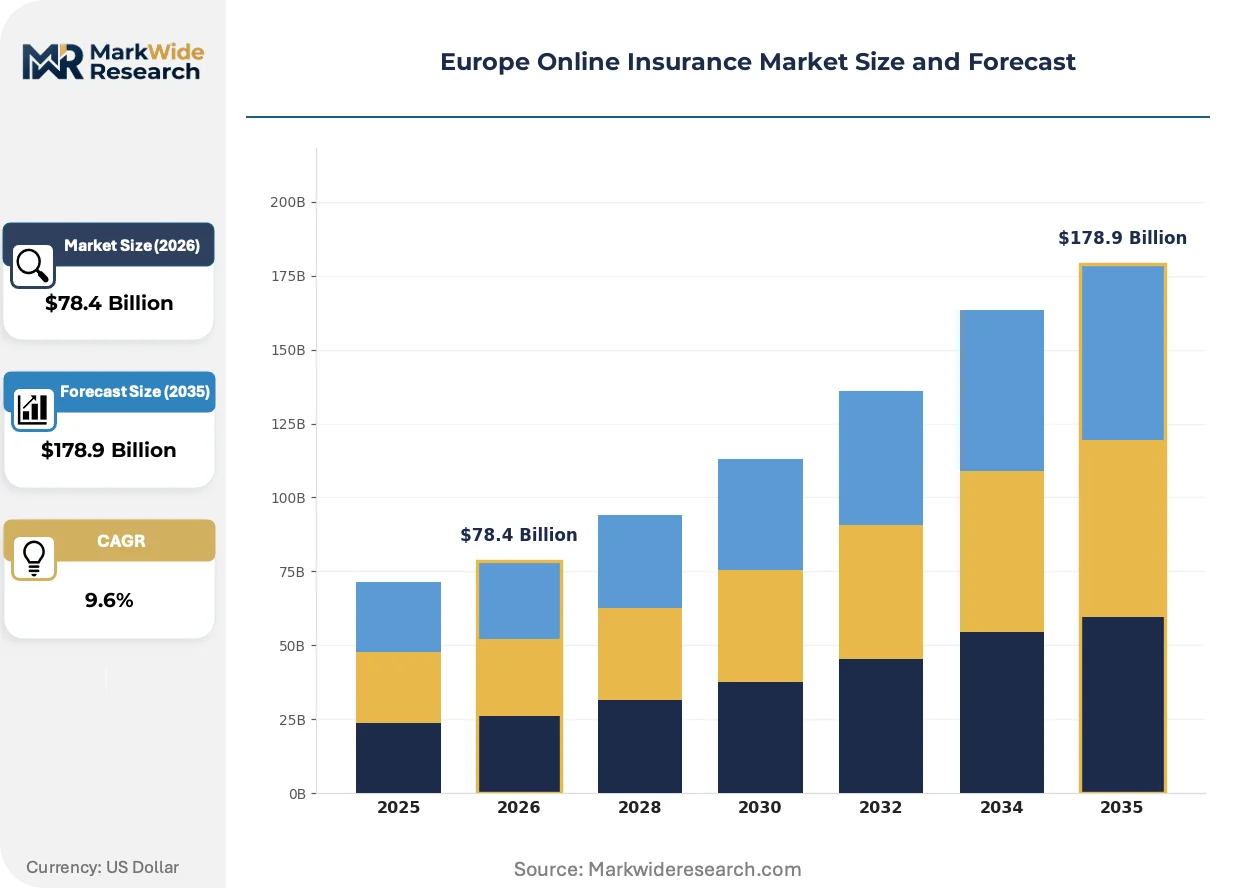
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Direct Sales, Aggregator Sites, Partner Networks, Mobile Apps Customer Type: Individuals, Small Businesses, Corporates, Startups Insurance Type: Health Insurance, Auto Insurance, Life Insurance, Property Insurance Premium Tier: Low, Mid, High, Luxury |
| Companies Covered | Generali Group, Wefox Insurance AG, Allianz Direct, Getsafe, Lemonade, Inc., AXA Group, Aviva plc, INZMO, Zurich Insurance Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Insurance Market Shifts & Advancements
Real-time data streams from connected devices and transactional platforms are reconstructing risk assessment from static demographic buckets to dynamic behavioral signals. This transformation compresses pricing cycles and fragments traditional pooling mechanisms.
Telematics-based usage insurance is decomposing annual premium models into per-mile or per-trip micro-contracts. Fleet operators and gig-economy drivers in Germany and the Netherlands adopt pay-as-you-drive coverage through smartphone sensors. This granularity compresses cross-subsidies between high and low-mileage policyholders.
EIOPA's Digital Operational Resilience Act implementation deadlines force infrastructure redundancy investments. Cloud-native insurers must demonstrate geographic failover capabilities and third-party risk management frameworks. The regulation particularly affects UK-authorised firms seeking EU market access through temporary permissions.
Aggregator-dependent customer acquisition is giving way to embedded distribution at point-of-sale. Travel platforms and e-commerce checkouts insert cancellation and warranty coverage without separate shopping journeys. France and Spain lead this shift where digital retail penetration exceeds insurance direct channel adoption.
Europe Online Insurance Market Segmentation
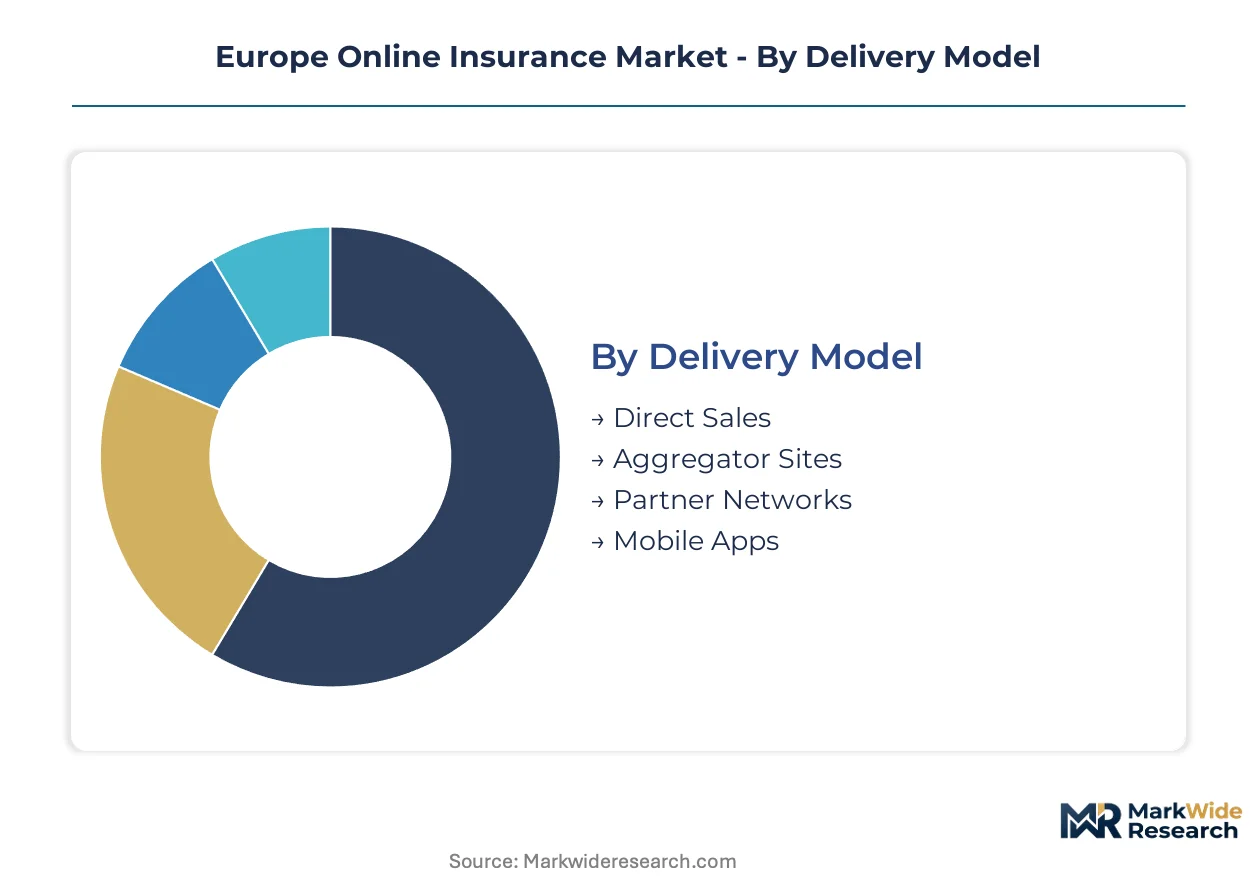
Segmentation in Europe online insurance reveals how distribution economics, customer sophistication, and regulatory complexity fragment addressable markets. Understanding these divisions exposes where automated underwriting investments yield disproportionate returns versus where legacy intermediation persists.
Delivery Model:
Substitution pressure from embedded APIs is most acute where aggregator commissions have institutionalized price transparency as the primary purchase driver.
- Direct Sales:Carrier-owned portals bypass intermediary commissions entirely. Germany's BaFin licensing requirements for cross-border direct writers concentrate investment in compliant platform architecture. Real-time pricing engines and instant policy issuance capabilities define competitive viability.
- Aggregator Sites:Price comparison platforms consolidate consumer traffic through standardized quote interfaces. Commission structures extract 15-25% of premium value, forcing carriers to optimize for conversion velocity rather than margin retention.
- Partner Networks:Embedded distribution at automotive dealerships and travel booking platforms inserts coverage at transaction points. Contextual purchase triggers reduce shopping friction.
- Mobile Apps:Smartphone-first interfaces target digitally native demographics with micro-policy offerings. Push notification engagement replaces traditional renewal cycles.
Direct Sales anchors the volume base while Mobile Apps gain share at the steepest rate.
Customer Type:
Cost tier stratification separates automated eligibility screening investments from manual underwriting requirements.
- Individuals:Mass-market personal lines dominate transaction volume through standardized risk profiles. GDPR consent management and instant claims adjudication expectations shape platform design.
- Small Businesses:Commercial coverage for sub-50 employee enterprises migrates fastest to digital channels. Simplified question sets and API-connected payroll data replace traditional loss runs.
- Corporates:Large enterprise risk placement retains broker intermediation for complex coverage structuring. Digital tools supplement rather than replace relationship-based placement.
- Startups:Venture-backed emerging companies demand flexible, month-to-month coverage without multi-year commitments. Parametric and usage-based products align with cash-flow volatility.
Individuals generate the highest transaction velocity while Small Businesses exhibit the steepest expansion trajectory.
Insurance Type:
Application-specific regulatory mandates determine where compulsory coverage guarantees addressable demand versus discretionary purchase friction.
- Auto Insurance:EU member state compulsory coverage requirements lock in premium volume. Germany's KBA registration data feeds directly into real-time policy issuance systems. Telematics integration enables usage-based pricing granularity.
- Health Insurance:National healthcare system variations fragment digital distribution potential. Supplementary private coverage faces divergent tax treatment across France, Germany, and Netherlands.
- Life Insurance:Long-duration contracts resist instant digital issuance due to medical underwriting requirements. Simplified issue products gain traction among younger demographics.
- Property Insurance:Homeowners and renters coverage integrates with mortgage and rental platform workflows. Satellite-indexed parametric products enable automatic payout triggers.
Auto Insurance commands the premium base while Property Insurance climbs fastest through embedded distribution partnerships.
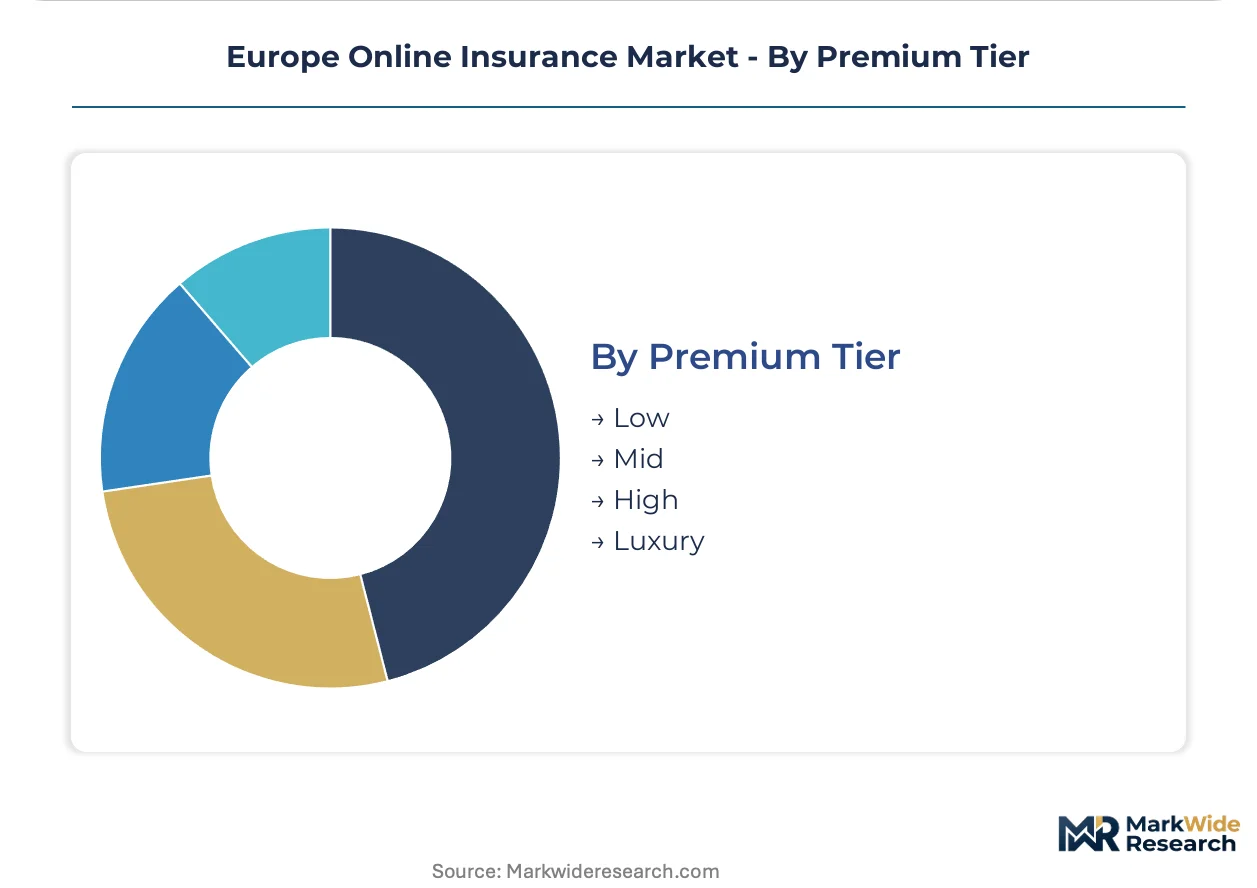
Premium Tier:
Margin concentration separates mass-market automation investments from high-touch advisory requirements.
- Low:Stripped-down coverage with minimal service layers targets price-sensitive segments. Automated claims handling and chatbot support maintain unit economics.
- Mid:Balanced coverage depth with moderate customization options captures mainstream demand. Digital self-service coexists with human escalation pathways.
- High:Comprehensive coverage with concierge claims service retains agent involvement. Digital tools enhance rather than replace advisory relationships.
- Luxury:Bespoke coverage for high-net-worth individuals requires specialized underwriting expertise. White-glove service delivery resists full automation.
Mid-tier policies generate the broadest volume while Low-tier offerings expand most quickly through app-first distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digitally native policyholders in Germany and Austria drive premium concentration, while embedded distribution partnerships reshape acquisition economics across Southern and Eastern Europe.
Germany
KBA registration data feeds directly into real-time auto policy issuance systems, accelerating embedded coverage at automotive dealerships. BaFin enforces supplementary licensing conditions for cross-border digital distribution, elevating compliance costs for foreign entrants. Berlin-Brandenburg hosts Wefox Insurance AG's hybrid broker-aggregator operations, anchoring revenue in automated underwriting platforms.
United Kingdom
FCA conduct standards shape product transparency requirements for direct-to-consumer portals, influencing platform architecture investments. Post-Brexit data adequacy dependencies delay UK-EU policyholder data transfers, complicating cross-border servicing. London's insurtech cluster concentrates app-first micro-policy development targeting mobile-native demographics.
France
ANSM and CNIL jointly supervise health data processing for supplementary private coverage, fragmenting digital distribution potential. E-commerce checkout integration for cancellation and warranty coverage outpaces direct channel adoption in digital retail. Île-de-France anchors AXA Group's embedded partnership networks with travel and mobility platforms.
Spain
Automotive dealership embedded partnerships concentrate margin pools through contextual purchase-triggered conversions for compulsory coverage. National tax treatment variations for supplementary health products resist standardization across EU member states. Madrid and Barcelona host Generali Group's captive agency network sustaining distribution control across Southern Europe.
Poland
Underdeveloped traditional agency networks create first-mover advantages for smartphone-first distribution bypassing intermediation entirely. EIOPA's sandbox frameworks enable pilot programs for parametric climate coverage indexed to satellite data. Warsaw's emerging insurtech cluster attracts venture capital targeting digitally underserved small business segments.
Europe Online Insurance Market Competitive Landscape
Player mix skews toward established carriers with captive distribution networks, though insurtech entrants gain share through API-first architectures. The competitive landscape bifurcates between legacy mainframe-dependent institutions and cloud-native challengers. Three archetypes dominate: hybrid broker-aggregators blending digital efficiency with agent relationships, direct-to-consumer portals competing on price transparency, and embedded distribution specialists inserting coverage at transaction points. Dominant competitive moves include strategic partnerships with automotive and travel platforms, plus technology licensing agreements accelerating legacy system modernization.
Within the hybrid broker-aggregator tier, Wefox Insurance AG and Getsafe exemplify contrasting approaches to digital-native customer acquisition. Among established carrier direct channels, Allianz Direct occupies a position defined by instant policy issuance capabilities and real-time pricing engines. Generali Group anchors the captive agency archetype, its Southern European network resisting pure digital disintermediation through relationship-based servicing. These three companies represent the structural tension between legacy distribution control and API-enabled platform economics reshaping premium flows across the continent.
| Leading Market Players |
|---|
| Generali Group |
| Wefox Insurance AG |
| Allianz Direct |
| Getsafe |
| Lemonade, Inc. |
| AXA Group |
| Aviva plc |
| INZMO |
| Zurich Insurance Group |
| Others |
Supply & Pricing Matrix
Thirty-to-forty-five-day platform deployment cycles concentrate vendor selection power among German and Irish cloud infrastructure providers, compressing margins for carriers locked into legacy mainframe servicing agreements. This lead-time band tightens pricing discipline across embedded API partnerships while elevating cost transparency for direct-channel entrants.
Pricing Analysis
Cost-plus contracts with cloud infrastructure providers index compute and storage costs to AWS, Azure, or Google Cloud regional pricing tiers. Three-tier pricing structure across premium, standard, and economy levels segments policyholders by claims service depth and digital engagement intensity. Pricing pressure stems from aggregator commission compression extracting 15-25% of premium value, forcing direct channel investments. Price-sensitive individual policyholders in Poland and Romania gravitate toward stripped-down app-first offerings, while luxury-tier buyers in Germany and France retain advisory relationships.
Supply Chain Analysis
Germany and Ireland anchor cloud-native core system development, housing API-first policy administration platforms and embedded insurance orchestration layers. Ireland draws from EU data center concentration and GDPR-compliant hosting infrastructure. Germany sources underwriting algorithms and telematics integration modules. Supply chain risk centers on single-source vulnerability for real-time KBA registration data feeds. Distribution runs through hybrid broker-aggregator networks, direct-to-consumer portals, and automotive dealership embedded partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe online insurance operates as a service-attach opportunity where claims servicing APIs and usage-based policy administration layers expand premium retention faster than standalone coverage sales.
For Market Incumbents: Consolidate distribution control through captive API partnerships with automotive and travel platforms, neutralizing embedded entrant threats. Deepen backward integration into proprietary telematics data streams to reduce third-party scoring dependencies. Lock in BaFin and FCA licensing moats through compliant platform architecture investments that delay foreign challenger rollouts. For New Entrants and Emerging Players: Anchor in Poland and Romania's underdeveloped agency networks, where smartphone-first demographics bypass traditional intermediation entirely. Target small business commercial coverage with API-connected payroll data replacing loss runs. Pursue parametric climate pilots through EIOPA sandbox frameworks as the fastest regulatory clearance pathway. For Investors and Strategic Acquirers: Long-term, this sits as a data-aggregation play because policyholder behavioral signals from connected devices reconstruct risk assessment economics. Acquisition targets should display cloud-native core systems and embedded distribution partnerships. Watch EIOPA Digital Operational Resilience Act implementation deadlines as the inflection signal forcing infrastructure redundancy investments that alter cloud-native entrant cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded API Partnership | Inserts coverage at automotive and travel transaction points, compressing acquisition costs. |
| Cloud-Native Core Migration | Replaces legacy mainframe infrastructure with containerized microservices, reducing per-policy servicing costs. |
| EU AI Act Compliance Investment | Accelerates automated underwriting deployment through explainable AI architectures satisfying BaFin examinations. |
| Telematics Data Integration | Enables usage-based pricing granularity for pay-as-you-drive coverage in Germany and Netherlands. |
| Parametric Product Pilot | Leverages EIOPA sandbox frameworks for satellite-indexed climate coverage with automatic payout triggers. |
Research Methodology
Initial hypotheses were tested against primary input from insurance platform CTOs, digital distribution heads at established carriers, insurtech product managers, and regulatory affairs specialists at BaFin and EIOPA, and refined through secondary validation. Sources included EIOPA conduct standards documentation, BaFin cross-border licensing circulars, GDPR adequacy decision records, and carrier annual reports. Bottom-up transaction volume estimates triangulated against top-down premium pool assessments.
Variance decomposition across delivery model, customer type, insurance type, and premium tier dimensions shaped the analytical framework. CAGRs derived from segment-level growth rate distributions weighted by addressable policyholder populations. Forecast inputs incorporated EU AI Act implementation timelines and cloud infrastructure cost trajectories across the projection horizon.
Material uncertainties — regulatory delay in automated underwriting approvals, data adequacy disruption for UK-EU flows, and legacy system migration cost overruns — sit outside the modeled envelope. Forecasts reflect assumptions about sandbox framework expansion and embedded partnership penetration rates. Recalibration cycles align with material shifts in EIOPA digital operational resilience requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Europe Car Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
US Extended Warranty Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Business Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
EV Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Boiler Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Usage-Based Insurance for Automotive Market