
 Canada Cyber (Liability) Insurance Market | 2026-2036
Canada Cyber (Liability) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cyber (Liability) Insurance Market Outlook
Zero-trust architecture deployment is narrowing the attack surface that traditional perimeter-based policies were designed to cover, forcing underwriters to rebuild actuarial models from endpoint behavior rather than network topology. Chubb Limited leverages decades of specialty lines expertise to anchor high-limit towers for large corporations with complex digital supply chains. Intact Financial Corporation sustains dominant domestic distribution through its integrated broker network and proprietary risk engineering services. Coalition competes by embedding continuous security scanning directly into policyholder dashboards, creating a feedback loop between loss prevention and premium adjustment.
Cyber liability insurance constitutes a financial risk-transfer mechanism that indemnifies organizations against first-party recovery costs and third-party liability arising from unauthorized data access, network interruption, or digital asset destruction; policies typically specify waiting periods, sub-limits for social engineering fraud, and retroactive dates that bound coverage to discovered events. The primary commercial purpose centers on stabilizing enterprise balance sheets against unpredictable remediation expenses, regulatory penalties, and litigation cascades that follow confirmed breaches. Claims-made structures dominate Canadian policy issuance because they align premium collection with active exposure periods and simplify reserving for insurers. Privacy liability coverage commands the deepest margin pools as provincial privacy statutes impose statutory damages that outstrip traditional negligence frameworks. Small enterprises represent the fastest-growing end-user category as managed security service providers bundle insurance with remote monitoring, lowering barriers to entry.
Health Canada, the Office of the Privacy Commissioner of Canada, and provincial privacy commissioners jointly shape demand through mandatory breach reporting thresholds and escalating penalty schedules that make self-insurance untenable for regulated entities. OSFI's Guideline B-13 on technology and cyber risk management imposes baseline security expectations that insurers reference in underwriting questionnaires, effectively converting supervisory guidance into market access criteria. Stakeholders must monitor whether federal critical infrastructure legislation expands mandatory coverage to additional sectors beyond finance and energy, as this would restructure available capacity and pricing dynamics across the domestic market.
Market Dynamics
Zero-trust security architectures are dismantling the perimeter-based risk assumptions that underpinned two decades of cyber underwriting, forcing actuaries to rebuild models around endpoint behavior telemetry rather than network topology maps.
Growth Catalysts
- OSFI Guideline B-13:The Office of the Superintendent of Financial Institutions mandates baseline technology and cyber risk management standards that insurers embed directly into underwriting questionnaires, converting supervisory expectations into binding coverage criteria.
- Ransomware frequency in healthcare:Health Canada and provincial privacy commissioners impose mandatory breach notification timelines that make self-insurance economically untenable for hospitals and clinics.
- Metropolitan corridor concentration:Finance and retail enterprises in Toronto, Montreal, and Vancouver generate concentrated demand for high-limit towers as digital supply chain complexity escalates.
Market Restraints
- Actuarial data scarcity:Limited historical claims datasets for emerging threat vectors like supply chain compromise prevent accurate loss modeling and compress available capacity.
- Reinsurance market concentration:Global reinsurers in London and Bermuda dominate retrocession capacity, transmitting international pricing volatility directly to Canadian primary markets.
- Social engineering sub-limits:Policy structures cap coverage for business email compromise at levels that leave mid-sized enterprises exposed to their fastest-growing loss category.
Strategic Opportunities
- Managed security service bundling:Remote monitoring providers in Ontario and British Columbia integrate insurance distribution into technical service contracts, lowering acquisition costs for small enterprises.
- Continuous security telemetry:Real-time vulnerability scanning embedded in policyholder portals enables dynamic premium adjustment tied to measured risk posture rather than static questionnaire responses.
- Critical infrastructure expansion:Federal legislation under consideration would extend mandatory coverage requirements beyond finance and energy into transportation and telecommunications verticals.
Industry Challenges
- Cyber actuary shortage:The domestic talent pool lacks sufficient depth in both information security and property-casualty pricing to support rapid market expansion.
- Retroactive date disputes:Claims-made policy structures generate litigation over when discovered events actually commenced, complicating reserving and claims settlement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cyber (Liability) Insurance Market |
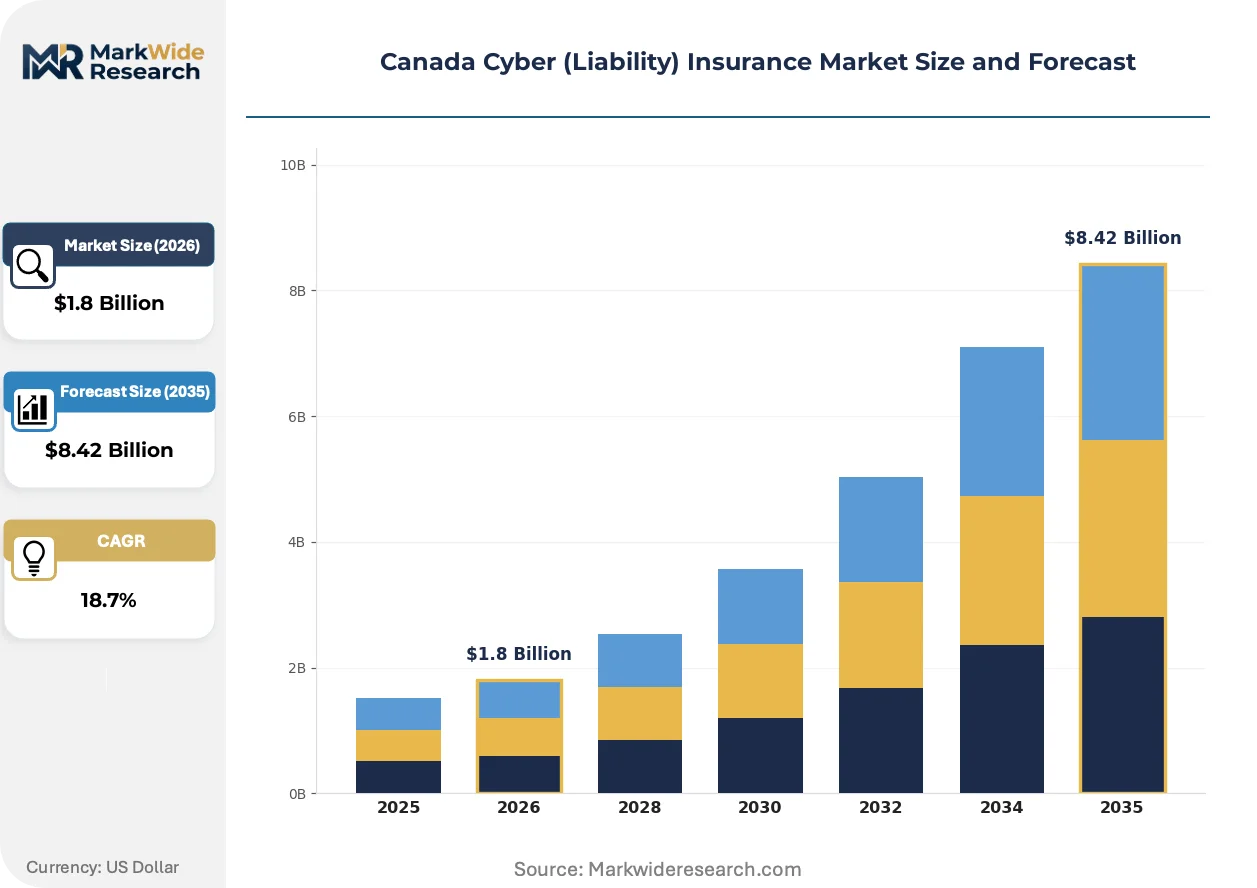
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Healthcare, Finance, Retail, Manufacturing Policy Type: Claims Made, Occurrence, Cyber Extortion, Data Breach Coverage Type: Privacy Liability, Network Security, Media Liability, Regulatory Defense End User: Small Enterprises, Medium Enterprises, Large Corporations, Public Sector |
| Companies Covered | Intact Financial Corporation, Chubb Limited, AIG Canada, Zurich Canada, CNA Canada, Travelers Canada, Hiscox, Aviva Canada, Coalition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cyber (Liability) Insurance Market Strategic Shifts
Continuous monitoring technologies are collapsing the information asymmetry between insurers and policyholders, enabling real-time premium adjustment based on measured security posture rather than annual questionnaire snapshots.
Security orchestration platforms are digitizing the relationship between loss prevention and coverage pricing. Mid-sized enterprises in Ontario and British Columbia adopt these tools fastest, attracted by immediate premium reductions tied to patching velocity and multi-factor authentication deployment rates. This telemetry feedback loop compresses the traditional annual renewal cycle into continuous underwriting adjustments.
Health Canada and the Office of the Privacy Commissioner of Canada coordinate enforcement actions that tighten breach notification timelines to 72 hours. Healthcare providers respond by expanding coverage limits and purchasing dedicated regulatory penalty sub-limits that provincial privacy statutes make essential. The statutory damages framework in British Columbia and Alberta outstrips traditional negligence calculations, deepening margin pools for privacy liability specialists.
Small enterprises now purchase cyber coverage through managed security service providers rather than traditional broker channels. These technical intermediaries bundle remote monitoring with insurance placement, reducing friction for buyers lacking dedicated risk management functions. The fastest uptake occurs in Toronto and Vancouver metropolitan corridors where MSP density is highest and ransomware incidents have generated visible business interruption losses.
Canada Cyber (Liability) Insurance Market Segmentation
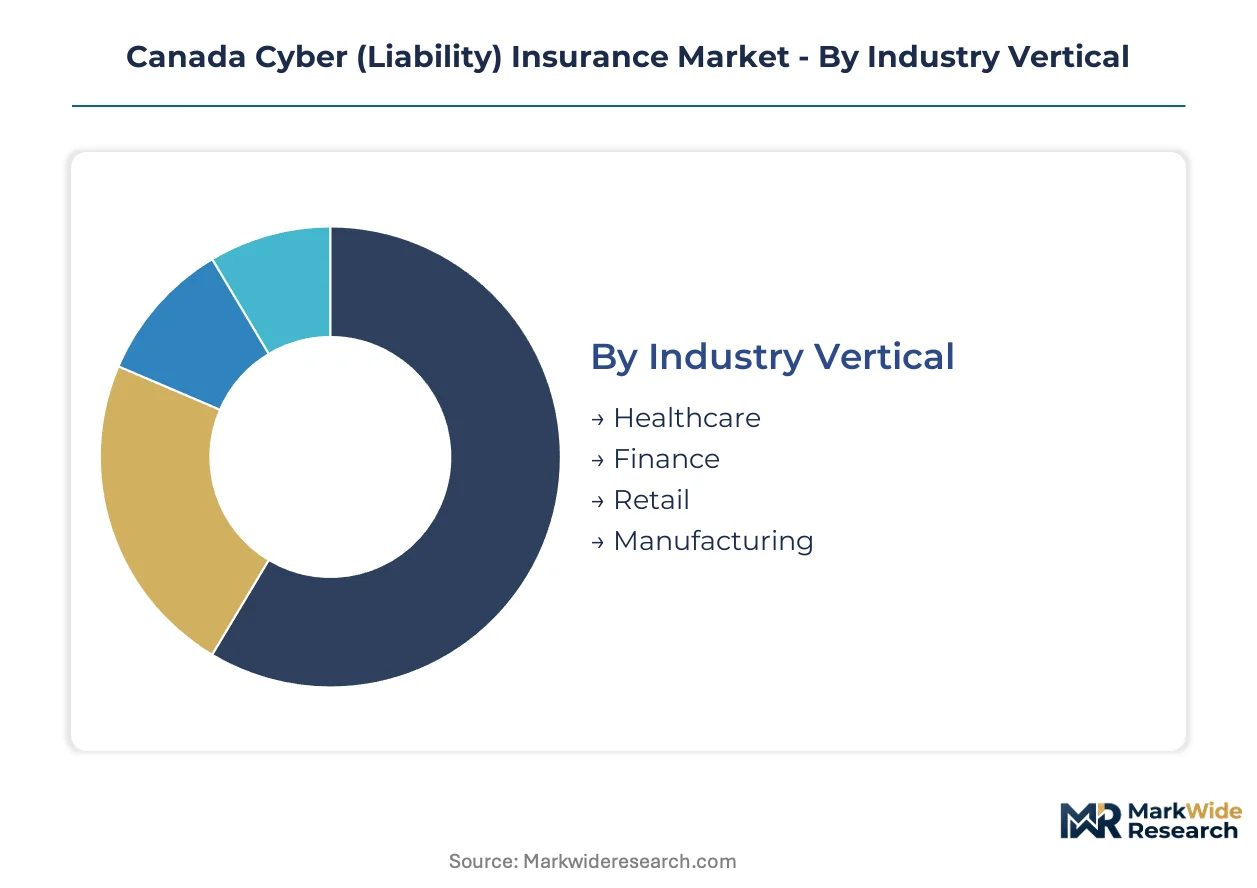
Segmentation in Canadian cyber liability insurance reveals how risk transfer mechanisms align with distinct operational exposures, regulatory pressures, and organizational scale. Each dimension shapes underwriting complexity, pricing granularity, and distribution channel selection across the domestic market.
Industry Vertical:
Healthcare policies turn over fastest as breach notification rules tighten, while manufacturing renewals stretch longest due to lower claims frequency and simpler digital footprints.
- Healthcare:Policies cover electronic health record breaches, medical device network intrusions, and provincial privacy commissioner penalties. Hospitals in Ontario and British Columbia drive demand as Health Canada mandates 72-hour notification windows that make self-insurance economically untenable.
- Finance:Coverage addresses OSFI Guideline B-13 compliance, payment card network liabilities, and securities litigation following credential compromise. Toronto metropolitan banks purchase the highest limits as digital supply chain complexity escalates third-party exposure.
- Retail:Point-of-sale system breaches and e-commerce platform interruptions dominate claims. Vancouver and Montreal corridors generate concentrated submissions as omnichannel transaction volumes expand attack surfaces.
- Manufacturing:Industrial control system coverage and operational technology network segmentation define policy structures. Lower breach frequency relative to other verticals permits extended waiting periods and reduced premiums.
Finance dominates installed base by premium volume. Healthcare is where expansion concentrates as ransomware incidents multiply and statutory damages frameworks deepen.
Policy Type:
Cost tier structures separate budget-conscious buyers seeking narrow peril coverage from enterprises purchasing comprehensive multi-peril towers.
- Claims Made:Triggers coverage when claims are first reported during the active policy period, aligning premium collection with current exposure. OSFI-supervised institutions in Toronto favor this structure for reserving predictability and simplified retroactive date management.
- Occurrence:Covers incidents happening during the policy window regardless of discovery timing. Manufacturing and public sector entities prefer this certainty for long-tail privacy exposures where breaches surface years after initial compromise.
- Cyber Extortion:Specific coverage for ransomware negotiation, cryptocurrency payments, and business interruption during system restoration. Mid-sized enterprises in British Columbia accelerate purchases as attack frequency outstrips general liability endorsements.
- Data Breach:Narrow peril coverage for notification costs, credit monitoring, and forensic investigation following confirmed unauthorized access. Small enterprises adopt this entry-level product through managed security service provider bundles.
Claims Made structures dominate transactional volume. Cyber Extortion is gaining share fastest as ransomware economics reshape buyer priorities.
Coverage Type:
Margin concentration pools deepest in segments where statutory damages outstrip traditional negligence calculations, creating pricing power for specialized underwriters.
- Privacy Liability:Addresses provincial privacy statute violations, class action settlements, and regulatory penalties. British Columbia and Alberta statutory damages frameworks generate the steepest premium rates per million dollars of coverage.
- Network Security:Covers system restoration, malware remediation, and business interruption from network failures. Finance sector buyers in Montreal prioritize this coverage as distributed workforce architectures expand endpoint vulnerability.
- Media Liability:Defends against defamation, intellectual property infringement, and content-related claims arising from digital publishing. Technology and professional services firms purchase standalone towers as user-generated content volumes grow.
- Regulatory Defense:Funds legal representation during Office of the Privacy Commissioner investigations and provincial commissioner proceedings. Healthcare providers expand these sub-limits as enforcement coordination tightens between federal and provincial regulators.
Privacy Liability commands the deepest margin pools. Regulatory Defense is expanding most quickly as multi-jurisdictional enforcement actions proliferate.
End User:
Customer type determines distribution channel selection, with small enterprises bypassing traditional brokers for technical intermediary bundles that lower acquisition friction.
- Small Enterprises:Organizations under 50 employees purchasing through managed security service providers that embed insurance into remote monitoring contracts. Toronto and Vancouver corridors show fastest uptake where MSP density intersects with visible ransomware losses.
- Medium Enterprises:Mid-sized organizations in Ontario and British Columbia accelerating purchases as social engineering sub-limits expose gaps in traditional crime policies. Continuous security telemetry enables dynamic premium adjustment tied to measured risk posture.
- Large Corporations:Complex digital supply chains requiring high-limit towers and international program coordination. Chubb Limited anchors this segment through decades of specialty lines expertise and proprietary risk engineering.
- Public Sector:Provincial hospitals, Crown corporations, and municipal governments subject to mandatory procurement rules and political risk considerations. Extended occurrence structures prevail given long-tail discovery horizons for citizen data breaches.
Large Corporations dominate premium volume. Small Enterprises are climbing the fastest as bundled distribution dismantles traditional barriers to entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finance and retail buyers in Toronto, Montreal, and Vancouver metropolitan corridors generate concentrated demand for high-limit cyber towers as digital supply chain complexity escalates.
Ontario
Toronto's banking sector drives premium volume through OSFI Guideline B-13 compliance requirements that convert supervisory expectations into binding coverage criteria. The Office of the Superintendent of Financial Institutions mandates baseline technology risk management standards that insurers embed directly into underwriting questionnaires. Healthcare providers in Ottawa and Hamilton accelerate purchases as Health Canada imposes 72-hour breach notification windows.
British Columbia
Vancouver's technology sector and Victoria's provincial government cluster create dual demand streams for privacy liability coverage. The provincial privacy commissioner's statutory damages framework outstrips traditional negligence calculations, deepening margin pools for specialized underwriters. Mid-sized enterprises in the Lower Mainland adopt continuous security telemetry fastest, attracted by premium reductions tied to patching velocity.
Quebec
Montreal's financial services and aerospace sectors purchase occurrence-based structures for long-tail privacy exposures where breaches surface years after initial compromise. The province's distinct civil law tradition shapes policy language negotiations and claims resolution frameworks. Retail omnichannel expansion in the Montreal metropolitan corridor expands attack surfaces and drives submissions for point-of-sale breach coverage.
Alberta
Calgary's energy sector and Edmonton's healthcare systems face divergent regulatory pressures that shape coverage purchasing patterns. Provincial privacy statutes impose statutory damages that make self-insurance economically untenable for hospitals and clinics. The energy corridor's operational technology networks require specialized industrial control system coverage that extends waiting periods and reduces premiums relative to other verticals.
Canada Cyber (Liability) Insurance Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered market structure where domestic distribution networks anchor volume and technology-embedded entrants capture growth segments. Intact Financial Corporation sustains dominant domestic distribution through integrated broker networks, while global specialty lines carriers anchor high-limit towers for complex digital supply chains. Two strategic archetypes dominate: incumbent property-casualty insurers with established broker relationships, and technology-native entrants bundling continuous security monitoring with coverage placement. Competitive moves concentrate on strategic partnerships with managed security service providers and portfolio diversification into adjacent technology risk lines.
Within the domestic incumbent tier, Intact Financial Corporation and Chubb Limited occupy distinct positioning. Intact's integrated broker network and proprietary risk engineering services exemplify channel-control strategy. Chubb represents global specialty lines expertise applied to high-limit towers for large corporations. Coalition sits within the technology-native archetype, embedding continuous security scanning into policyholder dashboards to create feedback loops between loss prevention and premium adjustment.
| Leading Market Players |
|---|
| Intact Financial Corporation |
| Chubb Limited |
| AIG Canada |
| Zurich Canada |
| CNA Canada |
| Travelers Canada |
| Hiscox |
| Aviva Canada |
| Coalition |
| Others |
Value Chain & Pricing Dynamics
Reinsurance market concentration in London and Bermuda determines both premium tier spreads and supply chain configuration across Canadian primary markets. Global retrocession capacity shortages transmit pricing volatility directly to domestic underwriters while compressing available limits for mid-sized enterprise buyers.
Pricing Analysis
Cost-plus treaty arrangements with London market indexation anchor primary carrier pricing structures. Three-tier pricing structure across premium, standard, and economy levels separates large corporate towers from mid-market bundled policies and small enterprise MSP-sourced coverage. Price differentiation rests on retroactive date breadth and continuous telemetry participation. Pricing pressure stems from social engineering loss frequency outpacing sub-limit adequacy. Small enterprises exhibit highest price sensitivity, while finance sector buyers in Toronto demonstrate lowest elasticity due to OSFI-mandated coverage requirements.
Supply Chain Analysis
Bermuda-based reinsurers and Lloyd's syndicates hold dominant retrocession capacity for Canadian cyber towers. Geographic supply concentration centers on Bermuda, London, and Zurich for risk-bearing capacity. Raw material dependencies include actuarial talent pools, forensic investigation networks, and legal defense panels. Single-source vulnerability runs through the narrow reinsurance intermediary layer. Distribution runs through integrated broker networks for large accounts and managed security service providers for small enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's cyber liability insurance market sits at a regulatory inflection where OSFI Guideline B-13 and Health Canada notification mandates are converting compliance requirements into compulsory coverage demand. This structural shift favors carriers with telemetry-embedded underwriting capabilities.
For Market Incumbents: Pre-empt technology-native entrants by acquiring continuous monitoring platforms or forming exclusive MSP partnerships. Anchor distribution through proprietary risk engineering services that OSFI-supervised institutions require for B-13 compliance. Defend against Coalition-style telemetry bundling by embedding security scanning into policyholder portals with dynamic premium adjustment.
For New Entrants and Emerging Players: Mid-sized enterprises in British Columbia and Ontario represent the most penetrable entry point given their accelerating purchase velocity and underserved continuous underwriting needs. Target healthcare providers facing 72-hour notification windows with regulatory penalty sub-limits as a differentiated product anchor. Partner with regional MSPs to bypass established broker networks and lower customer acquisition costs.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors specialty lines carriers with reinsurance relationships and telemetry integration capabilities. Long-term viability hinges on underwriting profitability restoration after years of loss ratio deterioration. Acquisition targets should demonstrate either proprietary risk engineering platforms or embedded security monitoring technology. Watch ransomware frequency trends and provincial statutory damage expansion as inflection indicators for capacity deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Continuous security scanning enables dynamic premium adjustment tied to measured risk posture rather than static questionnaires. |
| MSP Distribution Partnership | Managed security service provider bundling dismantles traditional broker barriers for small enterprise customer acquisition. |
| Regulatory Penalty Sub-limit Expansion | Provincial privacy commissioner statutory damages frameworks deepen margin pools for specialized privacy liability underwriters. |
| Reinsurance Capacity Securement | Bermuda and London retrocession relationships determine available limits and pricing stability for primary market towers. |
| Cyber Actuary Talent Acquisition | Domestic shortage in information security and property-casualty pricing expertise constrains rapid market expansion capability. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with underwriting executives at domestic carriers, reinsurance brokers placing Canadian risk, managed security service providers bundling coverage, and risk managers at OSFI-supervised financial institutions. Secondary validation drew from OSFI Guideline B-13 documentation, Office of the Privacy Commissioner enforcement action records, provincial privacy commissioner annual reports, and Insurance Bureau of Canada market statistics. Bottom-up policy submission analysis and top-down premium pool estimation were triangulated to establish market sizing.
Calibration against historical claims development patterns and reinsurance pricing cycles informed the projection framework. Segmentation modeling spanned industry vertical, policy structure, coverage type, and end-user scale across the analysis window. CAGRs were derived from loss cost trend analysis, regulatory expansion scenarios, and penetration rate assumptions by enterprise size. Forecast inputs included ransomware incident frequency trajectories and provincial statutory damage framework evolution.
Practitioners should monitor reinsurance market hardening indicators and federal critical infrastructure legislation progress for early signals of capacity constraint or mandatory coverage expansion. Forecasts reflect assumptions about regulatory enforcement intensity and threat actor targeting patterns that could shift with technological or geopolitical developments. Quarterly review of Lloyd's syndicate retrocession appetite and provincial privacy commissioner penalty schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Internet of Things Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
United States Dental Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
Takaful Market
Insurance
India Life and Non-Life Insurance Market
Insurance
China Group Health Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Insurance Protection Products Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Fire Insurance Market
Insurance
Event Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
China Business Income Insurance Market
Insurance
Agricultural Insurance Market