
 Canada Home Insurance Market | 2026-2036
Canada Home Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Home Insurance Market Outlook
A chronic shortage of actuarial talent specializing in catastrophe modeling is unwinding traditional pricing cycles across the sector. Intact Financial Corporation leverages proprietary flood-risk geocoding to sustain underwriting discipline in high-exposure zones. Desjardins Group anchors its Quebec franchise through mutual-ownership structures that compete on member retention rather than price alone.
Canada home insurance constitutes a property and casualty contract indemnifying residential structures and personal belongings against named perils including fire, windstorm, water damage, and liability claims, with policies typically written on all-risk or broad-form bases subject to deductibles and coverage limits. The coverage type dimension tilts toward homeowners policies as the core margin pool, while renters insurance represents the fastest-expanding segment amid urban rental growth in Toronto and Vancouver. Distribution channel dynamics show brokers controlling the majority of policy placements, though direct sales and online platforms are gaining share among digitally native customer cohorts seeking quote-comparison transparency.
OSFI supervises federally licensed insurers through capital and liquidity requirements, while provincial regulators including FSRA in Ontario and AMF in Quebec govern market conduct, policy form approval, and claims handling standards that directly shape product availability and pricing. Health Canada and PMRA coordinate on environmental hazard assessments that inform exclusion clauses for mold and contamination risks. Stakeholders must monitor how climate-stress testing mandates from federal and provincial authorities will recalibrate capital reserves and reshape coverage terms in high-catastrophe corridors.
Market Dynamics
Climate-stress testing mandates from OSFI are recalibrating capital reserves across the sector, forcing insurers to embed catastrophe models directly into pricing engines and rewrite coverage terms for high-risk corridors.
Growth Catalysts
- Flood-plain disclosure rules:Provincial regulators in Ontario and Quebec now mandate transparent risk mapping, accelerating policy uptake among informed buyers in exposed zones.
- First-time homebuyer expansion:Suburban Ontario and British Columbia are seeing concentrated demand from younger cohorts entering ownership, expanding the insured base.
- Mutual-ownership structures:Member-retention models in Quebec compete on service depth rather than price, stabilizing renewal rates.
Market Restraints
- Actuarial talent scarcity:Chronic shortages in catastrophe modeling specialists are compressing underwriting cycles and inflating compensation costs.
- Reinsurance capacity concentration:Global reinsurers are retreating from Canadian wildfire corridors, tightening retrocession markets.
- Input cost volatility:Construction material inflation and labor shortages are driving claim severity higher in property replacement.
Strategic Opportunities
- Parametric coverage expansion:Index-triggered products for flood and hail are penetrating underinsured rural markets where traditional indemnity fails.
- Digital distribution platforms:Direct-to-consumer channels are capturing digitally native renters in Toronto and Vancouver who bypass broker networks.
- Provincial climate adaptation funds:Alberta and Quebec are deploying public mitigation investments that reduce modeled losses and enable premium stabilization.
Industry Challenges
- Catastrophe model integration:Legacy policy administration systems require expensive retrofitting to ingest real-time geospatial risk feeds.
- Claims handling standardization:FSRA and AMF are tightening response-time mandates, forcing operational rewrites across multi-jurisdictional portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Home Insurance Market |
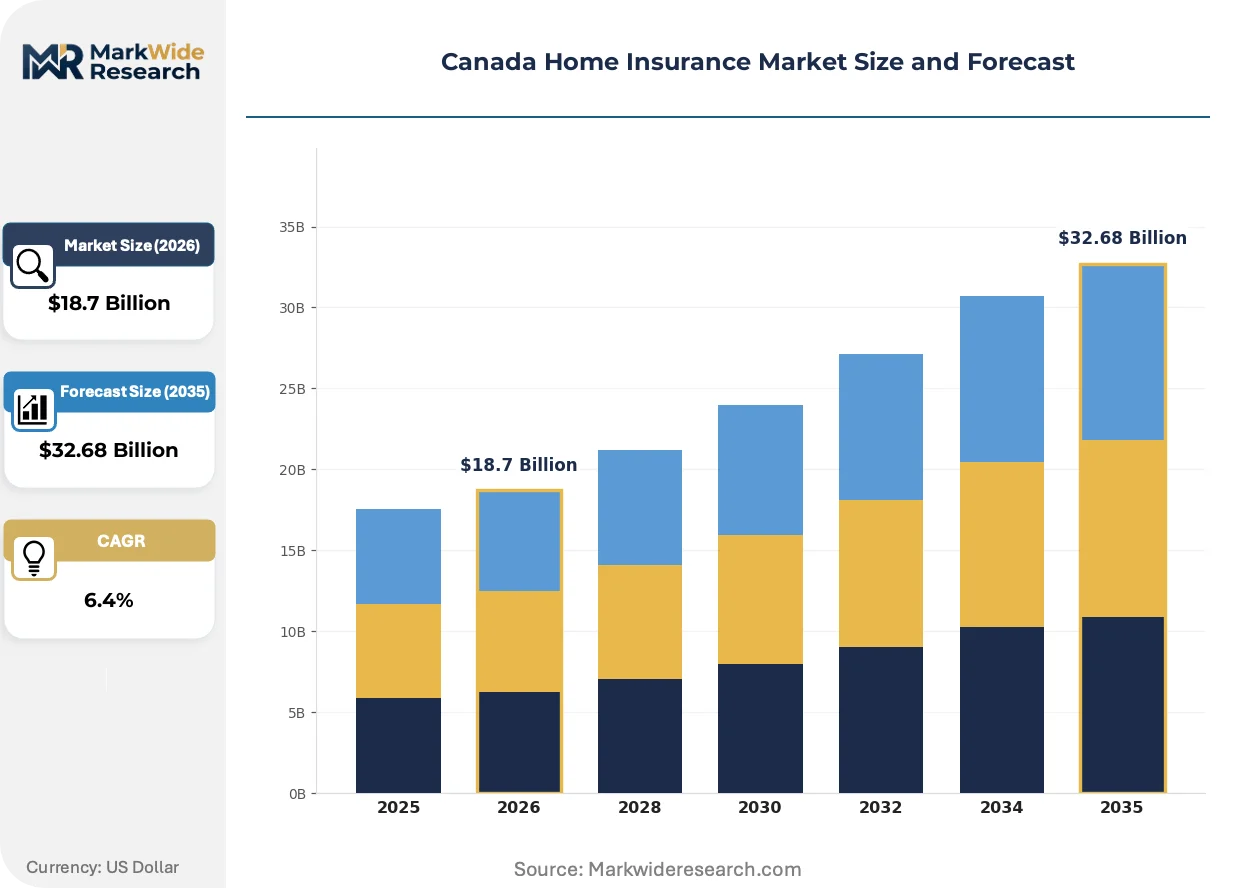
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Homeowners, Renters, Landlord, Contents Policy Type: Full Coverage, Basic Coverage, Additional Coverage, Customized Coverage Customer Type: Individual Owners, Tenants, Property Investors, Corporate Clients Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents |
| Companies Covered | The Co-operators Group, Definity Financial, Intact Financial Corporation, TD Insurance, Wawanesa Mutual, Desjardins Group, Fairfax Financial Holdings, Beneva, Aviva Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Home Insurance Market Strategic Shifts
Telematics and IoT sensor networks are penetrating residential risk assessment, shifting underwriting from retrospective loss experience to predictive prevention models.
Geospatial flood-risk geocoding is decomposing traditional territorial rating bands into property-specific pricing. Intact and regional carriers are adopting these tools in high-exposure Ontario and British Columbia corridors. The granularity is compressing cross-subsidies between adjacent properties and forcing explicit risk selection.
OSFI's B-13 guideline on climate risk management is mandating scenario analysis for all federally licensed insurers. The framework requires disclosure of transition and physical risk exposures across mortgage and property portfolios. Smaller provincially regulated entities in Saskatchewan and Manitoba face compliance gaps that favor consolidation.
Channel preferences among urban renters are fragmenting away from bundled broker placements toward unbundled digital comparison. Younger policyholders in Vancouver and Toronto now initiate quotes through aggregator platforms before selecting direct writers. This behavior is compressing acquisition costs for digital-first carriers while pressuring traditional broker commissions.
Canada Home Insurance Market Segmentation
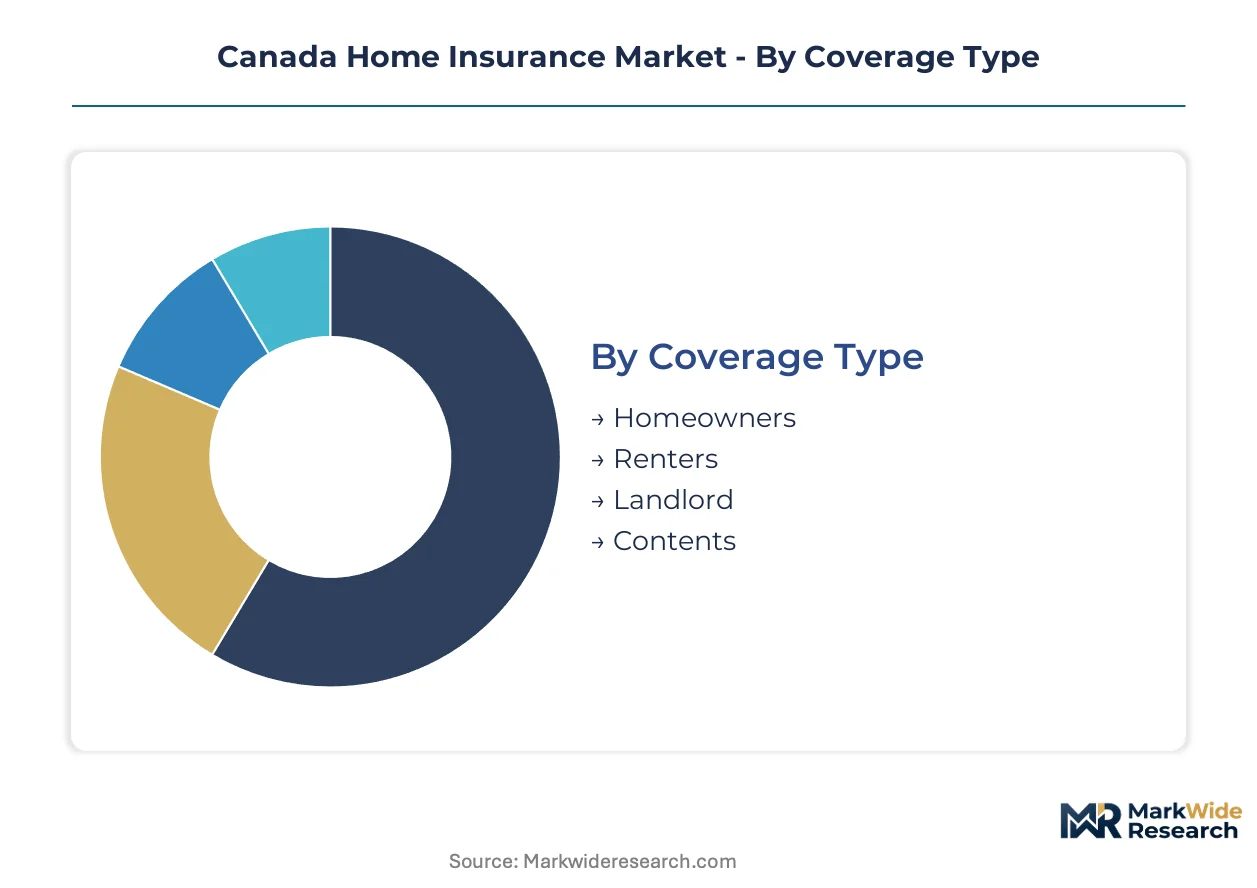
Canada home insurance segmentation reveals divergent risk profiles and margin structures across coverage forms and buyer categories. Policy construction, distribution economics, and customer lifecycle value vary substantially by segment, shaping carrier resource allocation and capital deployment priorities.
Coverage Type:
Homeowners policies face substitution pressure from bundled mortgage protection products and lender-placed coverage, forcing traditional carriers to defend policyholder relationships through service differentiation.
- Homeowners:Comprehensive dwelling and liability protection for owner-occupied residences, typically written on all-risk bases with scheduled personal property endorsements. Demand concentrates in suburban Ontario and British Columbia where first-time buyer entry is expanding the insured base amid OSFI capital adequacy recalibration.
- Renters:Contents and liability coverage for non-owner occupants, excluding structural protection. Urban rental growth in Toronto and Vancouver is driving uptake among digitally native cohorts who bypass traditional broker channels for direct-to-consumer platforms.
- Landlord:Dwelling coverage for income-producing residential properties, often with loss-of-rent provisions.
- Contents:Standalone personal property protection, frequently purchased as supplemental coverage or for specialized high-value items.
Homeowners retains volume leadership; Renters holds the steepest expansion curve.
Policy Type:
Cost tier differentiation separates mass-market basic offerings from premium full-coverage products, with margin compression most severe in the middle tier where price transparency is highest.
- Full Coverage:All-risk protection against named and unnamed perils, with replacement cost guarantees and enhanced liability limits. High-net-worth households in Quebec and Alberta are concentrating demand here as climate exposure resets coverage requirements.
- Basic Coverage:Named-peril policies covering fire, windstorm, and theft with actual cash value settlements. Cost-conscious buyers in Saskatchewan and Manitoba gravitate toward this tier amid construction cost inflation.
- Additional Coverage:Endorsements for sewer backup, overland flood, and earthquake risks.
- Customized Coverage:Bespoke policy construction for unique dwellings or specialized risk profiles.
Full Coverage commands premium pricing power; Additional Coverage is climbing the fastest as flood-plain disclosure rules accelerate rider uptake.
Customer Type:
Volume concentration tilts toward individual owners, though property investors are expanding share through portfolio-scale purchasing that reshapes carrier servicing economics.
- Individual Owners:Owner-occupants purchasing primary residence protection, representing the core retention pool for mutual insurers like Desjardins. Suburban expansion in Ontario and British Columbia is feeding new policy formation among younger demographic cohorts.
- Tenants:Non-owner occupants seeking contents and liability protection, often with lower coverage limits and higher price sensitivity. Urban density in Vancouver and Toronto is expanding this segment through rental market growth.
- Property Investors:Landlords and real estate investment trusts requiring dwelling and loss-of-rent coverage.
- Corporate Clients:Employers and housing providers arranging group coverage or master policies for employee or tenant populations.
Individual Owners retain volume leadership; Property Investors hold the steepest expansion curve.
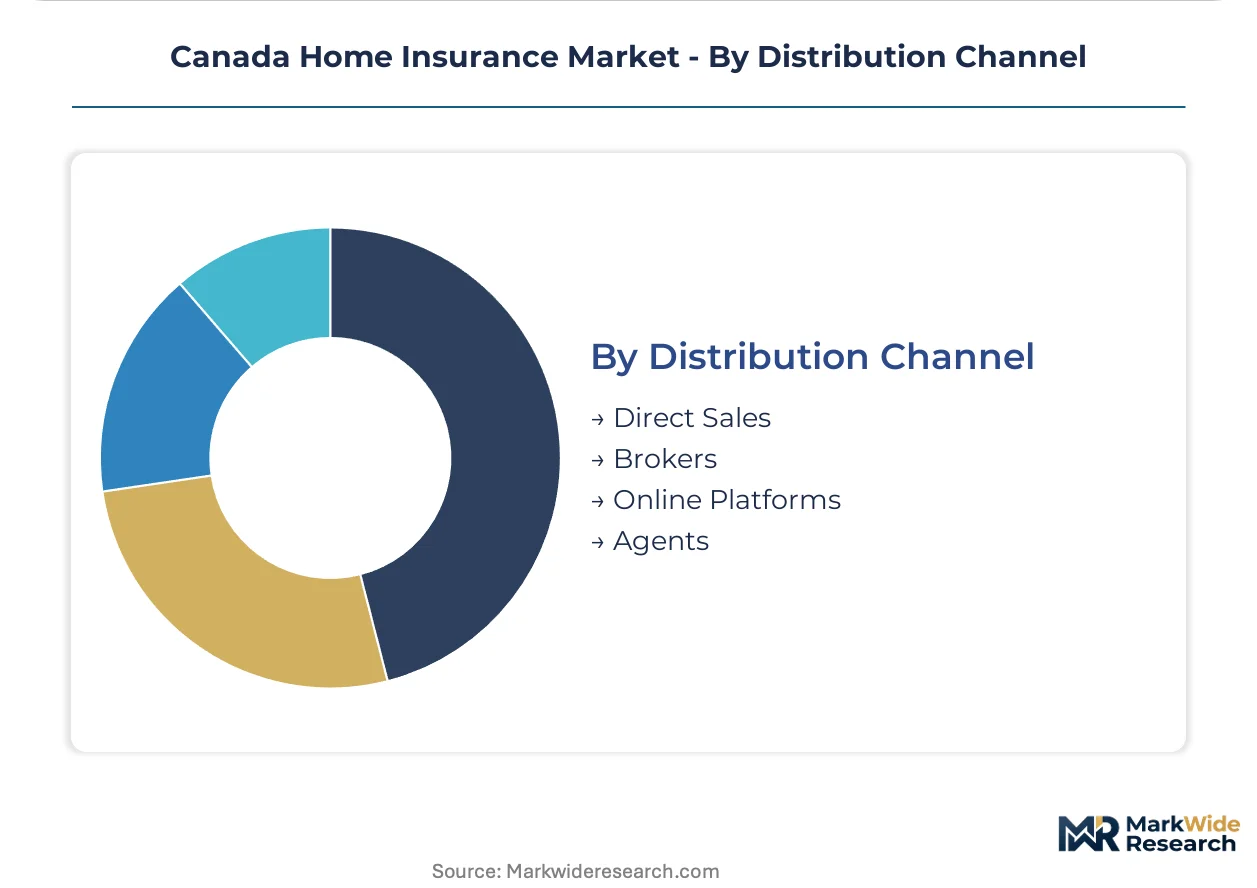
Distribution Channel:
Channel economics fragment as digital acquisition costs compress for direct writers while broker networks defend placement share through advisory relationships in complex coverage scenarios.
- Brokers:Independent intermediaries controlling majority policy placements through comparative quoting and coverage advisory. Alberta and Quebec maintain strong broker penetration where catastrophe exposure demands personalized risk assessment.
- Online Platforms:Aggregator and direct-to-consumer digital channels capturing digitally native renters in Toronto and Vancouver. Intact and regional carriers are investing here to bypass commission structures and capture behavioral data.
- Direct Sales:Carrier-owned channels including call centers and proprietary websites.
- Agents:Captive or exclusive representatives tied to single carrier product portfolios.
Brokers retain volume leadership; Online Platforms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSFI supervises federally licensed insurers through capital and liquidity requirements that anchor national underwriting standards. Provincial regulators including FSRA in Ontario and AMF in Quebec govern market conduct and policy forms that directly shape regional availability.
Ontario
First-time homebuyer expansion in suburban corridors around Toronto and Ottawa is accelerating policy formation among younger demographic cohorts. FSRA's flood-plain disclosure rules mandate transparent risk mapping that informs buyer decisions in exposed zones. The Golden Horseshoe concentration is seeing carriers embed catastrophe models directly into pricing engines as climate exposure intensifies.
Quebec
Mutual-ownership structures at Desjardins and Beneva compete on member retention rather than price alone, stabilizing renewal rates across the province. AMF oversight of policy form approval and claims handling standards shapes product construction and servicing economics. Montreal and Quebec City urban cores are experiencing rental market growth that expands renters insurance uptake through digital channels.
Alberta
Wildfire exposure in the foothills and severe-weather corridors is resetting coverage requirements and compressing cross-subsidies between adjacent properties. Provincial climate adaptation funds are deploying public mitigation investments that reduce modeled losses. Calgary and Edmonton metropolitan areas concentrate demand for full-coverage policies as high-net-worth households seek enhanced protection.
British Columbia
Earthquake risk overlays and overland flood exposure in the Lower Mainland are accelerating rider uptake for additional coverage endorsements. Provincial regulators coordinate with Health Canada on environmental hazard assessments that inform exclusion clauses. Vancouver's urban density and Victoria's suburban expansion are driving digitally native renters toward direct-to-consumer platforms bypassing traditional broker networks.
Atlantic Canada
Coastal storm surge exposure in Nova Scotia and New Brunswick is forcing explicit risk selection as geospatial pricing granularity advances. Smaller provincially regulated entities face compliance gaps with OSFI's B-13 climate risk management guidelines that favor consolidation. Halifax anchors regional carrier servicing infrastructure while rural markets remain underpenetrated for parametric coverage products.
Canada Home Insurance Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that competes on mutual-ownership structures and regional franchise depth. The sector shows moderate consolidation with national carriers controlling majority placement volume while mutual insurers defend retention through service differentiation. Strategic archetypes include integrated multi-line underwriters leveraging proprietary geocoding, mutual insurers anchored in member-retention models, and direct writers capturing digitally native cohorts. Dominant competitive moves center on catastrophe model integration into pricing engines and digital platform investments to bypass traditional broker commissions.
Within the integrated carrier tier, Intact Financial Corporation and Desjardins Group exemplify divergent strategic positioning. Intact occupies a position representing technology-forward underwriting discipline through proprietary flood-risk geocoding deployment in high-exposure corridors. Desjardins anchors the mutual-insurer archetype with member-ownership structures that prioritize retention economics over price competition in its Quebec franchise. Definity Financial sits within the regional specialist category, representing carriers that concentrate resources on specific provincial markets rather than national scale.
| Leading Market Players |
|---|
| The Co-operators Group |
| Definity Financial |
| Intact Financial Corporation |
| TD Insurance |
| Wawanesa Mutual |
| Desjardins Group |
| Fairfax Financial Holdings |
| Beneva |
| Aviva Canada |
| Others |
Value Chain & Pricing Dynamics
Proprietary catastrophe-model adoption by Intact and regional carriers is displacing traditional territorial rating bands across Ontario and British Columbia corridors, compressing cross-subsidies between adjacent properties while redrawing supply geography toward specialized geocoding vendors and actuarial talent pools concentrated in Toronto and Montreal.
Pricing Analysis
Geographic price spreads between high-exposure Alberta wildfire corridors and stable Quebec mutual-ownership markets exceed three-to-one for equivalent dwelling coverage. Three-tier pricing structure across full coverage, basic coverage, and additional riders dominates policy construction, with price differentiation driven by OSFI capital adequacy requirements and provincial flood-plain disclosure compliance costs. Pricing pressure stems from construction material inflation and labor shortages driving claim severity higher in property replacement. First-time homebuyers in suburban Ontario exhibit highest price sensitivity, while high-net-worth households in Calgary and Edmonton demonstrate lowest sensitivity amid climate exposure resets.
Supply Chain Analysis
Strategic stockpiling of actuarial talent and catastrophe-modeling expertise dominates inventory strategy, with carriers bidding against reinsurers and consulting firms for limited specialist pools. Supply concentrates in Canada for underwriting operations and customer servicing, with reinsurance capacity drawing from Bermuda, London, and Zurich markets. Raw material dependencies include construction labor, building materials, and claims-adjusting capacity. Single-source vulnerability in global reinsurance markets threatens capacity availability for Canadian wildfire corridors. Distribution runs through broker networks controlling majority policy placements, though direct-to-consumer platforms are capturing digitally native renters in Toronto and Vancouver.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a defensive-moat story anchored in regulatory entrenchment: OSFI capital requirements and provincial licensing barriers create switching costs that protect incumbent renewal economics against price-based disruption.
For Market Incumbents: Secure catastrophe-model integration into pricing engines before compliance deadlines tighten, and lock in exclusive geocoding partnerships with specialized vendors serving high-exposure corridors. The actuarial talent scarcity threatens underwriting cycle compression, making vertical integration into in-house modeling capabilities the priority defensive lever against reinsurance capacity concentration.
For New Entrants and Emerging Players: Rural parametric coverage gaps expose underserved markets where traditional indemnity products fail, particularly in underpenetrated Saskatchewan and Manitoba corridors. Digital-native renters in Vancouver and Toronto represent the most penetrable segment, accessible through aggregator-platform partnerships and unbundled quote-comparison tools that bypass established broker commissions.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mutual-insurer acquisition targets with sticky member-retention models and provincial franchise depth. Long-term viability hinges on climate-adaptation fund deployment and mitigation investment flows. The signal to watch is OSFI stress-testing disclosure thresholds that would trigger capital reserve recalibration and force distressed divestitures.
| Strategic Initiative | Industry Significance |
|---|---|
| Catastrophe Model Integration | Embedding OSFI-mandated climate scenarios into pricing engines recalibrates capital reserves for high-risk corridors. |
| Parametric Product Development | Index-triggered flood and hail coverage penetrates rural markets where traditional indemnity structures fail. |
| Digital Platform Investment | Direct-to-consumer channels capture Toronto and Vancouver renters bypassing broker network commissions. |
| Geocoding Partnership Lockup | Exclusive flood-risk data agreements with specialized vendors create property-specific pricing granularity. |
| Mutual-Ownership Expansion | Member-retention models in Quebec compete on service depth rather than price, stabilizing renewal economics. |
Study Parameters
A standing panel of underwriting executives, actuarial directors, broker network heads, and provincial regulatory affairs officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against OSFI disclosure filings, FSRA and AMF regulatory bulletins, provincial climate adaptation fund reports, and industry association data. Bottom-up policy formation modeling and top-down premium pool triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. The analytical framework modeled segmentation dimensions including coverage type, policy tier, customer archetype, and distribution channel complexity. CAGRs derived from trend extrapolation of first-time homebuyer expansion, climate-exposure recalibration effects, and digital channel penetration curves. Forecast inputs incorporated construction cost inflation trajectories and reinsurance capacity availability assumptions.
Forecasts assume regulatory continuity in OSFI capital adequacy guidelines and provincial flood-plain disclosure regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include catastrophic wildfire or flood events exceeding modeled loss thresholds, abrupt reinsurance market contraction, and construction cost volatility spikes. Revision becomes warranted when climate-stress testing mandates trigger capital reserve recalibration beyond current provisioning assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
GCC Health Insurance Market
Insurance
Commercial Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Fire Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Global Healthcare Claims Management Market
Insurance
United States Dental Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Asia-Pacific EV Insurance Market