
 Asia-Pacific Accounts Payable Automation Market | 2026-2036
Asia-Pacific Accounts Payable Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Accounts Payable Automation Market Analytics
Singapore's enterprise software corridor is reshaping procurement patterns for AP automation across ASEAN trade lanes. SAP SE leverages its S/4HANA installed base to anchor large-scale deployment pipelines across Indonesian conglomerates. Oracle sustains competitive pressure through database-to-finance suite integration that reduces implementation friction. Zycus specializes in source-to-pay convergence, occupying a distinct position among procurement-native vendors seeking invoice automation adjacencies.
Accounts payable automation encompasses software systems that digitize invoice ingestion, validation, approval routing, and payment execution through configurable workflow engines with optical character recognition extraction accuracy thresholds typically exceeding 95 percent. These platforms eliminate manual data entry, reduce processing cycle times from weeks to days, and enforce three-way matching between purchase orders, receipts, and supplier invoices. Cloud-based deployment leads segment momentum as mid-market enterprises bypass capital-intensive infrastructure builds, while artificial intelligence capabilities represent the fastest-growing technology layer as vendors embed predictive coding for anomaly detection. Software Solutions captures the dominant margin pool due to recurring subscription economics, though Integration services command premium pricing where legacy ERP connectivity demands custom middleware development.
India's RBI operational guidelines on digital lending and payment system harmonization directly shape AP automation requirements for financial institutions and their corporate clients. Australia's ASIC regulatory framework around continuous disclosure and audit trail integrity elevates demand for immutable invoice processing records. China's SAMR data localization provisions and Japan's METI cybersecurity standards for financial infrastructure collectively determine cloud architecture decisions and vendor eligibility across the region. Stakeholders must evaluate sovereign data residency requirements against multi-tenant platform economics when selecting deployment models.
Market Dynamics
Cloud migration mandates from India's RBI and real-time payment infrastructure rollouts across ASEAN are compressing procurement cycles for AP automation platforms. Financial institutions and manufacturing conglomerates now face simultaneous pressure to modernize invoice processing while maintaining sovereign data controls.
Growth Catalysts
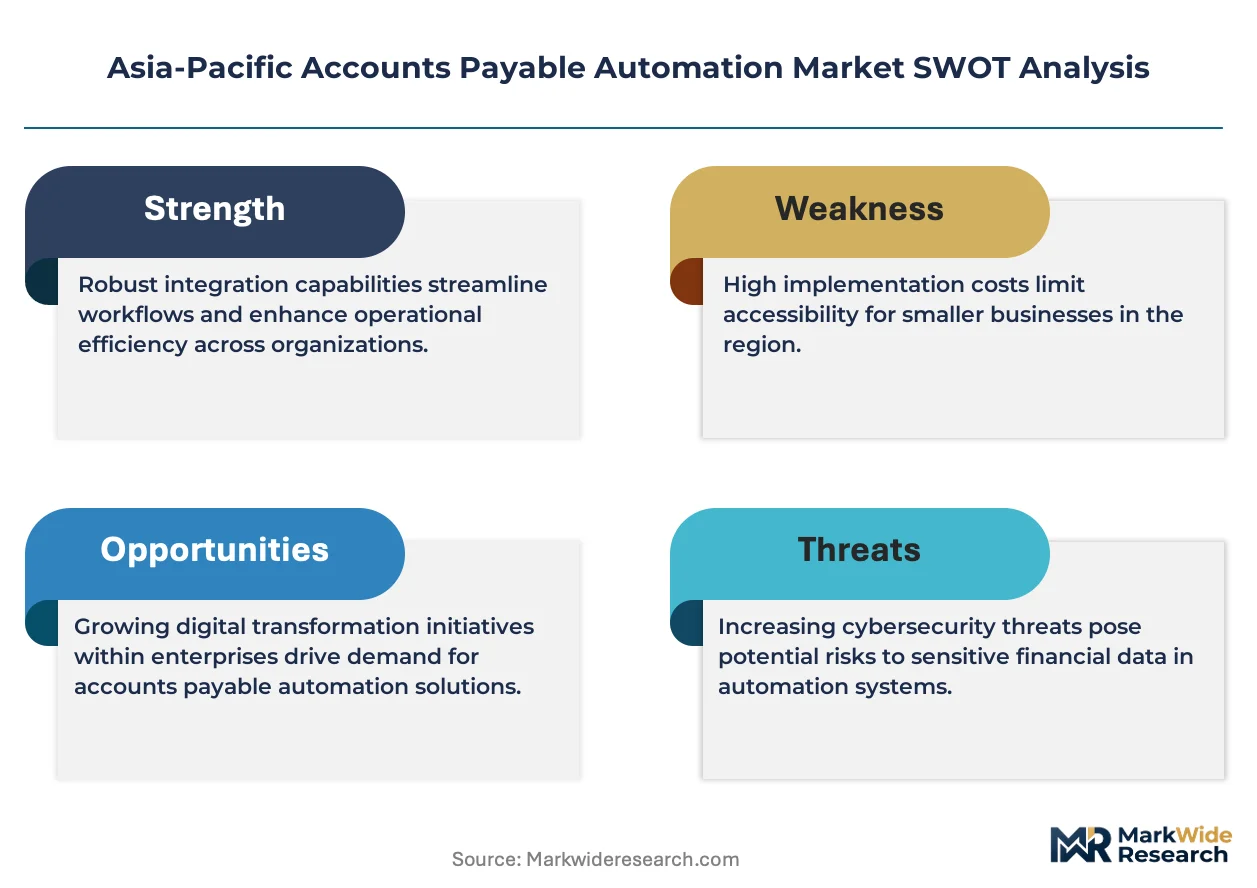
- RBI Digital Lending Guidelines:India's central bank operational directives on payment system harmonization compel banks and NBFCs to automate invoice verification workflows, creating immediate demand for compliant platforms.
- Multi-currency manufacturing operations:Southeast Asian conglomerates expanding cross-border supplier networks require automated handling of invoice currency conversion and tax jurisdiction complexity.
- Optical character recognition advancement:Extraction accuracy thresholds surpassing 95 percent eliminate manual data entry bottlenecks, reducing processing cycles from weeks to days for mid-market enterprises.
Market Restraints
- Legacy ERP integration costs:Custom middleware development for connecting cloud AP platforms to on-premise Oracle or SAP systems commands premium pricing that excludes smaller enterprises.
- Sovereign data localization requirements:China's SAMR provisions and India's draft data protection frameworks fragment cloud architecture decisions, forcing vendors to maintain separate infrastructure instances.
- Skilled implementation talent scarcity:Shortages of certified workflow engineers and finance-IT hybrid professionals extend deployment timelines and elevate professional services costs.
Strategic Opportunities
- Vietnam's manufacturing expansion:Underpenetrated industrial zones in northern Vietnam present first-mover advantage for vendors establishing localized cloud nodes and Vietnamese-language extraction models.
- Artificial intelligence convergence:Predictive coding for anomaly detection combined with natural language processing for contract interpretation creates differentiated platform capabilities.
- ASIC audit trail mandates:Australia's regulatory framework around continuous disclosure elevates demand for immutable invoice processing records with cryptographic verification.
Industry Challenges
- Three-way matching complexity:Discrepancies between purchase orders, goods receipts, and supplier invoices require exception handling workflows that resist full automation in fragmented supply chains.
- Cross-border tax compliance:GST regime variations across India, Singapore, Australia, and emerging ASEAN markets demand continuous platform updates to maintain calculation accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Accounts Payable Automation Market |
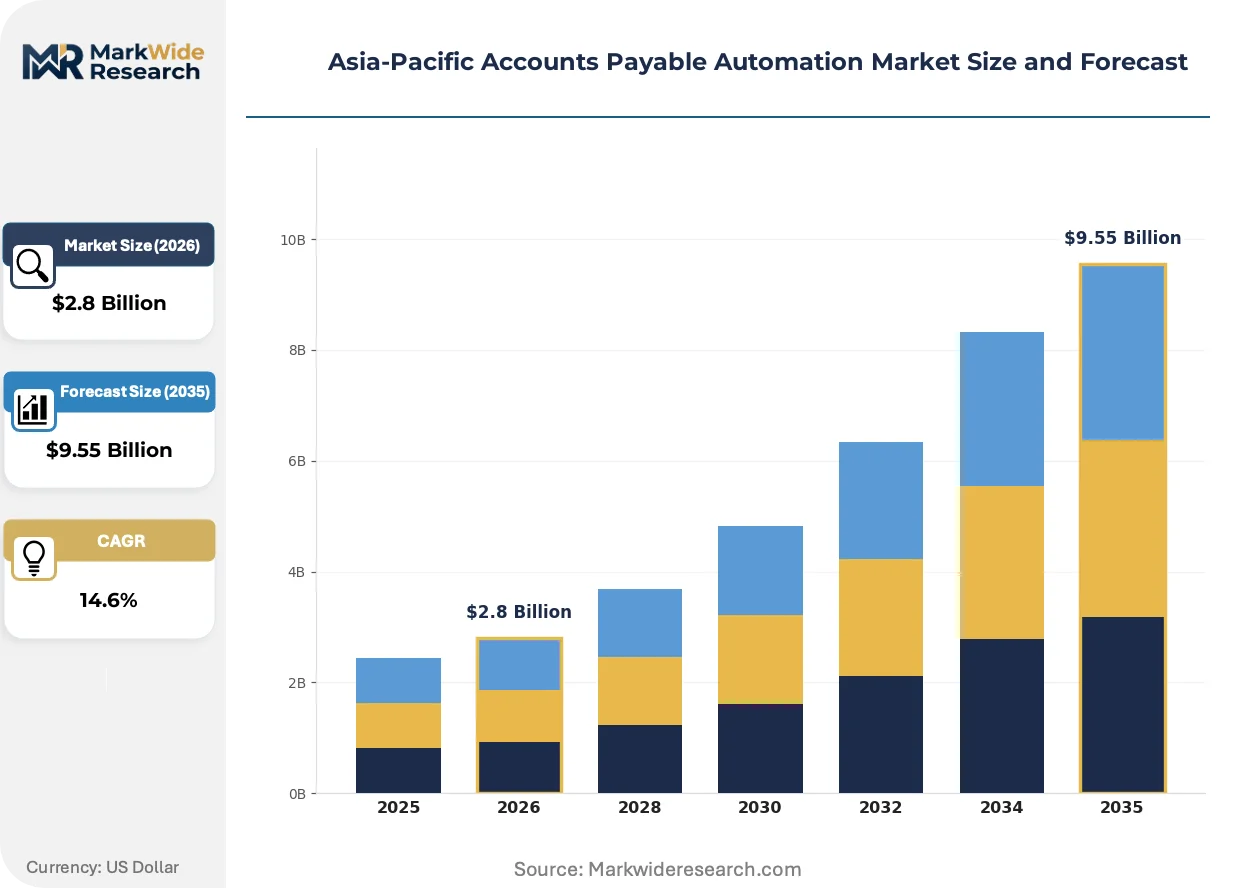
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premise, Cloud-based, Hybrid, Managed Services Service Type: Software Solutions, Consulting, Integration, Support Services End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Agencies Technology: Machine Learning, Optical Character Recognition, Workflow Automation, Artificial Intelligence |
| Companies Covered | AvidXchange, Bottomline Technologies, SAP SE, Zycus, Esker, Coupa Software, Tipalti, Sage Group, Oracle, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Accounts Payable Automation Market Evolving Landscape
Artificial intelligence layers are embedding into core AP workflows, shifting competitive advantage from data capture accuracy toward predictive cash flow optimization. Vendors now compete on anomaly detection sophistication rather than extraction speed alone.
Intelligent document processing with machine learning-based classification is digitizing unstructured invoice formats across supplier ecosystems. Mid-market manufacturers in Thailand and Indonesia are adopting these tools at accelerated pace to handle fragmented vendor documentation standards. The technology is digitizing supplier onboarding processes that previously required manual template configuration for each new trading partner.
Japan's METI cybersecurity standards for financial infrastructure mandate encryption protocols and access logging that exceed baseline cloud certifications. Platform providers serving Japanese enterprises must maintain dedicated compliance engineering teams to satisfy annual audit requirements. Financial services firms in Tokyo's corporate banking corridor are prioritizing vendors with pre-certified METI compliance to accelerate procurement approvals.
Subscription-based pricing models are displacing perpetual license structures as mid-market buyers prefer operational expenditure treatment for software investments. Channel partners in Australia and Singapore are restructuring implementation offerings to align with recurring revenue recognition. Manufacturing verticals with seasonal cash flow patterns show strongest preference for usage-scaled subscription tiers that flex with invoice volume fluctuations.
Asia-Pacific Accounts Payable Automation Market Segmentation
AP automation vendors structure pricing and implementation intensity around deployment models and service tiers. After-sales complexity varies dramatically between cloud-native platforms and legacy on-premise integrations requiring ongoing engineering support.
Deployment:
After-sales-service intensity peaks with deployment architecture, dictating vendor staffing models and customer success investments across the Asia-Pacific corridor.
- Cloud-based:Multi-tenant SaaS architectures enable automated updates and remote monitoring, minimizing field engineering requirements. Australian financial services firms and Singaporean trade finance hubs concentrate demand here, drawn by subscription economics that convert capital expenditure to operational budgets.
- On-premise:Dedicated infrastructure installations demand continuous hardware maintenance, security patching, and version management by certified technicians. Indian manufacturing conglomerates with RBI-mandated data sovereignty requirements and Chinese enterprises under SAMR localization provisions sustain this segment despite higher total cost of ownership.
- Hybrid:Split architectures connecting cloud analytics layers to on-premise transaction databases require specialized integration engineering.
- Managed Services:Fully outsourced invoice processing operations transfer operational risk to vendor-operated delivery centers.
By volume, Cloud-based leads. By growth pace, Hybrid is gaining share fastest as regulatory fragmentation forces compromise architectures.
Service Type:
Margin concentration follows the technology-intensity gradient, with pure software subscriptions capturing recurring revenue pools while professional services absorb implementation complexity.
- Software Solutions:License and subscription revenues from workflow engines, extraction modules, and analytics dashboards generate the dominant margin pool. Mid-market enterprises across Thailand and Indonesia bypass capital-intensive builds through per-invoice pricing tiers that flex with seasonal volume fluctuations.
- Integration:Custom middleware development for ERP connectivity commands premium day rates that extend payback periods. Japanese enterprises requiring METI-certified encryption protocols and Australian firms under ASIC audit trail mandates drive specialized compliance engineering demand.
- Consulting:Process redesign and change management services precede technical deployment.
- Support Services:Tiered helpdesk and escalation contracts stabilize post-implementation relationships.
Software Solutions dominates absolute revenue. Integration services exhibit the steepest expansion trajectory as legacy system complexity intensifies.
End User:
Procurement authority and technical sophistication stratify sharply across organizational scale, shaping sales cycle length and pilot program design.
- Large Corporations:Multi-entity conglomerates with cross-border supplier networks require sophisticated multi-currency handling and intercompany netting capabilities. Southeast Asian manufacturing groups expanding across Vietnam, Indonesia, and Thailand anchor demand for scalable platforms processing millions of annual transactions.
- Medium Enterprises:Growth-phase companies with 50-500 employees represent the fastest conversion opportunity as manual processing costs become unsustainable. India's NBFC sector, responding to RBI digital lending guidelines, automates invoice verification at accelerating pace.
- Small Enterprises:Owner-managed businesses with limited finance staff prioritize low-touch, template-driven solutions.
- Government Agencies:Public sector procurement modernization drives specialized tender requirements around transparency and auditability.
Large Corporations command the deepest per-account revenue. Medium Enterprises are climbing the fastest as cloud accessibility dismantles previous scale barriers.
Technology:
Competitive differentiation migrates upstream from data capture accuracy toward predictive intelligence and autonomous decision-making capabilities.
- Artificial Intelligence:Predictive coding for anomaly detection and cash flow forecasting embeds into core workflows, shifting vendor competition toward optimization sophistication. Financial institutions in Tokyo's corporate banking corridor and Sydney's fintech cluster prioritize platforms with pre-trained models for fraud pattern recognition.
- Optical Character Recognition:Extraction engines with accuracy thresholds exceeding 95 percent eliminate manual data entry bottlenecks. Fragmented supplier documentation standards across Indonesian and Thai manufacturing ecosystems sustain investment in format-agnostic parsing technology.
- Machine Learning:Continuous model improvement from transaction feedback loops refines classification accuracy.
- Workflow Automation:Configurable approval routing and three-way matching engines form the foundational infrastructure layer.
Optical Character Recognition retains the largest installed base. Artificial Intelligence is expanding most quickly as vendors embed generative capabilities for contract interpretation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI operational guidelines on digital lending and payment system harmonization anchor demand generation across the Asia-Pacific corridor. Sovereign data residency requirements and real-time payment infrastructure rollouts compress procurement cycles for compliant AP automation platforms.
India
NBFCs and corporate banks automate invoice verification workflows to satisfy RBI digital lending mandates. The central bank's payment system harmonization directives eliminate manual processing pathways. Mumbai's financial services corridor concentrates deployment activity among conglomerates modernizing multi-entity operations.
Australia
ASIC regulatory frameworks around continuous disclosure and audit trail integrity elevate demand for immutable invoice processing records. Cryptographic verification capabilities attract financial institutions under compliance pressure. Sydney's fintech cluster anchors regional vendor selection activity.
Singapore
Trade finance hubs require sophisticated multi-currency handling for cross-border supplier networks. The Monetary Authority of Singapore's payment infrastructure standards accelerate platform upgrade timelines. Enterprise software corridors concentrate procurement authority for ASEAN-wide rollouts.
China
SAMR data localization provisions fragment cloud architecture decisions for multinational enterprises. Manufacturing conglomerates balance efficiency gains against sovereign data controls. Yangtze River Delta industrial zones sustain demand for hybrid deployment models.
Japan
METI cybersecurity standards for financial infrastructure mandate encryption protocols exceeding baseline certifications. Corporate banking corridors in Tokyo prioritize pre-certified vendors to accelerate procurement approvals. Annual audit requirements sustain dedicated compliance engineering investments.
Asia-Pacific Accounts Payable Automation Market Competitive Landscape
ERP-native suites and procurement-native specialists split the market along integration-depth versus functional-breadth axes. The vendor base stratifies into three tiers: global enterprise suites with installed-base leverage, vertical specialists with regulatory pre-certifications, and cloud-native challengers with subscription pricing flexibility. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized cloud nodes.
Within the ERP-native tier, SAP SE and Oracle occupy positions defined by database-to-finance suite integration capabilities. Zycus represents the procurement-native archetype, anchoring source-to-pay convergence strategies. These three exemplify how vendor selection criteria vary between manufacturing conglomerates prioritizing legacy system connectivity and mid-market enterprises seeking rapid cloud deployment without custom middleware development.
| Leading Market Players |
|---|
| AvidXchange |
| Bottomline Technologies |
| SAP SE |
| Zycus |
| Esker |
| Coupa Software |
| Tipalti |
| Sage Group |
| Oracle |
| Others |
Value Network & Pricing Analysis
RBI data localization mandates compressing vendor infrastructure choices determine both subscription tier spreads and supply chain architecture across the Asia-Pacific corridor. Cloud-native platforms command premium positioning in Australia's financial services corridor and Singapore's trade finance hub, while hybrid deployments absorb compliance engineering costs in India and China.
Pricing Analysis
Geographic price spreads widen substantially between ASEAN manufacturing zones and developed Asia-Pacific financial centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by METI certification status and integration complexity. Cost compression in mid-market tiers intensifies as Indian NBFCs and Indonesian conglomerates negotiate volume-scaled SaaS contracts. Small enterprises exhibit highest price sensitivity, while Japanese corporate banking corridors prioritize pre-certified vendors regardless of premium positioning.
Supply Chain Analysis
Extended payment terms from systems integrators to cloud infrastructure providers reshape working capital requirements for AP automation vendors. Software development concentrates in India, Singapore, and Australia, with extraction engine training data sourcing from fragmented Indonesian and Thai supplier documentation. Single-source vulnerability persists for GPU compute provisioning supporting AI model training. Distribution runs through channel partners restructuring implementation offerings around recurring revenue recognition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific AP automation market functions as a service-attach opportunity where integration services expand faster than core software subscriptions as legacy ERP complexity intensifies.
For Market Incumbents: Insulate installed-base revenue by embedding predictive cash flow optimization modules that raise switching costs for SAP SE and Oracle customers. Acquire certified workflow engineering talent pools in Mumbai and Sydney to compress deployment timelines threatened by skilled implementation scarcity. Channel control through exclusive systems integrator partnerships defends margin position against procurement-native specialists. For New Entrants and Emerging Players: Build out Vietnamese-language extraction models and localized cloud nodes in northern Vietnam's underpenetrated industrial zones. Target India's NBFC sector responding to RBI digital lending guidelines with rapid-deployment templates bypassing custom middleware. White-label partnerships with Australian channel partners accelerate recurring revenue recognition without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: ASIC audit trail mandates reshaping the acquisition landscape elevate platforms with cryptographic verification capabilities above commodity extraction vendors. Long-term viability hinges on AI convergence trajectory rather than installed-base scale alone. Watch for anomaly detection sophistication separating acquisition targets from margin-compressed workflow automation providers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Database-to-finance suite connectivity reduces implementation friction for Indonesian conglomerates. |
| Geographic Expansion | Localized cloud nodes in Vietnam satisfy data residency requirements for manufacturing expansion. |
| Strategic Partnership | Systems integrator alliances accelerate procurement approvals in Tokyo's corporate banking corridor. |
| Product Launch | AI-powered anomaly detection modules differentiate offerings beyond extraction accuracy thresholds. |
| Acquisition of Specialist Firm | Procurement-native vendors gain invoice automation adjacencies through source-to-pay convergence. |
Research Methodology
A spread of perspectives from CTOs at financial institutions, IT procurement officers at manufacturing conglomerates, platform engineers at cloud-native vendors, and integration specialists at systems integrators converged on the working assumptions shaping this analysis. Secondary validation drew from RBI operational guidelines, ASIC regulatory frameworks, METI cybersecurity standards, SAMR data localization provisions, and SEC filings of publicly traded enterprise software providers. Bottom-up transaction volume estimates and top-down addressable market calculations were triangulated to anchor projections.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from trend extrapolation of cloud migration velocity and AI capability embedding rates. Forecast inputs incorporated real-time payment infrastructure rollout schedules and sovereign data residency requirement evolution.
Stress conditions across RBI guideline implementation timelines, ASIC audit mandate enforcement intensity, and cross-border tax compliance fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Thailand Mobile Payments Market
Payments
Mobile Payment Market
Payments
Recurring Payments Market
Payments
Asia-Pacific Payments Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
Mobile Payment Security Market
Payments
Contactless Payment Ring Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Smart Payment Market
Payments
US Gift Card and Incentive Card Market
Payments
Sweden Mobile Payments Market
Payments
Payment Instruments Market
Payments
Blockchain Payments Software Market
Payments
Mobile Payment Security Software Market
Payments
Saudi Arabia POS Terminal Market
Payments
Online Charging System (OCS) Market