
 Norway Property and Casualty Insurance Market | 2026-2036
Norway Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Property and Casualty Insurance Market Analytics
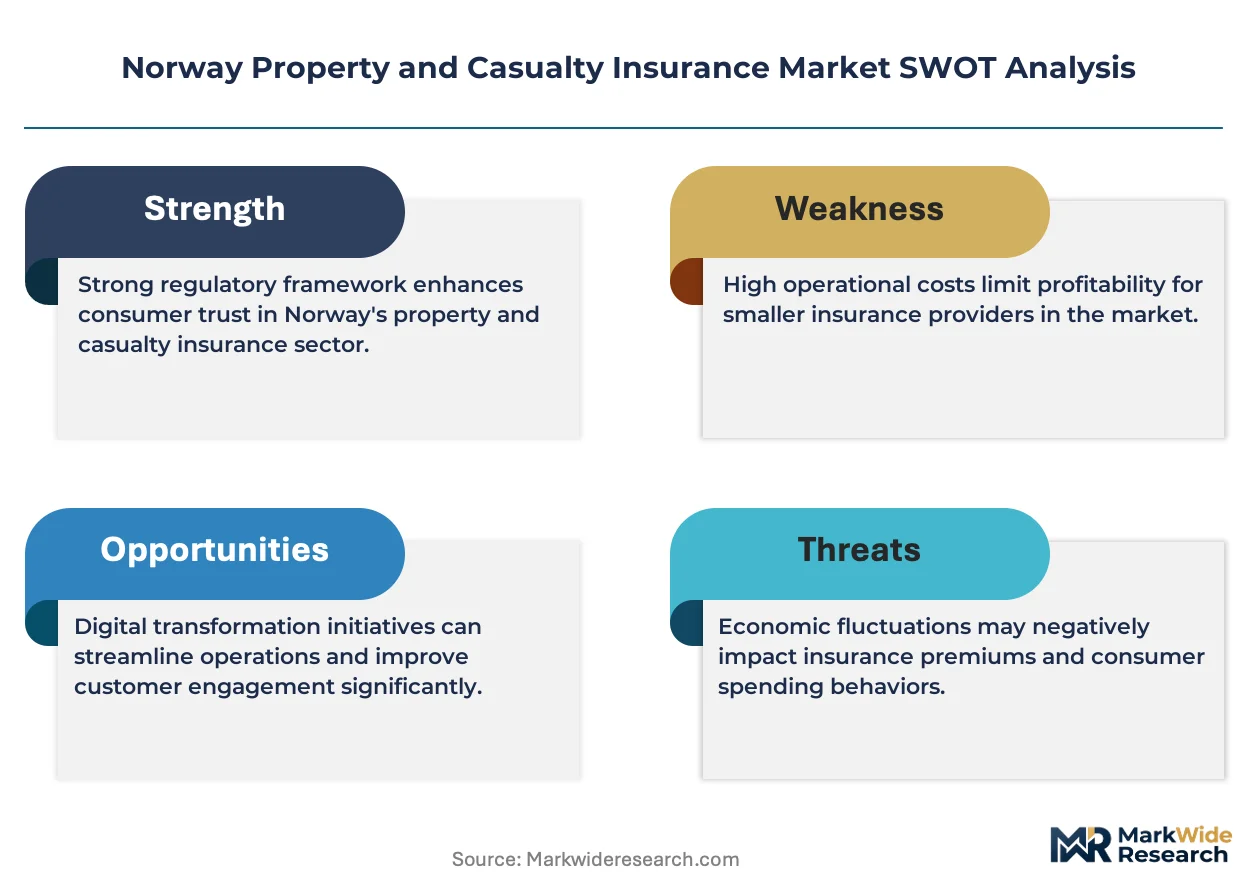
The EU Green Deal's climate adaptation benchmarks is consolidating demand for natural disaster coverage across Norwegian portfolios. Gjensidige Forsikring ASA leverages its rural agency network to sustain market presence in weather-exposed coastal municipalities. If Skadeforsikring anchors its competitive stance through advanced flood risk modeling capabilities. Fremtind Forsikring AS differentiates via digital-first distribution that competes with traditional broker channels.
Property and casualty insurance constitutes risk transfer contracts indemnifying policyholders against physical asset damage, bodily injury liability, and financial loss from specified perils, with Norwegian contracts typically incorporating strict natural catastrophe deductibles tied to reinstatement cost indices. Auto Insurance commands the largest premium volume pool due to Norway's high vehicle density and mandatory third-party liability requirements, while Commercial Property exhibits the fastest expansion as Oslo's logistics and data center construction drives insured value inflation. Homeowners Insurance remains structurally mature with thin margins, though comprehensive coverage variants with climate adaptation riders capture improving yields.
Finanstilsynet enforces Solvency II-aligned capital adequacy rules that shape product pricing and reserve requirements, while the EU AI Act increasingly governs automated underwriting algorithms used by domestic carriers. The Norwegian Natural Perils Pool mandates collective participation for landslide and flood exposure, creating standardized coverage obligations across all licensed writers. Stakeholders must monitor evolving ESG disclosure rules under the CSRD framework and assess how climate scenario testing will reshape risk selection and capital deployment priorities.
Market Dynamics
Finanstilsynet's Solvency II alignment is compressing capital buffers across Norwegian insurers, forcing portfolio rebalancing toward lower-risk asset classes and tighter underwriting discipline. This regulatory pressure cascades into product redesign, distribution economics, and reinsurance purchasing patterns.
Growth Catalysts
- EU Green Deal climate mandates:Property owners in Bergen and Stavanger face mandatory resilience upgrades, expanding demand for construction all-risk and climate-adapted homeowners coverage.
- Oslo logistics construction:Data center and cold storage buildouts in Akershus and Østfold inflate commercial property insured values and drive premium volume expansion.
- Telematics penetration:Connected vehicle adoption among Norwegian fleet operators enables usage-based auto pricing and loss ratio improvement through behavioral monitoring.
Market Restraints
- Reinsurance cost volatility:Natural catastrophe retrocession pricing swings constrain Norwegian carriers' ability to offer fixed-rate multi-year commercial property contracts.
- Agricultural exposure concentration:Crop and livestock coverage in Trøndelag and Innlandet generates correlated loss accumulation during drought or flood events.
- Long-tail liability reserves:Asbestos and environmental impairment claims from industrial legacy policies require capital lock-up extending decades.
Strategic Opportunities
- Norwegian Natural Perils Pool reforms:Proposed parametric payout structures for flood and landslide coverage would reduce loss adjustment expense and accelerate claims settlement.
- Embedded insurance distribution:Integration with Nordic banking apps and real estate platforms captures policyholders at point of property transaction or vehicle financing.
- CSRD disclosure services:Commercial clients require climate risk quantification for regulatory reporting, creating advisory revenue streams beyond risk transfer.
Industry Challenges
- Actuarial talent scarcity:Climate risk modeling and Solvency II technical provisions demand specialized expertise that Norwegian labor markets undersupply.
- Legacy core system migration:Policy administration platforms from the 1990s impede real-time data integration with IoT sensors and automated underwriting engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Property and Casualty Insurance Market |
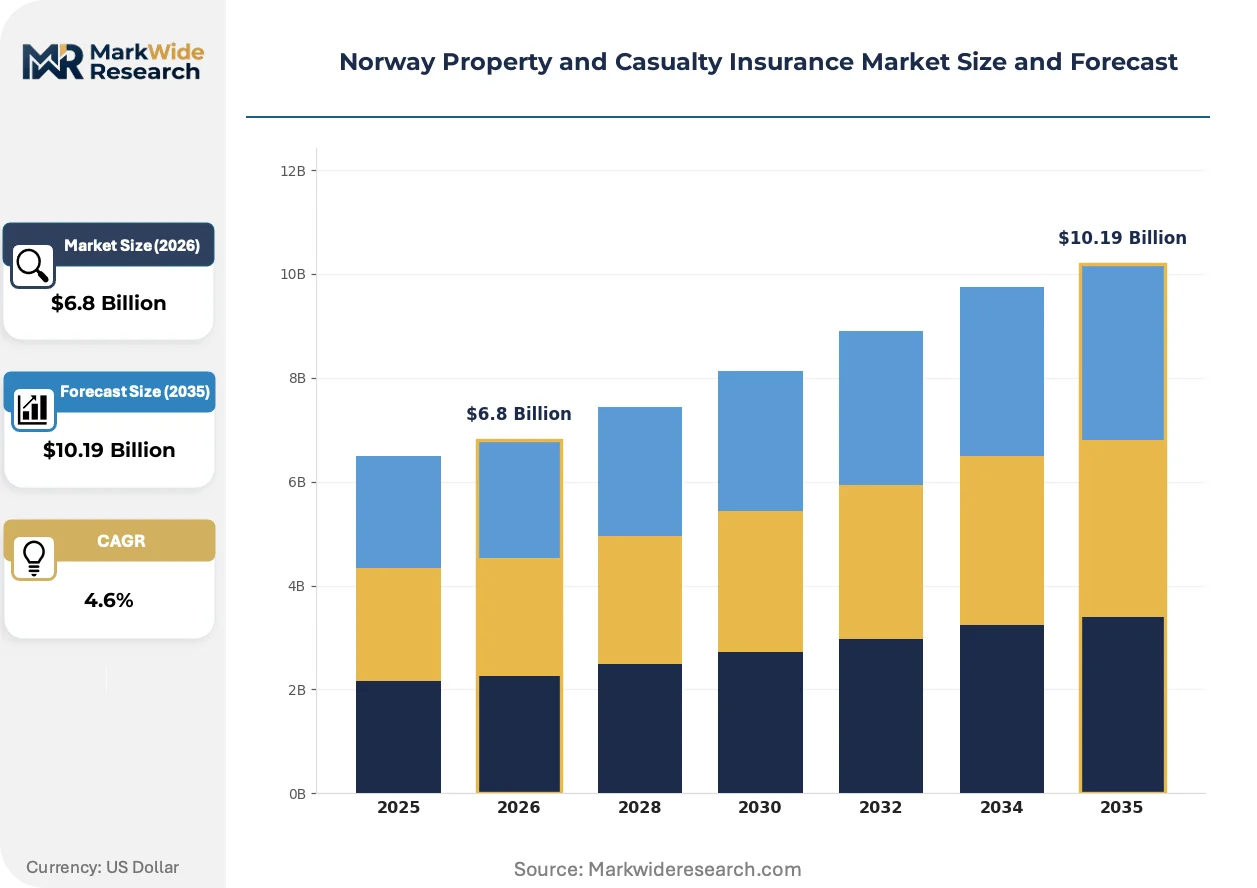
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto Insurance, Homeowners Insurance, Commercial Property, General Liability Customer Type: Individual Consumers, Small Businesses, Corporations, Non-Profit Organizations Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms Coverage Type: Comprehensive, Third-Party Liability, Fire and Theft, Natural Disaster |
| Companies Covered | If Skadeforsikring, Frende Forsikring, Gjensidige Forsikring ASA, Codan Forsikring, Tide Forsikring AS, Tryg Forsikring, SpareBank 1 Forsikring AS, Eika Forsikring, Fremtind Forsikring AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Property and Casualty Insurance Market Evolving Landscape
Digital distribution architectures and climate risk quantification tools are restructuring how Norwegian insurers acquire customers, price coverage, and manage accumulated exposures. These shifts compress traditional intermediary roles while elevating data science capabilities.
Parametric flood coverage is modularizing traditional indemnity structures in Norwegian coastal municipalities. Insurers in Møre og Romsdal and Vestland deploy satellite-based water level monitoring to trigger predetermined payouts without loss adjustment. This compression of claims settlement timelines reduces administrative burden while creating basis risk transfer to policyholders.
Finanstilsynet's implementation of EU AI Act governance requirements imposes algorithmic transparency mandates on automated underwriting systems. Domestic carriers must document decision logic for machine learning models used in risk selection and pricing. Personal lines auto and home segments face the steepest compliance costs as these algorithms handle high transaction volumes.
Corporate risk managers in Oslo's financial and energy sectors now unbundle insurance purchasing from traditional broker relationships. Direct carrier negotiations and digital placement platforms capture mid-market commercial accounts previously intermediated by wholesale brokers. This channel compression is most visible among technology and professional services firms with standardized property and liability exposures.
Norway Property and Casualty Insurance Market Segmentation
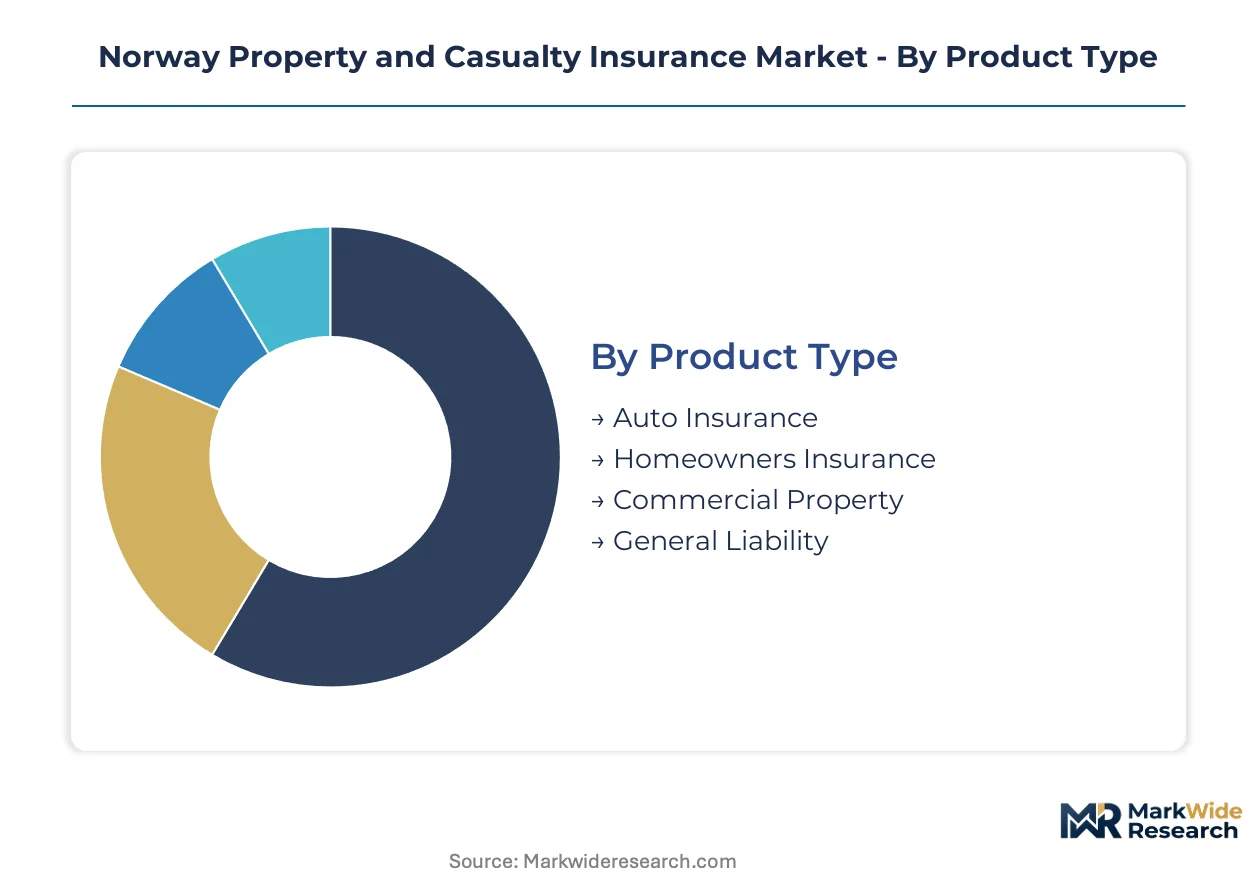
Segmentation in the Norwegian property and casualty insurance market reveals how product design, customer risk profiles, and distribution economics interact with Finanstilsynet's regulatory framework. Each axis exposes different margin structures and capital deployment requirements that shape competitive positioning.
Product Type:
Technical specifications and peril definitions differentiate product architectures, with each line carrying distinct reserving patterns and reinsurance dependencies.
- Auto Insurance:Mandatory third-party liability coverage combined with voluntary comprehensive protection for collision, theft, and weather damage. Norwegian fleet operators in Oslo and Bergen drive telematics-linked policy growth as Finanstilsynet's capital requirements compress pricing flexibility.
- Homeowners Insurance:Dwelling coverage incorporating strict natural catastrophe deductibles tied to reinstatement cost indices. Coastal municipalities in Vestland and Møre og Romsdal generate concentrated demand for flood and landslide riders as the Norwegian Natural Perils Pool mandates collective participation.
- Commercial Property:Industrial and logistics facility coverage with capacity constraints tied to reinsurance availability. Oslo's data center construction in Akershus inflates insured values and premium volumes.
- General Liability:Bodily injury and property damage protection for businesses and professionals. Long-tail exposure from industrial legacy policies requires extended reserve periods under Solvency II technical provisions.
Auto Insurance leads on scale; Commercial Property leads on momentum.
Customer Type:
Risk sophistication and purchasing power segment the market into distinct service tiers, with each category demanding different advisory intensity and policy customization.
- Individual Consumers:Standardized personal lines coverage purchased through digital channels or agent networks. Oslo metropolitan households exhibit highest penetration of comprehensive homeowners variants with climate adaptation features.
- Small Businesses:Bundled property and liability packages with simplified underwriting. Trøndelag agricultural operators face correlated exposure accumulation during drought or flood events.
- Corporations:Complex risk transfer structures involving captive arrangements and international program coordination. Energy and financial sector firms in Oslo unbundle purchasing from traditional broker relationships.
- Non-Profit Organizations:Specialized coverage for volunteer liability and facility protection. Community organizations in Innlandet rely on standardized packages with limited customization options.
Individual Consumers anchor premium volume; Corporations command the highest policy values per account.
Distribution Channel:
Channel economics reflect customer acquisition costs and retention mechanics, with digital disruption compressing traditional intermediary margins.
- Direct Sales:Carrier-controlled channels eliminating commission overhead. Fremtind Forsikring AS deploys digital-first distribution competing with traditional broker economics.
- Brokers:Independent intermediaries serving commercial accounts with complex placement needs. Wholesale brokers face displacement as mid-market firms negotiate directly with carriers.
- Agents:Tied representatives with localized relationship networks. Gjensidige Forsikring ASA sustains rural presence through agency infrastructure in weather-exposed coastal municipalities.
- Online Platforms:Aggregator and embedded insurance integration with banking and real estate transactions. Nordic banking apps capture policyholders at vehicle financing and property closing moments.
Brokers retain commercial account dominance; Online Platforms gain share fastest among younger demographics.
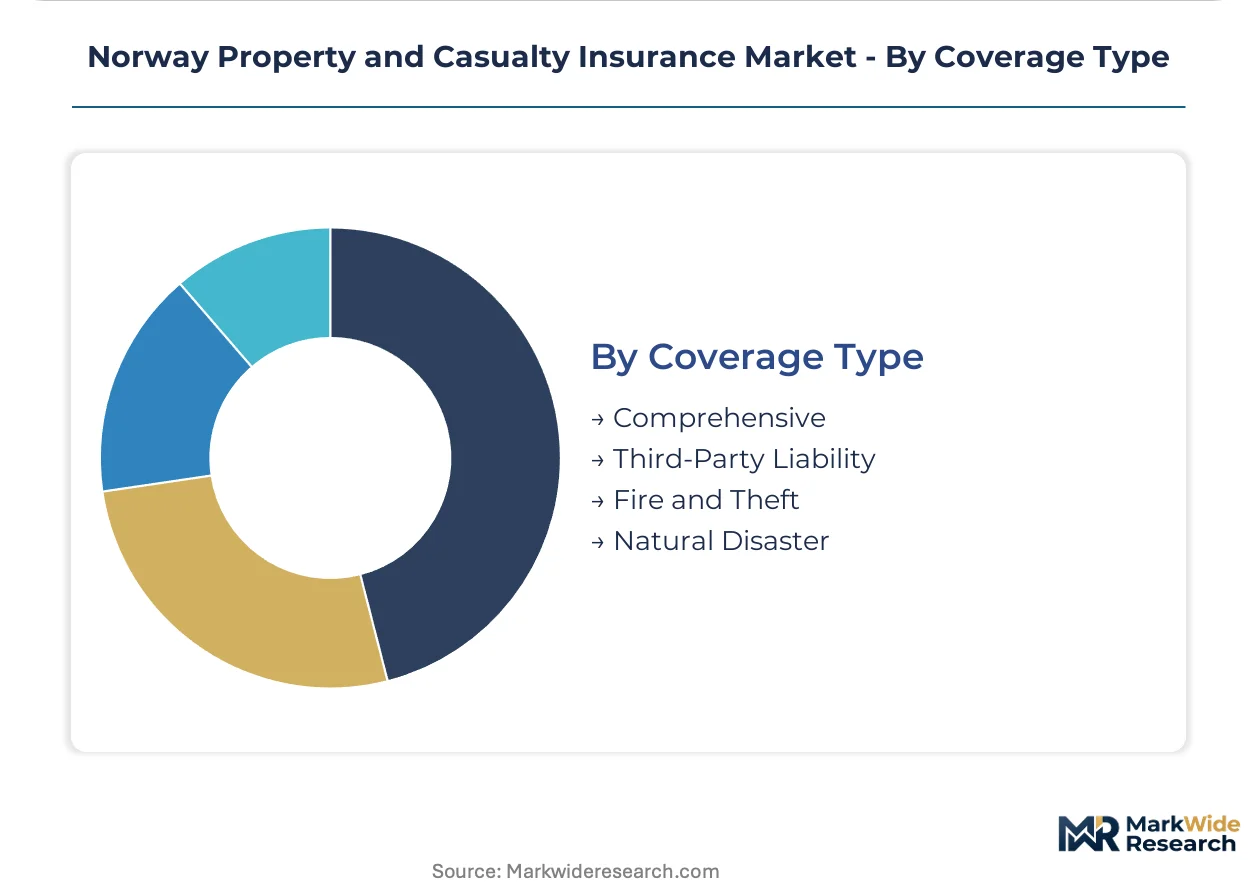
Coverage Type:
Peril scope and indemnity structure define product economics, with parametric innovations disrupting traditional loss adjustment models.
- Comprehensive:All-risk protection covering multiple perils under single policy terms. Auto and homeowners segments in Oslo's high-value property clusters show strongest attachment rates.
- Third-Party Liability:Mandatory coverage for bodily injury and property damage to others. Norwegian vehicle density sustains this as the largest statutory premium pool.
- Fire and Theft:Named-peril coverage with lower premiums and restricted scope. Commercial tenants in logistics facilities select this tier to control occupancy costs.
- Natural Disaster:Flood, landslide, and storm coverage through pooled mechanisms and supplemental riders. Satellite-based water level monitoring in Møre og Romsdal enables parametric payout structures.
Third-Party Liability leads on mandatory volume; Natural Disaster expands most quickly as climate adaptation mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern property and casualty insurance in Norway traces its institutional roots to the establishment of mutual fire insurance societies in coastal trading communities during the late 19th century. These cooperative structures evolved into today's regulated market framework. Regional variation reflects Norway's elongated geography, with distinct risk profiles emerging across its sub-regional economies.
Oslo and Akershus
Corporate headquarters concentration and high-value commercial construction dominate premium generation in Norway's capital region. Finanstilsynet's Solvency II enforcement tightest here given systemic importance. Data center and logistics facility buildouts in Akershus inflate insured values and attract specialized commercial property underwriters.
Vestland
Bergen's maritime heritage and Stavanger's energy sector anchor diversified commercial insurance demand. The Norwegian Natural Perils Pool mandates collective flood and landslide participation across this weather-exposed coastline. Satellite-based parametric coverage pilots in Møndal and Ålesund compress claims settlement timelines.
Trøndelag
Agricultural exposure concentration generates correlated loss accumulation risks for crop and livestock coverage. Drought and flood events in Innlandet-adjacent valleys stress regional reinsurance purchasing. Trondheim's technology sector diversifies risk profiles beyond traditional primary industries.
Northern Norway
Troms and Finnmark present extreme weather exposure and sparse population density challenging traditional distribution economics. Arctic infrastructure development around Hammerfest and Kirkenes expands construction all-risk demand. Remote agency networks sustain coverage access where digital channels underpenetrate.
Norway Property and Casualty Insurance Market Competitive Landscape
Capital-heavy mutual insurers compete with asset-light digital distributors for Norwegian policyholder relationships. The market structure consolidates around three to five dominant carriers with substantial balance sheet capacity, while smaller regional mutuals retain localized loyalty through agency infrastructure. Strategic archetypes include rural-network mutuals, digital-first challengers, and bank-integrated bancassurance operators. Competitive moves center on reinsurance purchasing optimization and embedded distribution partnerships with Nordic banking platforms.
Within the incumbent tier, Gjensidige Forsikring ASA and If Skadeforsikring occupy positions reflecting divergent geographic strategies. Gjensidige's rural agency network exemplifies the mutual heritage archetype sustaining presence in weather-exposed coastal municipalities. If Skadeforsikring represents the data-driven underwriting specialist segment, with flood risk modeling capabilities anchoring its competitive stance. Fremtind Forsikring AS sits within the digital challenger category, competing against traditional broker economics through direct channel investment.
| Leading Market Players |
|---|
| If Skadeforsikring |
| Frende Forsikring |
| Gjensidige Forsikring ASA |
| Codan Forsikring |
| Tide Forsikring AS |
| Tryg Forsikring |
| SpareBank 1 Forsikring AS |
| Eika Forsikring |
| Fremtind Forsikring AS |
| Others |
Value Network & Pricing Analysis
Parametric-digital divergence between traditional indemnity contracts and satellite-triggered coverage splits Norwegian carriers into capital-intensive legacy underwriters and asset-light data specialists. This bifurcation manifests in pricing power concentration among flood-modeling specialists while distribution economics favor embedded insurance platforms with Nordic banking partnerships.
Pricing Analysis
Risk-based capital tiering anchored in Finanstilsynet's Solvency II enforcement separates well-capitalized mutuals from thinly reserved challengers. Price differentiation rests on reinsurance security ratings and natural catastrophe modeling depth rather than brand alone. Cost compression in commercial property lines intensifies as Oslo data center construction inflates insured values while retrocession markets harden. Small agricultural operators in Trøndelag exhibit highest price sensitivity; Oslo corporate risk managers prioritize coverage certainty over premium minimization.
Supply Chain Analysis
Single-source vulnerability sits with London and Zurich retrocession markets for Norwegian carriers' peak catastrophe exposure. Reinsurance capacity draws from Bermuda, Germany, and Switzerland for natural peril layers. Raw material dependencies include satellite imagery from European Space Agency partners, IoT telematics hardware from Nordic suppliers, and proprietary flood simulation software. Regulatory restriction through EU AI Act algorithmic governance creates compliance cost concentration. Distribution runs through captive agency networks in rural municipalities and direct digital channels in Oslo metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norwegian property and casualty insurance represents a late-cycle quality story as climate adaptation mandates shift commercial demand toward comprehensive coverage with parametric riders. Premium specifications now prioritize loss settlement velocity and basis risk transparency over traditional indemnity structures.
For Market Incumbents: Deploy reinsurance optimization levers to defend balance sheet capacity against Solvency II capital compression. Secure long-term retrocession treaties before market hardening accelerates. Invest in satellite-based flood monitoring infrastructure to differentiate from broker-dependent competitors. Channel control through Nordic banking app integration protects against digital challenger erosion. For New Entrants and Emerging Players: AI-driven underwriting automation offers the clearest technology-first wedge into personal lines auto and homeowners segments. Target underpenetrated agricultural coverage in Innlandet valleys where legacy mutuals lack telematics infrastructure. Embedded distribution through real estate closing platforms captures policyholders at property transaction moments with minimal acquisition cost. For Investors and Strategic Acquirers: Consolidation pressure builds where Solvency II capital requirements exceed smaller mutuals' organic generation capacity. Long-term viability favors carriers with parametric product capabilities and direct channel economics over agency-heavy rural networks. Watch Finanstilsynet's climate scenario testing implementation as the inflection signal for capital reallocation toward resilience-focused underwriters.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Satellite-triggered flood coverage reduces loss adjustment expense for Møre og Romsdal coastal municipalities. |
| Embedded Distribution Partnership | Nordic banking app integration captures policyholders at vehicle financing and property closing moments. |
| Reinsurance Security Optimization | Long-term retrocession treaties with Zurich and London markets lock in capacity before pricing hardens. |
| Climate Risk Advisory Services | CSRD disclosure support generates fee revenue beyond risk transfer for Oslo corporate clients. |
| Legacy Core System Migration | Real-time IoT integration enables automated underwriting for telematics-linked fleet policies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged underwriting executives at domestic carriers, reinsurance brokers placing Norwegian catastrophe layers, Finanstilsynet supervisory staff, and corporate risk managers in Oslo's energy and financial sectors. Secondary validation drew from Finanstilsynet solvency filings, Norwegian Natural Perils Pool participation data, EU AI Act regulatory texts, and Nordic insurance association statistical reports. Bottom-up premium volume estimates triangulated against top-down macroeconomic exposure indicators.
Segment-weighting across product type, customer category, distribution channel, and coverage architecture drove forecast construction. Auto insurance, homeowners coverage, commercial property, and general liability lines each carried distinct growth trajectories over the projection horizon. CAGRs derived from historical premium progression adjusted for regulatory capital requirement changes and climate exposure accumulation. Forecast inputs included Oslo construction permit data for commercial property value inflation and connected vehicle penetration rates for telematics-linked auto pricing.
The model holds under stable Solvency II implementation and gradual EU Green Deal adaptation; deviation in catastrophic flood frequency or retrocession market dislocation would shift carrier profitability and capital deployment priorities. Forecasts reflect documented assumptions about reinsurance availability and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Car Insurance Market
Insurance
Green Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Business Income Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Commercial Insurance Market
Insurance
EV Insurance Market
Insurance
Spain Group Health Insurance Market
Insurance
Engineering Insurance Market
Insurance
IoT Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Global Healthcare Claims Management Market