
 Intellectual Property Liability Insurance Market | 2026-2036
Intellectual Property Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Intellectual Property Liability Insurance Market Insights
The Intellectual Property Liability Insurance Market is recalibrating around a widening split between bespoke policies for high-exposure patent portfolios and standardized coverage for copyright and trademark risks. AIG dominates the upper tier with captive legal panels and in-house claim assessment infrastructure. Chubb leverages its Lloyd's syndicate relationships to sustain capacity for complex multi-jurisdictional disputes. Hiscox competes aggressively in the SME segment with modular policy structures that reduce underwriting friction.
Intellectual property liability insurance is a specialized casualty product that indemnifies policyholders against legal defense costs, damages awards, and settlement obligations arising from allegations of IP infringement or misappropriation; underwriters typically require prior art searches, freedom-to-operate opinions, and claims history documentation before binding coverage. Litigation defense coverage within the scope dimension commands the largest premium pool because defense costs often exceed damages in protracted patent disputes. Patent infringement policies across the type dimension attract the steepest rate increases as NPE litigation volumes persist in key federal districts.
The USPTO's patent trial and appeal board proceedings interact with district court litigation to create dual-track exposure that carriers must model, while the EU's Unified Patent Court framework reshapes European enforcement geography and demand patterns. The FTC's scrutiny of patent assertion entities influences litigation frequency and therefore loss ratio projections for underwriters. Stakeholders must monitor how generative AI training data disputes create novel copyright exposure categories not captured in legacy policy wordings.
Market Dynamics
The Intellectual Property Liability Insurance Market is bifurcating around generative AI training data disputes, which carriers struggle to price due to unresolved copyright precedents and ambiguous fair-use boundaries in machine learning contexts.
Growth Catalysts
- First-to-file patent pressure:The America Invents Act's procedural shift compels mid-sized enterprises to secure defensive patent portfolios, expanding policy uptake for defensive litigation coverage.
- NPE litigation persistence:Patent assertion entities sustain enforcement volumes in Eastern and Western Texas federal districts, sustaining demand for patent infringement indemnification.
- Biotech patent density:CRISPR and antibody platform patent thickets in pharmaceuticals generate freedom-to-operate review requirements that underwriters mandate before binding coverage.
Market Restraints
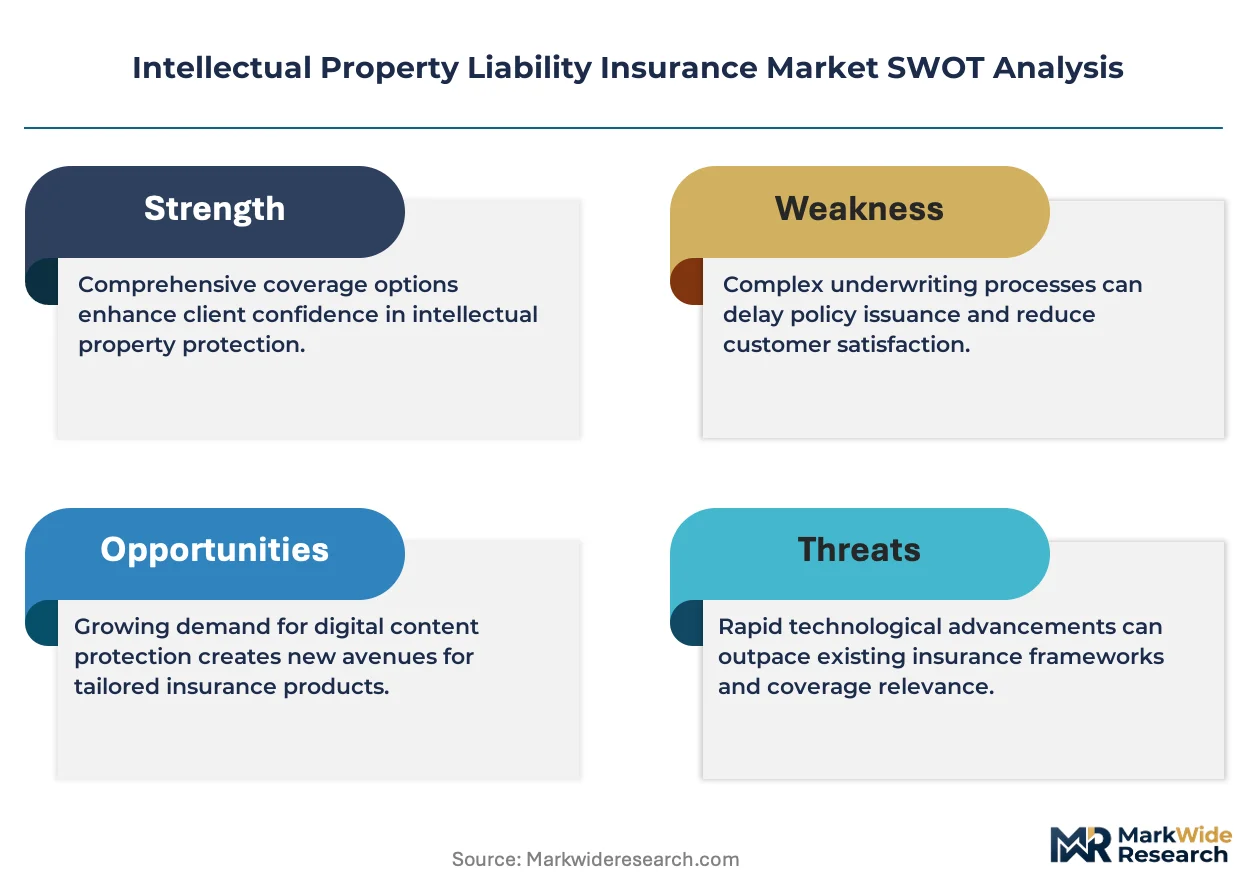
- Defense cost inflation:Protracted patent disputes now routinely generate legal fees exceeding damages awards, compressing loss ratios and forcing rate hardening.
- Capacity concentration:Complex multi-jurisdictional disputes require Lloyd's syndicate backing that concentrates in London, creating geographic supply bottlenecks.
- Prior art search burden:Underwriting workflows demand freedom-to-operate opinions and claims history documentation that elongate binding timelines.
Strategic Opportunities
- Modular SME products:Standardized copyright and trademark coverage for technology startups reduces underwriting friction and accelerates premium collection.
- EU Unified Patent Court:The new European enforcement framework consolidates previously fragmented national litigation, enabling pan-European policy structures.
- AI training data coverage:Novel copyright exposure categories from generative AI development create first-mover advantage for carriers drafting bespoke rider language.
Industry Challenges
- Dual-track exposure modeling:USPTO Patent Trial and Appeal Board proceedings run parallel to district court litigation, requiring simultaneous reserve allocation across administrative and judicial forums.
- Legacy policy wording gaps:Standard intellectual property liability contracts omit machine learning training data disputes, forcing costly manuscript endorsement drafting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intellectual Property Liability Insurance Market |
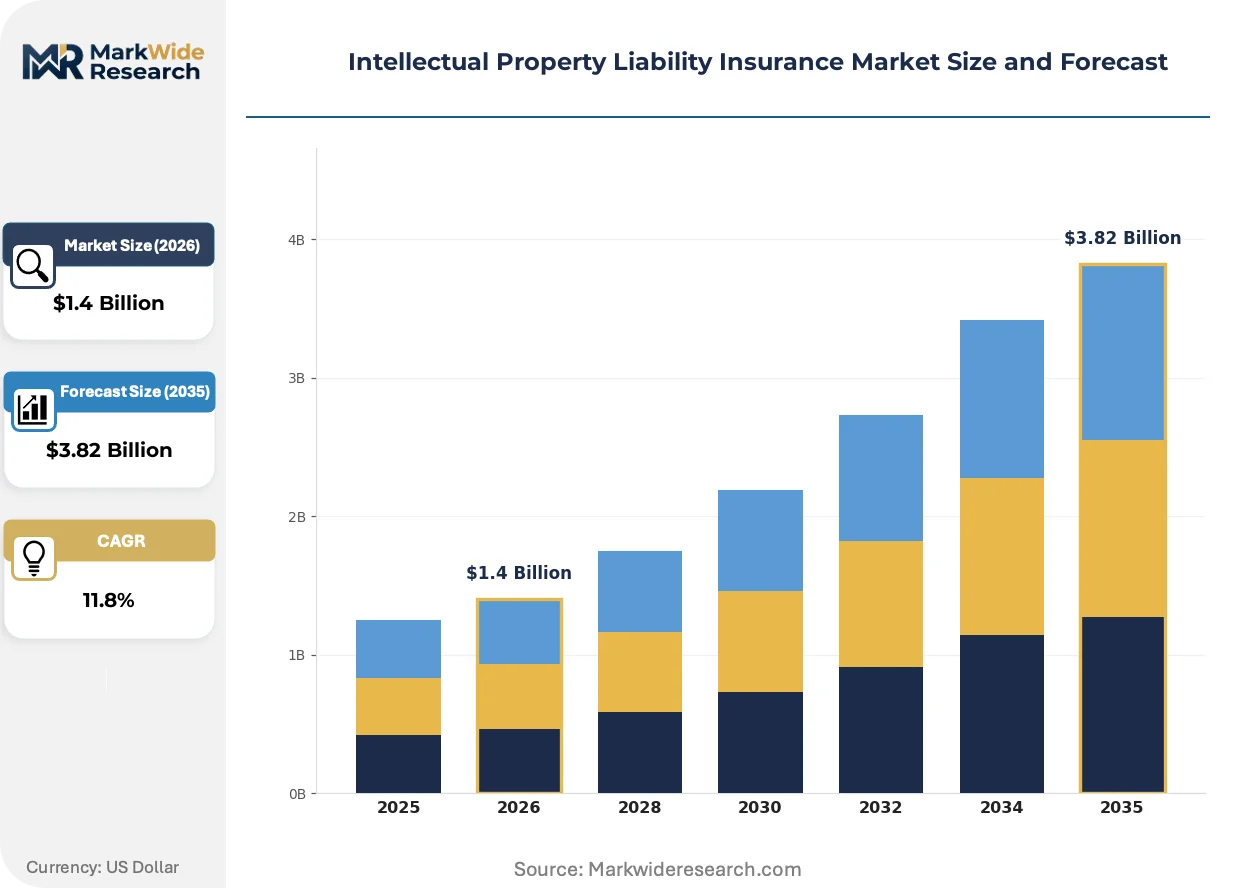
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Patent Infringement, Trademark Infringement, Copyright Infringement, Trade Secret Misappropriation, Design Rights Violation Coverage Scope: Litigation Defense, Monetary Damages, Settlement Costs, Legal Consultation, Expert Witness Fees End User Industry: Technology Startups, Manufacturing Firms, Media Agencies, Pharmaceutical Companies, Financial Services Distribution Channel: Direct Sales, Broker Networks, Online Platforms, Affinity Programs, Insurance Aggregators |
| Companies Covered | Willis Towers Watson (WTW), The Hartford, Intellectual Property Insurance Services Corporation (IPISC), AIG, Hiscox, Marsh, Ambridge Partners, Chubb, Aon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intellectual Property Liability Insurance Market Trends and Innovations
Generative AI development is forcing rapid recalibration of coverage scopes as training data copyright claims outpace existing policy language. Carriers now face pressure to innovate in real-time as litigation precedents establish new liability contours.
Predictive analytics is integrating into underwriting workflows to assess patent litigation probability. Mid-sized technology enterprises now demand algorithmic risk scoring that incorporates prior art density and competitor enforcement history. This capability is compressing quote turnaround times and enabling dynamic premium adjustment based on portfolio composition shifts.
The FTC's scrutiny of patent assertion entities is reshaping enforcement geography. Reduced NPE activity in certain federal districts is pushing assertion strategies toward alternative venues, which carriers must monitor for loss ratio projection accuracy. European patent litigation is responding through the Unified Patent Court framework, which consolidates previously national enforcement channels.
Technology startups now procure intellectual property liability coverage through embedded distribution models. Insurance APIs integrated into venture capital due diligence platforms and law firm client onboarding workflows are displacing traditional broker channels for early-stage companies. This pattern concentrates in Silicon Valley and Boston venture ecosystems where investor mandates require coverage verification.
Intellectual Property Liability Insurance Market Segmentation
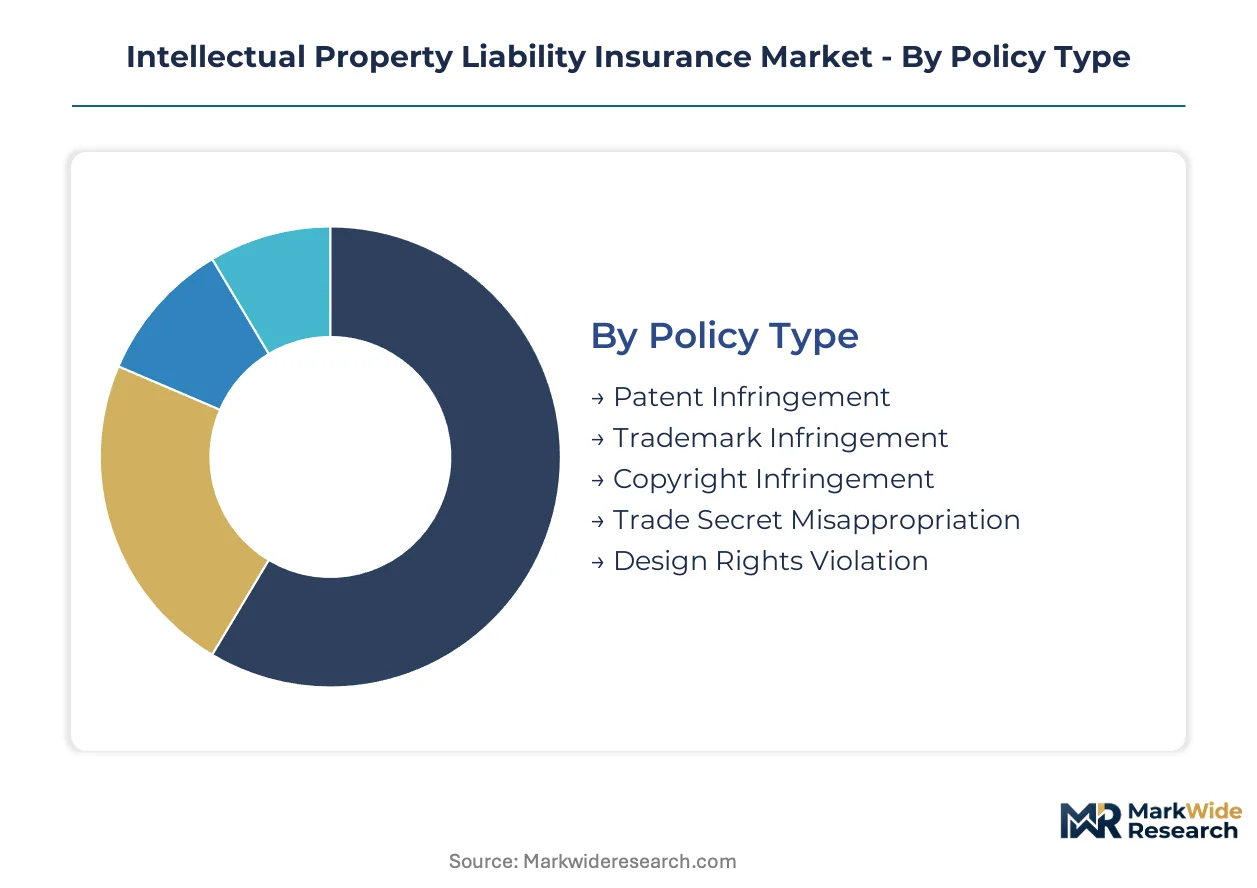
Intellectual property liability insurance segments reflect divergent risk profiles and underwriting complexity. Patent disputes demand bespoke legal panels, while copyright coverage scales through modular products. Carrier pricing models vary dramatically across these boundaries.
Policy Type:
Technology specifications define coverage architecture and premium calculation methodology.
- Patent Infringement:Policies indemnify against utility and design patent claims, requiring freedom-to-operate opinions and prior art searches before binding. Mid-sized enterprises in software and biotech drive uptake as NPE litigation persists in Eastern and Western Texas federal districts.
- Copyright Infringement:Coverage addresses unauthorized reproduction, distribution, and derivative works. Media agencies and generative AI developers generate demand as training data disputes create novel exposure categories not captured in legacy wordings.
- Trademark Infringement:Protects against brand confusion and dilution claims. Consumer goods manufacturers and franchise operators constitute the core buyer base.
- Trade Secret Misappropriation:Covers confidential information theft, particularly in pharmaceutical and technology sectors where employee mobility risks are elevated.
- Design Rights Violation:Addresses aesthetic and ornamental infringement in consumer products and industrial equipment.
Patent infringement leads on scale; copyright infringement leads on momentum.
Coverage Scope:
Cost tier differentiation separates premium pricing for high-exposure defense components from standardized ancillary benefits.
- Litigation Defense:Indemnifies legal fees, court costs, and discovery expenses. Defense costs now routinely exceed damages in protracted disputes, compressing carrier loss ratios and forcing rate hardening across all policy tiers.
- Monetary Damages:Covers adverse judgment awards and statutory penalties. Technology startups in patent-dense sectors face the steepest premium adjustments.
- Settlement Costs:Funds negotiated resolution payments and release agreements. Early-stage companies prioritize this coverage to preserve runway capital.
- Legal Consultation:Provides pre-litigation advisory services and portfolio audits. Manufacturing firms leverage this for freedom-to-operate reviews.
- Expert Witness Fees:Retains technical specialists and damages economists. Complex multi-jurisdictional disputes require Lloyd's syndicate backing.
Litigation defense dominates premium pools; settlement costs are expanding most quickly among SME buyers.
End User Industry:
Application-specific risk profiles dictate underwriting workflows and policy structure complexity.
- Technology Startups:Venture-backed software and AI companies represent the fastest-growing buyer segment. Embedded insurance APIs integrated into VC due diligence platforms displace traditional broker channels in Silicon Valley and Boston ecosystems.
- Manufacturing Firms:Industrial equipment and consumer goods producers require design rights and patent infringement coverage. The America Invents Act's first-to-file rules intensify defensive patenting behavior among mid-sized enterprises.
- Media Agencies:Content creators and publishers concentrate demand for copyright and trademark coverage. Generative AI training data disputes force rapid recalibration of policy wordings.
- Pharmaceutical Companies:CRISPR and antibody platform patent thickets generate freedom-to-operate review requirements. Underwriters mandate extensive documentation before binding.
- Financial Services:Fintech patent disputes and trade secret risks around algorithmic trading systems drive specialized coverage needs.
Technology startups lead on velocity; pharmaceutical companies lead on premium density.
Distribution Channel:
Customer type and purchase context determine channel economics and policy customization depth.
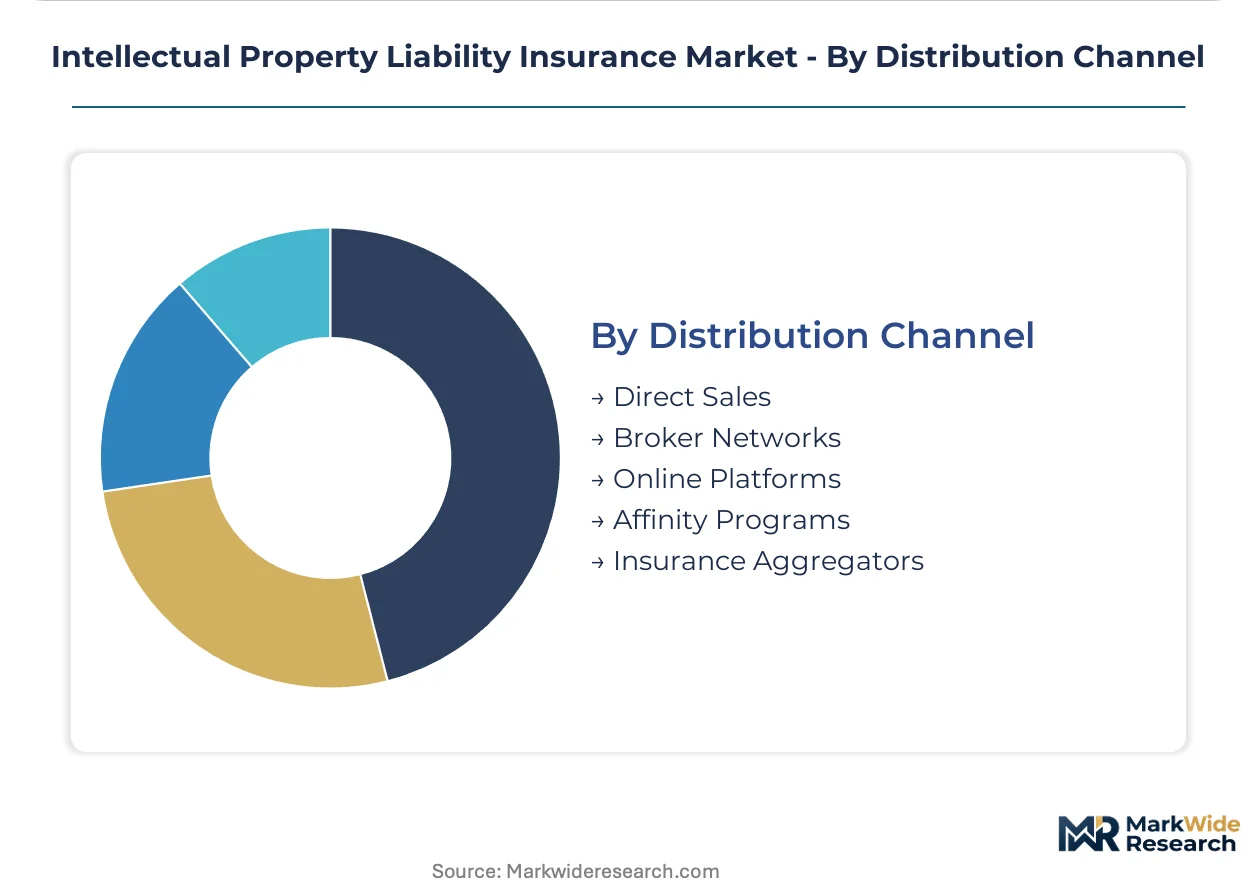
- Direct Sales:Carriers deploy captive underwriters for Fortune 500 accounts with complex multi-jurisdictional exposures. AIG dominates this tier with in-house claim assessment infrastructure.
- Broker Networks:Independent intermediaries serve mid-market enterprises requiring tailored manuscript endorsements. Chubb leverages Lloyd's relationships through this channel.
- Online Platforms:Digital quoting engines reduce underwriting friction for standardized copyright and trademark products. Hiscox competes aggressively here with modular structures.
- Affinity Programs:Law firms and venture capital platforms embed coverage into client onboarding workflows. This pattern concentrates where investor mandates require verification.
- Insurance Aggregators:Comparison engines aggregate quotes for small enterprises with straightforward risk profiles.
Broker networks retain the largest premium share; online platforms are gaining share fastest among technology startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patent litigation specialists cluster in United States federal districts, while Lloyd's syndicate underwriters anchor European capacity. Regulatory divergence between first-to-file regimes and unified patent frameworks shapes regional demand patterns.
United States
Forum shopping in Eastern and Western Texas federal courts sustains elevated litigation risk for technology startups and mid-sized enterprises. The America Invents Act's first-to-file rules intensify defensive patenting behavior among software and biotech companies. Silicon Valley and Boston venture ecosystems embed insurance verification into capital due diligence workflows.
United Kingdom
Lloyd's of London syndicates concentrate capacity for complex multi-jurisdictional patent disputes requiring cross-border enforcement expertise. The Financial Conduct Authority oversees carrier solvency standards for international IP liability coverage. London's legal services cluster supports captive claim assessment infrastructure for Fortune 500 accounts.
Germany
Industrial equipment manufacturers in Bavaria and Baden-Württemberg drive design rights and patent infringement coverage demand. The EU's Unified Patent Court framework consolidates previously fragmented national litigation channels into pan-European enforcement geography. Munich's patent law specialization supports freedom-to-operate review requirements for automotive and machinery exporters.
China
Domestic patent filing volume expansion generates defensive portfolio management needs among technology enterprises in Beijing and Shenzhen. The National Intellectual Property Administration implements examination guidelines that influence freedom-to-operate opinion standards. Yangtze River Delta manufacturing clusters increasingly procure trade secret misappropriation coverage for employee mobility risks.
Japan
Pharmaceutical and electronics patent thickets in Tokyo and Osaka generate specialized indemnification requirements for CRISPR and semiconductor platform technologies. The Japan Patent Office's accelerated examination programs interact with district court litigation to create dual-track exposure scenarios. METI's intellectual property policy frameworks shape corporate defensive patenting incentives.
Intellectual Property Liability Insurance Market Competitive Landscape
Top-tier vendors anchor the Fortune 500 segment with captive legal panels, while mid-market specialists compete through modular product structures. The market exhibits tiered concentration with three to five carriers controlling complex patent dispute capacity. Strategic archetypes include syndicate-backed multi-jurisdictional players, SME-focused digital distributors, and integrated claim assessment operators. Competitive moves center on embedded insurance API development and Lloyd's relationship leveraging for international dispute backing.
Within the integrated infrastructure tier, AIG and Chubb exemplify divergent approaches to claim assessment and capacity sourcing. AIG occupies a position emphasizing in-house legal panel control for high-exposure patent portfolios. Chubb represents the syndicate-leveraged archetype, utilizing Lloyd's relationships to sustain international dispute backing. Hiscox anchors the digital-first vector, competing through online platform distribution and modular policy structures that reduce underwriting friction for technology startups.
| Leading Market Players |
|---|
| Willis Towers Watson (WTW) |
| The Hartford |
| Intellectual Property Insurance Services Corporation (IPISC) |
| AIG |
| Hiscox |
| Marsh |
| Ambridge Partners |
| Chubb |
| Aon |
| Others |
Pricing and Supply Chain Analysis
Generative AI training data disputes are forcing carriers to simultaneously recalibrate underwriting cost structures and consolidate legal panel networks. This technological inflection compresses margins for standardized products while concentrating premium pricing power among syndicate-backed specialists with captive claim assessment infrastructure.
Pricing Analysis
Bundled litigation defense and damages coverage commands premium multiples over unbundled copyright-only policies. Patent infringement policies stratify across premium, standard, and economy tiers based on freedom-to-operate documentation depth and prior art search rigor. Pricing pressure stems from defense cost inflation exceeding damages in protracted Texas federal court disputes. Technology startups exhibit highest price sensitivity due to runway capital constraints, while Fortune 500 accounts accept rate hardening for captive legal panel access.
Supply Chain Analysis
Reverse-logistics flows for policy endorsements and manuscript amendments cycle through Lloyd's of London syndicates for complex multi-jurisdictional disputes. Primary capacity concentrates in the United States, United Kingdom, and Germany. Underwriting workflows draw from freedom-to-operate opinions, prior art databases, and claims history repositories. Single-source vulnerability sits with Lloyd's syndicate backing for international patent enforcement. Distribution runs through broker networks for mid-market accounts and embedded insurance APIs for technology startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intellectual property liability insurance functions as a geographic-arbitrage play between Eastern Texas litigation exposure and EU Unified Patent Court consolidation, with rate differentials of 40-60% between these enforcement venues.
For Market Incumbents: Extend captive legal panel networks into Munich and Tokyo to capture EU Unified Patent Court and Japan Patent Office dual-track proceedings. Consolidate claims assessment infrastructure against modular SME entrants eroding premium pools. Capacity addition in London preserves syndicate relationships for complex cross-border disputes.
For New Entrants and Emerging Players: Mid-sized biotech enterprises without freedom-to-operate documentation represent the most penetrable buyer archetype. White-space targets include CRISPR platform developers needing defensive patent coverage and antibody manufacturers facing employee mobility risks. Go-to-market execution should embed through venture capital due diligence platforms in Boston and San Francisco.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional carriers with Lloyd's syndicate access but underdeveloped digital distribution. Long-term viability hinges on underwriting workflow automation for prior art search burden reduction. The signal to watch is FTC enforcement action against patent assertion entities reshaping Eastern Texas litigation volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance API Development | Integration into venture capital due diligence platforms in Silicon Valley accelerates startup coverage verification. |
| Lloyd's Syndicate Capacity Expansion | London backing sustains international patent dispute reserves for complex multi-jurisdictional enforcement. |
| AI Training Data Rider Drafting | Bespoke copyright coverage for generative AI developers captures novel exposure categories ahead of precedent. |
| EU Unified Patent Court Structuring | Pan-European policy consolidation reduces fragmentation costs for automotive and machinery exporters. |
| Predictive Analytics Integration | Algorithmic risk scoring compresses quote turnaround for mid-sized technology enterprises. |
Research Methodology
Direct dialogue with insurance underwriters, patent litigation attorneys, venture capital due diligence officers, and technology startup CFOs grounded qualitative findings. Secondary validation drew from USPTO patent trial filings, Eastern and Western Texas federal court dockets, Lloyd's syndicate capacity disclosures, and EU Unified Patent Court procedural documents. Bottom-up premium pool estimates triangulated against top-down carrier reported line data.
Top-down market sizing anchored total addressable premium by jurisdiction, while bottom-up builds aggregated policy counts by buyer segment across the projection horizon. Segmentation dimensions modeled include policy type, coverage scope, end user industry, and distribution channel. CAGRs derived from patent litigation frequency trends, NPE enforcement volume trajectories, and first-to-file patent application growth curves.
Underlying measurement precision varies by segment; patent infringement policies carry tighter precision than emerging AI training data coverage. Forecasts reflect assumptions around FTC regulatory posture, USPTO examination timeline efficiency, and generative AI copyright precedent evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Credit Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Family Floater Health Insurance Market
Insurance
IoT Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Digital Transformation in Insurance Market