
 Cancer Insurance Market | 2026-2036
Cancer Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Insurance Market Insights
Insurer underwriting capacity in the United States is hardening as actuarial models absorb escalating oncology treatment costs. UnitedHealth Group leverages its Optum care delivery arm to align insurance risk with clinical outcomes. CVS Health anchors its cancer coverage portfolio within Aetna's employer-sponsored benefit structures. Cigna competes through integrated behavioral health support bundled with oncology case management.
Cancer insurance constitutes a supplemental health policy that pays lump-sum benefits or indemnities upon diagnosis of malignant neoplasms, with coverage triggers typically requiring histopathological confirmation and specified staging criteria. These products bridge cost gaps left by primary medical insurance, covering experimental therapies, travel for treatment, and non-medical expenses such as lost income. Individual policies command premium multiples above group equivalents due to adverse selection dynamics, while critical illness riders increasingly attach to term life products rather than standing alone. Distribution through brokers and agents still dominates policy origination volume, though online platforms capture younger demographics seeking streamlined underwriting.
The National Association of Insurance Commissioners coordinates state reserve requirements and policy form approvals, while CMS reimbursement schedules indirectly set the baseline against which supplemental benefits calculate payouts. State insurance departments in California, New York, and Texas enforce distinct mandated benefit laws that constrain product flexibility. Stakeholders must monitor whether gene therapy and CAR-T administration costs force benefit limit restructuring before policyholder shock claims erode trust.
Market Dynamics
Escalating CAR-T therapy costs and precision oncology pricing are forcing insurers to redesign benefit triggers and payout structures before reserve adequacy erodes. The gap between primary medical coverage and actual patient out-of-pocket exposure continues widening as novel biologics launch at six-figure price points.
Growth Catalysts
- Employer-Sponsored Expansion:Large employers in the United States are adding supplemental cancer coverage to core benefit menus as retention tools amid labor competition. Group policy attachment rates climb in manufacturing and technology sectors.
- State Mandate Accumulation:California, New York, and Texas now require minimum cancer screening coverage in fully insured plans, creating standardized demand pools that reduce adverse selection for supplemental products.
- Immunotherapy Cost Trajectory:Checkpoint inhibitor regimens extending treatment duration multiply the financial exposure gap that supplemental policies are designed to bridge.
Market Restraints
- Actuarial Uncertainty:Gene therapy reimbursement volatility and one-time curative dosing models defy traditional premium-reserve matching frameworks.
- Adverse Selection Concentration:Individual policy channels attract disproportionate enrollment from higher-risk demographics with family cancer histories, compressing margins.
- Primary Plan Benefit Compression:High-deductible health plans with health savings account pairing reduce the perceived value of supplemental first-dollar cancer benefits.
Strategic Opportunities
- Middle-Market Employer Penetration:Firms with 100-500 employees in the United States remain undersupplied relative to Fortune 500 saturation, representing white space for simplified group underwriting.
- Behavioral Health Bundling:Integrated oncology case management with psychiatric support addresses unmet patient needs during active treatment, differentiating beyond pure indemnity payout.
- Digital Distribution Infrastructure:Direct-to-consumer platforms with accelerated underwriting using electronic health record integration capture younger, healthier risk pools outside traditional agent channels.
Industry Challenges
- Specialized Underwriting Talent Scarcity:Actuaries with oncology claims modeling expertise command premium compensation, constraining product development velocity at mid-size carriers.
- Legacy System Integration Friction:Core policy administration platforms require expensive retrofitting to accommodate episode-based benefit triggers and real-time claims adjudication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Insurance Market |
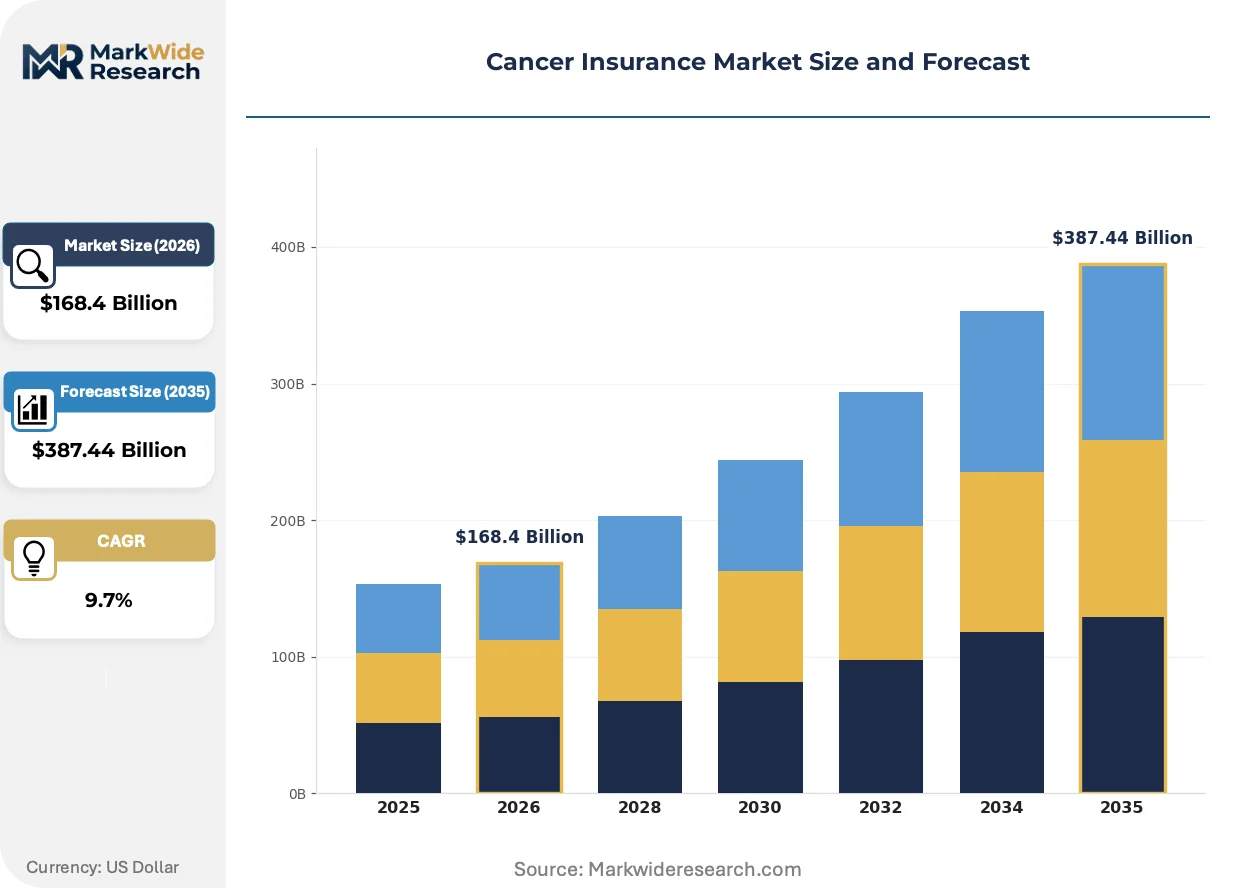
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $387.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family Floater, Senior Citizen, Critical Illness, Group Coverage Benefits: Inpatient Hospitalization, Outpatient Treatment, Diagnostic Tests, Chemotherapy, Radiotherapy, Surgical Procedures Distribution Channel: Direct Sales, Brokers & Agents, Bancassurance, Online Platforms, Corporate Tie-ups Customer Profile: Young Adults, Middle-aged Professionals, Seniors, High-risk Individuals |
| Companies Covered | Centene Corporation, CVS Health, UnitedHealth Group, Health Care Service Corporation, Cigna, Elevance Health, Humana, Molina Healthcare, Kaiser Permanente, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Insurance Market Trends and Innovations
Digital health data streams and alternative benefit structures are compressing the traditional supplemental insurance model toward embedded, predictive coverage. Product design is pivoting from post-diagnosis indemnity to pre-diagnosis risk management and care navigation.
Parametric trigger designs using biomarker surveillance and wearable-generated data are overtaking histopathological confirmation as the preferred coverage activation mechanism. Employers with self-funded health plans pilot these products to compress time-to-treatment and reduce catastrophic claim incidence. The structural consequence is a shift from pure financial indemnity toward care coordination and early intervention services bundled within the insurance contract.
The Affordable Care Act's essential health benefit definitions and state-level mandated benefit laws are constraining product flexibility in the United States. Insurers must navigate fifty distinct regulatory regimes when designing portable supplemental coverage. Carriers respond by concentrating product development resources in states with harmonized benefit requirements and broker distribution density.
Brokers and independent agents still originate the majority of cancer insurance volume, yet employer benefits administration platforms and payroll-integrated enrollment systems are capturing decision-making influence. Large employers in the United States increasingly demand API-enabled enrollment and real-time eligibility verification. This channel migration pressures traditional carriers to modernize agent compensation structures and digital quoting infrastructure.
Cancer Insurance Market Segmentation
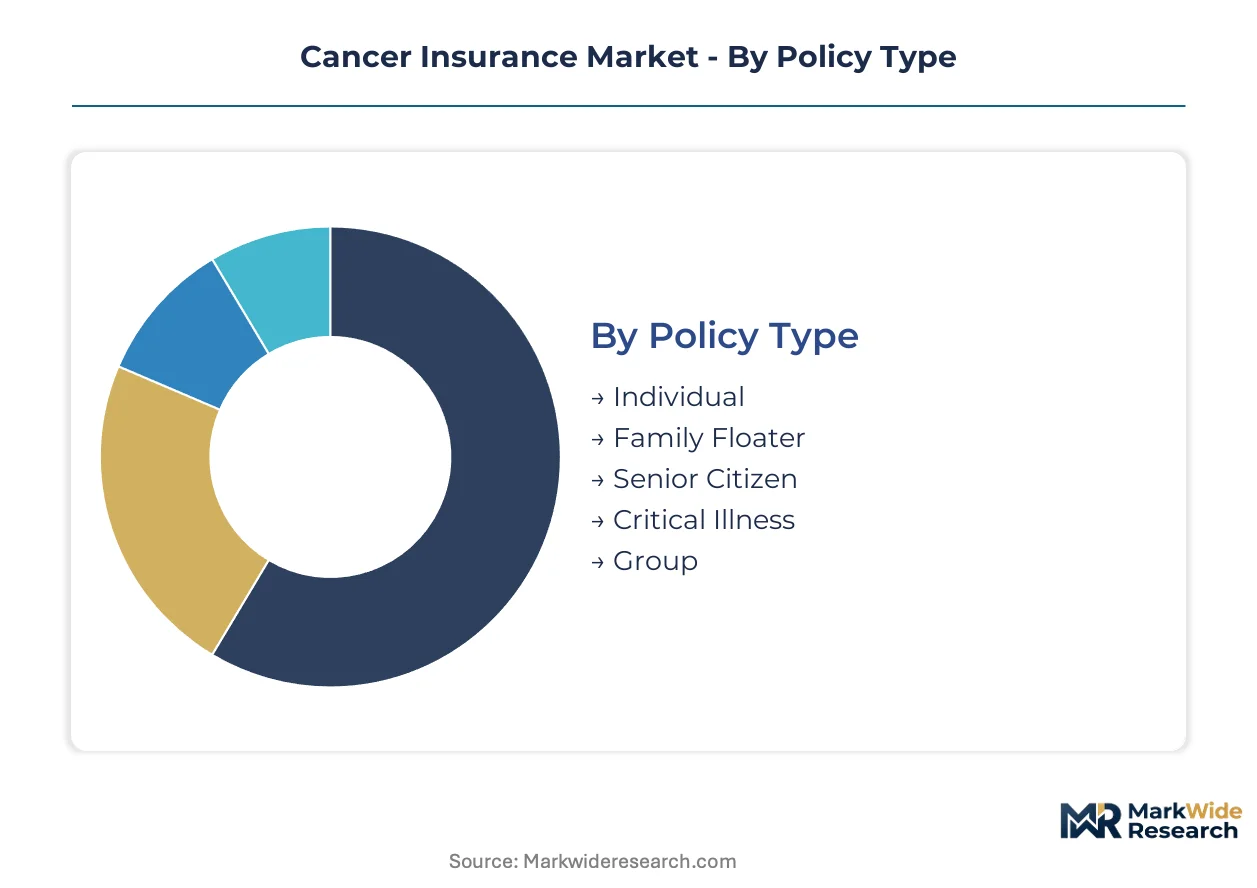
Cancer insurance segmentation reveals how product architecture aligns with divergent risk profiles and purchasing behaviors. Insurers calibrate premium-reserve ratios and benefit triggers distinctly across policy structures, creating tiered market access points.
Policy Type:
Group policies command lower per-capita premiums through pooled risk distribution, while individual policies absorb adverse selection costs through rate multiples.
- Individual:Underwritten on a single-life basis with full medical disclosure requirements. Demand concentrates among self-employed professionals in Texas and California seeking portable coverage outside employer channels. Premium loadings reflect family history disclosures and lifestyle risk factors.
- Family Floater:Single sum insured covers multiple lives under one contract, typically spouses and dependent children. Middle-income households in suburban United States markets select this structure for cost efficiency versus separate individual policies. Sum insured exhaustion by one member reduces coverage availability for others.
- Senior Citizen:Age-entry restrictions and waiting periods apply for first-time buyers above threshold ages. Coverage limits and co-payment structures reflect elevated incidence curves in older demographics.
- Critical Illness:Standalone or rider-based products paying lump-sum benefits upon histopathological confirmation. Simplified underwriting attracts applicants with primary medical coverage gaps.
- Group:Employer-sponsored or association-based coverage with guaranteed issue provisions. Manufacturing and technology sectors in the United States show climbing attachment rates as retention instruments.
Mature deployment sits with Group policies. Newer deployment is concentrated in Critical Illness riders attached to term life products.
Coverage Benefits:
Benefit design tracks the treatment cost trajectory, with inpatient coverage anchoring traditional products and outpatient benefits expanding to capture ambulatory oncology shifts.
- Inpatient Hospitalization:Room charges, nursing, and facility fees during confinement episodes. Demand remains strongest in markets with high deductible health plan penetration where hospitalization triggers substantial out-of-pocket exposure.
- Outpatient Treatment:Ambulatory infusion, observation, and same-day surgical services. Expanding fastest as checkpoint inhibitor regimens and oral oncolytics shift care from inpatient to clinic settings.
- Diagnostic Tests:Imaging, biopsy, and molecular profiling expenses. State mandates in New York and California require minimum screening coverage, standardizing demand pools.
- Chemotherapy:Cytotoxic drug administration and supportive medications. Traditional coverage anchor with established reimbursement schedules.
- Radiotherapy:External beam and brachytherapy sessions. Proton therapy centers in select United States metropolitan areas drive benefit limit negotiations.
- Surgical Procedures:Tumor resection, reconstructive, and palliative operations. Robotics-assisted techniques command supplemental benefit riders in premium products.
Standardized benefits concentrate in Inpatient Hospitalization. Experimental and extended-duration therapies are driving expansion in Outpatient Treatment.
Distribution Channel:
Channel selection determines customer acquisition cost and risk pool composition, with traditional intermediaries retaining volume leadership while digital platforms capture younger demographics.
- Direct Sales:Carrier-employed agents and captive distribution forces. Higher persistency rates offset elevated fixed cost structures compared to independent channels.
- Brokers & Agents:Independent intermediaries originating majority of individual policy volume. Compensation structures face pressure from digital quoting transparency.
- Bancassurance:Bank branch and digital banking platform distribution. Deposit base access enables lower-cost customer acquisition in mass-market segments.
- Online Platforms:Direct-to-consumer enrollment with accelerated underwriting using electronic health record integration. Climbing fastest among demographics under 40 seeking streamlined purchase journeys.
- Corporate Tie-ups:Employer benefits administration platforms and payroll-integrated enrollment systems. Large United States employers demand API-enabled eligibility verification and real-time data exchange.
Established volume sits with Brokers & Agents. Steepest expansion trajectory belongs to Online Platforms with embedded underwriting technology.
Customer Profile:
Risk selection and product positioning diverge sharply across life-stage segments, with age-band pricing reflecting actuarial incidence curves.
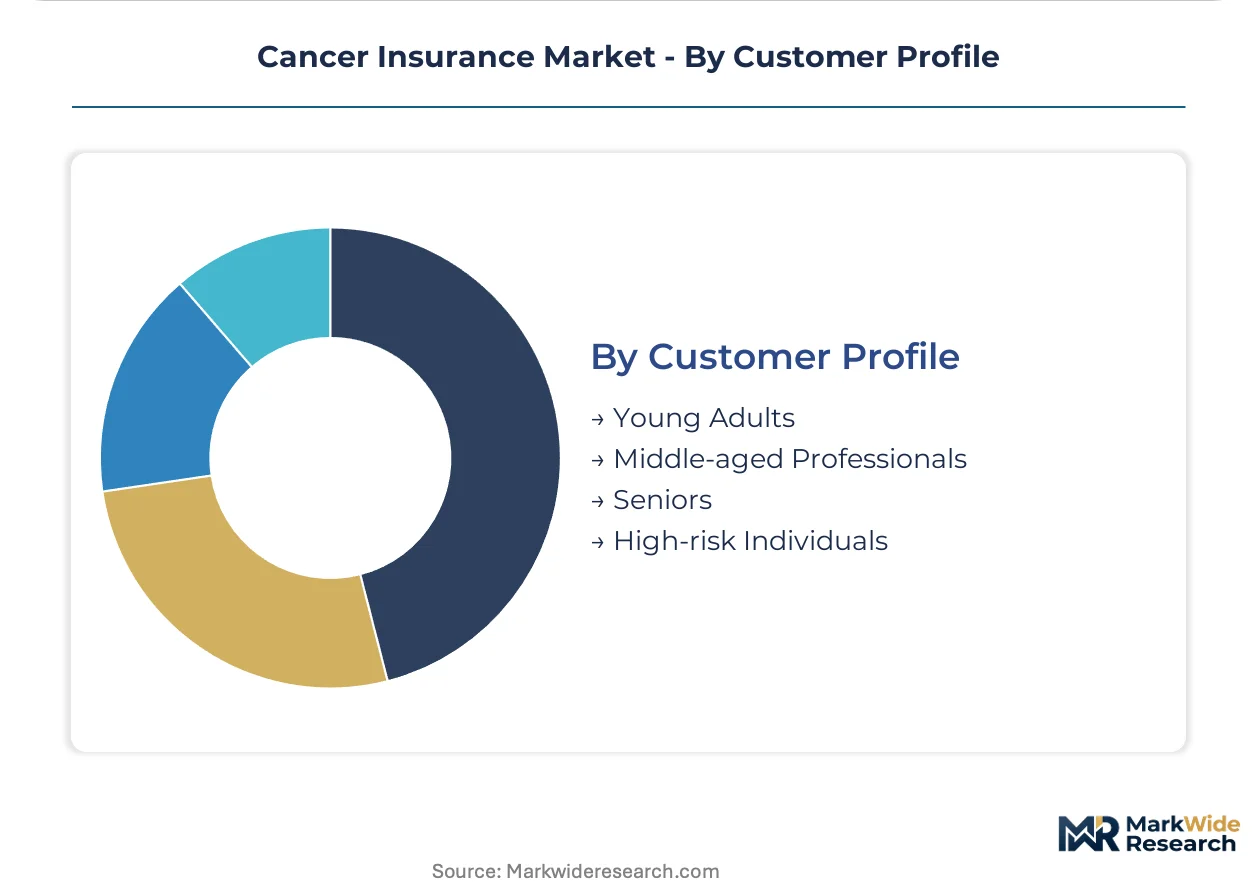
- Young Adults:Ages 18-35 with limited health service utilization history. Digital-native purchasing preferences and price sensitivity drive term-life rider attachment rather than standalone cancer products.
- Middle-aged Professionals:Prime earning years with employer benefit decision authority. Family floater selection peaks in this segment alongside supplemental individual coverage for coverage gaps.
- Seniors:Ages 60+ with elevated risk profiles and restricted entry options. Guaranteed-issue products with graded benefits attract first-time buyers despite higher premium multiples.
- High-risk Individuals:Documented family history or genetic predisposition carriers. Adverse selection concentration compresses margins; simplified issue products with waiting periods manage selection risk.
Volume concentration rests with Middle-aged Professionals. Product innovation and digital distribution investment targets Young Adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High treatment costs in the United States anchor geographic demand concentration, while employer-sponsored benefit expansion and regulatory fragmentation create distinct market conditions across national boundaries.
United States
Employer-sponsored group plans drive volume expansion as Fortune 500 firms add supplemental cancer coverage to retention packages. The Affordable Care Act's essential health benefit requirements establish baseline coverage floors, while state-level mandates in California, New York, and Texas constrain product portability. The Dallas-Fort Worth metroplex hosts dense broker distribution networks serving mid-market employer segments.
Canada
Provincial health plan gaps in prescription drug coverage and out-of-hospital services sustain demand for private supplemental products. Health Canada regulates medical device and drug reimbursement schedules that indirectly shape benefit trigger calculations. Toronto's financial district concentrates group insurance underwriting capacity serving Ontario-based employers.
Germany
Statutory health insurance benefit limitations for experimental oncology therapies create addressable market space for private supplementary policies. The BfArM (Federal Institute for Drugs and Medical Devices) governs reimbursement eligibility for novel cancer treatments. Munich and Frankfurt insurance clusters develop products calibrated to German incidence patterns and treatment protocols.
United Kingdom
NHS waiting time pressures and restricted access to specialized oncology centers drive uptake of private medical insurance with cancer riders. The Prudential Regulation Authority and Financial Conduct Authority supervise insurer solvency and consumer protection standards. London's Lloyd's market structures specialty reinsurance capacity backing primary cancer risk.
Japan
Aging demographics and elevated gastric cancer incidence sustain demand for disease-specific coverage products. The Ministry of Health, Labour and Welfare regulates standardized benefit designs through the Cancer Insurance Standard Policy Terms. Tokyo-based life insurers dominate product distribution through tied agency networks and bancassurance partnerships.
Cancer Insurance Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and care integration depth. Market structure tilts toward consolidated national champions in the United States, where vertical integration between insurance underwriting and care delivery creates defensive moats. Strategic archetypes include integrated payer-providers owning captive delivery assets, diversified health services conglomerates anchoring coverage within retail pharmacy footprints, and specialized regional plans concentrating on narrow network oncology management. Dominant competitive moves encompass acquisitions of oncology practices to align risk with outcomes, and partnerships with digital health platforms to compress underwriting friction.
Within the integrated payer-provider tier, UnitedHealth Group and Kaiser Permanente occupy positions that exemplify care delivery ownership as a risk management instrument. Among diversified health services conglomerates, CVS Health anchors coverage distribution through retail pharmacy proximity and Aetna's employer benefit infrastructure. Cigna represents the specialty carve-out archetype, bundling behavioral health and oncology case management to differentiate beyond indemnity structures.
| Leading Market Players |
|---|
| Centene Corporation |
| CVS Health |
| UnitedHealth Group |
| Health Care Service Corporation |
| Cigna |
| Elevance Health |
| Humana |
| Molina Healthcare |
| Kaiser Permanente |
| Others |
Pricing and Supply Chain Analysis
Guaranteed-issue versus fully underwritten policy bifurcation creates divergent cost structures that reshape both premium-setting authority and distribution infrastructure. Group employer channels leverage pooled risk pools to compress per-capita pricing, while individual direct-to-consumer products absorb adverse selection through rate multiples that strain agent commission sustainability.
Pricing Analysis
Warranty-style service bundling separates premium oncology case management products from stripped-down indemnity-only policies. Three-tier pricing structure across premium, standard, and economy levels reflects actuarial confidence in risk pools, with premium tiers incorporating care navigation and behavioral health support. Cost compression in the individual channel is intensifying because electronic health record-enabled accelerated underwriting reduces acquisition friction. Price sensitivity peaks among young adults seeking term-life rider attachments, while middle-market employers demonstrate inelastic demand for retention-focused group benefits.
Supply Chain Analysis
State-level policy form approval processes gate product portability across regulatory jurisdictions. Underwriting capacity concentrates in the United States, with actuarial talent clusters in Hartford and Chicago feeding product development pipelines. Reinsurance capacity draws from London's Lloyd's market and Bermuda's catastrophe bond structures. Single-source vulnerability sits with specialized oncology claims modeling expertise, where talent scarcity constrains mid-size carrier velocity. Distribution runs through broker networks in mature markets and payroll-integrated enrollment platforms in employer-sponsored segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around carriers with integrated care delivery assets, as gene therapy cost volatility forces thinly capitalized players toward exit or acquisition. Actuarial uncertainty from one-time curative dosing models accelerates the winnowing.
For Market Incumbents: Cement defensive moats through captive oncology practice acquisitions that align premium risk with clinical outcomes. Deepen backward integration into care delivery assets in Texas and California, where state mandate accumulation standardizes demand pools. Counter digital-native distributors by modernizing agent compensation structures and API-enabled quoting infrastructure. For New Entrants and Emerging Players: Capture white space in the 100-500 employee mid-market employer segment, where Fortune 500 saturation leaves simplified group underwriting underserved. Penetrate suburban United States family floater demand through bancassurance partnerships with deposit-base access. Lead with accelerated underwriting using electronic health record integration to outflank legacy agent channels on acquisition cost. For Investors and Strategic Acquirers: Re-rating potential sits with regional carriers possessing narrow-network oncology management capabilities given employer demand for integrated behavioral health bundling. Long-term viability favors platforms with care coordination infrastructure over pure indemnity underwriters. Monitor CAR-T reimbursement volatility as the signal to watch for reserve adequacy stress and forced seller dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Oncology Practice Acquisition | UnitedHealth Group's Optum model demonstrates risk-outcome alignment through captive delivery ownership. |
| Digital Distribution Infrastructure | Electronic health record integration enables accelerated underwriting that captures healthier risk pools outside agent channels. |
| Behavioral Health Bundling | Cigna's integrated psychiatric support with oncology case management differentiates beyond pure indemnity payout structures. |
| Mid-Market Employer Penetration | Simplified group underwriting for 100-500 employee firms addresses white space left by Fortune 500 saturation. |
| Parametric Trigger Redesign | Biomarker surveillance activation shifts products from post-diagnosis indemnity toward pre-diagnosis risk management services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with actuarial directors, benefits consultants, employer benefits administrators, and state insurance commissioners combined with secondary validation from NAIC policy form filings, CMS reimbursement schedules, and employer benefits survey databases. Bottom-up policy origination volume estimates triangulated against top-down premium pool calculations across the analysis window.
Granularity-level modeling operated at policy type, coverage benefit, distribution channel, and customer profile dimensions. CAGRs derived from segmented growth rate assumptions calibrated to treatment cost trajectories and employer benefit expansion patterns. Forecast inputs incorporated immunotherapy pricing volatility, state mandate accumulation timelines, and digital distribution penetration curves throughout the projection horizon.
The model holds under stable gene therapy reimbursement frameworks and employer-sponsored benefit expansion; deviation in CAR-T cost trajectory or federal essential health benefit redefinition would shift reserve adequacy assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Extended Warranty Market
Insurance
Business Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Engineering Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Property Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
United States Commercial Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Europe Health Insurance Market