
 Europe Electronic Gadgets Insurance Market | 2026-2036
Europe Electronic Gadgets Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electronic Gadgets Insurance Market Foresight
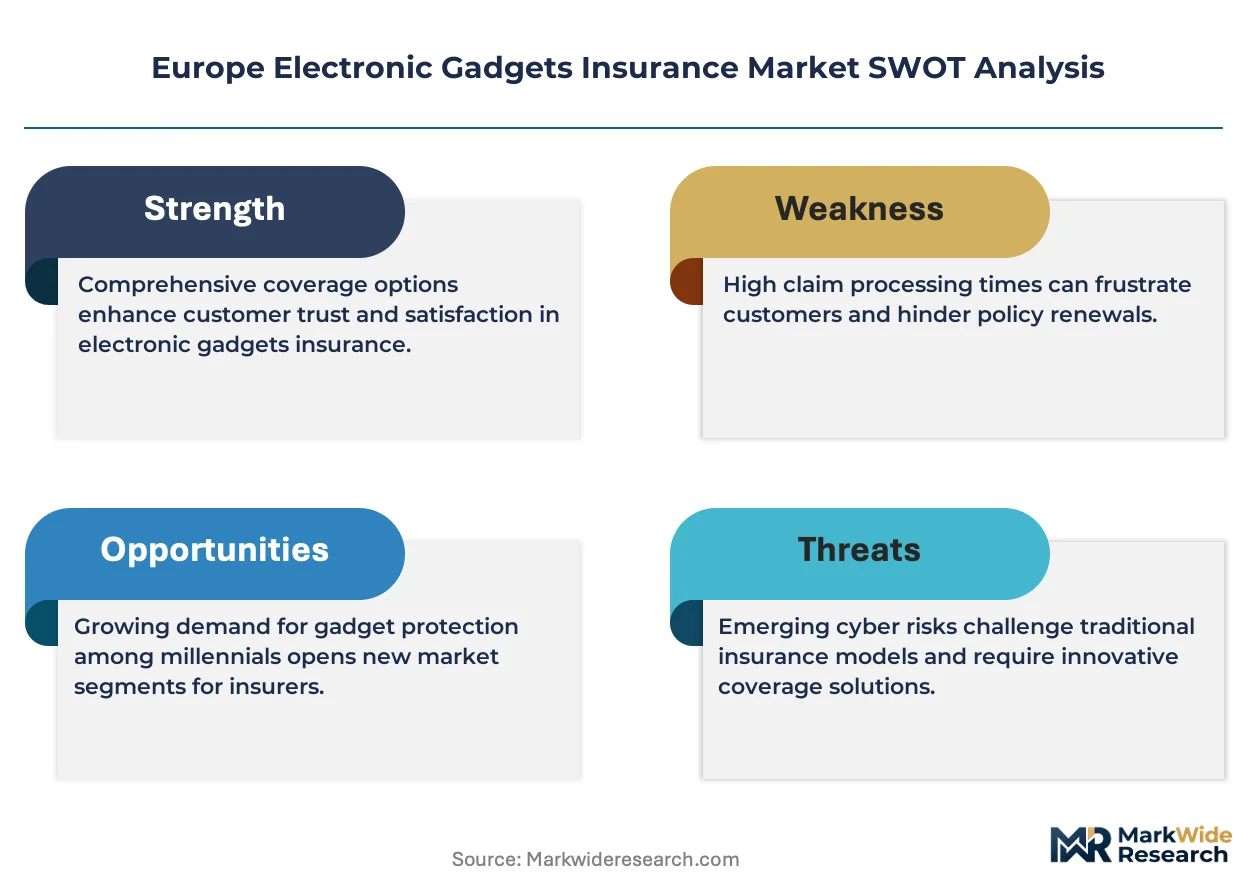
Premium-tier coverage with same-day replacement guarantees is unwinding legacy deductible structures across the European gadget insurance landscape. AXA leverages its pan-European broker network to sustain cross-border policy portability. simplesurance GmbH anchors embedded checkout partnerships with major electronics retailers. Assurant, Inc. competes through specialized liquid-damage underwriting expertise for high-end smartphones.
Electronic gadgets insurance constitutes a risk-transfer mechanism covering repair, replacement, and liability costs for portable consumer electronics, typically underwritten with depreciation-adjusted valuations and fraud-detection protocols. Smartphone policies command the largest premium pool due to high device turnover and repair cost inflation, while wearables coverage represents the fastest-expanding segment as fitness trackers and smartwatches penetrate corporate wellness programs. Extended warranty products retain mature margin profiles in laptop and tablet categories where manufacturer coverage periods have shortened.
The EU Digital Operational Resilience Act and national implementations of the Insurance Distribution Directive reshape product transparency requirements and commission disclosure standards across member states. EIOPA guidelines on conduct risk push carriers toward clearer policy wordings and accelerated claims resolution timelines. Stakeholders must monitor how embedded insurance partnerships with mobile carriers evolve under evolving EU consumer credit and distance-selling frameworks.
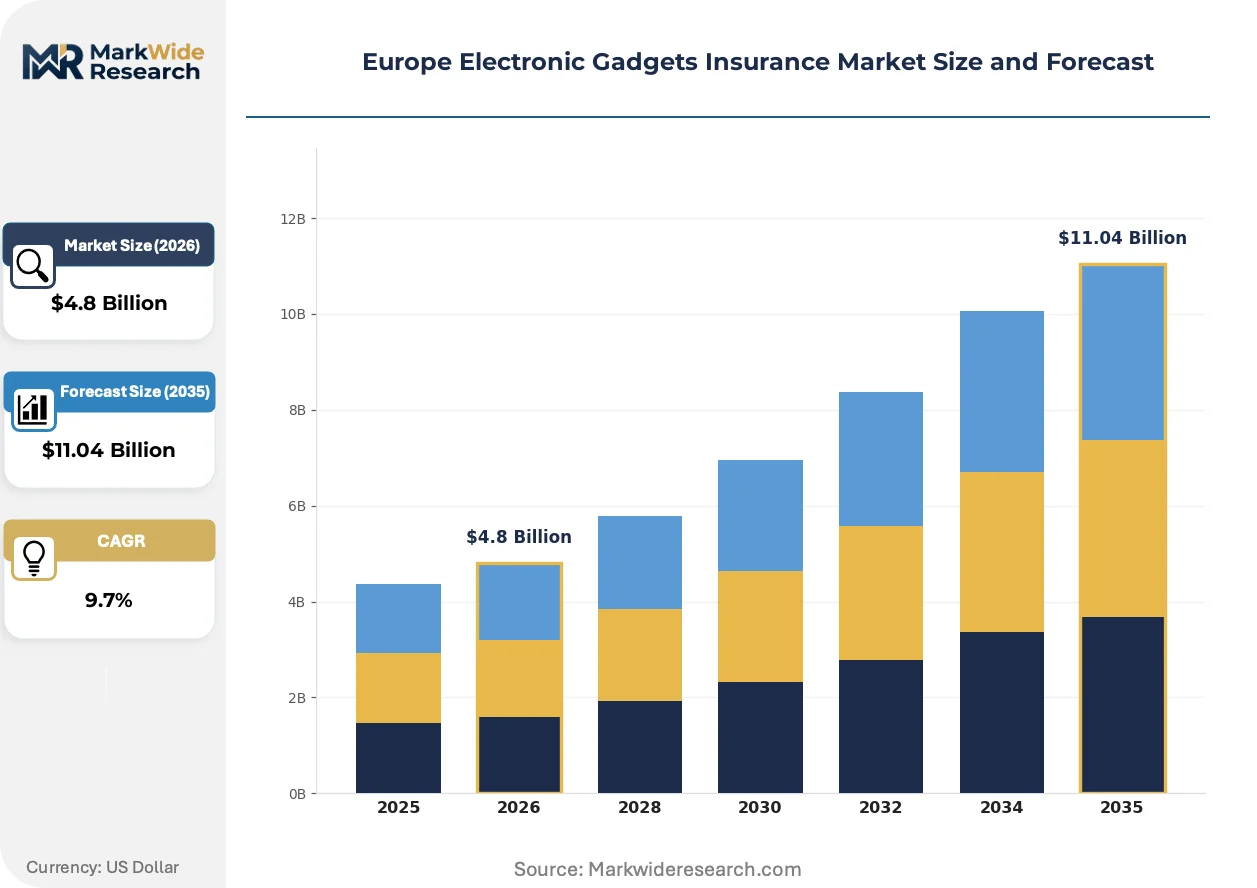
Market Dynamics
The EU Digital Operational Resilience Act is forcing carriers to rebuild underwriting frameworks for connected device risk, compressing policy development cycles and elevating compliance costs across national boundaries.
Growth Catalysts
- Remote Work Hardware Bundling:Young professionals in Germany and France are consolidating laptop, smartphone, and peripheral coverage into single policies, expanding addressable premium pools beyond traditional smartphone-only segments.
- EIOPA Conduct Risk Guidelines:Accelerated claims resolution mandates are differentiating responsive carriers from legacy players, rewarding operational investment with retention gains.
- Smartwatch Corporate Wellness Integration:Fitness trackers and health-monitoring wearables are penetrating employer-sponsored benefit programs, creating group policy channels that bypass individual consumer acquisition costs.
Market Restraints
- Repair Cost Inflation:OLED display and foldable hinge components for premium smartphones are driving loss ratios upward, squeezing margins on flagship device coverage.
- Fraud Detection Complexity:Synthetic identity schemes targeting same-day replacement guarantees are elevating verification overhead in France and Spain.
- Embedded Partnership Concentration:Checkout-integrated distribution depends on a narrow electronics retailer base, creating channel dependency risk.
Strategic Opportunities
- Eastern European Underpenetration:Poland and Romania exhibit sub-15% gadget insurance penetration versus Western European averages, offering first-mover expansion potential.
- EU AI Act Compliance Services:Algorithmic underwriting transparency requirements are creating advisory revenue streams for carriers with explainable risk-scoring capabilities.
- Telematics-Warranty Convergence:Connected car gadget policies are merging with usage-based auto modules, opening cross-sell pathways through mobility platforms.
Industry Challenges
- Legacy System Integration:Real-time claims APIs must interface with decades-old policy administration platforms, extending implementation timelines.
- Cross-Border Licensing Complexity:Passporting variations under national Insurance Distribution Directive implementations fragment product standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electronic Gadgets Insurance Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables Coverage Type: Theft, Accidental Damage, Liquid Damage, Extended Warranty Customer Type: Individuals, Families, Businesses, Educational Institutions Distribution Channel: Online Retailers, Insurance Brokers, Direct Sales, Mobile Carriers |
| Companies Covered | Allianz Insurance, AXA, Aviva, Asurion, LLC, Assurant, Inc., AIG, simplesurance GmbH, SPB UK & Ireland Ltd, Wertgarantie, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electronic Gadgets Insurance Market Shifts & Advancements
Embedded distribution partnerships and AI-driven claims automation are compressing policy lifecycles and reshaping carrier-retailer power dynamics across European markets.
Blockchain-enabled parametric settlement is bifurcating the claims resolution landscape. High-frequency, low-value smartphone repairs are migrating to smart-contract-triggered payouts. German and Dutch carriers are piloting these systems for screen-damage categories, reducing loss adjustment expense while compressing customer resolution time from days to hours.
GDPR Article 22 provisions on automated decision-making are tightening underwriting transparency requirements. Carriers must now document algorithmic risk-scoring logic for declined coverage or premium surcharges. French and Italian regulators are enforcing these mandates most aggressively, pushing carriers toward simpler, rules-based rating engines for entry-tier products.
Subscription-style coverage models are displacing annual policy structures in Nordic markets. Swedish and Danish consumers are migrating to monthly-cancellable gadget protection bundled with streaming and cloud storage services. Retailers are responding by unbundling point-of-sale insurance attachments, shifting distribution toward digital wallet and telco channels.
Europe Electronic Gadgets Insurance Market Segmentation
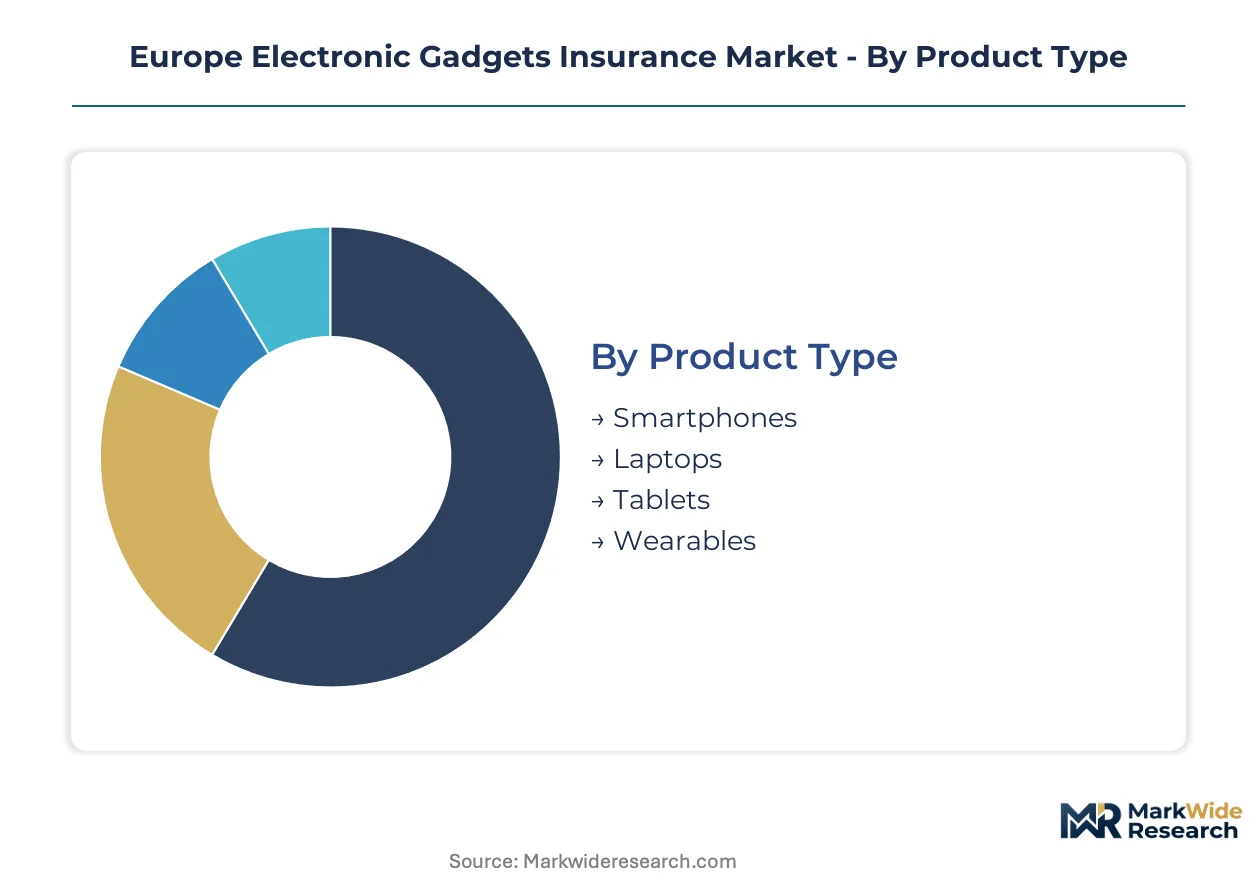
Segmentation in the European gadget insurance market reveals how regulatory frameworks and distribution economics fragment risk pools across device categories and customer profiles. Understanding these divisions exposes where carriers can optimize capital allocation and where embedded partnerships deliver superior acquisition economics.
Product Type:
GDPR Article 22 provisions on automated decision-making apply differentially across device categories, with biometric-enabled wearables triggering stricter algorithmic transparency requirements than standard laptops.
- Smartphones:OLED display assemblies and foldable hinge mechanisms drive repair cost inflation, compressing margins on flagship coverage. German and French urban corridors concentrate demand through mobile carrier bundled distribution, though fraud detection overhead for same-day replacement guarantees elevates operational costs.
- Laptops:Corporate remote work hardware bundling consolidates premium pools as young professionals seek consolidated coverage. Depreciation-adjusted valuations align with shortened manufacturer warranty periods, creating coverage gaps that extended warranty products exploit.
- Tablets:Educational procurement cycles in Italy and Spain generate seasonal demand spikes through institutional volume tenders.
- Wearables:Fitness trackers and health-monitoring smartwatches penetrate employer-sponsored wellness programs, bypassing individual acquisition costs through group policy channels.
Established volume favors Smartphones; emerging adoption favors Wearables.
Coverage Type:
EIOPA conduct risk guidelines mandate accelerated claims resolution timelines that reshape loss adjustment economics across damage categories.
- Accidental Damage:Screen replacement frequency dominates claims volume, with blockchain-enabled parametric settlement pilots in Germany and the Netherlands reducing resolution time from days to hours.
- Liquid Damage:Specialized underwriting expertise concentrates in high-end smartphone categories where corrosion assessment complexity justifies premium pricing tiers.
- Theft:Synthetic identity schemes targeting replacement guarantees elevate verification overhead, particularly in France and Spain.
- Extended Warranty:Mature margin profiles persist in laptop and tablet segments where manufacturer coverage periods have compressed, creating predictable revenue streams.
Accidental Damage commands the largest premium pool; Liquid Damage extracts the highest per-claim margins.
Customer Type:
EU Digital Operational Resilience Act requirements reshape how carriers underwrite connected device risk across organizational boundaries.
- Businesses:Remote work hardware consolidation drives policy bundling across laptop, smartphone, and peripheral categories. Cross-border policy portability requirements under national Insurance Distribution Directive implementations fragment standardization efforts for multinational accounts.
- Individuals:Monthly-cancellable subscription models displace annual structures in Nordic markets, with Swedish and Danish consumers migrating coverage toward digital wallet and telco channels.
- Families:Multi-device household policies leverage embedded checkout partnerships with major electronics retailers.
- Educational Institutions:Volume procurement tenders in Southern Europe create seasonal demand concentration with compressed margin profiles.
Businesses generate the highest policy values; Individuals are climbing the fastest toward subscription-style coverage.
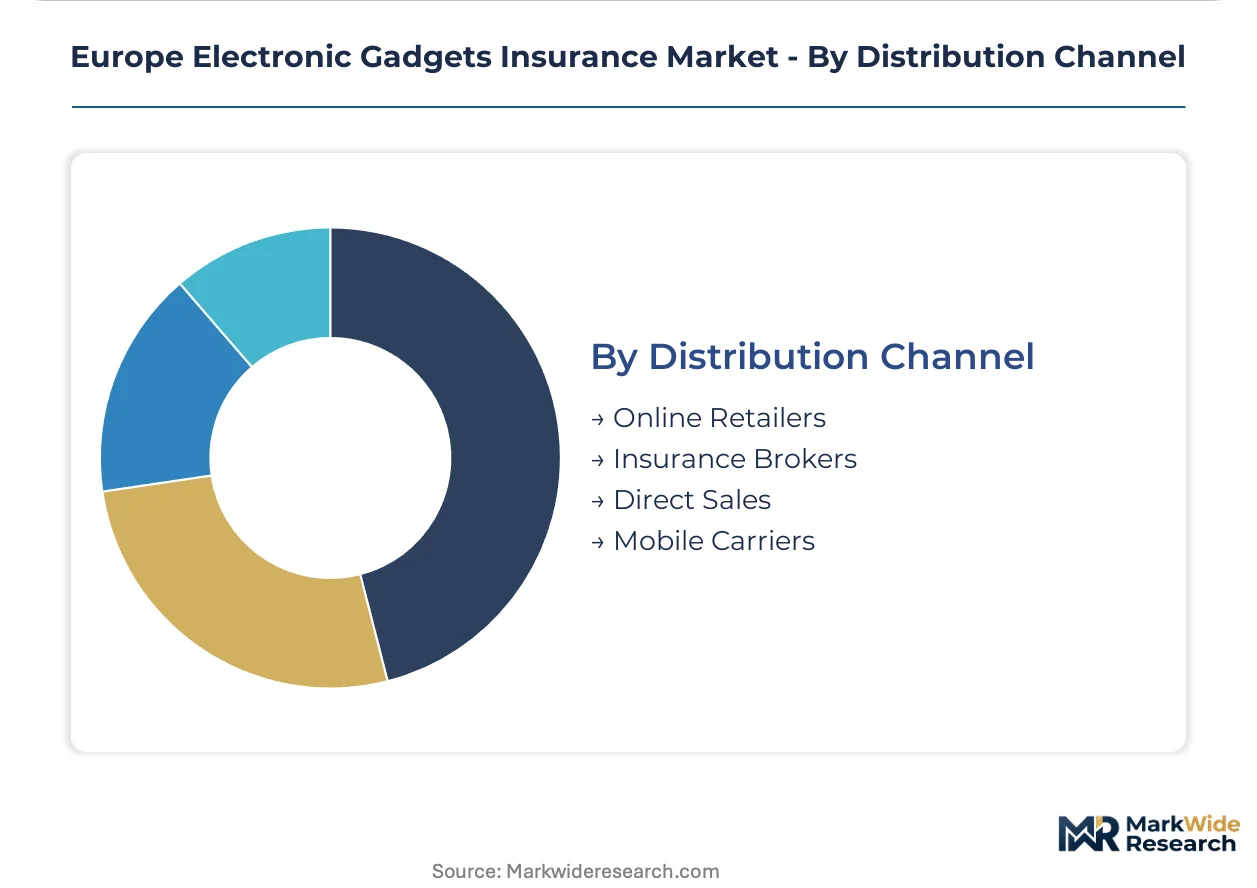
Distribution Channel:
EU consumer credit and distance-selling frameworks govern how embedded insurance partnerships evolve at point-of-sale.
- Mobile Carriers:Bundled smartphone coverage anchors subscriber retention strategies, with pan-European broker networks enabling cross-border policy portability.
- Online Retailers:Checkout-integrated distribution depends on narrow electronics retailer bases, creating channel dependency risk that unbundling trends in Nordic markets accelerate.
- Insurance Brokers:National licensing variations under Insurance Distribution Directive implementations complicate product standardization.
- Direct Sales:Digital-first acquisition targets underpenetrated Eastern European markets where Poland and Romania exhibit sub-15% penetration versus Western European averages.
Mobile Carriers dominate smartphone attachment rates; Online Retailers face margin compression from unbundling pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pan-European carriers dominate underwriting capacity, though national regulatory implementations fragment product portability across member states. Distribution economics favor mobile carrier bundling in Western corridors while direct digital channels penetrate Eastern markets.
Germany
Remote work hardware bundling concentrates premium pools among young professionals in Berlin and Munich. The national financial regulator BaFin enforces strict conduct risk standards under EIOPA guidelines, accelerating claims resolution timelines. Frankfurt anchors reinsurance capacity for cross-border gadget portfolios.
France
Synthetic identity fraud elevates verification overhead for same-day replacement guarantees in Paris and Lyon. CNIL enforces GDPR Article 22 provisions on automated underwriting decisions most aggressively here. The Île-de-France corridor drives smartphone policy volume through mobile carrier distribution.
United Kingdom
Post-Brexit regulatory divergence complicates passporting for London-based carriers serving EU gadget policies. The Financial Conduct Authority mandates clearer policy wordings under national Insurance Distribution Directive implementations. Manchester and Birmingham clusters specialize in extended warranty administration for laptop categories.
Poland
Sub-15% gadget insurance penetration creates first-mover expansion potential in Warsaw and Krakow. National transposition of EU consumer credit frameworks governs embedded checkout partnerships. Direct digital acquisition targets underpenetrated individual segments outside mobile carrier channels.
Sweden
Monthly-cancellable subscription models displace annual structures fastest here, with Stockholm consumers migrating coverage toward digital wallet channels. The Swedish Financial Supervisory Authority monitors distance-selling compliance for unbundled retail distribution. Malmö clusters pilot blockchain-enabled parametric settlement for screen-damage claims.
Europe Electronic Gadgets Insurance Market Competitive Landscape
Concentration sits with diversified insurance groups holding pan-European broker networks. The market structures around three tiers: integrated multiline carriers with cross-border licensing, specialized gadget underwriters with liquid-damage expertise, and embedded distribution platforms anchored at electronics retail checkout. Strategic moves center on portfolio diversification into wearables coverage and technology licensing for AI-driven claims automation.
Within the integrated carrier tier, Allianz Insurance and AXA occupy positions exemplifying scale-driven underwriting capacity and cross-border policy portability. Among specialized players, simplesurance GmbH represents the embedded distribution archetype through checkout-integrated partnerships. Assurant, Inc. anchors the liquid-damage specialization segment for high-end smartphone categories.
| Leading Market Players |
|---|
| Allianz Insurance |
| AXA |
| Aviva |
| Asurion, LLC |
| Assurant, Inc. |
| AIG |
| simplesurance GmbH |
| SPB UK & Ireland Ltd |
| Wertgarantie |
| Others |
Supply & Pricing Matrix
EIOPA conduct risk guidelines gate both carrier qualification and premium differentiation simultaneously, mandating accelerated claims resolution timelines that compress loss adjustment expense allowances while elevating operational investment requirements for policy wordings clarity.
Pricing Analysis
EIOPA conduct risk guidelines dictate the pricing tier structure across the European gadget insurance landscape. Three-tier pricing structure across premium, standard, and economy levels separates same-day replacement guarantees from depreciation-adjusted settlements and basic repair coverage. Cost compression in premium tiers is intensifying because OLED display and foldable hinge repair inflation outpaces premium rate adjustments. Small businesses and educational institutions exhibit highest price sensitivity due to volume procurement tender economics, while young professionals in urban corridors show lowest sensitivity to monthly subscription premiums.
Supply Chain Analysis
Just-in-time claims fulfillment dominates smartphone screen replacement logistics, though strategic stockpiling of liquid-damage assessment components persists for high-end device categories. Supply concentrates in Germany, France, and the Netherlands for underwriting capacity, with claims service networks drawing from Poland and Romania for cost-adjusted repair labor pools. Component dependencies hinge on OEM-authorized parts for flagship devices, third-party display assemblies for mid-tier coverage, and blockchain-enabled parametric settlement infrastructure. Single-source vulnerability sits with narrow electronics retailer bases for embedded checkout distribution. Distribution runs through mobile carrier bundling, direct digital acquisition, and insurance broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electronic Gadgets Insurance Market sits in early-cycle expansion, with Eastern European sub-15% penetration rates offering runway comparable to Western European corridors a decade prior.
For Market Incumbents: Secure cross-border policy portability through pan-European broker network reinforcement before national Insurance Distribution Directive implementations fragment standardization further. Invest in explainable AI risk-scoring capabilities to meet GDPR Article 22 algorithmic transparency mandates. Vertical integration into claims service networks reduces loss adjustment expense exposure as repair cost inflation accelerates. For New Entrants and Emerging Players: Differentiate on blockchain-enabled parametric settlement speed, targeting screen-damage categories where German and Dutch pilots demonstrate resolution compression from days to hours. Poland and Romania present the most penetrable geographies for direct digital acquisition outside mobile carrier channel dependency. Corporate wellness program integration for wearables coverage offers employer-sponsored group policy channels that bypass individual acquisition economics. For Investors and Strategic Acquirers: The EU Digital Operational Resilience Act reshapes the acquisition landscape by elevating compliance infrastructure valuations for carriers with real-time claims API capabilities. Long-term viability favors diversified platforms spanning smartphone, laptop, and wearables coverage rather than single-device specialists. Target acquisition archetypes include embedded distribution platforms with checkout-integrated electronics retailer relationships. Watch EIOPA enforcement patterns on conduct risk guidelines as the signal for operational investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Parametric Settlement | Smart-contract-triggered payouts compress German and Dutch screen-damage resolution timelines from days to hours. |
| Embedded Checkout Partnership Expansion | simplesurance GmbH's electronics retailer anchoring demonstrates superior acquisition economics versus direct channels. |
| Wearables Corporate Wellness Integration | Employer-sponsored benefit programs bypass individual consumer acquisition costs for fitness trackers and smartwatches. |
| Eastern European Direct Digital Launch | Poland and Romania's sub-15% penetration creates first-mover expansion potential outside mobile carrier dominance. |
| Cross-Border Policy Portability Investment | AXA's pan-European broker network sustains multinational account retention amid Insurance Distribution Directive fragmentation. |
Research Methodology
A standing panel of underwriting executives, claims operations directors, embedded distribution platform managers, and EIOPA regulatory affairs specialists provided ongoing calibration throughout the research cycle. Primary interviews with these stakeholders combined with secondary validation against EIOPA guideline documents, national Insurance Distribution Directive implementations, EU Digital Operational Resilience Act technical standards, and carrier annual disclosures. Bottom-up policy volume estimates triangulated against top-down premium pool assessments across the analysis window.
Consistency checks validated volume and value outputs against external regulatory filing benchmarks and embedded partnership disclosure patterns. The analytical framework modeled segmentation dimensions including device category, coverage type, customer profile, and distribution channel complexity across the projection horizon. CAGRs derived from fitted growth curves applied to premium pool trajectories, with inputs including remote work hardware bundling adoption curves, corporate wellness program penetration rates, and repair cost inflation indices.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of conduct risk guidelines or accelerated repair cost inflation trajectories would require recalibration. Forecasts reflect documented assumptions on embedded partnership evolution and fraud detection technology diffusion. Revision becomes warranted when GDPR Article 22 enforcement intensity or synthetic identity scheme sophistication crosses thresholds that materially alter verification overhead economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Liability Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Crime Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
China Property and Casualty Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Global Sports Insurance Market