
 Europe Home Mortgage Finance Market | 2026-2036
Europe Home Mortgage Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Mortgage Finance Market Foresight
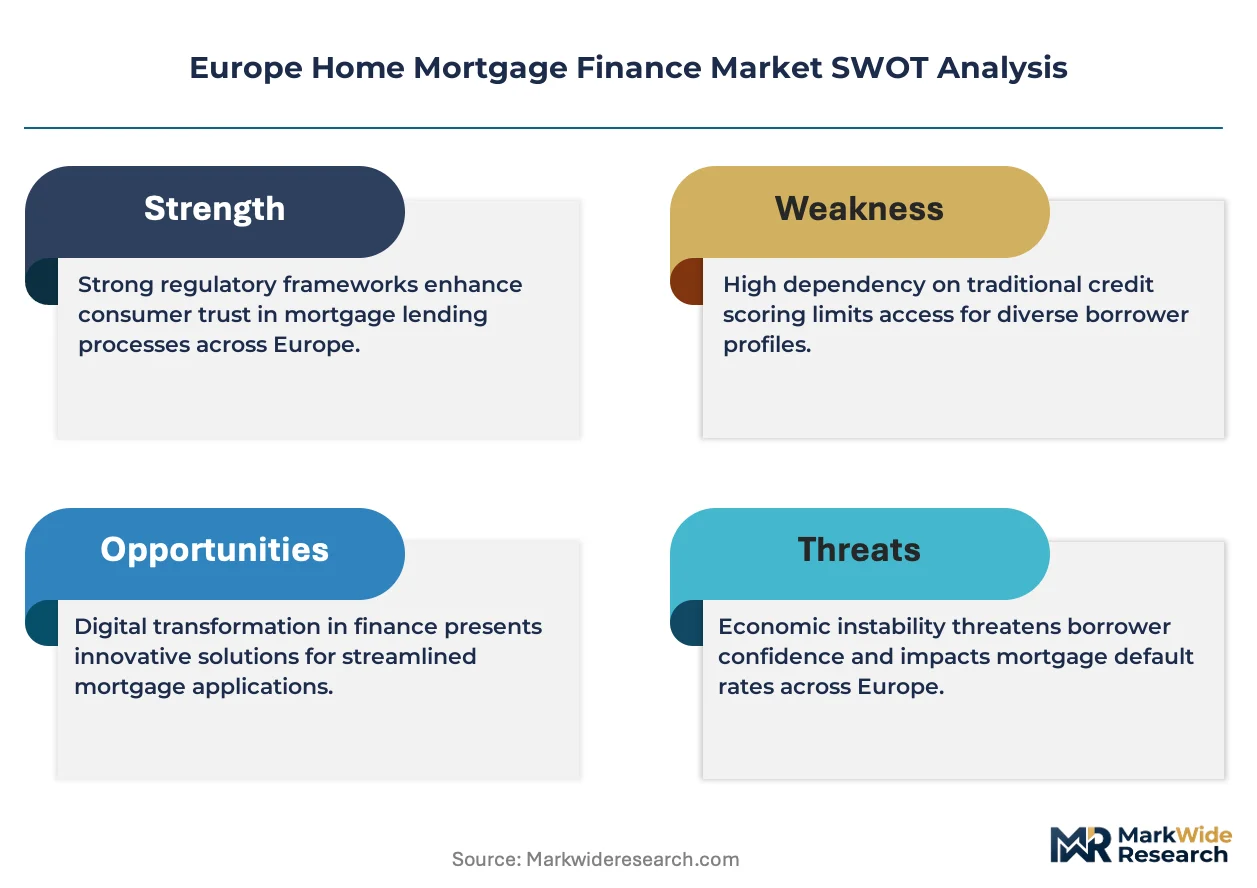
Germany's housing finance infrastructure is reconfiguring around rising interest rate environments and stricter capital reserve requirements. Deutsche Bank AG leverages its pan-European distribution network to sustain diversified origination across retail and commercial property segments. BNP Paribas anchors its position through specialized green mortgage products tied to energy performance certificates. Lloyds Banking Group competes on digital origination speed, reducing time-to-offer through automated valuation models.
Europe home mortgage finance encompasses secured lending instruments collateralized by residential real property, typically structured with loan-to-value ratios between 60% and 90% and amortization schedules spanning 15 to 30 years. These instruments channel household savings into property acquisition while generating interest income for depository institutions and covered bond investors. Fixed-rate mortgages dominate origination volumes in Northern Europe, where borrowers prioritize payment certainty over rate flexibility. Adjustable-rate mortgages concentrate in economies with established interbank reference rate traditions, offering lower initial spreads that reset against EURIBOR or national equivalents. Interest-only mortgages occupy a niche among high-net-worth investors seeking leverage optimization rather than principal amortization.
The European Banking Authority's capital adequacy frameworks and the EU's Mortgage Credit Directive shape product transparency, affordability stress-testing, and cross-border passporting rights for lenders. ESG disclosure requirements under the Corporate Sustainability Reporting Directive extend to mortgage portfolios, pressuring institutions to quantify and report financed emissions from residential collateral. Stakeholders must monitor how the transition from EURIBOR to alternative risk-free rates recalibrates pricing mechanics and hedging strategies across legacy and new originations.
Market Dynamics
The EU Green Deal's energy-efficiency lending incentives are redirecting capital flows toward green mortgage-linked instruments, forcing lenders to restructure product architectures around building renovation targets and carbon performance benchmarks.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Building renovation targets create dedicated origination pipelines for green mortgage products collateralized by energy performance certificates.
- Digital onboarding platforms:Automated documentation verification reduces friction for first-time buyers across Southern Europe, expanding addressable borrower pools.
- Spain:Rental-to-own conversion trends sustain elevated origination volumes as housing supply constraints persist in major metropolitan clusters.
Market Restraints
- Interest rate volatility:Rising rate environments compress net interest margins and strain affordability stress-testing thresholds under the EU Mortgage Credit Directive.
- Capital reserve requirements:European Banking Authority frameworks elevate risk-weighted asset charges, constraining balance sheet capacity for high-LTV originations.
- Interbank rate transition:The shift from EURIBOR to alternative risk-free rates introduces pricing uncertainty and hedging complexity across legacy portfolios.
Strategic Opportunities
- Portugal:Underpenetrated digital origination channels present first-mover advantages for automated valuation model deployment in secondary cities.
- Green mortgage securitization:Covered bond market integration of energy-efficient collateral pools attracts ESG-mandated institutional capital.
- API-based income verification:Open banking convergence with tax authority data streams enables real-time borrower qualification.
Industry Challenges
- Valuation model recalibration:Automated valuation systems require continuous training data updates to maintain accuracy amid volatile property price cycles.
- Legacy core banking integration:Green mortgage product modules face API compatibility friction with decades-old loan servicing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Mortgage Finance Market |
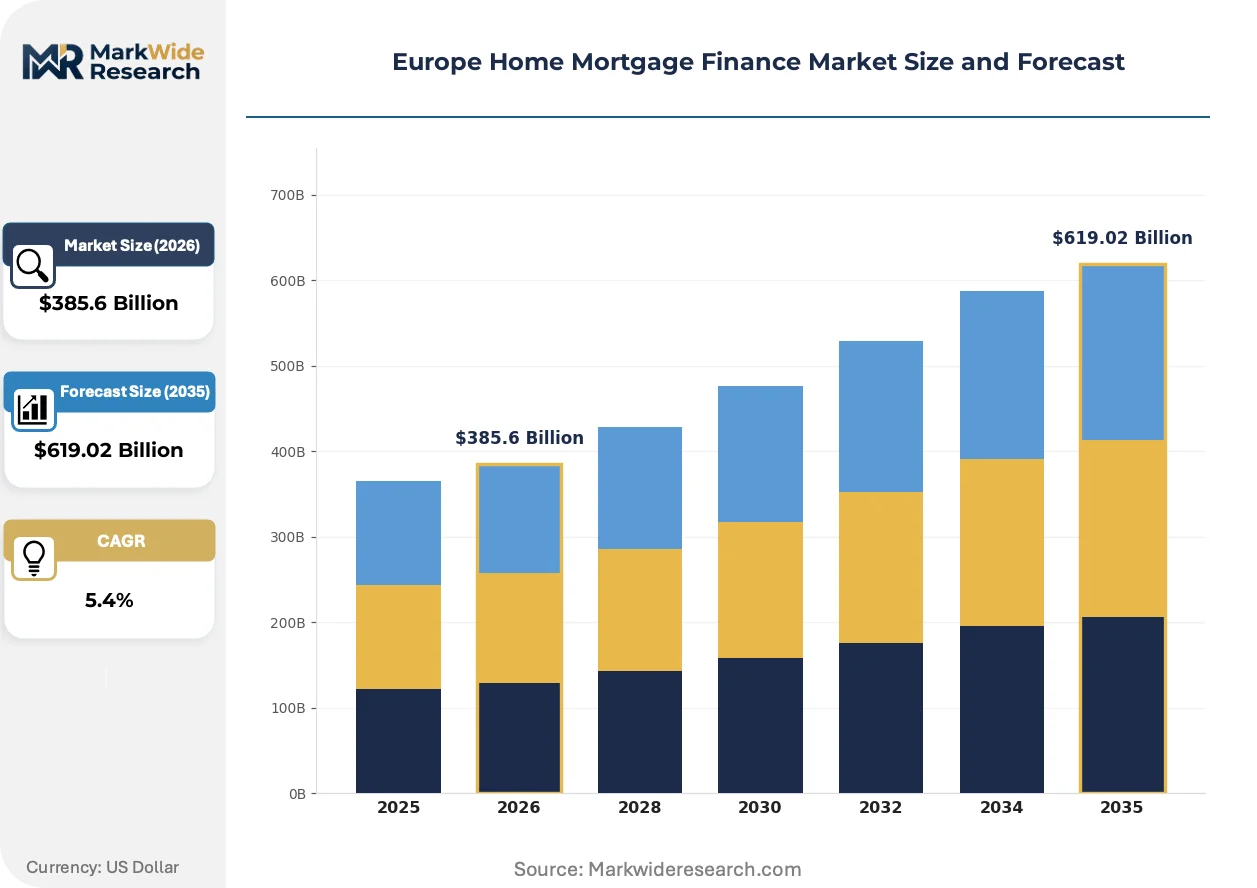
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $619.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Rate Mortgages, Adjustable-Rate Mortgages, Interest-Only Mortgages, Reverse Mortgages Client Type: First-Time Buyers, Refinancers, Investors, Homeowners Loan Term: Short-Term, Medium-Term, Long-Term, Flexible Term Service Type: Online Loans, In-Person Services, Brokered Services, Hybrid Services |
| Companies Covered | Crédit Agricole, Deutsche Bank AG, Lloyds Banking Group, Rocket Mortgage, Aareal Bank, Banco Santander, Barclays plc, Erste Group, BNP Paribas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Mortgage Finance Market Shifts & Advancements
Digital origination architectures are compressing time-to-offer metrics while regulatory disclosure mandates reshape portfolio transparency requirements across European lending institutions.
Automated valuation models leveraging satellite imagery and municipal transaction databases are rendering obsolete traditional in-person appraisal workflows for standard residential collateral. German savings banks deploy these systems for properties below specific value thresholds, compressing origination timelines from weeks to hours. The structural consequence is margin pressure on appraisal management companies and geographic expansion of direct-to-consumer lending channels.
The EU Corporate Sustainability Reporting Directive extends ESG disclosure obligations to residential mortgage portfolios, requiring institutions to quantify and report financed emissions from collateral properties. This mandate forces integration of energy performance certificate data into loan origination systems and risk rating methodologies. French and Dutch lenders face the most immediate compliance deadlines, driving vendor selection for carbon accounting software platforms.
First-time buyer segments across Italy and Greece increasingly favor fixed-rate instruments over adjustable-rate alternatives, reversing decades of rate-flexibility preference. This behavioral pivot reflects payment certainty prioritization amid volatile rate environments and compressed household savings buffers. Southern European retail banks respond by lengthening fixed-rate tenor offerings and hedging through covered bond issuance.
Europe Home Mortgage Finance Market Segmentation
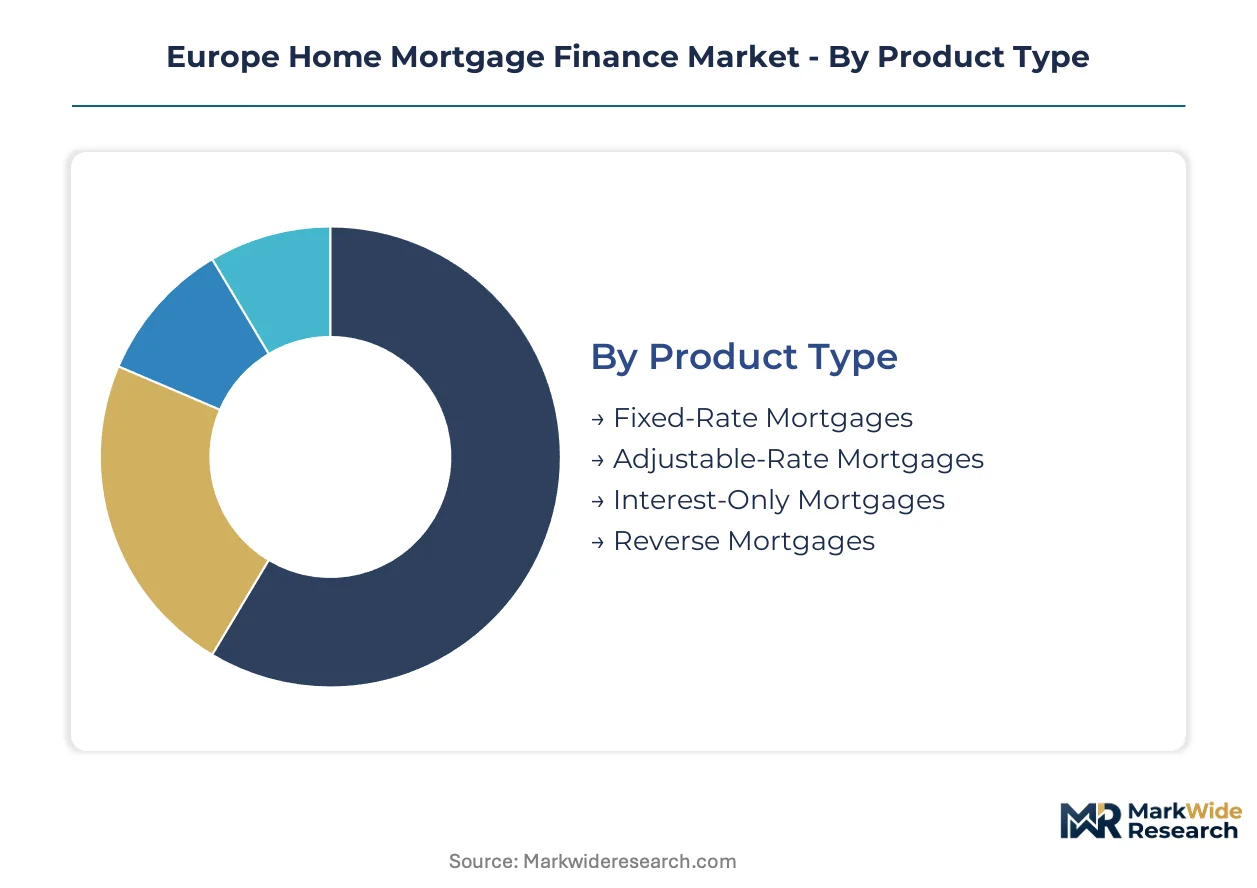
Mortgage product architectures in Europe fragment across borrower lifecycle stages, interest rate preferences, and digital adoption patterns. Lenders configure origination workflows and capital allocation around these segment boundaries to optimize risk-adjusted returns.
Product Type:
Fixed-rate instruments lock in spreads for decades while adjustable products reprice within months, creating divergent balance sheet velocity and hedging demands across lender portfolios.
- Fixed-Rate Mortgages:Borrowers lock nominal rates for 10-30 year tenors, transferring interest risk to lenders who hedge through covered bond issuance. German and French households concentrate demand here, prioritizing payment certainty over rate optimization.
- Adjustable-Rate Mortgages:Spreads reset against EURIBOR successors or national reference rates at predefined intervals. Spanish and Italian originations favor these for lower initial carrying costs, though ECB policy volatility now compresses their share.
- Interest-Only Mortgages:High-net-worth borrowers in Benelux and UK markets deploy these for leverage optimization without amortization schedules.
- Reverse Mortgages:Elderly homeowners in Italy and Portugal convert unencumbered equity into income streams without displacement.
Fixed-rate mortgages dominate installed base across Northern Europe. Adjustable-rate products are where expansion concentrates in Southern European first-time buyer segments.
Client Type:
Acquisition costs and lifetime value profiles diverge sharply across borrower cohorts, with digital-native first-time buyers costing less to onboard but carrying thinner equity cushions.
- First-Time Buyers:Southern European digital platforms reduce documentation friction for this cohort, expanding addressable pools in Spain and Italy where rental-to-own conversion accelerates.
- Refinancers:Rate-sensitive borrowers in Germany and Netherlands trigger origination spikes when spreads compress 50+ basis points below existing notes.
- Investors:Leverage-seeking landlords in UK and Ireland prioritize interest-only structures and rapid underwriting for portfolio expansion.
- Homeowners:Existing borrowers in France and Belgium tap equity for energy renovations aligned with EU Green Deal incentives.
Homeowners dominate installed base through legacy amortizing portfolios. First-time buyers are where expansion concentrates as digital onboarding penetrates underbanked Southern European cohorts.
Loan Term:
Duration decisions reflect household cash flow horizons and lender asset-liability matching constraints, with longer tenors concentrating in high-certainty employment markets.
- Short-Term:5-10 year maturities appeal to high-income professionals in Switzerland and Luxembourg seeking rapid equity accumulation.
- Medium-Term:15-20 year schedules balance affordability with total interest burden for dual-income households in Austria and Denmark.
- Long-Term:25-30 year amortizations sustain purchasing power in Germany's supply-constrained metropolitan clusters.
- Flexible Term:Payment holidays and recasting options attract gig economy participants in Netherlands and Sweden.
Long-term mortgages dominate installed base in Northern European price-elevated markets. Flexible term structures are where expansion concentrates as non-standard employment spreads.
Service Type:
Channel economics reshape competitive positioning, with automated platforms capturing margin from branch-heavy incumbents while hybrid models retain advisory-dependent segments.
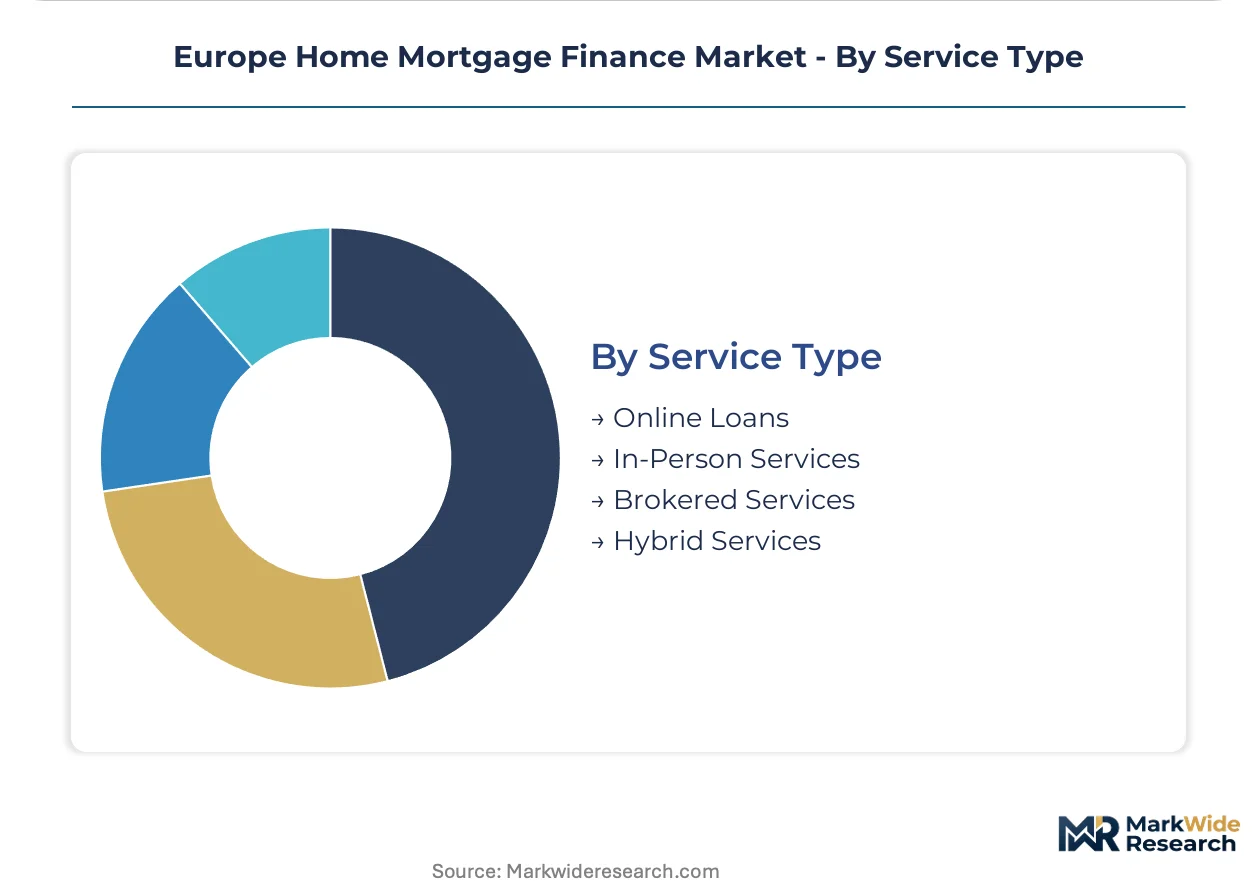
- Online Loans:Automated valuation models and API-based income verification compress German and UK time-to-offer metrics from weeks to hours.
- In-Person Services:Relationship-driven advisory persists in Italy and Greece where borrowers demand face-to-face rate negotiation.
- Brokered Services:Independent intermediaries aggregate offers across Spanish and Portuguese lender panels, capturing commission on complexity.
- Hybrid Services:Digital pre-qualification with human closing support dominates French and Belgian originations.
In-person services dominate installed base among older cohorts in Southern Europe. Online loans are where expansion concentrates as automated underwriting platforms scale across Northern European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households favor fixed-rate tenors exceeding 20 years, while Spanish and Italian borrowers increasingly select adjustable-rate products for lower initial carrying costs. This consumption-mix differential reflects Northern Europe's payment-certainty culture against Southern Europe's rate-flexibility traditions.
Germany
Housing supply constraints in Berlin, Munich, and Hamburg sustain elevated origination volumes as rental-to-own conversion accelerates. The EU Mortgage Credit Directive mandates affordability stress-testing that compresses high-LTV lending. Frankfurt's banking cluster anchors covered bond issuance for fixed-rate portfolio hedging.
United Kingdom
Refinancing waves trigger origination spikes when spreads compress 50 basis points below existing notes. The Financial Conduct Authority enforces strict interest-only lending criteria post-2014 regulatory overhaul. London's fintech corridor concentrates automated valuation model deployment for digital-first lenders.
France
Green mortgage products tied to energy performance certificates capture ESG-mandated institutional capital. The EU Green Deal's building renovation targets create dedicated origination pipelines for efficiency-linked instruments. Paris-Ile-de-France dominates green securitization structuring for covered bond markets.
Spain
First-time buyer segments expand through digital onboarding platforms that reduce documentation friction. The Bank of Spain enforces countercyclical capital buffers that constrain balance sheet capacity during credit upswings. Barcelona and Madrid metropolitan clusters concentrate proptech-enabled origination workflows.
Netherlands
Interest-only mortgage stock among high-net-worth investors sustains niche demand for leverage optimization without amortization. The Dutch Central Bank monitors systemic risk from elevated household debt-to-income ratios. Amsterdam's financial district anchors API-based income verification pilots integrating tax authority data streams.
Europe Home Mortgage Finance Market Competitive Landscape
Capability concentration sits with pan-European universal banks possessing covered bond market access; scale advantage sits with national champions leveraging branch density for relationship-driven origination. The market structures around three tiers: integrated universal banks, specialized mortgage lenders, and digital-native direct-to-consumer platforms. Dominant competitive moves include green product portfolio diversification and automated underwriting technology licensing.
Among Germany-based institutions, Deutsche Bank AG and Aareal Bank exemplify divergent archetypes within the sector. Deutsche Bank occupies a position representing pan-European distribution scale across retail and commercial property segments. Aareal Bank sits within the specialized commercial real estate lending tier. France-based Crédit Agricole and BNP Paribas anchor the universal banking segment, with the latter exemplifying green mortgage product specialization. United Kingdom-based Lloyds Banking Group and Barclays plc represent the digital origination speed competitive vector.
| Leading Market Players |
|---|
| Crédit Agricole |
| Deutsche Bank AG |
| Lloyds Banking Group |
| Rocket Mortgage |
| Aareal Bank |
| Banco Santander |
| Barclays plc |
| Erste Group |
| BNP Paribas |
| Others |
Supply & Pricing Matrix
Overcapacity in Southern European digital origination channels is compressing vendor margins while forcing lenders toward automated platform investments that reshape both cost structures and pricing postures across the value chain.
Pricing Analysis
Long-term offtake contracts dominate institutional covered bond placements, while retail originations price through spot-adjusted spreads against EURIBOR successors. Price differentiation rests on energy performance certification tiers and loan-to-value ratios, with green mortgage products commanding tighter spreads. Cost compression in high-LTV segments is intensifying because European Banking Authority capital charges elevate risk-weighted asset costs. First-time buyers in Southern Europe exhibit highest price sensitivity, while high-net-worth investors in Benelux markets prioritize leverage optimization over rate minimization.
Supply Chain Analysis
Export-control regimes on financial data processing technologies limit flows of automated underwriting algorithms from US and UK vendors into EU institutions, fragmenting technology sourcing. Origination technology supply concentrates in Ireland, Estonia, and Germany. Raw material dependencies include cloud compute infrastructure, API middleware, and satellite imagery feeds. Single-source vulnerability sits with proprietary automated valuation model providers. Distribution runs through branch networks for relationship-driven segments and direct-to-consumer platforms for digital-native cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as ECB policy rate stabilization restores refinancing velocity and borrower confidence across rate-sensitive segments.
For Market Incumbents: Pre-empt margin erosion by accelerating backward integration into proprietary automated valuation model development rather than licensing third-party platforms. Consolidate market position through targeted acquisition of Portuguese and Greek digital origination specialists before first-mover advantages solidify. Channel control through exclusive broker relationships remains the priority lever against direct-to-consumer entrants.
For New Entrants and Emerging Players: Pursue underpenetrated secondary cities in Portugal where automated valuation model deployment lags metropolitan benchmarks. White-space exists in API-based income verification integrating tax authority data streams, particularly in Netherlands and Sweden. Go-to-market positioning should emphasize hybrid service models combining digital pre-qualification with localized closing support.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among lenders with covered bond market access and fixed-rate portfolio dominance. Long-term viability favors institutions with green mortgage product architectures already integrated into origination systems. Acquisition targets should display energy performance certificate data integration capabilities. The signal to watch is ECB policy rate trajectory as inflection indicator for refinancing volume recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Mortgage Product Portfolio Expansion | Captures EU Green Deal energy-efficiency lending incentives and ESG-mandated institutional capital flows. |
| Automated Valuation Model Deployment | Compresses German and UK time-to-offer metrics from weeks to hours against branch-heavy incumbents. |
| Covered Bond Market Integration | Enables fixed-rate portfolio hedging for French and Dutch lenders facing CSRD disclosure deadlines. |
| API-Based Income Verification | Integrates open banking with tax authority data streams for real-time borrower qualification in Amsterdam pilots. |
| Digital Onboarding Platform Scaling | Expands addressable first-time buyer pools across underbanked Southern European cohorts in Spain and Italy. |
Research Methodology
The analysis maps fixed-rate, adjustable-rate, interest-only, and reverse mortgage sub-sectors, each validated through chief lending officers, digital transformation heads, covered bond structurers, and regulatory compliance leads. Primary interviews with these stakeholders combined with secondary validation from European Banking Authority guidance documents, ECB statistical releases, EU Mortgage Credit Directive implementation reports, and national central bank lending surveys. Bottom-up origination volume triangulation against top-down macroeconomic scenario modeling ensures consistency.
Assumption sets held ECB policy rate paths and housing supply elasticity fixed while varying energy efficiency renovation uptake and digital adoption curves across the projection horizon. Segmentation dimensions modeled include product type, client lifecycle stage, loan duration, and service channel preference. CAGRs derived from cohort-specific origination growth rates applied to risk-adjusted balance sheet capacity constraints. Industry-specific inputs incorporated EU Green Deal building renovation targets and EURIBOR transition timelines.
Macroeconomic conditions sit as an overlay; deviation in ECB policy rates, unemployment spikes, or housing supply shocks would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timing and technology adoption curves. Material shifts in EU Green Deal incentive structures or alternative risk-free rate transition mechanics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
UK Factoring Services Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
France Auto Loan Market
Loans and Leasing
Micro Lending Market