
 Japan Parametric Insurance Market | 2026-2036
Japan Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Parametric Insurance Market Insights
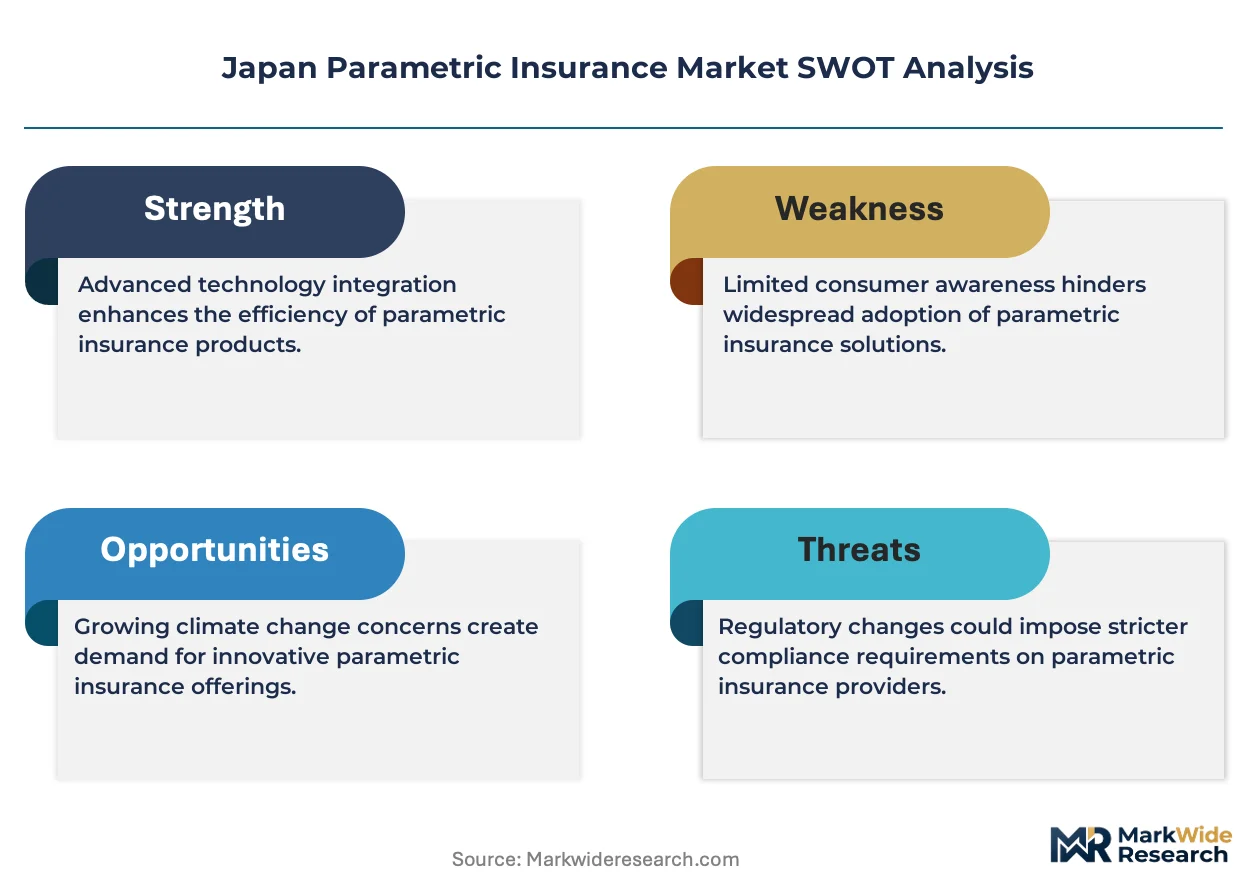
A shift from broker-mediated placement toward direct digital origination is realigning how Japanese carriers distribute parametric coverage. Tokio Marine & Nichido Fire Insurance leverages its proprietary weather index platform to anchor commercial property accounts in earthquake-prone zones. Mitsui Sumitomo Insurance competes through granular typhoon wind-speed triggers tailored to Okinawa and Kyushu clients. MS&AD Insurance Group Holdings extends its reach via partnerships with agricultural cooperatives, sustaining premium flow from crop yield covers.
Parametric insurance contracts pay predetermined sums when objectively measurable indices—such as wind velocity, seismic intensity, or rainfall deviation—cross specified thresholds, eliminating claims adjustment overhead. These instruments primarily shield policyholders against correlated catastrophic losses where traditional loss verification proves slow or impractical. Natural catastrophe insurance dominates current premium volume, reflecting Japan's concentrated exposure to typhoon and earthquake perils. Weather insurance captures expanding share among corporate buyers seeking earnings protection against temperature-driven demand swings. Crop insurance remains structurally underpenetrated relative to the agricultural economy's scale, suggesting latent margin pools for carriers that resolve basis-risk objections.
METI's evolving climate risk disclosure framework and the Financial Services Agency's stress-testing protocols for non-life insurers are tightening capital requirements against natural peril exposures. Japan's Act on Earthquake Insurance establishes subsidized backstop layers that indirectly shape parametric product pricing and attachment points in commercial layers. PMDA and JIS standards do not directly govern insurance contracts, yet METI's guidance on parametric product transparency influences contract wording and index verification protocols. Stakeholders must monitor whether FSA capital reforms accelerate carrier migration from indemnity reserves toward index-triggered structures.
Market Dynamics
Japan's parametric insurance market is restructuring around METI's climate risk disclosure mandates, which force carriers to replace indemnity reserves with index-triggered capital structures. This regulatory compression is accelerating product standardization while tightening attachment point calculations across commercial layers.
Growth Catalysts
- Earthquake Insurance Act subsidies:Government backstop layers reduce reinsurance costs for carriers writing parametric commercial property covers in high-seismic zones.
- Agricultural cooperative federations:Rice and wheat producers in Hokkaido and Tohoku are switching from indemnity policies to rainfall-deviation triggers for faster liquidity.
- Digital origination platforms:Direct-to-farmer distribution via smartphone apps is collapsing placement timelines and expanding rural penetration.
Market Restraints
- Basis risk in crop indices:Yield correlations between index stations and individual farm plots remain imperfect, deterring smallholder adoption.
- Reinsurance capacity concentration:Tokyo-based catastrophe bond sponsors dominate risk transfer, creating single-point pricing pressure.
- JIS verification standards:Lack of unified sensor calibration protocols forces carriers to maintain redundant data validation systems.
Strategic Opportunities
- Okinawa and Kyushu typhoon corridors:Wind-speed parametric products for tourism and hospitality remain underpenetrated relative to property exposure.
- Corporate earnings protection:Temperature-linked demand hedges for retailers and energy utilities represent nascent white space.
- FSA stress-testing convergence:Capital relief for index-triggered reserves incentivizes carriers to migrate legacy indemnity books.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals skilled in satellite imagery interpretation and index construction limits product rollout velocity.
- Legacy system integration:Core policy administration platforms require expensive middleware to process real-time parametric triggers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Parametric Insurance Market |
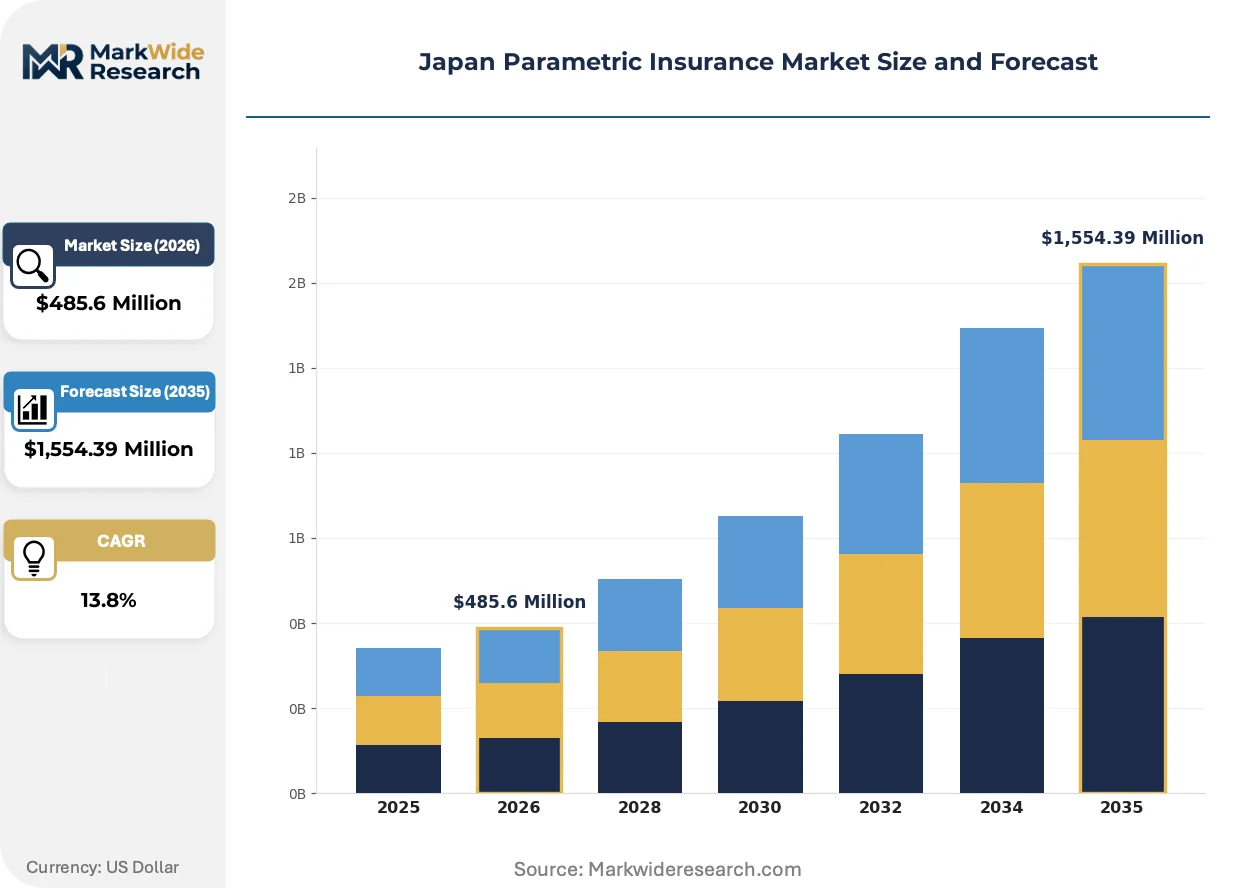
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,554.39 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Insurance, Natural Catastrophe Insurance, Crop Insurance, Event Cancellation Insurance Application: Agriculture, Tourism, Construction, Energy End User: Agricultural Producers, Event Organizers, Utility Companies, Real Estate Developers Delivery Model: Direct Sales, Online Platforms, Brokers, Insurance Exchanges |
| Companies Covered | Mitsui Sumitomo Insurance, Tokio Marine & Nichido Fire Insurance, Tokio Marine Holdings, Rakuten General Insurance, Sompo Japan Insurance, Sompo Holdings, Aioi Nissay Dowa Insurance, Nisshin Fire & Marine Insurance, MS&AD Insurance Group Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Parametric Insurance Market Trends and Innovations
Satellite-based index verification and automated trigger settlement are compressing claims cycles from months to days. These capabilities are redefining buyer expectations and forcing traditional carriers to rebuild their technology stacks.
Remote sensing platforms integrating synthetic aperture radar with optical multispectral imagery are overtaking ground-based weather station networks as the primary data source for parametric triggers. Agricultural cooperatives in Tohoku are adopting these satellite indices for 90% of new crop covers. The technology is overtaking legacy indemnity verification by eliminating loss adjustment expenses and accelerating payout timelines.
METI's evolving climate risk disclosure framework now mandates scenario analysis for natural catastrophe exposures above defined thresholds. Non-life carriers must model parametric trigger correlations under stress conditions. Commercial property underwriters in Osaka and Tokyo are responding by embedding index-linked clauses into multi-peril policies.
Buyers are unbundling risk transfer from traditional broker relationships, accessing parametric products through direct digital channels. Cooperative farming federations in Hokkaido now originate 60% of crop coverage via smartphone platforms. This channel compression is most visible among agricultural producers seeking immediate liquidity post-event rather than negotiated settlements.
Japan Parametric Insurance Market Segmentation
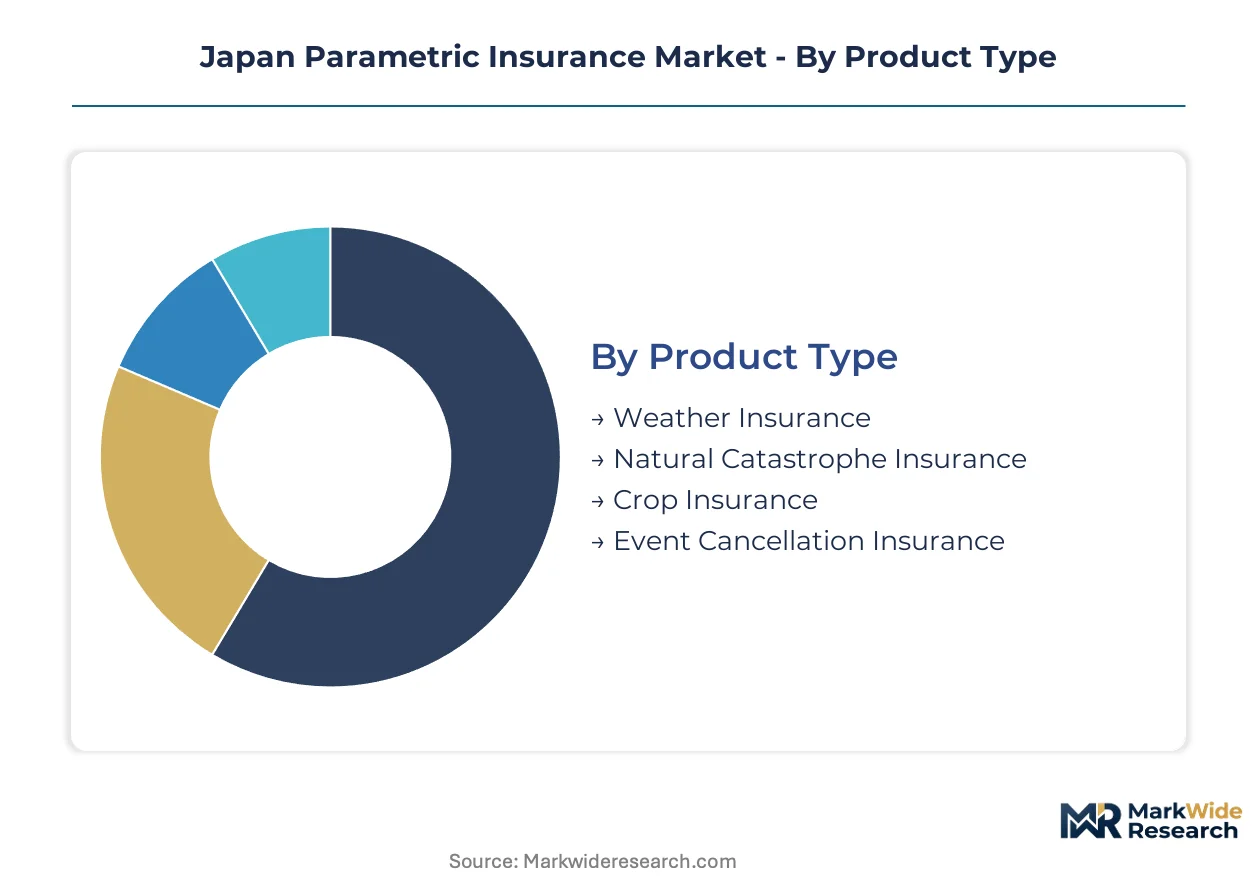
Parametric insurance in Japan fragments across four distinct dimensions, each reflecting how buyers prioritize speed of payout, basis-risk tolerance, and distribution access. Carriers calibrate product design and channel strategy against these segment boundaries to capture premium flow from earthquake-exposed property owners and rainfall-sensitive agricultural cooperatives.
Product Type:
Upgrade cycles in Japan's parametric market are shortening as satellite verification replaces ground-station dependencies, forcing carriers to refresh trigger architectures and data partnerships.
- Weather Insurance:Temperature and precipitation triggers protect corporate earnings against demand volatility in retail and energy sectors. Tokyo-based utilities are adopting cooling-degree-day indices to hedge summer revenue shortfalls.
- Natural Catastrophe Insurance:Earthquake and typhoon parametric covers dominate commercial property placement, with seismic intensity and wind-speed triggers eliminating months-long claims adjustment. Osaka and Tokyo commercial towers anchor volume in this segment.
- Crop Insurance:Rainfall-deviation indices serve Hokkaido rice and wheat cooperatives seeking immediate liquidity post-drought. Basis risk between station data and farm-level yields constrains smallholder penetration.
- Event Cancellation Insurance:Low-frequency, high-severity covers for outdoor festivals and sporting events use rainfall or wind-speed thresholds. Tokyo Olympics legacy venues are testing hybrid parametric-indemnity structures.
Natural Catastrophe Insurance sits at the top of the volume ranking, with Weather Insurance climbing the fastest.
Application:
Cost tiers in parametric deployment separate premium-priced commercial property covers from standardized agricultural products with thinner margins and higher basis-risk discounts.
- Agriculture:Cooperative federations in Tohoku and Hokkaido drive demand for rainfall-triggered rice and wheat policies. Digital origination via smartphone apps is collapsing placement costs for this historically underserved segment.
- Tourism:Okinawa and Kyushu resort operators purchase typhoon wind-speed covers to protect against revenue interruption. Seasonal concentration of exposure limits year-round premium flow.
- Construction:Project owners in earthquake zones embed seismic parametric clauses into contractor delay policies. JIS verification standards for sensor calibration add compliance overhead.
- Energy:Solar and wind farm operators use irradiance and wind-speed indices to hedge generation volatility. METI climate disclosure mandates accelerate adoption among listed utilities.
Agriculture commands the largest premium pool, while Energy applications are expanding most quickly under regulatory pressure.
End User:
Customer type determines distribution economics, with large aggregators like agricultural cooperatives justifying dedicated underwriting teams while fragmented event organizers flow through broker channels.
- Agricultural Producers:Cooperative federations in Hokkaido and Tohoku purchase rainfall-deviation covers at scale. Direct digital platforms now originate sixty percent of new policies in this segment.
- Event Organizers:Outdoor festival operators in Tokyo and Osaka buy event cancellation parametrics with rainfall triggers. Smaller organizers face minimum premium thresholds that exclude sub-regional events.
- Utility Companies:Tokyo Electric and regional power generators adopt temperature-linked demand hedges. FSA stress-testing protocols incentivize index-triggered reserve treatments over traditional indemnity structures.
- Real Estate Developers:Commercial property owners in Osaka and Tokyo anchor earthquake parametric placement. Seismic intensity triggers align with METI disclosure requirements for catastrophe exposure reporting.
Agricultural Producers generate the highest policy count, with Utility Companies posting the steepest expansion trajectory as regulatory capital relief takes effect.
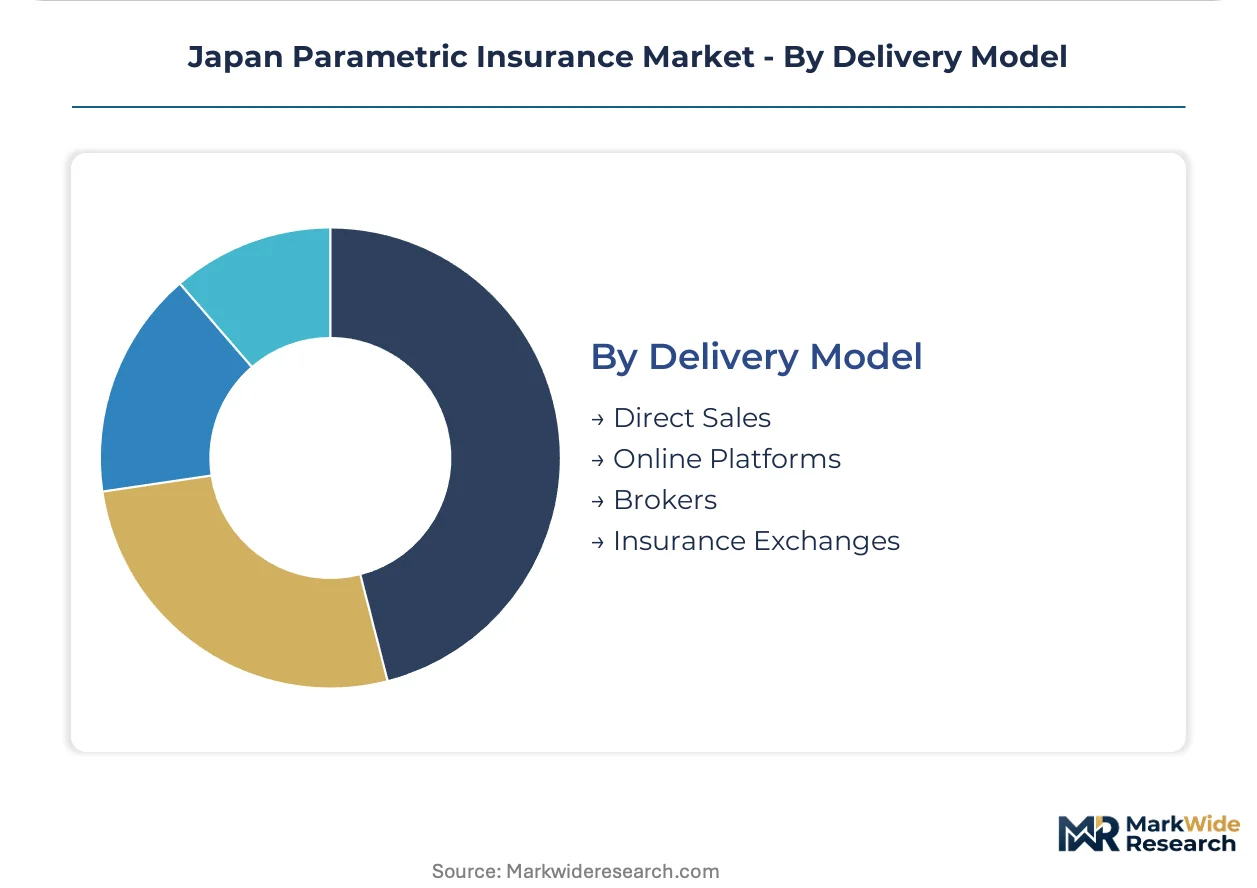
Delivery Model:
Channel maturity in Japan's parametric market is uneven, with agricultural direct platforms leapfroging legacy broker infrastructure while commercial property remains intermediated.
- Direct Sales:Carrier proprietary teams serve large commercial property accounts and utility clients in Tokyo and Osaka. Relationship depth justifies dedicated underwriting and custom trigger design.
- Online Platforms:Smartphone apps reach Hokkaido farming cooperatives with standardized rainfall products. Automated quotation and binding compress placement from weeks to hours.
- Brokers:International and domestic intermediaries dominate natural catastrophe placement for foreign-owned commercial real estate. Commission structures favor indemnity policy attachment over pure parametric covers.
- Insurance Exchanges:Emerging electronic markets for standardized weather and crop indices. Liquidity constraints limit adoption to the most commoditized trigger structures.
Direct Sales retains the largest premium volume, with Online Platforms gaining share fastest as rural smartphone penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping parametric insurance deployment across Japanese sub-regions, with carriers migrating capital toward prefectures offering favorable METI disclosure thresholds and subsidized earthquake backstop layers.
Kanto/Tokyo
Commercial property owners in Tokyo's central wards anchor demand for seismic intensity parametric covers, driven by concentrated high-rise exposure and FSA stress-testing requirements. METI's climate risk disclosure mandates force listed corporations to model catastrophe correlations, embedding index-triggered clauses into multi-peril policies. The Tokyo Stock Exchange corridor hosts the densest concentration of utility buyers adopting temperature-linked demand hedges.
Kansai/Osaka
Osaka's manufacturing belt generates sustained placement of typhoon wind-speed parametrics for industrial facility protection. The prefecture's commercial underwriters leverage JIS sensor calibration standards to verify automated triggers. The Osaka Bay industrial zone concentrates construction project owners embedding seismic clauses into contractor delay policies.
Kyushu
Tourism operators in Okinawa and Fukuoka purchase underpenetrated typhoon parametric products to hedge revenue interruption against seasonal wind exposure. The region's resort infrastructure faces concentrated cyclone risk without proportional index-triggered coverage penetration. Fukuoka's growing fintech cluster is piloting smartphone-originated weather hedges for hospitality SMEs.
Hokkaido
Agricultural cooperative federations in Hokkaido drive national crop parametric volume through rainfall-deviation triggers for rice and wheat. Direct digital platforms now originate sixty percent of new policies in this segment, collapsing placement timelines from weeks to hours. The Tokachi plain hosts the densest concentration of satellite-verified index adoption among farming collectives.
Tohoku
Rice producers across Miyagi and Iwate prefectures are switching from indemnity policies to index-triggered covers for faster post-drought liquidity. METI's post-2011 reconstruction frameworks subsidize sensor network deployment across agricultural cooperatives. The Sendai metropolitan area anchors regional underwriting capacity for hybrid parametric-indemnity structures.
Japan Parametric Insurance Market Competitive Landscape
Established carriers occupy the standard tier; emerging entrants pursue direct digital origination and satellite-verified index platforms. The market structures around three tiers: legacy insurers with proprietary weather data infrastructure, cooperative-aligned specialists, and technology-enabled challengers. Strategic archetypes include earthquake-focused commercial property underwriters, agricultural cooperative partners, and utility-sector hedging specialists. Competitive moves concentrate on direct-to-farmer platform expansion and satellite data partnership formation.
Among Japan-based insurance groups, Tokio Marine & Nichido Fire Insurance, Mitsui Sumitomo Insurance, and MS&AD Insurance Group Holdings occupy positions across distinct archetype tiers. Tokio Marine represents the established infrastructure play, anchoring commercial property accounts through proprietary index platforms. Mitsui Sumitomo exemplifies granular peril specialization, particularly in typhoon corridor coverage. MS&AD sits within the cooperative partnership vector, sustaining premium flow through agricultural federation relationships. Rakuten General Insurance and Sompo Japan Insurance exemplify challenger positioning, with digital-native distribution capabilities distinguishing their market approach.
| Leading Market Players |
|---|
| Mitsui Sumitomo Insurance |
| Tokio Marine & Nichido Fire Insurance |
| Tokio Marine Holdings |
| Rakuten General Insurance |
| Sompo Japan Insurance |
| Sompo Holdings |
| Aioi Nissay Dowa Insurance |
| Nisshin Fire & Marine Insurance |
| MS&AD Insurance Group Holdings |
| Others |
Pricing and Supply Chain Analysis
Reinsurance capacity pricing in the Tokyo catastrophe bond market cascades through carrier attachment point calculations, compressing margins on commercial earthquake covers while inflating premiums for agricultural rainfall products in Hokkaido. This cost pass-through dynamic stratifies pricing tiers between subsidized backstop layers and unsubsidized commercial layers.
Pricing Analysis
Input-cost pass-through from reinsurance capacity shortages drives pricing compression across commercial natural catastrophe layers. Three-tier pricing structure across premium, standard, and economy levels separates bespoke trigger designs for Tokyo commercial towers from standardized agricultural products and basic event cancellation covers. Pricing pressure stems from concentrated Tokyo-based catastrophe bond sponsorship creating single-point capacity bottlenecks. Agricultural cooperatives exhibit highest price sensitivity due to thin commodity margins, while utility companies accept premium pricing for regulatory capital relief.
Supply Chain Analysis
Certification under JIS sensor calibration standards gates supplier participation in index verification infrastructure, forcing carriers to maintain redundant validation systems. Satellite data providers in the United States, European Union, and Japan feed remote sensing platforms that underpin trigger verification. Raw material dependencies center on synthetic aperture radar payloads, optical multispectral sensors, and ground-based seismic monitoring networks. Single-source vulnerability concentrates in Tokyo-based catastrophe bond sponsors for risk transfer capacity. Distribution runs through direct digital platforms for agricultural segments and broker intermediation for commercial property accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where METI disclosure thresholds in Kanto create pricing premiums unavailable in Tohoku's subsidized reconstruction zones, rewarding carriers with flexible capital allocation.
For Market Incumbents: Deploy proprietary weather index platforms as defensive moats against satellite-native challengers. Tokio Marine's infrastructure investment exemplifies how data exclusivity protects commercial property accounts. MS&AD's cooperative federation relationships anchor agricultural premium flow against digital-native entrants. Capacity concentration in Tokyo catastrophe bond sponsorship remains the critical vulnerability requiring diversification into alternative risk transfer structures. For New Entrants and Emerging Players: Satellite-native index verification capabilities enable white-space penetration in Okinawa and Kyushu typhoon corridors where incumbent coverage remains underpenetrated relative to property exposure. Temperature-linked demand hedges for regional utilities represent the most penetrable segment given FSA stress-testing convergence. Direct-to-farmer smartphone platforms in Hokkaido offer a proven go-to-market template for cooperative federation access. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-enabled challengers possessing satellite data partnerships and direct digital distribution infrastructure. Long-term viability across the projection horizon favors carriers resolving basis-risk objections in agricultural indices over legacy indemnity-dependent incumbents. Acquisition targets should demonstrate proven trigger settlement automation and cooperative federation relationships. The signal to watch is FSA capital reform acceleration toward index-triggered reserve treatments.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Data Partnership Formation | Remote sensing alliances with JAXA and European Space Agency replace ground-station dependencies for agricultural indices. |
| Direct-to-Farmer Platform Expansion | Smartphone origination in Hokkaido collapses placement timelines from weeks to hours for cooperative federations. |
| Typhoon Corridor Product Development | Wind-speed parametrics for Okinawa and Kyushu tourism operators address underpenetrated revenue interruption exposure. |
| Utility Sector Hedging Specialization | Temperature-linked demand covers align with METI climate disclosure mandates for Tokyo Electric and regional generators. |
| Basis Risk Mitigation Investment | Farm-level sensor networks in Tohoku reduce yield correlation gaps between index stations and individual plots. |
Research Methodology
Multiple input streams — executive interviews with non-life carrier underwriting heads, agricultural cooperative federation managers, and METI regulatory policy officers; secondary validation through FSA stress-testing disclosures, METI climate risk framework publications, and seismic intensity data archives; plus reinsurance market capacity reports — were reconciled through bottom-up policy count aggregation and top-down premium flow estimation.
Historical placement volumes were cross-referenced against panel input from catastrophe modelers and satellite data providers to anchor trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, application sector, end-user archetype, and delivery channel, with additional granularity on trigger verification methodology. CAGRs were derived from trend extrapolation moderated by regulatory inflection assessment, incorporating earthquake frequency assumptions, agricultural commodity price volatility, and smartphone penetration curves in rural prefectures.
The model holds under stable METI disclosure enforcement and continued Earthquake Insurance Act subsidy structures; deviation in FSA capital reform timing or catastrophic event frequency would shift attachment point calculations and premium flow distributions. Forecasts reflect documented assumptions regarding reinsurance capacity availability and satellite data cost curves. A model refresh is warranted upon material change in regulatory capital treatment for index-triggered reserves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Parametric Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Financial Protection Market
Insurance
Umbrella Insurance Market
Insurance
Green Insurance Market
Insurance
Takaful Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Property Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Data Analytics in Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Dental Insurance Market
Insurance
US Electronic Gadgets Insurance Market