
 Europe Mobile Phone Insurance Market | 2026-2036
Europe Mobile Phone Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Phone Insurance Market Analytics
European mobile operators is decoupling device insurance from traditional handset subsidies, creating standalone policy ecosystems that require new underwriting infrastructure. Allianz SE leverages its pan-European property and casualty network to anchor multi-country distribution partnerships with retail chains. AXA competes through digital-first claims platforms that reduce loss-adjustment cycles for cracked-screen incidents. Assurant, Inc. specializes in embedded insurance APIs that integrate directly into mobile operator billing systems.
Mobile phone insurance constitutes a financial risk-transfer instrument covering repair, replacement, or indemnity for portable cellular devices against physical damage, theft, electronic failure, or loss, with policies typically specifying deductible tiers, coverage caps, and claims frequency limits. Its primary commercial purpose is to reduce total cost of ownership volatility for consumers and enterprise fleets while generating recurring premium revenue for underwriters and distribution commissions for channel partners. Accidental Damage coverage commands the largest premium pool due to high-frequency screen and liquid damage claims, while Malfunction Coverage carries thinner margins as manufacturer warranty periods expand. Mobile Operators dominate distribution channel economics through point-of-sale attachment at device activation, though Online Retail is capturing faster growth among SIM-only customers seeking post-purchase coverage flexibility.
GDPR imposes strict data-handling requirements on insurers processing geolocation and device telemetry for fraud detection, while the EU Digital Services Act subjects platform-distributed policies to enhanced transparency obligations. EIOPA guidelines on product oversight and governance shape solvency reserving and policy wording standardization across member states. Stakeholders must monitor divergence between national implementations of the Insurance Distribution Directive as regulators in Italy, Spain, and the Netherlands test stricter conduct standards for embedded sales practices.
Market Dynamics
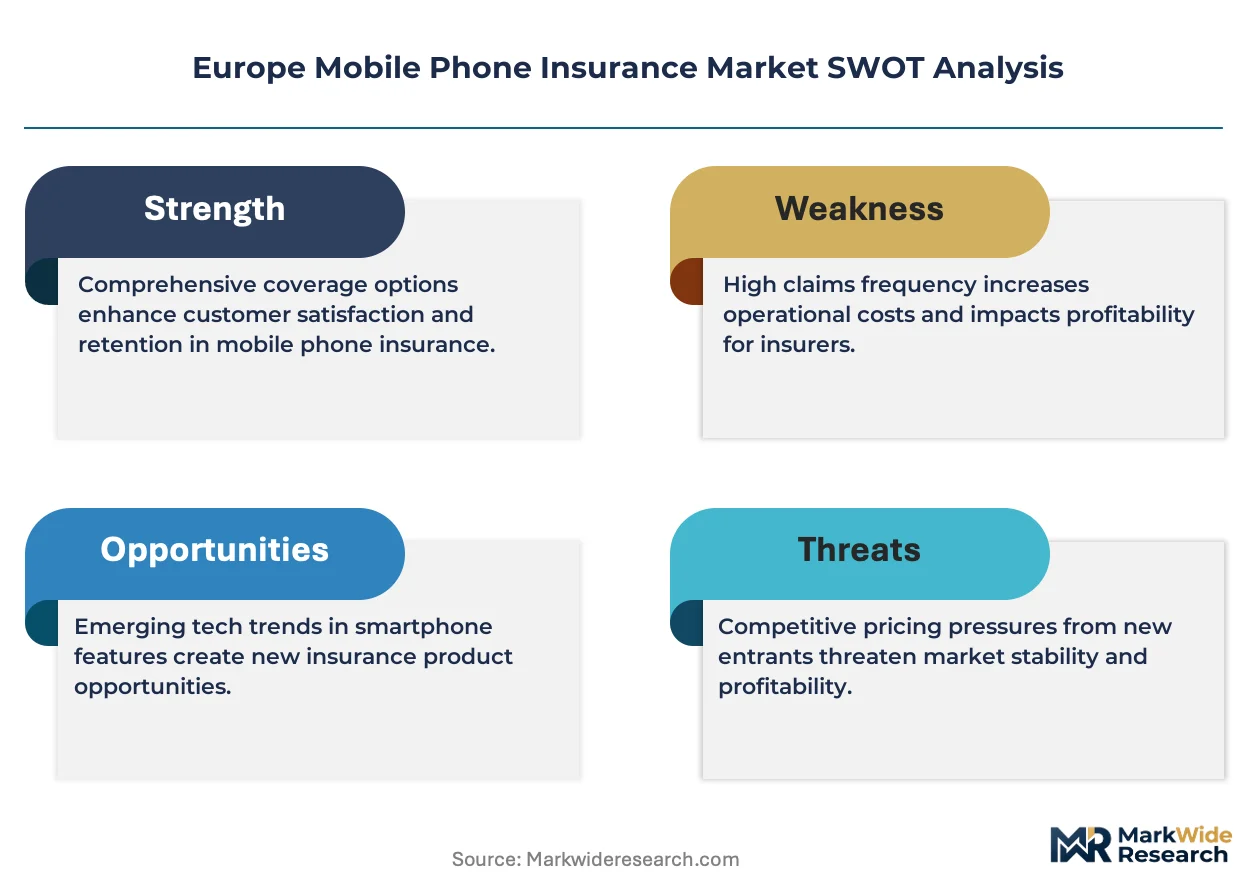
European mobile operators are dismantling bundled handset subsidies, forcing insurers to build standalone digital infrastructure for policy origination and claims management without relying on point-of-sale attachment economics.
Growth Catalysts
- GDPR-compliant fraud analytics:Insurers deploying privacy-preserving machine learning for device telemetry analysis are reducing claims leakage while satisfying EU data protection mandates.
- Corporate fleet mandates:German and French enterprises are expanding mandatory coverage for employee smartphones as remote work policies institutionalize device liability.
- Operator billing integration:Embedded insurance APIs that synchronize with mobile operator invoicing systems are lowering customer acquisition costs and improving policy persistency.
Market Restraints
- Extended manufacturer warranties:Apple and Samsung now offer 24-36 month hardware defect coverage, compressing the addressable market for third-party malfunction policies.
- Input cost volatility:Semiconductor and OLED display pricing fluctuations are destabilizing replacement cost reserves and deductible calibration models.
- EIOPA solvency requirements:Pan-European capital adequacy rules are elevating compliance overhead for insurers operating across multiple member states.
Strategic Opportunities
- Spain and Italy penetration gaps:SIM-only subscriber bases in Mediterranean markets remain underserved by post-purchase insurance offerings relative to Northern European benchmarks.
- EU Digital Services Act transparency:Platform-distributed policies must meet enhanced disclosure standards, creating first-mover advantage for compliant digital-native underwriters.
- Telematics-claims convergence:Integration of device health sensors with automated damage assessment APIs is enabling real-time premium adjustment and instant settlement.
Industry Challenges
- Legacy core system integration:Established insurers face technical debt when connecting decades-old policy administration platforms to modern mobile operator billing architectures.
- Cross-border licensing complexity:Divergent national implementations of the Insurance Distribution Directive create operational friction for multi-country distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Phone Insurance Market |
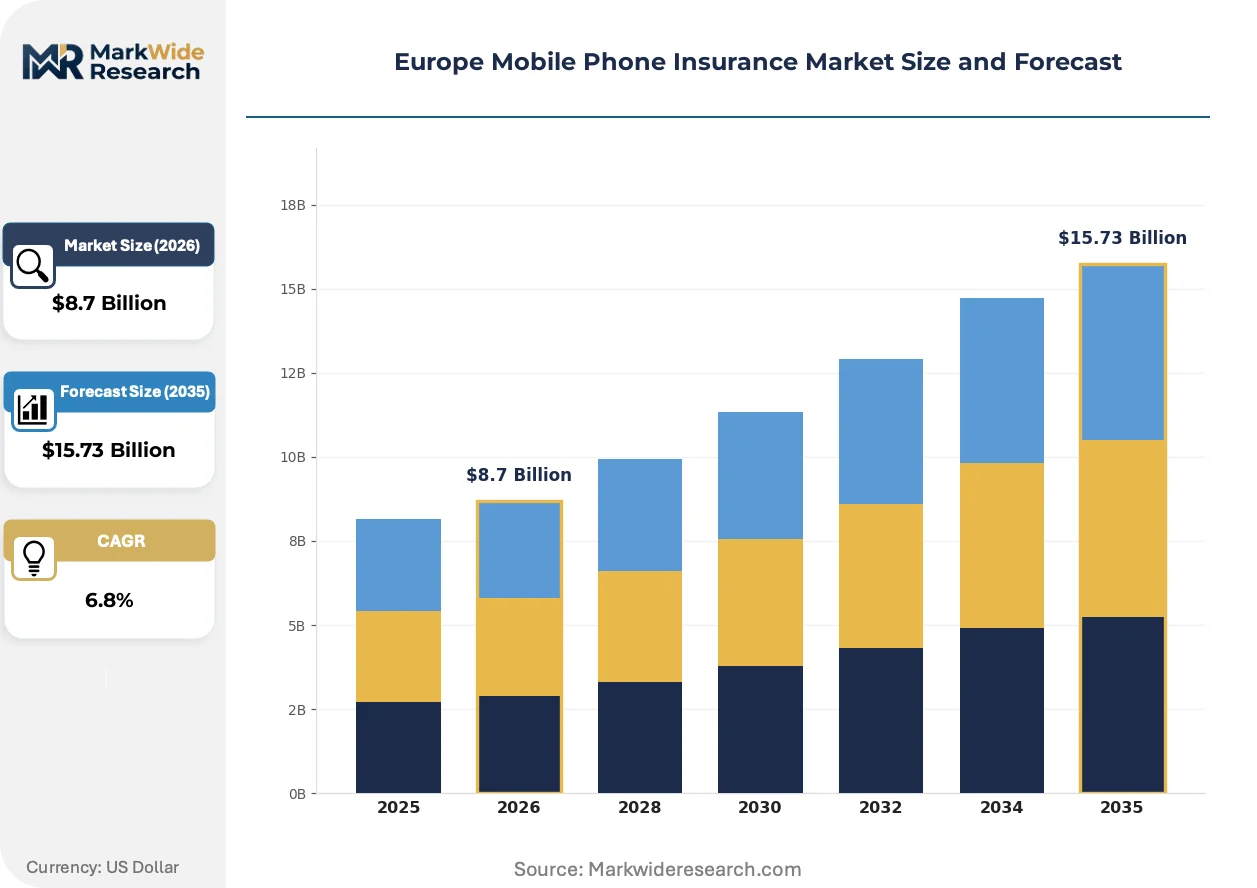
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Accidental Damage, Theft, Extended Warranty, Malfunction Coverage Distribution Channel: Online Retail, Mobile Operators, Insurance Agents, Retail Stores Customer Segment: Individual Users, Corporate Users, Students, Senior Citizens Policy Duration: Monthly, Annually, Two-Year, Multi-Year |
| Companies Covered | Asurion, LLC, American International Group, Inc., Allianz SE, Telefonica UK Limited, Apple Inc., AXA, Assurant, Inc., Better Buy Insurance, Aviva Insurance Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Phone Insurance Market Evolving Landscape
Digital claims automation and embedded distribution architectures are restructuring how European insurers originate policies and settle losses, compressing traditional intermediation layers.
AI-powered computer vision for damage assessment is electrifying the claims workflow. Mobile insurers in France and Germany are deploying automated cracked-screen verification tools that reduce loss-adjustment expenses by eliminating manual inspection requirements. This technology is electrifying cost structures across the value chain, forcing traditional adjusters to reposition toward complex fraud investigations.
GDPR Article 22 restrictions on automated decision-making are tightening claims adjudication protocols. Insurers processing device telemetry for fraud detection must now implement human-in-the-loop review mechanisms for contested determinations. Italian and Dutch regulators are testing stricter conduct standards for these embedded sales practices, requiring explicit consent documentation at point of purchase.
Enterprise procurement of fleet coverage is consolidating through dedicated insurance brokers rather than direct operator channels. German automotive and logistics corporations are negotiating master policies covering thousands of employee devices under single contracts with customized deductible tiers. This shift is most visible in the DACH region, where corporate risk managers prioritize centralized premium management over convenience-driven point-of-sale attachment.
Europe Mobile Phone Insurance Market Segmentation
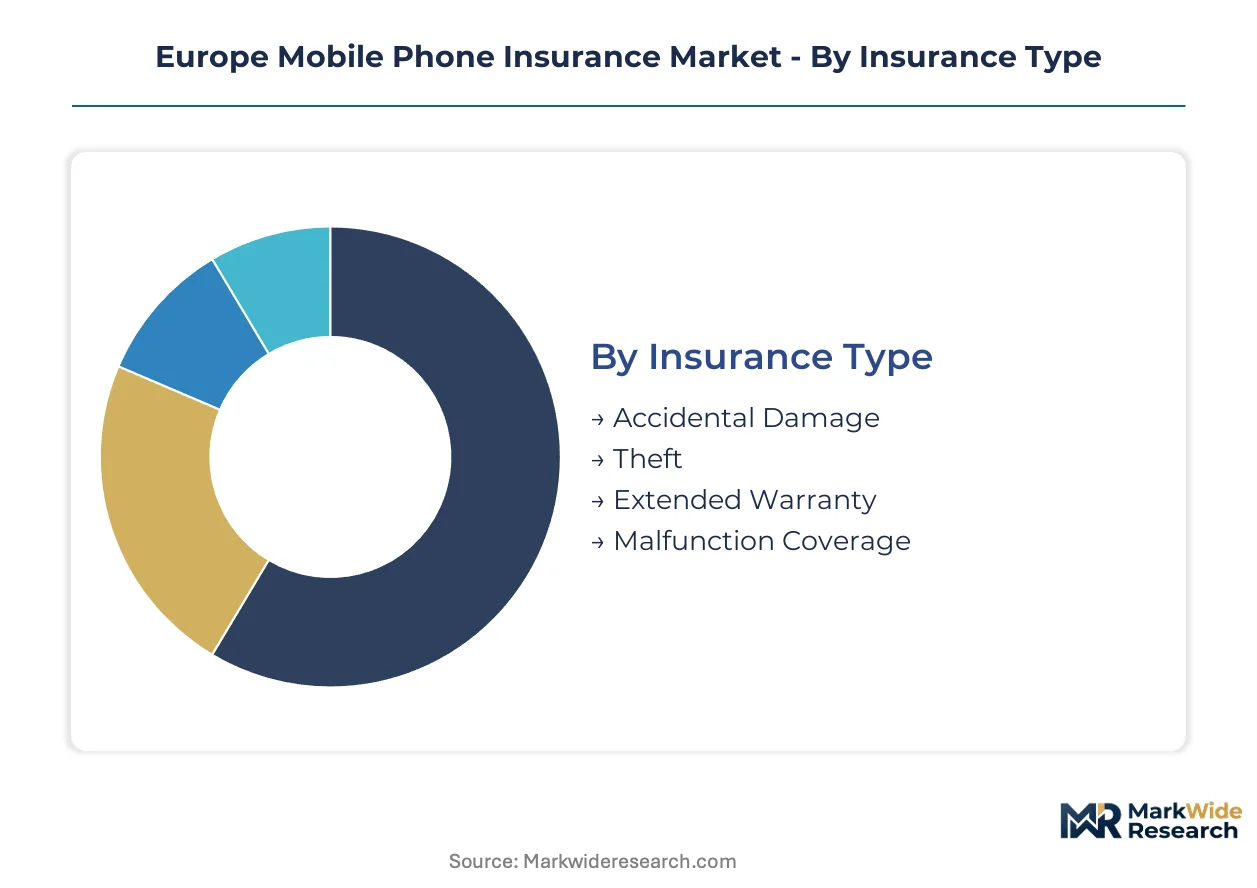
European mobile phone insurance segmentation reveals how underwriting capacity concentrates around high-frequency claims categories while distribution economics fragment across legacy and digital channels. Understanding these divides exposes where capital deployment and customer acquisition strategies diverge.
Insurance Type:
Supply-side actuarial capacity concentrates heavily in damage categories with predictable loss ratios, leaving thinner margins for coverage types competing against manufacturer warranty extensions.
- Accidental Damage:Policies covering screen cracks, liquid ingress, and impact trauma generate the largest premium pool due to high claim frequency. German and UK subscribers drive disproportionate volume as premium smartphone penetration exceeds regional averages and repair costs outpace deductible thresholds.
- Theft:Coverage for device loss through criminal activity carries elevated premiums in urban postal codes with elevated crime indices. French and Belgian metropolitan areas show concentrated demand where street-level device snatching incidents trigger indemnity payouts rather than repair workflows.
- Extended Warranty:Hardware defect coverage beyond manufacturer terms faces margin compression as Apple and Samsung expand standard warranty periods to 24-36 months.
- Malfunction Coverage:Electrical and mechanical failure policies compete directly with OEM guarantee programs, limiting addressable market scope to devices outside standard protection windows.
Today's leader: Accidental Damage. Tomorrow's challenger: Theft coverage in Southern European urban corridors.
Distribution Channel:
Channel economics stratify sharply between embedded point-of-sale attachment and post-purchase digital origination, with divergent customer acquisition cost structures shaping profitability.
- Mobile Operators:Point-of-sale integration at device activation captures the highest attachment rates through billing system embedding. Vodafone and Deutsche Telekom leverage subscriber data for risk scoring, reducing underwriting friction at the moment of hardware purchase.
- Online Retail:Post-purchase digital platforms serve SIM-only subscribers seeking coverage flexibility outside operator ecosystems. Amazon and dedicated insurtech portals gain traction among price-sensitive consumers comparing deductible tiers across multiple underwriters.
- Insurance Agents:Intermediary-driven distribution persists in Mediterranean markets where personal advisory relationships influence purchasing decisions for complex multi-device household policies.
- Retail Stores:Electronics chains and independent mobile shops provide physical consultation for consumers preferring in-person policy explanation before commitment.
Mobile Operators dominate current premium volume. Online Retail platforms are climbing the fastest as SIM-only subscriber bases expand across Northern Europe.
Customer Segment:
Demand concentration patterns reflect divergent risk profiles and purchasing power across demographic and organizational boundaries.
- Individual Users:Single-device consumers purchasing coverage for personal smartphones represent the foundational volume base, with purchasing decisions driven by device replacement cost anxiety and prior claims experience.
- Corporate Users:Enterprise fleet managers negotiate master policies covering thousands of employee devices under centralized procurement frameworks. German automotive and logistics corporations in the DACH region lead this segment through mandatory remote-work device coverage mandates.
- Students:Younger subscribers with limited disposable income gravitate toward lower-premium policies with higher deductibles, creating adverse selection pressures in this demographic tier.
- Senior Citizens:Older users demonstrate lower claims frequency for accidental damage but elevated vulnerability to theft and loss incidents, requiring specialized pricing models.
Individual Users anchor current premium flows. Corporate Users represent the steepest expansion trajectory as enterprise mobility policies institutionalize across the EU.
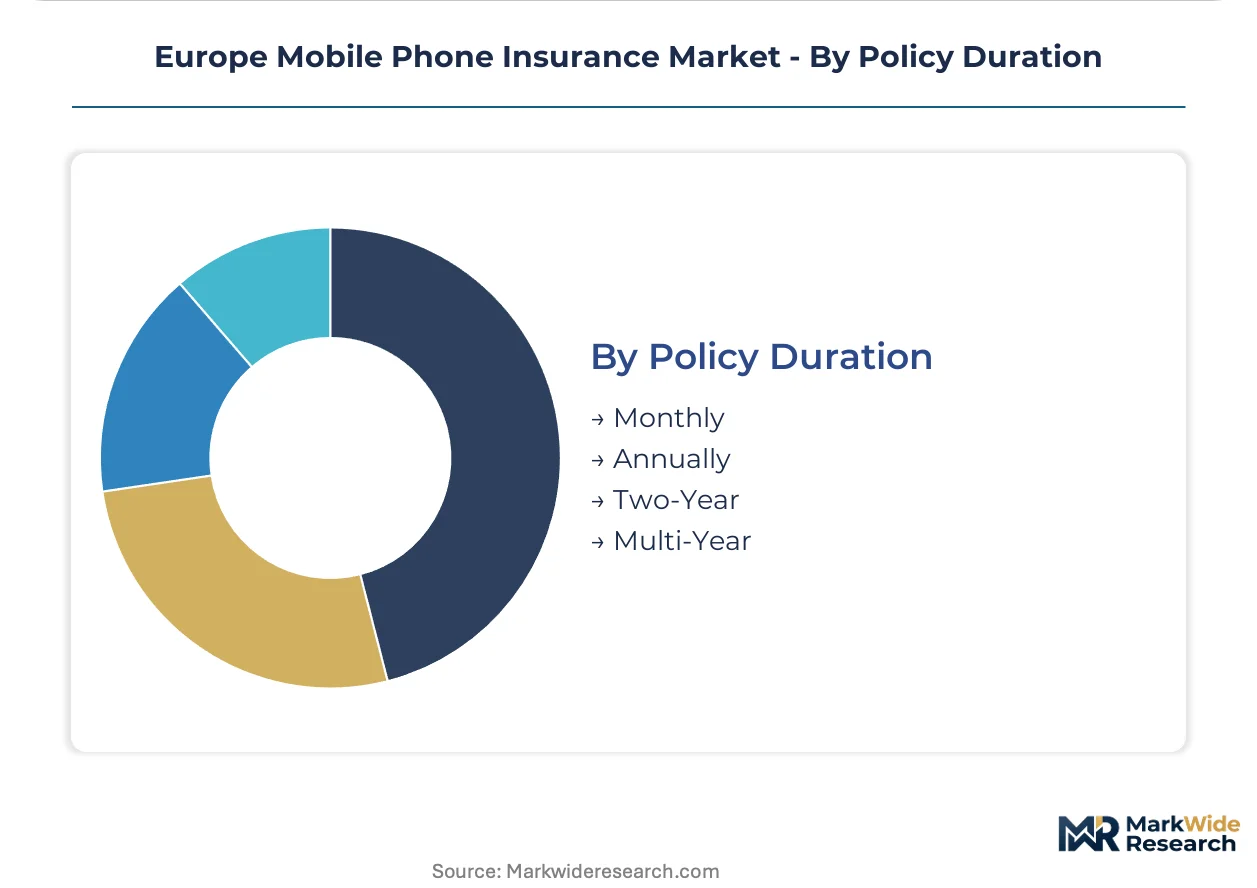
Policy Duration:
Duration selection reveals customer commitment horizons and insurer capital lock-up preferences, with structural implications for persistency and renewal economics.
- Monthly:Rolling coverage with cancellation flexibility attracts subscribers uncertain about long-term device retention or seeking to align payments with salary cycles.
- Annually:Single-year commitments balance premium discounting against moderate lock-in, representing the dominant duration choice across European markets.
- Two-Year:Mid-term policies align with typical handset replacement cycles, reducing administrative overhead for both underwriters and subscribers.
- Multi-Year:Extended duration contracts beyond twenty-four months concentrate in corporate fleet arrangements where device standardization programs run on predictable refresh schedules.
Annually-billed policies command today's volume leadership. Monthly subscriptions are gaining share fastest among digitally-native customer cohorts seeking flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between member states creates compliance-cost arbitrage, prompting insurers to route capital deployment through jurisdictions with lighter conduct requirements while maintaining EU passporting rights. This dynamic concentrates underwriting capacity in select markets while fragmenting distribution economics.
Germany
Corporate fleet mandates from automotive and logistics sectors drive premium growth as employers institutionalize remote-work device liability. The Federal Financial Supervisory Authority (BaFin) enforces strict solvency reporting under EIOPA guidelines, elevating compliance overhead for multi-country operators. Munich and Frankfurt host the densest concentration of underwriter headquarters and operator billing integration teams.
United Kingdom
Premium smartphone penetration exceeds European averages, sustaining high-frequency accidental damage claims and repair cost volatility. The Financial Conduct Authority maintains post-Brexit alignment with EU consumer protection standards while testing stricter embedded sales disclosure rules. London anchors insurtech development for automated claims platforms serving operator-integrated policies.
France
Urban theft rates in Paris and Marseille elevate demand for loss coverage over repair-centric policies. The Autorité de Contrôle Prudentiel et de Résolution supervises product governance under Insurance Distribution Directive implementations. Lyon hosts specialized adjusters for device damage assessment serving southeastern subscriber bases.
Italy
SIM-only subscriber growth outpaces operator-embedded attachment, creating penetration gaps for post-purchase digital platforms. IVASS testing of stricter conduct standards for point-of-sale insurance sales requires explicit consent documentation. Milan concentrates retail chain distribution partnerships with pan-European underwriters.
Spain
Underserved SIM-only bases in Madrid and Barcelona attract online retail platforms seeking coverage flexibility outside operator ecosystems. The Dirección General de Seguros y Fondos de Pensiones monitors compliance with EU Digital Services Act transparency obligations. Valencia hosts emerging insurtech clusters focused on Mediterranean market expansion.
Europe Mobile Phone Insurance Market Competitive Landscape
German underwriters anchor one tier of the market through pan-European property and casualty networks; US-based specialists hold embedded distribution capabilities through operator billing integrations. The vendor base stratifies between established multi-line insurers with legacy infrastructure and digital-native platforms with API-first architectures. Three archetypes dominate: pan-European underwriters leveraging cross-border scale, operator-captive distributors controlling point-of-sale attachment, and insurtech platforms compressing claims cycles through automation. Competitive moves concentrate on strategic partnerships with retail chains and technology licensing for automated damage assessment.
Among the pan-European underwriter tier, Allianz SE and AXA exemplify divergent strategic positioning—Allianz anchoring multi-country retail chain partnerships, AXA occupying digital-first claims platform development. Assurant, Inc. sits within the operator-embedded archetype, representing specialized API integration capabilities for billing system synchronization. These three companies illustrate how underwriting capacity and distribution control separate across distinct competitive vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Asurion, LLC |
| American International Group, Inc. |
| Allianz SE |
| Telefonica UK Limited |
| Apple Inc. |
| AXA |
| Assurant, Inc. |
| Better Buy Insurance |
| Aviva Insurance Limited |
| Others |
Value Network & Pricing Analysis
Corporate fleet managers in Germany and France anchor pricing power through master policy negotiations covering thousands of employee devices, compressing per-unit premiums while elevating service-level requirements for underwriters. This buyer concentration forces insurers toward subscription-based recurring revenue models with customized deductible tiers rather than transactional point-of-sale attachments.
Pricing Analysis
Operator billing integration margins dominate the pricing structure, with Vodafone and Deutsche Telekom extracting distribution fees that compress underwriter net premiums. Price differentiation rests on claims automation capability and geographic repair network density. Cost compression in the SIM-only segment intensifies because online retail platforms enable instant deductible comparison across multiple underwriters. Students and younger demographics exhibit highest price sensitivity, while corporate procurement officers prioritize centralized premium management over per-unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from EIOPA solvency guidelines force insurers to maintain qualified repair networks across multiple jurisdictions, preventing single-vendor dependency for claims fulfillment. Component supply draws from Germany, Poland, and Netherlands for authorized service parts, with aftermarket display assemblies sourcing from China and Vietnam. Semiconductor and OLED pricing volatility creates replacement cost reserve instability. Distribution runs through mobile operator billing systems for embedded policies and direct API connections for online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe mobile phone insurance functions as a stable compounder where enterprise fleet digitization mandates generate predictable premium expansion with low cyclical sensitivity.
For Market Incumbents: Deepen API integration capabilities with mobile operator billing architectures to defend against insurtech disintermediation. Invest in GDPR-compliant computer vision claims automation to reduce loss-adjustment expenses as manual inspection costs escalate. Prioritize pan-European licensing consolidation under EIOPA guidelines to streamline multi-country capital adequacy compliance. For New Entrants and Emerging Players: The mid-market price gap between premium-tier AXA digital platforms and economy-tier retail chain partnerships offers white-space entry opportunity. Target underserved SIM-only subscriber bases in Spain and Italy through post-purchase digital origination with flexible monthly billing. Deploy embedded insurance APIs for electronics retailer point-of-sale integration as operator subsidies dismantle. For Investors and Strategic Acquirers: Mobile operators seeking vertical control over device lifecycle revenue represent the most active acquirer category in this space. Five-to-ten year viability hinges on claims automation technology differentiation rather than underwriting scale alone. Monitor IVASS and Dutch regulator conduct standard implementations as signals for embedded sales practice compliance costs that could reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Claims Automation | Privacy-preserving computer vision reduces French and German loss-adjustment expenses while satisfying Article 22 human-in-the-loop requirements. |
| Operator Billing API Integration | Embedded insurance synchronization with Deutsche Telekom and Vodafone systems lowers customer acquisition costs and improves policy persistency. |
| Pan-European Licensing Consolidation | EIOPA passporting rights enable cross-border premium pooling that satisfies solvency requirements across Germany, France, and Benelux markets. |
| Corporate Fleet Master Policies | Centralized procurement frameworks with DACH automotive and logistics corporations generate recurring premium volumes with standardized deductible tiers. |
| Telematics-Claims Convergence | Device health sensor integration with automated damage assessment APIs enables real-time premium adjustment for Italian and Spanish subscribers. |
Research Methodology
Direct dialogue with insurance underwriting executives, mobile operator partnership directors, enterprise fleet procurement managers, and EIOPA regulatory specialists grounded the qualitative foundation. Secondary validation drew from EIOPA solvency reports, Insurance Distribution Directive national implementation filings, mobile operator annual disclosures, and claims frequency datasets. Bottom-up premium volume estimates triangulated against top-down market sizing from regulatory capital filings.
Segment-level projections across insurance type, distribution channel, customer segment, and policy duration dimensions fed into the analytical framework. CAGRs derived from historical premium growth trajectories adjusted for regulatory implementation timelines and technology adoption curves. Forecast inputs incorporated corporate fleet mandate expansion rates, manufacturer warranty extension impacts, and GDPR compliance cost escalations.
Caveats apply where EIOPA solvency requirement recalibrations or manufacturer warranty period extensions beyond thirty-six months could materially shift the outlook. Deviation in operator subsidy dismantling velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Art Insurance Market
Insurance
Digital Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Critical Illness Insurance Market
Insurance
Business Income Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Cargo Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Group Health Insurance Market