
 Europe Car Insurance Market | 2026-2036
Europe Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Car Insurance Market Insights
Market Context with Strategic Players
German direct underwriters is repositioning toward telematics-enabled pricing models across the European Economic Area. Allianz SE leverages its captive data infrastructure to refine risk segmentation in connected vehicle portfolios. AXA SA anchors its continental strategy through digital-first distribution platforms targeting urban mobility ecosystems. Munich RE competes at the reinsurance layer, sustaining capacity for primary carriers exposed to climate-related claims volatility.
Technical Definition and Structural Segments
Europe car insurance constitutes a contractual risk-transfer mechanism indemnifying policyholders against financial loss arising from vehicle damage, bodily injury, or third-party liability, with premiums calculated through actuarial models incorporating vehicle telemetry, driver behavior data, and geographic risk density. The product serves to restore capital position after insurable events while satisfying compulsory coverage mandates under national traffic codes. Comprehensive coverage dominates premium income across the region, though personal injury protection is gaining structural weight as medical cost inflation outpaces property damage trends. Commercial fleets represent the fastest-expanding customer type, driven by last-mile logistics electrification and corporate duty-of-care obligations.
Regulatory Framework and Forward Outlook
The EU AI Act, national implementations of the Insurance Distribution Directive, and EIOPA's supervisory convergence mandates collectively reshape product governance, algorithmic transparency requirements, and cross-border passporting conditions for carriers operating in multiple member states. GDPR constraints on telematics data processing limit granularity in usage-based pricing while creating compliance cost differentials between integrated incumbents and newer digital entrants. Stakeholders must monitor how automated vehicle liability attribution evolves under the Product Liability Directive revision and whether national regulators harmonize no-fault frameworks for autonomous operation scenarios.
Market Dynamics
Telematics-enabled usage-based insurance is compressing traditional risk-pooling models across the European Economic Area, forcing carriers to rebuild pricing infrastructure around real-time driving behavior data rather than static demographic proxies.
Growth Catalysts
- EU AI Act liability frameworks:The regulation establishes clear fault attribution protocols for automated vehicle incidents, reducing legal uncertainty that previously suppressed commercial fleet coverage expansion in Germany and France.
- Last-mile logistics electrification:Commercial van and light truck operators across the Netherlands and Belgium are mandating comprehensive coverage as corporate duty-of-care obligations intensify for driver safety.
- Connected vehicle data pipelines:OEM-integrated telemetry streams from Volkswagen Group and Stellantis platforms enable dynamic premium adjustment based on actual mileage and braking patterns.
Market Restraints
- GDPR telematics constraints:The regulation limits granular data retention periods for driver behavior tracking, forcing carriers to sacrifice predictive accuracy or absorb compliance infrastructure costs.
- Reinsurance capacity concentration:Climate-related claims volatility has compressed retrocession availability, particularly for carriers exposed to Central European flood damage corridors.
- Legacy policy administration systems:Cobol-based core platforms at established insurers resist real-time API integration with telematics service providers, delaying product launch cycles.
Strategic Opportunities
- Polish and Romanian motor insurance penetration:These markets exhibit significant underinsurance gaps in comprehensive coverage relative to Western European compulsory third-party baselines.
- Pay-per-mile urban mobility products:Car-sharing platform partnerships in Milan and Barcelona enable micro-duration coverage activation tied to actual vehicle usage rather than annual policies.
- CSRD sustainability disclosure alignment:Fleet operators face Scope 3 emissions reporting mandates that favor insurers offering carbon-offset-integrated coverage products with verified telemetry documentation.
Industry Challenges
- Actuarial talent scarcity:The shortage of professionals combining traditional pricing expertise with machine learning model governance creates bottlenecks in algorithmic product development.
- Cross-border claims adjudication:Divergent national interpretations of the Insurance Distribution Directive complicate seamless service delivery for policyholders operating across multiple member states.
- Autonomous vehicle liability ambiguity:Pending Product Liability Directive revisions leave unresolved questions about manufacturer versus operator fault allocation in Level 3+ automation scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Car Insurance Market |
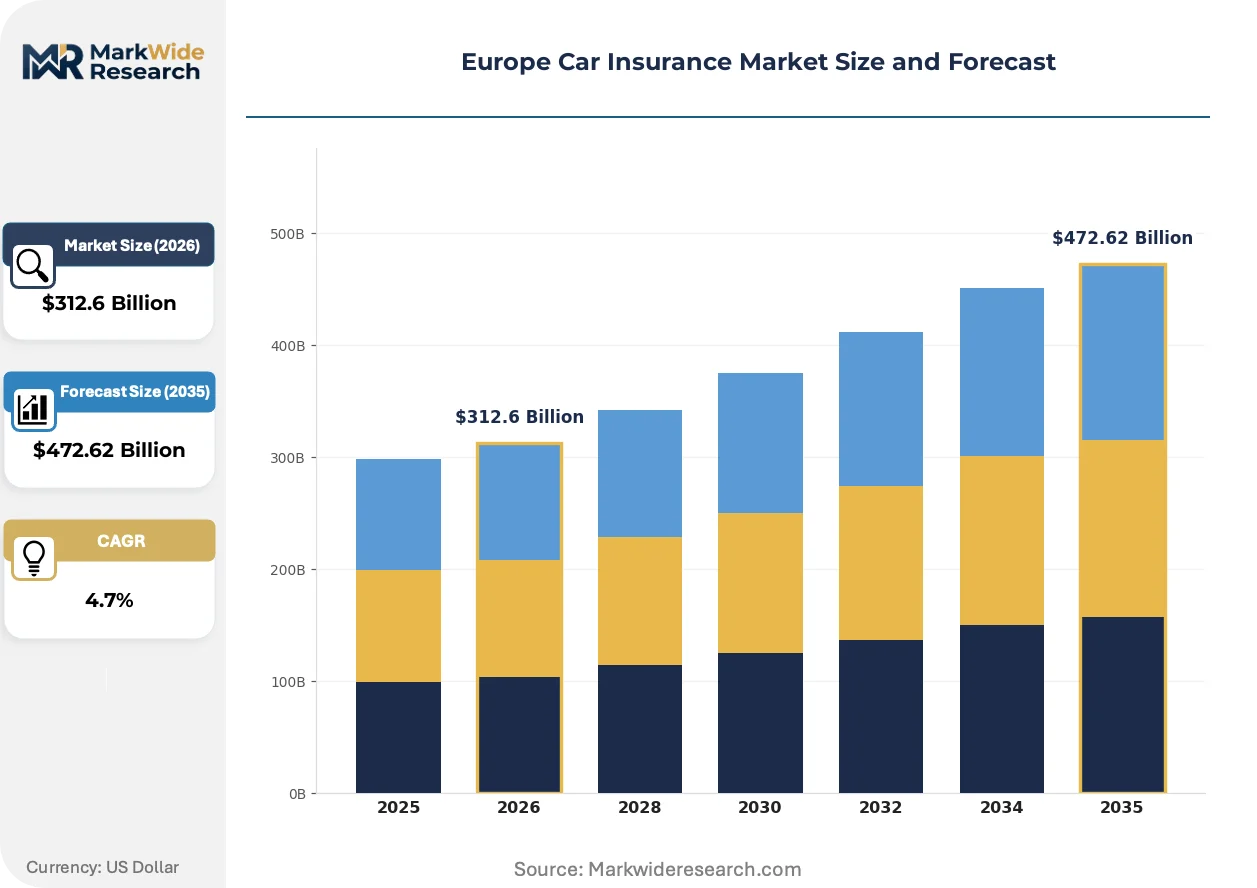
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Third Party Liability, Comprehensive, Collision, Personal Injury Protection Customer Type: Private Individuals, Commercial Fleets, Ride-Sharing Services, Car Rental Agencies Coverage Type: Mandatory Coverage, Additional Benefits, Excess Waiver, Theft Protection Distribution Channel: Direct Sales, Agents, Online Platforms, Brokers |
| Companies Covered | Allianz SE, AXA SA, Assicurazioni Generali SpA, Munich RE, Zurich Insurance Group, Swiss Re AG, Chubb Ltd., Liberty Mutual Insurance, Crédit Agricole Assurances, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Car Insurance Market Trends and Innovations
Artificial intelligence and embedded distribution channels are dismantling the traditional annual-renewal, broker-mediated transaction model that dominated European motor insurance for decades.
Computer vision damage assessment is automating claims settlement workflows for property damage incidents. German and French direct carriers are deploying smartphone-based image analysis to accelerate repair authorization decisions. The technology is automating adjuster dispatch decisions for low-severity collisions, compressing cycle times from days to hours.
The EU AI Act mandates algorithmic transparency documentation for automated underwriting decisions. Carriers must maintain technical files explaining risk score derivation to satisfy national competent authority audits. Personal lines portfolios face the steepest compliance burden as mass-market policy volumes multiply documentation requirements.
Fleet procurement teams are consolidating insurance buying through mobility-as-a-service platform marketplaces. Large logistics operators in the Rhine-Ruhr corridor now source coverage through integrated fleet management software rather than traditional broker relationships. Spain and Portugal exhibit the fastest platform adoption rates among mid-sized commercial vehicle operators.
Europe Car Insurance Market Segmentation
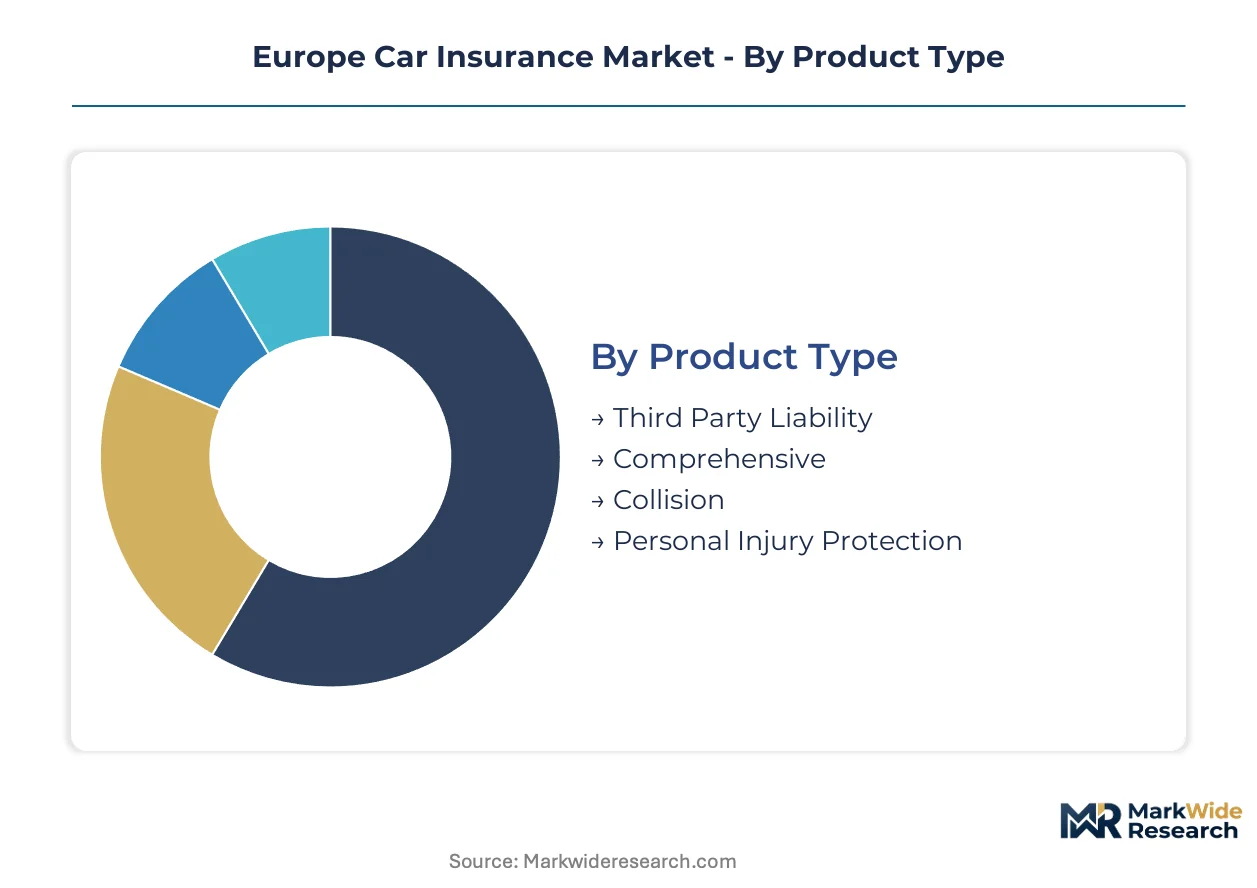
Car insurance product architecture in Europe reflects divergent national compulsory mandates alongside elective coverage tiers. Risk transfer mechanisms vary substantially across customer profiles, from standardized third-party liability to bespoke commercial fleet programs. Distribution economics shift dramatically between legacy broker networks and API-embedded digital platforms.
Product Type:
Standardized compulsory coverage sits at one pole; highly customized comprehensive products occupy the other, with telematics integration creating hybrid middle tiers.
- Third Party Liability:The statutory minimum across all EU member states, indemnifying policyholders against damage to other vehicles, property, or persons. Demand concentrates in Poland and Romania where compulsory coverage penetration lags Western European comprehensive adoption rates. Premium compression is severe due to regulatory rate caps in several jurisdictions.
- Comprehensive:Bundles own-damage, theft, and third-party exposure into single contracts with deductible structures. German and French direct underwriters dominate this segment through telematics-enabled dynamic pricing. Fleet procurement teams in the Rhine-Ruhr corridor increasingly mandate comprehensive terms as corporate duty-of-care obligations intensify.
- Collision:Narrow coverage for at-fault vehicle damage excluding third-party liability. Italian and Spanish markets show residual demand among price-sensitive private individuals.
- Personal Injury Protection:Medical cost reimbursement regardless of fault attribution. Belgian and Dutch regulators are expanding mandatory PIP minimums as healthcare cost inflation accelerates.
Most installed capacity flows through Comprehensive. Expansion is steepest in Personal Injury Protection.
Customer Type:
Volume economics favor standardized private individual portfolios; margin concentration sits with complex commercial accounts requiring bespoke risk engineering.
- Private Individuals:Mass-market personal lines characterized by price elasticity and low switching costs. Digital-first distribution platforms in France and Germany capture disproportionate share through smartphone-native onboarding workflows.
- Commercial Fleets:Multi-vehicle accounts with customized loss control programs and captive self-insured retentions. Last-mile logistics electrification across the Netherlands and Belgium is accelerating coverage expansion as van and light truck operators face intensified corporate safety obligations.
- Ride-Sharing Services:Platform-mediated drivers requiring micro-duration coverage activation tied to actual passenger-carrying periods. Regulatory clarity under the EU AI Act is reducing legal uncertainty that previously suppressed market development.
- Car Rental Agencies:Fleet operators demanding excess waiver products and loss-of-use coverage. Spanish and Portuguese airport hub operators represent concentrated demand nodes.
Private Individuals generate the largest premium volume. Commercial Fleets are climbing the fastest as fleet electrification mandates expand.
Coverage Type:
Regulatory floor products compete against value-added tiers where carriers extract margin through deductible manipulation and benefit packaging.
- Mandatory Coverage:Legally prescribed minimum benefits varying by member state implementation of the Motor Insurance Directive. German KBA enforcement maintains the region's strictest compliance standards.
- Additional Benefits:Roadside assistance, legal protection, and courtesy vehicle provisions bundled at point of sale. French direct carriers leverage these attachments to defend margin against pure price competition.
- Excess Waiver:Premium surcharge eliminating policyholder deductible obligations. Car rental channel penetration is deepest in Spanish and Italian leisure tourism corridors.
- Theft Protection:Dedicated coverage for vehicle theft and unauthorized use, increasingly integrated with OEM immobilizer telemetry. Eastern European markets exhibit elevated loss ratios driving premium rate differentiation.
Mandatory Coverage commands universal participation. Additional Benefits are gaining share fastest as carriers seek attachment revenue.
Distribution Channel:
Legacy intermediation persists in complex commercial lines; direct and platform channels capture standardized personal lines through cost advantage.
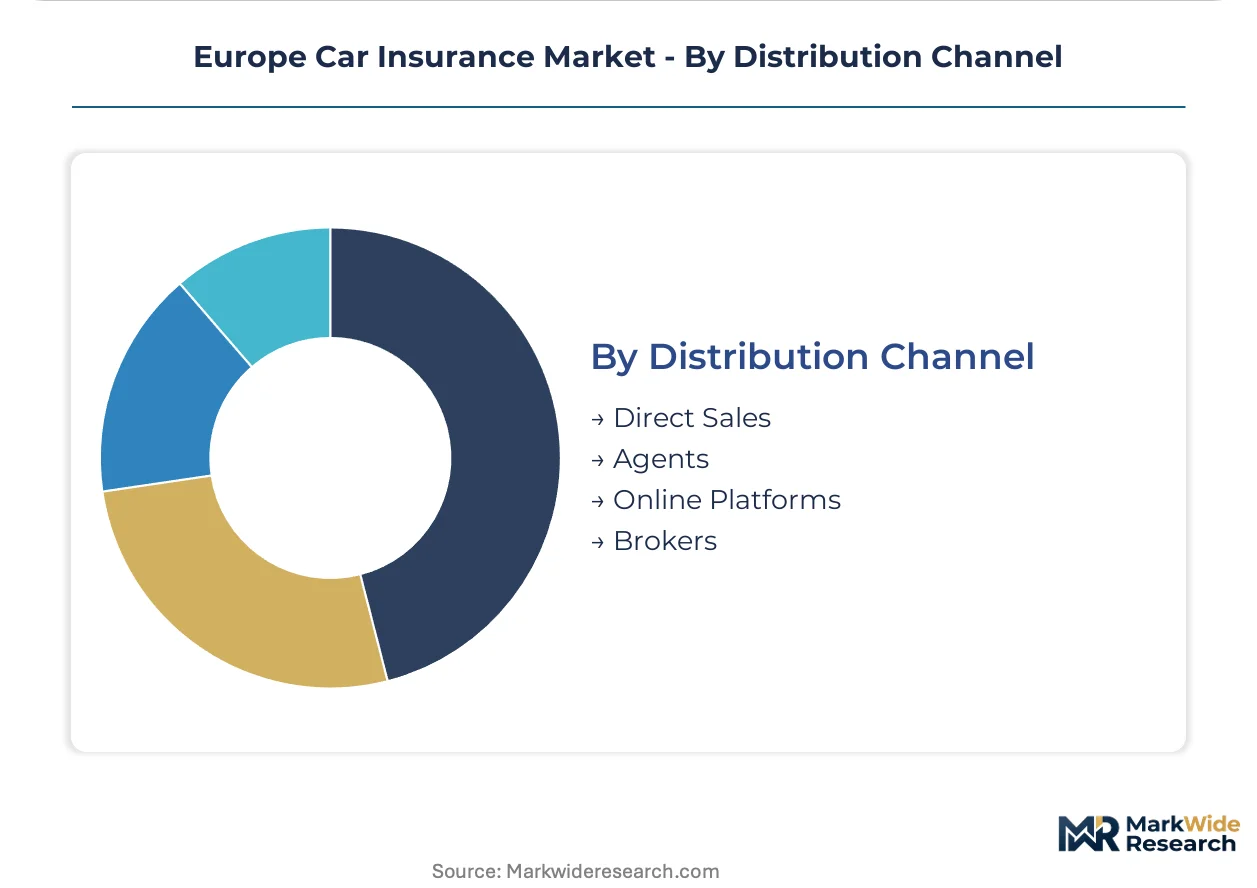
- Direct Sales:Captive agent networks and telephone operations controlled by primary carriers. Allianz SE maintains the region's largest direct sales infrastructure across Germany and Austria.
- Agents:Tied intermediaries with exclusive or preferential carrier relationships. Italian and Spanish markets retain higher agent dependency than Northern Europe.
- Online Platforms:Price comparison websites and insurer-owned digital storefronts. GDPR constraints on telematics data processing create compliance friction for algorithmic quote generation.
- Brokers:Independent intermediaries serving commercial accounts with placement expertise. Munich RE capacity access is a critical broker selection criterion for large fleet risks.
Direct Sales and Agents together handle the majority of premium volume. Online Platforms are expanding most quickly as smartphone-native customer segments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between member states are redirecting commercial fleet underwriting capacity toward jurisdictions with lighter compliance burdens. German and French carriers are expanding Polish and Romanian operations to escape GDPR-constrained telematics pricing limitations. The EU AI Act harmonization timeline remains uncertain, preserving these arbitrage windows through the forecast period.
Germany
KBA enforcement maintains Europe's strictest compulsory coverage compliance standards, driving premium motor insurance penetration depths unmatched elsewhere. The EU AI Act implementation is clarifying automated vehicle liability attribution for commercial fleets operating across federal states. Rhine-Ruhr logistics clusters are mandating comprehensive coverage terms as corporate duty-of-care obligations intensify for last-mile electrification.
France
ANSM and CNIL oversight creates dual-layer compliance costs for telematics-enabled pricing models that compress carrier margins. AXA SA anchors digital-first distribution platforms targeting urban mobility ecosystems in Paris and Lyon metropolitan corridors. The Insurance Distribution Directive national implementation is reshaping cross-border passporting conditions for carriers operating from French domiciles.
United Kingdom
Post-Brexit regulatory divergence from EU AI Act frameworks is creating uncertainty for automated vehicle liability coverage sold into Northern Irish markets. London-based insurtech platforms are capturing price-sensitive private individual segments through smartphone-native onboarding workflows. The Prudential Regulation Authority is tightening capital requirements for carriers exposed to climate-related claims volatility.
Italy
Agent-mediated distribution retains higher dependency than Northern European markets, slowing telematics adoption among traditional customer bases. Assicurazioni Generali SpA leverages captive infrastructure across Lombardy and Piedmont industrial clusters. IVASS supervision is converging with EIOPA mandates on algorithmic transparency documentation for automated underwriting decisions.
Poland
Significant underinsurance gaps in comprehensive coverage relative to Western European baselines present expansion opportunities for direct underwriters. Polish Financial Supervision Authority implementation of Insurance Distribution Directive provisions lags German and French timelines, creating compliance cost advantages. Warsaw and Krakow metropolitan areas are experiencing fastest platform adoption rates among mid-sized commercial vehicle operators.
Europe Car Insurance Market Competitive Landscape
Established underwriters occupy the standard tier; emerging insurtech entrants pursue embedded distribution partnerships with mobility platforms. The market structure concentrates around integrated incumbents with captive data infrastructure, while digital-first challengers capture price-sensitive segments through API-enabled quote generation. Three archetypes dominate: legacy carriers with direct sales networks, reinsurance capacity providers, and platform-native distributors. Competitive moves center on telematics integration partnerships and geographic expansion into underpenetrated Eastern European markets.
Among Germany-based integrated carriers, Allianz SE exemplifies the legacy-digital hybrid archetype through telematics-enabled pricing infrastructure. AXA SA, domiciled in France, occupies a position within the continental direct distribution tier targeting urban mobility ecosystems. Munich RE, a German Aktiengesellschaft, anchors the reinsurance capacity layer sustaining primary carrier exposure to climate-related claims volatility. These three entities represent distinct strategic postures without exhausting the competitive field.
| Leading Market Players |
|---|
| Allianz SE |
| AXA SA |
| Assicurazioni Generali SpA |
| Munich RE |
| Zurich Insurance Group |
| Swiss Re AG |
| Chubb Ltd. |
| Liberty Mutual Insurance |
| Crédit Agricole Assurances |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement consolidation across the Rhine-Ruhr corridor is forcing primary carriers to absorb telematics infrastructure costs while maintaining competitive premium levels for comprehensive coverage mandates.
Pricing Analysis
Direct-to-consumer digital platforms compress distributor margins that traditional agent networks once captured. Three-tier pricing structure across premium, standard, and economy levels segments risk pools by telematics-verified driving behavior and claims history. Cost compression in the economy tier intensifies because GDPR compliance infrastructure disproportionately burdens smaller carriers. Private individual segments exhibit highest price sensitivity, while commercial fleets prioritize loss control services over premium minimization.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Netherlands anchor claims service capacity for cross-border policyholders. Reinsurance capacity draws from Munich, Zurich, and London markets, with retrocession layers resting on Bermuda and Singapore specialty providers. Single-source vulnerability concentrates in telematics service provider partnerships where OEM-integrated data pipelines lack interoperability standards. Distribution runs through direct sales networks, price comparison aggregators, and embedded fleet management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in telematics-enabled risk selection, where granular driving behavior data justifies premium tier separation that static demographic models cannot defend.
For Market Incumbents: Cement data infrastructure advantages through exclusive OEM telemetry partnerships with Volkswagen Group and Stellantis platforms. Deepen captive reinsurance arrangements to buffer climate-related claims volatility that threatens capital adequacy ratios under EIOPA stress testing protocols.
For New Entrants and Emerging Players: Capture Polish and Romanian comprehensive coverage gaps where compulsory third-party baselines leave significant underinsurance exposure. Deploy API-native distribution through car-sharing platform partnerships in Warsaw and Krakow metropolitan corridors, leveraging lagging Insurance Distribution Directive implementation timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with digital-first carriers possessing algorithmic underwriting capabilities and clean GDPR compliance architecture. Long-term viability hinges on telematics data rights ownership rather than policy volume scale. Monitor EU AI Act liability framework harmonization progress as the decisive inflection signal for autonomous vehicle coverage market development.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Infrastructure Partnership | Exclusive data access from Stellantis and Volkswagen Group platforms enables dynamic pricing granularity. |
| Polish and Romanian Geographic Expansion | Underinsurance gaps in comprehensive coverage offer first-mover premium growth outside saturated Western markets. |
| GDPR Compliance Architecture Investment | Clean data processing frameworks create sustainable cost advantages against legacy system-dependent incumbents. |
| Captive Reinsurance Capacity Buildup | In-house retrocession layers buffer climate-related claims volatility compressing third-party capacity availability. |
| Embedded Fleet Platform Integration | API-native distribution through mobility-as-a-service marketplaces captures commercial procurement consolidation trends. |
Research Methodology
Direct dialogue with actuarial directors, telematics product managers, fleet procurement officers, and EIOPA supervisory staff grounded qualitative findings in operational reality. Secondary validation drew from EIOPA statistical reports, national competent authority filings, Motor Insurance Directive implementation texts, and carrier Solvency II disclosures. Bottom-up policy volume estimates triangulated against top-down premium income aggregates across the analysis window.
Segment-level projections incorporate product type, customer archetype, distribution channel, and national regulatory cluster variations. CAGRs derive from actuarial trend analysis applied to historical loss ratio patterns and forward premium rate indications. Modeled inputs include telematics adoption curves, automated vehicle liability framework evolution, and climate-related claims frequency adjustments.
Regulatory harmonization delays, reinsurance capacity shocks, and autonomous vehicle liability attribution disputes are the dominant revision risks. Forecasts reflect documented assumptions regarding GDPR enforcement intensity and EU AI Act implementation sequencing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Commercial Earthquake Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Canada House Insurance Market
Insurance
Europe EV Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Green Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Africa Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
France Car Insurance Market
Insurance
Takaful Market