
 Global Healthcare Claims Management Market | 2026-2036
Global Healthcare Claims Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Claims Management Market Intelligence
The transition from fragmented, in-house claims processing to integrated, outsourced revenue cycle management is consolidating the provider landscape. Optum leverages its extensive payer-provider network to offer end-to-end services. Cognizant specializes in business process outsourcing for large insurance carriers. Oracle Corporation extends its enterprise database and cloud infrastructure to support complex healthcare financial workflows.
Healthcare claims management involves the systems and workflows for submitting, processing, and paying medical service claims between providers and payers. These platforms use standardized codes, such as ICD-10 and CPT, to document patient encounters and justify reimbursement requests. Cloud-based deployment is becoming the standard for new implementations due to its scalability. Within solution types, fraud detection and denial management applications deliver the highest return on investment for payers and providers, respectively.
Data handling is governed by regulations like the Health Insurance Portability and Accountability Act (HIPAA) in the United States, which mandates security protocols. In Europe, the General Data Protection Regulation (GDPR) imposes stringent rules on patient information privacy, impacting any entity processing EU citizen data. Future platform competitiveness will depend on a vendor's ability to navigate these evolving, cross-jurisdictional data security mandates.
Market Dynamics
The consolidation of payer-provider data streams into unified, outsourced platforms is the central force structuring the market. This shift is driven by the increasing complexity of reimbursement models and stringent data security mandates like the Health Insurance Portability and Accountability Act (HIPAA) and General Data Protection Regulation (GDPR).
Growth Catalysts
- AI Integration:Artificial intelligence for real-time fraud detection and pre-authorization reduces revenue leakage for payers, accelerating platform adoption.
- Standardization Mandates:The use of coding systems like ICD-10 in the United States compels providers to adopt specialized software for compliance and billing accuracy.
- Large Hospital Networks:Hospital system consolidation creates demand for scalable solutions to manage high claims volume and complex revenue cycles across facilities.
Market Restraints
- High Implementation Costs:Significant upfront investment to integrate platforms with legacy electronic health record (EHR) systems deters smaller healthcare providers.
- Data Interoperability Issues:Lack of universal standards for data exchange between disparate provider and payer systems creates processing bottlenecks and data errors.
- Cross-Jurisdictional Compliance:Navigating conflicting data privacy laws, like GDPR in Europe and HIPAA in the U.S., increases operational complexity and legal risk.
Strategic Opportunities
- Emerging Asian Markets:Privatizing healthcare sectors in countries like India and Indonesia present an underpenetrated market for outsourced revenue cycle management.
- Blockchain for Adjudication:Distributed ledger technology can create immutable, transparent claims records, reducing disputes between payers and providers.
- Value-Based Care Analytics:The shift to outcome-based payments creates a need for new analytics tools to track performance and justify reimbursement.
Industry Challenges
- Cybersecurity Threats:The high value of protected health information (PHI) makes claims platforms a prime target for cyberattacks, demanding constant security investment to comply with HIPAA.
- Talent Scarcity:A shortage of professionals skilled in both medical coding, such as ICD-10, and data analytics creates a bottleneck for optimizing claims processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Claims Management Market |
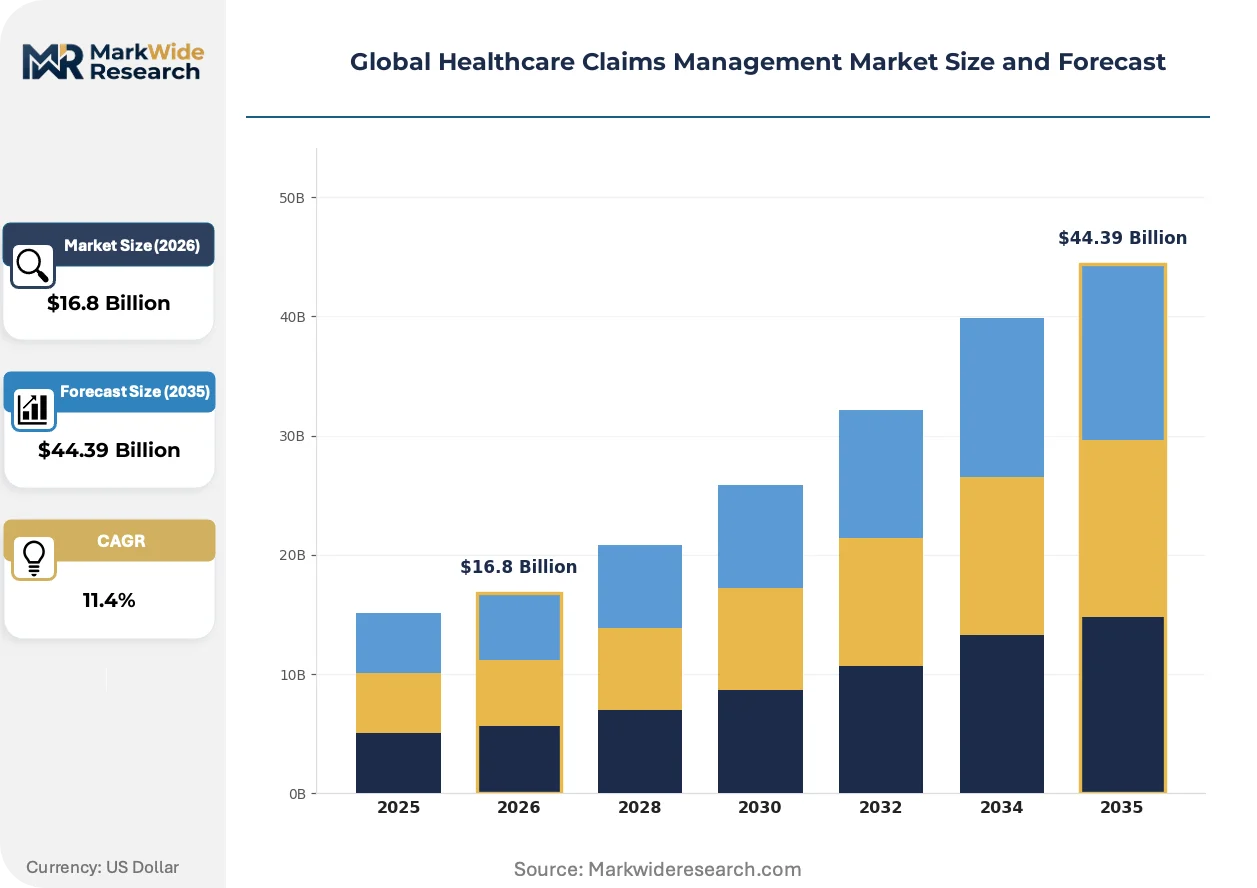
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $44.39 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Type: Billing Management, Payment Processing, Fraud Detection, Patient Eligibility Verification, Revenue Cycle Management Application: Provider Credentialing, Claims Adjudication, Payment Reconciliation, Denial Management, Compliance Monitoring End User: Hospitals, Diagnostic Centers, Pharmaceutical Companies, Insurance Carriers, Medical Billing Companies |
| Companies Covered | Athenahealth, Optum, Cognizant, Oracle Corporation, McKesson Corporation, Allscripts Healthcare Solutions, Cerner Corporation, eClinicalWorks, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Claims Management Market Strategic Shifts & Innovations
The application of artificial intelligence is evolving beyond process automation to encompass predictive analytics for denial management and revenue forecasting. This shift moves platform value from transactional efficiency to strategic financial planning for healthcare organizations.
Generative AI is a key technology being applied to automate the creation of appeals letters for denied claims and summarize complex patient histories. Large hospital networks and billing companies are rapidly piloting these tools to reduce administrative overhead. This automated content generation capability is expanding into patient communication, drafting pre-authorization requests and explaining benefits in simple terms.
In the United States, the No Surprises Act mandates new transparency and dispute resolution processes for out-of-network charges. This regulation requires claims management platforms to incorporate new workflows for price estimation, patient consent, and arbitration management. Payers and providers are prioritizing platform updates that automate compliance with these complex billing and patient notification rules.
Healthcare providers are moving away from purchasing standalone, best-of-breed applications for different revenue cycle functions. They increasingly favor integrated, end-to-end platforms from a single vendor that cover everything from patient registration to final payment reconciliation. This trend is most visible among mid-sized hospital groups in North America seeking to simplify their IT infrastructure and vendor relationships.
Global Healthcare Claims Management Market Segmentation
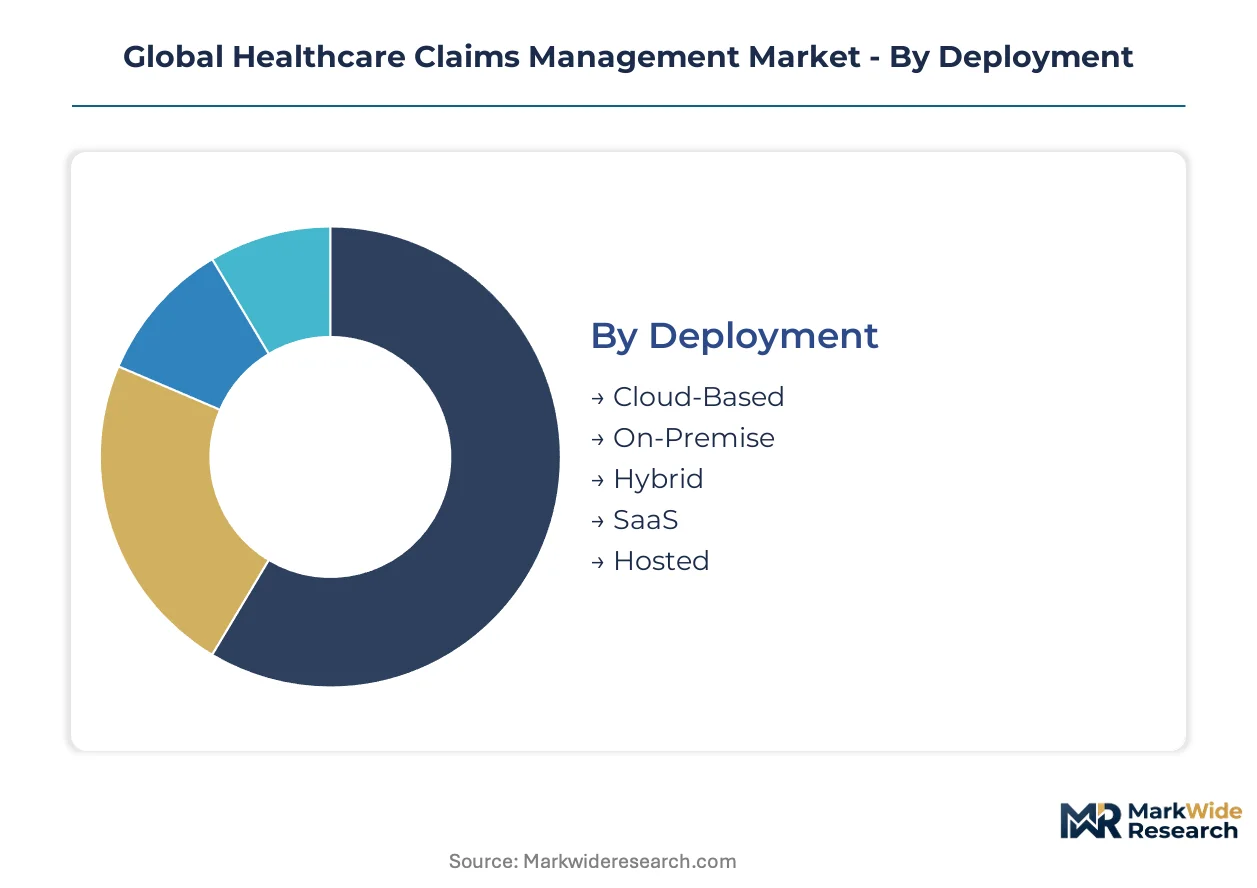
The segmentation of the Global Healthcare Claims Management Market reveals critical distinctions in operational approaches and technological priorities across the healthcare ecosystem. Understanding these segments is vital for vendors to tailor solutions that meet specific industry needs and regulatory demands.
Deployment:
The deployment of healthcare claims management solutions necessitates adherence to specific regulatory frameworks, particularly for segments handling sensitive patient data.
- Cloud-Based:Cloud-Based solutions leverage remote servers for data storage and processing, offering enhanced scalability and accessibility for healthcare organizations. Demand for these platforms is concentrating in the United States, driven by the need for flexible infrastructure to manage complex reimbursement models and HIPAA compliance.
- SaaS:Software-as-a-Service models provide subscription-based access to claims management functionalities, reducing upfront capital expenditure for providers. This model is gaining traction in European markets, where GDPR compliance requires robust data handling without extensive in-house IT investment.
- On-Premise:On-Premise deployments involve installing software directly on the end-user's local servers and infrastructure, offering greater control over data.
- Hybrid:Hybrid models combine elements of both on-premise and cloud deployments, allowing organizations to maintain sensitive data locally while leveraging cloud scalability for other functions.
- Hosted:Hosted solutions involve a third-party provider managing the software and hardware infrastructure, often tailored for specific client needs.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
Solution Type:
Solution types vary significantly in their functional depth and complexity, addressing distinct operational challenges within the healthcare revenue cycle.
- Fraud Detection:Fraud Detection solutions employ advanced algorithms and artificial intelligence to identify suspicious billing patterns and prevent revenue leakage for payers. Insurance carriers in Germany are prioritizing these solutions to mitigate financial losses from erroneous claims.
- Revenue Cycle Management:Revenue Cycle Management platforms offer comprehensive services spanning patient registration, claims submission, and payment reconciliation, optimizing financial performance for providers. Large hospital networks in Canada are increasingly adopting these integrated systems to streamline their administrative processes.
- Billing Management:Billing Management solutions focus on the accurate generation and submission of claims, ensuring compliance with coding systems like ICD-10.
- Payment Processing:Payment Processing modules facilitate the secure and efficient handling of financial transactions between payers and providers.
- Patient Eligibility Verification:Patient Eligibility Verification tools confirm insurance coverage and benefits before service delivery, reducing claim denials.
Billing Management solutions continue to command significant volume. Fraud Detection is expanding most quickly due to its direct impact on cost savings.
Application:
Applications for healthcare claims management systems are distinguished by their specific operational focus and the type of workflow they automate within the claims process.
- Denial Management:Denial Management applications analyze rejected claims, identify root causes, and automate the appeals process, improving reimbursement rates for providers. Providers in Australia are heavily investing in these tools to combat increasing claim denial rates.
- Claims Adjudication:Claims Adjudication modules systematically review claims against policy rules and medical necessity criteria to determine payment liability for payers. Payers in France are enhancing these systems to comply with evolving national health insurance regulations.
- Payment Reconciliation:Payment Reconciliation applications match received payments against billed amounts, identifying discrepancies and ensuring financial accuracy.
- Compliance Monitoring:Compliance Monitoring tools ensure that claims processing adheres to regulatory mandates such as HIPAA and local billing guidelines.
- Provider Credentialing:Provider Credentialing applications manage the verification of healthcare professionals' qualifications and licensure.
Payment Reconciliation applications see consistent usage. Denial Management is climbing the fastest as providers seek to maximize revenue capture.
End User:
End users of healthcare claims management systems span a diverse spectrum of organizations, each with unique operational scales and compliance requirements.
- Hospitals:Hospitals represent a major end-user segment, requiring robust platforms to manage high volumes of complex claims across multiple departments and specialties. Large hospital systems in the United Kingdom are consolidating their claims processing onto unified platforms.
- Insurance Carriers:Insurance Carriers utilize these systems to process claims from their large member bases, detect fraud, and ensure compliance with regulatory mandates like HIPAA in the United States. Major insurers are investing in AI-driven platforms for enhanced efficiency.
- Medical Billing Companies:Medical Billing Companies outsource claims processing services for various healthcare providers, demanding scalable and efficient management solutions.
- Diagnostic Centers:Diagnostic Centers use claims management platforms to handle billing for specialized medical tests and imaging services.
- Pharmaceutical Companies:Pharmaceutical Companies employ these systems for managing claims related to drug reimbursements and patient assistance programs.
Hospitals exhibit the highest adoption rates. Medical Billing Companies are demonstrating robust expansion as outsourcing trends continue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for healthcare claims management solutions, driven by its intricate reimbursement models and high healthcare spending. This complex environment necessitates sophisticated platforms for efficient processing and compliance. Regulations like HIPAA significantly influence technology adoption and data security standards across the market.
United States
The United States market for healthcare claims management is shaped by its complex payer landscape and significant healthcare expenditure. HIPAA mandates stringent data security protocols for all claims processing, influencing platform design. Major technology hubs like Silicon Valley and Boston are centers for innovation in AI-driven claims solutions.
Germany
German insurance carriers increasingly adopt fraud detection solutions to mitigate financial losses from erroneous claims. GDPR imposes strict patient data privacy rules, requiring robust compliance features in claims platforms. The Rhine-Main region, particularly Frankfurt, hosts significant health tech companies developing these advanced systems.
Canada
Canadian large hospital networks prioritize comprehensive revenue cycle management platforms to streamline administrative processes. Health Canada oversees national healthcare standards, influencing claims software interoperability and reporting. Toronto and Montreal are key development centers for integrated healthcare IT solutions.
Australia
Australian providers invest heavily in denial management applications to combat rising claim rejection rates and maximize revenue capture. The Therapeutic Goods Administration (TGA) sets standards for medical devices and software, impacting claims processing for new treatments. Sydney and Melbourne are focal points for health IT startups specializing in claims optimization.
India
India's privatizing healthcare sector presents an underpenetrated market for outsourced revenue cycle management services. The National Health Authority (NHA) promotes digital health initiatives, driving demand for compliant claims platforms. Bengaluru and Hyderabad emerge as key centers for developing scalable healthcare BPO and IT solutions.
Global Healthcare Claims Management Market Key Industry Players
Strategic partnerships dominate the current landscape, as vendors seek to offer integrated solutions across the healthcare revenue cycle. The market exhibits a consolidating structure, moving from fragmented point solutions to comprehensive, end-to-end platforms. Three strategic archetypes include integrated service providers that manage the full revenue cycle, specialized business process outsourcers for specific payer or provider needs, and enterprise technology platform vendors. Key competitive moves involve M&A activities to acquire niche capabilities and portfolio diversification to expand service offerings across the value chain.
Integrated service providers, such as Optum, leverage extensive payer-provider networks to deliver end-to-end claims management services, optimizing the entire revenue cycle. Cognizant exemplifies specialized business process outsourcing, focusing on large insurance carriers with tailored solutions for complex administrative tasks. Oracle Corporation occupies a position as an enterprise technology platform vendor, extending its robust database and cloud infrastructure to support intricate healthcare financial workflows. These companies anchor distinct segments of the market by offering varied value propositions, from comprehensive outsourcing to foundational technology.
| Leading Market Players |
|---|
| Athenahealth |
| Optum |
| Cognizant |
| Oracle Corporation |
| McKesson Corporation |
| Allscripts Healthcare Solutions |
| Cerner Corporation |
| eClinicalWorks |
| Accenture |
| Others |
Cost & Logistics Intelligence
Outsourced revenue cycle management, a key integration pattern, anchors both the service supply position and pricing power within healthcare claims. This model allows specialized vendors to achieve economies of scale, influencing cost structures for providers and payers globally.
Pricing Analysis
Service-level agreements, often bundling support and feature updates, define the pricing structure for healthcare claims management platforms. Subscription-based SaaS models dominate, offering tiered access based on claims volume and integrated functionality. Customization level and regulatory compliance features drive price differentiation for large hospital networks. Pricing softness stems from intense vendor competition, making mid-sized provider groups highly price-sensitive, while insurance carriers, requiring advanced fraud detection, exhibit lower price sensitivity.
Supply Chain Analysis
Regional data centers and cloud infrastructure, often following a hub-and-spoke pattern, form the distribution layer for claims management services. Core software development concentrates in the United States, India, and Canada, drawing from specialized AI algorithms and secure cloud computing resources. Cybersecurity threats represent a significant structural risk given the high value of protected health information. Distribution runs through direct sales teams and strategic partnerships with system integrators to reach end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
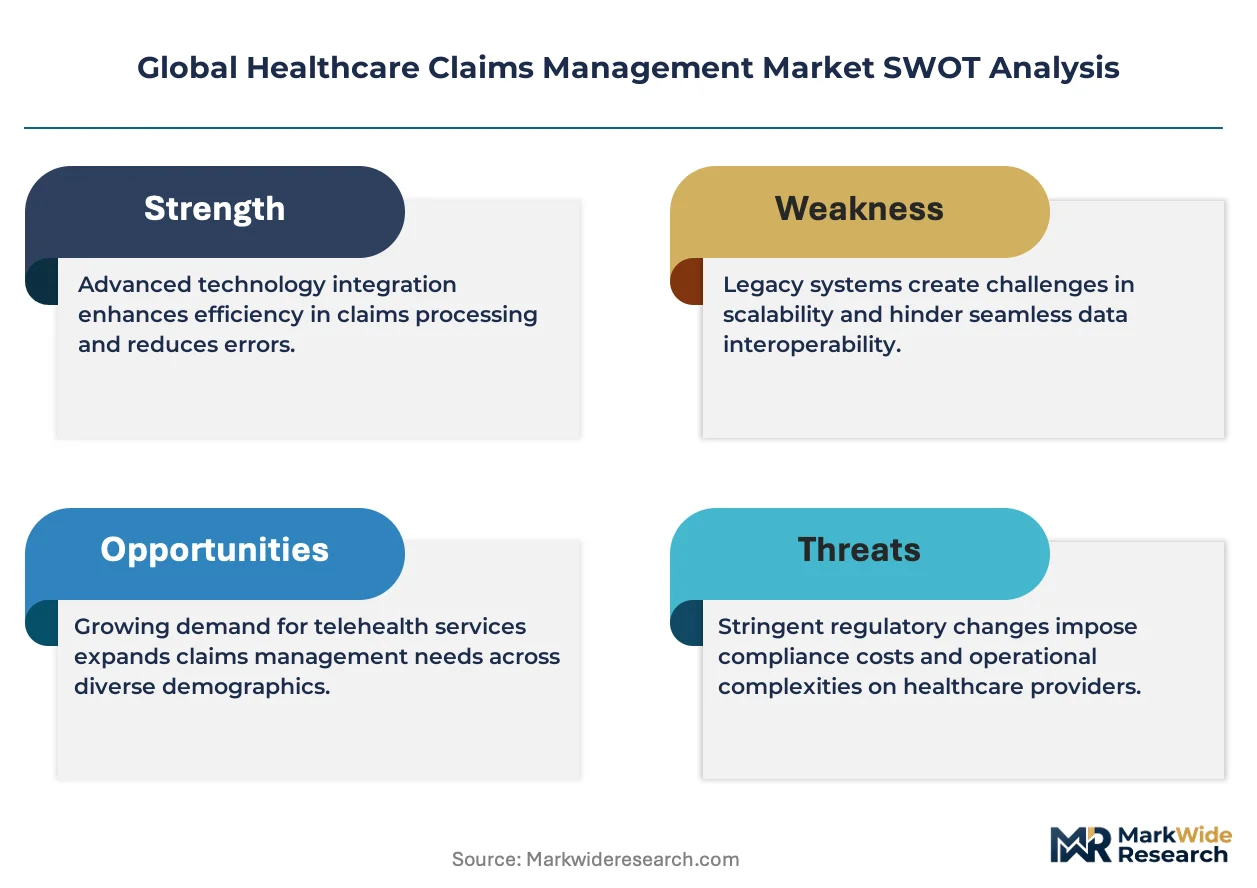
This market is fundamentally a cost-of-compliance story, where stringent regulations like HIPAA create a significant barrier-to-entry moat. Robust data security and privacy protocols are essential for market participation and competitive differentiation.
For Market Incumbents: Deepen integration with electronic health record (EHR) systems to enhance data interoperability and streamline workflows. Acquire niche AI firms specializing in predictive analytics for denial management, countering emerging entrant archetypes focused on specific revenue cycle functions. Invest in advanced cybersecurity infrastructure to mitigate the constant threat of data breaches, leveraging this as a key differentiator. This strategic capacity addition secures market share against smaller, less compliant competitors. For New Entrants and Emerging Players: Launch via strategic partnerships with medical billing companies to access a broad provider base. Focus on developing AI-powered solutions for specific, underpenetrated applications like automated appeals letter generation for small to mid-sized clinics. The denial management segment in emerging Asian markets presents a highly penetrable opportunity. Offer a value-based pricing model tied to demonstrable revenue recovery for providers. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated service providers seeking to expand their end-to-end revenue cycle management capabilities. The market exhibits strong long-term viability over the next decade due to increasing regulatory complexity and rising healthcare expenditures. Acquisition targets should be niche technology firms with proprietary AI algorithms for fraud detection or compliance automation. The widespread adoption of blockchain for claims adjudication will serve as a critical inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI-driven Fraud Detection Firm | This move enhances payer capabilities to mitigate revenue leakage from erroneous claims. |
| Partnership with Large Hospital Network | Secures long-term contracts and expands platform adoption across multiple facilities. |
| Development of Generative AI for Appeals | Automates administrative tasks, significantly reducing overhead for providers managing denials. |
| Expansion into Emerging Asian Markets | Captures underpenetrated demand for outsourced revenue cycle management services. |
| Investment in Blockchain for Adjudication | Creates immutable, transparent claims records, reducing disputes between payers and providers. |
Research Approach
Document review covered regulatory filings, industry reports, and academic journals, complemented by interviews with hospital CFOs, insurance carrier claims managers, and health-tech solution architects. This approach combined primary insights with extensive secondary validation for comprehensive data collection. Bottom-up analysis of claims volumes and top-down market sizing were triangulated for robust market estimates.
Market volume and value projections emerged from a quantitative model integrating historical performance with future growth drivers across the analysis window. Segmentation dimensions modeled included deployment type, solution type, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from a weighted average of segment-specific growth trajectories, incorporating healthcare expenditure trends and AI adoption rates as key inputs.
Evolving data privacy regulations, rapid technological advancements, and shifts in healthcare policy are the dominant revision risks for these forecasts. The projections reflect assumptions regarding market dynamics and adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Health and Medical Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
US Travel Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Art Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Bancassurance Market
Insurance
Credit Insurance Market
Insurance
Earthquake Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market