
 Critical Illness Insurance Market | 2026-2036
Critical Illness Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Illness Insurance Market Intelligence
Expansion of digital distribution channels in China is tilting the market's center of gravity toward technology-led engagement. Ping An Insurance Company of China Ltd. leverages its extensive digital ecosystem to reach new customer segments. Meanwhile, AXA SA differentiates through its focus on comprehensive wellness programs linked to its policies. Aflac Inc. sustains its market position in the United States through strong broker relationships and workplace marketing.
Critical illness insurance is a type of supplemental health coverage that pays a tax-free, lump-sum benefit upon the diagnosis of a specified serious medical condition. This financial payout is distinct from traditional health insurance and is not tied to incurred medical costs, offering policyholders flexibility. Policies covering cancer and heart attack dominate the market, reflecting their high incidence rates. Online platforms represent the fastest-growing distribution channel, particularly for individual and family policies, displacing some traditional broker-led sales.
Regulatory frameworks, such as Solvency II in Europe and rules set by the National Financial Regulatory Administration (NFRA) in China, mandate stringent capital adequacy and consumer protection standards. In the United States, state-level insurance commissions enforce policy language clarity and claims-handling procedures. Insurers must now decide how to integrate predictive analytics for risk assessment without violating emerging data privacy regulations like GDPR.
Market Dynamics
The market's central dynamic is the rapid consumerization of insurance products, driven by digital platforms that enable direct engagement and policy personalization. This shift is moving the industry away from traditional, broker-centric sales models toward a more accessible, on-demand ecosystem, particularly for individual policyholders.
Growth Catalysts
- Digital-First Distribution:The proliferation of InsurTech platforms and mobile applications simplifies policy comparison, purchase, and management, lowering barriers to entry for new customers and expanding market reach.
- Employer Benefit Expansion:Small and medium-sized enterprises in markets like the United States are increasingly offering critical illness plans as a competitive benefit to attract and retain talent in tight labor markets.
- Health Awareness in China:A growing middle class with increased disposable income and greater consciousness of health risks, amplified by public health events, is driving strong demand for supplemental health coverage in China.
Market Restraints
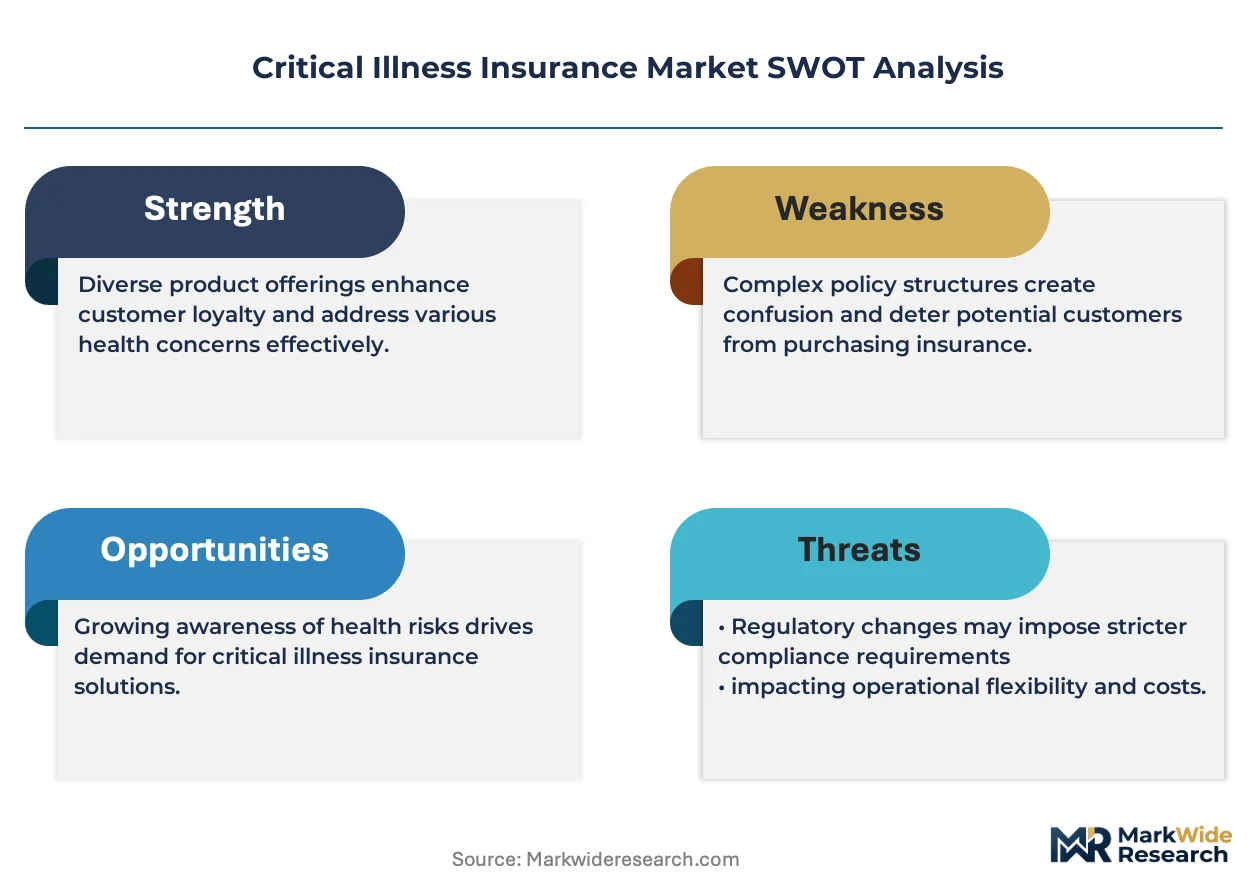
- Regulatory Complexity:A fragmented regulatory landscape, such as the state-by-state insurance commission oversight in the United States, creates high compliance costs and can slow the introduction of innovative products.
- Premium Affordability:Rising healthcare costs and improved diagnostics that increase the incidence of claims exert upward pressure on premiums, potentially making policies unaffordable for lower-income segments.
- Product Misunderstanding:A persistent lack of consumer understanding about how critical illness insurance differs from traditional health or disability insurance can lead to low uptake and sales friction.
Strategic Opportunities
- Wellness-Integrated Policies:Insurers can develop products that integrate with wearable technology and health apps, offering premium discounts or rewards for preventative behaviors and healthy lifestyles.
- Gig Economy Solutions:Designing flexible, portable critical illness policies tailored to the needs of independent contractors and gig economy workers represents a significant, underserved market segment.
- Underpenetrated Asian Markets:Beyond China, emerging economies in Southeast Asia with rising incomes and low insurance penetration offer substantial greenfield opportunities for expansion.
Industry Challenges
- Data Privacy Compliance:Insurers face a significant challenge in leveraging personal health data for underwriting and risk modeling while adhering to stringent data privacy regulations like GDPR and various state-level laws.
- Legacy System Integration:Established insurers often struggle with the technical and financial burden of integrating modern, agile InsurTech platforms with their decades-old, inflexible core administrative systems.
- Claims Adjudication Complexity:Defining and verifying diagnoses for an expanding list of covered critical illnesses can lead to disputes and reputational risk, requiring clear policy language and robust medical review processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Illness Insurance Market |
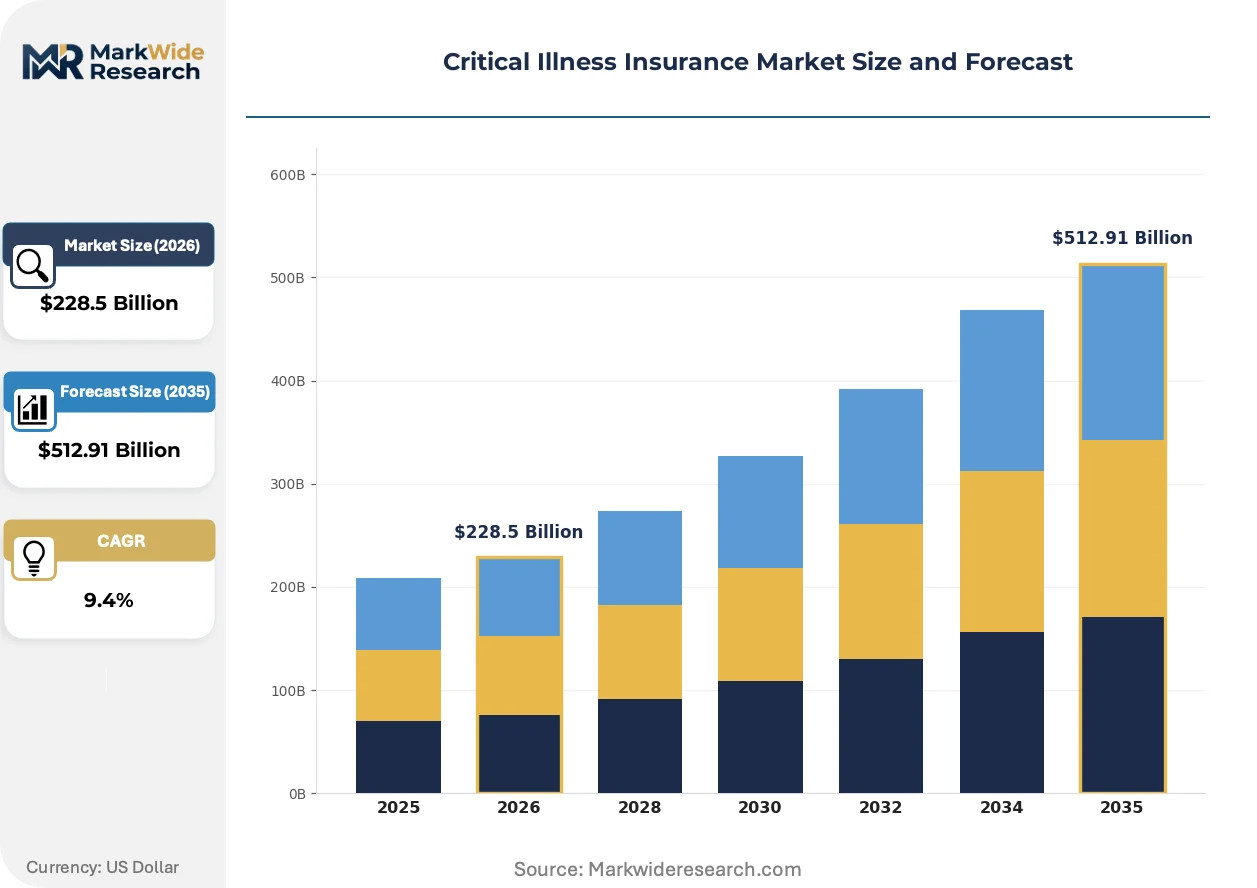
| Market Size in 2026 | $228.5 Billion |
| Market Size in 2035 | $512.91 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Individual, Family, Group, Key Person, Return of Premium Covered Conditions: Cancer, Stroke, Heart Attack, Kidney Failure, Multiple Sclerosis, Organ Transplant Distribution Channel: Direct Sales, Insurance Brokers, Banks, Online Platforms, Financial Advisors Customer Type: Salaried Employees, Small Businesses, Senior Citizens, Freelancers, High Net Worth Individuals |
| Companies Covered | Aflac Inc., AXA SA, China Life Insurance Company Limited, Sun Life Financial Inc., Aegon NV, Allianz SE, MetLife Inc., Prudential plc, Ping An Insurance Company of China Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Illness Insurance Market Strategic Shifts & Innovations
Personalization is fundamentally altering product design and underwriting, as insurers move from standardized group policies to data-informed, individualized coverage. This evolution is powered by advanced analytics and a deeper integration of technology into the customer lifecycle, from initial risk assessment to claims processing.
AI-Powered Underwriting
Artificial intelligence engines use machine learning to analyze diverse data points for highly accurate, real-time risk assessment. InsurTech firms and progressive incumbents are rapidly adopting this for individual and family policy applications. This automated, data-centric approach is rendering obsolete the slow, manual, and often inconsistent underwriting processes that have long characterized the industry.
Regulatory Risk Modeling
Europe's Solvency II framework mandates stringent capital adequacy and enterprise risk management standards for insurers. The regulation forces companies to maintain sufficient capital reserves to cover unexpected losses, directly impacting product pricing and investment strategies. Insurers in the European Union must continuously refine their internal risk models, affecting the design and availability of high-risk critical illness products.
Direct-to-Consumer Channel Shift
A notable behavioral change is the consumer preference for researching and purchasing policies directly through digital channels. This trend is disrupting the traditional agent-led distribution model, which is ceding ground to online comparison websites and direct insurer portals. The move to direct-to-consumer is most pronounced for individual policies in technologically advanced markets like South Korea and China.
Critical Illness Insurance Market Segmentation
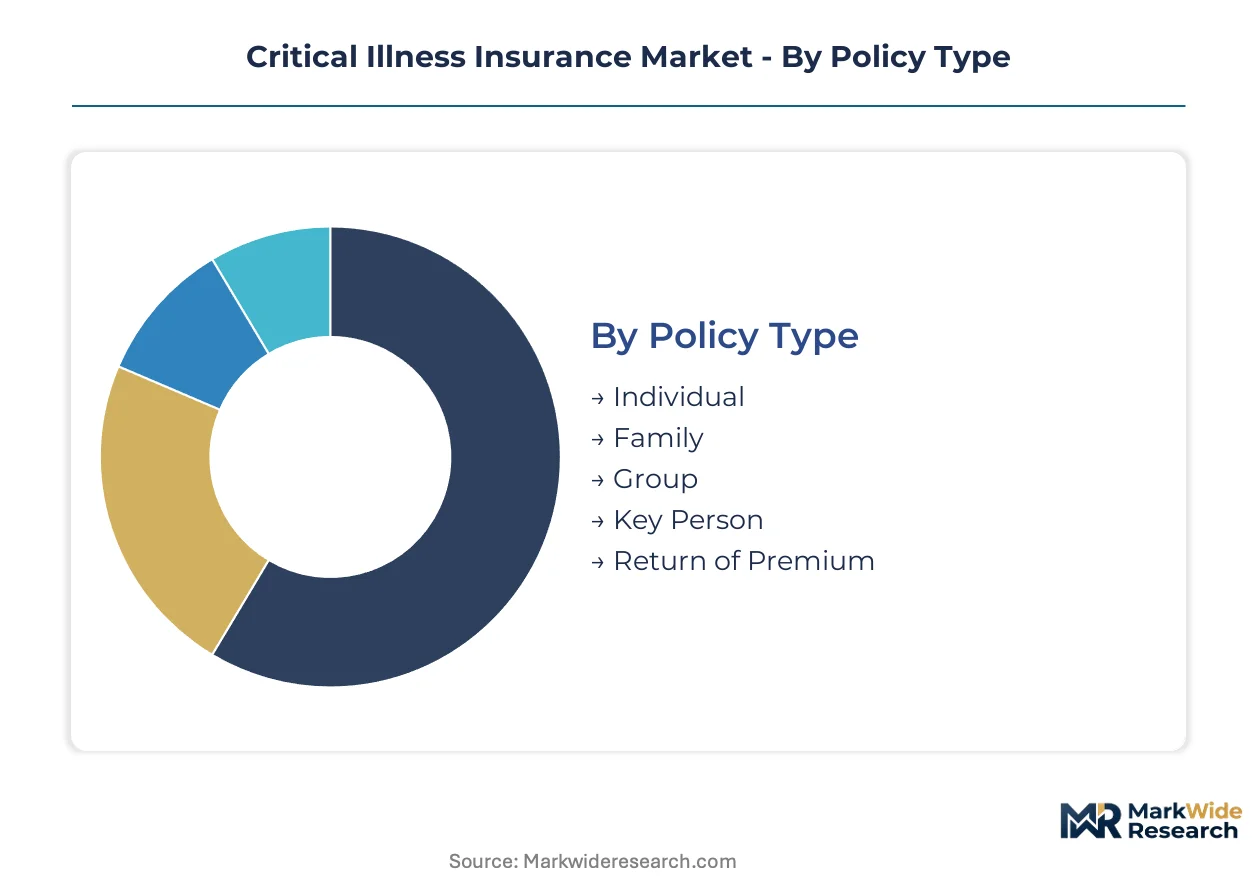
Segmentation provides a granular view of the Critical Illness Insurance Market, revealing specific growth avenues and areas of concentrated demand. Understanding these distinct segments allows insurers to tailor products and refine distribution strategies effectively. This analysis highlights how different market components contribute to overall industry expansion and innovation.
Policy Type:
The policy type segmentation highlights how different critical illness products respond to varying durations of coverage needs and renewal cycles within the market.
- Individual:These policies provide a lump-sum benefit directly to a single policyholder upon diagnosis of a covered condition. Demand for individual policies is concentrating in markets like China, driven by expanding health awareness and the availability of direct-to-consumer digital platforms.
- Family:Family policies extend coverage to multiple members of a household under a single plan, streamlining administration for policyholders.
- Group:Group policies are typically employer-sponsored benefits, offering coverage to multiple employees under a master contract. Small businesses in the United States are increasingly adopting group critical illness plans to enhance their competitive employee benefits packages.
- Key Person:Key Person policies protect businesses against financial losses incurred if a crucial employee suffers a critical illness, impacting company operations.
- Return of Premium:These policies offer a refund of premiums paid if no claim is made by the end of the policy term, appealing to risk-averse consumers.
Group policies anchor the volume base while Individual policies gain share at the steepest rate.
Covered Conditions:
The array of covered conditions reflects the varying prevalence and severity of illnesses that drive consumer concern and policy uptake.
- Cancer:This segment covers various forms of malignant tumors, representing a significant portion of critical illness claims due to its high incidence. Demand is substantial across all demographics, particularly as improved diagnostics increase early detection rates.
- Stroke:Stroke coverage provides a benefit for a cerebrovascular event causing permanent neurological deficit, a common and debilitating condition.
- Heart Attack:Heart attack coverage provides a lump-sum payout following a myocardial infarction, a leading cause of critical illness claims globally. Its high incidence rate and associated medical costs make it a primary concern for policyholders in many markets.
- Kidney Failure:Policies covering kidney failure provide benefits for end-stage renal disease requiring dialysis or transplantation, addressing a chronic and costly condition.
- Multiple Sclerosis:Multiple Sclerosis coverage addresses this chronic, progressive neurological disease, offering financial support for long-term care needs.
- Organ Transplant:Organ transplant policies provide funds for the medical expenses and recovery period associated with receiving a major organ transplant.
Cancer and Heart Attack coverage represent the highest claim frequency, influencing premium structures across the market.
Distribution Channel:
Distribution channel segmentation illustrates the evolving preferences for customer interaction and the reach of different sales models.
- Direct Sales:Direct sales involve insurers selling policies directly to consumers through their own agents or call centers, maintaining direct customer relationships.
- Insurance Brokers:Insurance brokers act as intermediaries, offering expert advice and comparing policies from multiple providers to clients. Strong broker relationships remain critical for market position in the United States, particularly for Aflac Inc.
- Banks:Banks distribute critical illness policies as part of their bancassurance strategies, leveraging existing customer relationships and trust.
- Online Platforms:Online platforms facilitate policy comparison, purchase, and management through digital interfaces, offering convenience and accessibility. This channel represents the fastest-growing distribution channel, particularly for individual and family policies.
- Financial Advisors:Financial advisors integrate critical illness insurance into broader financial planning services, guiding clients on comprehensive risk management.
Online Platforms offer unparalleled reach and efficiency, while Insurance Brokers maintain a critical role in complex policy sales.
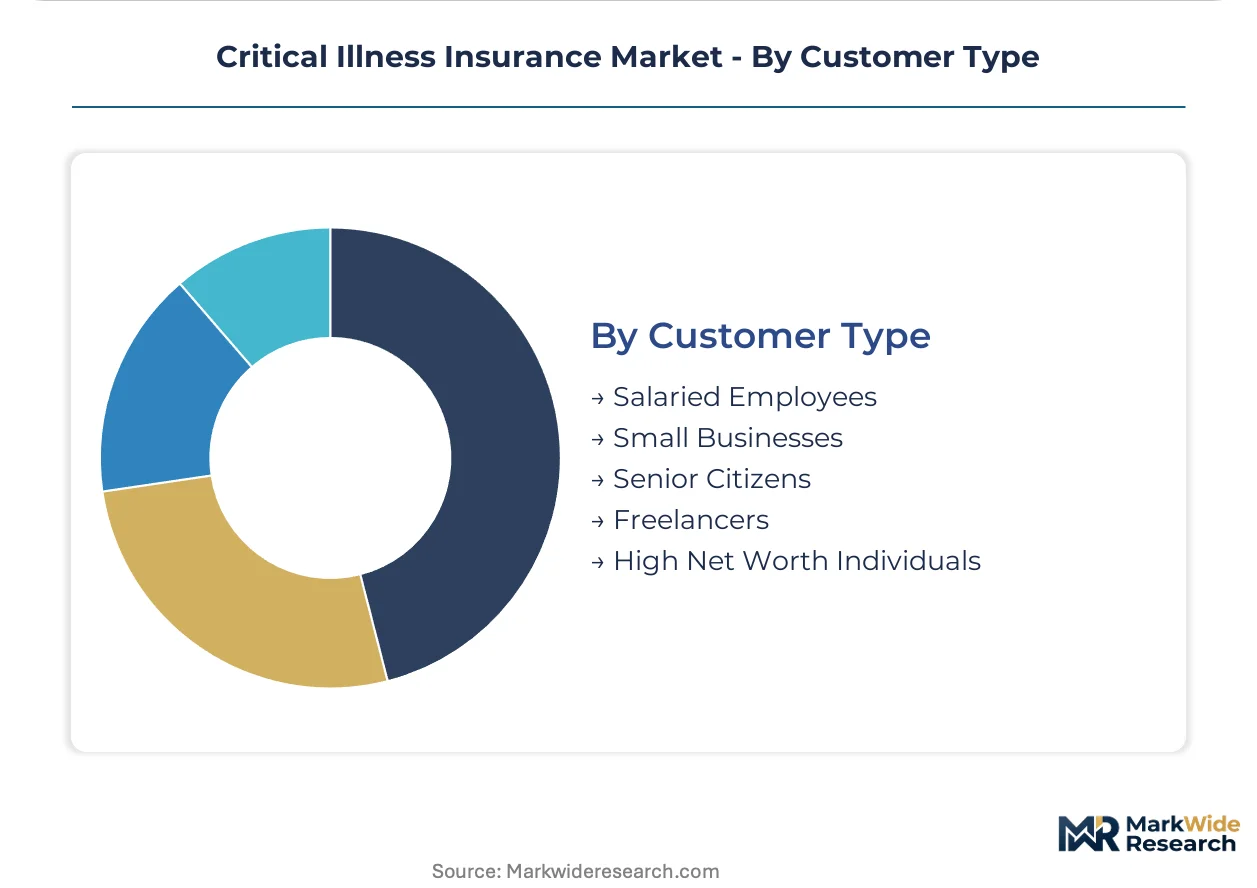
Customer Type:
Customer type segmentation highlights the diverse financial protection needs and purchasing power across different demographic and professional groups.
- Salaried Employees:Salaried employees often receive critical illness coverage as part of employer-sponsored group benefits, reducing individual purchasing effort.
- Small Businesses:Small businesses increasingly offer critical illness plans as a competitive employee benefit, attracting and retaining talent in tight labor markets. This segment drives significant growth in the United States market.
- Senior Citizens:Senior citizens seek critical illness coverage to mitigate health-related financial risks in later life, often focusing on conditions prevalent in older age groups.
- Freelancers:Freelancers and gig economy workers require flexible, portable critical illness policies to secure financial stability without employer-provided benefits. This represents a significant underserved market segment with high growth potential.
- High Net Worth Individuals:High Net Worth Individuals utilize critical illness policies for wealth preservation and tax-efficient lump-sum payouts, often as part of sophisticated financial planning.
Small Businesses demonstrate high responsiveness to competitive benefit offerings, while Freelancers present a significant opportunity for tailored product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital distribution channels underwrite the market's global reach, enabling insurers to connect with diverse customer segments efficiently. These technology-led platforms facilitate easier access and policy management across various geographies. Such infrastructure supports the rapid consumerization of insurance products, driving expansion globally.
China
Expanding health awareness among China's growing middle class drives significant demand for critical illness policies. The National Financial Regulatory Administration (NFRA) mandates stringent capital adequacy and consumer protection standards. Ping An Insurance leverages its digital ecosystem to reach new customer segments in major urban centers like Shanghai and Beijing.
United States
Small businesses in the United States increasingly offer critical illness plans as competitive employee benefits. State-level insurance commissions enforce policy language clarity and claims-handling procedures. Aflac Inc. sustains its market position through strong broker relationships and workplace marketing across key industrial states.
Germany
European demand benefits from a focus on comprehensive wellness programs linked to policies. Solvency II mandates stringent capital adequacy and enterprise risk management standards for insurers. Major insurers in financial hubs like Frankfurt continuously refine internal risk models affecting product design. This regulatory environment influences the availability of high-risk critical illness products.
India
Rising incomes and low insurance penetration in India present substantial greenfield opportunities for expansion. The IRDAI (Insurance Regulatory and Development Authority of India) governs the insurance sector, promoting market development. Digital-first platforms are gaining traction, especially in metropolitan hubs such as Mumbai and Bangalore.
Critical Illness Insurance Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing specialized risk assessment tools. The critical illness insurance market exhibits a tiered structure, with large multinational insurers competing alongside agile InsurTech firms. Key archetypes include established players leveraging extensive broker networks and digital-first providers focusing on direct-to-consumer channels. Dominant competitive moves involve strategic partnerships for technology integration and geographic expansion into underpenetrated markets.
Within the established insurer archetype, Aflac Inc. anchors its market presence in the United States through strong broker relationships and workplace marketing. AXA SA, a global insurance group, exemplifies a strategy focused on comprehensive wellness programs linked to its policies, particularly in European markets. Ping An Insurance Company of China Ltd. occupies a position as a technology-led insurer, leveraging its extensive digital ecosystem to reach new customer segments in China. These companies collectively illustrate the diverse approaches to market penetration and customer engagement.
| Leading Market Players |
|---|
| Aflac Inc. |
| AXA SA |
| China Life Insurance Company Limited |
| Sun Life Financial Inc. |
| Aegon NV |
| Allianz SE |
| MetLife Inc. |
| Prudential plc |
| Ping An Insurance Company of China Ltd. |
| Others |
Cost & Logistics Intelligence
Data privacy compliance, mandated by regulations like GDPR and state-level laws, significantly determines both pricing tier spreads through risk assessment constraints and the shape of the insurance supply chain by dictating data flows.
Pricing Analysis
Volume-based discounts characterize group critical illness policies, while individual premiums are tiered by risk. Underwriting risk assessment, considering factors like age and health history, drives significant price differentiation. Rising healthcare costs and improved diagnostics exert upward pressure on premiums across all segments. Lower-income segments exhibit high price sensitivity, whereas High Net Worth Individuals prioritize comprehensive coverage over cost.
Supply Chain Analysis
Digital platform integrators, particularly those specializing in InsurTech solutions, concentrate core processing capacity for critical illness insurance. The supply chain draws from technology hubs in the United States and China, which develop advanced analytics tools. Health data, actuarial models, and AI algorithms serve as key dependencies. Data privacy compliance presents a structural risk, particularly with cross-border data transfers. Distribution runs through online platforms and traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The critical illness insurance market presents a defensive-moat story, primarily justified by significant regulatory entrenchment that creates high barriers to entry for new players.
For Market Incumbents: Insulate existing customer bases by integrating comprehensive wellness programs directly into policy offerings. Acquire agile InsurTech firms to modernize legacy systems and enhance digital distribution capabilities. This defends against rapid consumerization of products by digital-first players. Strategic partnerships for technology integration serve as a vital lever.
For New Entrants and Emerging Players: The underserved gig economy workers in technologically advanced markets represent a penetrable entry point. Underpenetrated Asian markets beyond China offer significant greenfield opportunities. Focus on flexible, portable policies with simplified digital onboarding as a key go-to-market angle. Tailored solutions for specific professional groups can build early market share.
For Investors and Strategic Acquirers: Niche InsurTech platforms specializing in predictive analytics or direct-to-consumer distribution represent attractive acquisition targets. The market offers stable, long-term growth prospects over a five to ten-year window. Increased regulatory harmonization across major markets serves as a key signal to watch for accelerated expansion. Consolidation opportunities will emerge as smaller players seek scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Ecosystem Integration | Ping An Insurance leverages its digital ecosystem to reach new customer segments in China. |
| Wellness Program Development | AXA SA differentiates through comprehensive wellness programs linked to its critical illness policies. |
| InsurTech Acquisition | Established insurers can modernize legacy systems and enhance digital capabilities through targeted acquisitions. |
| Gig Economy Product Launch | Designing flexible policies for independent contractors addresses a significant underserved market segment. |
| Asia-Pacific Market Expansion | Emerging economies in Southeast Asia offer substantial greenfield opportunities due to rising incomes. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through extensive research. Key stakeholders included insurance executives, InsurTech founders, brokers, and financial advisors. Secondary data sources comprised regulatory filings from bodies like the NFRA, Solvency II reports, and financial news archives. Bottom-up market sizing was cross-referenced with top-down economic indicators for robust triangulation.
Macroeconomic indicators, evolving regulatory frameworks, and technological advancements were considered as forecast inputs. The analytical framework integrated historical performance data across the analysis window. Segmentation dimensions modeled included policy type, covered conditions, distribution channel, and customer type. Compound annual growth rates were derived from a multi-variant regression model, incorporating health awareness trends and InsurTech investment levels.
Practitioners should monitor shifts in global economic stability and major regulatory changes for early signals. Forecasts reflect assumptions regarding consumer behavior and technological adoption across the projection horizon. Geopolitical events or new public health crises represent risk factors that could necessitate revisions. Quarterly review of global health indices and insurance policy uptake rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Business Income Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Global Fine Art Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
AI in Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Travel Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Takaful Market