
 Saudi Arabia Cash Management Services Market | 2026-2036
Saudi Arabia Cash Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cash Management Services Market Insights
Modular bundling of payment processing with fraud prevention and reconciliation is rebalancing buyer choice toward integrated suites rather than standalone modules. NCR Corporation leverages its ATM and software portfolio to anchor enterprise relationships across the Kingdom. Diebold Nixdorf competes through hardware-software convergence in branch transformation. GRG Banking Equipment specializes in cost-optimized cash handling systems for mid-tier financial institutions.
Cash management services encompass the operational infrastructure, software platforms, and outsourced processes that corporations and financial institutions use to optimize liquidity, control disbursements, accelerate collections, and mitigate settlement risk. These services rely on real-time data feeds, automated clearing house protocols, and AI-driven forecasting algorithms to maintain target balance positions and reduce idle cash. Payment Processing and Reconciliation Services dominate current revenue pools, reflecting the volume intensity of SAR-denominated transactions and regulatory reporting requirements. Cloud-Based delivery models represent the fastest-expanding segment, as SAMA-aligned institutions pursue elastic infrastructure and reduced capital deployment.
SAMA, the central bank, enforces payment system oversight and cybersecurity standards that shape vendor qualification and data residency requirements for cash management providers. The Saudi Data and Artificial Intelligence Authority complements this framework with cloud governance rules affecting where transaction data resides and how AI analytics process sensitive financial information. Stakeholders must monitor how open banking API standards and real-time gross settlement integration reshape interoperability expectations between banks and their corporate clients.
Market Dynamics
SAMA's real-time payment mandates and open banking API standards are forcing wholesale infrastructure replacement across Saudi financial institutions, compressing procurement cycles and privileging vendors with integrated platform architectures over point-solution specialists.
Growth Catalysts
- SAMA Instant Payment System (SIPS):The central bank's real-time gross settlement mandate requires banks to modernize legacy payment rails, creating immediate demand for API-enabled cash management platforms that interoperate with corporate ERP systems.
- Corporate treasury centralization:Saudi conglomerates consolidating regional liquidity operations are selecting vendors offering multi-bank connectivity and automated cash positioning across Riyadh, Jeddah, and Dammam operations.
- AI-driven forecasting modules:Machine learning algorithms predicting intraday liquidity gaps are automating previously manual treasury functions, reducing working capital buffers and justifying platform investments.
Market Restraints
- Data residency compliance costs:SAMA and SDAIA cloud governance rules mandating local transaction data storage impose infrastructure duplication expenses that disadvantage smaller foreign vendors without Saudi-based data centers.
- Concentrated banking sector:The dominance of four major domestic banks in corporate relationships limits fintech challenger access to primary cash management contracts and constrains price competition.
- Legacy core system interdependence:Decades-old mainframe architectures at established banks create technical debt that slows API-based platform integration and extends implementation timelines.
Strategic Opportunities
- Eastern Province industrial corridor:Jubail and Ras Al-Khair manufacturing clusters remain underserved by sophisticated treasury services, offering first-mover advantage to platforms targeting petrochemical and mining supply chain finance.
- Islamic liquidity management instruments:Integration of Sharia-compliant short-term investment vehicles with operational cash pools addresses unmet demand from Islamic banking windows and fully Sharia-compliant institutions.
- Embedded finance convergence:Partnerships between cash management providers and ERP vendors are creating pre-integrated treasury modules that reduce implementation friction for mid-market Saudi enterprises.
Industry Challenges
- API standardization gaps:Inconsistent implementation of SAMA's open banking technical specifications across domestic banks forces vendors to maintain multiple integration layers, inflating development costs.
- Cybersecurity certification timelines:SAMA's stringent vendor security assessment procedures extend sales cycles by six to twelve months, compressing revenue recognition windows for platform providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cash Management Services Market |
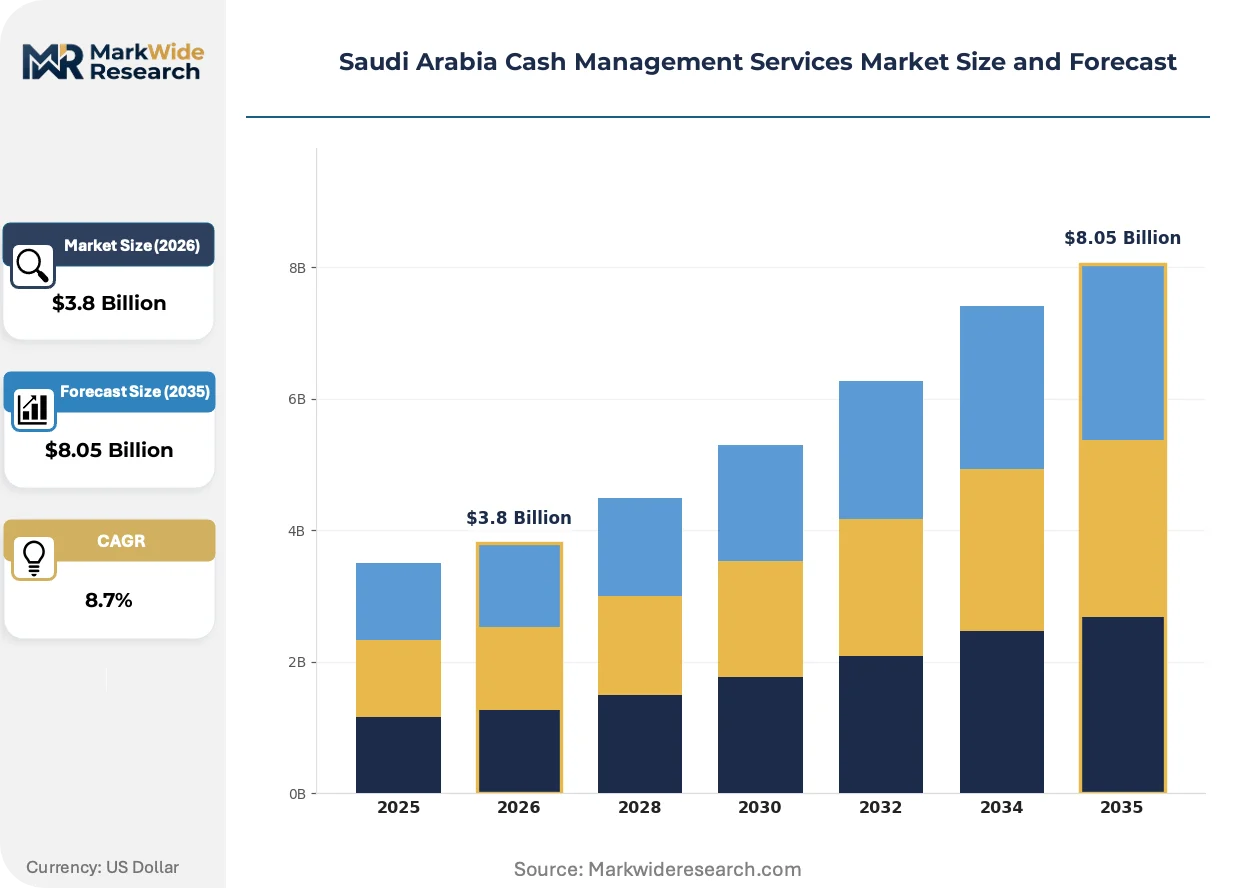
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Fraud Prevention, Cash Vaulting, Reconciliation Services End User: Corporations, Small Businesses, Government Entities, Financial Institutions Delivery Model: On-Premises, Cloud-Based, Hybrid, Mobile Access Technology: Automated Clearing House, Real-Time Gross Settlement, Blockchain, AI Analytics |
| Companies Covered | NCR Corporation, Diebold Nixdorf, GRG Banking Equipment, Hyosung TNS, Abana Enterprises Group, Hamrani Universal Company, G4S Al Majal, BRINKS, Sanid Organization, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cash Management Services Market Trends and Innovations
Intelligent automation and regulatory technology are converging to transform how Saudi institutions manage liquidity, with vendor competition shifting from feature breadth to real-time processing latency and predictive accuracy.
Machine learning-powered cash forecasting is automating working capital optimization for Saudi corporate treasuries. Large conglomerates in Riyadh are deploying these tools to reduce idle cash buffers by predicting intraday funding requirements with greater precision. The technology is automating previously manual spreadsheet-based forecasting processes, compressing the role of traditional treasury workstations.
SAMA's open banking framework is mandating standardized API access for third-party cash management providers. This regulatory architecture is dismantling proprietary bank-client data silos and enabling multi-bank aggregation platforms. Domestic banks are responding by accelerating internal API modernization to retain corporate relationships against fintech challengers.
Mid-market enterprises are consolidating vendor relationships around integrated suites rather than standalone modules. Saudi family-owned conglomerates in Jeddah are selecting platforms combining payments, reconciliation, and forecasting to reduce integration overhead. This concentration pattern favors established providers with broad functional coverage over specialized point-solution vendors.
Saudi Arabia Cash Management Services Market Segmentation
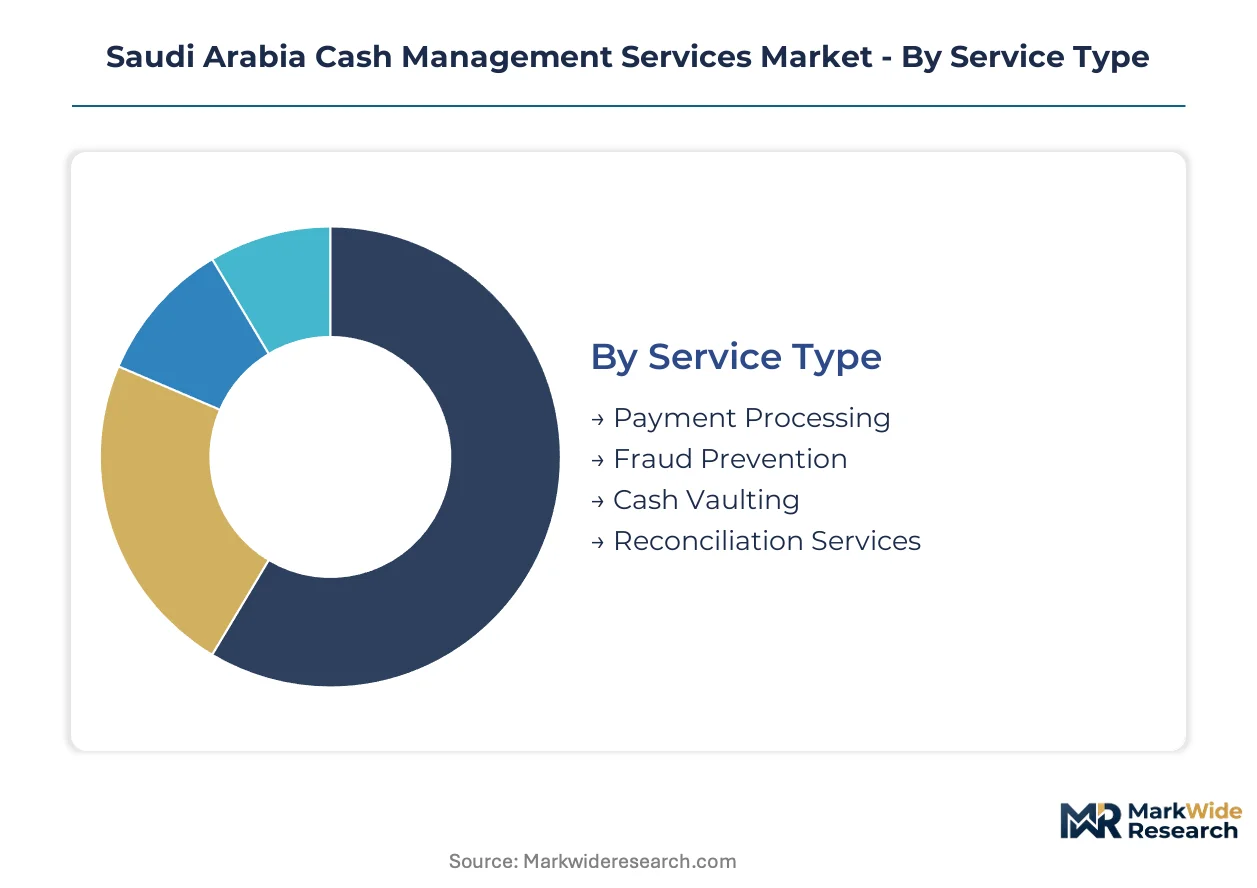
Segmentation in Saudi Arabia's cash management services market reveals how SAMA's regulatory mandates and corporate treasury modernization priorities are reshaping vendor strategies across service delivery models and technology stacks.
Service Type:
Functional specialization within service portfolios determines competitive positioning as Saudi institutions prioritize integrated platforms over fragmented point solutions.
- Payment Processing:High-volume SAR transaction routing through SAMA Instant Payment System rails dominates revenue pools. Corporate treasuries in Riyadh are consolidating around API-enabled disbursement engines that interoperate with ERP systems to reduce manual intervention.
- Fraud Prevention:Behavioral analytics and real-time transaction monitoring modules address escalating cybersecurity threats. SAMA's stringent vendor certification requirements are concentrating procurement among providers with dedicated Saudi-based security operations centers.
- Cash Vaulting:Physical cash handling infrastructure for retail banking networks and ATM replenishment.
- Reconciliation Services:Automated matching engines for multi-bank statement aggregation and exception management.
Payment Processing leads on scale; Fraud Prevention leads on momentum.
End User:
Customer scale and regulatory complexity create distinct procurement patterns across the Saudi institutional landscape.
- Corporations:Large conglomerates operating across Riyadh, Jeddah, and Dammam demand multi-entity liquidity visibility. Treasury centralization mandates from headquarters are driving adoption of automated cash positioning and intraday forecasting tools.
- Financial Institutions:Domestic banks face the most intense SAMA compliance pressure for real-time payment modernization. Legacy core system constraints at these institutions extend implementation timelines for API-based platforms.
- Government Entities:Public sector procurement of centralized disbursement and collection services.
- Small Businesses:Mobile-first cash management adoption among family-owned enterprises in Jeddah's trading sector.
Corporations anchor current revenue; Financial Institutions drive platform upgrade cycles.
Delivery Model:
Infrastructure deployment choices reflect trade-offs between data sovereignty compliance and operational flexibility.
- Cloud-Based:Elastic infrastructure with SAMA-aligned data residency configurations is expanding most quickly. SDAIA governance rules mandating local transaction storage are forcing hyperscaler partnerships with Saudi-based facilities.
- Hybrid:Split architectures separating sensitive payment data on-premises from analytics workloads in cloud environments. Mid-tier banks prefer this model to balance compliance with cost reduction targets.
- On-Premises:Legacy deployments at institutions with mainframe-dependent core banking systems.
- Mobile Access:Smartphone-based treasury dashboards for executive approval workflows and exception alerts.
Cloud-Based delivery climbs the fastest; Hybrid architectures capture transitional demand.
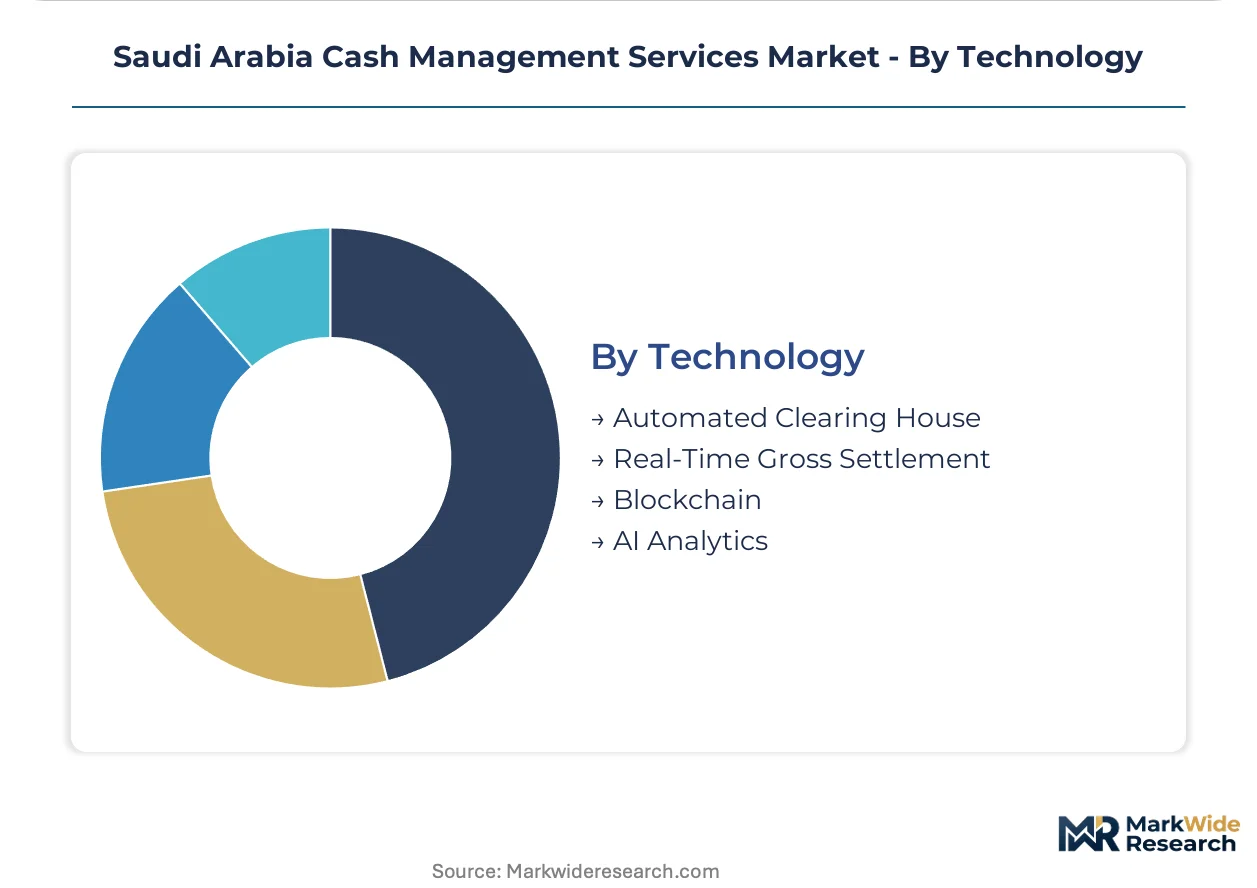
Technology:
Underlying protocol selection determines interoperability scope and settlement finality guarantees.
- Real-Time Gross Settlement:SAMA's SIPS mandate requires immediate funds availability with intraday finality. Corporate treasuries are reconfiguring liquidity buffers around instant settlement capabilities to reduce overnight funding costs.
- AI Analytics:Machine learning models predicting cash flow gaps and automating investment sweep decisions. Saudi conglomerates deploying these tools report reduced idle cash positions and improved working capital efficiency.
- Automated Clearing House:Batch processing infrastructure for recurring payroll and supplier payments.
- Blockchain:Distributed ledger pilots for trade finance reconciliation and cross-border correspondent banking.
Real-Time Gross Settlement dominates transaction volume; AI Analytics gains share fastest in new implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cash management services in Saudi Arabia trace their modern infrastructure to the 1980s banking expansion centered on Riyadh and Jeddah, when SAMA established the regulatory framework that now underpins real-time payment modernization.
Riyadh
Riyadh hosts the headquarters of Saudi National Bank and Al Rajhi Bank, driving concentrated procurement of treasury management platforms. SAMA's regulatory directives emanate from the capital, accelerating compliance-driven technology upgrades. King Abdullah Financial District anchors fintech innovation clusters where corporate treasuries pilot AI-driven cash forecasting tools.
Eastern Province
Jubail and Ras Al-Khair industrial zones generate specialized demand for supply chain finance and petrochemical-sector liquidity solutions. SABIC and Aramco subsidiaries mandate multi-currency cash pooling across hydrocarbon operations. The Dammam metropolitan corridor remains underserved by sophisticated treasury services compared to Riyadh-Jeddah infrastructure density.
Western Region
Jeddah's commercial trading heritage sustains family-owned conglomerate demand for Islamic liquidity management instruments. The Red Sea port logistics cluster requires integrated payment-reconciliation suites for import-export financing. Makkah and Madinah pilgrimage economies create seasonal cash handling volume spikes requiring elastic infrastructure.
NEOM Northwest
The giga-project's zero-carbon industrial city mandates green financing-aligned cash management architectures from inception. NEOM's digital-first regulatory sandbox permits experimental treasury technologies prohibited in conventional banking zones. The Oxagon industrial zone attracts vendors offering cloud-native platforms without legacy system interdependencies.
Saudi Arabia Cash Management Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth, with API-enabled platform vendors commanding pricing power over standalone hardware suppliers. The vendor base stratifies into three tiers: multinational technology conglomerates with full-stack capabilities, regional system integrators with SAMA compliance expertise, and specialized hardware fabricators competing on equipment cost. Strategic archetypes include integrated platform providers, ATM-centric hardware-software convergers, and cost-optimized cash handling specialists. Dominant competitive moves encompass hyperscaler partnerships for cloud data residency and embedded finance alliances with ERP vendors.
Within the integrated platform tier, NCR Corporation and Diebold Nixdorf represent multinational incumbents leveraging hardware portfolios to anchor enterprise relationships. GRG Banking Equipment occupies a position exemplifying cost-optimized specialization for mid-tier financial institutions. These three anchors illustrate the competitive spectrum from full-stack convergence to targeted equipment supply.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| GRG Banking Equipment |
| Hyosung TNS |
| Abana Enterprises Group |
| Hamrani Universal Company |
| G4S Al Majal |
| BRINKS |
| Sanid Organization |
| Others |
Pricing and Supply Chain Analysis
Corporate treasury departments at Saudi conglomerates anchor procurement decisions, concentrating buying power around integrated platform vendors and compressing margins for standalone module providers. SAMA's compliance mandates elevate total cost of ownership calculations, privileging vendors with local data residency infrastructure over low-cost foreign alternatives.
Pricing Analysis
Subscription-tiered SaaS models dominate enterprise cash management contracts, with annual recurring revenue structures replacing perpetual licensing. Price differentiation rests on API integration depth and SAMA cybersecurity certification status, with certified providers commanding premiums. Cost compression in the mid-market tier intensifies as regional system integrators bundle implementation services below multinational rates. Small family-owned conglomerates in Jeddah exhibit highest price sensitivity, while Riyadh-headquartered banking groups prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Freight costs for ATM hardware and cash handling equipment from manufacturing centers in China, South Korea, and Germany feed into landed cost calculations for Saudi deployments. Cloud infrastructure dependencies draw from hyperscaler facilities in the UAE, Singapore, and domestic Saudi data centers under SDAIA governance. Single-source vulnerability concentrates in specialized encryption chipsets required for SAMA-compliant payment terminals. Distribution runs through Riyadh-based system integrators with SAMA audit clearance, extending fulfillment timelines for non-certified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMA's Instant Payment System mandate operates as a regulatory compounder, forcing infrastructure replacement cycles that expand addressable market size for compliant platform vendors.
For Market Incumbents: Cement enterprise relationships by embedding AI-driven forecasting modules into existing treasury platforms before fintech challengers achieve SAMA certification. Deepen backward integration into local data center operations to satisfy SDAIA residency requirements without hyperscaler margin sharing. Defensive priority: lock in multi-year contracts with Saudi National Bank and Al Rajhi Bank before open banking APIs democratize bank connectivity. For New Entrants and Emerging Players: Begin with Eastern Province industrial corridors where Jubail petrochemical complexes remain underserved by sophisticated treasury services. Target mid-market family conglomerates in Jeddah's trading sector with pre-integrated ERP-cash management bundles that reduce implementation friction. Go-to-market angle: partner with SAP or Oracle implementation partners for embedded finance distribution. For Investors and Strategic Acquirers: Regional system integrators with SAMA compliance expertise and existing hyperscaler partnerships are the most active acquirer category in this space. Long-term viability rests on regulatory moat durability rather than technology differentiation alone. Acquisition target archetype: mid-tier cash handling equipment vendors with established Saudi maintenance networks and dormant API development capabilities. Signal to watch: SAMA acceleration of open banking standard enforcement that would erode incumbent bank-vendor exclusivity arrangements.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Partnership for Data Residency | SDAIA-compliant local cloud infrastructure satisfies transaction storage mandates without capital-heavy facility builds. |
| ERP Embedded Finance Alliance | Pre-integrated treasury modules reduce implementation friction for mid-market Saudi family conglomerates. |
| SAMA Cybersecurity Certification Investment | Certified vendor status compresses sales cycles and unlocks primary banking relationships. |
| AI Forecasting Module Development | Machine learning liquidity prediction justifies platform premiums through working capital efficiency gains. |
| Eastern Province Geographic Expansion | Jubail and Ras Al-Khair industrial zones offer first-mover advantage in petrochemical supply chain finance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork encompassed treasury managers at Saudi conglomerates, SAMA regulatory affairs officers, platform engineering leads at domestic banks, and procurement directors at ATM fleet operators. Secondary validation drew from SAMA payment system circulars, SDAIA cloud governance frameworks, SEC filings of listed banking groups, and hyperscaler Saudi facility announcements. Bottom-up transaction volume estimates triangulated against top-down banking sector IT spending allocations.
Segment-weighting approaches applied differential growth assumptions across service delivery models and end-user categories. The analytical framework modeled cloud adoption velocity, corporate treasury centralization patterns, and real-time payment infrastructure deployment across the projection horizon. CAGRs derived from regression analysis of historical SAMA payment statistics and vendor revenue disclosures. Industry-specific inputs included SIPS transaction volume trajectories and open banking API implementation timelines.
Several conditions sit outside the modeled scope, including potential SAMA relaxation of data residency requirements, geopolitical disruption to hyperscaler Gulf operations, and macroeconomic shocks affecting Saudi corporate capital expenditure cycles. Forecasts reflect assumptions about regulatory enforcement consistency and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Cross-Border Payment Platform Market
Payments
Qatar Payments Market
Payments
Europe Gift Card and Incentive Card Market
Payments
India Payments Market
Payments
GCC Payment Gateway Market
Payments
Third Party Payment Market
Payments
Digital Payment Market
Payments
Southeast Asia POS Terminal Market
Payments
Global Prepaid Cards Market
Payments
Mobile Payment Data Protection Market
Payments
Global Telecom Billing Market
Payments
Gift Card and Incentive Card Market
Payments
APAC Mobile Payments Market
Payments
India Payment Gateway Market
Payments
Canada POS Terminal Market
Payments
Canada Mobile Payments Market