
 Financial Guarantee Market | 2026-2036
Financial Guarantee Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Guarantee Market Analysis
Singapore is rewriting the competitive map for Asia-Pacific guarantee origination through its wealth-management licensing reforms and dollar-clearing infrastructure. Assured Guaranty leverages its monoline specialization in municipal bond insurance to sustain pricing power across U.S. state-level infrastructure. HSBC Holdings plc anchors trade-finance guarantee volumes through its network across ASEAN and Gulf corridors. JPMorgan Chase competes in investment-grade corporate standby facilities through balance-sheet scale and rating-agency relationships.
A financial guarantee is a contractual promise by a third party to fulfill a borrower's debt obligation upon default, typically structured as an insurance policy or standby letter of credit with defined coverage limits, trigger events, and claim-payment timelines. The instrument enables issuers to access capital markets at reduced interest costs by substituting the guarantor's credit rating for their own. Surety bonds and performance bonds dominate product-type revenue due to their embedded position in construction and public-works procurement cycles. Payment guarantees attached to cross-border commodity trade are expanding fastest as emerging-market buyers seek counterparty risk mitigation. Advisory services within the service-type dimension command premium fees where guarantee structuring intersects with complex project-finance documentation.
The U.S. Securities and Exchange Commission and the National Association of Insurance Commissioners shape disclosure standards and capital reserving for guarantee underwriters, while the EU's Solvency II framework governs European monoline insurers through risk-based capital charges. China's National Association of Financial Market Institutional Investors and the Banking and Insurance Regulatory Commission impose issuer-eligibility criteria and concentration limits on domestic guarantee providers. Stakeholders must monitor how climate-risk disclosure mandates from the U.S. SEC and the EU's CSRD reshape the credit-assessment models underlying long-duration infrastructure guarantees.
Market Dynamics
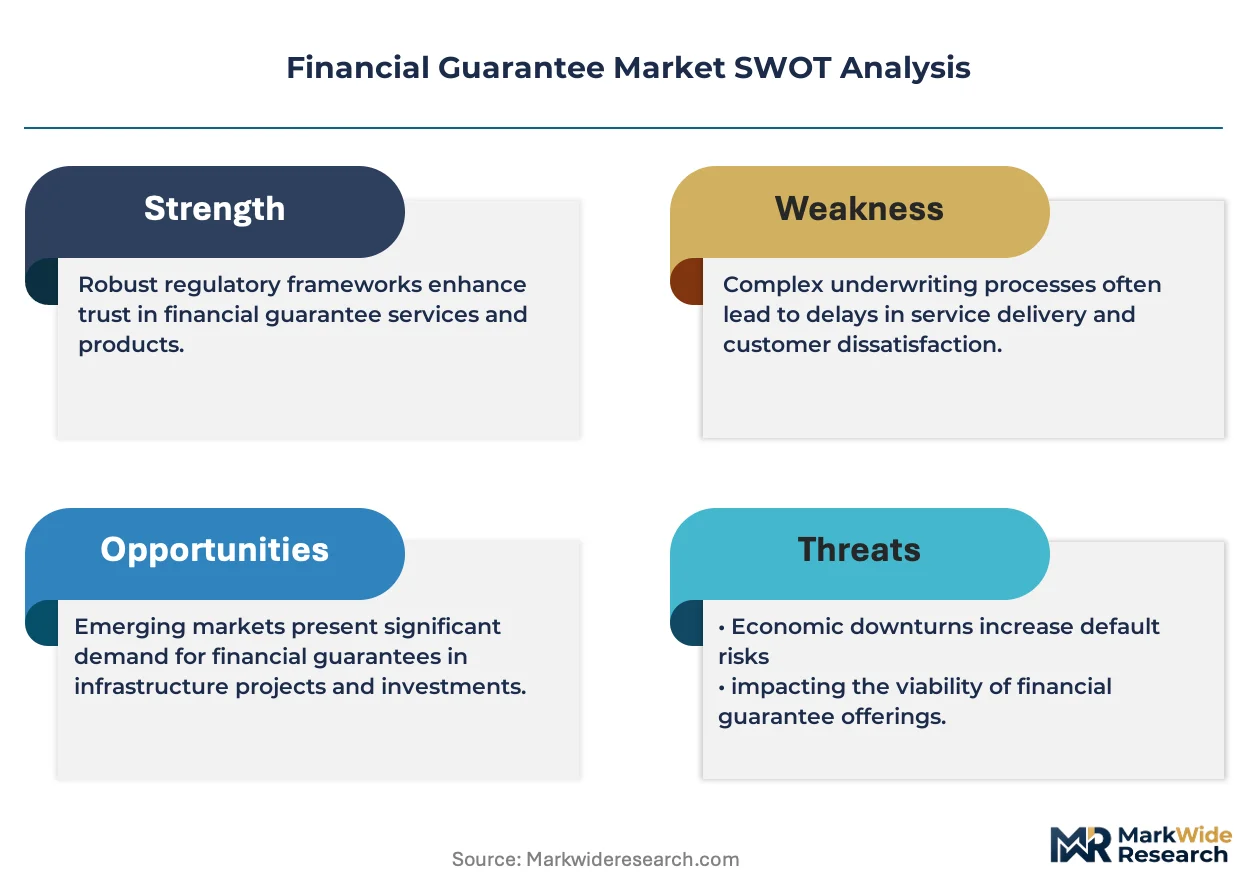
Basel III capital adequacy reforms have compressed bank balance-sheet capacity for long-duration credit support, redirecting municipal bond issuance toward monoline insurers and accelerating the displacement of traditional bank standby letters of credit.
Growth Catalysts
- Municipal infrastructure expansion:U.S. state-level transportation and water-utility projects require wrap guarantees to access institutional bond markets at investment-grade spreads.
- Basel III leverage ratios:European and U.S. banking regulators impose punitive capital charges on unfunded credit commitments, pushing corporate borrowers toward insurance-market alternatives.
- Offshore project finance in China:State-backed development banks mandate financial guarantees for Belt and Road Initiative loans denominated in foreign currency.
Market Restraints
- Reinsurance capacity constraints:Catastrophe bond spreads and climate-loss volatility have tightened retrocession markets for monoline insurers writing long-dated infrastructure exposure.
- Concentrated guarantor supply:The U.S. municipal bond insurance market depends on a shrinking pool of AAA-rated monolines, creating single-name counterparty risk in primary issuance.
- Solvency II risk charges:European insurers face elevated capital requirements for illiquid, long-duration guarantee liabilities under the EU's prudential framework.
Strategic Opportunities
- Singapore wealth-management licensing:Reforms permitting guarantee origination through private-banking subsidiaries open captive distribution channels for Asia-Pacific ultra-high-net-worth capital deployment.
- Green bond guarantee wrappers:EU taxonomy-aligned project finance requires third-party credit enhancement to meet institutional investor ESG mandates.
- Blockchain-enabled smart guarantees:Programmable escrow and automated claim triggers converge with trade-finance digitization to compress documentation and settlement latency.
Industry Challenges
- Climate-risk modeling talent scarcity:Underwriters lack actuarial capacity to price physical-risk exposure in 30-year infrastructure guarantees.
- Legacy IT integration friction:Monoline insurers struggle to embed API-driven data feeds from project monitoring systems into decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Guarantee Market |
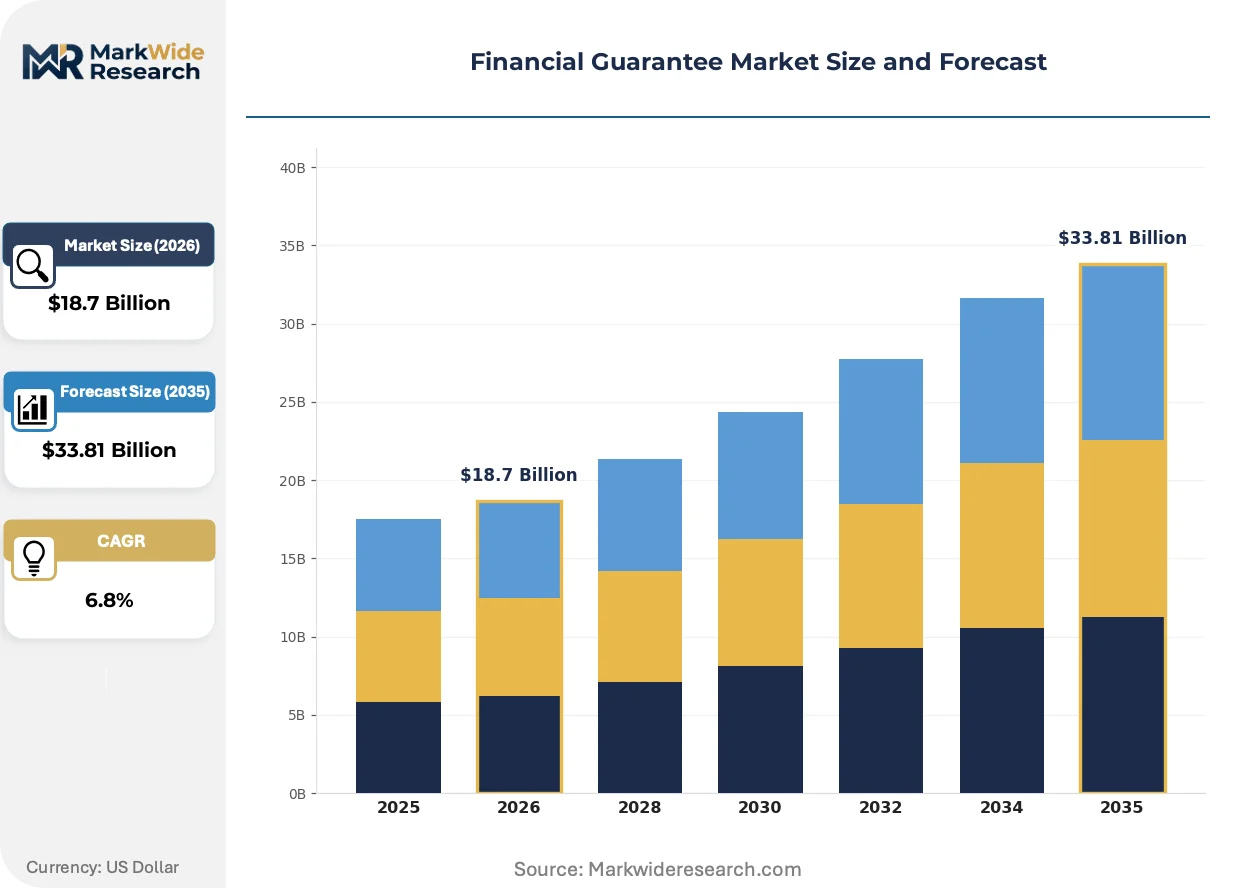
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surety Bonds, Performance Bonds, Payment Guarantees, Bid Bonds End User: Contractors, Developers, Government Agencies, Corporations Service Type: Financial Services, Insurance Services, Legal Services, Advisory Services Transaction Size: Small Contracts, Medium Contracts, Large Contracts, Jumbo Contracts |
| Companies Covered | Barclays plc, Bank of America, HSBC Holdings plc, Assured Guaranty, JPMorgan Chase, Citigroup Inc, The Industrial and Commercial Bank of China, AMBAC Assurance Corporation, BNP Paribas SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Guarantee Market Emerging Trajectories
Guarantee markets are bifurcating between standardized, exchange-traded instruments and bespoke structured solutions, with technology and regulation jointly compressing margins on commoditized products while expanding fee pools for complex documentation.
Artificial intelligence-driven credit scoring is collapsing the due-diligence timeline for trade-finance guarantees. Commodity traders in Singapore and Dubai now receive automated limit approvals within hours rather than weeks. This velocity compression is enabling just-in-time guarantee issuance tied to spot cargo movements rather than annual revolving facilities.
The U.S. SEC's climate-risk disclosure mandates require registrants to quantify forward-looking physical and transition risks in long-dated obligations. Infrastructure underwriters must now model flood, heat, and policy scenarios across 20-30 year guarantee horizons. European insurers face parallel pressure from the EU's CSRD, which extends comparable requirements to non-listed entities in their covered portfolios.
Buyers now unbundle guarantee procurement from relationship banking, treating credit enhancement as a standalone commodity purchased through competitive auction platforms. Corporate treasury functions in the United States and United Kingdom run reverse auctions for standby letter of credit facilities, compressing arrangement fees and forcing guarantors to compete on price rather than incumbent status. This disintermediation is most advanced in investment-grade corporate segments where credit quality is transparent and documentation is standardized.
Financial Guarantee Market Segmentation
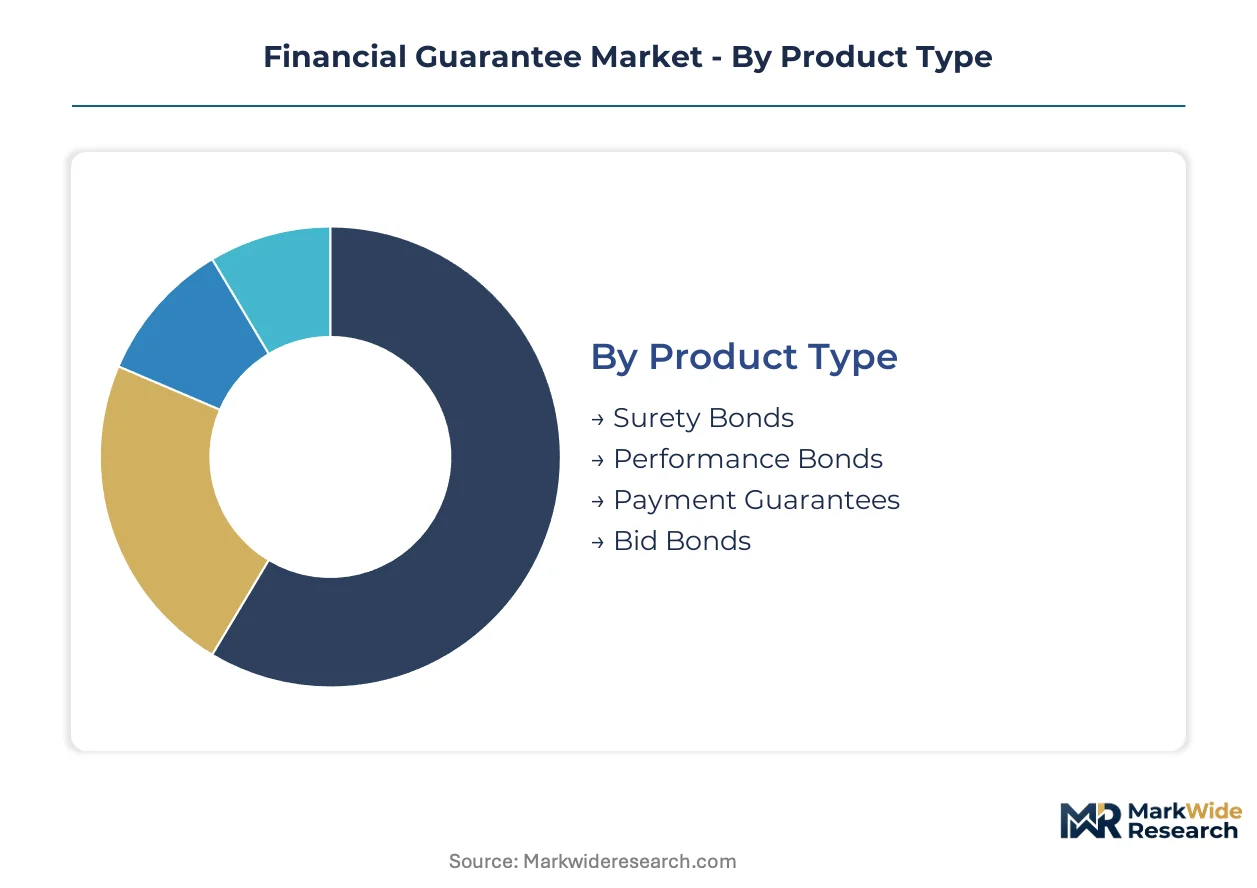
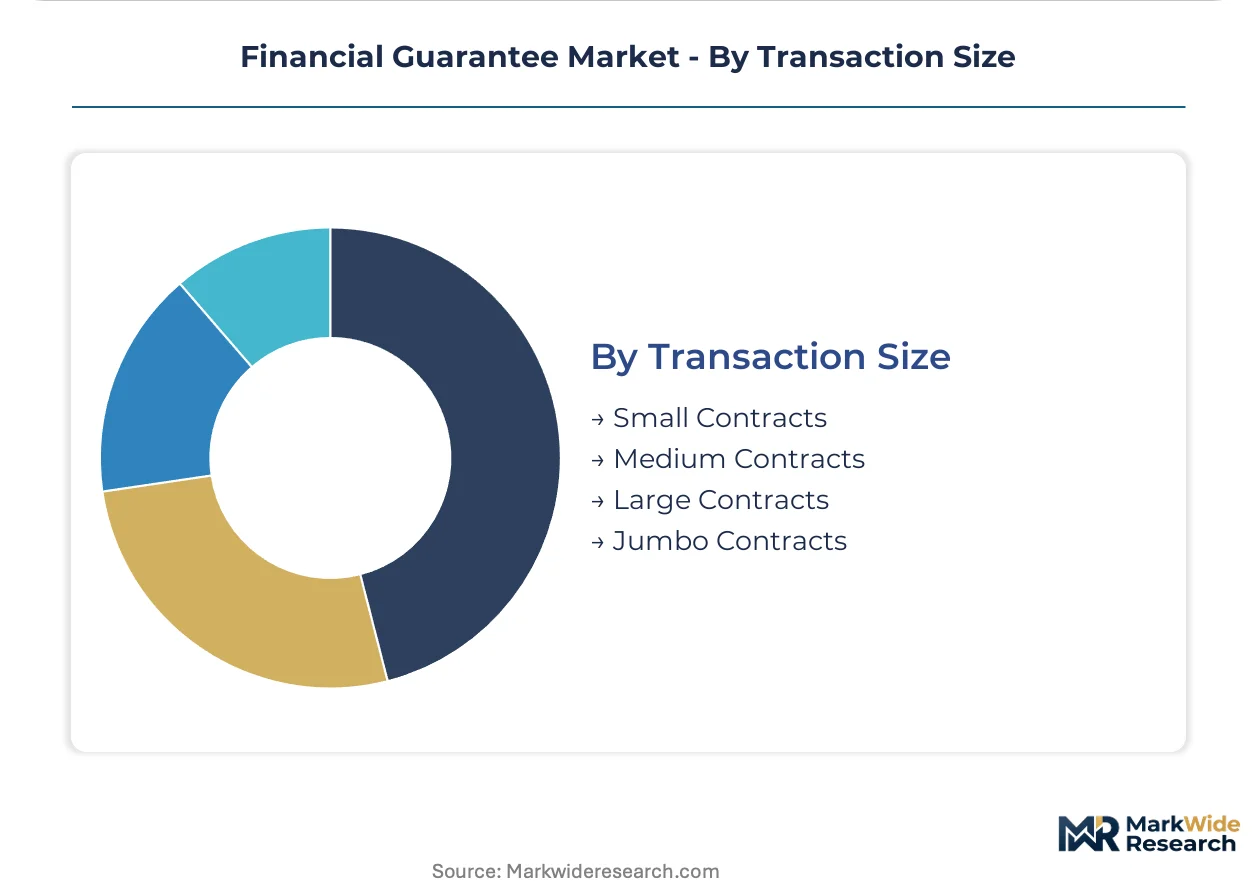
Financial guarantee markets fragment across four dimensions that determine pricing, documentation complexity, and counterparty eligibility. Product type governs risk-transfer mechanics. End-user identity drives regulatory treatment and capital requirements. Service type separates commoditized execution from premium advisory fees. Transaction size stratifies guarantor specialization and reinsurance placement.
Product Type:
Mature instruments dominate premium volumes while emerging structures capture regulatory-driven demand shifts.
- Surety Bonds:Tripartite agreements where the guarantor answers for the principal's default to the obligee, typically structured as conditional guarantees with defined penal sums. Demand concentrates in U.S. state transportation departments where federal funding mandates Miller Act compliance for public works above threshold contract values.
- Performance Bonds:Guarantee completion of contractual obligations rather than mere payment, embedding inspection rights and cure periods. Developers in Singapore and Dubai procurement frameworks require these for design-build contracts, with claims triggered by certified non-performance rather than insolvency.
- Payment Guarantees:Unconditional undertakings securing cross-border trade receivables. Chinese state-owned enterprises deploy these for Belt and Road commodity imports.
- Bid Bonds:Tender-stage instruments forfeitable if the successful bidder withdraws. European public procurement directives standardize these at 2-5% of estimated contract value.
Surety bonds retain volume leadership; payment guarantees hold the steepest expansion curve.
End User:
Customer-type concentration shapes distribution economics and renewal retention rates.
- Contractors:Construction firms with bonded backlogs requiring continuous surety capacity. U.S. general contractors in the $50-500 million revenue tier face the tightest underwriting scrutiny as bank alternatives retreat.
- Developers:Real estate sponsors needing completion guarantees for project finance lenders. Australian and Canadian pension fund mandates now require third-party completion wraps for speculative development exposure.
- Government Agencies:Sovereign and municipal obligees with statutory guarantee requirements. U.S. federal contracting officers rely on Treasury-certified sureties for defense and infrastructure awards.
- Corporations:Investment-grade issuers accessing standby letter of credit facilities for commercial paper programs and derivative margining. Basel III leverage ratios push these borrowers toward insurance-market solutions.
Contractors generate the deepest premium pool; corporations are climbing the fastest as bank capacity contracts.
Service Type:
Margin structure inverts between execution-only and advisory-embedded offerings.
- Financial Services:Standby letters of credit and demand guarantees issued through bank channels. HSBC and JPMorgan compete here on balance-sheet scale and rating-agency relationships.
- Insurance Services:Monoline financial guaranty policies with long-dated tail risk. Assured Guaranty specializes in municipal bond insurance within this segment.
- Legal Services:Guarantee documentation, opinion letters, and enforceability review. Singapore law firms capture premium fees for English-law guarantee structures governing Asia-Pacific project finance.
- Advisory Services:Structuring complex multi-currency, multi-jurisdictional guarantee programs. Demand clusters where guarantee wrappers intersect with green bond eligibility and EU taxonomy alignment.
Insurance services command the widest margins; advisory services are gaining share fastest as documentation complexity escalates.
Transaction Size:
Scale tiering determines guarantor specialization, reinsurance placement, and documentation standardization.
- Small Contracts:Sub-$1 million exposures with standardized forms and automated underwriting. Regional sureties in the U.S. Southeast dominate this tier through agency distribution.
- Medium Contracts:$1-50 million range requiring named underwriter review but templated documentation. European mid-market construction generates consistent flow here.
- Large Contracts:$50-500 million mandates needing syndicated guarantee capacity and bespoke reinsurance. Offshore oil and gas projects in the Gulf of Mexico and North Sea concentrate demand.
- Jumbo Contracts:Excess of $500 million requiring multi-guarantor participation and political risk overlay. Chinese state-backed development banks mandate these for Belt and Road power and transport infrastructure.
Medium contracts retain volume leadership; jumbo contracts hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC anchors the dominant geography through disclosure standards governing municipal bond insurance and credit enhancement. Basel III leverage ratios in Europe and prudential frameworks across Asia redirect guarantee demand toward non-bank providers. Five national markets concentrate origination volume and regulatory innovation.
United States
State transportation departments and water utilities drive municipal bond wrap demand. The SEC and NAIC impose capital reserving requirements on monoline underwriters. New York and California infrastructure clusters concentrate issuance volume for long-dated public works financing.
China
State-backed development banks mandate foreign-currency guarantees for Belt and Road project finance. The National Association of Financial Market Institutional Investors and CBIRC enforce issuer-eligibility criteria and concentration limits. Shanghai and Beijing financial centers anchor guarantee origination for offshore energy and transport infrastructure.
Singapore
Wealth-management licensing reforms enable guarantee origination through private-banking subsidiaries for ultra-high-net-worth capital deployment. The Monetary Authority of Singapore supervises dollar-clearing infrastructure and trade-finance digitization. The Marina Bay financial district concentrates advisory services for multi-currency guarantee structuring.
Germany
Mid-market construction and renewable energy project finance sustain surety bond demand. Solvency II risk-based capital charges elevate reserving requirements for long-duration guarantee liabilities. Frankfurt and Munich insurance clusters specialize in municipal infrastructure and green bond credit enhancement.
United Kingdom
Corporate treasury functions run reverse auctions for standby letter of credit facilities, treating credit enhancement as a standalone commodity. The Prudential Regulation Authority implements Basel III leverage ratios on unfunded credit commitments. London's wholesale banking district dominates investment-grade corporate guarantee origination for commercial paper programs.
Financial Guarantee Market Vendor Landscape
Capability concentration sits with monoline specialists; scale advantage sits with universal banking networks. The market structures around a shrinking pool of AAA-rated monolines and balance-sheet-heavy commercial banks. Two strategic archetypes dominate: credit-rating-driven municipal bond insurers and relationship-driven trade-finance providers. Competitive moves center on regulatory arbitrage between banking and insurance capital regimes and technology investments in automated underwriting.
Within the monoline tier, Assured Guaranty exemplifies municipal bond specialization, while AMBAC Assurance Corporation occupies a comparable position in legacy infrastructure exposure. HSBC Holdings plc anchors trade-finance guarantee volumes through network scale across ASEAN and Gulf corridors. These three entities represent the bifurcation between rating-driven insurance underwriting and balance-sheet-driven banking capacity.
| Leading Market Players |
|---|
| Barclays plc |
| Bank of America |
| HSBC Holdings plc |
| Assured Guaranty |
| JPMorgan Chase |
| Citigroup Inc |
| The Industrial and Commercial Bank of China |
| AMBAC Assurance Corporation |
| BNP Paribas SA |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on AAA-rated monoline capacity in the United States and United Kingdom determines both pricing tier spreads and supply chain shape, compressing margins on standardized municipal bond wraps while elevating premiums for bespoke infrastructure credit enhancement.
Pricing Analysis
Geographic price spreads between U.S. municipal bond insurance and Asia-Pacific trade-finance guarantees exceed threefold, reflecting divergent capital charges under Basel III versus Solvency II. Pricing stratifies across premium, standard, and economy tiers, with premium tiers commanded by monoline specialists holding S&P AAA ratings and economy tiers populated by regional sureties in the U.S. Southeast. Cost compression in standard-tier surety bonds is intensifying because corporate treasury functions now run reverse auctions for standby letter of credit facilities. Contractors in the $50-500 million revenue tier exhibit the highest price sensitivity, while jumbo infrastructure sponsors demonstrate the least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for guarantee documentation and reinsurance placement. Geographic supply concentration centers on the United States, United Kingdom, and Singapore, where monoline insurers, universal banks, and wealth-management licensing hubs respectively anchor capacity. Raw material dependencies include actuarial talent pools, regulatory capital reserves, and reinsurance retrocession markets. Single-source vulnerability concentrates in the shrinking pool of AAA-rated U.S. municipal bond insurers. Distribution runs through relationship banking networks for corporate standby facilities and competitive auction platforms for investment-grade credit enhancement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The financial guarantee market is entering a cyclical recovery phase as Basel III leverage ratios force persistent displacement of bank credit commitments toward insurance-market alternatives.
For Market Incumbents: Pre-empt margin erosion in standardized surety bonds by embedding API-driven data feeds from project monitoring systems into legacy policy administration platforms. Deepen captive distribution control through private-banking subsidiaries in Singapore before wealth-management licensing reforms saturate origination channels. The priority lever rests on climate-risk modeling talent acquisition to price physical-risk exposure in long-dated infrastructure guarantees. For New Entrants and Emerging Players: Establish a beachhead in blockchain-enabled smart guarantees for trade-finance digitization, where programmable escrow and automated claim triggers remain underdeveloped. Target medium-contract guarantee tiers in European mid-market construction, where documentation standardization lowers barriers to entry. The optimal go-to-market angle pairs green bond guarantee wrappers with EU taxonomy-aligned project finance advisory services. For Investors and Strategic Acquirers: Solvency II risk charge recalibration for long-duration guarantee liabilities reshapes the acquisition landscape toward insurers with matched-duration asset portfolios. Long-term viability favors monoline specialists with municipal bond insurance concentration over universal banks facing punitive capital charges on unfunded credit commitments. The acquisition target archetype comprises regional sureties with automated underwriting platforms in the U.S. Southeast. Monitor catastrophe bond spread widening as the inflection signal for reinsurance capacity constraints affecting monoline infrastructure exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Risk Modeling Investment | Builds actuarial capacity to price physical-risk exposure in 30-year infrastructure guarantees under SEC disclosure mandates. |
| Blockchain-Enabled Smart Guarantee Development | Compresses documentation and settlement latency through programmable escrow tied to trade-finance digitization in Singapore. |
| Singapore Wealth-Management Licensing Expansion | Opens captive distribution channels for Asia-Pacific ultra-high-net-worth capital deployment in guarantee origination. |
| Green Bond Guarantee Wrapper Structuring | Enables EU taxonomy-aligned project finance to meet institutional investor ESG mandates through third-party credit enhancement. |
| API-Driven Legacy Platform Modernization | Embeds real-time project monitoring data feeds into decades-old policy administration systems for velocity compression. |
Methodological Framework
Desk research of regulatory filings, trade association capital surveys, and reinsurance market reports preceded structured interviews with monoline underwriters, municipal bond issuers, corporate treasury officers, and project finance lenders. Primary fieldwork captured underwriting capacity constraints, pricing mechanics, and documentation complexity across guarantee product types. Secondary validation drew from NAIC statutory filings, SEC disclosure databases, EU Solvency II public reports, and Singapore MAS regulatory circulars. Bottom-up segmentation modeling triangulated against top-down macroeconomic scenario analysis.
Assumptions regarding Basel III leverage ratio implementation, Solvency II risk charge stability, and Singapore wealth-management licensing reform timelines were held fixed across baseline scenarios while climate-loss volatility and reinsurance retrocession capacity were stress-tested. Segmentation dimensions modeled include product type, end-user identity, service type, and transaction size tier. CAGRs were derived through logarithmic trend fitting across the projection horizon. Industry-specific forecast inputs incorporated municipal infrastructure backlog data and Belt and Road Initiative foreign-currency guarantee mandate flows.
Stress conditions across reinsurance capacity, regulatory capital charge recalibration, and monoline counterparty concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions that may require revision should climate-risk disclosure mandates accelerate or single-name guarantor supply contract further. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Medical Claims Processing Services Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Travel Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
India Online Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
China Liability Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Global Cargo Transportation Insurance Market