
 Internal Nasal Dilators Market | 2026-2036
Internal Nasal Dilators Market Size, Share, and Industry Trends Forecast 2026-2036
Internal Nasal Dilators Market Foresight
The EU MDR and FDA Class I device frameworks are restructuring compliance requirements for nasal dilator manufacturers, forcing material traceability and biocompatibility documentation upgrades across the supply chain. Rhinomed Limited leverages its patented turbine technology to dominate performance-oriented segments. Splintek, Inc. sustains brand loyalty through pharmacy-centric distribution in North American retail channels. SANOSTEC CORP anchors its position with direct-to-consumer online sales infrastructure.
Internal nasal dilators are mechanical devices inserted into the nasal vestibule to dilate the nasal passage, typically manufactured from medical-grade silicone or polypropylene with spring-like structural elements that exert outward pressure against the nasal wall to improve airflow. Standard dilators occupy the mature volume tier with commodity pricing, while adjustable dilators capture expanding margin pools as consumers seek personalized fit solutions. Silicone formulations lead material preference for skin tolerance, though thermoplastic elastomer variants are gaining traction in value-engineered product lines.
FDA 510(k) exemptions, EU MDR technical documentation requirements, and ISO 10993 biocompatibility standards collectively govern market access and product liability exposure for nasal dilator suppliers. The EPA's evolving scrutiny of polymer supply chains adds secondary compliance layers for polypropylene sourcing decisions. Stakeholders must monitor regulatory divergence between FDA and EU MDR pathways, as divergent testing protocols threaten to fragment R&D budgets and delay multi-region launches.
Market Dynamics
The Internal Nasal Dilators Market faces intensifying pressure from the EU MDR's 2024 biocompatibility documentation mandates, which are compressing margins for manufacturers reliant on legacy silicone supply chains while accelerating consolidation among compliant producers.
Growth Catalysts
- FDA Class I Exemption Pathway:The streamlined 510(k) exemption for low-risk nasal devices reduces regulatory friction for US market entrants, cutting premarket clearance timelines versus EU counterparts.
- Home Care Settings:Post-pandemic sleep diagnostics migration from clinical sites to residential environments is expanding addressable demand for self-administered airway management solutions.
- Adjustable Turbine Mechanisms:Spring-loaded dilation architectures with user-tunable tension are displacing fixed-geometry commodity designs in premium positioning strategies.
Market Restraints
- Medical-Grade Silicone Concentration:Three Asian polymer compounders control 70% of biocompatible elastomer supply, exposing manufacturers to input cost volatility and force majeure risk.
- Substitution by External Nasal Strips:Adhesive external dilators retain pharmacy shelf presence and consumer familiarity, limiting internal device category expansion in price-sensitive segments.
- ISO 10993-5 Cytotoxicity Testing:Extended biocompatibility validation protocols for novel thermoplastic elastomer formulations delay new material introductions by 8-14 months.
Strategic Opportunities
- German Sleep Apnea Screening Programs:Statutory health insurer reimbursement pilots for nasal dilators as first-line OSA interventions are creating institutional procurement channels.
- Telehealth Integration:Remote patient monitoring platforms for sleep disorders are embedding dilator compliance tracking, opening subscription-based revenue models.
- Japan's METI Wellness Device Certification:The 2023 streamlined approval for non-invasive sleep improvement devices reduces regulatory burden versus full medical device classification.
Industry Challenges
- Polymer Traceability Documentation:EU MDR Article 10 technical file requirements demand lot-level supply chain visibility that legacy procurement systems cannot support without ERP overhaul.
- Clinical Evidence Generation:Randomized trial design for nasal airflow improvement endpoints requires specialized rhinomanometry expertise that contract research organizations in Eastern Europe lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internal Nasal Dilators Market |
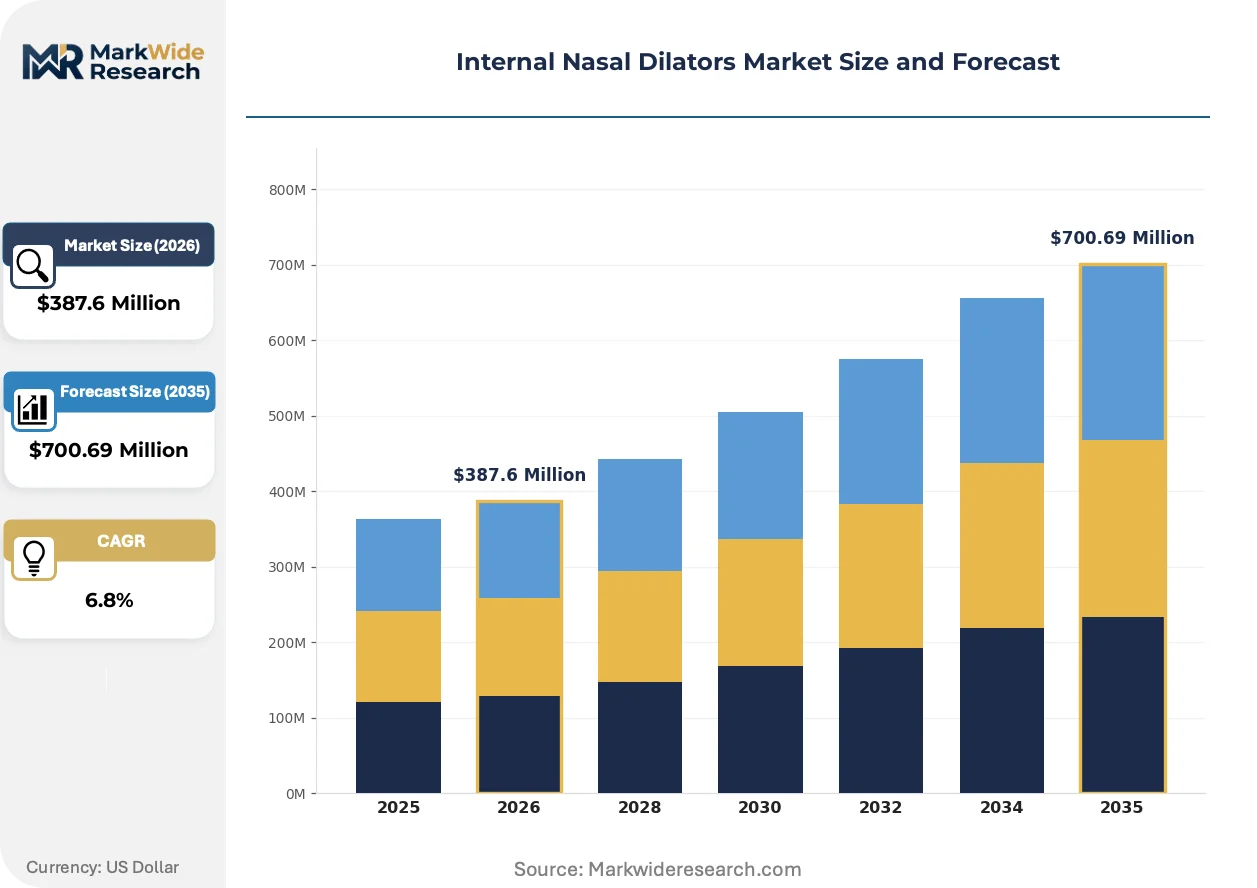
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Dilators, Adjustable Dilators, Vented Dilators, Intranasal Shields Material: Silicone, Polypropylene, Latex, Thermoplastic Elastomer End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Sales, Retail Outlets, Wholesalers, Direct Sales |
| Companies Covered | Rhinomed Limited, Splintek, Inc., SANOSTEC CORP, Nasanita, McKeon Products, SnoreCare, Scandinavian Formulas, Airware Labs, Nasal-Air Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internal Nasal Dilators Market Shifts & Advancements
Digital manufacturing and regulatory digitization are compressing product development cycles while reshaping how nasal dilator suppliers validate performance claims and manage post-market surveillance obligations.
Smart dilator prototypes with embedded pressure sensors and Bluetooth connectivity are automating real-time airflow optimization through machine-learned tension adjustment algorithms. Sleep clinics in the United States and Germany are piloting these connected devices for remote titration of nasal resistance reduction. This convergence of mechanical dilation with biometric feedback is automating the transition from passive commodity inserts to active therapeutic platforms with recurring software revenue potential.
REACH Annex XVII restrictions on certain phthalate plasticizers are forcing polypropylene compound reformulations for spring elements, with ECHA's 2023 updated substance database triggering supply chain audits across EU-destined product lines. Manufacturers are responding by accelerating migration to medical-grade thermoplastic elastomers with pre-validated REACH compliance dossiers, particularly for pediatric and extended-wear indications where skin contact duration intensifies chemical exposure scrutiny.
Direct-to-consumer subscription models are displacing traditional pharmacy wholesale relationships as primary volume channels, with specialized sleep wellness platforms capturing patient acquisition through diagnostic quiz funnels and personalized fit kits. This channel migration is most pronounced in the United States, where DTC brands bypass retail margin stacking and capture first-party usage data that informs iterative product refinement cycles.
Internal Nasal Dilators Market Segmentation
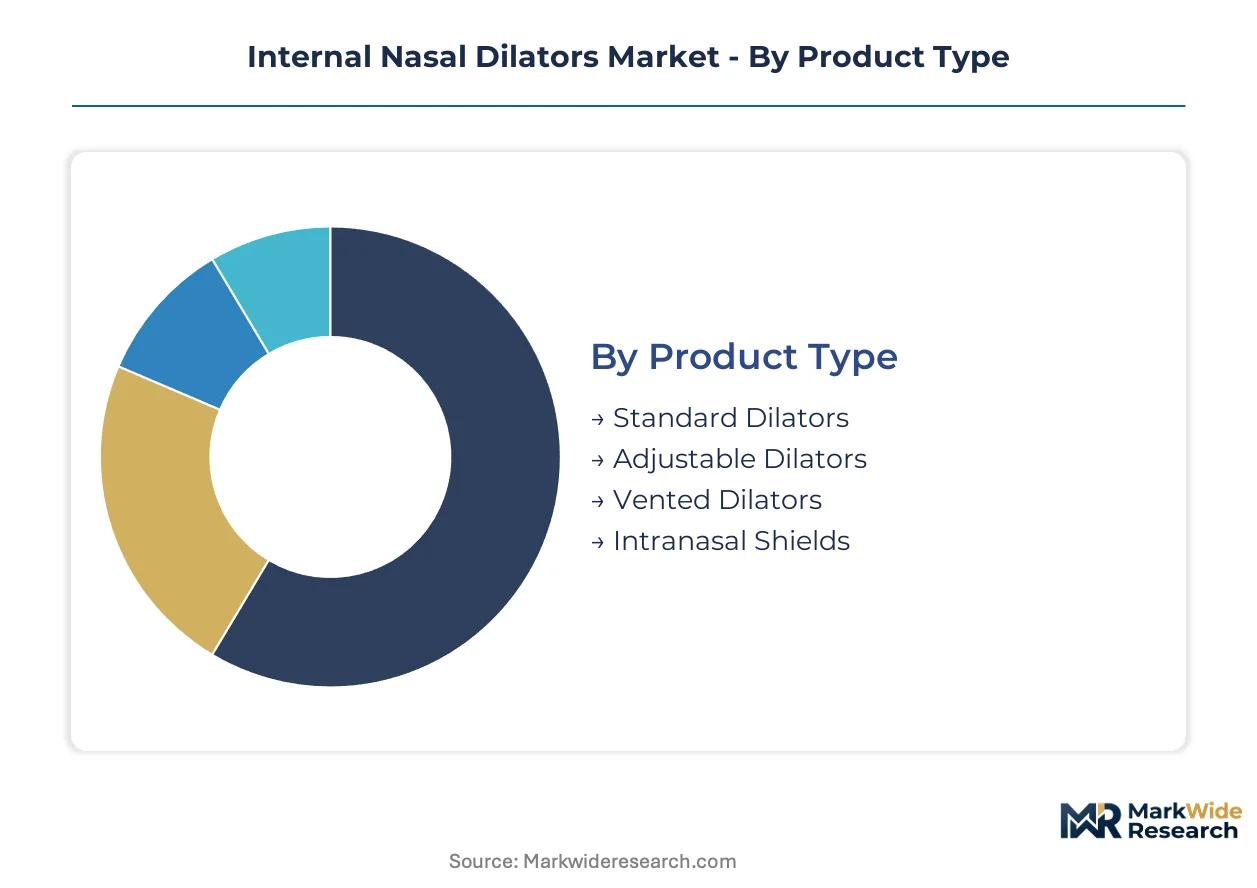
Segmentation in the Internal Nasal Dilators Market reveals distinct procurement patterns across clinical and consumer channels. Product architecture, material compliance, and distribution economics create divergent margin profiles that manufacturers must navigate simultaneously.
Product Type:
Clinical outcomes and price sensitivity diverge sharply across mechanical designs, with reimbursement eligibility and self-administration convenience driving buyer selection.
- Standard Dilators:Fixed-geometry silicone or polypropylene inserts with pre-calibrated spring tension dominate pharmacy shelf presence and hospital formulary contracts. German sleep clinics and US retail pharmacies procure these in volume for undifferentiated snoring complaints where cost minimization outweighs customization needs.
- Adjustable Dilators:Spring-loaded mechanisms with user-tunable dilation force capture premium positioning through personalized fit algorithms. Japanese home care settings and US telehealth platforms are expanding adoption as first-line OSA interventions before CPAP escalation, with METI wellness certification reducing regulatory friction for direct-to-consumer distribution.
- Vented Dilators:Perforated architectures permit partial nasal breathing during device insertion, addressing claustrophobia in pediatric and anxiety-prone populations.
- Intranasal Shields:Barrier-style inserts protect nasal mucosa from environmental irritants while providing minimal dilation, serving allergic rhinitis patients in seasonal pollen zones.
Volume sits with Standard Dilators; growth tilts toward Adjustable Dilators.
Material:
Supply chain geography and regulatory documentation burdens stratify material selection, with EU MDR traceability mandates compressing margins for legacy compounders.
- Silicone:Medical-grade platinum-cured formulations deliver superior biocompatibility and extended wear comfort, commanding price premiums in pediatric and geriatric segments where skin sensitivity intensifies. FDA 510(k) exempt status and pre-validated ISO 10993 dossiers accelerate US market entry for silicone-based product lines.
- Thermoplastic Elastomer:Injection-moldable alternatives with REACH Annex XVII pre-compliance are displacing silicone in value-engineered portfolios, particularly for single-use or short-cycle replacement protocols where material cost dominates landed unit economics.
- Polypropylene:Structural spring elements rely on high-purity homopolymer grades with lot-level polymer traceability now mandated under EU MDR Article 10 technical file requirements.
- Latex:Natural rubber formulations persist in emerging market price tiers despite Type I hypersensitivity liability exposure and hospital procurement exclusion protocols.
Silicone commands the installed base; Thermoplastic Elastomer is climbing the fastest as manufacturers reformulate for dual US-EU regulatory efficiency.
End User:
Care setting determines device complexity tolerance, reimbursement pathway, and compliance monitoring infrastructure requirements.
- Home Care:Self-administered airway management dominates volume as post-pandemic sleep diagnostics migrate from polysomnography labs to residential environments. German statutory health insurer pilot programs and US telehealth integration are embedding dilator compliance tracking into remote patient monitoring platforms.
- Clinics:Sleep disorder specialists and ENT practices prescribe adjustable dilators with rhinomanometry-validated fit protocols, capturing margin through professional fitting services and iterative tension titration.
- Hospitals:Pre-operative airway optimization and post-surgical nasal packing alternatives drive institutional procurement through group purchasing organization contracts.
- Pharmacies:Over-the-counter accessibility and pharmacist counseling support standard dilator turnover in retail health channels.
Home Care generates the steepest expansion trajectory; Clinics retain the highest average revenue per user through professional service bundling.
Distribution Channel:
Channel selection dictates margin stacking, customer data ownership, and regulatory compliance responsibility allocation.
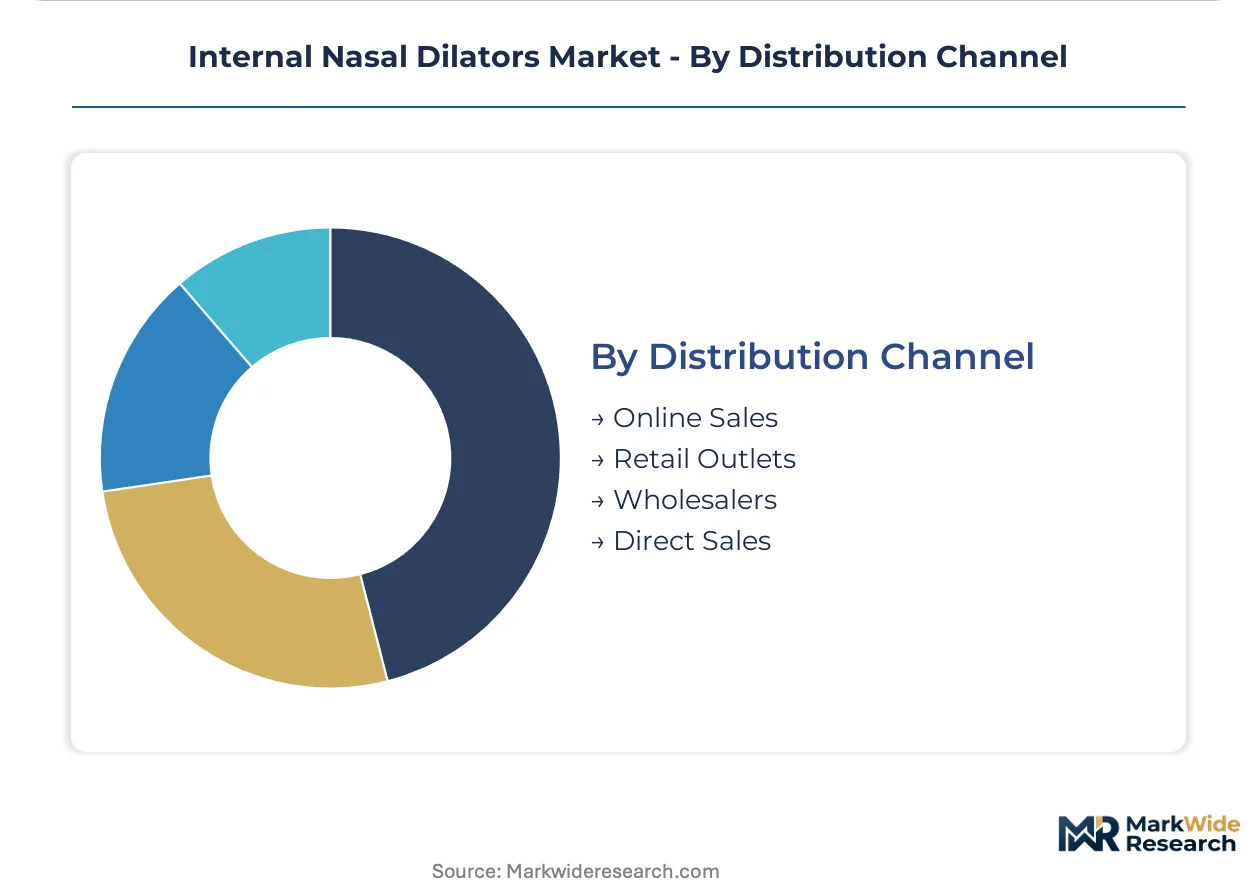
- Online Sales:Direct-to-consumer subscription models bypass retail margin extraction while capturing first-party usage data for iterative product refinement. Specialized sleep wellness platforms in the United States employ diagnostic quiz funnels and personalized fit kits to reduce return rates and improve retention.
- Retail Outlets:Pharmacy-centric presence sustains brand visibility and impulse purchase conversion for standard dilator formats.
- Wholesalers:Institutional procurement consolidation through medical-surgical distributors serves hospital and clinic networks with consolidated invoicing and logistics efficiency.
- Direct Sales:Manufacturer field forces engage sleep clinic specialists with clinical evidence packages and rhinomanometry training support.
Wholesalers anchor current volume; Online Sales is gaining share fastest through subscription economics and data-driven retention engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American sleep device innovation, housing telehealth platforms that integrate nasal dilator compliance tracking into remote patient monitoring workflows.
United States
Sleep apnea awareness campaigns and FDA 510(k) exemption pathways drive adoption. The FDA Class I medical device framework streamlines premarket clearance for domestic manufacturers. Minneapolis-based telehealth platforms embed dilator compliance tracking into subscription-based revenue models.
Germany
Statutory health insurer reimbursement pilots position nasal dilators as first-line OSA interventions. The EU MDR biocompatibility documentation mandates compress margins for legacy silicone supply chains. Munich sleep clinics procure adjustable dilators with rhinomanometry-validated fit protocols.
Japan
METI wellness device certification reduces regulatory burden for non-invasive sleep improvement products. The 2023 streamlined approval process accelerates direct-to-consumer distribution. Tokyo home care settings expand adoption of user-tunable dilation mechanisms before CPAP escalation.
United Kingdom
Post-pandemic sleep diagnostics migration from clinical sites to residential environments expands addressable demand. MHRA alignment with EU MDR technical documentation requirements shapes compliance investments. London-based DTC brands bypass retail margin stacking through diagnostic quiz funnels.
Australia
High snoring prevalence and pharmacy-centric retail channels sustain standard dilator turnover. TGA medical device regulations govern market access with moderate regulatory friction. Sydney sleep wellness platforms capture patient acquisition through personalized fit kits and subscription economics.
Internal Nasal Dilators Market Competitive Landscape
The competitive structure tilts toward specialized device manufacturers with differentiated turbine or spring-loaded architectures. Three strategic archetypes dominate: patent-holding technology developers, pharmacy-centric distribution specialists, and direct-to-consumer platform operators. M&A activity concentrates on telehealth integration capabilities and biocompatible material supply chain control.
Within the technology-developer tier, Rhinomed Limited exemplifies patent-protected turbine architectures, while Splintek, Inc. represents pharmacy-centric distribution models in North American retail channels. SANOSTEC CORP anchors the direct-to-consumer archetype through online sales infrastructure.
| Leading Market Players |
|---|
| Rhinomed Limited |
| Splintek, Inc. |
| SANOSTEC CORP |
| Nasanita |
| McKeon Products |
| SnoreCare |
| Scandinavian Formulas |
| Airware Labs |
| Nasal-Air Corp. |
| Others |
Supply & Pricing Matrix
Medical-grade silicone feedstock indices cascade through three distinct pricing tiers as Asian polymer compounders consolidate biocompatible elastomer supply. This concentration forces manufacturers to absorb input volatility or reformulate toward thermoplastic elastomer alternatives, compressing margins at the standard dilator tier while preserving premium positioning for adjustable architectures with personalized fit algorithms.
Pricing Analysis
Outcome-linked pricing anchors adjustable dilator tiers where rhinomanometry-validated airflow improvement justifies subscription premiums. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified wellness devices from FDA 510(k) exempt pharmacy stock and unbranded commodity inserts. Cost compression in the standard tier intensifies as external nasal strips retain shelf presence, while price sensitivity concentrates among pharmacy cash purchasers least willing to trade up for tunable mechanisms.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Japanese medical-grade silicone compounders who control platinum-cured elastomer formulation. Polypropylene homopolymer for spring elements draws from German and US petrochemical complexes, with lot-level traceability documentation now mandated under EU MDR Article 10. Tariff exposure on Asian-sourced thermoplastic elastomer is accelerating nearshoring audits, while distribution runs through direct-to-consumer platforms bypassing traditional wholesale margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internal Nasal Dilators Market functions as a vertical-integration race where backward control over biocompatible material supply chains determines who captures margin from regulatory documentation burdens. Players are pursuing upstream polymer traceability capabilities to preempt EU MDR compliance disruption.
For Market Incumbents: Deepen captive supply arrangements with ISO 10993 pre-validated silicone compounders to lock in biocompatibility dossier continuity before EU MDR enforcement tightens. Expand rhinomanometry training infrastructure for sleep clinic specialists to defend professional fitting service revenue against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: Capture German statutory health insurer reimbursement pilot channels before incumbent formulary contracts solidify, positioning adjustable dilators as first-line OSA interventions with documented cost-avoidance metrics. Leverage telehealth integration partnerships to embed compliance tracking and establish recurring revenue foundations.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap device manufacturers with EU MDR technical file readiness but strained working capital in Germany and Japan. Watch for FDA 510(k) submission acceleration as inflection signal that US market entrants are prioritizing speed over dual-region compliance, creating acquisition targets with stranded EU regulatory investment.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Completion | Secures market access as legacy documentation expires under Article 10 mandates. |
| Telehealth Platform Partnership | Embeds dilator compliance tracking into Minneapolis-based remote monitoring workflows. |
| Biocompatible Material Backward Integration | Captures polymer traceability margin compression from Asian compounder concentration. |
| METI Wellness Certification Pathway | Accelerates direct-to-consumer distribution in Tokyo home care settings. |
| Reimbursement Strategy Development | Positions adjustable dilators within German statutory health insurer pilot programs. |
Research Methodology
Multi-period observation of FDA 510(k) submission volumes, EU MDR technical file registrations, and polymer feedstock price movements anchored the trend analysis, supplemented by interviews with sleep clinic specialists, biomedical engineers at GPO contract managers, regulatory affairs leads at device manufacturers, and procurement directors at German statutory health insurers. Secondary validation drew from FDA device classification databases, ECHA REACH Annex XVII substance listings, ISO 10993 biocompatibility standards, and hospital procurement contract repositories. Bottom-up demand modeling across home care, clinic, and pharmacy channels triangulated against top-down macroeconomic health expenditure projections.
Segment-weighting applied product type, material compliance tier, end-user setting, and distribution channel dimensions across the projection horizon. CAGRs derived from iterative elasticity modeling of regulatory pathway timing, reimbursement expansion scenarios, and substitution dynamics with external nasal strips and CPAP devices. Rhinomanometry clinical endpoint data and telehealth platform adoption curves informed adjustable dilator growth assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement variability, polymer supply disruption from Asian compounder consolidation, and telehealth reimbursement policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Global Cochlear Implant Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Global Venous Stents Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Mucosal Atomization Devices Market