
 Non-Invasive Surgical Wound Closure Market | 2026-2036
Non-Invasive Surgical Wound Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Surgical Wound Closure Market Analytics
Topical adhesive polymer chemistry is fragmenting into cyanoacrylate, polyethylene glycol, and novel hybrid formulations that alter manufacturing scale economics for wound closure platforms. 3M leverages its materials science heritage to sustain proprietary adhesive portfolios across surgical suites. Medtronic anchors its position through channel density in acute-care distribution networks. Baxter differentiates via hospital formulary control and integrated wound-care bundles.
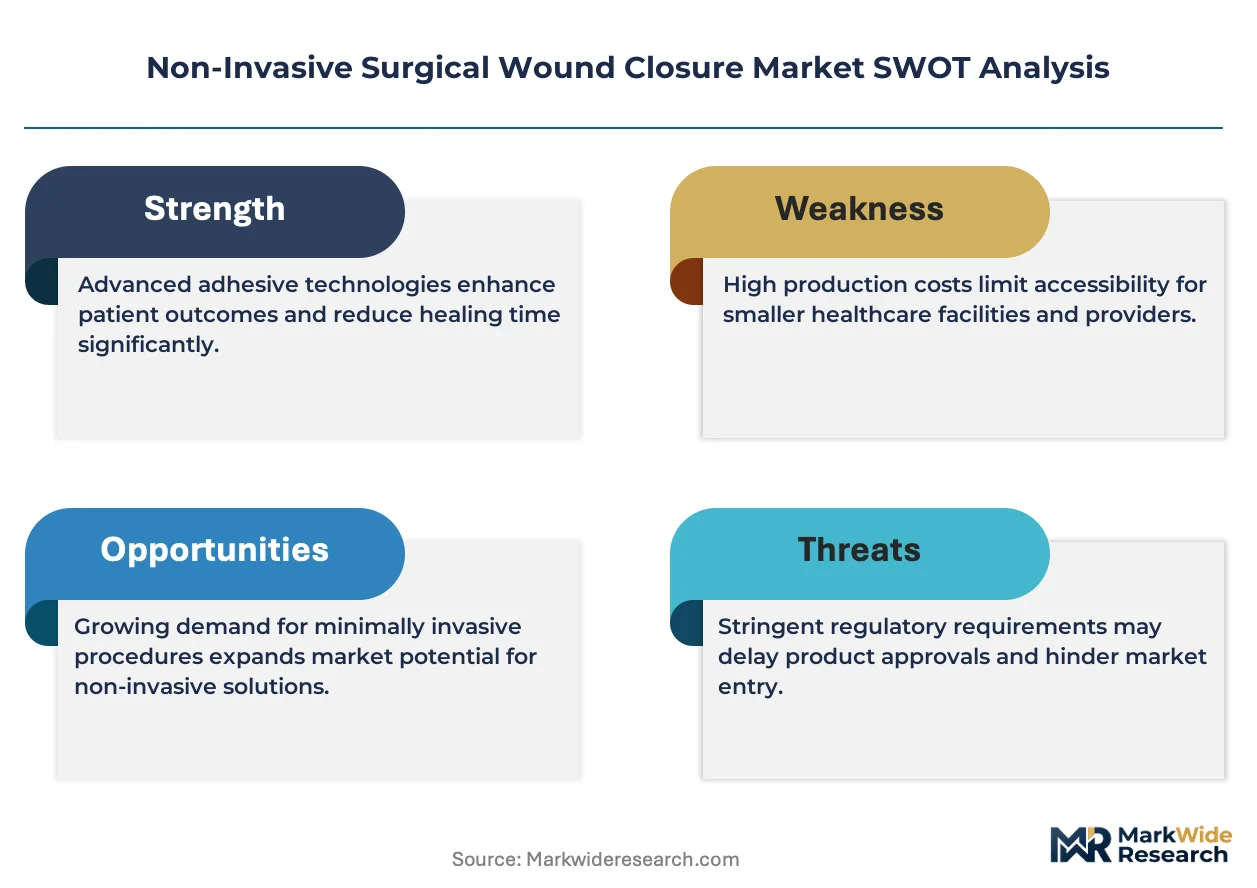
Non-invasive surgical wound closure encompasses devices and materials that approximate tissue edges without percutaneous needle penetration, typically employing adhesive polymers with tensile strengths exceeding 200 psi or mechanical applicators delivering uniform compression. These systems reduce infection vectors, eliminate suture track scars, and accelerate operating-room throughput for superficial and select deep-layer closures. Adhesives command the dominant revenue share due to premium pricing in cosmetic and pediatric applications, while ambulatory surgery centers represent the fastest-growing end-user segment as procedural volume migrates from inpatient settings. Ultrasonic technology occupies an emerging niche where thermal welding of protein structures offers alternatives for fragile or vascularized tissues.
FDA 510(k) premarket notification requirements shape product development cycles and predicate-device selection for adhesive and clip-based systems entering the US market. ISO 10993 biocompatibility testing standards govern cytotoxicity and sensitization protocols that manufacturers must complete before clinical trials. The EU Medical Device Regulation intensifies notified-body scrutiny for electrosurgical and laser-based wound closure platforms seeking CE marking. Stakeholders must monitor evolving reimbursement codes for adhesive-based closures in outpatient settings versus traditional suture reimbursement tiers.
Market Dynamics
Migration of surgical volume toward ambulatory settings is compressing reimbursement timelines and forcing manufacturers to redesign wound closure platforms for rapid application without anesthesia support. This structural shift privileges adhesive systems over mechanical alternatives in same-day discharge protocols.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for Class II skin adhesives reduces predicate-device matching burden. Device sponsors now target 90-day clearance cycles for cyanoacrylate reformulations.
- Ambulatory surgery center expansion:CMS reimbursement shifts favor outpatient wound closure over inpatient suture protocols. Facility operators stock adhesive platforms to minimize procedure time and eliminate needlestick protocols.
- Pediatric and cosmetic demand concentration:Parents and aesthetic surgeons prioritize scar-minimizing outcomes. Polymer chemistry advances deliver tensile strength without suture track marks.
Market Restraints
- Raw material concentration:Medical-grade cyanoacrylate monomer supply clusters in German and Japanese chemical production corridors. Disruptions propagate through adhesive formulation pipelines.
- EU MDR compliance burden:Notified-body scrutiny of biocompatibility documentation extends CE marking timelines for novel polymer platforms. Small manufacturers lack capital for expanded clinical evaluation.
- Suture substitution economics:Conventional needle-and-thread systems retain cost advantage in emerging markets. Price-sensitive hospital procurement committees delay adhesive adoption.
Strategic Opportunities
- India outpatient infrastructure:Ayushman Bharat expansion funds same-day surgical facilities. Domestic device distributors seek adhesive platforms compatible with high-throughput cataract and hernia protocols.
- Ultrasonic tissue welding convergence:Thermal protein bonding technology addresses fragile vascularized tissues where adhesives fail. Academic medical centers pilot hybrid closure systems combining mechanical and energy-based approaches.
- Veterinary medicine extension:Companion animal surgery volume rises in US metropolitan markets. Adhesive formulations bypass species-specific suture removal compliance challenges.
Industry Challenges
- ISO 10993 testing backlog:Biocompatibility laboratory capacity constraints delay cytotoxicity and sensitization studies. Manufacturers queue six months for complete evaluation panels.
- Application training standardization:Operating room nurses require competency certification for adhesive dispensing systems. Hospital systems lack uniform protocols for polymer curing time verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Surgical Wound Closure Market |
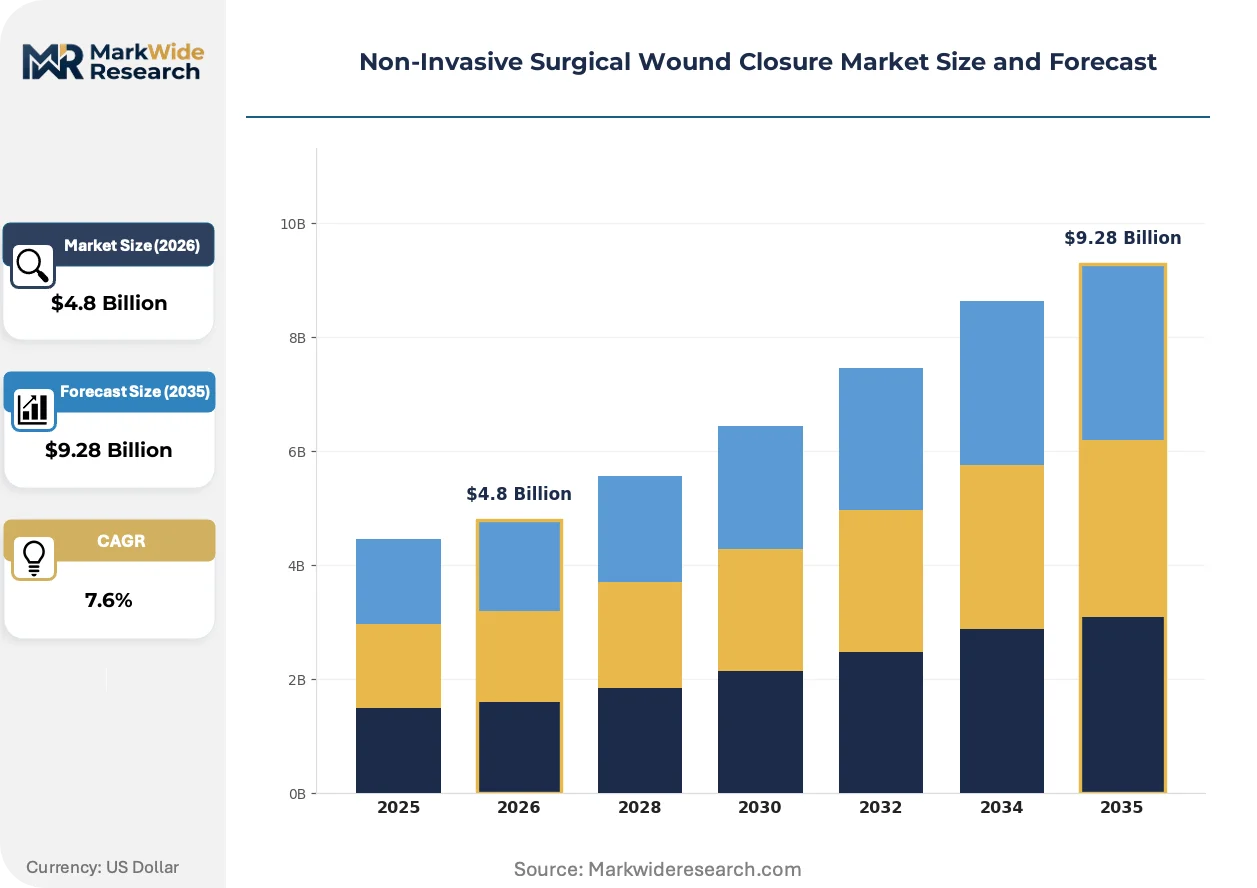
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Staples, Suture, Clips End User: Hospitals, Clinics, Outpatient Facilities, Ambulatory Surgery Centers Application: Orthopedic Surgery, Cardiovascular Surgery, General Surgery, Cosmetic Surgery Technology: Laser Technology, Ultrasonic Technology, Electrosurgery, Negative Pressure |
| Companies Covered | Johnson & Johnson, 3M, Medtronic, Baxter, B. Braun, Smith & Nephew, Stryker, Integra LifeSciences, Corza Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Surgical Wound Closure Market Evolving Landscape
Digital integration of wound closure platforms is compressing documentation burden and enabling real-time supply chain visibility. Manufacturers embed connectivity features to capture procedure data and automate replenishment.
Polymer formulation software is digitizing adhesive development cycles. Computational chemistry platforms predict cyanoacrylate curing kinetics and tissue adhesion profiles before bench testing. Material science teams at contract research organizations compress formulation iterations from months to weeks. This capability is digitizing competitive barriers, as algorithm-trained databases become proprietary assets distinct from manufacturing scale.
The EU Medical Device Regulation intensifies post-market surveillance obligations for electrosurgical wound closure platforms. Manufacturers must establish systematic procedures for capturing and analyzing clinical performance data across notified-body jurisdictions. Adhesive-based systems face heightened scrutiny of degradation byproduct documentation. European hospital procurement committees now require MDR compliance certification as a gatekeeping criterion in tender evaluations.
Hospital supply chain consolidation is centralizing purchasing authority for wound closure categories. Integrated delivery networks negotiate enterprise-wide contracts covering adhesives, sutures, and mechanical clips. Independent ambulatory surgery centers respond through group purchasing organization membership to match acute-care pricing tiers. This concentration is most visible in Texas and Florida metropolitan corridors where health system mergers have collapsed vendor bases.
Non-Invasive Surgical Wound Closure Market Segmentation
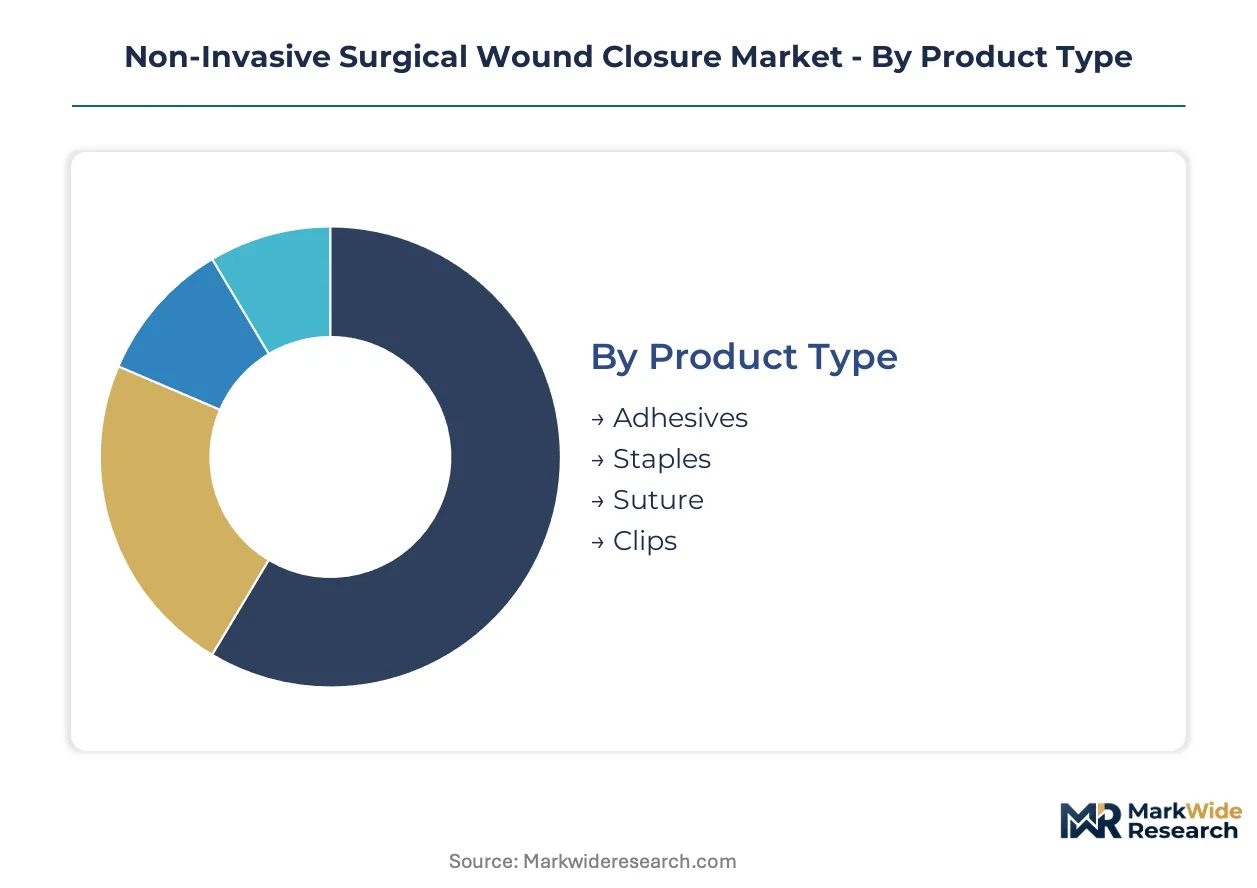
Wound closure segmentation reveals how technology maturity and reimbursement economics partition commercial opportunity. Product categories span disposable adhesives through capital-intensive energy platforms, while end-user channels diverge sharply between inpatient infrastructure and ambulatory throughput models.
Product Type:
Cost tier determines procurement authority and margin structure across the four product categories, with premium formulations competing against legacy mechanical systems.
- Adhesives:Cyanoacrylate and polyethylene glycol polymer systems deliver tensile strength exceeding 200 psi without percutaneous penetration. Demand concentrates in pediatric wards and cosmetic suites across United States metropolitan hospitals where scar minimization justifies premium positioning.
- Staples:Mechanical compression devices approximate tissue edges through titanium or stainless steel delivery systems. Procurement committees in German and Japanese acute-care networks favor staples for high-tension closures where adhesive curing times exceed procedural windows.
- Suture:Conventional needle-and-thread systems retain cost advantage in price-sensitive procurement environments. Emerging market distributors in India and Brazil prioritize suture inventory for hernia and cataract volume.
- Clips:Absorbable and non-absorbable mechanical fasteners target laparoscopic port sites and superficial fascia. United States ambulatory surgery centers stock polymer clips for same-day discharge protocols.
Adhesives command the established base. The steepest expansion runs through clips optimized for minimally invasive port closure.
End User:
Customer type fragmentation mirrors the structural migration of surgical volume from inpatient beds to outpatient throughput environments.
- Hospitals:Integrated delivery networks in Texas and Florida metropolitan corridors negotiate enterprise-wide contracts spanning adhesives through mechanical clips. Formulary committees prioritize FDA 510(k) clearance documentation for novel polymer platforms.
- Clinics:Physician office laboratories and minor procedure rooms stock adhesive strips and tissue adhesives for laceration repair. Reimbursement coding complexity limits penetration of advanced closure systems.
- Outpatient Facilities:Standalone surgical facilities outside hospital licensing frameworks seek rapid-application platforms compatible with nursing staff scope-of-practice limitations. German outpatient surgery centers pilot hybrid adhesive-clip systems under EU MDR transitional provisions.
- Ambulatory Surgery Centers:CMS reimbursement shifts favor outpatient wound closure modalities over inpatient suture protocols. Facility operators in United States same-day markets stock adhesive platforms to minimize procedure time and eliminate needlestick exposure protocols.
Hospitals retain the volume anchor. Ambulatory surgery centers are gaining share fastest as procedural migration accelerates.
Application:
Application specialization drives polymer formulation requirements and regulatory predicate selection across surgical disciplines.
- Orthopedic Surgery:High-tension joint capsule and fascia closures demand mechanical staples or reinforced adhesive strips. United States sports medicine practices favor absorbable clip systems for arthroscopic port sites.
- Cardiovascular Surgery:Fragile vascularized tissues require ultrasonic welding or specialized low-exotherm adhesives. Academic medical centers in Japan pilot thermal protein bonding for sternal closure.
- General Surgery:Breadth of closure sites from skin through fascia supports multi-modal platform stocking. Indian Ayushman Bharat-funded facilities prioritize cost-optimized suture and staple combinations for high-volume hernia repair.
- Cosmetic Surgery:Scar-minimization outcomes justify premium cyanoacrylate formulations with cosmetic-grade curing profiles. Aesthetic surgery suites in United States coastal metropolitan markets specify adhesive systems with demonstrated histological acceptance data.
General surgery commands the established base. Cosmetic surgery is climbing the fastest as elective procedure volume recovers.
Technology:
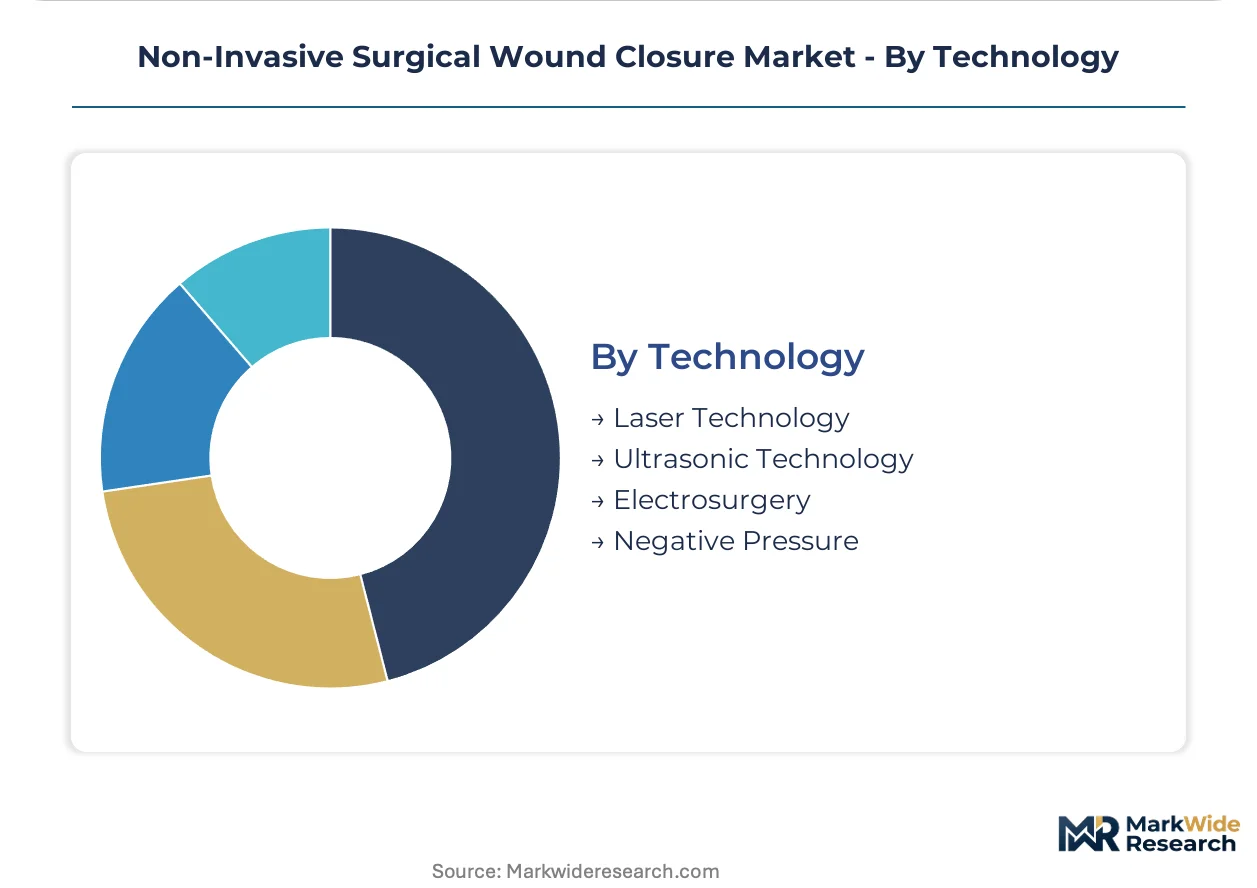
Technology maturity stratifies between established electrosurgical platforms and emerging energy-based modalities with limited predicate availability.
- Laser Technology:Coherent light sources achieve tissue welding through controlled thermal denaturation. CE marking under EU MDR intensifies post-market surveillance obligations for European laser platform sponsors.
- Ultrasonic Technology:High-frequency mechanical vibration generates frictional heat for protein structure bonding without foreign material implantation. Academic medical centers in United States and Germany pilot hybrid systems combining ultrasonic welding with adhesive reinforcement for vascular anastomosis.
- Electrosurgery:Radiofrequency and bipolar current platforms dominate established thermal closure with extensive predicate-device libraries. Hospital capital equipment committees prioritize electrosurgical units with integrated documentation connectivity.
- Negative Pressure:Vacuum-assisted closure systems manage open wounds through macrodeformation and microdeformation of granulation tissue. United States wound care centers specify negative pressure platforms for dehisced surgical closures.
Electrosurgery commands the established base. Ultrasonic technology is gaining share fastest as predicate-device pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical manufacturers export medical-grade cyanoacrylate monomers to adhesive formulators in the United States and Japan, establishing a trade-flow corridor that concentrates raw material supply in Central Europe while demand clusters in North American and East Asian surgical markets.
United States
Medicare reimbursement shifts favor outpatient wound closure modalities over inpatient suture protocols, accelerating adhesive platform stocking in same-day surgical facilities. FDA 510(k) clearance pathways compress time-to-market for novel cyanoacrylate reformulations to 90-day cycles. Texas and Florida metropolitan corridors concentrate integrated delivery network purchasing authority through enterprise-wide formulary contracts.
Germany
Notified-body scrutiny under EU MDR extends CE marking timelines for novel polymer platforms, particularly for electrosurgical and laser-based wound closure systems. German outpatient surgery centers pilot hybrid adhesive-clip systems under transitional provisions. The Rhine-Ruhr chemical production corridor anchors medical-grade cyanoacrylate monomer supply for European and export markets.
Japan
PMDA regulatory frameworks govern biocompatibility documentation requirements for thermal protein bonding technologies entering clinical use. Academic medical centers in Tokyo and Osaka pilot ultrasonic welding systems for sternal and vascular anastomosis applications. The Kanto region concentrates device distribution networks serving high-volume metropolitan surgical facilities.
India
Ayushman Bharat expansion funds same-day surgical facilities in tier-2 and tier-3 cities, creating procurement demand for cost-optimized adhesive platforms compatible with high-throughput cataract and hernia protocols. CDSCO medical device regulations require local clinical evaluation for novel polymer formulations. Maharashtra and Gujarat host domestic device distributors seeking partnerships with international adhesive manufacturers.
United Kingdom
NHS procurement frameworks prioritize MDR compliance certification as a gatekeeping criterion in tender evaluations for wound closure categories. London and Southeast England surgical hubs stock multi-modal closure platforms spanning adhesives through mechanical clips. The Midlands region concentrates contract research organization capacity supporting ISO 10993 biocompatibility testing for European market entry.
Non-Invasive Surgical Wound Closure Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base stratifies between diversified medical technology conglomerates with acute-care distribution density and focused adhesive manufacturers with materials science capabilities. Three archetypes dominate: diversified surgical device conglomerates with formulary control, specialty adhesive manufacturers with polymer chemistry expertise, and emerging ultrasonic technology developers with academic medical center partnerships. Competitive moves concentrate on strategic partnerships for regulatory predicate access and portfolio diversification into hybrid mechanical-adhesive systems.
Among diversified surgical device conglomerates, Johnson & Johnson and Medtronic exemplify channel-control archetypes through acute-care distribution network density. Baxter occupies a position within the integrated wound-care bundle tier, while 3M represents materials science heritage in proprietary adhesive portfolios. B. Braun and Smith & Nephew sit within the European-centered surgical device tier with established notified-body relationships.
| Leading Market Players |
|---|
| Johnson & Johnson |
| 3M |
| Medtronic |
| Baxter |
| B. Braun |
| Smith & Nephew |
| Stryker |
| Integra LifeSciences |
| Corza Health |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr chemical production corridor anchors medical-grade cyanoacrylate monomer capacity for adhesive formulators, concentrating upstream supply leverage among German chemical manufacturers who export to United States and Japanese device sponsors. This geographic clustering grants raw material suppliers pricing power over downstream wound closure platforms, particularly for novel polymer formulations requiring high-purity monomer grades.
Pricing Analysis
Next-generation ultrasonic welding platforms command substantial premiums over established electrosurgical systems, while prior-generation suture lines face commoditization pressure. Three-tier pricing structure across premium cyanoacrylate formulations, standard adhesive strips, and economy suture bundles reflects FDA 510(k) clearance tier and clinical outcome documentation depth. Pricing pressure stems from CMS reimbursement compression in outpatient settings, with ambulatory surgery centers exhibiting highest price sensitivity and academic medical centers showing lowest sensitivity due to research funding buffers.
Supply Chain Analysis
Contract manufacturing for adhesive polymer systems concentrates among German specialty chemical houses and Japanese precision coating facilities serving United States device sponsors. Raw material dependencies center on medical-grade cyanoacrylate monomers, titanium staple substrates, and absorbable polymer resins. Single-source vulnerability runs through the Rhine-Ruhr corridor, where production disruptions propagate globally. Distribution runs through integrated delivery network formularies in Texas and Florida metropolitan corridors, with group purchasing organizations matching pricing tiers for independent ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in procedural volume recovery as elective surgery backlogs clear and ambulatory migration accelerates, with cyclical demand tied to hospital capital equipment refresh cycles.
For Market Incumbents: Insulate formulary positions by deepening captive supply of medical-grade monomers through backward integration into German chemical production partnerships. Prioritize ISO 10993 biocompatibility certification investment to accelerate predicate-device matching for novel adhesive platforms, defending against ultrasonic technology entrants targeting vascularized tissue applications.
For New Entrants and Emerging Players: Establish a beachhead in Indian Ayushman Bharat-funded outpatient facilities where cost-optimized adhesive demand outstrips domestic supply. Target hybrid adhesive-clip systems for German outpatient surgery centers operating under EU MDR transitional provisions, leveraging white-space in notified-body relationships held by European-centered surgical device tiers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because channel density in acute-care distribution networks determines pricing power and procurement access. Acquisition targets include specialty adhesive manufacturers with polymer chemistry expertise and established FDA 510(k) predicate libraries. The signal to watch is CMS reimbursement code expansion for adhesive-based closures in outpatient settings versus traditional suture tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined clearance compresses time-to-market for cyanoacrylate reformulations targeting 90-day cycles. |
| Hospital System Partnership | Enterprise-wide formulary contracts in Texas and Florida corridors lock out competing adhesive platforms. |
| Backward Integration into Monomer Supply | Captive production of medical-grade cyanoacrylate insulates margins from Rhine-Ruhr supply disruptions. |
| CE Marking Pathway Investment | EU MDR compliance certification satisfies NHS procurement gatekeeping and German outpatient tender requirements. |
| Software Companion Development | Digital integration captures procedure data and automates replenishment for integrated delivery networks. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, GPO contracts managers, biomedical engineers, and regulatory affairs leads at adhesive manufacturers, then refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 10993 biocompatibility study registries. Bottom-up demand modeling triangulated with top-down market sizing across product type, end user, application, and technology dimensions.
Demand-supply balance framing anchored the analytical framework, with segmentation across adhesives, staples, sutures, and clips by product type; hospitals, clinics, outpatient facilities, and ambulatory surgery centers by end user; and electrosurgery, ultrasonic, laser, and negative pressure by technology. CAGRs were derived from procedure volume migration trends and reimbursement elasticity estimates, incorporating adhesive curing kinetics data and predicate-device clearance timelines as industry-specific inputs across the projection horizon.
Stress conditions across raw material supply disruptions, EU MDR compliance timeline extensions, and CMS reimbursement code revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procedural volume migration and regulatory pathway efficiency. Quarterly review of FDA 510(k) clearance velocity and ambulatory surgery center stocking patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Wound Care Biologics Market
Wound Care
Alginate Dressing Market
Wound Care
Surgical Wound Care Market
Wound Care
Wound Healing Nutrition Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
US Wound Care Management Devices Market
Wound Care
France Wound Care Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Patch Based Wound Healing Products Market