
 Global Breast Implants Market | 2026-2036
Global Breast Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Implants Market Foresight
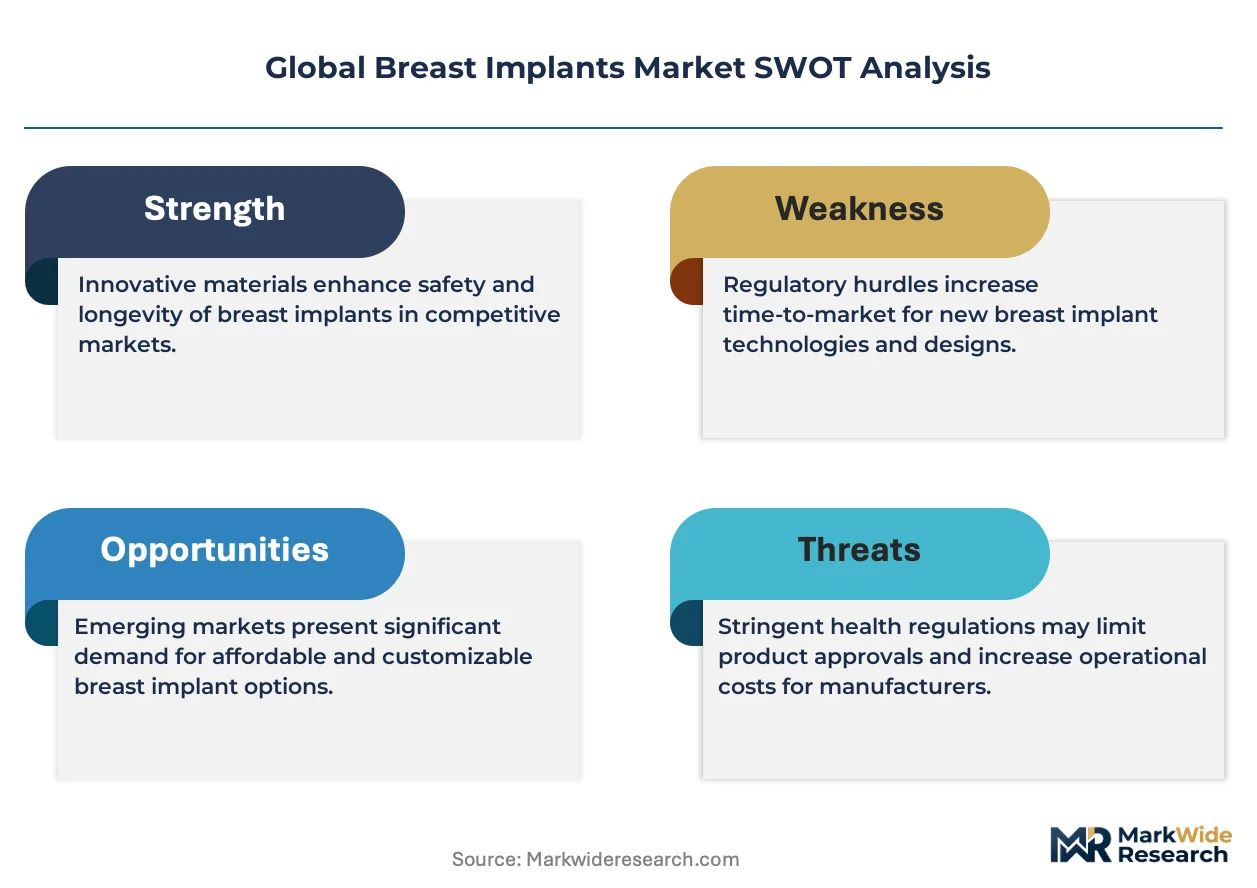
The gap between premium silicone gel implants and basic saline alternatives is shifting from a price divide to a clinical-outcomes hierarchy. Mentor Worldwide LLC leverages its vertically integrated manufacturing infrastructure to sustain cost advantages across the Americas. Establishment Labs anchors its competitive position through proprietary surface technologies that differentiate its anatomical portfolio. Sientra, Inc. specializes in high-strength cohesive gel formulations that command premium positioning among board-certified plastic surgeons.
Breast implants are medical prostheses comprising an elastomer silicone shell filled with either viscous silicone gel or sterile saline solution, engineered to restore or augment mammary contour through submuscular or subglandular placement. Silicone gel variants dominate value pools due to superior tactile properties and lower capsular contracture rates in long-term follow-up studies. Reconstructive surgery applications represent a mature, reimbursement-backed segment, while gender affirmation procedures constitute the fastest-expanding application category as specialized surgical centers proliferate. Round implant shapes retain volume leadership, though anatomical and teardrop configurations capture disproportionate margins through premium pricing tied to custom-fit surgical planning.
The FDA enforces stringent premarket approval pathways and post-approval safety surveillance for silicone gel devices, directly elevating compliance costs and consolidation pressure among smaller manufacturers. Europe's MDR and EMA oversight through notified bodies impose parallel clinical evidence requirements that filter market access for non-EU producers. ISO 14630 and ISO 10993 biocompatibility standards establish baseline material safety protocols recognized across multiple jurisdictions. Stakeholders must monitor evolving regulatory divergence between the FDA's risk-classification framework and the EU's enhanced post-market clinical follow-up mandates to align portfolio investments with compliance trajectories.
Market Dynamics
The FDA's updated silicone gel breast implant labeling requirements are forcing manufacturers to restructure patient informed-consent protocols and post-market surveillance systems. This regulatory pressure is compressing margins while accelerating consolidation among smaller producers unable to absorb compliance costs.
Growth Catalysts
- Gender Affirmation Surgery Expansion:Specialized surgical centers in Brazil and South Korea are scaling procedural volumes for gender affirmation applications, creating new demand pools outside traditional aesthetic and reconstructive segments.
- ISO 14630 Biocompatibility Standards:Harmonized material safety protocols across multiple jurisdictions are reducing regulatory friction for qualified manufacturers seeking multi-market entry.
- Private Clinic Network Density:Premium silicone gel adoption concentrates in the United States and Germany where vertically integrated clinic chains drive volume through standardized surgical protocols.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Raw material production clusters in Germany and Japan create vulnerability to input cost volatility and geopolitical supply disruptions.
- FDA Premarket Approval Pathway Duration:Extended clinical trial requirements and post-approval safety surveillance mandates delay product commercialization and elevate R&D amortization burdens.
- Saline Alternative Price Competition:Basic saline-filled implants retain cost-sensitive segment share despite inferior tactile properties, capping premium silicone gel pricing power in budget-constrained markets.
Strategic Opportunities
- Anatomical Configuration Premiumization:Teardrop and custom-fit implant shapes command disproportionate margins through surgical planning software integration and patient-specific modeling capabilities.
- Europe MDR Compliance Gap Exploitation:Enhanced post-market clinical follow-up mandates under the EU's Medical Device Regulation are filtering market access, creating first-mover advantages for prepared manufacturers.
- Telemedicine-Enabled Remote Consultation:Digital pre-operative assessment platforms are expanding geographic reach for specialized aesthetic surgery centers into underserved secondary cities.
Industry Challenges
- Capsular Contracture Surveillance Expertise:Long-term patient monitoring requires specialized clinical research infrastructure that mid-tier manufacturers struggle to fund and staff.
- Surface Technology IP Fragmentation:Proprietary texturing and nano-surface innovations face patent thickets and licensing complexity that slow product differentiation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Implants Market |
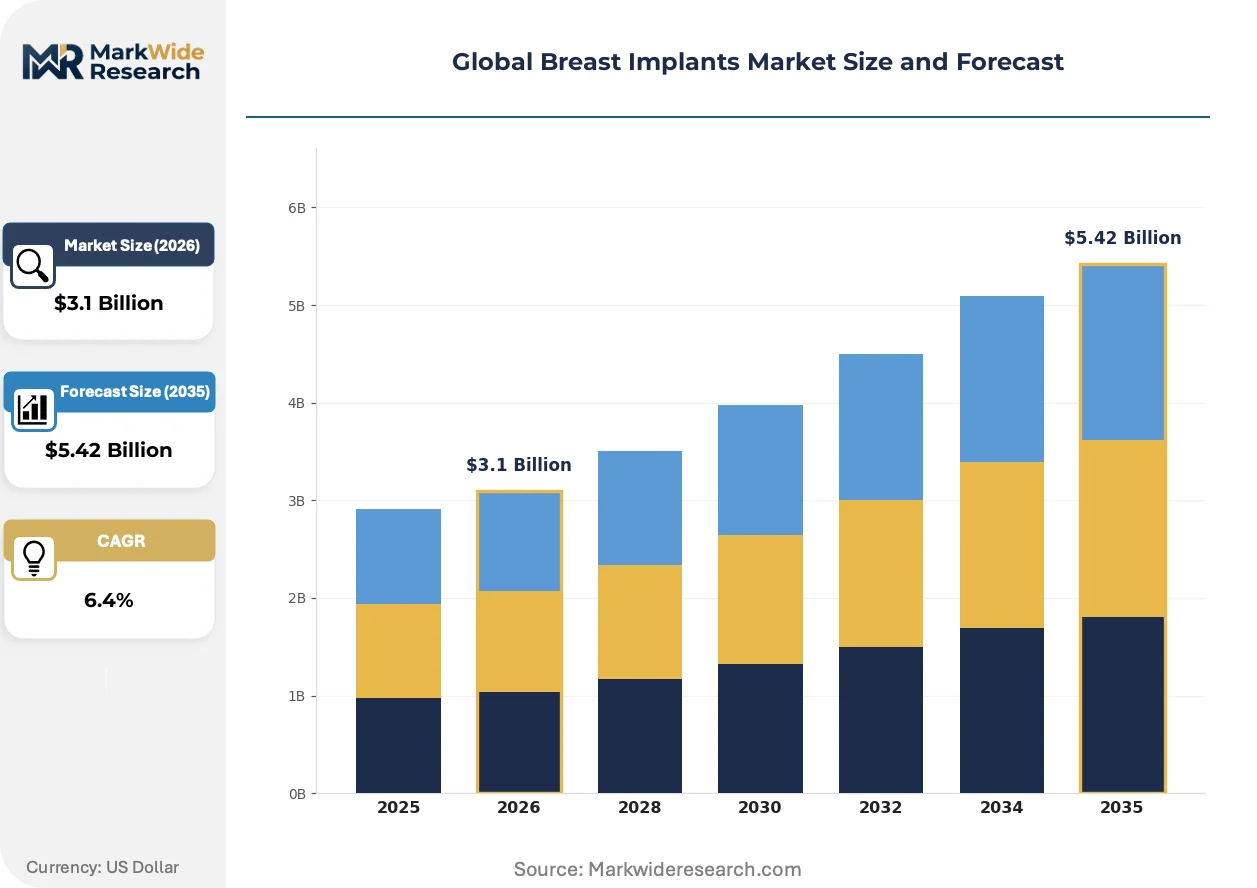
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gel, Saline, Structured, Composite, Polyurethane Implant Shape: Round, Anatomical, Teardrop, Contour, Custom Molded Application: Reconstructive Surgery, Cosmetic Enhancement, Gender Affirmation, Correction of Congenital Deformities, Post-Trauma Repair End User: Private Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Aesthetic Surgery Centers, Dermatology Clinics |
| Companies Covered | Allergan Aesthetics, Mentor Worldwide LLC, Sientra, Inc., Establishment Labs, GC Aesthetics, Sebbin, Polytech Health & Aesthetics, HansBiomed, Silimed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Implants Market Shifts & Advancements
Patient-specific surgical planning is displacing standardized implant selection across premium aesthetic segments. Three interconnected developments are compressing traditional procurement models while elevating outcomes-based competition.
3D imaging and additive manufacturing integration is decentralizing implant customization from centralized manufacturing to distributed surgical planning workflows. High-volume aesthetic surgery centers in South Korea and Brazil are adopting patient-specific anatomical modeling at scale. This technology is decentralizing production planning authority from manufacturers to board-certified surgeons equipped with in-house modeling capabilities.
The EU's Medical Device Regulation (MDR) is mandating enhanced post-market clinical follow-up and systematic literature review obligations for silicone gel devices. Manufacturers must now maintain active implant registries and submit periodic safety update reports beyond initial CE marking. High-strength cohesive gel formulations face the steepest compliance escalation, driving portfolio rationalization toward evidence-rich product lines.
Direct-to-consumer digital education platforms are compressing the traditional surgeon-mediated information pathway. Prospective patients in the United States and Germany now research surface technologies and fill cohesivity specifications before initial consultation. This behavior shift elevates manufacturer brand recognition over clinic loyalty, rewarding companies with transparent safety data repositories and interactive outcome visualization tools.
Global Breast Implants Market Segmentation
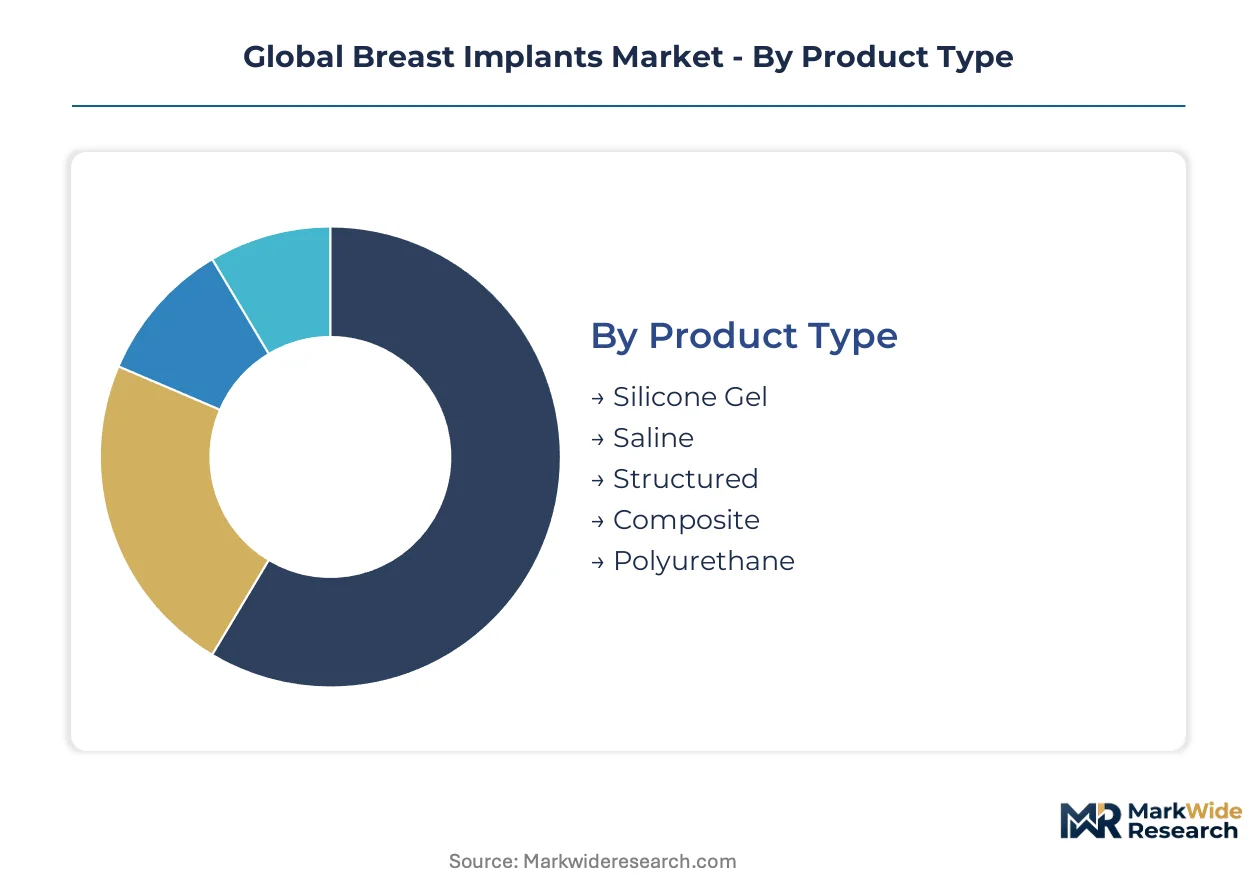
Segmentation in the breast implants market reflects divergent clinical priorities across aesthetic and reconstructive pathways. Manufacturers configure product portfolios around tactile performance, surgical placement requirements, and end-user procurement sophistication rather than uniform specifications.
Product Type:
Customization versus standardization varies sharply across this category, with formulation chemistry and shell engineering determining clinical positioning.
- Silicone Gel:High-strength cohesive gel formulations deliver superior tactile properties and reduced capsular contracture rates in long-term FDA surveillance studies. Demand concentrates in private clinic networks across the United States and Germany, where premium positioning aligns with board-certified plastic surgeon preferences for aesthetic applications.
- Saline:Sterile saline-filled shells offer intraoperative volume adjustability and simpler explantation protocols. Cost-sensitive procurement in ambulatory surgical centers and budget-constrained markets sustains volume despite inferior aesthetic outcomes and higher rippling incidence.
- Structured:Internal baffle architectures reduce fluid movement and improve shape retention in subglandular placement.
- Composite:Hybrid filler systems combine gel and saline layers for intermediate performance positioning.
- Polyurethane:Foam-coated surfaces reduce capsular contracture through tissue integration, with concentrated use in European reconstructive protocols.
Leading the category by volume: Silicone Gel. Expanding most quickly: Structured configurations.
Implant Shape:
Margin stratification across this category follows surgical planning complexity and patient-specific modeling adoption.
- Round:Symmetrical profiles simplify surgical placement and inventory management for high-volume aesthetic centers. Standardized sizing dominates procedural volumes in Brazil and South Korea, where operational efficiency priorities override custom-fit considerations.
- Anatomical:Asymmetric base dimensions with tapered upper poles mimic natural breast contour. Premium pricing in German and US private clinics reflects integration with 3D surgical planning software and patient-specific modeling workflows.
- Teardrop:Heightened projection at lower pole addresses specific aesthetic goals in gender affirmation procedures.
- Contour:Variable base widths accommodate chest wall asymmetries in reconstructive applications.
- Custom Molded:Additive-manufactured shells from patient imaging data command highest per-unit margins.
Dominating volume: Round shapes. Gaining share fastest: Custom Molded configurations.
Application:
Reimbursement architecture and out-of-pocket payment dynamics create divergent growth trajectories across clinical use cases.
- Reconstructive Surgery:Post-mastectomy restoration constitutes a mature, reimbursement-backed segment with established clinical protocols. Volume concentrates in specialty hospitals across the United States, where insurance coverage mandates drive standardized silicone gel adoption.
- Gender Affirmation:Chest masculinization and feminization procedures are climbing the fastest as specialized surgical centers proliferate in Brazil and South Korea. Out-of-pocket payment models and dedicated clinical infrastructure support premium product positioning.
- Cosmetic Enhancement:Elective augmentation remains the largest value pool in aesthetic surgery centers.
- Correction of Congenital Deformities:Poland syndrome and tuberous breast corrections require anatomical customization.
- Post-Trauma Repair:Burn and injury reconstruction utilizes both temporary tissue expanders and permanent implants.
Generating highest revenue: Cosmetic Enhancement. Steepest expansion trajectory: Gender Affirmation.
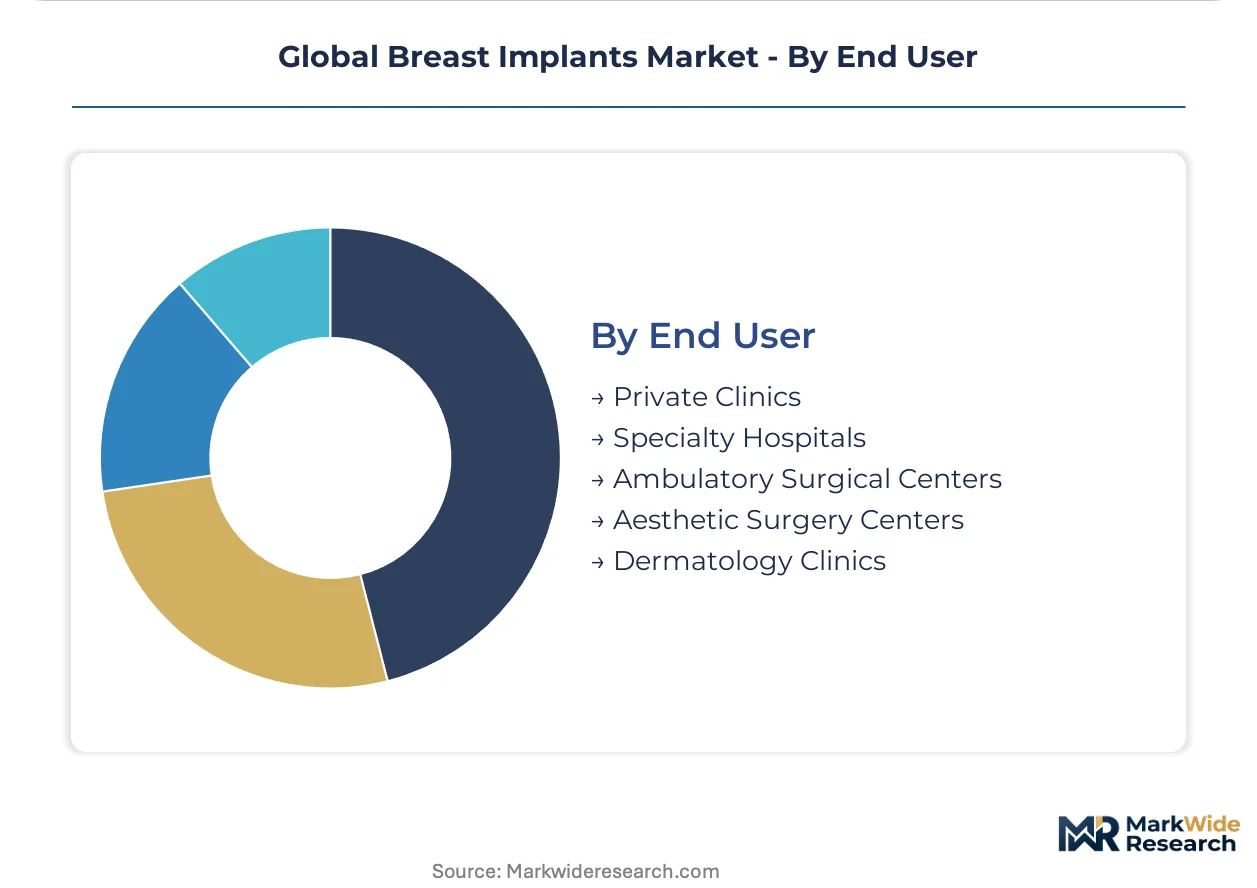
End User:
Procurement sophistication and volume scale determine product mix and pricing power across facility types.
- Private Clinics:Vertically integrated aesthetic networks in Germany and the United States standardize on premium silicone gel portfolios through centralized purchasing agreements. Direct manufacturer relationships and high procedural density support favorable unit economics and preferred access to anatomical configurations.
- Aesthetic Surgery Centers:Specialized facilities in South Korea and Brazil combine high throughput with advanced surgical planning capabilities. Patient-specific modeling adoption and gender affirmation specialization differentiate procurement requirements from general plastic surgery practices.
- Specialty Hospitals:Academic medical centers manage reconstructive case complexity and resident training needs.
- Ambulatory Surgical Centers:Cost-focused models favor saline alternatives and streamlined inventory.
- Dermatology Clinics:Limited procedural scope restricts implant procurement to collaborative arrangements.
Highest volume concentration: Private Clinics. Fastest facility expansion: Aesthetic Surgery Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district anchors procedural volume for gender affirmation surgery, while São Paulo's aesthetic surgery corridors drive silicone gel adoption across Latin America. The United States, Germany, Brazil, South Korea, and Japan concentrate manufacturing capacity, regulatory expertise, and high-volume clinical infrastructure.
United States
Private clinic networks in Miami and Los Angeles standardize premium silicone gel portfolios through centralized purchasing agreements. The FDA enforces stringent premarket approval pathways and post-approval safety surveillance that elevate compliance costs and compress margins among smaller producers. Board-certified plastic surgeons in academic medical centers drive reconstructive volume through insurance-backed protocols.
Germany
Medical-grade silicone production clusters in the Ruhr region and Bavaria supply raw materials to implant manufacturers across Europe. The EMA and notified bodies under the MDR impose enhanced post-market clinical follow-up mandates that filter market access for non-EU producers. Frankfurt and Munich host vertically integrated aesthetic clinic chains that command favorable unit economics through high procedural density.
Brazil
Specialized surgical centers in São Paulo and Rio de Janeiro scale gender affirmation procedural volumes faster than any other market segment. ANVISA regulates silicone gel devices through parallel clinical evidence requirements that align with FDA risk-classification frameworks. The country's aesthetic surgery culture supports out-of-pocket payment models that sustain premium product positioning.
South Korea
Gangnam's high-volume aesthetic surgery centers adopt patient-specific anatomical modeling at scale through 3D imaging integration. The MFDS enforces biocompatibility standards harmonized with ISO 14630 protocols that reduce regulatory friction for qualified manufacturers. Seoul-based clinics combine throughput efficiency with advanced surgical planning capabilities that differentiate procurement requirements from general plastic surgery practices.
Japan
Reconstructive applications dominate procedural mix in Tokyo and Osaka specialty hospitals with established insurance reimbursement pathways. The PMDA maintains rigorous clinical trial requirements that delay product commercialization and elevate R&D amortization burdens for market entrants. Medical-grade silicone supply from domestic chemical producers insulates manufacturers from geopolitical input cost volatility.
Global Breast Implants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across surface technology differentiation and cohesive gel formulation chemistry. The market consolidates around vertically integrated manufacturers with captive silicone supply chains and specialized surgical planning software integration. Three archetypes dominate: formulation specialists commanding premium positioning through high-strength cohesive gels, surface technology innovators leveraging proprietary texturing IP, and scale-driven producers optimizing cost structures across standardized round implant portfolios. Competitive moves concentrate on M&A to secure manufacturing capacity and strategic partnerships with high-volume aesthetic surgery centers.
Within the premium-tier vector, Allergan Aesthetics and Mentor Worldwide LLC occupy positions anchored by vertically integrated manufacturing infrastructure and established surgeon training networks. Sientra, Inc. exemplifies the formulation specialist archetype through its focus on high-strength cohesive gel portfolios. Establishment Labs represents surface technology differentiation through proprietary innovations in anatomical implant configurations. These three companies illustrate how competitive positioning stratifies across manufacturing scale, material science expertise, and clinical evidence depth.
| Leading Market Players |
|---|
| Allergan Aesthetics |
| Mentor Worldwide LLC |
| Sientra, Inc. |
| Establishment Labs |
| GC Aesthetics |
| Sebbin |
| Polytech Health & Aesthetics |
| HansBiomed |
| Silimed |
| Others |
Supply & Pricing Matrix
Private clinic networks in the United States and Germany concentrate procurement authority and enforce value-based pricing tied to surgical outcomes and patient satisfaction metrics rather than unit costs alone.
Pricing Analysis
Outcome-based pricing anchors premium tiers where high-strength cohesive gel formulations command superior positioning through demonstrated capsular contracture reduction in FDA surveillance data. Price differentiation separates FDA-approved silicone gel portfolios from basic saline alternatives through certification grade and tactile performance tier. Cost compression in saline-filled segments intensifies as ambulatory surgical centers prioritize inventory simplicity over aesthetic outcomes. Ambulatory centers exhibit highest price sensitivity while German private clinic networks demonstrate lowest sensitivity due to standardized premium procurement protocols.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade silicone production clusters in Germany and Japan that feed shell manufacturing and gel formulation facilities worldwide. Raw material dependencies center on elastomer silicone polymers, platinum catalyst systems, and sterile saline solutions. Tariff exposure on Japanese medical-grade silicone imports creates margin volatility for non-vertically integrated manufacturers. Distribution runs through manufacturer-direct relationships with high-volume aesthetic surgery centers and specialized surgical distributors serving secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is transitioning from standardized implant selection toward patient-specific anatomical modeling, with 3D surgical planning software displacing legacy procurement workflows across premium segments.
For Market Incumbents: Acquire surface technology IP portfolios to defend against formulation specialists eroding margin through proprietary texturing claims. Consolidate manufacturing capacity in Ruhr region and Bavaria clusters to secure captive silicone supply. Backward integration into medical-grade silicone production insulates against Japanese supply volatility and ANVISA regulatory alignment costs. For New Entrants and Emerging Players: The mid-tier pricing gap between premium silicone gel and economy saline configurations offers white-space entry for structured implant architectures with intermediate performance positioning. Target aesthetic surgery centers in São Paulo and Seoul where patient-specific modeling adoption outpaces manufacturer software capabilities. Lead with telemedicine-enabled remote consultation platforms to bypass established clinic relationships. For Investors and Strategic Acquirers: The window for entry favors formulation specialists with FDA-approved high-strength cohesive gel portfolios and active implant registry infrastructure. Long-term viability hinges on evidence depth rather than manufacturing scale, with MDR compliance capabilities serving as the primary moat. Watch for EMA safety update report submissions as inflection indicators for portfolio rationalization trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Patient-Specific Modeling Platform Development | 3D surgical planning software integration shifts procurement authority from manufacturers to board-certified surgeons. |
| MDR Compliance Infrastructure Buildout | Enhanced post-market clinical follow-up mandates under EU Medical Device Regulation filter market access for prepared manufacturers. |
| Gender Affirmation Center Partnership | Specialized surgical centers in Brazil and South Korea scale procedural volumes faster than traditional aesthetic segments. |
| Surface Technology IP Acquisition | Proprietary nano-texturing innovations differentiate anatomical portfolios against commodity round implant competition. |
| Telemedicine-Enabled Remote Consultation Launch | Digital pre-operative assessment platforms expand geographic reach into underserved secondary cities. |
Research Methodology
Document review covered FDA premarket approval filings, EMA periodic safety update reports, and ISO 14630 biocompatibility standards, complemented by interviews with board-certified plastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from ANVISA regulatory databases, MFDS device registrations, and academic medical center procurement records. Bottom-up procedural volume estimates triangulated against top-down manufacturer capacity assessments.
Historical procedural volume trajectories cross-referenced against expert panel inputs on regulatory timeline shifts and technology adoption curves across the projection horizon. Segmentation modeling addressed product type, implant shape, application pathway, and end-user facility tier. CAGRs were derived from elasticity-adjusted demand functions incorporating reimbursement policy changes and patient demographic shifts.
Inputs from FDA surveillance studies and EMA post-market clinical follow-up databases were available through the study window; gaps in long-term gender affirmation procedure registries introduce uncertainty bands around fastest-expanding segment forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Hysteroscope Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Gracey Curette Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Band Ligators Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market