
 Syringe Filling Machine Market | 2026-2036
Syringe Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
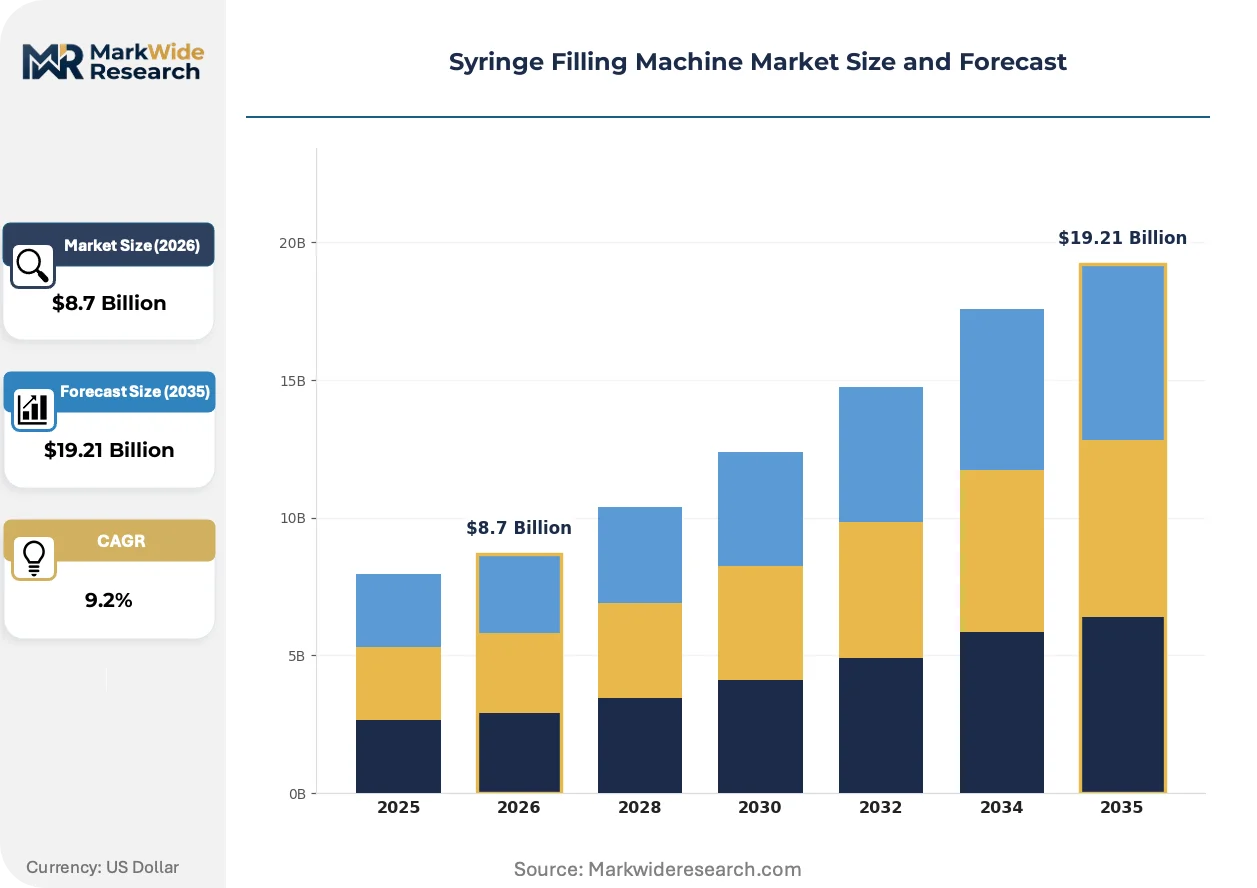
Syringe Filling Machine Market Analysis
Direct equipment procurement from pharmaceutical manufacturers is fragmenting as Contract Manufacturing Organizations build captive filling capabilities and multi-product facilities diversify supplier relationships. Syntegon Technology GmbH leverages its isolator-integrated rotary platform portfolio to dominate high-speed biologics lines. Groninger & Co. GmbH anchors German precision engineering through custom-built containment solutions for potent compounds. IMA Group competes across price tiers with modular electric systems designed for rapid format changeover.
A syringe filling machine is an automated or semi-automated production system designed to dose sterile liquid or viscous drug products into pre-sterilized syringe barrels at rates ranging from dozens to over 600 units per minute, with fill accuracy typically within plus or minus one percent. These machines incorporate in-process check-weighing, nitrogen overlay, and stopper placement to maintain product stability and sterility throughout the aseptic processing sequence. Automatic syringe fillers command the largest installed base due to throughput requirements in commercial vaccine manufacturing, while servo-driven systems represent the fastest-expanding technology segment as magnetic linear drives replace pneumatic actuators for improved dosing precision and reduced particle generation. Laboratory syringe fillers occupy a distinct margin pool where single-use fluid path configurations and compact isolator footprints address early-phase clinical material needs.
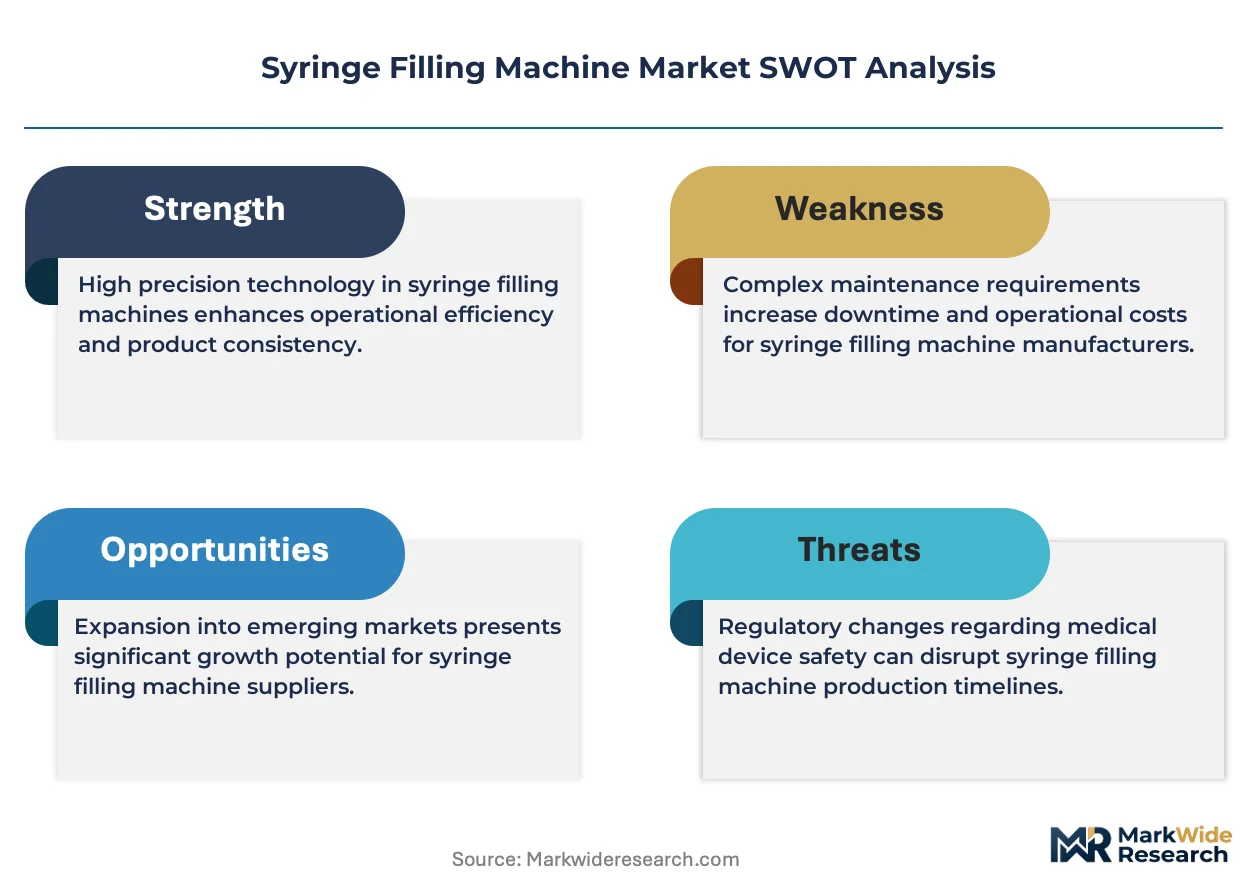
The FDA, EMA, and EU GMP Annex 1 frameworks collectively mandate continuous viable and non-viable environmental monitoring, compelling upgrades to closed restricted access barrier systems and isolator-based filling architectures. The EU AI Act and FDA's evolving computer system validation guidance further shape demand for machine learning-enabled in-process control and electronic batch record integration. Stakeholders must weigh capital deployment between brownfield retrofit compatibility and greenfield isolator-native designs as regulatory stringency tightens across major pharmaceutical manufacturing jurisdictions.
Market Dynamics
Isolator-integrated filling architectures are displacing conventional restricted access barrier systems as FDA and EU GMP Annex 1 revisions mandate continuous environmental monitoring and closed processing environments for sterile injectables.
Growth Catalysts
- Biologics capacity expansion:Contract Manufacturing Organizations are building captive filling lines for monoclonal antibodies and cell therapies, creating sustained equipment demand across multi-product facilities.
- EU GMP Annex 1 compliance deadlines:Pharmaceutical manufacturers must upgrade to isolator-based or closed barrier systems, accelerating replacement cycles for legacy open-filling equipment.
- Servo-driven dosing technology:Magnetic linear actuators are replacing pneumatic systems to achieve sub-one-percent fill accuracy and reduce particulate generation in high-speed vaccine lines.
Market Restraints
- Stainless steel and specialized alloy costs:Input material volatility for 316L pharmaceutical-grade steel and titanium components compresses margins for equipment fabricators.
- Precision engineering concentration:Critical subsystems including isolator enclosures and servo drives concentrate among German and Swiss component suppliers, creating supply vulnerability.
- Validation timeline compression:FDA computer system validation requirements for electronic batch records extend commissioning periods and delay revenue recognition for machine builders.
Strategic Opportunities
- India biologics manufacturing:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting greenfield investments in sterile injectable capacity.
- Single-use fluid path integration:Convergence of disposable polymer-based product contact surfaces with isolator architectures enables rapid product changeover in clinical-scale filling.
- Machine learning in-process control:EU AI Act frameworks for high-risk AI systems create first-mover advantage for vendors embedding real-time fill-weight feedback and predictive maintenance algorithms.
Industry Challenges
- Aseptic processing expertise scarcity:Qualified engineers capable of isolator qualification, media fill validation, and contamination control strategy implementation command premium compensation and extend project timelines.
- Brownfield retrofit complexity:Legacy filling lines in existing cleanroom suites require structural modifications for isolator integration, including HVAC rebalancing and facility layout reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syringe Filling Machine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Syringe Fillers, Semi-Automatic Syringe Fillers, Manual Syringe Fillers, Laboratory Syringe Fillers End User: Pharmaceutical Companies, Hospitals, Research Laboratories, Contract Manufacturing Organizations Application: Vaccines, Biologics, Injectable Drugs, Diagnostics Technology: Pneumatic Systems, Electric Systems, Servo-Driven Systems, Rotary Systems |
| Companies Covered | Syntegon Technology GmbH, IMA Group, Groninger & Co. GmbH, OPTIMA packaging group GmbH, Cytiva, Dara Pharmaceutical Packaging, Harro Höfliger Verpackungsmaschinen GmbH, Cozzoli Machine Company, NJM Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syringe Filling Machine Market Emerging Trajectories
Magnetic linear drive technology, real-time release testing protocols, and outcome-based equipment performance contracts are restructuring how pharmaceutical manufacturers evaluate and deploy filling automation.
Servo-driven dosing systems utilizing magnetic linear motors are replacing pneumatic piston pumps in high-speed syringe fillers. Commercial vaccine manufacturers and large-molecule biologics facilities are adopting these architectures for fill rates exceeding 600 units per minute. The technology is rendering obsolete mechanical cam-driven filling mechanisms that generate particulates and require frequent maintenance interventions.
EU GMP Annex 1's 2022 revision mandates continuous viable and non-viable particle monitoring throughout Grade A filling zones. Pharmaceutical manufacturers must implement closed restricted access barrier systems or full isolators with automated environmental sampling. High-potency cytotoxic and oncology product lines face the steepest compliance burden, driving demand for integrated isolator-native machine designs over retrofit-compatible alternatives.
Equipment procurement is fragmenting from direct capital purchase toward performance-guaranteed service agreements. Multi-product Contract Manufacturing Organizations now demand throughput commitments, spare parts availability guarantees, and training inclusion from machine vendors. This shift is most pronounced in Germany and Switzerland, where precision engineering clusters support rapid response service networks for biologics manufacturers operating continuous production schedules.
Syringe Filling Machine Market Segmentation
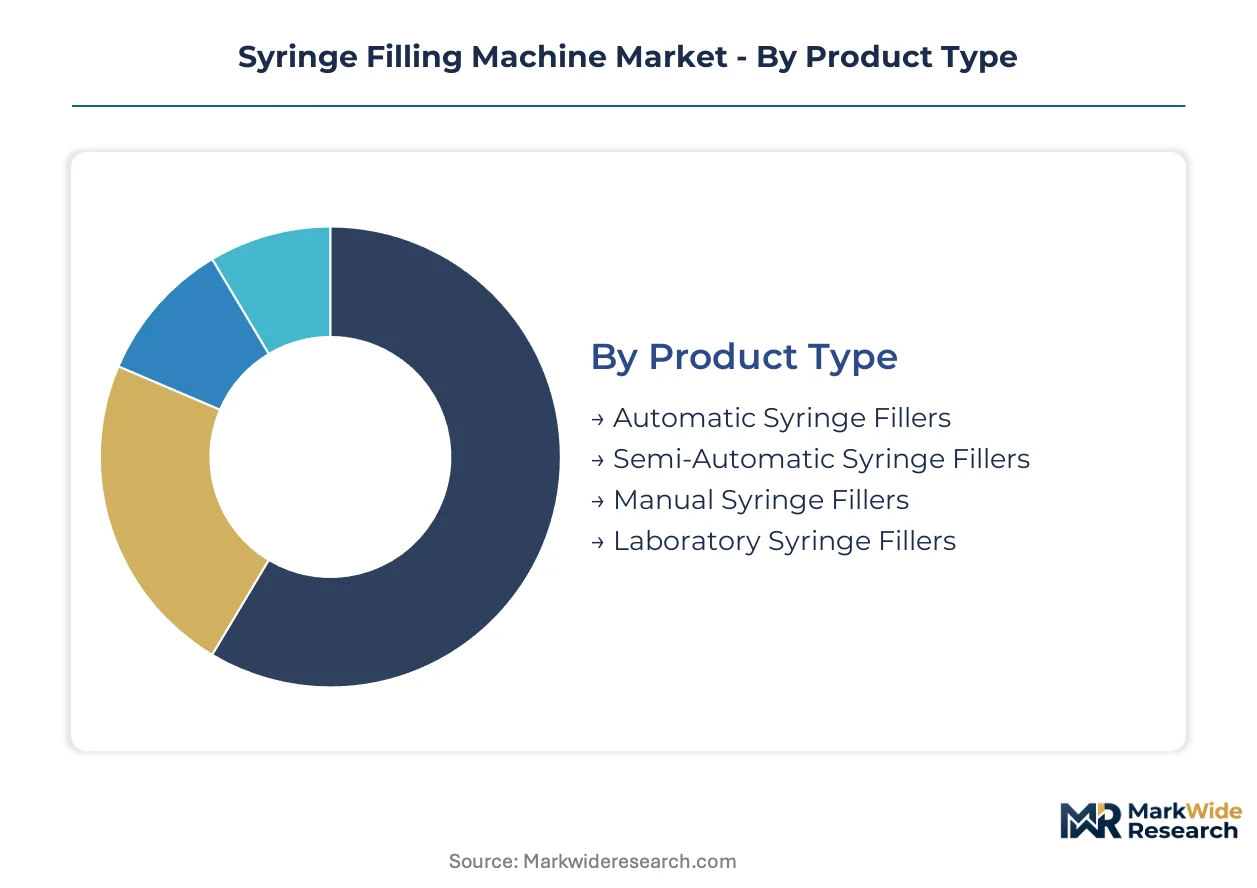
Syringe filling machine procurement patterns diverge sharply across automation levels and end-use settings. Pharmaceutical manufacturers prioritize throughput and isolator integration, while research laboratories demand single-use flexibility and compact footprints.
Product Type:
Automation intensity maps directly to production scale, with commercial vaccine manufacturing demanding continuous high-speed architectures and clinical operations favoring adaptable batch configurations.
- Automatic Syringe Fillers:These systems integrate rotary indexing, servo-driven dosing, and isolator enclosures to achieve fill rates exceeding 600 units per minute with sub-one-percent accuracy. Demand concentrates at multi-product Contract Manufacturing Organizations in Germany, where Syntegon and Groninger anchor precision engineering clusters serving biologics capacity expansion.
- Laboratory Syringe Fillers:Compact benchtop units with single-use fluid paths address early-phase clinical material needs and stability testing requirements. Research laboratories in Switzerland and the United States are adopting these systems to reduce cross-contamination risk during multi-product development campaigns.
- Semi-Automatic Syringe Fillers:Intermediate automation suited for orphan drug manufacturing and mid-scale specialty pharmaceutical operations.
- Manual Syringe Fillers:Hand-operated units retained for compounding pharmacies and veterinary vaccine production with low volume requirements.
The dominant share belongs to Automatic Syringe Fillers, while Laboratory Syringe Fillers are closing the gap fastest.
End User:
Procurement authority is shifting from direct pharmaceutical ownership toward outsourced manufacturing partnerships and captive CMO filling networks.
- Pharmaceutical Companies:Large-scale manufacturers deploy isolator-integrated lines for commercial monoclonal antibody production, with FDA and EU GMP Annex 1 compliance driving replacement of legacy open-filling equipment.
- Contract Manufacturing Organizations:Multi-product facilities demand rapid format changeover and outcome-based service agreements, creating sustained equipment demand across sterile injectable capacity buildouts in India and Germany.
- Hospitals:In-house compounding operations require compact aseptic processing units for patient-specific biologics preparation.
- Research Laboratories:Early-phase development sites prioritize disposable product contact surfaces and reduced validation burden.
Contract Manufacturing Organizations command the steepest growth trajectory, though Pharmaceutical Companies retain the largest installed base.
Application:
Therapeutic category determines containment requirements, with cytotoxic compounds and live virus vaccines demanding the most stringent closed processing architectures.
- Biologics:Monoclonal antibodies, cell therapies, and gene therapy vectors require cold-chain-compatible filling with nitrogen overlay and precision dosing for high-value, low-volume products. German and Swiss precision engineering clusters dominate this segment.
- Vaccines:Pandemic preparedness programs and routine immunization drives sustain demand for high-throughput rotary filling lines with continuous environmental monitoring per EU GMP Annex 1.
- Injectable Drugs:Small-molecule sterile solutions and suspensions fill the mid-tier automation market with established pneumatic system architectures.
- Diagnostics:Reagent filling for molecular and immunoassay applications requires accuracy-focused systems with minimal batch sizes.
Biologics applications lead capital deployment, while Vaccines production shows the most consistent replacement cycle demand.
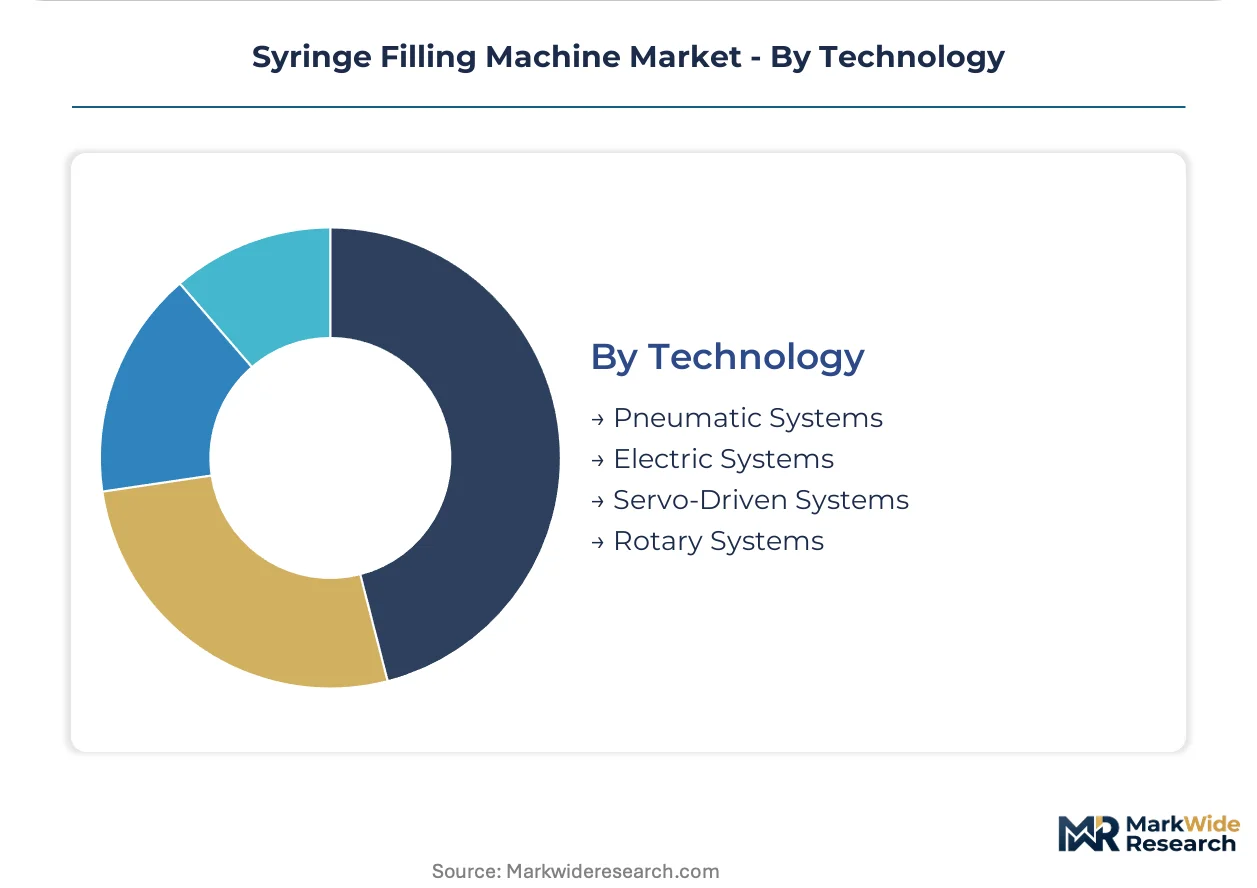
Technology:
Actuation mechanism selection determines particle generation, maintenance intervals, and regulatory validation complexity for sterile manufacturing.
- Servo-Driven Systems:Magnetic linear motors replace pneumatic actuators to eliminate compressed air particulate contamination and achieve precise piston control. Commercial vaccine manufacturers in Germany and the United States are adopting these architectures for fill rates exceeding 600 units per minute.
- Electric Systems:Modular motor-driven designs from IMA Group enable rapid format changeover across multi-product CMO facilities with reduced mechanical complexity versus cam-driven alternatives.
- Pneumatic Systems:Compressed air actuation retains presence in cost-sensitive markets and legacy facility retrofits where isolator integration is constrained by brownfield infrastructure.
- Rotary Systems:Continuous motion architectures maximize throughput for high-volume vaccine and insulin manufacturing with minimal dwell time in Grade A environments.
Servo-Driven Systems are expanding most quickly, though Rotary Systems maintain the largest share of high-speed commercial production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main logistics corridor underwrites Germany's dominance in precision pharmaceutical machinery distribution, connecting Baden-Württemberg engineering clusters to global vaccine manufacturers.
Germany
Baden-Württemberg and Bavaria host Syntegon, Groninger, and Harro Höfliger engineering clusters serving biologics capacity expansion. EU GMP Annex 1 compliance deadlines accelerate isolator-native line investments across Stuttgart and Munich metropolitan manufacturing zones.
United States
Greater Boston and Research Triangle Park biologics corridors drive demand for servo-driven high-speed filling architectures. FDA computer system validation requirements for electronic batch records extend commissioning timelines at Massachusetts and North Carolina contract manufacturing sites.
Switzerland
Basel's pharmaceutical machinery ecosystem supplies containment solutions for high-potency cytotoxic compounds. Swissmedic's alignment with EU regulatory standards enables seamless equipment qualification across German-speaking precision engineering networks.
India
Hyderabad and Bengaluru biologics clusters attract greenfield sterile injectable investments. CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives compress project timelines for multi-product CMO facilities.
China
Yangtze River Delta vaccine manufacturers upgrade to closed barrier systems under NMPA sterile manufacturing guidance. Shanghai and Suzhou precision engineering suppliers develop domestic isolator component alternatives to reduce import dependency.
Syringe Filling Machine Market Vendor Landscape
On the supply side, the industry is consolidating around precision engineering clusters with deep isolator integration capabilities. German and Swiss fabricators command premium positioning through regulatory validation expertise. Three strategic archetypes dominate: isolator-native system architects, modular electric platform specialists, and single-use fluid path integrators. Competitive dynamics center on brownfield retrofit compatibility versus greenfield isolator-native design, alongside outcome-based service contract structures.
Among German precision engineering houses, Syntegon Technology GmbH, Groninger & Co. GmbH, and Harro Höfliger Verpackungsmaschinen GmbH exemplify the isolator-native archetype, anchoring high-containment biologics filling expertise. IMA Group represents the modular electric platform approach, while OPTIMA packaging group GmbH occupies a position across containment and packaging integration tiers.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| IMA Group |
| Groninger & Co. GmbH |
| OPTIMA packaging group GmbH |
| Cytiva |
| Dara Pharmaceutical Packaging |
| Harro Höfliger Verpackungsmaschinen GmbH |
| Cozzoli Machine Company |
| NJM Packaging |
| Others |
Supply Flow & Price Mechanics
The Frankfurt Rhine-Main logistics corridor channels 316L pharmaceutical-grade steel and titanium isolator components from Baden-Württemberg fabricators to global biologics manufacturers, with freight cost volatility amplifying price differentiation between isolator-native system architects and modular electric platform suppliers serving cost-sensitive Contract Manufacturing Organizations.
Pricing Analysis
Volume-discount tiering structures separate isolator-integrated rotary platforms from benchtop laboratory units, with fill-rate thresholds above 400 units per minute commanding premium positioning. Price differentiation rests on EU GMP Annex 1 certification grade and servo-drive precision specifications, with stainless steel input volatility compressing margins at the standard tier. Cost compression in economy-tier pneumatic systems is intensifying as Indian and Chinese domestic suppliers expand capacity. Contract Manufacturing Organizations exhibit the sharpest price sensitivity, while commercial vaccine manufacturers prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Export-control regimes limiting magnetic linear motor and precision isolator enclosure technologies constrain flows from German and Swiss engineering clusters to Chinese vaccine manufacturers. Supply concentration centers on Germany, Switzerland, and the United States for servo-drive actuators, isolator-grade steel alloys, and contamination control subsystems. Component sourcing draws from titanium foundries in the US Midwest, 316L steel mills in the Ruhr region, and ceramic piston suppliers in Bavaria. Single-source vulnerability pervades high-precision linear motor controllers. Distribution runs through OEM direct sales for large pharmaceutical accounts and specialized distributor networks serving mid-scale CMO facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The syringe filling machine market sits in early-cycle expansion, with EU GMP Annex 1 compliance deadlines forcing replacement of legacy open-filling equipment across European and North American sterile manufacturing footprints.
For Market Incumbents: Harden isolator-native design leadership by capturing captive servo-drive supply agreements with Baden-Württemberg component specialists, and accelerate brownfield retrofit compatibility engineering to defend against modular electric platform entrants targeting CMO price sensitivity. Vertical integration into precision steel alloy sourcing mitigates margin compression from commodity volatility. For New Entrants and Emerging Players: Mid-scale biologics Contract Manufacturing Organizations in Hyderabad and Bengaluru represent the most penetrable entry point, where CDSCO streamlined pathways and PLI incentives compress qualification timelines for isolator-integrated lines. Single-use fluid path configurations for clinical-scale laboratory fillers offer a second white-space avenue with reduced validation burden. A service-contract-first go-to-market model, bundling throughput guarantees with spare parts availability, bypasses capital-purchase committee resistance. For Investors and Strategic Acquirers: Precision engineering boutiques with isolator qualification expertise and established FDA validation track records command scarcity premiums in consolidation scenarios. Long-term viability favors vendors with greenfield-native isolator architectures over retrofit-dependent legacy portfolios, as regulatory stringency tightens across major jurisdictions. Watch for CDSCO and NMPA alignment with EU GMP Annex 1 standards as the inflection signal for Asia-Pacific capacity deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Native Platform Development | EU GMP Annex 1 mandates closed barrier systems, privileging purpose-built architectures over retrofits. |
| Servo-Drive Technology Licensing | Magnetic linear motor adoption eliminates particulate generation in high-speed vaccine lines. |
| Single-Use Fluid Path Integration | Disposable polymer contact surfaces enable rapid product changeover for clinical-scale CMO operations. |
| Outcome-Based Service Contracting | Throughput commitments and spare parts guarantees align vendor incentives with continuous biologics production schedules. |
| India Biologics Manufacturing Partnership | CDSCO streamlined biosimilar pathways and PLI incentives accelerate sterile injectable capacity buildouts. |
Methodological Framework
The analysis maps automatic, semi-automatic, and laboratory syringe filler sub-sectors, each validated through equipment procurement directors at Contract Manufacturing Organizations, regulatory affairs leads at pharmaceutical manufacturers, and aftermarket service heads at precision engineering clusters. Primary interviews with isolator qualification engineers and contamination control specialists cross-reference secondary validation from FDA 483 inspection observations, EMA GMP inspection databases, and EU GMP Annex 1 guidance documents. Bottom-up installed base estimates and top-down capital expenditure forecasts triangulate market sizing.
The analytical framework holds regulatory compliance deadlines and biologics capacity expansion rates fixed across the projection horizon, while varying stainless steel input cost assumptions and servo-drive technology adoption curves. Segmentation dimensions modeled include automation intensity, end-user procurement authority, therapeutic application containment requirements, and actuation mechanism technology tier. CAGRs derive from equipment replacement cycle analysis and greenfield capacity announcement tracking, with fill-rate demand curves and isolator integration penetration rates as key forecast inputs.
Practitioners should monitor CDSCO and NMPA regulatory alignment trajectories, plus 316L steel alloy price indices, for early signals requiring forecast revision. Cross-checking against EMA GMP inspection deficiency trends for isolator-based filling lines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Pipette Controllers Market
Medical Devices
Bone Power Tools Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Artificial Implants Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
3D Printed Medical Implants Market