
 Electrochemical Biosensors Market | 2026-2036
Electrochemical Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochemical Biosensors Market Analysis
Clinical-grade accuracy thresholds is unwinding legacy performance benchmarks across the electrochemical biosensors landscape. Abbott Laboratories leverages its vertically integrated glucose monitoring platform to sustain manufacturing scale in North American diabetes care. F. Hoffmann-La Roche Ltd anchors its competitive stance through deep specialization in laboratory-based amperometric systems. Siemens Healthineers competes by extending its diagnostic automation portfolio into integrated electrochemical readout modules.
Electrochemical biosensors are analytical devices that transduce biological recognition events into measurable electrical signals, typically operating at working potentials between -0.2 and +0.8 V against Ag/AgCl reference electrodes with detection limits reaching picomolar concentrations. Their primary commercial purpose centers on rapid, label-free quantification of metabolites, pathogens, and toxicants in complex matrices. Amperometric platforms dominate current revenue pools due to mature manufacturing infrastructure, while nanomaterial-enhanced electrodes represent the fastest-growing architecture by sensitivity improvement. Enzyme-based sensors retain the largest installed base in clinical diagnostics, though molecularly imprinted polymers are displacing biological recognition elements in environmental monitoring applications where thermal stability governs procurement decisions.
FDA premarket notification pathways for continuous glucose monitors and EPA methods for water quality electrochemical detection shape product development timelines and validation costs. ISO 15197 and IEC 61010-1 standards further constrain design choices for devices targeting clinical and analytical laboratory deployments. Stakeholders must monitor convergence between wearable form factors and laboratory-grade precision as this tension determines which technology architectures capture the next wave of point-of-care contracts.
Market Dynamics
FDA tightened accuracy standards for glucose monitoring are forcing sensor recalibration protocols across the electrochemical biosensors landscape. This regulatory compression is restructuring competitive positioning around clinical-grade precision thresholds.
Growth Catalysts
- Point-of-Care Diagnostics Expansion:Hospital settings are accelerating deployment of portable amperometric systems for rapid metabolite quantification. Chronic disease management programs in the United States, Germany, and China are institutionalizing bedside electrochemical testing protocols.
- ISO 15197 Compliance Mandates:Clinical laboratory accreditation requirements are standardizing performance benchmarks for self-monitoring blood glucose devices. Diagnostic automation vendors are integrating electrochemical readout modules to meet these specifications.
- Nanomaterial-Enhanced Electrodes:Carbon nanotube and graphene-modified working electrodes are achieving picomolar detection limits. Environmental monitoring agencies are procuring these architectures for toxicant screening in complex aqueous matrices.
Market Restraints
- Precious Metal Input Volatility:Palladium and gold electrode coatings expose manufacturers to commodity price swings. Working electrode fabrication costs fluctuate with London Metal Exchange pricing cycles.
- Enzyme Stability Limitations:Biological recognition elements degrade above 40°C, constraining deployment in industrial process monitoring. Molecularly imprinted polymers are substituting in thermal-stability-critical applications.
- Reference Electrode Supply Concentration:Ag/AgCl electrode production clusters in East Asian chemical processing hubs. Single-source dependency for chloride-saturated gel electrolytes creates procurement vulnerability.
Strategic Opportunities
- EPA Water Quality Methods:Electrochemical detection protocols for heavy metal and pesticide residues are expanding municipal procurement specifications. Environmental testing laboratories are retrofitting legacy colorimetric systems with amperometric cells.
- Wearable-Laboratory Precision Convergence:Flexible printed circuit integration with microfabricated electrodes is enabling continuous lactate and ketone monitoring. Athlete performance clinics and metabolic research centers are piloting subcutaneous sensor arrays.
- India Chronic Disease Programs:The country's national diabetes screening initiatives are creating procurement scale for low-cost glucose test strips. Domestic manufacturers are localizing enzyme electrode production under PLI scheme incentives.
Industry Challenges
- Multiplexed Assay Integration Complexity:Simultaneous detection of glucose, lactate, and creatinine requires orthogonal working potentials and interference rejection algorithms. Firmware development timelines extend validation cycles.
- IEC 61010-1 Electrical Safety Certification:Potentiostat circuit designs must demonstrate isolation compliance for patient-connected devices. Third-party testing laboratory queues are elongating product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochemical Biosensors Market |
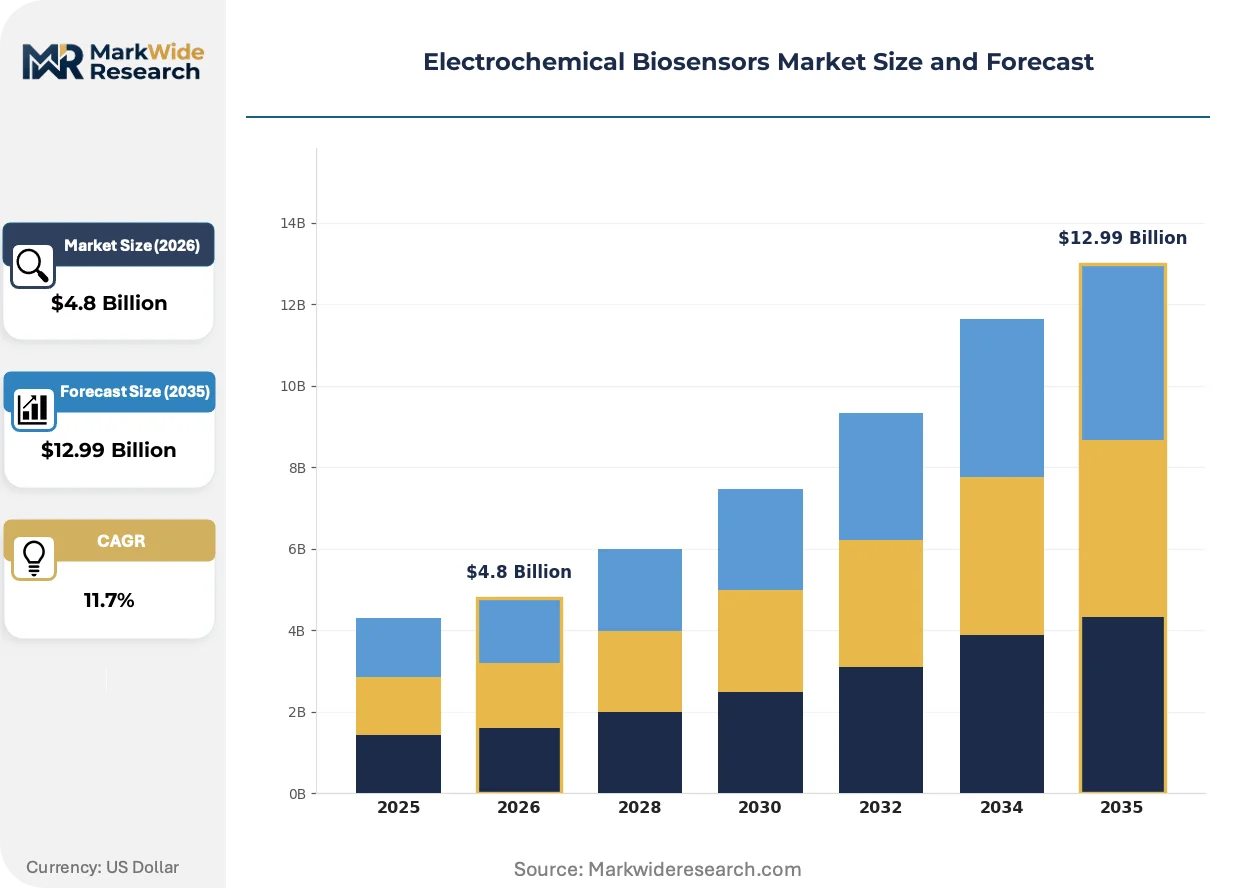
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent, Colorimetric, Amperometric, Potentiometric End User: Healthcare, Environmental Monitoring, Food Industry, Academic Research Technology: Molecularly Imprinted Polymers, Nanomaterials, Enzyme-Based Sensors, Conductive Polymers Application: Clinical Diagnostics, Food Safety Testing, Water Quality Assessment, Bioremediation |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Medtronic, Thermo Fisher Scientific, Bio-Rad Laboratories, Johnson & Johnson, Biosensors International Group, Dexcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochemical Biosensors Market Emerging Trajectories
Electrochemical biosensor architectures are bifurcating between disposable strip formats and reusable implantable platforms. This divergence is reshaping manufacturing scale requirements and regulatory submission pathways.
Printed electrode fabrication using conductive inks is supplanting traditional screen-printed carbon manufacturing. Point-of-care diagnostic distributors in Germany are adopting roll-to-roll gravure printing for glucose test strip production. This transition is compressing unit economics for high-volume consumables while enabling geometric customization for niche metabolite assays.
REACH restrictions on mercury-containing reference electrodes are compelling redesign of Ag/AgCl chloride gel formulations. European analytical instrument manufacturers are qualifying alternative ionic liquid electrolytes for potentiometric stability. Laboratory-grade pH and ion-selective electrode suppliers are reformulating product lines to maintain CE marking compliance.
Health systems are unbundling sensor hardware from reagent supply contracts. Hospital procurement departments in China are negotiating separate pricing for electrochemical readers versus per-test consumables. This purchasing pattern is most visible in tier-one municipal medical centers consolidating diabetes management programs under value-based reimbursement frameworks.
Electrochemical Biosensors Market Segmentation
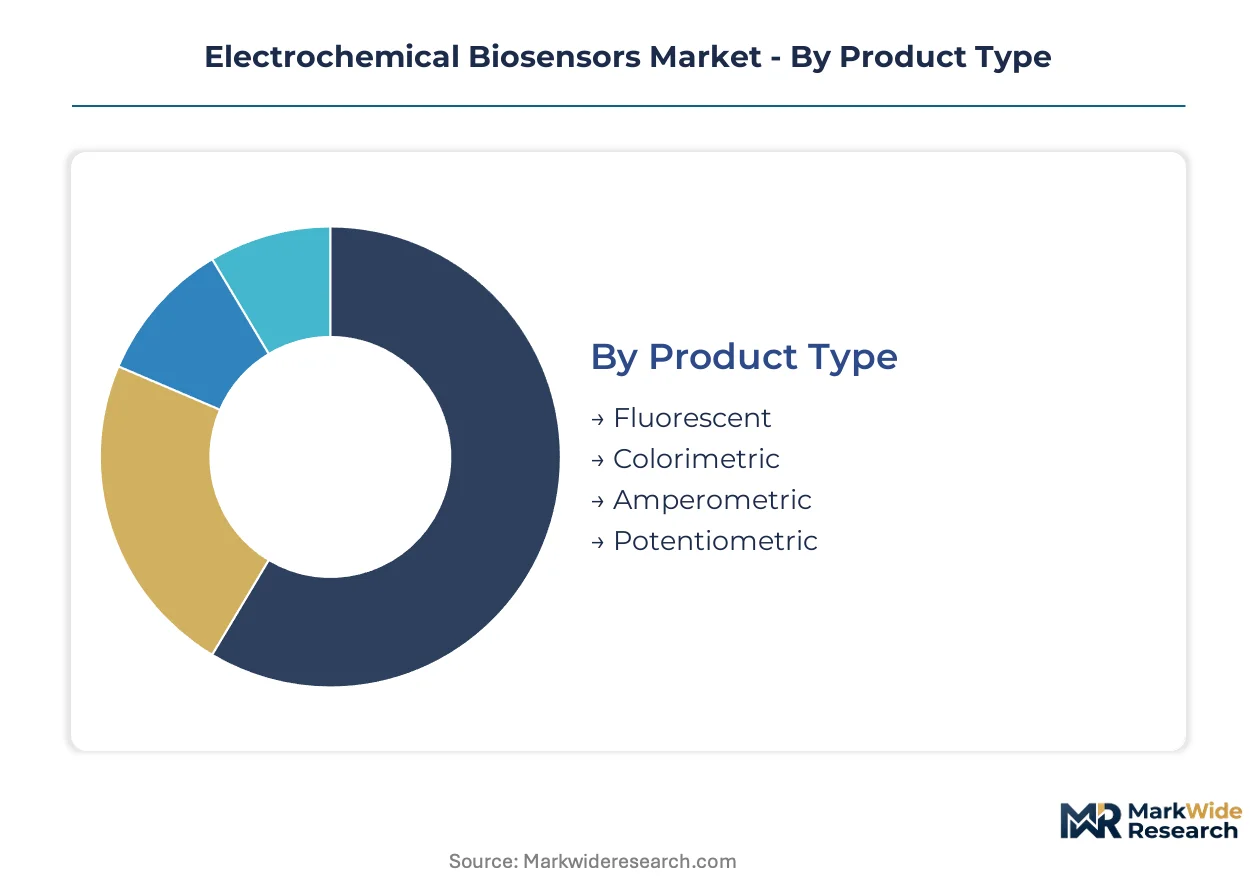
Electrochemical biosensor architectures diverge sharply across detection principles, recognition chemistries, and deployment environments. Each segmentation axis carries distinct margin profiles, regulatory burdens, and manufacturing scale requirements that reshape competitive positioning.
Product Type:
Amperometric platforms command the deepest margin pools due to established glucose monitoring reimbursement codes and consumable recurring revenue models.
- Amperometric:These sensors measure current generated by redox reactions at fixed working potentials, typically -0.2 to +0.8 V against Ag/AgCl references. Hospital point-of-care systems in the United States and Germany concentrate procurement, driven by FDA and ISO 15197 compliance mandates for continuous glucose monitoring accuracy.
- Potentiometric:Ion-selective electrodes transduce membrane potential changes into concentration readings without current flow. Water quality assessment laboratories in China are expanding procurement for heavy metal detection under MEE environmental monitoring protocols.
- Fluorescent:Optical-electrochemical hybrid architectures combine fluorophore signal amplification with electrical readout.
- Colorimetric:Visual indicator systems with electrochemical confirmation layers for resource-limited settings.
The dominant share belongs to Amperometric, while Potentiometric is closing the gap fastest.
End User:
Healthcare institutions generate volume concentration through chronic disease management program scale, though environmental monitoring agencies are accelerating procurement velocity.
- Healthcare:Hospital systems and diabetes management clinics deploy bedside amperometric systems for rapid metabolite quantification. United States integrated delivery networks are consolidating glucose test strip purchasing under value-based reimbursement frameworks.
- Environmental Monitoring:Municipal water authorities and industrial compliance laboratories detect toxicants in complex aqueous matrices. China's MEE and the EPA in the United States are expanding electrochemical detection protocols for heavy metal and pesticide residues.
- Food Industry:Quality control laboratories screen for pathogens and chemical contaminants in processing facilities.
- Academic Research:University laboratories prototype novel recognition chemistries and electrode geometries.
Healthcare retains the largest installed base, though Environmental Monitoring is expanding most quickly.
Technology:
Enzyme-based recognition elements dominate current revenue through glucose oxidase immobilization maturity, while nanomaterial architectures capture premium pricing on sensitivity metrics.
- Enzyme-Based Sensors:Biological recognition elements such as glucose oxidase and lactate oxidase are immobilized on electrode surfaces for substrate-specific detection. Chronic disease management programs in Germany and the United States standardize procurement around these proven architectures.
- Nanomaterials:Carbon nanotube and graphene-modified electrodes achieve picomolar detection limits through enhanced electron transfer kinetics. Environmental monitoring agencies in China are qualifying these architectures for regulatory compliance screening.
- Molecularly Imprinted Polymers:Synthetic antibody mimics replace biological elements where thermal stability governs deployment.
- Conductive Polymers:Polypyrrole and polyaniline matrices enable flexible form factors for wearable applications.
Enzyme-Based Sensors hold the revenue concentration, while Nanomaterials are gaining share fastest.
Application:
Clinical diagnostics anchors manufacturing scale through test strip volume, though water quality assessment is restructuring procurement around regulatory compliance mandates.
- Clinical Diagnostics:Blood glucose, lactate, and creatinine quantification in hospital and home settings. Point-of-care deployment in the United States, Germany, and China is institutionalizing bedside electrochemical testing protocols under chronic disease management programs.
- Water Quality Assessment:Heavy metal, pesticide, and microbial contaminant detection in municipal and industrial water systems. EPA methods in the United States and MEE protocols in China are expanding amperometric cell retrofit specifications.
- Food Safety Testing:Pathogen and toxin screening in processing and distribution chains.
- Bioremediation:In-situ pollutant monitoring during environmental cleanup operations.
Clinical Diagnostics commands the dominant position, while Water Quality Assessment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrode fabrication capacity clusters in East Asian chemical processing hubs and North American precision manufacturing corridors, creating asymmetric supply access across end-use markets. Procurement vulnerability in Ag/AgCl reference electrodes concentrates in single-source jurisdictions, while demand expansion in chronic disease management programs redistributes contract volumes toward hospital systems in Germany, China, and the United States.
United States
Integrated delivery networks in Texas and California are consolidating glucose test strip purchasing under value-based reimbursement frameworks. FDA premarket notification pathways for continuous glucose monitors extend validation timelines for new entrants. Abbott Laboratories anchors manufacturing scale in North American diabetes care through vertically integrated production.
Germany
Hospital point-of-care systems concentrate procurement in Bavaria and North Rhine-Westphalia, driven by ISO 15197 compliance mandates. Roll-to-roll gravure printing for glucose test strip production is compressing unit economics for high-volume consumables. Siemens Healthineers extends diagnostic automation portfolios into integrated electrochemical readout modules.
China
Municipal medical centers in Shanghai and Beijing are unbundling sensor hardware from reagent supply contracts under tier-one consolidation programs. MEE environmental monitoring protocols expand amperometric cell retrofit specifications for water quality assessment. Domestic manufacturers localize enzyme electrode production under PLI scheme incentives.
India
National diabetes screening initiatives in Maharashtra and Karnataka create procurement scale for low-cost glucose test strips. CDSCO clinical trial requirements shape product development timelines for wearable form factors. Academic research laboratories in Delhi-NCR prototype novel recognition chemistries for regional metabolic disease profiles.
Japan
Metabolic research centers in Kanto and Kansai regions pilot subcutaneous sensor arrays for continuous lactate monitoring. PMDA regulatory convergence with FDA accuracy standards accelerates validation protocol harmonization. Precision electronics manufacturers in Nagoya corridor supply microfabricated electrode components to regional diagnostic device assemblers.
Electrochemical Biosensors Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the electrochemical biosensors landscape. Vertically integrated multinationals command glucose monitoring reimbursement codes and consumable recurring revenue models, while specialized component suppliers capture premium pricing on nanomaterial-enhanced architectures. Three archetypes dominate: full-stack diagnostic platforms, precision electrode fabricators, and regulatory-specialized contract manufacturers. Competitive moves concentrate on backward integration into enzyme immobilization chemistry and geographic expansion through hospital procurement consolidation.
Among diversified health technology conglomerates, Abbott Laboratories, F. Hoffmann-La Roche Ltd, and Siemens Healthineers occupy positions that exemplify contrasting strategic postures. Abbott Laboratories represents vertically integrated scale in consumable manufacturing, while F. Hoffmann-La Roche Ltd exemplifies laboratory-based specialization in amperometric systems. Siemens Healthineers sits within the diagnostic automation tier, extending hardware portfolios into electrochemical readout integration. These three anchors illustrate how regulatory compliance depth and manufacturing scope determine contract capture in hospital point-of-care procurement.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Medtronic |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Johnson & Johnson |
| Biosensors International Group |
| Dexcom |
| Others |
Supply Flow & Price Mechanics
Carbon nanotube electrode coatings substituting for palladium-gold formulations are redrawing procurement geography toward East Asian chemical processing hubs while compressing working electrode fabrication premiums. This substitution dynamic simultaneously destabilizes legacy precious metal supply contracts and creates pricing arbitrage between nanomaterial-enhanced and conventional architectures.
Pricing Analysis
ISO 15197 accuracy compliance dictates the pricing tier structure across clinical-grade electrochemical biosensors, separating FDA-cleared continuous glucose monitors from uncertified wellness devices. Three-tier pricing structure across premium, standard, and economy levels anchors on certification grade and volume scale, with hospital procurement committees in the United States and Germany exhibiting lowest price sensitivity due to reimbursement code capture. Cost compression in economy-tier glucose test strips is intensifying because Indian domestic manufacturers are scaling enzyme electrode production under PLI scheme incentives.
Supply Chain Analysis
Strategic stockpiling of Ag/AgCl reference electrodes dominates inventory strategy over just-in-time approaches due to single-source concentration in East Asian chemical processing hubs. Working electrode fabrication draws from palladium and gold coating supplies anchored in South African mining corridors and Chinese refining operations, while chloride-saturated gel electrolytes hinge on Japanese and South Korean specialty chemical producers. Single-source vulnerability for reference electrode components creates structural procurement risk. Distribution runs through diagnostic device OEMs and hospital GPO contracts rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of picomolar-sensitivity electrode fabrication expertise concentrates competitive advantage with nanomaterial chemistry specialists, creating asymmetric returns for stakeholders who secure this capability layer.
For Market Incumbents: Fortify backward integration into enzyme immobilization chemistry to defend consumable recurring revenue against molecularly imprinted polymer substitutes. Capture manufacturing scale in North American and German hospital procurement consolidation waves by embedding electrochemical readout modules within diagnostic automation portfolios.
For New Entrants and Emerging Players: Differentiate on thermal-stability-critical environmental monitoring applications where molecularly imprinted polymers displace enzyme-based architectures. Penetrate China's MEE water quality assessment retrofit specifications and India's national diabetes screening procurement programs through localized production partnerships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision electrode fabricators holding nanomaterial-enhanced architecture patents. Long-term viability centers on convergence between wearable form factors and laboratory-grade precision. Watch FDA premarket notification queue lengths as inflection indicator for competitive entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Immobilization Chemistry Acquisition | Captures consumable recurring revenue in glucose monitoring reimbursement codes. |
| Nanomaterial Electrode Patent Portfolio Expansion | Secures picomolar detection limits for EPA water quality compliance screening. |
| Hospital GPO Contract Consolidation | Locks in tier-one municipal medical center procurement under value-based frameworks. |
| East Asian Reference Electrode Supply Agreement | Mitigates Ag/AgCl single-source vulnerability through multi-hub qualification. |
| Roll-to-Roll Gravure Printing Scale-Up | Compresses unit economics for high-volume glucose test strip manufacturing. |
Methodological Framework
Desk research of FDA 510(k) filings, EPA method validation databases, and ISO standard technical committees preceded structured interviews with biomedical engineers, hospital GPO contracts managers, diagnostic device procurement leads, and nanomaterial electrode fabricators. Secondary validation drew from SEC 10-K disclosures, patent assignment records, and customs trade data for precious metal coating imports. Bottom-up test strip volume modeling and top-down chronic disease management program expenditure estimates were triangulated to constrain forecast variance.
Variance decomposition across detection principle, recognition chemistry, and deployment environment segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from hospital point-of-care system installation trajectories and environmental monitoring agency procurement cycles. Enzyme stability degradation curves and nanomaterial electron transfer kinetics literature informed sensitivity improvement assumptions.
Decision-makers should treat outputs as directional under sustained FDA accuracy standard tightening and REACH mercury electrode phase-out timelines; material deviation would warrant model refresh. Revision becomes warranted when Ag/AgCl reference electrode supply concentration or palladium price volatility crosses thresholds that alter working electrode fabrication cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Pulmonary Function Testing Devices Market