
 Cholesterol Management Devices Market | 2026-2036
Cholesterol Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cholesterol Management Devices Market Intelligence
Specialized manufacturing capacity for high-sensitivity enzymatic assays is hardening supply chains for clinical chemistry analyzers. Siemens Healthineers leverages its scale in diagnostic imaging to bundle lipid analyzers with other hospital systems. Abbott differentiates through its extensive portfolio of point-of-care devices, targeting both clinical and home settings. F. Hoffmann-La Roche Ltd. competes on the precision of its photometric methods for large diagnostic laboratories.
Cholesterol management devices are instruments and consumables designed to quantify levels of total cholesterol, HDL, and LDL in blood samples. They frequently use enzymatic assays that generate a measurable electrochemical signal. The primary purpose is screening for dyslipidemia to assess cardiovascular risk. Point-of-care devices represent the fastest-growing product segment, while diagnostic laboratories remain the largest end-user base by volume.
Market access requires clearance from regulatory bodies such as the US FDA and China's NMPA, which scrutinize device accuracy and clinical validation data. In Europe, compliance with the Medical Device Regulation (MDR) and CE marking is mandatory for all cholesterol testing devices. Navigating the divergent data requirements for clinical utility across these jurisdictions is a critical strategic consideration for manufacturers.
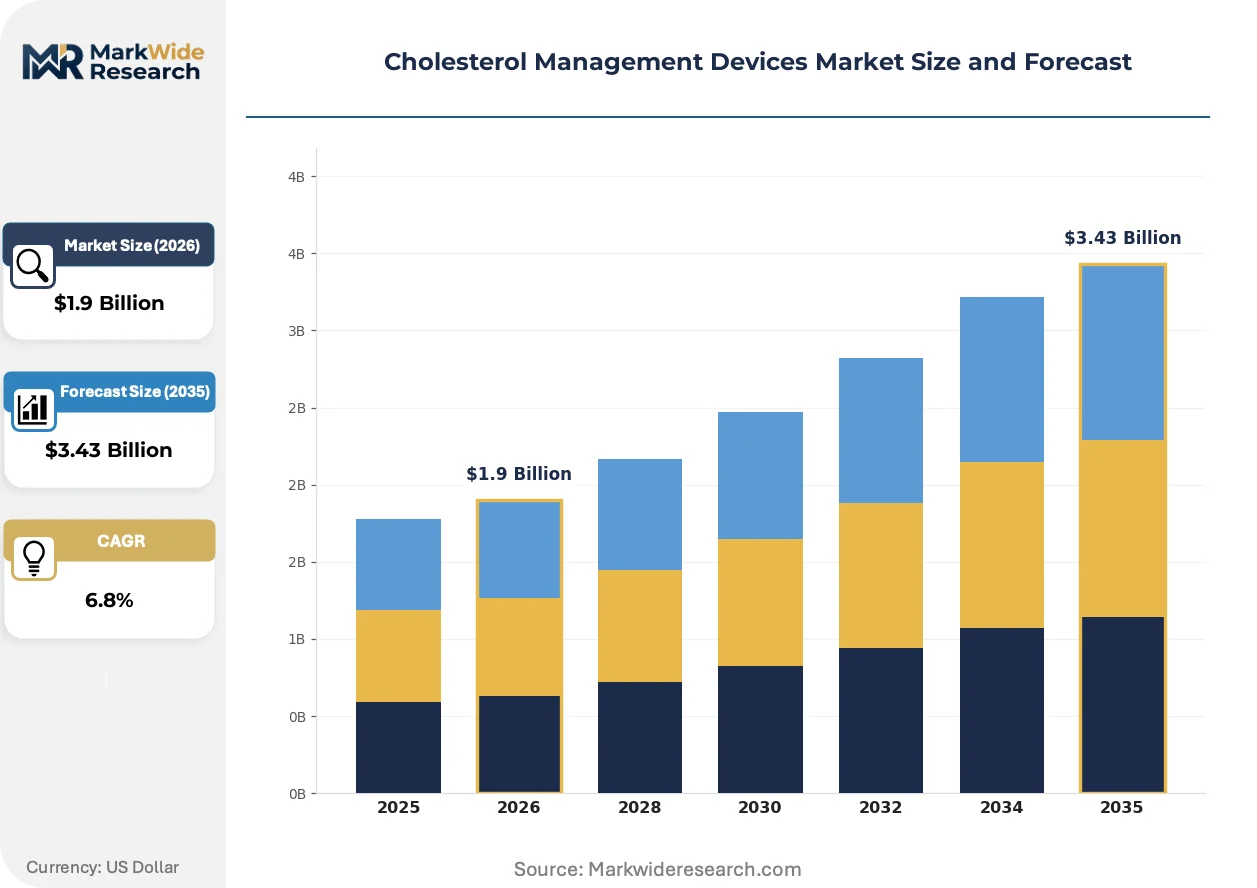
Market Dynamics
The decentralization of cardiovascular risk assessment is the central force shaping the cholesterol management devices market. This shift is driven by the convergence of miniaturized sensor technology, which enables point-of-care testing, and public health initiatives in major economies focused on preventive screening.
Growth Catalysts
- Government Health Initiatives:China's national health policies aimed at reducing cardiovascular disease prevalence are creating substantial demand for screening devices in primary care settings and public health programs.
- Sensor Miniaturization:Advances in electrochemical sensor design and manufacturing allow for smaller, more affordable point-of-care devices, expanding access beyond traditional diagnostic laboratories into clinics and wellness centers.
- Preventive Healthcare Expansion:A growing emphasis on preventive medicine and employee wellness programs in corporate settings is creating a new end-user base for cholesterol screening tools outside of acute care.
Market Restraints
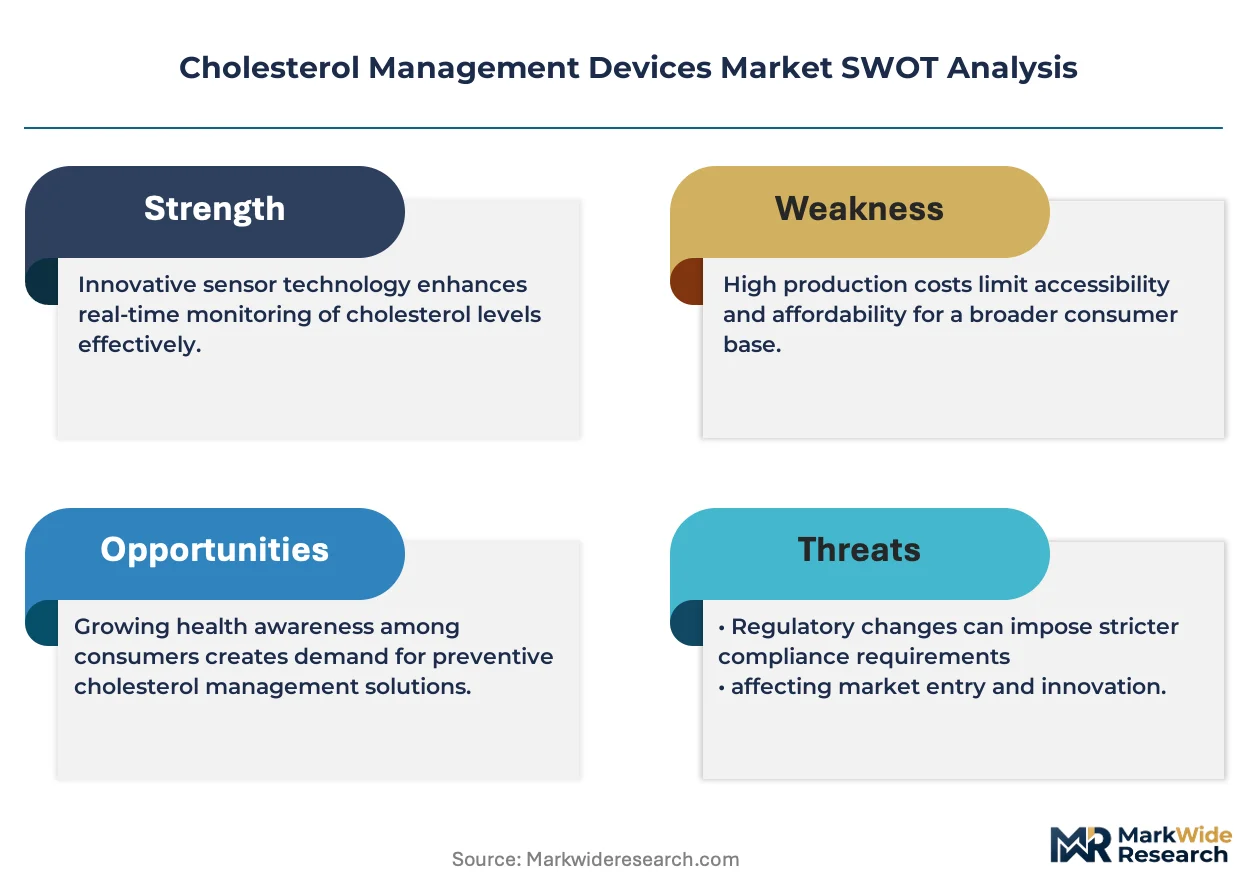
- Enzymatic Assay Supply Bottlenecks:The production of high-sensitivity enzymatic assays, a critical consumable, is concentrated among a few specialized manufacturers, creating potential supply chain vulnerabilities and price pressures.
- Divergent Regulatory Pathways:Navigating disparate clinical data and validation requirements between the US FDA, China's NMPA, and Europe's MDR framework complicates and lengthens product development timelines.
- High-Precision Technology Barriers:The advanced photometric methods required for high-throughput analyzers in large diagnostic laboratories demand significant R&D investment, posing a high barrier to entry for new competitors.
Strategic Opportunities
- Digital Health Integration:Connecting point-of-care cholesterol devices to digital health platforms and mobile applications offers an opportunity to provide integrated chronic disease management and telehealth services.
- Emerging Market Penetration:Beyond China, countries like India and Brazil with large populations and rising cardiovascular disease rates represent significant untapped markets for affordable point-of-care screening devices.
- Continuous Monitoring Development:Developing minimally invasive or non-invasive sensors for semi-continuous cholesterol monitoring could create a new market segment for managing high-risk patient populations more proactively.
Industry Challenges
- System Interoperability:Ensuring new point-of-care devices can seamlessly integrate with diverse hospital electronic health record (EHR) and laboratory information systems (LIS) remains a significant technical and operational challenge.
- Clinical Data Generation:Manufacturers face the ongoing operational burden of conducting clinical studies to generate the validation data required by regulators like the FDA to support accuracy claims and maintain market clearance.
- Cross-Disciplinary Talent Gaps:A scarcity of talent proficient in both the biochemistry of enzymatic assays and the microfabrication of electrochemical sensors can hinder innovation and product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholesterol Management Devices Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lipid Analyzers, Point-of-Care Devices, Home Test Kits, Clinical Chemistry Analyzers Technology: Enzymatic Assays, Electrochemical Sensors, Photometric Methods, Fluorometric Techniques Application: Cardiovascular Risk Screening, Diabetes Management, Preventive Healthcare, Nutritional Monitoring End User: Diagnostic Laboratories, Research Institutes, Wellness Centers, Cardiologists |
| Companies Covered | Abbott, Medtronic, Boston Scientific Corporation, F. Hoffmann-La Roche Ltd., Koninklijke Philips N.V., Quest Diagnostics Incorporated, Thermo Fisher Scientific, Randox Laboratories Ltd., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholesterol Management Devices Market Strategic Shifts & Innovations
The market's evolution is defined by a move from centralized, reactive testing toward decentralized, proactive screening. This transition is powered by advancements in sensor technology and a greater consumer focus on personal health management, altering traditional diagnostic workflows and business models.
Miniaturized electrochemical sensors that utilize enzymatic assays are the core technology enabling portable devices. Adoption by non-laboratory settings, including pharmacies, corporate wellness programs, and home-use environments, is accelerating rapidly. This accessibility is rewriting the traditional diagnostic pathway, moving initial screening away from large centralized laboratories and closer to the patient.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence, quality management, and post-market surveillance on all device manufacturers. This legislation increases the cost and time required to achieve CE marking, particularly for software-driven and connected devices. Point-of-care device makers face heightened scrutiny on accuracy and data traceability to comply with the new framework.
A distinct shift toward consumer-driven health monitoring is changing purchasing behaviors for screening devices. Direct-to-consumer channels, including online platforms and retail pharmacies, are gaining traction, creating a sales pathway that bypasses traditional clinical procurement. This trend is most visible in North America, where consumer engagement in personal health and wellness is particularly strong.
Cholesterol Management Devices Market Segmentation
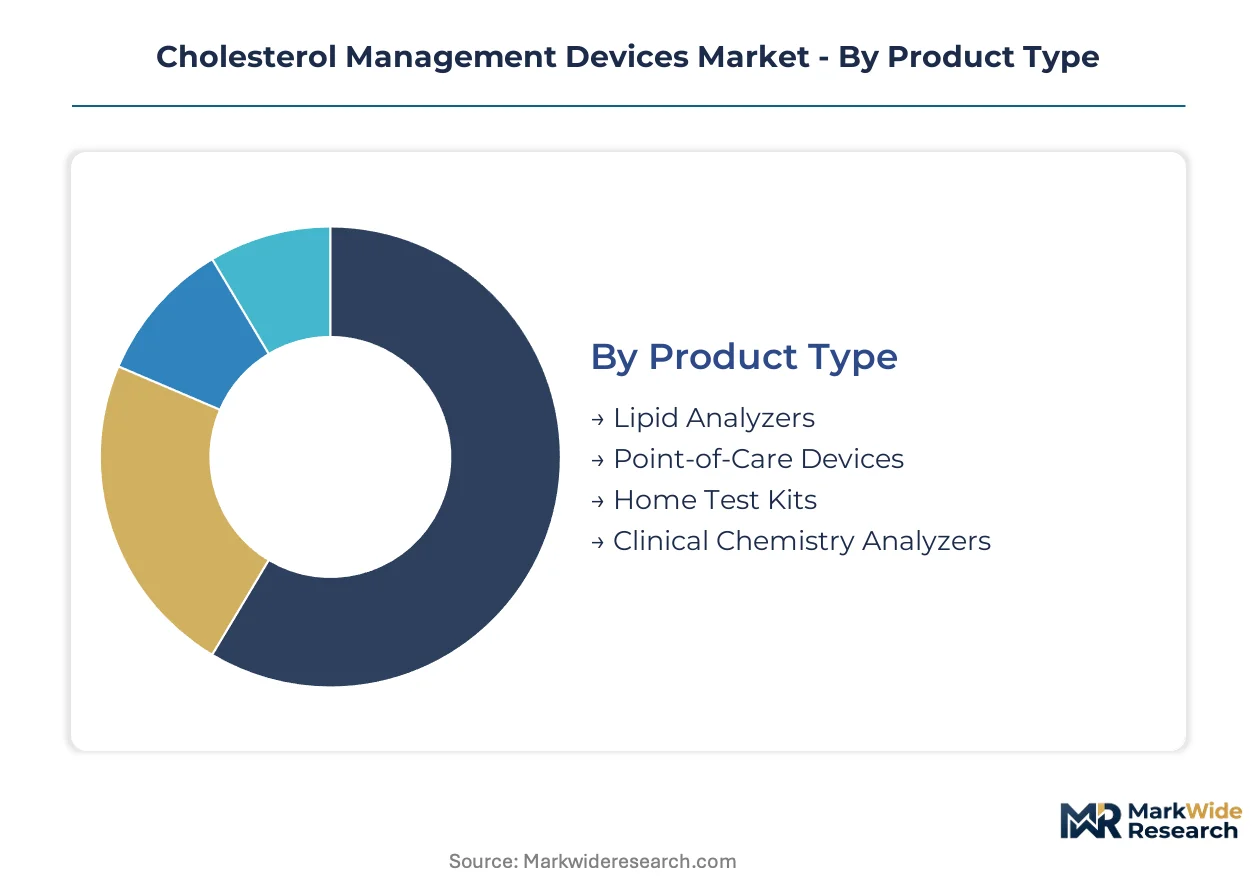
The Cholesterol Management Devices Market is categorized across several dimensions, reflecting the diverse technologies, applications, and end-user requirements. Understanding these segments helps manufacturers tailor product development and market access strategies. This segmentation highlights the varied landscape of diagnostic tools and their deployment across healthcare settings.
Product Type:
The supply of cholesterol management devices is concentrating around specific product types, driven by technological advancements and evolving healthcare delivery models.
- Point-of-Care Devices:These portable instruments deliver rapid lipid panel results outside traditional laboratories, often utilizing electrochemical sensors for immediate feedback. Demand is concentrating in China's primary care settings, supported by national health policies for preventive screening.
- Clinical Chemistry Analyzers:These high-throughput systems process large volumes of samples in central diagnostic laboratories, relying on precise photometric methods. Procurement is shifting towards integrated systems in major hospital networks in Europe, driven by efficiency demands.
- Lipid Analyzers:Specialized benchtop instruments quantify specific lipid fractions, often used in research and specialized clinical settings.
- Home Test Kits:These consumer-friendly kits enable self-monitoring of cholesterol levels, primarily adopted in North America for personal wellness management.
Clinical Chemistry Analyzers absorb the bulk of installed capacity; Point-of-Care Devices are expanding most quickly.
Technology:
Different technologies underpin cholesterol management devices, each suited for specific applications and levels of analytical precision.
- Enzymatic Assays:These biochemical reactions form the basis for most cholesterol quantification, generating a measurable signal proportional to lipid concentration. Their application is expanding in point-of-care testing due to miniaturization, driven by the need for accessible diagnostics.
- Electrochemical Sensors:These sensors detect changes in electrical properties resulting from enzymatic reactions, offering high sensitivity and rapid results. Their application is critical for developing portable and handheld devices, supporting decentralized cardiovascular risk assessment.
- Photometric Methods:These techniques measure light absorption or transmission, primarily used in high-throughput clinical chemistry analyzers for precise quantification.
- Fluorometric Techniques:These methods utilize fluorescence detection for high-sensitivity analysis, often employed in research and specialized diagnostic applications.
The market for Enzymatic Assays remains dominant due to widespread adoption, while Electrochemical Sensors exhibit strong growth potential.
Application:
The diverse applications of cholesterol management devices cater to varying customer needs across the healthcare spectrum.
- Cardiovascular Risk Screening:This primary application identifies individuals at risk of heart disease by measuring lipid profiles, facilitating early intervention strategies. Demand from public health programs in China is significant, driven by national initiatives to reduce CVD prevalence.
- Preventive Healthcare:This application integrates cholesterol testing into wellness programs and routine check-ups, promoting proactive health management. Corporate wellness initiatives in North America are increasingly adopting these tools, aiming to improve employee health outcomes.
- Diabetes Management:Cholesterol monitoring is crucial for diabetic patients, as dyslipidemia is a common comorbidity requiring regular assessment.
- Nutritional Monitoring:These devices support dietary interventions and track the impact of lifestyle changes on lipid levels, particularly in wellness centers.
Cardiovascular Risk Screening represents the largest application segment, with Preventive Healthcare showing considerable expansion.
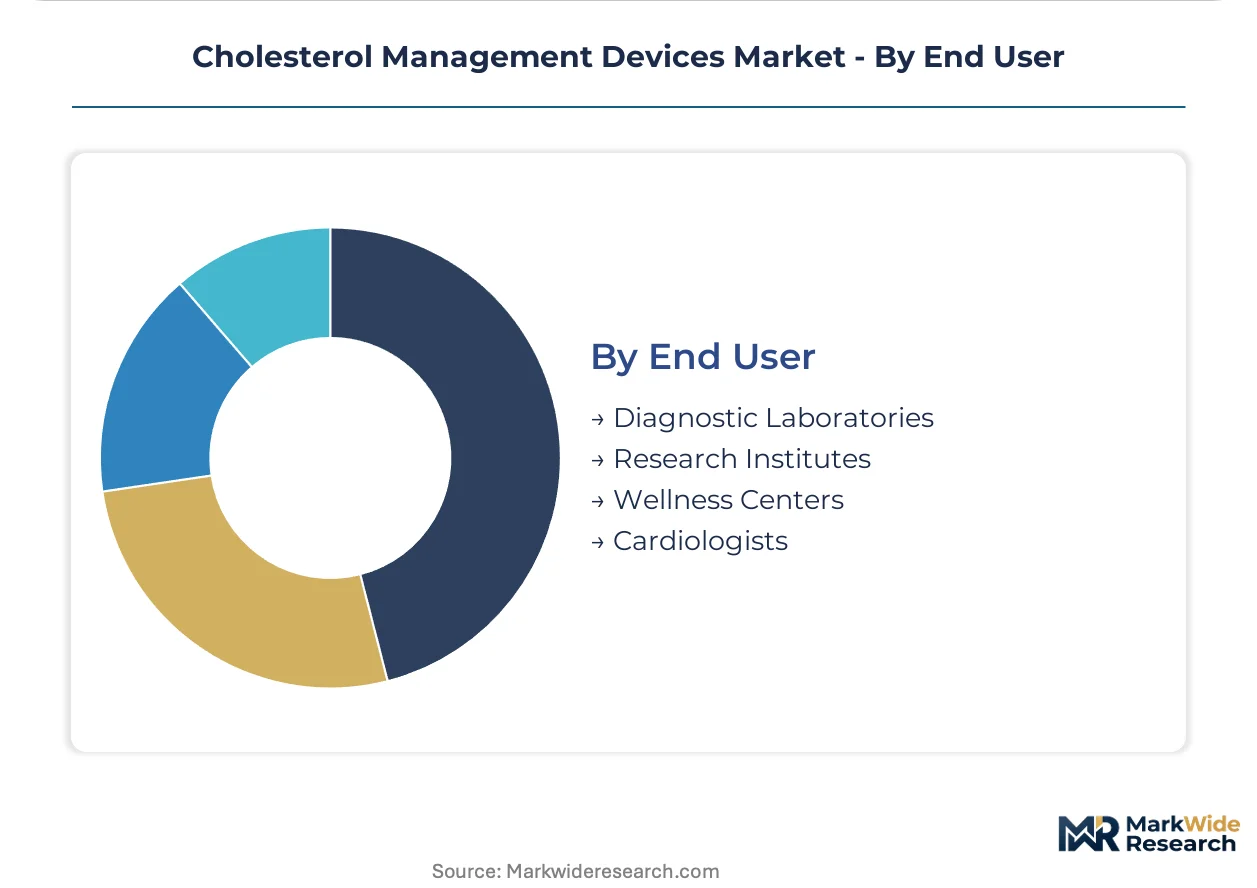
End User:
The maturity of end-user segments influences the adoption patterns and technological requirements for cholesterol management devices.
- Diagnostic Laboratories:These centralized facilities conduct high-volume, precise lipid analyses using advanced clinical chemistry analyzers, serving as the backbone of diagnostic services. Their operational maturity drives demand for robust, automated systems capable of integrating with LIS.
- Wellness Centers:These facilities focus on health promotion and disease prevention, utilizing point-of-care devices for accessible screening. Their growing maturity in preventive care models in Europe is increasing the uptake of user-friendly cholesterol testing solutions.
- Research Institutes:These entities use cholesterol management devices for clinical studies and drug discovery, requiring high-precision and specialized analytical capabilities.
- Cardiologists:Specialist physicians utilize these devices for targeted patient management and treatment efficacy monitoring, often preferring rapid, in-office testing.
Diagnostic Laboratories constitute the foundational end-user base, while Wellness Centers are experiencing rapid integration of new devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's strategic focus on reducing cardiovascular disease prevalence anchors significant demand for cholesterol management devices. This national health priority, coupled with technological advancements in sensor miniaturization, drives the decentralization of diagnostic capabilities across diverse healthcare settings. Other major economies also contribute to market growth through preventive care initiatives and regulatory frameworks.
United States
The United States market is driven by consumer engagement in personal health management and corporate wellness programs. Point-of-care devices find increasing adoption in pharmacies and employer-sponsored health initiatives. The US FDA mandates rigorous clinical validation data for device clearance, ensuring accuracy and reliability. Major diagnostic and medical device clusters in California and Massachusetts foster innovation in connected health solutions.
China
China's robust government health initiatives specifically target cardiovascular disease prevention and screening, creating substantial demand. National health policies promote the widespread deployment of screening devices in primary care settings. The NMPA's stringent approval process ensures device quality and safety for the vast patient population. Beijing and Shanghai serve as key hubs for medical device manufacturing and diagnostic laboratory operations.
Germany
Germany's market for cholesterol management devices is influenced by the European Medical Device Regulation (MDR) and its emphasis on clinical evidence. Efficiency demands in major hospital networks drive procurement of integrated clinical chemistry analyzers. Wellness centers across urban areas are increasingly adopting user-friendly cholesterol testing solutions. The Bavaria region hosts significant medical technology companies and research institutions.
India
India represents a significant untapped market due to its large population and rising incidence of cardiovascular diseases. Affordable point-of-care screening devices are gaining traction in tier-2 and tier-3 cities for early detection. The CDSCO regulates medical device imports and manufacturing, focusing on accessibility and safety standards. Cities like Bengaluru and Hyderabad are emerging as centers for medical diagnostics and health tech development.
Brazil
Brazil's market expansion is linked to its growing middle class and increasing focus on preventive healthcare. Public health programs aim to address the rising cardiovascular disease burden through accessible screening. ANVISA, the national health surveillance agency, oversees device registration and post-market surveillance. São Paulo and Rio de Janeiro metropolitan areas concentrate diagnostic laboratories and medical device distribution networks.
Cholesterol Management Devices Market Key Industry Players
Global majors compete with regional champions across the spectrum of diagnostic precision and accessibility in the cholesterol management devices market. The market structure exhibits stratification, with established players dominating high-throughput laboratory solutions and nimble innovators focusing on point-of-care. Strategic archetypes include integrated diagnostic solution providers and specialized point-of-care device manufacturers. Dominant competitive moves involve portfolio diversification and geographic expansion into emerging markets.
Companies like F. Hoffmann-La Roche Ltd. represent the high-precision segment, providing advanced photometric methods for large diagnostic laboratories. Abbott exemplifies a diversified approach, offering an extensive portfolio of point-of-care devices for clinical and home settings. Siemens Healthineers, a Germany-based entity, occupies a strong position by leveraging its scale in diagnostic imaging to bundle lipid analyzers with other hospital systems.
| Leading Market Players |
|---|
| Abbott |
| Medtronic |
| Boston Scientific Corporation |
| F. Hoffmann-La Roche Ltd. |
| Koninklijke Philips N.V. |
| Quest Diagnostics Incorporated |
| Thermo Fisher Scientific |
| Randox Laboratories Ltd. |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
High-precision photometric methods command premium pricing due to specialized R&D and manufacturing, while portable point-of-care devices prioritize accessibility through cost-effective designs. This divergence shapes supply chains, concentrating high-end component sourcing for labs and broader distribution for PoC.
Pricing Analysis
Warranty and service bundles significantly influence the total cost of ownership for clinical chemistry analyzers, often integrated into long-term contracts. The dominant pricing structure is a hybrid, combining per-unit transactional pricing for enzymatic assay consumables with contract-based agreements for high-throughput systems. Price differentiation stems from accuracy claims validated by regulatory bodies like the US FDA and robust after-sales support. Pricing softness runs through point-of-care devices, driven by public health programs in China demanding affordability, making wellness centers and emerging market primary care highly price-sensitive compared to large diagnostic laboratories.
Supply Chain Analysis
Direct sales channels handle procurement for large diagnostic laboratories and hospital networks, while a broader network of distributors and online platforms serves point-of-care and home test kit segments. Geographic supply concentration for device manufacturing centers on China, with specialized component production in Germany and the United States. The supply chain draws from critical inputs like high-sensitivity enzymatic assays and miniaturized electrochemical sensors. Single-source vulnerability for specialized enzymatic assays presents a structural supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cholesterol management devices market operates as a supply-constrained story, particularly for specialized inputs. Limited manufacturing capacity for high-sensitivity enzymatic assays creates a bottleneck, propping up pricing for critical consumables across all device types.
For Market Incumbents:Cement existing relationships with large diagnostic laboratories by offering integrated system solutions and robust after-sales support. Invest in captive production capacity for high-sensitivity enzymatic assays to mitigate single-source vulnerability and control input costs. This vertical integration defends against margin pressure from specialized component suppliers and emerging point-of-care device entrants. Prioritize R&D in next-generation sensor miniaturization to maintain a competitive edge against new technologies.
For New Entrants and Emerging Players:Miniaturized sensor technology offers a technology-first wedge into underserved primary care settings and wellness centers. Target affordable point-of-care devices for cardiovascular risk screening in India and Brazil, where public health initiatives are expanding access. Develop digital health integration features for remote monitoring and patient engagement, enabling a direct-to-consumer go-to-market angle. Partnerships with corporate wellness programs can accelerate market penetration.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized point-of-care device manufacturers given the accelerating decentralization of diagnostics and preventive healthcare. Long-term viability is strong for companies enabling proactive health management outside traditional clinical settings. Target firms with robust intellectual property in electrochemical sensor technology and established market access in high-growth regions like China. The signal to watch is successful regulatory clearances for minimally invasive or continuous cholesterol monitoring devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Enzymatic Assay Production | Secures critical supply for clinical chemistry analyzers and point-of-care devices, mitigating single-source vulnerability. |
| Digital Health Platform Integration | Connects point-of-care cholesterol devices with telehealth services, enhancing chronic disease management for patients. |
| NMPA Regulatory Pathway Acceleration | Expands market access for screening devices in China, aligning with national cardiovascular disease prevention goals. |
| Minimally Invasive Sensor R&D | Creates a new market segment for continuous monitoring, addressing the needs of high-risk patient populations. |
| Partnerships with Wellness Programs | Drives adoption of cholesterol screening tools in corporate settings, expanding the end-user base beyond traditional clinics. |
Research Approach
Independent corroboration across diagnostic lab directors, R&D leads for sensor technology, and regulatory affairs specialists underwrites the qualitative findings. This study combined primary interviews with industry stakeholders and extensive secondary validation. Secondary data sources included US FDA filings, NMPA approvals, EU MDR guidance documents, and medical device company 10-K filings. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Rate-of-change decomposition formed the basis of the analytical framework across the modeling period. The study modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market dynamics. Key industry-specific forecast inputs included the prevalence of dyslipidemia and government health spending on cardiovascular disease prevention initiatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regulatory changes or enzymatic assay supply shocks. Forecasts reflect assumptions regarding technological adoption rates and public health policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Medical Technology Market
Medical Devices
Global Holter ECG Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Infertility Devices Market
Medical Devices
Surgical Monitors Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Respiratory Devices Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Europe Aligner Sheet Market