
 ETCO2 Masks Market | 2026-2036
ETCO2 Masks Market Size, Share, and Industry Trends Forecast 2026-2036
ETCO2 Masks Market Foresight
Silicone is realigning material economics across ETCO2 mask portfolios as manufacturers shift from PVC to improve biocompatibility and patient comfort profiles. Masimo leverages its pulse oximetry-to-capnography integration to sustain technology leadership in multi-parameter monitoring suites. Drager anchors European supply through its anesthesia workstation ecosystem, while Philips Healthcare competes via its global hospital service contracts that bundle consumables with capital equipment.
An ETCO2 mask is a patient interface device that channels expired respiratory gases to a capnometer for continuous measurement of end-tidal carbon dioxide concentration, typically incorporating a gas sampling port with standard 15/22 mm connectors and either nasal prongs or oronasal cushion designs to maintain seal integrity during spontaneous or assisted ventilation. Disposable masks dominate unit volume in emergency medicine due to infection control protocols, whereas reusable silicone variants command margin pools in operating rooms where sterilization infrastructure exists. Pediatric masks represent the fastest-growing application subset as neonatal and pediatric anesthesia guidelines tighten monitoring requirements across tertiary care networks.
FDA 510(k) clearance pathways and EU MDR Class IIa designation shape product development timelines and clinical evidence requirements for capnography accessories entering commercial distribution. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards further constrain material selection and manufacturing process validation for suppliers targeting regulated markets. Stakeholders must monitor evolving capnography mandate expansions beyond operating rooms into procedural sedation and post-acute care settings to anticipate demand inflection points.
Market Dynamics
Capnography mandate expansion across procedural sedation and emergency medicine is restructuring demand composition for ETCO2 masks, as regulators embed continuous CO2 monitoring into standard-of-care protocols that previously relied on pulse oximetry alone.
Growth Catalysts
- EU MDR Class IIa designation:The European Medical Device Regulation's risk-based classification elevates clinical evidence requirements for capnography accessories, accelerating hospital procurement of validated, CE-marked mask systems over unverified alternatives.
- Neonatal anesthesia guidelines:Pediatric tertiary care networks in the United States, Germany, and China are tightening monitoring standards for infants, generating specialized mask demand that commands premium positioning.
- Silicone material transition:Manufacturers are abandoning PVC formulations to satisfy ISO 10993 biocompatibility testing and reduce patient contact dermatitis incidents during prolonged ventilation.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production clusters in Germany and Japan, exposing mask manufacturers to input cost volatility when petrochemical feedstock prices fluctuate.
- FDA 510(k) clearance timelines:The agency's substantial equivalence reviews for modified sampling port designs create 12-18 month commercialization delays that freeze product line refreshes.
- Reusable mask sterilization infrastructure:Healthcare facilities lacking centralized sterile processing departments face capital barriers to adopting margin-rich silicone variants, trapping them in disposable purchasing cycles.
Strategic Opportunities
- Post-acute care capnography:Skilled nursing facilities and long-term acute care hospitals in the United States remain underpenetrated for continuous respiratory monitoring, offering volume expansion beyond traditional hospital settings.
- Multi-parameter integration:Convergence of capnography sampling with pulse oximetry and respiratory rate sensing is electrifying demand for unified patient interfaces that reduce cable clutter at the bedside.
- Indian critical care infrastructure:Government hospital modernization programs under the country's national health mission are financing anesthesia workstation procurement that bundles ETCO2 masks as essential consumables.
Industry Challenges
- Biocompatibility validation expertise:ISO 10993 cytotoxicity and sensitization testing requires specialized toxicology partnerships that mid-tier manufacturers struggle to resource internally.
- Legacy anesthesia workstation compatibility:Proprietary 15/22 mm connector geometries from established equipment vendors force mask suppliers to maintain fragmented SKU portfolios.
- Sterilization revalidation cycles:Reusable silicone masks demand documented autoclave protocol adherence that burdens clinical engineering departments with compliance tracking overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ETCO2 Masks Market |
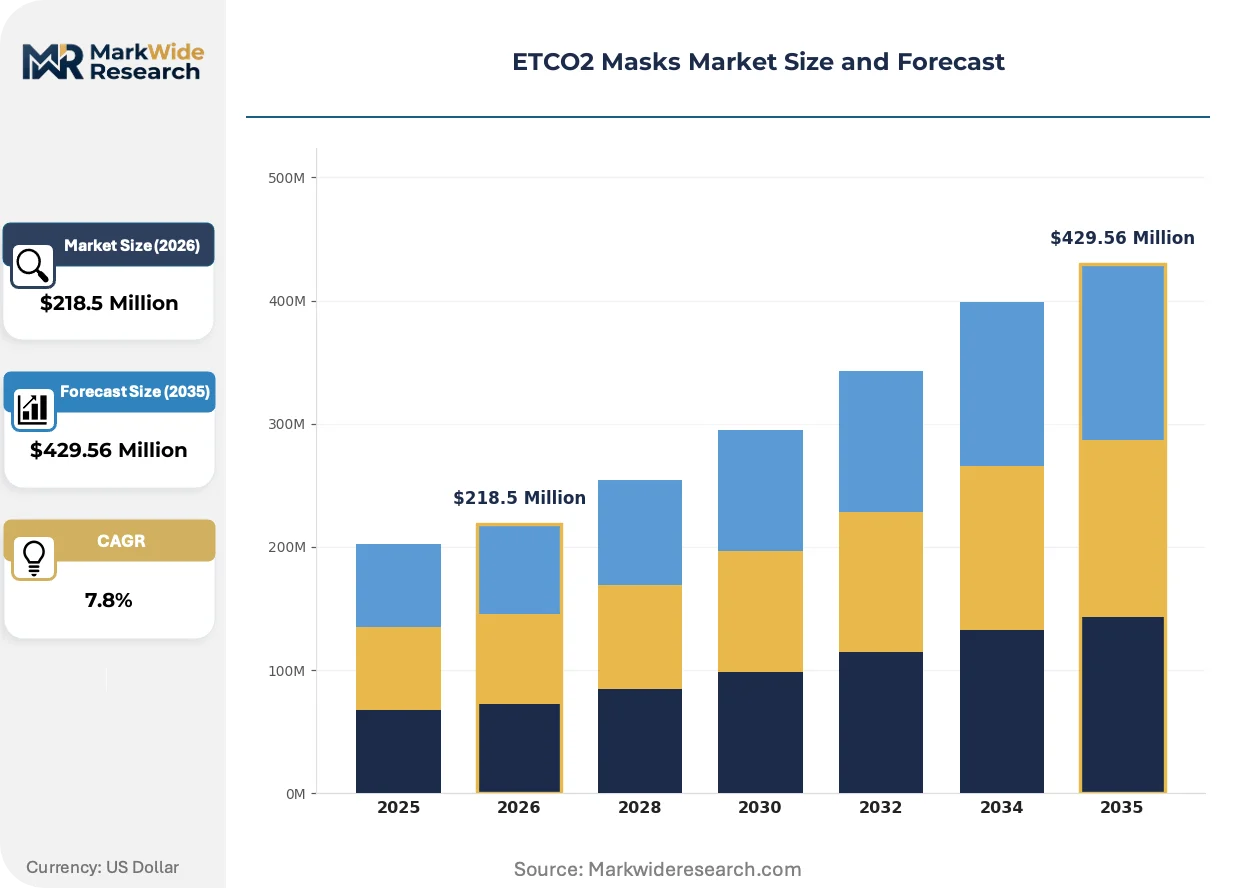
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $429.56 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Masks, Disposable Masks, Pediatric Masks, Adult Masks Application: Anesthesia Monitoring, Critical Care, Emergency Medicine, Outpatient Procedures End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Research Institutions Material: Silicone, PVC, Polypropylene, Latex |
| Companies Covered | Philips Healthcare, Mindray, Masimo, Drager, Medtronic, Smiths Medical, Nihon Kohden, ZOLL Medical, Nonin Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ETCO2 Masks Market Shifts & Advancements
Material science advances and regulatory harmonization efforts are compressing product development cycles while elevating performance benchmarks for patient interface devices across acute and ambulatory care environments.
Microstream capnography technology is electrifying adoption in conscious sedation procedures outside traditional operating rooms. The sidestream sampling method draws minute gas volumes through nasal prong interfaces, enabling reliable ETCO2 measurement during endoscopy and interventional radiology where patients breathe spontaneously. Outpatient surgical centers in the United States are standardizing these low-flow systems to satisfy The Joint Commission sedation monitoring requirements without intubation infrastructure.
EU MDR technical documentation mandates are reshaping supplier competitive dynamics across European distribution channels. The regulation's emphasis on post-market surveillance and clinical performance data forces mask manufacturers to maintain electronic patient registries that track device-specific adverse events. German university hospitals are leveraging these transparency requirements to consolidate purchasing around suppliers with demonstrated biocompatibility traceability.
Hospital procurement departments are consolidating consumable contracts through group purchasing organizations that bundle ETCO2 masks with anesthesia machines and patient monitors. This channel concentration disadvantages standalone mask suppliers lacking capital equipment portfolios. The purchasing pattern is most pronounced in United States integrated delivery networks seeking to standardize connector geometries and reduce bedside inventory complexity across multi-facility systems.
ETCO2 Masks Market Segmentation
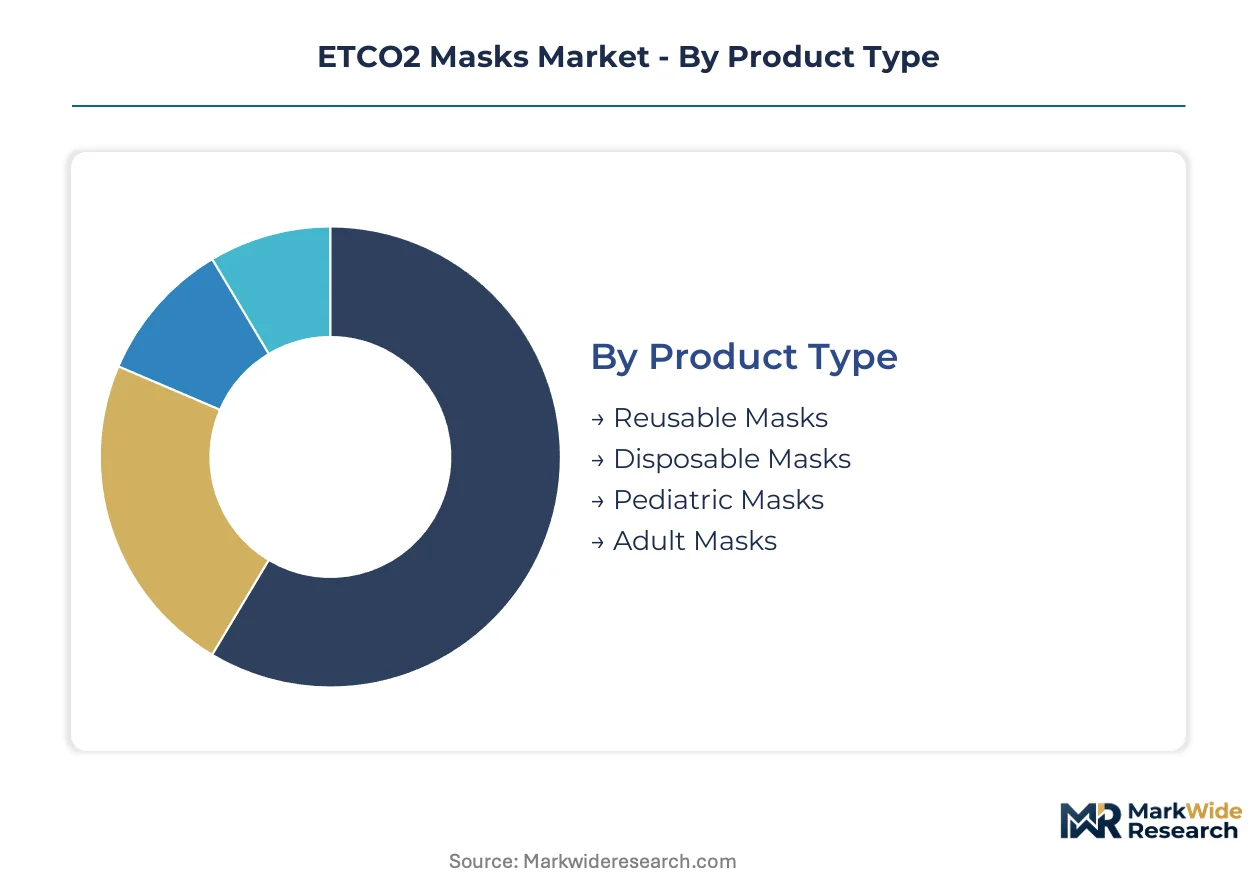
ETCO2 mask purchasing patterns diverge sharply between capital-intensive reusable systems and high-turnover disposable lines, with material selection and patient age cohorts further stratifying supplier portfolios across acute and ambulatory channels.
Product Type:
Standalone capnography masks function independently across ventilation modes, whereas embedded variants integrate into anesthesia workstation ecosystems that lock in consumable sourcing through proprietary connector geometries.
- Reusable Masks:Medical-grade silicone construction withstands 100+ autoclave cycles while maintaining sampling port seal integrity. Operating rooms in German university hospitals concentrate procurement here, driven by waste reduction mandates and centralized sterile processing infrastructure.
- Disposable Masks:Single-use PVC or polypropylene designs eliminate cross-contamination risk in high-turnover emergency departments. United States trauma centers dominate volume, constrained by infection control protocols that prohibit reprocessing between patients.
- Pediatric Masks:Specialized cushion geometries accommodate neonatal facial structures with dead space volumes under 5 mL.
- Adult Masks:Standard 15/22 mm connectors interface with mainstream capnography monitors across hospital wards.
Volume placements concentrate in Disposable Masks; the faster expansion belongs to Pediatric Masks.
Application:
Cost tiers separate mission-critical intraoperative monitoring from lower-acuity procedural sedation where capnography serves as a supplemental safety layer rather than primary respiratory surveillance.
- Anesthesia Monitoring:Continuous ETCO2 tracking during intubated ventilation demands sampling line compatibility with circle breathing systems. United States operating rooms anchor demand here, compelled by ASA standards mandating quantitative capnography for every general anesthetic.
- Critical Care:Non-invasive ventilation interfaces require masks that maintain seal integrity during BiPAP support while enabling sidestream gas sampling. ICU departments in Chinese tertiary hospitals are expanding procurement, supported by national critical care infrastructure investment programs.
- Emergency Medicine:Rapid-sequence intubation protocols prioritize disposable designs that deploy without fit testing.
- Outpatient Procedures:Conscious sedation for endoscopy and colonoscopy drives low-flow Microstream-compatible nasal prong demand.
Revenue concentrates in Anesthesia Monitoring; Critical Care is climbing the fastest as step-down units adopt continuous respiratory surveillance.
End User:
Customer type determines contracting mechanisms, with integrated delivery networks leveraging capital equipment bundles while standalone facilities negotiate consumable terms independently.
- Hospitals:Multi-department standardization programs favor suppliers offering both pediatric and adult SKUs with unified connector platforms. German hospital procurement consortia are consolidating around vendors with EU MDR Class IIa documentation completeness.
- Ambulatory Surgical Centers:Medicare reimbursement constraints drive preference for disposable masks that eliminate sterilization overhead. United States outpatient facilities concentrate here, responding to The Joint Commission sedation monitoring mandates without infrastructure investment.
- Home Care Settings:Portable capnography for sleep-disordered breathing and palliative ventilation remains nascent.
- Research Institutions:Specialized masks for metabolic cart calibration and respiratory physiology studies command small-batch premium pricing.
Procurement volume concentrates in Hospitals; Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
Material:
Supply concentration in medical-grade silicone production clusters exposes mask manufacturers to petrochemical feedstock volatility while biocompatibility testing requirements constrain formulation switching.
- Silicone:Platinum-cured elastomer formulations achieve ISO 10993 cytotoxicity Grade 0 ratings with shore hardness optimized for facial contour adaptation. Japanese specialty chemical suppliers dominate feedstock production, constraining mid-tier mask manufacturers without long-term supply agreements.
- PVC:Plasticized polyvinyl chloride remains dominant in emergency medicine disposables despite phthalate migration concerns. United States group purchasing organizations concentrate procurement here, prioritizing unit cost over material sustainability profiles.
- Polypropylene:Injection-molded structural components provide rigid connector housings with gamma sterilization compatibility.
- Latex:Natural rubber formulations persist in niche markets despite allergen labeling requirements under EU MDR.
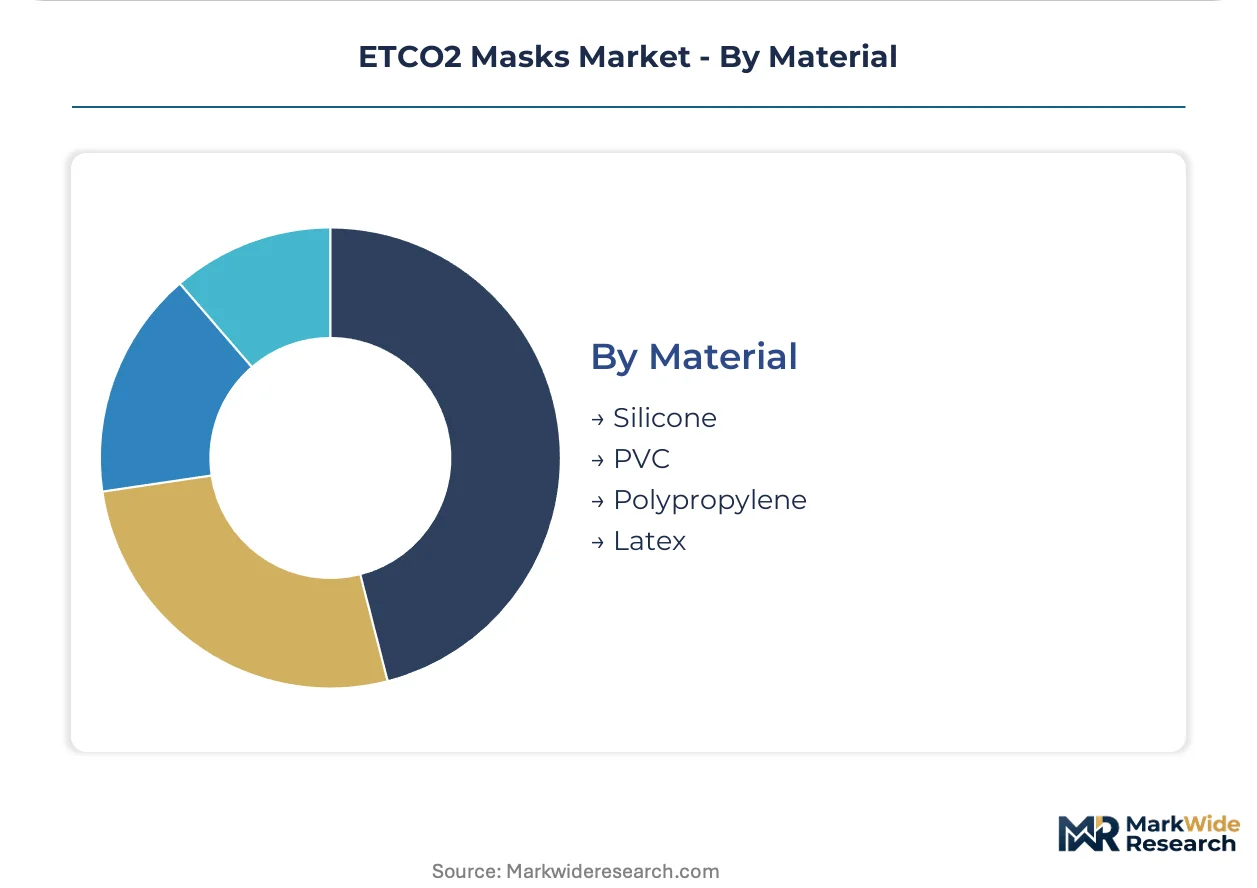
Unit volume concentrates in PVC; silicone is expanding most quickly as biocompatibility standards tighten across regulated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement for ETCO2 masks clusters in the United States, Germany, and China, where anesthesia and critical care infrastructure expansion drives concentrated demand. Regulatory mandates for capnography monitoring in these markets reshape supplier access requirements.
United States
FDA 510(k) clearance pathways structure competitive entry for capnography accessories, with Class II medical device standards elevating documentation burdens for sampling port modifications. The Joint Commission embeds continuous CO2 monitoring into procedural sedation protocols, accelerating disposable mask procurement across ambulatory surgical centers. Texas Medical Center in Houston anchors high-volume purchasing through integrated delivery network standardization programs.
Germany
EU MDR Class IIa designation forces mask manufacturers to maintain electronic patient registries tracking device-specific adverse events. University hospital consortia in Bavaria and North Rhine-Westphalia consolidate purchasing around suppliers with demonstrated biocompatibility traceability. Freiburg's medical technology cluster specializes in platinum-cured silicone formulations for reusable mask production serving European operating rooms.
China
NMPA medical device registration requirements constrain import timelines for foreign capnography accessory suppliers. National critical care infrastructure investment programs finance anesthesia workstation procurement in tertiary hospitals across the Yangtze River Delta. Shanghai's Pudong district concentrates domestic mask manufacturing capacity serving hospital networks in Jiangsu and Zhejiang provinces.
Japan
PMDA quality management system audits extend commercialization timelines for modified patient interface designs. METI industrial policy supports domestic production of medical-grade silicone feedstocks reducing import dependence from German and Japanese specialty chemical suppliers. Osaka's medical device manufacturing corridor hosts precision molding operations for pediatric mask geometries.
India
CDSCO medical device rules under the Drugs and Cosmetics Act classify capnography masks as notified devices requiring import licenses for foreign suppliers. National Health Mission hospital modernization programs in Maharashtra and Karnataka finance anesthesia equipment procurement bundling ETCO2 masks as essential consumables. Mumbai's pharmaceutical manufacturing belt expands into patient interface device assembly for domestic hospital chains.
ETCO2 Masks Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors bundle consumables with capital sales to lock in hospital procurement cycles. The vendor base stratifies across three tiers: diversified medical technology conglomerates with multi-parameter monitoring portfolios, anesthesia workstation specialists with proprietary connector ecosystems, and standalone consumable suppliers serving price-sensitive emergency medicine channels. Technology licensing agreements and backward integration into medical-grade silicone supply represent the dominant competitive moves reshaping margin structures.
Among diversified monitoring technology providers, Philips Healthcare and Masimo occupy positions exemplifying the convergence of pulse oximetry and capnography into unified patient interfaces. Drager represents the anesthesia workstation specialist archetype, anchoring European supply through integrated equipment-consumable ecosystems. These three entities illustrate how capital equipment relationships determine consumable market access across regulated hospital procurement channels.
| Leading Market Players |
|---|
| Philips Healthcare |
| Mindray |
| Masimo |
| Drager |
| Medtronic |
| Smiths Medical |
| Nihon Kohden |
| ZOLL Medical |
| Nonin Medical |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Germany and Japan anchor medical-grade silicone supply, constraining pricing discipline for mask manufacturers lacking long-term feedstock agreements while forcing tiered sourcing strategies across premium and disposable product lines.
Pricing Analysis
Volume placements in disposable PVC masks concentrate procurement leverage with United States group purchasing organizations, whereas reusable silicone variants command margin pools through after-sales service bundling with anesthesia workstations. Price differentiation hinges on ISO 10993 biocompatibility certification grade and sterilization cycle durability. Cost compression in emergency medicine disposables intensifies as infection control protocols mandate single-use consumption. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while German university hospitals prioritize total cost-of-ownership over unit economics.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and Singapore coordinate hub-and-spoke replenishment to hospital networks, compressing lead times for high-turnover consumables. Manufacturing concentrates in China, Germany, and the United States, with platinum-cured silicone feedstock drawn from Japanese and German specialty chemical suppliers. Single-source vulnerability in medical-grade elastomer production exposes mask makers to petrochemical price volatility. Distribution runs through group purchasing organization contracts that bundle consumables with capital equipment, locking out standalone suppliers lacking anesthesia machine portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class IIa documentation burdens and FDA 510(k) clearance timelines are consolidating vendor ranks, forcing mid-tier manufacturers without toxicology partnerships toward distressed exits or acquisition.
For Market Incumbents: Acquire biocompatibility validation capabilities through specialist toxicology laboratories or in-house ISO 10993 testing infrastructure. Philips Healthcare and Masimo defend multi-parameter monitoring suites against standalone mask entrants by embedding proprietary connector geometries into anesthesia workstation ecosystems. Backward integration into medical-grade silicone supply insulates margin structures from Japanese and German feedstock volatility. For New Entrants and Emerging Players: Capture skilled nursing facility and long-term acute care hospital demand in the United States, where post-acute capnography penetration remains underdeveloped relative to traditional hospital settings. Indian critical care infrastructure expansion under National Health Mission financing offers white-space procurement for domestic assembly operations. Position through disposable mask contracts that satisfy CDSCO import licensing requirements without capital equipment bundling overhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with incomplete EU MDR technical documentation in Germany and the United States, where clinical evidence shortfalls freeze commercialization timelines. Long-term viability centers on suppliers with demonstrated biocompatibility traceability and electronic patient registry infrastructure. Monitor NMPA registration acceleration for foreign capnography accessories as signal of Chinese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Electronic patient registries satisfy German university hospital procurement consolidation around traceability. |
| Backward Integration into Silicone Supply | Captive feedstock production insulates margin pools from Japanese and German petrochemical volatility. |
| Hospital System Partnership | Integrated delivery network contracts in Texas Medical Center standardize connector geometries across facilities. |
| Software Companion Development | Multi-parameter integration with pulse oximetry reduces bedside cable clutter in Chinese tertiary ICUs. |
| Reimbursement Strategy | Medicare alignment for ambulatory surgical centers satisfies The Joint Commission sedation mandates without infrastructure investment. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract repositories, and CMS Medicare reimbursement filings underwrites the qualitative findings. Primary interviews with clinicians, biomedical engineers, hospital purchasing committees, and GPO contracts managers combined with secondary validation from FDA 510(k) clearances, EU MDR technical documentation, and NMPA registration records. Bottom-up unit volume estimates triangulate against top-down anesthesia workstation installation data across the United States, Germany, and China.
Comparable-period anchoring to historical capnography mandate expansions structures the projection horizon across procedural sedation, emergency medicine, and post-acute care settings. Segmentation dimensions model product type, application, end user, material, and regional regulatory cluster. CAGRs derive from installed base growth in anesthesia workstations and monitoring device procurement cycles. Forecast inputs incorporate EU MDR transition timelines and FDA substantial equivalence review durations.
The model holds under steady regulatory enforcement intensity; deviation in capnography mandate expansion pace or silicone feedstock supply disruption would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Bone Power Tools Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
North America C-Arms Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Micro Syringes Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Global Artificial Limbs Market