
 Gas Turbine Service Market | 2026-2036
Gas Turbine Service Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Turbine Service Market Analysis
Saudi Arabia's power infrastructure expansion is reshaping competitive dynamics in gas turbine aftermarket services. Siemens Energy leverages its regional service hubs to anchor long-term agreements with state utility operators. GE Vernova competes through digital monitoring platforms that extend turbine availability guarantees. Mitsubishi Power specializes in hot gas path refurbishment for advanced-class turbines deployed across Middle Eastern combined-cycle facilities.
Gas turbine service encompasses inspection, repair, overhaul, and component replacement for rotating machinery operating above 1,000 degrees Celsius in continuous-duty cycles. Technicians perform borescope inspections, blade recoating, and combustion system recalibration to restore thermal efficiency and emissions compliance in power generation and mechanical drive applications. Component-level demand clusters around turbine blades and control systems, where thermal fatigue drives recurring replacement cycles with concentrated margin pools. Service type segmentation shows maintenance contracts generating stable baseline revenue while overhaul events create episodic demand spikes tied to fired-hour accumulations.
EPA emissions enforcement in the United States and EU Green Deal carbon benchmarks in Europe are tightening allowable NOx and CO2 thresholds for existing turbine fleets. Operators face capital decisions between control system upgrades, fuel switching modifications, or accelerated retirement pathways. The F-Gas Regulation in Europe further constrains refrigerant choices in turbine inlet cooling systems. Stakeholders must monitor regulatory phase-in timelines and assess retrofit economics against replacement alternatives.
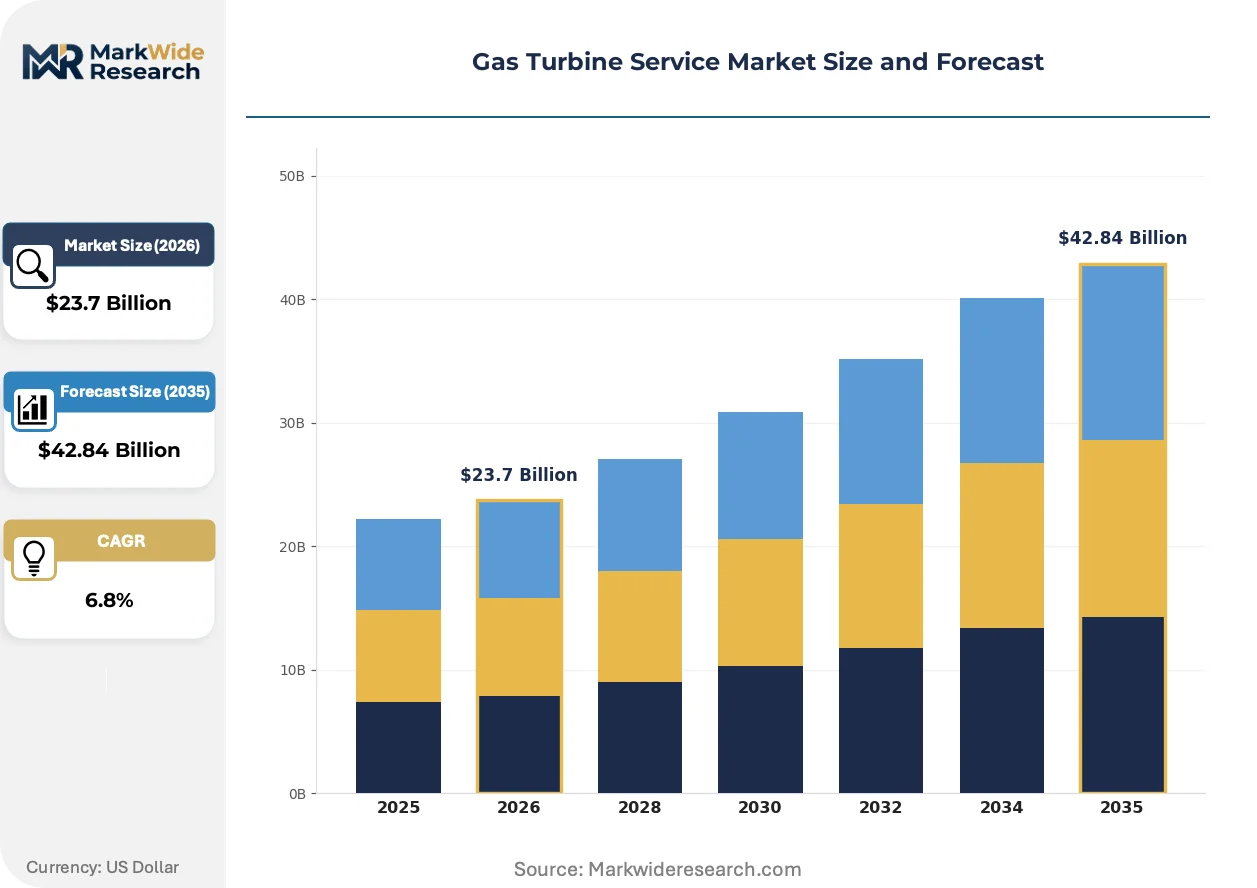
Market Dynamics
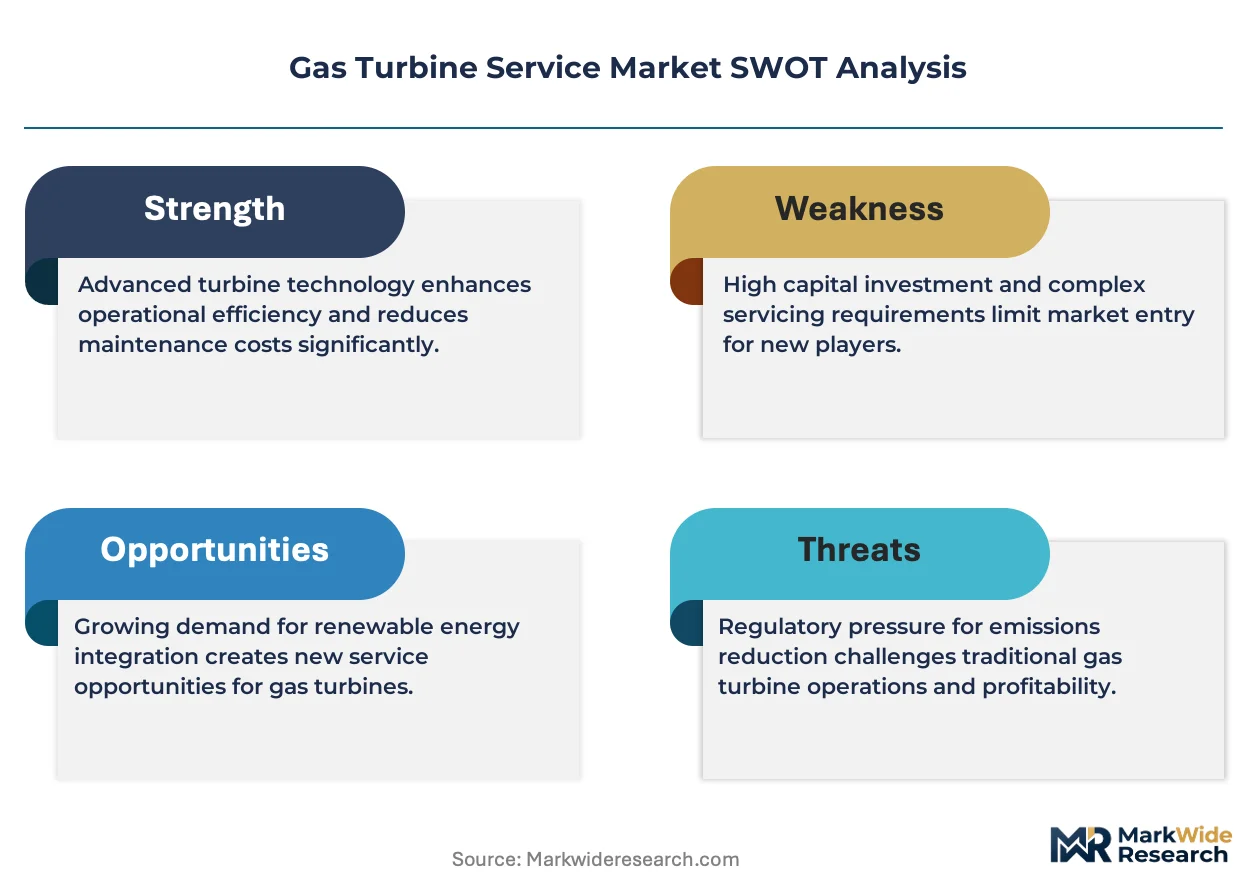
EPA emissions enforcement and EU Green Deal carbon benchmarks are forcing operators into capital-intensive fleet decisions, compressing upgrade timelines and reshaping service contract structures toward predictive maintenance and combustion system retrofits.
Growth Catalysts
- F-Gas Regulation in Europe:The refrigerant phase-down mandates turbine inlet cooling system overhauls, generating recurring service demand for OEMs and independent providers.
- Saudi Arabia state-backed power expansion:Combined-cycle plant deployments anchor long-term service agreements, concentrating aftermarket revenue in OEM-managed contracts.
- Predictive maintenance platforms:Digital monitoring systems reduce unplanned outages, extending turbine availability guarantees and locking in multi-year service relationships.
Market Restraints
- Specialized alloy supply concentration:Single-source dependence for nickel-based superalloys in blade casting creates input cost volatility and delivery risk.
- Technical limitation in hot section repair:Thermal barrier coating restoration for advanced-class turbines requires proprietary processes that constrain independent service provider entry.
- Regulatory friction from EPA NSR permitting:New Source Review requirements delay major combustion system upgrades, extending project timelines and freezing capital deployment.
Strategic Opportunities
- Underpenetrated Indonesia:Aging heavy-duty fleets in Southeast Asian power utilities lack comprehensive service coverage, creating white space for long-term agreement penetration.
- Hydrogen fuel blending retrofits:Combustion system modifications for hydrogen co-firing represent emerging application demand as operators pilot decarbonization pathways.
- Remote monitoring convergence with AI diagnostics:Machine learning integration with sensor networks enables condition-based maintenance, shifting revenue from scheduled to performance-guaranteed contracts.
Industry Challenges
- Specialized technician scarcity:Borescope inspection and blade recoating require certified expertise that outpaces vocational training pipeline output.
- Legacy control system integration:Digital platform deployment faces friction with analog turbine management systems installed in pre-2000s fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Turbine Service Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Component Replacement End User: Utilities, Oil & Gas, Power Generation, Aerospace Component: Turbine Blades, Exhaust Systems, Control Systems, Generators Service Provider: OEMs, Independent Service Providers, In-house Teams, Consultants |
| Companies Covered | Siemens Energy, GE Vernova, Mitsubishi Power, Ansaldo Energia, MAN Energy Solutions, Kawasaki Heavy Industries, Solar Turbines, MTU Aero Engines, Centrax Gas Turbines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Turbine Service Market Emerging Trajectories
Digitalization and decarbonization pressures are restructuring how operators procure, execute, and value gas turbine maintenance, compressing traditional service cycles and elevating performance-guaranteed contract models.
Additive manufacturing is hybridizing repair workflows for turbine blades and vanes. Power utilities in North America and the Middle East are adopting directed energy deposition for hot gas path component restoration. The technology is hybridizing supply chains, enabling localized repair hubs that reduce OEM parts dependence and compress turnaround timelines from weeks to days.
The EU F-Gas Regulation and EPA methane emissions rules are tightening operational envelopes for existing fleets. Operators face simultaneous compliance deadlines across refrigerant phase-down and greenhouse gas intensity reduction. Combined-cycle facilities in Germany and Texas are prioritizing control system upgrades over full unit replacement to meet overlapping mandates.
Long-term service agreements are displacing transactional overhaul procurement. State utilities in Saudi Arabia and independent power producers in Indonesia are consolidating vendor relationships into single-source, availability-based contracts. This concentration is most visible in the Middle East, where OEMs anchor regional hubs to capture multi-decade revenue streams tied to fired-hour accumulations.
Gas Turbine Service Market Segmentation
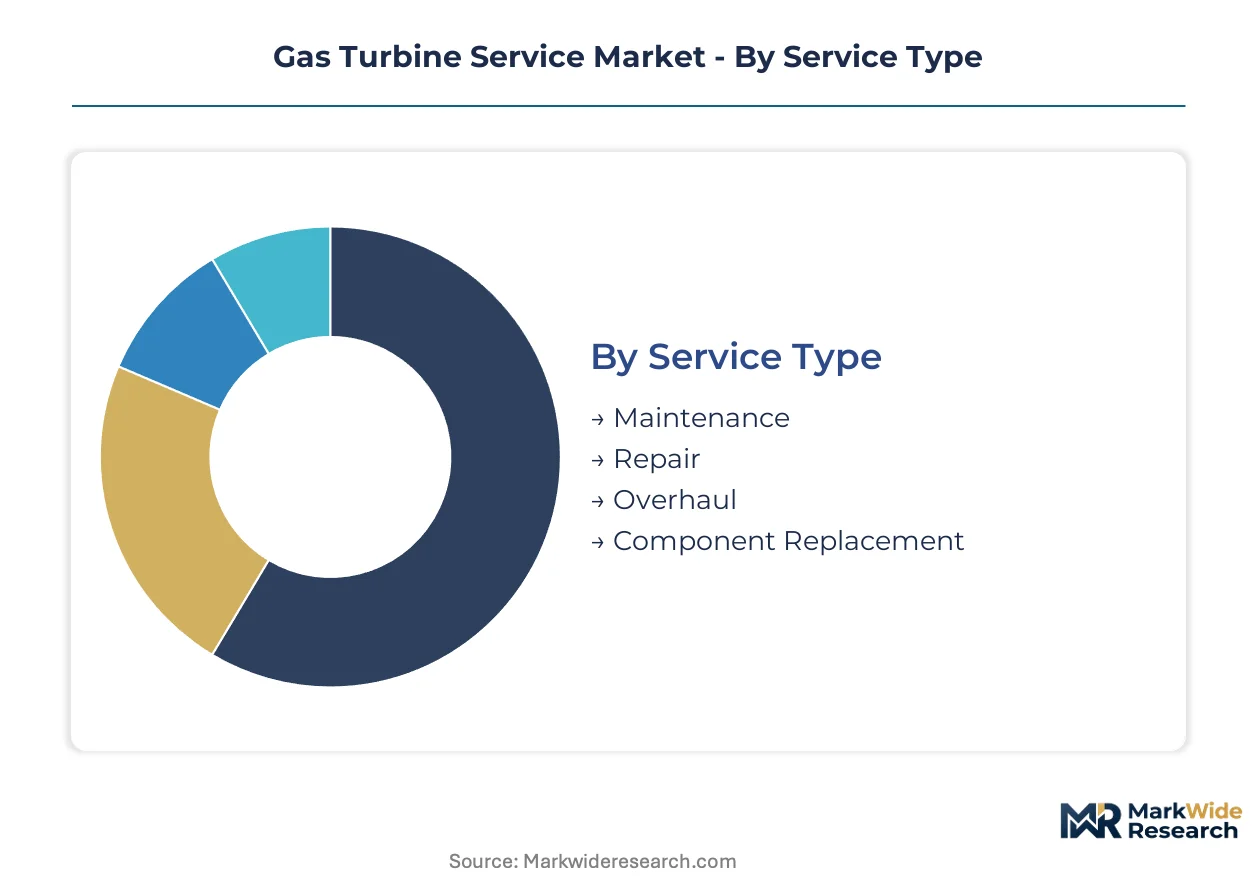
Gas turbine service procurement patterns diverge sharply across operational contexts. Segment boundaries reflect fired-hour accumulation rates, regulatory exposure, and the technical complexity of hot-section restoration.
Service Type:
Mature inspection protocols anchor baseline revenue while emerging digital interventions reshape contract economics.
- Maintenance:Scheduled borescope inspections and combustion tuning preserve thermal efficiency in continuous-duty cycles. Demand concentrates in Saudi Arabian combined-cycle facilities where state utilities lock in multi-year agreements with availability guarantees.
- Overhaul:Hot gas path refurbishment restores performance after fired-hour thresholds trigger mandatory outages. Southeast Asian power utilities are extending overhaul intervals through predictive diagnostics, compressing traditional cycle timelines.
- Repair:Blade recoating and casing weld restoration address thermal fatigue without full module replacement.
- Component Replacement:Rotor and combustor swaps eliminate downtime versus field restoration for aging fleets.
Maintenance handles the majority of throughput; Overhaul is the fastest mover on share.
End User:
Cost tier differentiation separates capital-rich utilities from margin-constrained independent operators.
- Utilities:State-backed operators in Saudi Arabia and Indonesia negotiate comprehensive long-term service agreements covering entire heavy-duty fleets. EPA emissions enforcement in the United States is accelerating control system upgrade procurement among municipal power authorities.
- Power Generation:Independent producers prioritize availability-based contracts over transactional overhaul procurement to secure financing.
- Oil & Gas:Mechanical drive applications in upstream and midstream operations demand rapid turnaround to minimize production loss.
- Aerospace:Derivative industrial turbines in aviation-linked facilities require specialized FAA-compliant documentation trails.
Utilities dominate contract value concentration; Power Generation is expanding most quickly as merchant plant deployment accelerates.
Component:
Supply concentration around superalloy casting creates margin stratification across replacement categories.
- Turbine Blades:Directionally solidified and single-crystal superalloy components endure temperatures exceeding 1,400 degrees Celsius. Nickel-based alloy supply constraints from single-source foundries drive procurement pre-positioning among Middle Eastern operators.
- Control Systems:Digital upgrades enable predictive maintenance and emissions compliance monitoring. German and Texan combined-cycle facilities are prioritizing control system retrofits over full unit replacement to meet overlapping EU F-Gas and EPA methane mandates.
- Exhaust Systems:Heat recovery steam generator integration requires corrosion-resistant metallurgy for cycling duty.
- Generators:Stator rewinding and rotor balancing restore electrical output efficiency in baseload configurations.
Turbine Blades capture the steepest margin pools; Control Systems is climbing the fastest as digitalization penetrates legacy fleets.
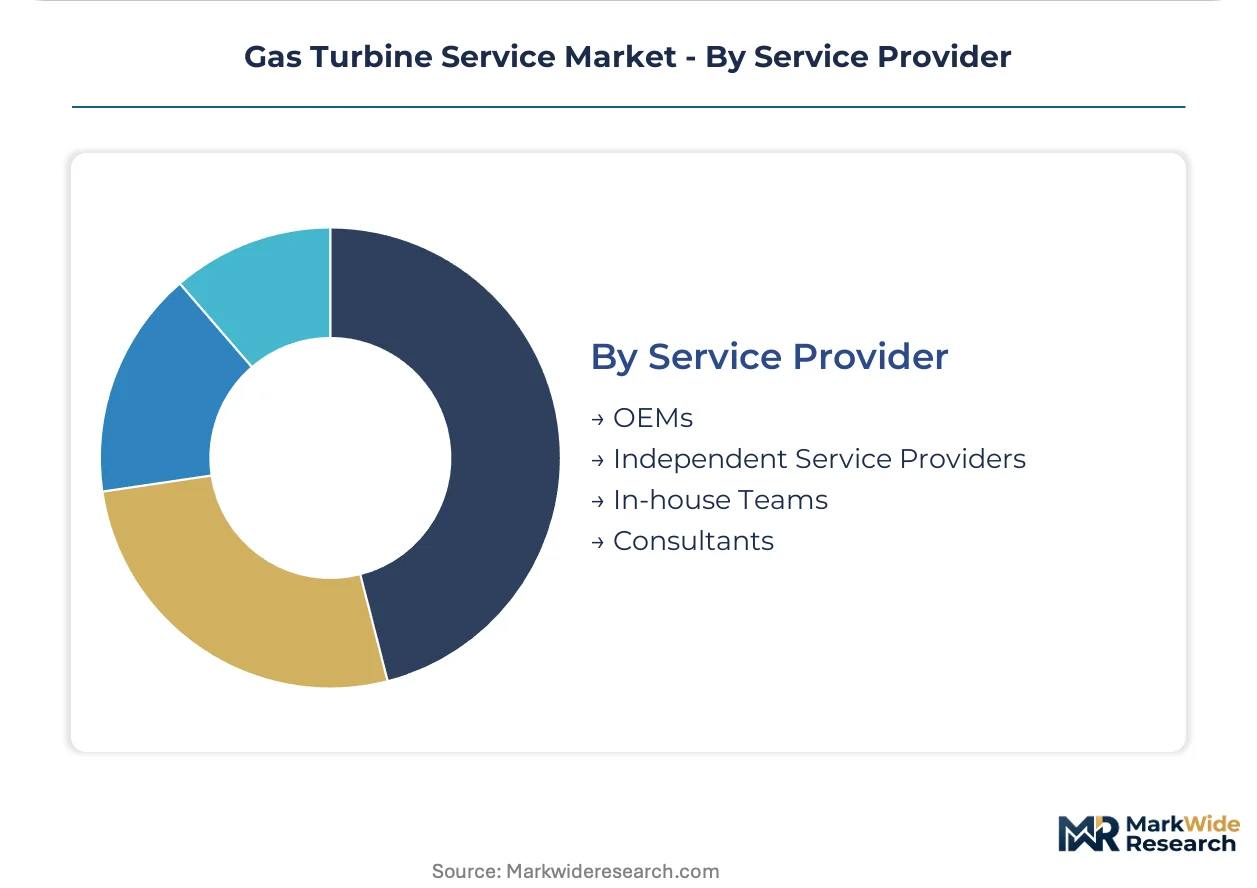
Service Provider:
Customer type fragmentation splits procurement between OEM-captive relationships and independent cost optimization.
- OEMs:Original equipment manufacturers anchor regional service hubs in Saudi Arabia to capture multi-decade revenue streams. Siemens Energy and GE Vernova compete through digital monitoring platforms that extend availability guarantees.
- Independent Service Providers:Third-party specialists target blade repair and combustion system upgrades where proprietary thermal barrier coating processes do not block entry.
- In-house Teams:Large utility operators in North America maintain captive technical capabilities for routine inspection and minor component replacement.
- Consultants:Engineering advisory firms guide capital decisions between retrofit, repowering, and retirement pathways under tightening EPA and EU emissions frameworks.
OEMs retain the dominant share of long-term agreements; Independent Service Providers are gaining share fastest in hot-section repair niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Original equipment manufacturers anchor regional service hubs in Saudi Arabia, Germany, and the United States to capture multi-decade revenue streams tied to fired-hour accumulations and emissions compliance mandates.
United States
EPA emissions enforcement accelerates control system upgrade procurement among municipal power authorities. The New Source Review permitting framework delays major combustion system retrofits, extending project timelines. Texan combined-cycle facilities prioritize control system upgrades over full unit replacement to meet overlapping EPA methane mandates.
Saudi Arabia
State-backed power expansion programs rely on OEM-managed service contracts for combined-cycle plant deployments. The national utility operator negotiates comprehensive long-term service agreements covering entire heavy-duty fleets. Riyadh and the Eastern Province concentrate aftermarket revenue in regional service hubs operated by Siemens Energy and GE Vernova.
Germany
The EU F-Gas Regulation and EU Green Deal carbon benchmarks tighten allowable NOx and CO2 thresholds for existing turbine fleets. German combined-cycle facilities face simultaneous compliance deadlines across refrigerant phase-down and greenhouse gas intensity reduction. Industrial clusters in North Rhine-Westphalia and Bavaria prioritize control system retrofits to meet overlapping mandates.
Indonesia
Aging heavy-duty fleets in Southeast Asian power utilities lack comprehensive service coverage, creating white space for long-term agreement penetration. State utility operators extend overhaul intervals through predictive diagnostics, compressing traditional cycle timelines. Jakarta and Surabaya concentrate demand for borescope inspections and combustion tuning in continuous-duty cycles.
United Arab Emirates
Independent power producers consolidate vendor relationships into single-source, availability-based contracts to secure project financing. Dubai and Abu Dhabi anchor regional demand for hot gas path refurbishment and blade recoating services. The Emirates' national energy strategy drives procurement pre-positioning for nickel-based superalloy components amid single-source supply constraints.
Gas Turbine Service Market Vendor Landscape
Original equipment manufacturers and independent service providers split the market between long-term availability contracts and transactional hot-section repair. The vendor base concentrates around OEM-captive relationships in Saudi Arabia and the United States, with third-party specialists gaining share in blade repair niches where proprietary thermal barrier coating processes do not block entry. Two strategic archetypes dominate: scale-driven OEMs with digital monitoring platforms, and specialized independents with directed energy deposition capabilities. Competitive moves center on regional hub expansion and predictive maintenance technology licensing.
Within the scale-driven tier, Siemens Energy, GE Vernova, and Mitsubishi Power occupy positions as archetype anchors. Siemens Energy exemplifies the OEM-captive model through regional service hubs in the Middle East. GE Vernova represents the digital monitoring convergence with sensor networks and AI diagnostics. Mitsubishi Power sits within the hot gas path specialization vector for advanced-class turbines. These three companies collectively illustrate how market structure rewards availability guarantees and fired-hour-based contract economics.
| Leading Market Players |
|---|
| Siemens Energy |
| GE Vernova |
| Mitsubishi Power |
| Ansaldo Energia |
| MAN Energy Solutions |
| Kawasaki Heavy Industries |
| Solar Turbines |
| MTU Aero Engines |
| Centrax Gas Turbines |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Singapore maritime corridor carries nickel-based superalloy castings and thermal barrier coating precursors from European foundries to Middle Eastern service hubs. Freight cost volatility on this route amplifies margin pressure for independent repair providers while reinforcing OEM pricing power through captive inventory positioning near Saudi combined-cycle installations.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across turbine inlet cooling system services. Three-tier pricing structure across premium, standard, and economy levels separates OEM-managed availability contracts from independent hot-section repairs and transactional component sales. Price differentiation stems from certification grade and fired-hour guarantee duration. Margins are tightening due to nickel superalloy supply constraints. Merchant power producers exhibit highest price sensitivity; state utilities in Saudi Arabia demonstrate lowest.
Supply Chain Analysis
Extended payment terms from OEMs to superalloy foundries anchor working capital structures for blade casting operations. Supply concentrates in Germany, Japan, and the United States for directionally solidified turbine components. Raw material dependencies include nickel, cobalt, and ceramic thermal barrier coating feedstocks. Single-source vulnerability in single-crystal casting creates structural risk. Distribution runs through regional OEM hubs and independent repair facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas turbine service market operates as a high-switching-cost defensive moat. Regulatory entrenchment through EPA emissions mandates and EU F-Gas compliance locks operators into long-term OEM relationships.
For Market Incumbents: Harden predictive maintenance platform differentiation through AI diagnostics integration to defend against independent service provider encroachment in blade repair niches. Deepen backward integration into nickel superalloy sourcing to offset single-source foundry concentration. Prioritize certification investment for hydrogen combustion system retrofits. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's aging heavy-duty fleet segment where comprehensive service coverage gaps persist. Target predictive diagnostics licensing to Southeast Asian utilities extending overhaul intervals. Pursue directed energy deposition repair capabilities as the go-to-market angle for hot gas path component restoration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive gas turbine service divisions lacking scale for digital platform investment. Five-to-ten year viability hinges on hydrogen retrofit capability positioning. Monitor EPA NSR permitting velocity as the inflection signal for upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Expansion | Saudi state utilities anchor multi-decade revenue through fired-hour-based contracts with Siemens Energy and GE Vernova. |
| Predictive Maintenance Platform Deployment | AI diagnostics integration enables condition-based contracts that displace scheduled maintenance revenue models. |
| Hydrogen Combustion Retrofit Development | EPA and EU Green Deal carbon benchmarks force pilot programs for hydrogen co-firing in combined-cycle plants. |
| Regional Hub Capacity Addition | Middle Eastern OEM service hubs capture aftermarket concentration from state-backed power expansion programs. |
| Additive Manufacturing Repair Capability | Directed energy deposition technologies compress blade turnaround timelines from weeks to days for North American utilities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Secondary validation drew from EIA generation data, IEA power sector reports, FERC filings, and project development databases. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates.
Calibration against historical contract award patterns and fired-hour accumulation rates refined projections across the analysis window. Segmentation dimensions modeled include service type, end-user category, component category, and regional regulatory framework. CAGRs derived from regression analysis of contract value growth against turbine fleet aging curves and emissions compliance investment cycles. Forecast inputs incorporated EPA enforcement timelines and EU F-Gas phase-down schedules.
Sensitivities concentrate around regulatory phase-in velocity and superalloy supply disruption scenarios. Forecasts reflect documented assumptions regarding maintenance interval extension rates and hydrogen retrofit adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market