
 Aero Engine Coatings Market | 2026-2036
Aero Engine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Aero Engine Coatings Market Analysis
MRO service providers is unwinding the historical dominance of OEM coating procurement as airlines extend engine life cycles and outsource thermal barrier refurbishment. Praxair S.T. Technology, Inc. leverages its plasma spray infrastructure to anchor North American aftermarket supply chains. OC Oerlikon Corporation AG competes through specialized PVD and CVD equipment lines that sustain European aerospace certification density.
Aero engine coatings are engineered surface treatments—typically yttria-stabilized zirconia ceramic layers deposited via air plasma spray or electron-beam physical vapor deposition—designed to insulate turbine blades from operating temperatures exceeding 1,200°C and prevent hot-section oxidation. Thermal barrier coatings command the deepest margin pools due to their criticality in next-generation high-bypass turbofans, while abradable coatings grow fastest from mounting demand for compressor clearance control in geared turbofan architectures. Ceramic materials dominate R&D allocation as OEMs pursue lower thermal conductivity formulations, though metallic alloys retain volume leadership in legacy engine overhaul programs.
FAA airworthiness directives and EASA certification standards jointly elevate coating qualification thresholds, forcing suppliers to maintain dual-continent testing protocols and traceable thermal cycling documentation. EPA emissions regulations indirectly tighten coating specifications by pushing engines toward higher combustion temperatures that stress thermal protection systems. Stakeholders must monitor evolving REACH chemical restrictions on hexavalent chromium pretreatments and assess in-house production of ceramic feedstock powders as supply security becomes a strategic priority.
Market Dynamics
FAA airworthiness directives on thermal management are compressing refurbishment cycles for commercial turbofan operators, forcing coating suppliers to accelerate qualification timelines while OEM overhaul facilities absorb capacity constraints from military depot backlogs.
Growth Catalysts
- High-bypass turbofan proliferation:Next-generation engines with bypass ratios exceeding 10:1 require thicker yttria-stabilized zirconia thermal barrier systems on high-pressure turbine blades, pulling demand from both OEM production lines and MRO channels.
- REACH chemical restrictions:European ECHA regulations on hexavalent chromium pretreatments are accelerating qualified alternative surface preparation methods, creating first-mover advantages for suppliers with validated chromium-free bonding layers.
- Geared turbofan architectures:Pratt & Whitney's PW1000G series and competing designs demand precision abradable coatings for compressor clearance control, expanding addressable coating surface area per engine by 15-20% over conventional turbofans.
Market Restraints
- Ceramic feedstock concentration:High-purity yttria-stabilized zirconia powder supply concentrates among three specialty chemical producers, exposing coating applicators to price volatility and allocation risk during aerospace production surges.
- Dual-continent testing burden:Simultaneous FAA and EASA certification requirements force suppliers to maintain parallel thermal cycling test facilities in the United States and Europe, duplicating capital expenditure without volume scaling benefits.
- Plasma spray equipment lead times:Automated high-velocity oxygen fuel and air plasma spray systems face 18-24 month delivery backlogs from European and Japanese equipment builders, constraining coating shop expansion plans.
Strategic Opportunities
- Indian MRO infrastructure buildout:The country's PLI scheme for aerospace manufacturing and emerging engine overhaul clusters in Hyderabad and Bengaluru create captive demand for thermal barrier coating application services as IndiGo and Air India expand leased-fleet refurbishment programs.
- Sustainability-linked procurement mandates:European airline group purchasing organizations are embedding lifecycle carbon metrics into coating supplier selection criteria, rewarding applicators with renewable-powered plasma spray facilities and closed-loop powder recovery systems.
- Hybrid electron beam-PVD integration:Convergence of directed vapor deposition with traditional electron-beam physical vapor deposition enables columnar ceramic microstructures with 30% lower thermal conductivity, opening performance gaps against conventional air plasma spray coatings in next-generation single-crystal turbine blades.
Industry Challenges
- Certified technician scarcity:FAA-approved plasma spray operators and NDT inspectors for thermal barrier coating quality assurance command premium wages and require 2,000+ hour apprenticeship programs, constraining MRO shop throughput expansion.
- Legacy engine documentation gaps:Pre-digital-era turbine blade substrate specifications and original coating thickness records are frequently incomplete, forcing destructive sectioning and re-qualification of refurbished components that delays turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aero Engine Coatings Market |
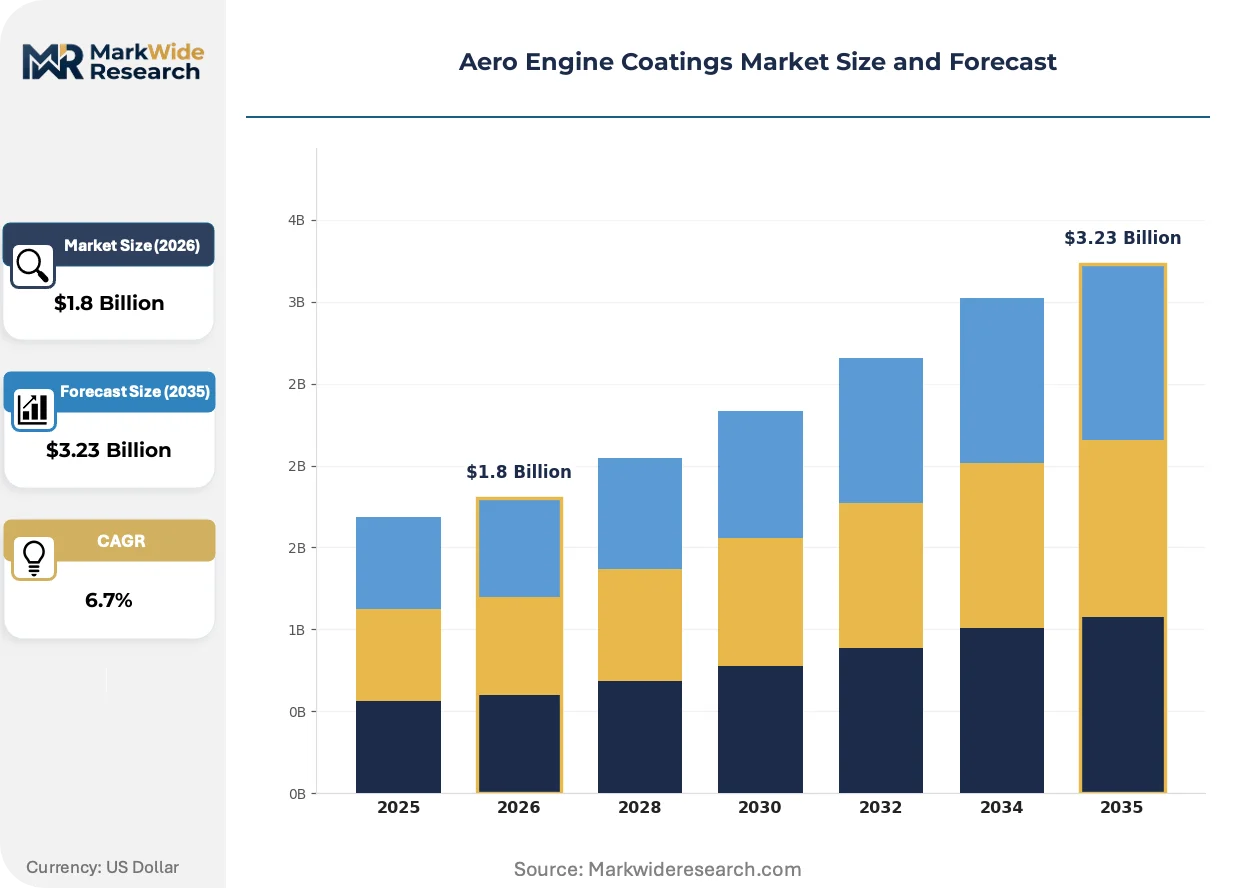
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Thermal Barrier Coatings, Abradable Coatings, Wear-Resistant Coatings, Corrosion-Resistant Coatings Application: Commercial Aviation, Military Aviation, General Aviation, Spacecraft End User: OEMs, MRO Service Providers, Tier-1 Suppliers, Aftermarket Distributors Material: Metallic Alloys, Ceramics, Composite Materials, Others |
| Companies Covered | Praxair S.T. Technology, Inc., A&A Thermal Spray Coatings, APS Materials, Inc., PPG Industries, Inc., OC Oerlikon Corporation AG, Akzo Nobel NV, Lincotek Surface Solutions SPA, Indestructible Paint Limited, Chromalloy Gas Turbine LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aero Engine Coatings Market Emerging Trajectories
Coating deposition technologies are diverging from standardized air plasma spray dominance as engine OEMs pursue property-specific microstructures, while regulatory chemical restrictions and airline procurement restructuring simultaneously reshape supplier qualification pathways.
Multilayer thermal barrier architectures with strain-tolerant bond coats and dense vertically cracked ceramic topcoats are fragmenting the historical single-layer coating standard. GE Aerospace and Rolls-Royce are qualifying these systems for their newest wide-body engine programs, enabling 50°C higher turbine inlet temperatures without substrate superalloy redesign. This materials differentiation is fragmenting the coating applicator base into specialists capable of precise layer thickness control versus generalist shops locked in commodity refurbishment.
EPA emissions regulations under the Clean Air Act are indirectly tightening coating specifications by pushing combustion temperatures higher to reduce NOx formation. Thermal barrier coatings must now demonstrate 1,200+ hour cyclic oxidation resistance under more severe thermal gradients, forcing reformulation of rare-earth dopant profiles in yttria-stabilized zirconia. High-pressure turbine segment suppliers in the United States are responding with accelerated thermal cycling test protocols that compress traditional 18-month qualification schedules.
Airline technical procurement departments are consolidating coating refurbishment awards under long-term MRO service agreements rather than transactional purchase orders. This contractual restructuring disintermediates independent coating applicators and favors vertically integrated engine overhaul facilities with captive thermal spray capacity. The shift is most visible among US-based ultra-low-cost carriers operating leased narrowbody fleets, where power-by-the-hour contracts bundle coating life extension into hourly engine maintenance rates.
Aero Engine Coatings Market Segmentation
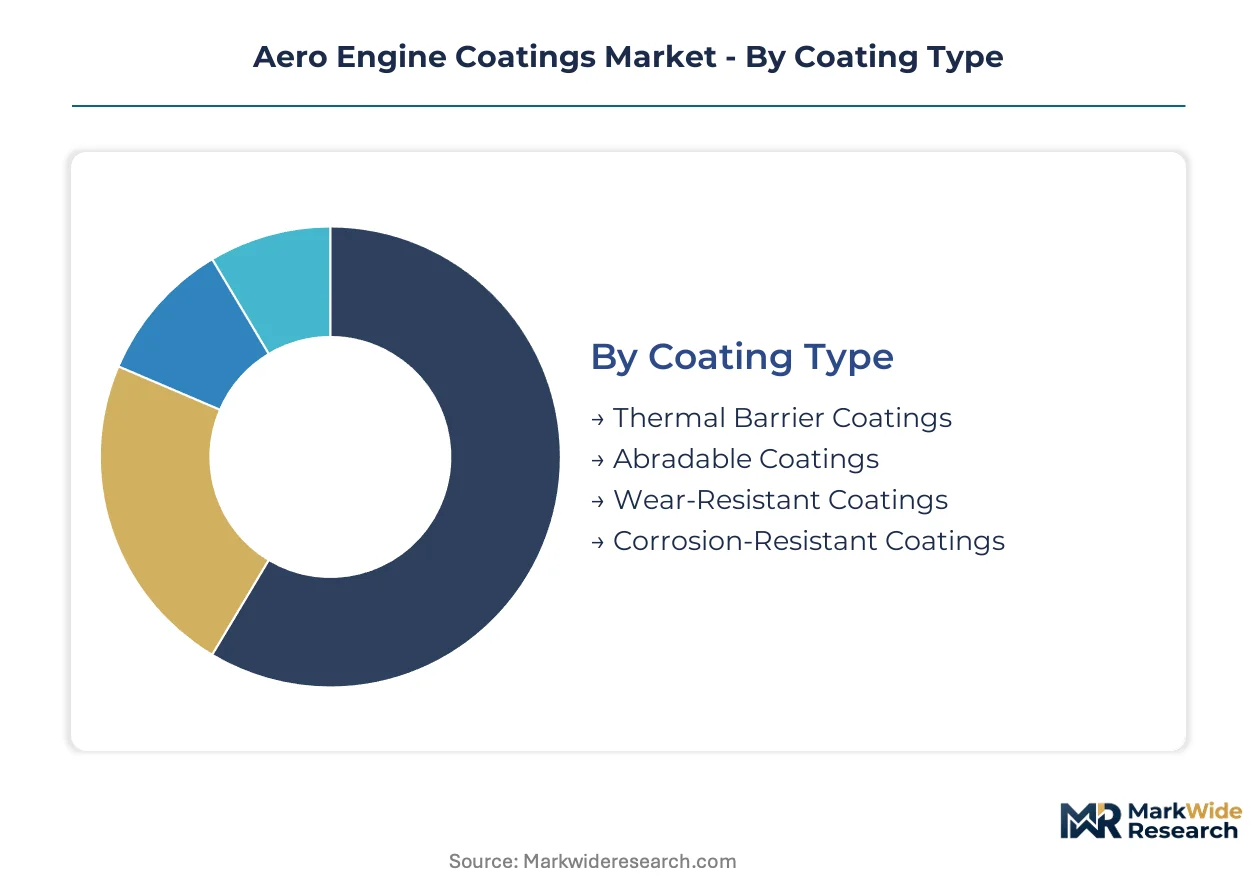
Coating procurement channels diverge sharply by segment, with OEM production lines demanding certified fresh applications while MRO channels handle refurbishment cycles compressed by FAA airworthiness directives. Understanding these pathway distinctions enables suppliers to align thermal spray capacity with the qualification burdens and volume profiles of each segment.
Coating Type:
Channel flow splits between OEM new-engine procurement and MRO refurbishment, with thermal barrier systems dominating production-line volumes while abradable coatings concentrate in aftermarket compressor restoration.
- Thermal Barrier Coatings:Yttria-stabilized zirconia ceramic layers deposited via air plasma spray or electron-beam PVD insulate high-pressure turbine blades from combustion temperatures exceeding 1,200°C. Demand concentrates in United States OEM overhaul facilities and military depots where FAA thermal management directives tighten refurbishment cycles.
- Abradable Coatings:Compressor clearance control formulations enable tighter blade-tip tolerances in geared turbofan architectures. Pratt & Whitney PW1000G series production and aftermarket programs in Connecticut and Singapore MRO clusters drive specification evolution toward aluminum-silicon-polyester blends.
- Wear-Resistant Coatings:Tungsten carbide-cobalt cermets protect bearing housings and gearbox components from fretting fatigue in high-cycle regional jet operations.
- Corrosion-Resistant Coatings:Aluminide and platinum-aluminide diffusion coatings guard against hot-section oxidation in marine-environment based fleets.
By volume, thermal barrier coatings lead. By growth pace, abradable coatings are expanding most quickly.
Application:
Cost tier stratification separates premium-certified military programs from commercial aviation volume procurement, with general aviation representing a price-sensitive refurbishment tier.
- Commercial Aviation:High-bypass turbofan fleets generate recurring thermal barrier refurbishment demand as airlines extend engine life cycles through power-by-the-hour contracts. United States ultra-low-cost carriers operating leased narrowbody fleets now bundle coating life extension into hourly maintenance rates.
- Military Aviation:Fighter engine depot programs require traceable thermal cycling documentation and dual-continent FAA-EASA qualification protocols. United States Air Force and Navy overhaul facilities absorb capacity from commercial MRO shops during surge procurement cycles.
- General Aviation:Turboprop and light jet operators prioritize cost-minimized refurbishment over OEM-certified fresh applications.
- Spacecraft:Reusable launch vehicle turbine components demand ultra-high-temperature ceramic matrix composites for brief-duration extreme thermal exposure.
Commercial aviation commands the largest refurbishment volume. Military aviation maintains the steepest certification premium.
End User:
Customer type determines procurement structure, with OEMs and Tier-1 suppliers locking in long-term supply agreements while MRO providers and aftermarket distributors compete on turnaround velocity.
- OEMs:GE Aerospace and Rolls-Royce qualify multilayer thermal barrier architectures with strain-tolerant bond coats for newest wide-body engine programs. These production-line contracts demand 50°C higher turbine inlet temperature capability without substrate superalloy redesign.
- MRO Service Providers:Independent coating shops face disintermediation as airlines consolidate refurbishment awards under vertically integrated engine overhaul facilities. Praxair S.T. Technology anchors North American aftermarket supply chains through plasma spray infrastructure.
- Tier-1 Suppliers:High-pressure turbine segment manufacturers in United States respond with accelerated thermal cycling test protocols.
- Aftermarket Distributors:Inventory positioning for emergency AOG coating replacement drives regional stocking requirements.
OEMs dominate fresh application value. MRO service providers are gaining refurbishment volume share fastest.
Material:
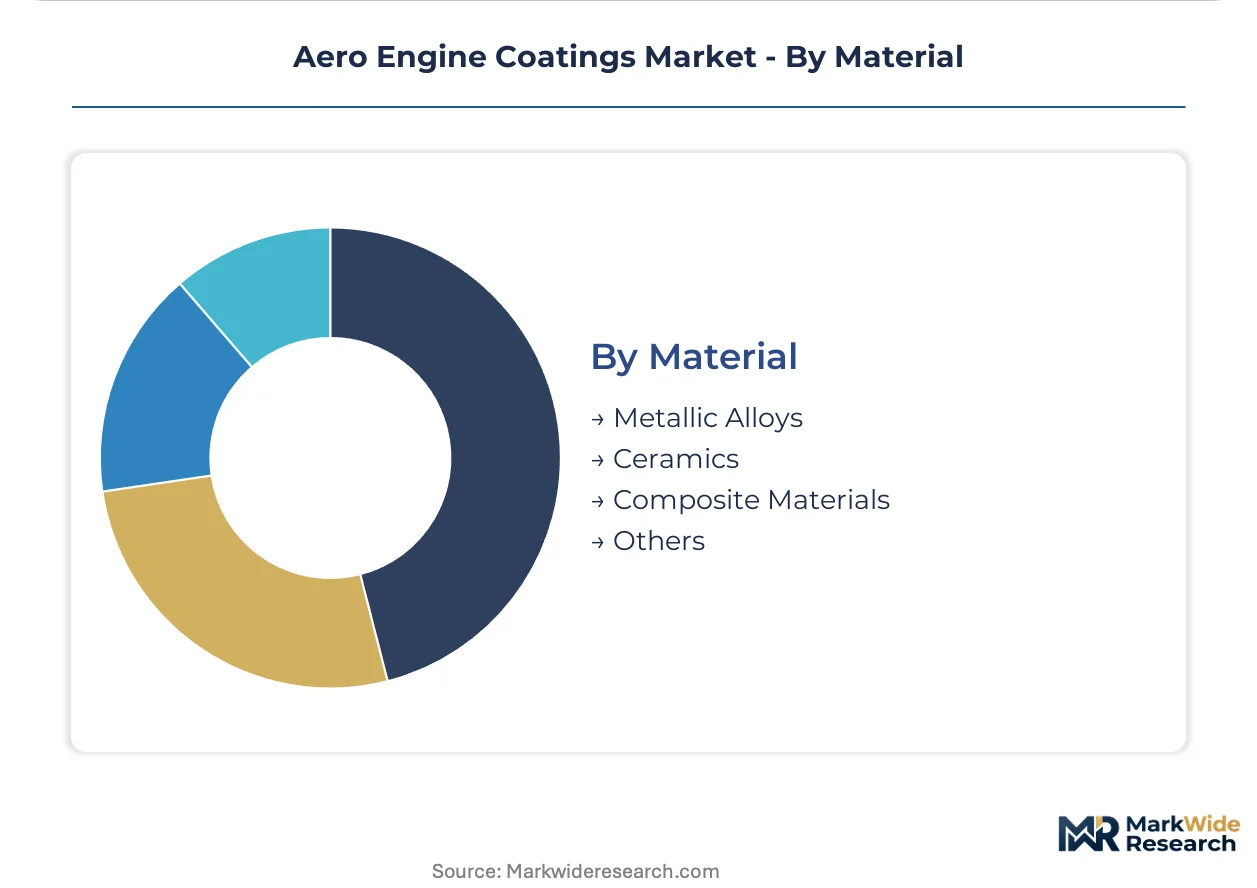
Supply concentration shapes material selection, with ceramic feedstock scarcity pushing R&D toward lower-thermal-conductivity formulations while metallic alloys retain legacy overhaul dominance.
- Ceramics:Yttria-stabilized zirconia with rare-earth dopant profiles dominates next-generation high-bypass turbofan thermal protection. High-purity powder supply concentrates among three specialty chemical producers, exposing coating applicators to allocation risk.
- Metallic Alloys:MCrAlY overlay coatings retain volume leadership in legacy engine overhaul programs where substrate specifications predate digital documentation. Pre-digital-era turbine blade records frequently force destructive sectioning and re-qualification.
- Composite Materials:Ceramic matrix composites emerge for reusable launch vehicle applications requiring brief extreme-temperature exposure.
- Others:Polymer-ceramic hybrids serve niche abradable applications in auxiliary power units.
Metallic alloys lead by current refurbishment volume. Ceramics are climbing the fastest on new-engine penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate pipeline network for natural gas and refined products underwrites North American aerospace manufacturing density, while European high-speed rail corridors and Asian port container throughput shape coating demand distribution across production clusters.
United States
FAA airworthiness directives on thermal management compress refurbishment cycles for commercial turbofan operators. The Department of Defense maintains fighter engine depot programs requiring traceable thermal cycling documentation. Connecticut hosts Pratt & Whitney's PW1000G geared turbofan production, pulling precision abradable coating demand into the Northeast corridor.
Germany
MTU Aero Engines and Rolls-Royce Deutschland drive thermal barrier system procurement for next-generation high-bypass turbofans. ECHA REACH regulations on hexavalent chromium pretreatments accelerate qualified alternative surface preparation methods. Bavaria's Munich aerospace cluster concentrates PVD and CVD equipment manufacturing for European certification density.
United Kingdom
Rolls-Royce Derby facilities qualify multilayer thermal barrier architectures with strain-tolerant bond coats for wide-body engine programs. UK CAA alignment with EASA certification standards forces dual-continent testing protocols. Southwest England's Bristol aerospace corridor hosts specialized plasma spray infrastructure for military and commercial overhaul.
India
IndiGo and Air India expand leased-fleet refurbishment programs, creating captive demand for thermal barrier coating application services. The PLI scheme for aerospace manufacturing subsidizes engine overhaul cluster development. Hyderabad and Bengaluru emerging MRO infrastructure attracts coating shop investment from global applicators seeking cost arbitrage.
Singapore
Pratt & Whitney and Rolls-Royce regional MRO hubs service Asia-Pacific geared turbofan fleets, concentrating abradable coating refurbishment demand. The Maritime and Port Authority's container throughput supports just-in-time ceramic feedstock powder imports. Seletar Aerospace Park hosts automated thermal spray capacity expansion serving Southeast Asian airline technical procurement.
Aero Engine Coatings Market Vendor Landscape
Listed leaders compete with private specialists across qualification burden and capital intensity dimensions, producing a tiered structure where scale-driven applicators absorb FAA-EASA dual certification costs while regional shops capture turnaround velocity premiums. Three archetypes dominate: integrated industrial gas suppliers with captive thermal spray infrastructure, specialized surface engineering houses with aerospace-specific accreditation, and diversified coatings conglomerates leveraging cross-sector formulation expertise. Competitive moves concentrate on geographic expansion into Indian MRO clusters and backward integration into ceramic feedstock powder production.
Among North American infrastructure-anchored players, Praxair S.T. Technology, Inc. exemplifies the industrial gas supplier archetype with plasma spray network density, while Chromalloy Gas Turbine LLC occupies a position within the specialized aerospace applicator tier. OC Oerlikon Corporation AG represents European equipment-integrated surface engineering, anchoring PVD and CVD qualification pathways. These three sit within distinct competitive vectors—feedstock supply security, military depot relationships, and European certification density—rather than direct product confrontation.
| Leading Market Players |
|---|
| Praxair S.T. Technology, Inc. |
| A&A Thermal Spray Coatings |
| APS Materials, Inc. |
| PPG Industries, Inc. |
| OC Oerlikon Corporation AG |
| Akzo Nobel NV |
| Lincotek Surface Solutions SPA |
| Indestructible Paint Limited |
| Chromalloy Gas Turbine LLC |
| Others |
Supply Flow & Price Mechanics
FAA-EASA dual certification requirements gate both supplier qualification and price differentiation simultaneously, forcing coating applicators to absorb redundant testing costs that compress margins while creating tiered pricing power for those holding both accreditations. Buyers face procurement fragmentation as military depot programs absorb commercial MRO capacity, stretching lead times and inflating premiums for traceable thermal cycling documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified fresh applications from depot-qualified military refurbishment and general aviation cost-minimized rework. Price differentiation centers on certification density and thermal cycling traceability, with dual-continent qualified suppliers commanding substantial premiums over single-accreditation shops. Cost compression in standard-tier commercial MRO channels is intensifying because airlines consolidate awards under power-by-the-hour contracts. General aviation turboprop operators exhibit highest price sensitivity, while United States Air Force and Navy depot programs remain least sensitive due to mission-critical requirements.
Supply Chain Analysis
Eighteen-to-twenty-four month delivery backlogs for automated plasma spray equipment from European and Japanese builders constrain coating shop expansion and force inventory pre-positioning of ceramic feedstock. Supply concentrates in the United States, Germany, and Japan for high-purity yttria-stabilized zirconia powder, specialty thermal spray systems, and electron-beam PVD equipment respectively. Raw material dependencies rest on rare-earth dopant chemicals, high-velocity oxygen fuel consumables, and precision gas supply infrastructure. Single-source vulnerability pervades ceramic feedstock production where three specialty chemical producers control aerospace-grade powder allocation. Distribution runs through OEM overhaul facilities, military depots, and emerging Indian MRO clusters with diverging qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering cyclically as commercial aviation fleet operators restore engine overhaul programs deferred during capacity constraints, with Pratt & Whitney PW1000G production ramp and IndiGo-Air India fleet expansion driving refurbishment demand normalization.
For Market Incumbents: Fortify captive ceramic feedstock supply through backward integration into yttria-stabilized zirconia powder production or long-term offtake agreements with specialty chemical producers, eliminating allocation risk exposure during aerospace production surges. Deepen certification moats by accelerating thermal cycling test protocol investments that compress qualification timelines for multilayer thermal barrier architectures, outrunning emerging applicators lacking parallel FAA-EASA facility infrastructure.
For New Entrants and Emerging Players: Lead with chromium-free surface preparation technologies validated under REACH chemical restrictions, capturing first-mover positioning as European ECHA regulations displace hexavalent chromium pretreatments across the supply base. Target Indian MRO infrastructure buildout in Hyderabad and Bengaluru, where PLI scheme subsidies and emerging engine overhaul clusters create captive demand without entrenched incumbent density. Deploy automated thermal spray capacity with renewable energy sourcing to meet sustainability-linked procurement mandates from European airline group purchasing organizations.
For Investors and Strategic Acquirers: FAA airworthiness directive tightening on thermal management reshapes the acquisition landscape by compressing refurbishment cycles and expanding addressable coating surface area per engine, favoring targets with scalable plasma spray infrastructure over equipment-light service models. Long-term viability over the next decade rests on exposure to geared turbofan architectures and high-bypass turbofan proliferation rather than legacy narrowbody overhaul dependence. Monitor Indian MRO cluster development velocity and Pratt & Whitney production ramp rates as inflection indicators for coating application service demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Feedstock | Captive yttria-stabilized zirconia supply eliminates allocation risk from three-producer concentration. |
| Dual-Continent Certification Investment | Parallel FAA-EASA testing protocols unlock military depot and European airline procurement simultaneously. |
| Indian MRO Geographic Expansion | Hyderabad and Bengaluru clusters capture PLI-subsidized demand from IndiGo and Air India refurbishment. |
| Chromium-Free Surface Preparation Development | REACH-compliant bonding layers secure first-mover advantage as ECHA restrictions displace hexavalent chromium. |
| Renewable-Powered Thermal Spray Capacity | Closed-loop powder recovery and clean energy sourcing meet European airline sustainability procurement mandates. |
Methodological Framework
The analysis maps thermal barrier coating application, abradable coating refurbishment, wear-resistant coating deposition, and corrosion-resistant coating services, each validated through coating shop operations directors, airline technical procurement managers, OEM platform engineers, and military depot program officers. Primary interviews with FAA-approved plasma spray operators and NDT inspectors combined with secondary validation against SEC filings from diversified coatings conglomerates, EASA certification databases, and United States Air Force logistics procurement records. Bottom-up coating volume estimates triangulated against top-down aerospace production forecasts.
Consistency checks validated volume and value outputs against external benchmarks including customs data for ceramic powder imports, thermal spray equipment manufacturer order backlogs, and airline fleet expansion disclosures. The analytical framework models coating type, application channel, end-user procurement structure, and material composition across the projection horizon. CAGRs derived from segment-level growth drivers including high-bypass turbofan penetration rates, geared turbofan production schedules, and MRO infrastructure development timelines. Industry-specific forecast inputs incorporate FAA airworthiness directive issuance patterns and REACH chemical restriction phase-in schedules.
Forecasts assume regulatory continuity in FAA thermal management directives and ECHA REACH chemical restrictions; material policy shifts would require re-modeling of qualification timelines and surface preparation technology adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market