
 Aircraft Inspection Covers Market | 2026-2036
Aircraft Inspection Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Inspection Covers Market Analytics
Carbon-fiber-reinforced polymer is recalibrating traditional aluminum inspection cover economics through weight reduction and corrosion resistance. Parker Hannifin Corp. leverages its aerospace fluid systems expertise to extend cover sealing technologies across multiple platforms. Collins Aerospace anchors North American supply chains with integrated avionics-adjacent access panel systems. Liebherr Group specializes in landing gear-adjacent inspection covers for European and Asian OEM programs.
Aircraft inspection covers are removable protective panels fabricated from nylon, polyester, vinyl, or canvas, designed to shield access points for avionics bays, fuel systems, and structural joints from environmental contamination and foreign object debris. Commercial aviation application leads segment value as scheduled maintenance intervals drive recurring replacement cycles, while military aviation represents the fastest-growing application amid defense fleet modernization programs. Hard covers dominate material-based revenue due to durability requirements in high-cycle operations, though soft covers gain traction in line maintenance for their reduced stowage footprint and faster deployment.
FAA airworthiness directives and EASA certification standards mandate traceable material specifications and fire-resistance ratings for all inspection cover installations on certified aircraft. The EU Green Deal's sustainable aviation fuel transition indirectly pressures cover manufacturers to reduce halogenated compounds in vinyl formulations. Stakeholders must monitor evolving MRO digitization requirements where RFID-embedded covers may become prerequisite for automated fleet tracking systems.
Market Dynamics
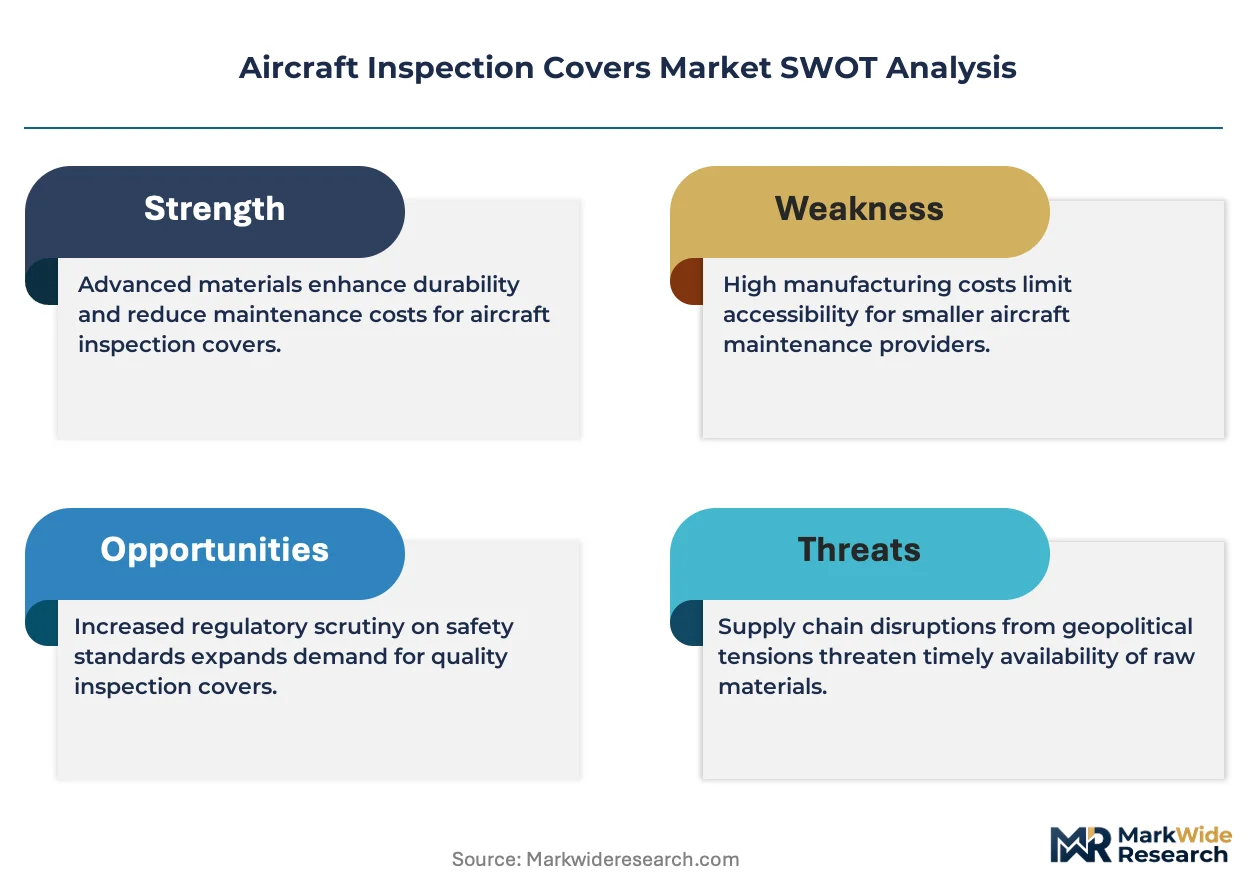
Fleet aging across North American commercial aviation is intensifying scheduled maintenance frequency, while FAA airworthiness directives mandate traceable inspection cover replacements that compress replacement cycles and elevate compliance documentation burdens for MRO providers.
Growth Catalysts
- FAA Directive Enforcement:Tightened inspection protocols for aging aircraft structures mandate more frequent cover replacements, creating recurring demand from major US carriers operating legacy fleets.
- Carbon-Fiber Material Transition:Weight reduction targets in next-generation aircraft programs accelerate substitution of traditional aluminum covers with corrosion-resistant composite alternatives.
- Defense Fleet Modernization:Military aviation procurement budgets prioritize platform upgrades requiring specialized hard covers for high-cycle operational environments.
Market Restraints
- Specialized Polymer Input Costs:Halogen-free vinyl formulations face feedstock volatility as EU Green Deal restrictions on chlorinated compounds constrain supplier flexibility.
- Regional Supply Concentration:North American MRO networks dominate certified installation capacity, limiting aftermarket access for smaller operators in secondary markets.
- Fire-Resistance Certification Friction:EASA flame-retardant testing protocols extend approval timelines for new material entrants seeking dual-certification status.
Strategic Opportunities
- RFID-Enabled Fleet Tracking:Automated MRO digitization requirements create white space for embedded sensor covers that integrate with airline inventory management systems.
- Sustainable Aviation Fuel Transition:EU regulatory pressure on halogenated compounds rewards early movers developing bio-based polymer formulations compliant with emerging environmental standards.
- Line Maintenance Soft Cover Adoption:Reduced stowage footprint requirements at hub airports drive demand for rapid-deployment fabric alternatives in high-frequency turnaround operations.
Industry Challenges
- Certified Technician Scarcity:FAA-approved repair station staffing constraints delay cover installation throughput during peak maintenance windows.
- Legacy Platform Documentation Gaps:Aging aircraft service manuals lack standardized cover specifications, forcing MROs to reverse-engineer fitments for obsolete part numbers.
- Multi-OEM Integration Complexity:Avionics-adjacent access panels must interface with proprietary connector systems from disparate manufacturers, complicating universal replacement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Inspection Covers Market |
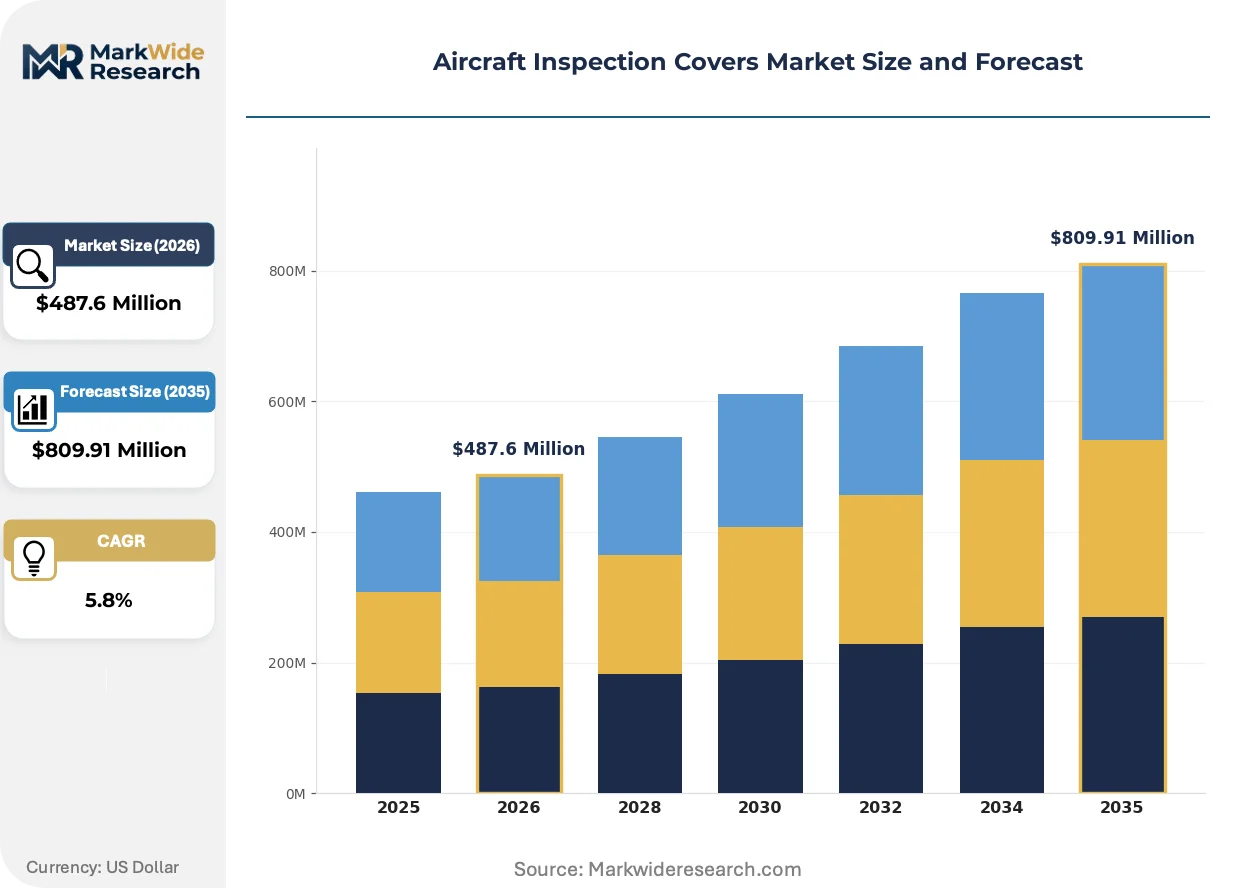
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Covers, Hard Covers, Customized Covers, Utility Covers Material: Nylon, Polyester, Vinyl, Canvas Application: Commercial Aviation, Military Aviation, Private Aviation, Cargo Aviation End User: Airlines, MRO Providers, Aircraft Manufacturers, Government Agencies |
| Companies Covered | The Wag Aero Group, Univair Aircraft Corporation, Parker Hannifin Corp., Collins Aerospace, Ametek, Inc., Liebherr Group, Mood Inc., Skytronics Inc., Embraer S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Inspection Covers Market Evolving Landscape
Material science breakthroughs and regulatory digitization mandates are converging to transform inspection cover functionality from passive protection to active fleet management infrastructure.
Carbon-fiber-reinforced polymer is electrifying traditional cover economics through substantial weight reduction and elimination of galvanic corrosion in structural joint applications. Regional carriers adopting these composites for narrow-body retrofits report reduced fuel burn penalties from access panel drag. The technology is electrifying competitive positioning among tier-one suppliers capable of certifying integrated sealing systems across multiple airframe platforms.
EU Green Deal sustainable aviation fuel transition requirements are indirectly reshaping vinyl formulation chemistry through restrictions on halogenated fire-retardant additives. Cover manufacturers reformulating polymer compounds face extended ECHA substance authorization timelines. European OEM programs represent the most affected segment, with procurement specifications now prioritizing REACH-compliant material declarations.
Airline procurement departments are consolidating inspection cover purchasing through integrated MRO service agreements rather than discrete component orders. This behavioral shift compresses supplier margins while rewarding vendors with captive repair station networks. The pattern is most visible among US legacy carriers restructuring aftermarket spend under unified fleet management contracts.
Aircraft Inspection Covers Market Segmentation
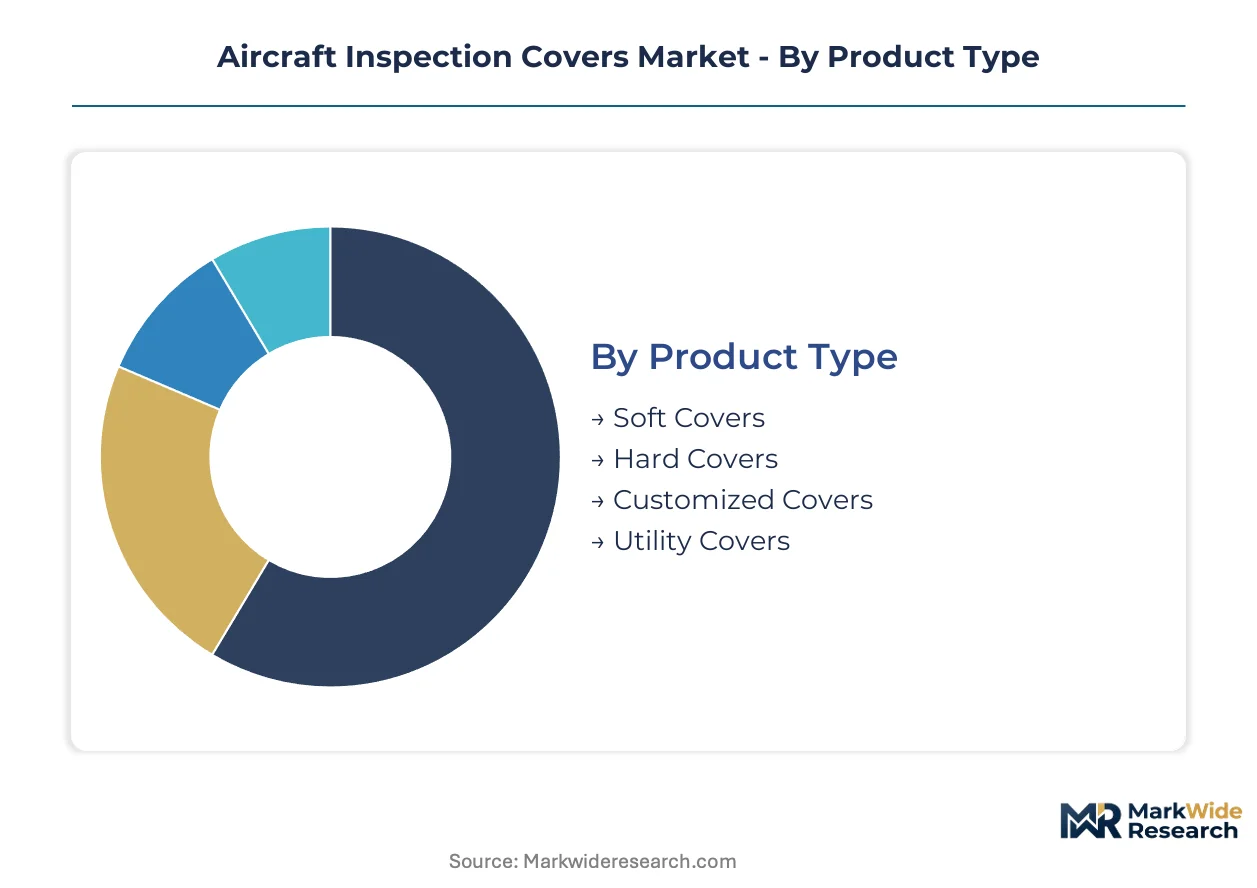
Aircraft inspection cover procurement varies sharply by operational context. Airlines prioritize rapid-deployment formats for line maintenance, while OEMs specify integrated hard covers for factory installation. Material selection and end-user workflows create distinct margin profiles across each segment boundary.
Product Type:
Integration depth separates standalone removable panels from embedded structural assemblies. Soft covers deploy as independent accessories without airframe modification; hard covers often ship pre-integrated with sealing systems.
- Soft Covers:Fabric-based panels constructed from nylon, polyester, or canvas weaves deploy without tools for temporary access protection. Demand clusters at hub airports in the United States where Delta Air Lines and United Airlines operate high-frequency turnaround schedules requiring minimal stowage footprint.
- Hard Covers:Rigid aluminum or carbon-fiber-reinforced polymer panels provide permanent structural closure with integrated gaskets and latch mechanisms. Boeing and Airbus specify these for fuel system and avionics bay access on new narrow-body programs where FAA airworthiness directives mandate corrosion-resistant sealing.
- Customized Covers:Tailored dimensions accommodate non-standard access apertures on aging regional turboprops and legacy military platforms.
- Utility Covers:General-purpose designs serve ground equipment and non-certified aircraft applications with reduced documentation requirements.
Volume placements concentrate in Hard Covers; the faster expansion belongs to Soft Covers.
Material:
Cost tier stratification mirrors performance requirements and regulatory compliance burden. Premium synthetics command higher unit economics where fire-resistance certification is mandatory; commodity fabrics serve price-sensitive utility applications.
- Nylon:High tensile strength and abrasion resistance make this polymer standard for soft cover applications in high-cycle commercial environments. Military aviation procurement in the United States specifies military-grade nylon weaves for tactical aircraft ground support equipment subject to harsh field conditions.
- Vinyl:Halogenated formulations face EU Green Deal restrictions; reformulated REACH-compliant compounds extend approval timelines but unlock European OEM contracts.
- Polyester:UV-stable synthetic dominates outdoor storage applications where prolonged sun exposure degrades alternative polymers.
- Canvas:Natural fiber blend retains niche demand for vintage aircraft restoration and heritage fleet operators prioritizing period-authentic materials.
Procurement weight tilts toward Nylon in commercial channels; Vinyl encounters regulatory headwinds in European markets.
Application:
Customer type and mission profile dictate replacement frequency and specification rigor. Scheduled airline operations generate recurring demand; defense programs emphasize durability over cost minimization.
- Commercial Aviation:Scheduled maintenance intervals at FAA-approved repair stations drive recurring replacement cycles for soft and hard covers across narrow-body and wide-body fleets. United States-based legacy carriers account for dominant procurement volumes as fleet aging intensifies inspection frequency.
- Military Aviation:High-cycle operational tempos and expeditionary deployment conditions require reinforced hard covers with enhanced impact resistance. Pentagon modernization programs for fighter and mobility aircraft represent the steepest expansion trajectory as platform upgrades accelerate.
- Private Aviation:Owner-operated aircraft generate sporadic demand through discretionary maintenance schedules and hangar storage protection needs.
- Cargo Aviation:Dedicated freighter operators prioritize rapid-access soft covers for main deck cargo door surrounds where turnaround speed dominates economics.
Revenue concentration sits with Commercial Aviation; Military Aviation climbs the fastest.
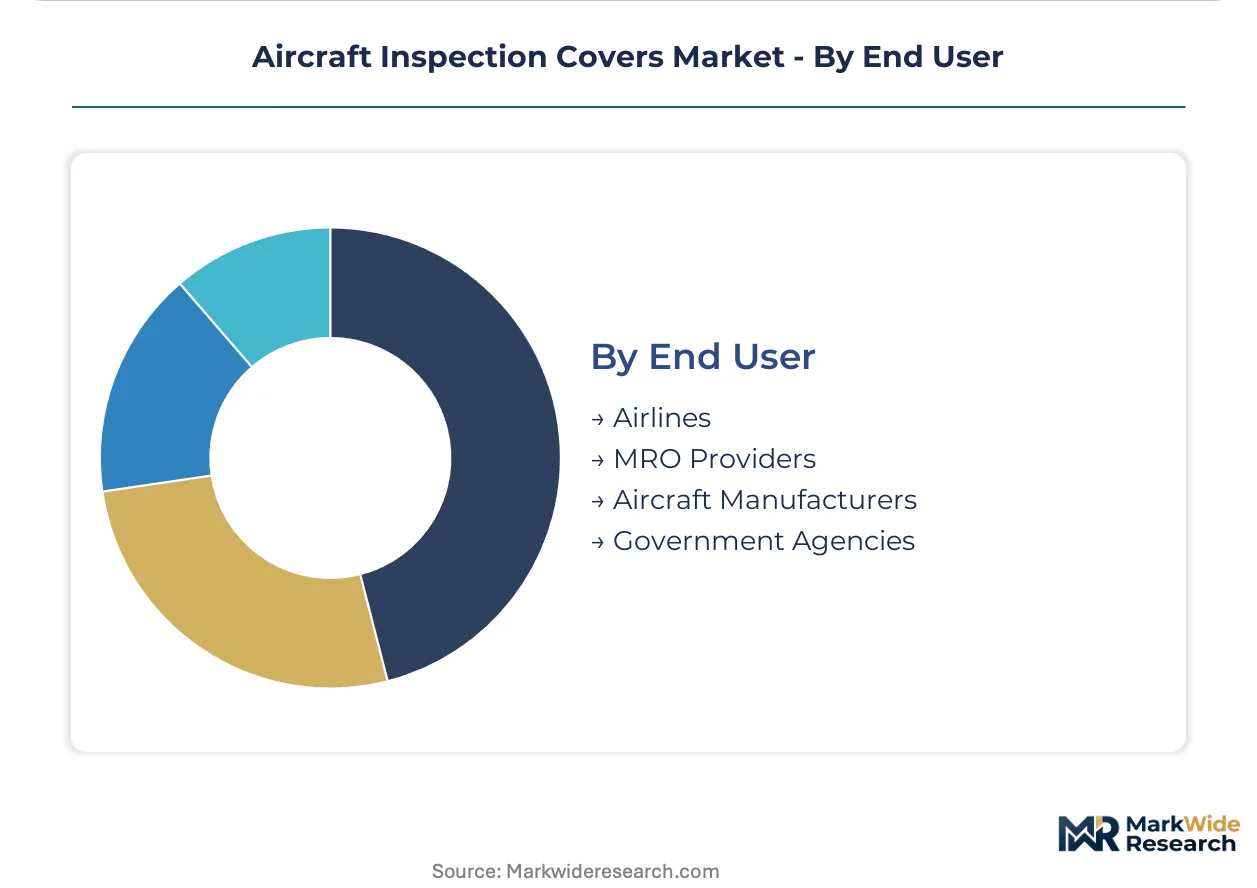
End User:
Supply chain proximity and technical certification requirements fragment purchasing authority. Captive MRO networks consolidate volumes; independent operators face procurement friction.
- Airlines:Fleet management departments negotiate integrated service agreements bundling inspection covers with heavy maintenance contracts. American Airlines and Southwest Airlines have shifted procurement to unified MRO partners, compressing discrete component margins.
- MRO Providers:FAA-certified repair stations in the United States stock standardized cover inventories to minimize AOG delays; staffing constraints limit installation throughput during peak maintenance windows.
- Aircraft Manufacturers:Boeing and Airbus specify inspection covers at airframe design phase, locking in multi-year supply agreements with tier-one aerostructures suppliers.
- Government Agencies:Defense departments and national aviation authorities procure through formal tender processes with extended qualification timelines and domestic content preferences.
Procurement authority is migrating toward MRO Providers; Government Agencies impose the longest sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers generate dominant procurement volumes through fleet protection programs and FAA-mandated replacement cycles. Regulatory tightening across multiple jurisdictions reshapes material specifications and compliance documentation requirements.
United States
Legacy carriers operate the world's largest commercial fleets, intensifying scheduled maintenance frequency for aging narrow-body and wide-body aircraft. FAA airworthiness directives mandate traceable inspection cover replacements with compressed documentation cycles. Dallas-Fort Worth and Atlanta anchor major MRO networks where Delta Air Lines and American Airlines consolidate aftermarket procurement.
Germany
European OEM supply chains demand REACH-compliant polymer formulations as EU Green Deal restrictions constrain halogenated vinyl feedstocks. ECHA substance authorization timelines extend approval windows for reformulated compounds. Hamburg and Munich host tier-one aerostructures suppliers integrating inspection covers into factory installation workflows.
China
Domestic aviation expansion drives demand for corrosion-resistant hard covers on indigenous narrow-body programs. MIIT certification standards align with international flame-retardant protocols while prioritizing local supply chain content. Shanghai and Xian concentrate COMAC-related manufacturing clusters where state-directed procurement favors domestic fabricators.
United Kingdom
Defense fleet modernization programs prioritize reinforced hard covers for high-cycle tactical aircraft operations. Ministry of Defence tender processes impose extended qualification timelines with domestic content preferences. Bristol and Broughton sustain aerospace manufacturing heritage through military aviation subcontracting networks.
France
Airbus supply chain integration locks in multi-year agreements for avionics-adjacent access panel systems. ANSM oversight of aerospace materials ensures alignment with EASA fire-resistance certification standards. Toulouse and Nantes anchor European aerostructures production where tier-one suppliers certify integrated sealing technologies.
Aircraft Inspection Covers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one aerostructures suppliers capturing OEM specification authority while independent fabricators serve aftermarket replacement demand. The vendor base concentrates around multi-platform certification capabilities and captive MRO network access. Three archetypes dominate: integrated aerospace conglomerates with fluid systems expertise, specialized landing gear-adjacent component suppliers, and regional maintenance-focused fabricators. Competitive positioning hardens through strategic partnerships with airline fleet management departments and backward integration into polymer formulation chemistry.
Among US-based diversified industrials, Parker Hannifin Corp. and Collins Aerospace occupy positions spanning fluid systems and avionics-adjacent access technologies. Liebherr Group exemplifies the European specialist archetype with concentrated expertise in landing gear-proximate applications. These three anchors represent distinct competitive vectors: systems integration breadth, platform certification depth, and sub-system specialization.
| Leading Market Players |
|---|
| The Wag Aero Group |
| Univair Aircraft Corporation |
| Parker Hannifin Corp. |
| Collins Aerospace |
| Ametek, Inc. |
| Liebherr Group |
| Mood Inc. |
| Skytronics Inc. |
| Embraer S.A. |
| Others |
Value Network & Pricing Analysis
Captive MRO network integration anchors pricing power for tier-one suppliers serving FAA-certified repair stations, compressing margins for independent fabricators lacking direct airline fleet management contracts while elevating compliance documentation costs across the value chain.
Pricing Analysis
Volume placements concentrate in hard covers with integrated sealing systems, while margin expansion belongs to soft covers deployed in rapid-turnaround line maintenance. Pricing stratifies across FAA-certified, EASA-compliant, and utility-grade tiers, with certification level commanding the steepest premium. Cost compression in soft cover segments is intensifying because airline procurement departments consolidate purchasing through bundled MRO service agreements. Cargo operators and regional carriers exhibit the highest price sensitivity; defense departments and Airbus supply chain partners demonstrate the least.
Supply Chain Analysis
Certified technician availability constraints in the United States, Germany, and France govern production throughput for precision-machined hard cover assemblies. Supply chains draw from carbon-fiber pre-preg suppliers, halogen-free vinyl compounders, and military-grade nylon weavers. Single-source vulnerability concentrates in REACH-compliant polymer formulations where ECHA authorization timelines extend qualification windows. Distribution runs through captive MRO networks and tier-one aerostructures suppliers rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FAA airworthiness directive documentation requirements create a barrier-to-entry moat for incumbent suppliers with established repair station networks.
For Market Incumbents: Anchor market position through backward integration into halogen-free polymer formulation chemistry, securing feedstock independence as EU Green Deal restrictions constrain supplier flexibility. Expand captive MRO installation capacity in Dallas-Fort Worth and Atlanta to capture Delta Air Lines and American Airlines fleet management contract consolidation. Carbon-fiber composite substitution technology represents the primary substitution threat requiring R&D defense. For New Entrants and Emerging Players: Enter via RFID-embedded cover development for automated fleet tracking systems, exploiting white space created by MRO digitization mandates. Target cargo aviation soft cover procurement where rapid-access main deck door surrounds face less stringent certification friction than avionics-adjacent applications. Pursue direct partnerships with COMAC supply chains in Shanghai and Xian to bypass entrenched Boeing-Airbus tier-one networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified aerospace conglomerates seeking fluid systems or aerostructures adjacencies. Long-term viability hinges on REACH-compliant material capabilities and multi-platform certification breadth. Watch for inflection in EASA flame-retardant testing protocol harmonization with FAA standards, which would compress approval timelines for reformulated compounds and reward early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Chemistry | REACH-compliant formulation capabilities unlock European OEM contracts constrained by ECHA authorization timelines. |
| RFID-Enabled Fleet Tracking Development | Automated MRO digitization requirements at Delta and United create embedded sensor cover demand. |
| Carbon-Fiber Composite Certification Investment | Weight reduction targets in Boeing and Airbus narrow-body programs accelerate aluminum substitution. |
| Captive MRO Network Expansion | Direct repair station access captures airline procurement consolidation under unified fleet management contracts. |
| COMAC Supply Chain Partnership | MIIT certification alignment with international protocols opens indigenous Chinese narrow-body programs. |
Research Methodology
Independent corroboration across MRO procurement directors, FAA-certified repair station managers, and tier-one aerostructures engineers underwrites the qualitative findings. Primary fieldwork engaged airline fleet management executives, polymer formulation chemists, and defense procurement officers alongside secondary validation through FAA airworthiness directive databases, EASA certification registries, and SEC filings from Parker Hannifin and Collins Aerospace parent entities. Bottom-up segment sizing triangulates against top-down fleet projection models.
Rate-of-change decomposition separates fleet aging velocity, regulatory tightening intensity, and material substitution pace across the analysis window. Segmentation dimensions model product type, material chemistry, application mission profile, and end-user procurement authority. CAGRs derive from fitted growth curves applied to base-year market estimates, with carbon-fiber adoption rates and defense modernization budget trajectories serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EASA-FAA regulatory harmonization delays or sustained halogenated compound feedstock volatility. Forecasts reflect documented assumptions on fleet retirement schedules and MRO digitization adoption curves. Material deviation in EU Green Deal enforcement intensity or COMAC production ramp warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
US Business Jet Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Firefighting Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Military Trainer Aircraft Market
Aircraft
Europe General Aviation Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Global Aircraft Transparencies Market