
 Piston Engine Aircraft Market | 2026-2036
Piston Engine Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Piston Engine Aircraft Market Intelligence
Direct-to-consumer sales channels for factory-new piston singles is narrowing as fractional ownership platforms and leaseback arrangements with flight schools capture an expanding share of annual deliveries. Textron Aviation leverages its Cessna brand heritage and global service network to sustain fleet loyalty among institutional buyers. Diamond Aircraft differentiates through diesel piston and hybrid-electric propulsion investments that reduce avgas dependency. Lycoming Engines dominates the aftermarket overhaul segment with its factory-certified engine remanufacturing program.
A piston engine aircraft is a fixed-wing aircraft propelled by one or more reciprocating internal combustion engines, typically operating on 100LL avgas or Jet-A diesel alternatives, with power outputs ranging from 100 to 400 horsepower and service ceilings between 12,000 and 25,000 feet depending on aspiration type. These aircraft serve commercial purposes spanning flight training, personal transportation, agricultural spraying, and aerial survey work where operating economics below turbine thresholds remain critical. Light aircraft and trainer aircraft represent the volume core, with trainer configurations commanding durable replacement cycles tied to FAA Part 141 school accreditation requirements. Turbocharged engine technology captures margin premiums in mountain-crossing and high-density-altitude operations, while hybrid systems remain developmental but attract R&D allocation from manufacturers positioning for future emissions standards.
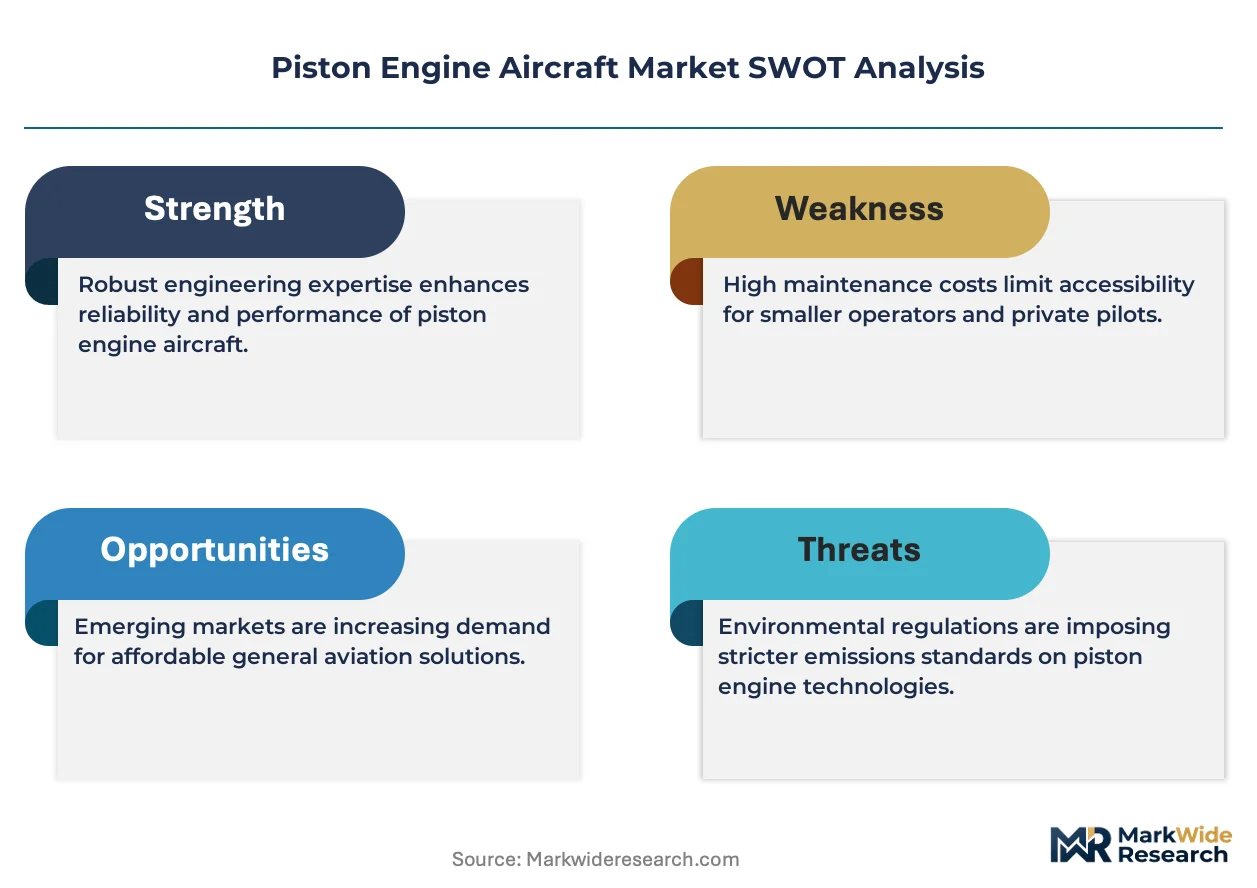
FAA airworthiness directives and EASA CS-23 certification standards govern airframe and powerplant compliance, with EPA leaded-fuel regulations now pressuring fleet transitions toward unleaded or diesel alternatives. The FAA's ongoing 100LL replacement initiative and EASA's environmental certification amendments are reshaping powerplant investment priorities across OEMs and engine houses. Stakeholders must monitor unleaded fuel certification timelines and hybrid propulsion maturity curves to align fleet renewal decisions with regulatory compliance windows and total cost of ownership trajectories.
Market Dynamics
Turbocharged piston powerplants are compressing replacement cycles across high-altitude training fleets as flight schools confront tightening FAA Part 141 certification mandates and avgas supply uncertainty.
Growth Catalysts
- FAA Part 141 Accreditation Mandates:Flight schools in the United States face intensified fleet renewal requirements to maintain institutional certification, forcing durable hardware replacement schedules.
- Turbocharged Engine Technology:High-density-altitude training environments from Colorado to the Alps are mandating forced-induction powerplants for safe mountain-crossing instruction.
- Avgas-to-Diesel Transition:EPA leaded-fuel regulations are accelerating powerplant diversification toward Jet-A diesel alternatives in European and North American training markets.
Market Restraints
- 100LL Avgas Supply Concentration:Refinery capacity for aviation gasoline concentrates among a handful of North American and European suppliers, exposing flight schools to input cost volatility and distribution bottlenecks.
- Engine House Oligopoly:Factory-certified overhaul capacity for Lycoming and Continental powerplants clusters in the United States and Austria, creating multi-month turnaround delays during peak training seasons.
- Airframe Certification Friction:EASA CS-23 and FAA Part 23 certification timelines for new piston designs extend development cycles, deterring clean-sheet investment in favor of derivative airframes.
Strategic Opportunities
- Indian General Aviation Liberalization:DGFT regulatory easing and the Ministry of Civil Aviation's regional connectivity schemes are opening flight training infrastructure investment in Maharashtra and Karnataka.
- Hybrid-Electric Convergence:Battery-electric range extenders paired with conventional piston cores are attracting R&D allocation from airframers positioning for 2030s emissions standards.
- Fractional Ownership Platforms:Leaseback arrangements with Part 61 schools are capturing factory-new delivery share previously routed through individual owner-pilot purchases.
Industry Challenges
- Airframe-Mechanic Certification Gap:FAA A&P mechanic pipelines are failing to match retirement outflows from the postwar general aviation workforce, extending maintenance turnaround times at busy flight schools.
- Unleaded Fuel Fleet Retrofit Complexity:STC approval timelines for 100LL replacement fuels are compressing operational windows for schools with mixed fleets of legacy and modern powerplants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piston Engine Aircraft Market |
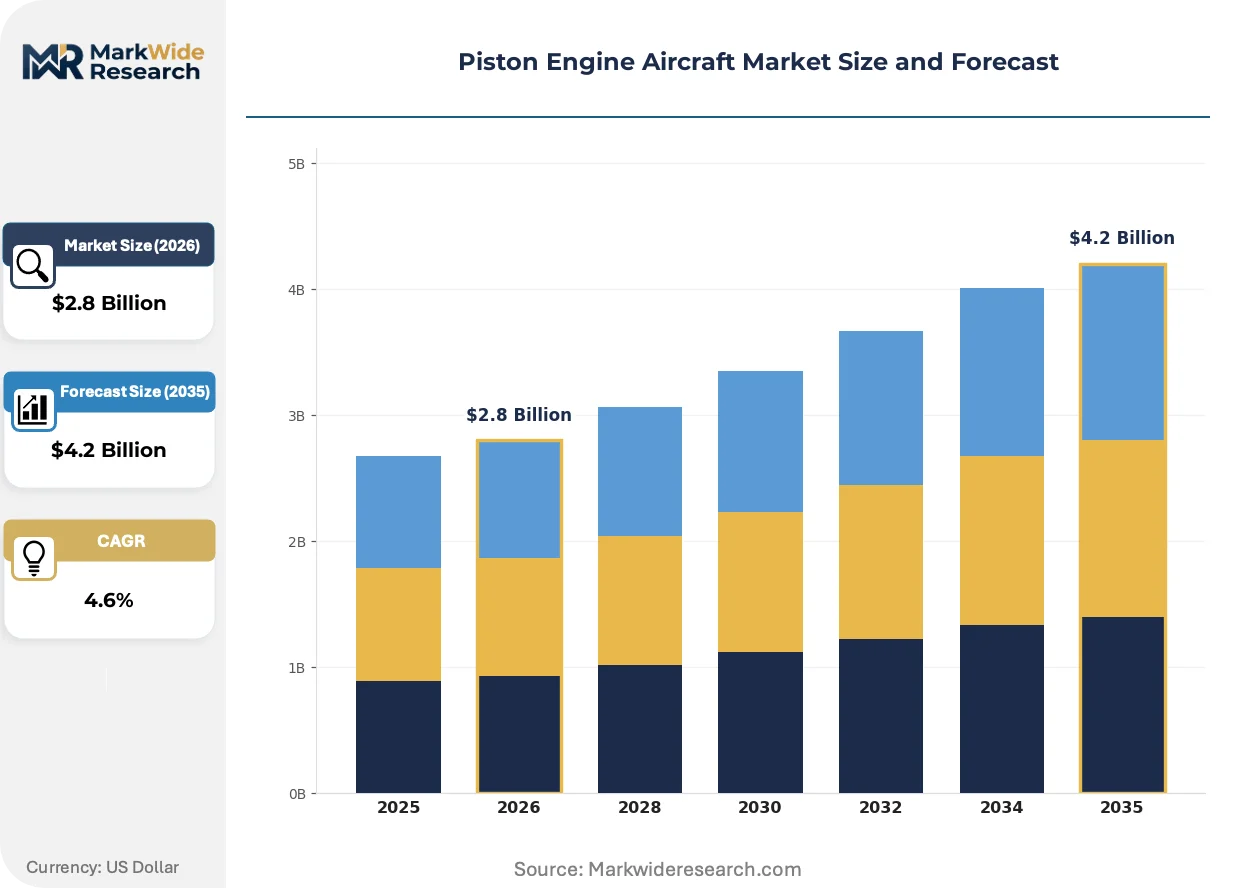
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Aircraft, Trainer Aircraft, Business Aircraft, Experimental Aircraft End User: Private Operators, Flight Schools, Military, Commercial Services Application: Recreational Flying, Flight Training, Aerial Photography, Agricultural Aviation Technology: Conventional Piston, Turbocharged Engine, Fuel Injection, Hybrid Systems |
| Companies Covered | Diamond Aircraft, Tecnam, Textron Aviation, Continental Aerospace Technologies, Flight Design, Piper Aircraft, American Champion Aircraft, Lycoming Engines, Cirrus Aircraft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piston Engine Aircraft Market Strategic Shifts & Innovations
Diesel piston propulsion and digital engine monitoring are rewriting operating economics for training fleets while regulatory pressure on leaded aviation fuels accelerates powerplant portfolio diversification.
Compression-ignition piston engines running Jet-A are rendering obsolete naturally aspirated avgas powerplants in high-utilization training environments. Flight schools in Germany, the United Kingdom, and the United States are adopting Austro Engine and Continental CD-200 series powerplants to eliminate leaded fuel dependency and reduce per-hour operating costs. The technology is rendering obsolete the century-old reliance on 100LL avgas infrastructure while compressing total cost of ownership calculations for institutional buyers.
EPA's ongoing 100LL replacement initiative is forcing engine houses and airframers to certify powerplants for unleaded alternatives ahead of anticipated supply phaseouts. The regulatory pressure is redirecting R&D budgets toward fuel-flexible combustion architectures and hybrid-electric backup systems. High-utilization training fleets in the United States are bearing the earliest compliance costs as STC availability determines retrofit feasibility.
Leaseback arrangements with flight schools are displacing direct-to-consumer retail as the dominant channel for factory-new piston singles. Institutional buyers with fleet standardization requirements and guaranteed utilization hours are capturing volume discounts unavailable to individual owner-pilots. The channel shift is most visible across the United States, where Part 141 networks in Florida, Arizona, and Texas are consolidating annual delivery volumes through multi-airframe procurement contracts.
Piston Engine Aircraft Market Segmentation
Piston engine aircraft segmentation reveals divergent aftermarket intensity across configurations. Flight schools and commercial operators generate predictable overhaul demand, while private owners stretch maintenance intervals. Technology choices increasingly determine lifetime service revenue per airframe.
Product Type:
After-sales-service intensity varies dramatically by airframe mission profile and annual flight hour accumulation.
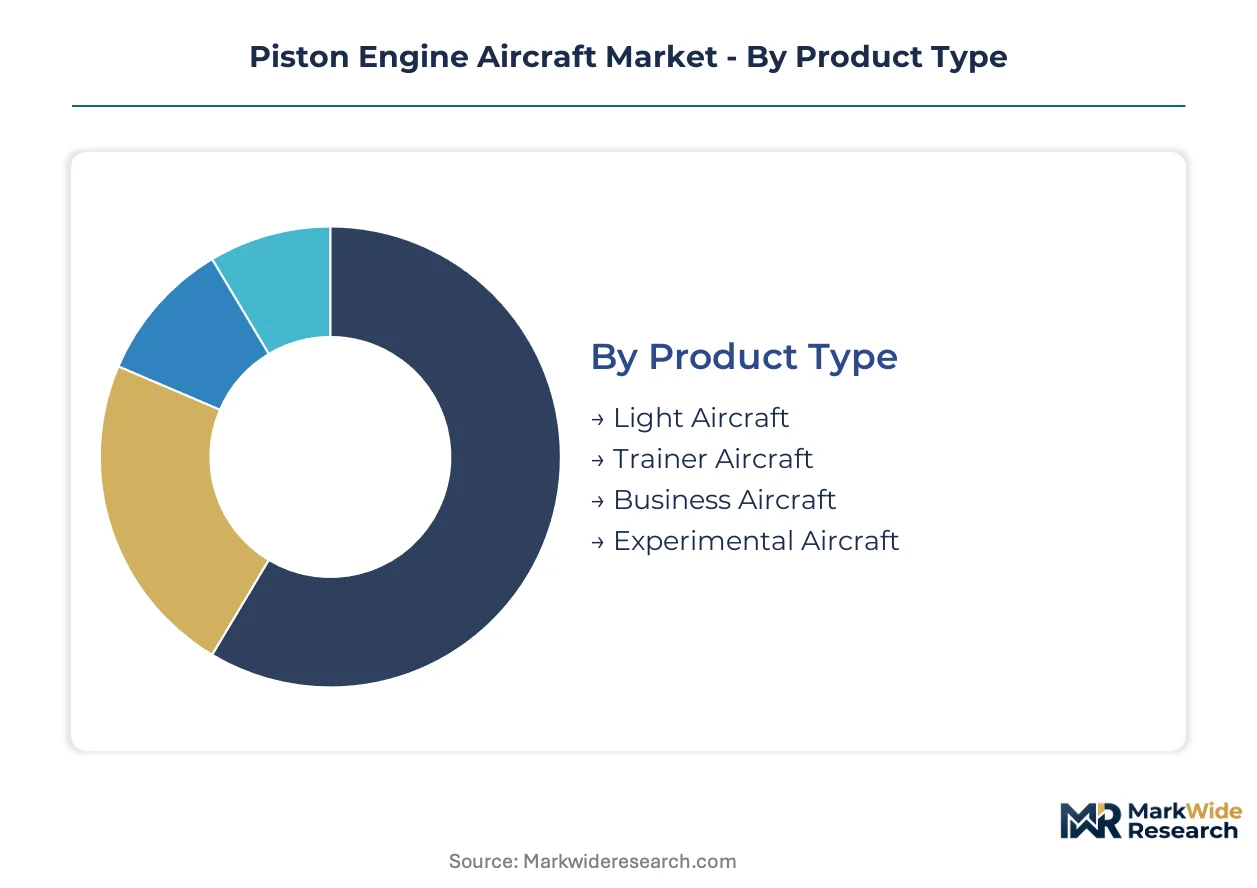
- Trainer Aircraft:Purpose-built for high-cycle operations with reinforced landing gear and simplified systems to withstand student pilot abuse. Demand concentrates at FAA Part 141 schools in Florida, Arizona, and Texas where annual utilization exceeds 1,000 hours per airframe and engine TBO compression drives factory-remanufactured powerplant demand.
- Light Aircraft:Single-engine piston configurations optimized for personal transportation and primary flight instruction with power outputs between 100 and 200 horsepower. Private owners in the United States sustain the installed base through owner-assisted maintenance, though leaseback arrangements with Part 61 schools are capturing an expanding share of new deliveries.
- Business Aircraft:High-performance piston twins and pressurized singles serving owner-operators and air taxi services requiring IFR capability and cabin comfort.
- Experimental Aircraft:Amateur-built and kit-plane configurations where powerplant selection flexibility and owner maintenance privileges reduce factory service capture.
Trainer Aircraft holds the largest share; momentum sits with Light Aircraft as leaseback channel expansion blurs traditional ownership boundaries.
End User:
Procurement authority and utilization patterns create distinct equipment specifications and replacement cadences across buyer categories.
- Flight Schools:Institutional buyers with fleet standardization requirements, guaranteed utilization hours, and volume procurement leverage. FAA Part 141 accreditation mandates in the United States compress replacement cycles as schools confront tightening certification standards and avgas supply uncertainty.
- Private Operators:Individual owner-pilots with low annual flight hours and extended ownership horizons. Direct-to-consumer retail channels are narrowing as fractional ownership platforms capture factory-new delivery share previously routed through this segment.
- Military:Defense forces utilizing piston trainers for primary flight screening and initial pilot qualification before jet transition.
- Commercial Services:Aerial survey, pipeline patrol, and banner tow operators with high-utilization requirements and compressed capital recovery timelines.
Flight Schools command the dominant procurement volume; Private Operators are expanding most quickly through leaseback participation.
Application:
Mission requirements dictate powerplant specification, avionics fit, and regulatory compliance burden across operational categories.
- Flight Training:Structured instruction environments requiring durable airframes and predictable operating economics. Turbocharged engine technology is displacing conventional naturally aspirated configurations in high-altitude training environments from Colorado to the Alps.
- Recreational Flying:Personal aviation for pleasure and transportation where acquisition cost sensitivity and fuel availability dominate equipment selection.
- Agricultural Aviation:Crop dusting and aerial application requiring specialized chemical handling systems and low-altitude maneuverability.
- Aerial Photography:Survey and imaging missions demanding stable platforms and precise flight path control.
Flight Training represents the foundational demand base; Agricultural Aviation shows the steepest expansion trajectory as precision agriculture adoption accelerates.
Technology:
Powerplant architecture determines fuel flexibility, altitude capability, and compliance positioning against evolving emissions standards.
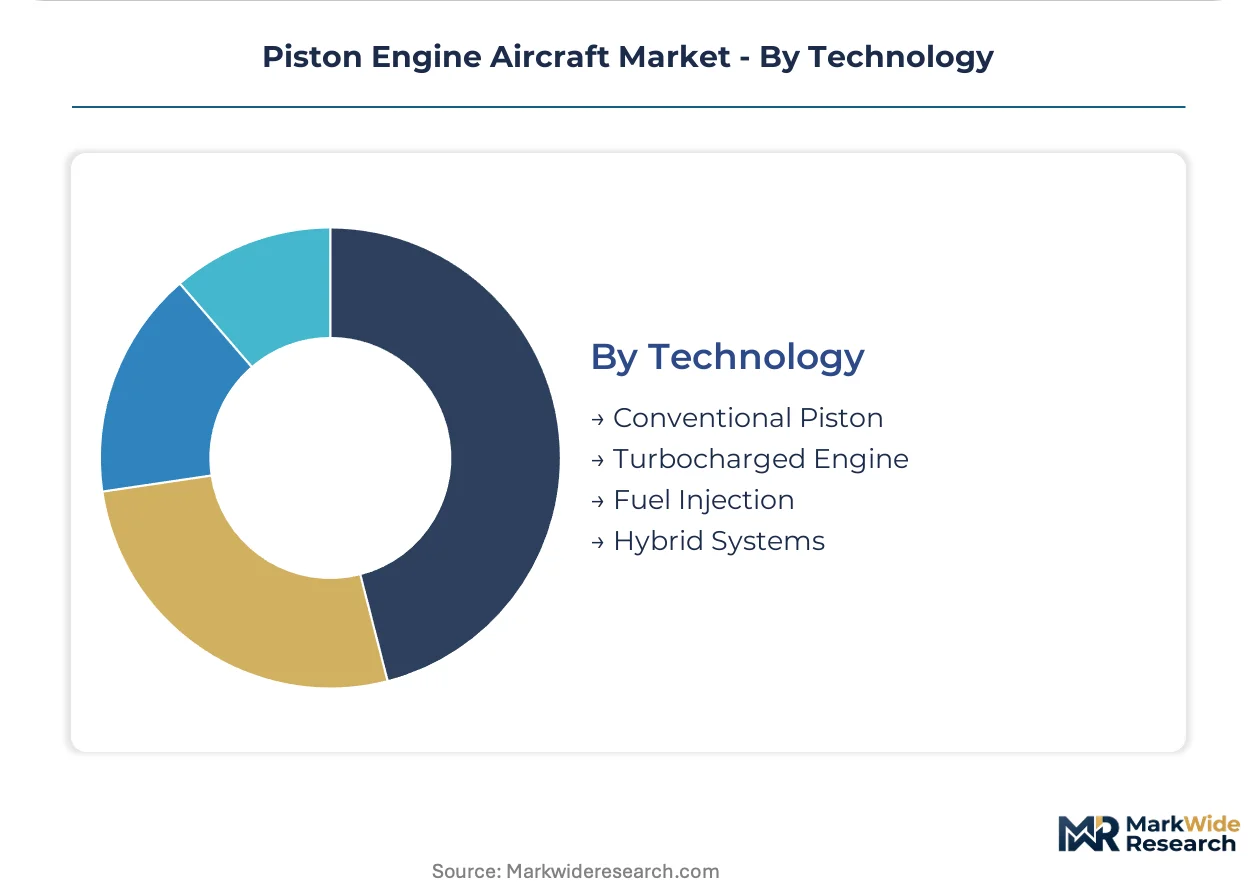
- Turbocharged Engine:Forced-induction systems enabling sea-level power output at density altitudes exceeding 12,000 feet. Flight schools in mountain-crossing training environments mandate this technology for safe instruction, capturing margin premiums over naturally aspirated alternatives.
- Conventional Piston:Naturally aspirated powerplants operating on 100LL avgas with established maintenance infrastructure and lowest acquisition cost.
- Fuel Injection:Precision fuel delivery systems improving altitude performance and reducing lead fouling in high-utilization operations.
- Hybrid Systems:Battery-electric range extenders paired with conventional piston cores attracting R&D allocation from manufacturers positioning for future emissions standards.
Conventional Piston retains the installed base majority; Hybrid Systems are gaining share fastest as regulatory pressure on leaded aviation fuels intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification mandates and avgas supply pressures anchor United States demand, while EASA environmental standards reshape European fleet renewal patterns. Training infrastructure investments concentrate in jurisdictions with liberalized airspace and institutional procurement capacity.
United States
Part 141 flight school networks in Florida, Arizona, and Texas drive trainer aircraft procurement through multi-airframe contracts. FAA airworthiness directives compress engine TBO cycles, accelerating factory-remanufactured powerplant demand. The Mountain West training corridor from Colorado to Utah mandates turbocharged configurations for high-density-altitude instruction.
Germany
Commercial pilot training academies in Bavaria and North Rhine-Westphalia adopt Jet-A diesel powerplants to eliminate leaded fuel dependency. EASA CS-23 certification amendments pressure fleet standardization toward emissions-compliant architectures. The Stuttgart industrial cluster hosts engine houses specializing in compression-ignition retrofit programs.
United Kingdom
Flight schools in Oxfordshire and Hampshire confront avgas distribution bottlenecks through diesel transition strategies. The Civil Aviation Authority's environmental certification guidance accelerates powerplant diversification timelines. Cambridge-area training providers pioneer hybrid-electric evaluation programs for future fleet positioning.
India
DGFT regulatory easing and Ministry of Civil Aviation regional connectivity schemes unlock flight training infrastructure in Maharashtra and Karnataka. BIS certification harmonization with FAA standards enables imported trainer aircraft deployment. The Bangalore aeronautical cluster attracts maintenance, repair, and overhaul investment for piston fleet support.
Canada
Transport Canada pilot licensing requirements sustain training fleet utilization across Ontario and British Columbia flight schools. Prairie province agricultural aviation operators demand ruggedized piston configurations for crop application missions. The Calgary-Edmonton corridor concentrates aftermarket engine overhaul demand from high-utilization commercial operators.
Piston Engine Aircraft Market Key Industry Players
Integrated airframe-engine manufacturers and specialized propulsion houses split the market along vertical scope lines. Consolidation concentrates among North American and European OEMs with certified service networks. Three archetypes dominate: legacy brand holders with institutional fleet loyalty, diesel technology specialists, and hybrid-electric R&D investors. Competitive moves center on leaseback channel capture and powerplant certification acceleration for unleaded fuel transitions.
Among legacy airframe manufacturers, Textron Aviation and Diamond Aircraft exemplify divergent technology strategies within the institutional buyer segment. Lycoming Engines anchors the aftermarket overhaul tier through factory-certified remanufacturing programs. Tecnam occupies a position within the light-sport and trainer specialization tier serving European training markets.
| Leading Market Players |
|---|
| Diamond Aircraft |
| Tecnam |
| Textron Aviation |
| Continental Aerospace Technologies |
| Flight Design |
| Piper Aircraft |
| American Champion Aircraft |
| Lycoming Engines |
| Cirrus Aircraft |
| Others |
Cost & Logistics Intelligence
Lycoming and Continental factory-certified overhaul capacity concentrates in the United States and Austria, anchoring margin capture in the aftermarket service tier while flight schools absorb premium pricing during peak training seasons. This geographic concentration of engine house oligopoly power compresses buyer leverage and extends turnaround timelines for institutional fleets.
Pricing Analysis
North American flight schools pay fifteen to twenty percent premiums over European counterparts for equivalent trainer aircraft configurations due to FAA Part 141 accreditation mandates and guaranteed utilization contracting. Three-tier pricing structure across turbocharged premium, fuel-injected standard, and naturally aspirated economy levels segments institutional procurement from individual owner-pilot purchases. Pricing pressure stems from diesel powerplant certification investments as EPA leaded-fuel regulations advance. Flight schools exhibit highest price sensitivity due to fleet standardization requirements and compressed capital recovery timelines, while private operators in leaseback arrangements demonstrate lowest sensitivity through guaranteed hour contracts.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates supply chain risk for airframe components and engine subassemblies crossing the Atlantic. Manufacturing concentrates in the United States, Germany, and Austria for certified powerplants and complete aircraft. Raw material dependencies span aluminum airframe alloys, avionics semiconductor components, and specialty lubricants formulated for aviation applications. Single-source vulnerability clusters around Lycoming crankcase castings and Continental fuel injection systems. Distribution runs through factory-direct institutional sales teams and specialized aviation dealers serving owner-pilot segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractional ownership platforms and leaseback arrangements are transforming piston engine aircraft from asset ownership to flight-hour utility, creating interoperability requirements between school scheduling systems and manufacturer maintenance tracking that favor integrated ecosystem providers.
For Market Incumbents: Insulate factory-remanufactured engine revenue streams by accelerating unleaded fuel certification timelines ahead of EPA regulatory phaseouts. Secure exclusive leaseback channel partnerships with expanding Part 141 networks in Florida, Arizona, and Texas to lock in multi-airframe procurement contracts before diesel transition investments mature. Vertical integration into digital engine monitoring subscriptions captures recurring revenue from high-utilization training fleets. For New Entrants and Emerging Players: Mid-market flight schools in Maharashtra and Karnataka represent the most penetrable entry point as DGFT regulatory easing unlocks Indian general aviation infrastructure investment. Hybrid-electric propulsion development programs at Cambridge-area evaluation centers offer technology licensing pathways for airframers lacking in-house R&D scale. Target military primary flight screening contracts in defense forces transitioning from jet-ab-initio to piston-based initial qualification. For Investors and Strategic Acquirers: Capital is best deployed toward diesel powerplant specialists with Jet-A certification breadth and established European training fleet references. Long-term viability hinges on regulatory compliance positioning across unleaded fuel transition timelines and hybrid-electric maturity curves. Monitor FAA STC approval velocity for 100LL replacement fuels as the inflection signal determining retrofit market size and timing.| Strategic Initiative | Industry Significance |
|---|---|
| Unleaded Fuel Certification Acceleration | EPA regulatory pressure compresses operational windows for legacy avgas-dependent fleets. |
| Leaseback Channel Partnership Expansion | Part 141 networks in Florida and Arizona consolidate procurement through institutional contracts. |
| Diesel Powerplant Portfolio Diversification | Continental CD-200 and Austro Engine Jet-A alternatives eliminate leaded fuel dependency. |
| Hybrid-Electric R&D Allocation | Battery-electric range extenders position manufacturers for 2030s emissions standards. |
| Aftermarket Service Network Consolidation | Factory-certified overhaul capacity captures margin from high-utilization training fleet TBO compression. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flight school fleet managers, FAA Part 141 accreditation officers, airframe manufacturer sales directors, engine house overhaul program leads, and aviation fuel distribution specialists. Secondary validation drew from FAA airworthiness directive filings, EASA CS-23 certification databases, EPA regulatory dockets on leaded aviation fuel, customs trade records for aircraft and engine imports, and SEC filings from publicly traded aviation OEMs. Bottom-up triangulation across individual airframe delivery records and top-down reconciliation against aggregate fleet size estimates ensured methodological robustness.
Calibration against historical delivery trajectories and installed base retirement patterns informed projection modeling across the analysis window. Segmentation dimensions included product type, end user category, application mission, and powerplant technology architecture alongside geographic regulatory cluster differentiation. CAGRs were derived from regression analysis of annual delivery volumes against driver variables including flight school enrollment trends, regulatory mandate implementation schedules, and fuel infrastructure transition timelines. Industry-specific forecast inputs encompassed FAA A&P mechanic pipeline data and avgas refinery capacity utilization rates.
Practitioners should monitor EPA 100LL replacement initiative timelines, EASA environmental certification amendment implementation, and hybrid-electric propulsion maturity curves for early signals requiring forecast revision. Forecasts reflect assumptions regarding regulatory compliance windows, fleet renewal cycle compression, and channel shift velocity toward institutional procurement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aircraft Turbine Engine Market
Aircraft Engine Systems and Services
Narrow-Body Turbofan Engine Shop Visit Services Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market