
 Global Aircraft Engine Fuel Systems Market | 2026-2036
Global Aircraft Engine Fuel Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Engine Fuel Systems Market Foresight
The distinction between hydro-mechanical and full-authority digital electronic control tiers is collapsing as engine OEMs mandate integrated fuel metering for next-generation propulsion. Parker Hannifin Corporation leverages its fuel pump specialization to anchor aftermarket contracts across multiple airframe programs. Safran SA sustains a dominant position in fuel nozzle architectures through captive metallurgy capabilities. Eaton Corporation competes aggressively on electro-hydraulic control valve integration for military and commercial dual-use platforms.
Aircraft engine fuel systems encompass the pumps, metering units, control valves, and distribution manifolds that deliver precisely conditioned fuel to combustion chambers across varying altitude and throttle conditions; these assemblies operate at pressures exceeding 1,000 psi and temperatures ranging from minus 40 degrees Celsius to over 150 degrees Celsius to ensure flame stability and thermal efficiency. The commercial jetliner application segment leads absolute volume as Airbus and Boeing ramp narrowbody output, while electronic engine control technology captures the fastest expansion trajectory given its compatibility with open-fan and hybrid-electric propulsion roadmaps. Fuel control units retain the deepest margin pools due to firmware certification barriers and long-term sole-source agreements.
The FAA's Part 33 airworthiness standards and EASA's CS-E certification requirements dictate fuel system redundancy thresholds and fire resistance specifications that OEMs must embed at the design phase. China's CAAC and Japan's JCAB maintain aligned but independently administered type certification pathways that add compliance cost layers for suppliers seeking multi-jurisdiction approvals. Stakeholders must monitor how evolving sustainable aviation fuel compatibility standards reshape seal materials, elastomer specifications, and thermal management architectures across the supply base.
Market Dynamics
The transition from hydro-mechanical to full-authority digital electronic control (FADEC) architectures is compressing supplier tiers and forcing fuel system OEMs to absorb firmware development costs previously borne by engine manufacturers.
Growth Catalysts
- FAA NextGen Fuel Efficiency Mandates:The FAA's operational efficiency requirements are compelling airlines to retrofit legacy fleets with electronically controlled fuel metering systems that optimize thrust-specific fuel consumption across flight phases.
- Sustainable Aviation Fuel Compatibility Standards:ASTM D7566 and DEF STAN 91-091 revisions are mandating seal material upgrades that expand replacement part volumes for elastomer-intensive fuel system components.
- Narrowbody Production Ramp:Airbus A320neo and Boeing 737 MAX output rates in the United States, China, and Germany are pulling demand for integrated fuel control units at volumes exceeding widebody platforms by a factor of four.
Market Restraints
- Titanium and Superalloy Input Volatility:Fuel nozzle and pump housing production depends on aerospace-grade titanium sponge and nickel-based superalloys subject to Russian supply disruption and spot price swings exceeding 30 percent annually.
- Single-Source Firmware Dependencies:FADEC software certification locks engine OEMs into decade-long sole-source agreements with control system suppliers, blocking competitive entry regardless of hardware performance.
- Fire-Resistance Certification Burden:FAA Part 33.67 and EASA CS-E 510 thermal endurance testing adds 18-24 months to new fuel system qualification timelines, freezing design iterations until full certification cycles complete.
Strategic Opportunities
- India Civil Aviation Expansion:The Directorate General of Civil Aviation's projected fleet doubling by 2030 creates greenfield demand for fuel system MRO infrastructure absent legacy supplier entrenchment.
- Open-Fan Propulsion Architectures:CFM International's RISE program and Pratt & Whitney's GTF Advantage roadmap require distributed fuel injection systems that bypass conventional manifold geometries, opening design competitions for new entrants.
- EU Green Deal SAF Blending Mandates:The European Union's 70 percent sustainable aviation fuel blending target by 2050 is accelerating thermal management R&D budgets for fuel system OEMs capable of certifying aromatic-resistant seal packages.
Industry Challenges
- Embedded Software Talent Scarcity:DO-178C certification expertise for airborne software resides with a shrinking pool of engineers concentrated at five North American and European engineering centers, inflating compensation premiums.
- Legacy Platform Spare Part Sustaining:CFM56 and V2500 fleets require hydro-mechanical fuel control unit maintenance through 2040, forcing suppliers to retain obsolete machining capabilities alongside digital production lines.
- Multi-Jurisdiction Certification Parallelism:China's CAAC, Japan's JCAB, and Brazil's ANAC maintain non-harmonized fuel system approval pathways that duplicate test matrices and extend program costs by 15-20 percent for global platform coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Engine Fuel Systems Market |
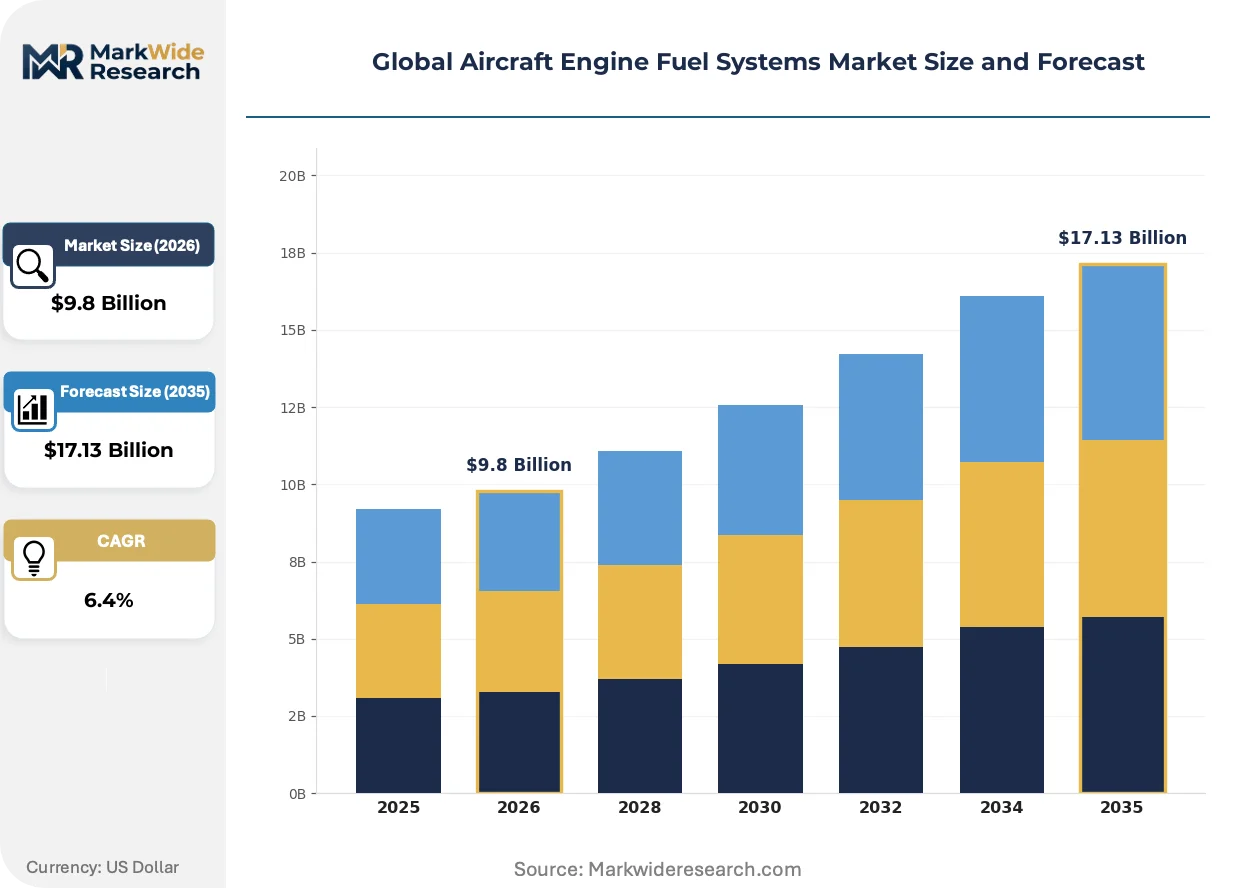
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Pumps, Fuel Control Units, Fuel Nozzles, Fuel Metering Units, Secondary Flow Control Valves Technology: Hydro-Mechanical, Electro-Mechanical, Electronic Engine Control, Digital Electronic Control, Mechanical Control Application: Commercial Jetliners, Military Aircraft, Business Jets, Regional Aircraft, Cargo Airplanes End User: Aircraft Manufacturers, Engine OEMs, Maintenance Repair Organizations, Aircraft Operators |
| Companies Covered | Honeywell International Inc., Eaton Corporation, Parker Hannifin Corporation, RTX Corporation, Woodward, Inc., Triumph Group, Inc., GKN plc, Safran SA, Crane Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Engine Fuel Systems Market Shifts & Advancements
Additive manufacturing is penetrating fuel system component production, compressing lead times for complex manifold geometries while introducing new powder qualification and process certification burdens.
Digital twin implementations for fuel control unit performance simulation are bifurcating the supplier base between tier-one integrators with embedded software capabilities and hardware-only manufacturers facing margin compression. Airlines and engine lessors are mandating predictive maintenance data feeds as contract prerequisites, forcing fuel system OEMs to embed sensor arrays and edge computing modules that transmit real-time metering accuracy diagnostics. The technology is compressing aftermarket service intervals and shifting revenue from scheduled overhauls toward condition-based interventions.
EASA's CS-E certification framework is tightening fuel system fire resistance and redundancy specifications in response to uncontained engine failure incidents, extending test campaign durations and documentation requirements. The regulation is elevating entry barriers for new suppliers while reinforcing incumbents with established certification track records. Narrowbody platforms serving European operators are experiencing the most intensive compliance scrutiny, with dual-channel electronic control architectures now mandatory for new type certifications.
Power-by-the-hour contracts are displacing traditional component sales for fuel system aftermarket coverage, transferring operational risk from airlines to suppliers and compressing upfront capital requirements for fleet operators. Engine OEMs and independent lessors are consolidating procurement decisions at the platform level, reducing the number of discrete fuel system purchasing relationships per airframe program. This consolidation is most advanced in North American and Western European narrowbody fleets, where maintenance cost predictability outweighs unit-level pricing optimization in contract awards.
Global Aircraft Engine Fuel Systems Market Segmentation
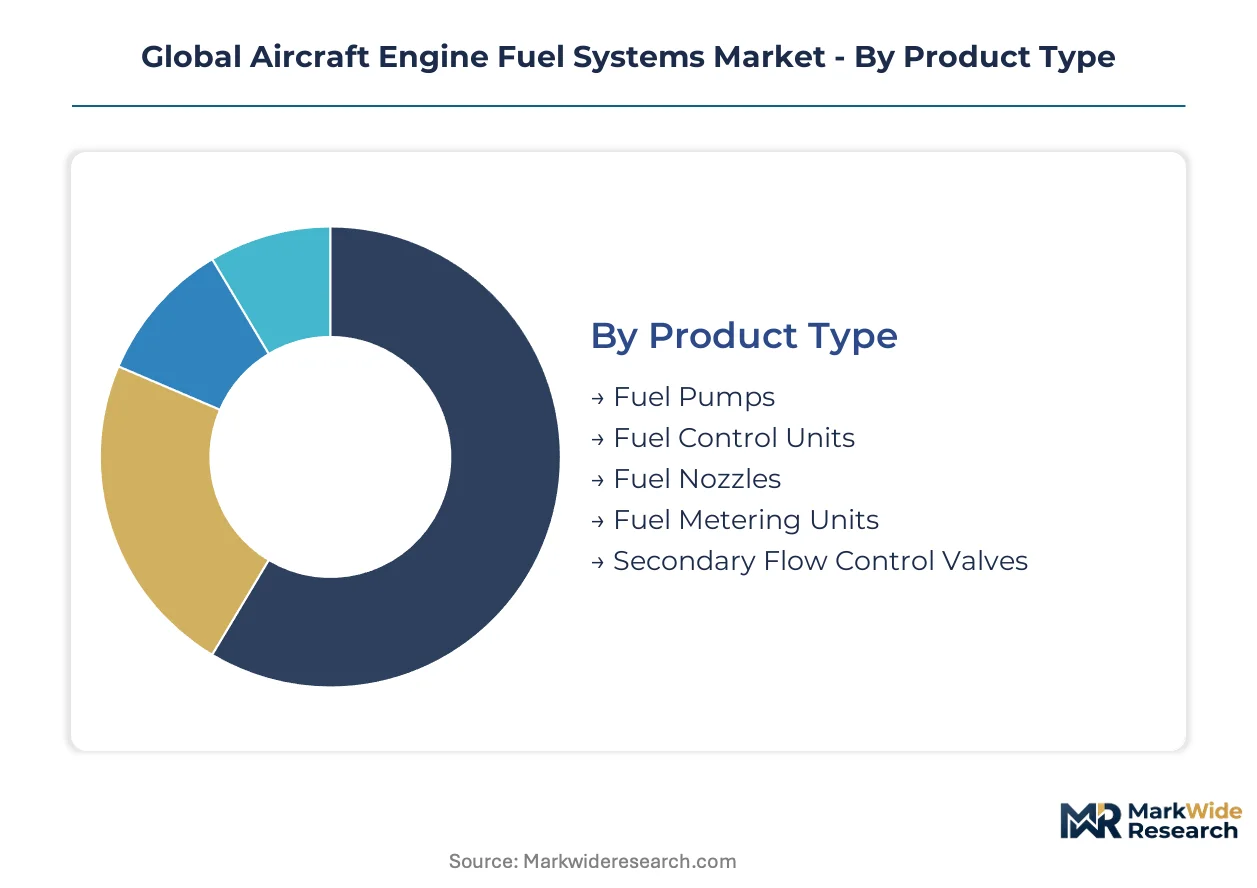
Segmentation in aircraft engine fuel systems reveals how procurement authority splits between engine OEMs and airframe integrators, with technology choices determining aftermarket lock-in duration. Channel dynamics vary sharply: fuel control units flow through engine manufacturer supply chains, while fuel pumps and nozzles serve dual channels through MRO networks and direct OEM contracts.
Product Type:
Fuel system hardware segments distribute through distinct procurement channels—engine OEMs dominate fuel control unit sourcing, while MRO channels capture higher volumes of pumps and nozzles for fleet maintenance cycles.
- Fuel Control Units:These integrated assemblies combine metering, scheduling, and shutoff functions in a single housing, with firmware architectures determining engine OEM sole-source relationships. Demand concentrates at Pratt & Whitney and GE Aviation procurement centers in the United States, driven by narrowbody production ramp requirements and long-term aftermarket service agreements.
- Fuel Pumps:High-pressure positive displacement pumps deliver conditioned fuel at pressures exceeding 1,000 psi across altitude regimes. Parker Hannifin anchors aftermarket contracts through its specialized pump architectures, with demand clustering at Boeing and Airbus final assembly lines in Washington State and Hamburg.
- Fuel Nozzles:Precision-machined spray orifices fabricated from nickel-based superallies ensure flame stability across throttle ranges.
- Fuel Metering Units:Hydro-mechanical or electronic devices regulating mass flow rate to combustion chambers.
- Secondary Flow Control Valves:Actuated valves managing bypass, recirculation, and thermal management functions.
By volume, fuel pumps lead given their replacement frequency across aging fleets. By growth pace, fuel control units are expanding most quickly on FADEC adoption curves.
Technology:
Technology segments stratify by certification burden and margin structure—digital architectures command premium pricing through firmware barriers, while hydro-mechanical systems sustain revenue through legacy fleet maintenance.
- Electronic Engine Control:Distributed digital architectures replacing centralized hydro-mechanical governors, with sensor arrays and actuator networks enabling real-time thrust optimization. CFM International and Pratt & Whitney engine programs in the United States and France drive adoption, compelled by FAA NextGen fuel efficiency mandates and EASA carbon reduction protocols.
- Full Authority Digital Electronic Control:Integrated FADEC systems consolidating all engine control functions under software-governed architectures. Demand clusters at next-generation propulsion programs including open-fan and hybrid-electric roadmaps, with engine OEMs absorbing firmware development costs previously borne by airframe manufacturers.
- Hydro-Mechanical:Legacy governor and servo architectures sustaining CFM56 and V2500 fleets through 2040.
- Electro-Mechanical:Hybrid architectures blending mechanical metering with electronic trim functions.
- Mechanical Control:Purely mechanical governors and linkages retained in specific military and general aviation applications.
By volume, hydro-mechanical systems still dominate installed base. By margin contribution, full authority digital electronic control captures the steepest expansion trajectory.
Application:
Application segments diverge by procurement cycle length and specification intensity—commercial jetliners drive volume through production rates, while military programs concentrate value through development contract structures.
- Commercial Jetliners:Narrowbody and widebody platforms requiring certified fuel system architectures for Part 25 airworthiness. Airbus A320neo and Boeing 737 MAX production in Germany, China, and the United States pulls integrated fuel control units at volumes exceeding other applications by substantial multiples, with fleet renewal cycles compressing procurement windows.
- Military Aircraft:Fighter and transport platforms subject to MIL-STD-810 environmental qualification and ITAR export controls. Lockheed Martin F-35 and Boeing defense programs in the United States sustain demand for dual-use electro-hydraulic valves, with classified specifications limiting supplier pools and extending contract durations.
- Business Jets:Corporate and fractional ownership platforms emphasizing dispatch reliability and cabin noise reduction.
- Regional Aircraft:Turboprop and small jet platforms serving short-haul networks.
- Cargo Airplanes:Dedicated freighter and converted passenger-to-cargo platforms.
By fleet size, commercial jetliners lead. By contract value concentration, military aircraft is ahead.
End User:
End user segments reflect where design authority and procurement budgets reside—engine OEMs control new program sourcing, while MROs capture aftermarket volume as fleets mature.
- Engine OEMs:Pratt & Whitney, Rolls-Royce, and GE Aviation integrate fuel systems at the propulsion system level, dictating specification tiers and sole-source agreements. These manufacturers in the United States and United Kingdom consolidate procurement decisions at the platform level, reducing discrete purchasing relationships per engine program.
- Maintenance Repair Organizations:Independent and airline-affiliated MROs source replacement pumps, nozzles, and seals for fleet sustainment. Lufthansa Technik in Germany and ST Engineering in Singapore expand fuel system MRO capabilities, with India's projected fleet doubling creating greenfield infrastructure demand absent legacy supplier entrenchment.
- Aircraft Manufacturers:Boeing and Airbus specify fuel system interfaces but delegate sourcing to engine OEMs for most platforms.
- Aircraft Operators:Airlines and lessors influence aftermarket procurement through power-by-the-hour contracts transferring operational risk to suppliers.
By new equipment value, engine OEMs lead. By transaction volume, MROs are climbing the fastest on fleet aging curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fuel system manufacturing clusters in the United States, Germany, and China concentrate precision machining and electronic control expertise. These three countries anchor narrowbody production supply chains and certification authority for next-generation propulsion architectures.
United States
Boeing's 737 MAX final assembly in Renton, Washington, and Pratt & Whitney's GTF engine production in Connecticut pull integrated fuel control units at volumes exceeding other platforms. FAA Part 33 airworthiness standards dictate fire resistance and redundancy thresholds that suppliers embed at the design phase. The Greater Seattle aerospace corridor hosts Parker Hannifin and Eaton Corporation manufacturing facilities serving both commercial and military propulsion programs.
Germany
Airbus A320neo production in Hamburg and MTU Aero Engines' final assembly in Munich sustain demand for high-pressure fuel pumps and metering units. EASA CS-E certification requirements extend qualification timelines for new fuel system designs, reinforcing incumbents with established track records. The Hamburg-Finkenwerder industrial zone concentrates fuel nozzle machining capabilities serving European narrowbody fleets.
China
COMAC C919 certification progress and CAAC type approval pathways are accelerating domestic fuel system supplier qualification. China's civil aviation regulator maintains aligned but independently administered certification standards that add compliance cost layers for foreign suppliers. The Shanghai Pudong aviation industrial cluster hosts emerging fuel control unit manufacturing serving both indigenous and joint-venture engine programs.
France
Safran's fuel nozzle metallurgy capabilities and CFM International's LEAP engine production in Villaroche anchor European propulsion supply chains. French regulatory alignment with EASA standards streamlines multi-jurisdiction approvals for suppliers based in the Île-de-France aerospace corridor. The Paris-Saclay engineering cluster concentrates DO-178C firmware certification expertise for FADEC system development.
United Kingdom
Rolls-Royce's UltraFan development program in Derby and civil aerospace headquarters in Bristol sustain demand for advanced fuel metering architectures. UK CAA certification pathways for sustainable aviation fuel compatibility are reshaping seal material specifications across supplier portfolios. The East Midlands aerospace cluster retains hydro-mechanical control unit machining capabilities for legacy fleet sustainment through 2040.
Global Aircraft Engine Fuel Systems Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized aerospace component manufacturers. The vendor base stratifies between tier-one integrators with embedded software capabilities and hardware-focused suppliers facing margin compression. Two dominant archetypes emerge: full-system integrators controlling firmware certification pathways, and precision component specialists capturing aftermarket volume through metallurgy and machining expertise. Competitive moves center on sole-source contract extensions for new engine programs and backward integration into superalloy supply chains.
Among diversified industrial conglomerates, Honeywell International Inc., Eaton Corporation, and Parker Hannifin Corporation exemplify the integrated-system archetype. These entities occupy positions spanning fuel control units, high-pressure pumps, and electro-hydraulic valves. Safran SA and RTX Corporation represent European and transatlantic aerospace specialists with captive capabilities in fuel nozzle architectures and combustion system integration. Woodward, Inc. anchors the control-system tier with electronic engine control firmware expertise concentrated in North American engineering centers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Eaton Corporation |
| Parker Hannifin Corporation |
| RTX Corporation |
| Woodward, Inc. |
| Triumph Group, Inc. |
| GKN plc |
| Safran SA |
| Crane Co. |
| Others |
Supply & Pricing Matrix
Narrowbody production scale economies at Boeing's Renton facility and Airbus's Hamburg complex concentrate procurement leverage among a handful of engine OEMs, compressing margin pools for fuel system suppliers while establishing price floors tied to superalloy input costs and firmware certification overhead. This concentration dynamic forces tier-two component manufacturers to absorb development expenses upfront in exchange for decade-long sole-source aftermarket agreements.
Pricing Analysis
FAA Part 33 airworthiness standards dictate the pricing tier structure across the aircraft engine fuel systems market, separating premium-grade FADEC-integrated fuel control units certified for narrowbody platforms from standard-tier hydro-mechanical systems serving legacy fleet maintenance and economy-grade aftermarket pumps subject to commodity superalloy cost fluctuations. Price differentiation hinges on DO-178C firmware certification grade and captive metallurgy capabilities for nickel-based superalloy nozzles. Cost compression in the hydro-mechanical tier is intensifying because engine OEMs are internalizing electronic control development, squeezing hardware-only suppliers. Military procurement officers exhibit the lowest price sensitivity due to ITAR compliance requirements, while independent MROs in emerging aviation markets drive the hardest bargain on replacement pump volumes.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Hamburg and Shanghai are extending lead times for aerospace-grade titanium sponge shipments, forcing fuel system manufacturers to hold elevated inventory buffers. Geographic supply concentration centers on the United States, Germany, and China, where precision machining clusters and electronic control expertise co-locate with narrowbody final assembly lines. Raw material dependencies draw from Russian-sourced titanium sponge, nickel-based superalloys from specialty foundries in the United States and France, and high-performance elastomers for seal packages. Single-source firmware vulnerabilities represent the dominant structural risk, as FADEC software certification locks engine OEMs into irreplaceable supplier relationships regardless of hardware alternatives. Distribution runs through engine manufacturer procurement centers for new equipment, while MRO networks capture aftermarket volume as power-by-the-hour contracts consolidate purchasing decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
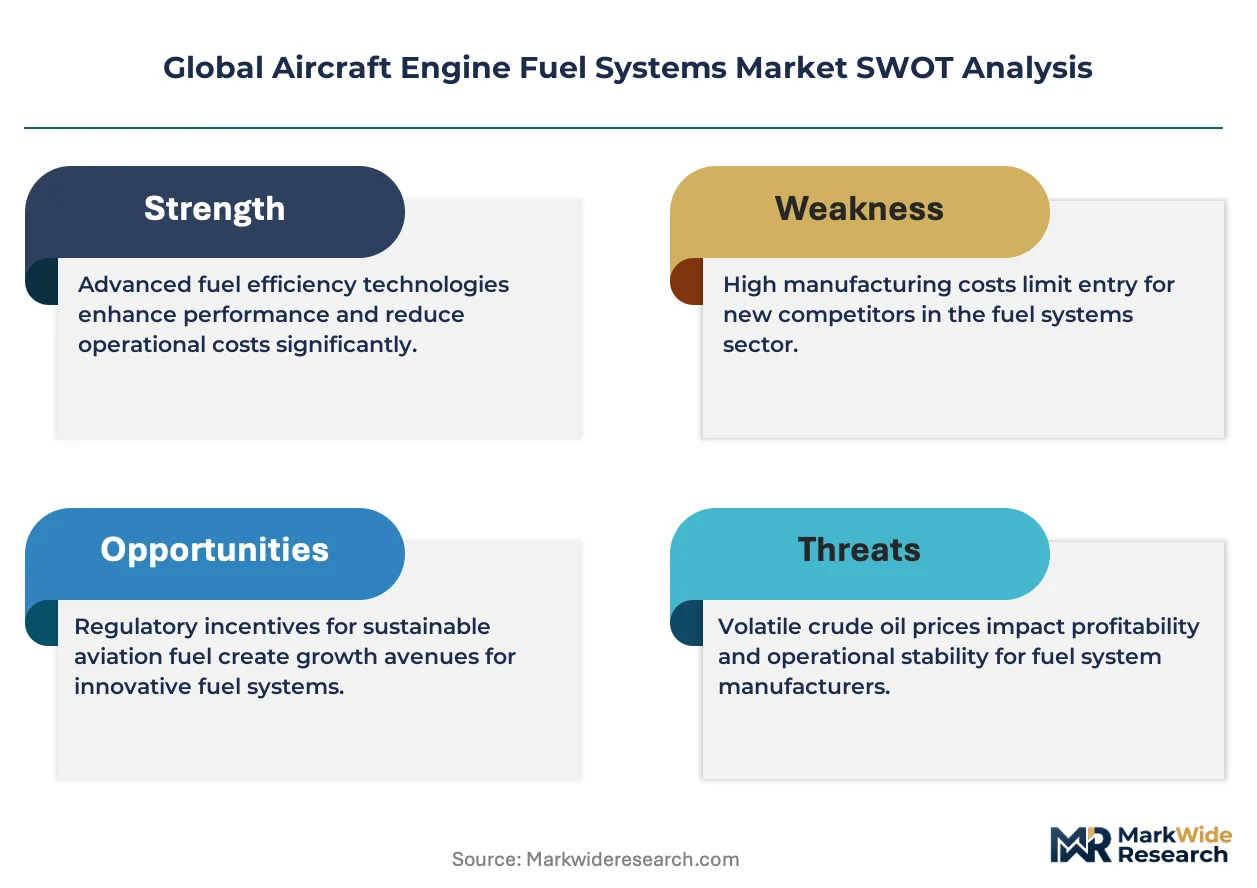
The aircraft engine fuel systems market functions as a regulatory moat business, where FAA and EASA certification entrenchment creates switching costs that protect incumbents from competitive displacement regardless of hardware performance advantages.
For Market Incumbents: Secure sole-source contract extensions for next-generation open-fan propulsion programs by embedding predictive maintenance data feeds as mandatory contract terms, while acquiring captive superalloy supply capabilities to insulate margin pools from titanium price volatility driven by Russian supply disruption. FADEC firmware talent scarcity at North American engineering centers represents the most pressing threat to execution capacity. For New Entrants and Emerging Players: Aftermarket service data integration gaps where Honeywell and Eaton under-serve independent MROs present the most penetrable entry point, particularly for edge-computing-enabled fuel metering diagnostics targeting India's projected fleet doubling. Target greenfield MRO infrastructure buildout in the Indian subcontinent through partnerships with ST Engineering and Lufthansa Technik, leveraging absence of legacy supplier entrenchment to establish first-mover relationships before domestic qualification pathways mature. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified industrial conglomerates with embedded software capabilities and established certification track records over hardware-focused precision component specialists facing margin compression from digital twin implementations. Long-term viability over the coming decade rests on backward integration into superalloy supply chains and firmware development capacity. Monitor EASA fire-resistance specification tightening as the critical inflection signal, as extended test campaign durations will accelerate consolidation toward incumbents with established CS-E compliance records.| Strategic Initiative | Industry Significance |
|---|---|
| FADEC Firmware Certification Investment | DO-178C expertise concentration at five North American engineering centers locks in decade-long sole-source agreements. |
| Backward Integration into Superalloy Supply | Safran's captive metallurgy capabilities for fuel nozzles insulate margin pools from nickel price volatility. |
| Predictive Maintenance Data Partnership | Airlines mandating real-time metering accuracy diagnostics compress aftermarket service intervals toward condition-based interventions. |
| India MRO Infrastructure Joint Venture | DGCA fleet doubling creates greenfield demand absent legacy Parker Hannifin and Eaton contract entrenchment. |
| Open-Fan Propulsion Design Competition | CFM International RISE program distributed fuel injection requirements bypass conventional manifold geometries. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fuel system engineering directors, engine OEM procurement leads, EASA certification officers, and MRO operations managers; and secondary validation against FAA Part 33 airworthiness filings, EASA CS-E certification databases, SEC 10-K disclosures from diversified industrial conglomerates, and customs records tracking aerospace-grade titanium sponge trade flows. Bottom-up triangulation across component-level production volumes and top-down reconciliation against engine manufacturer procurement disclosures anchored market sizing.
Across the analysis window, the forecast framework modeled demand trajectories by technology tier (electronic engine control, full-authority digital electronic control, hydro-mechanical), product category (fuel control units, pumps, nozzles, metering units), application segment (commercial jetliners, military aircraft, business jets), and end-user channel (engine OEMs, MROs, aircraft manufacturers). CAGRs derived from production rate projections at Boeing and Airbus final assembly lines, fleet renewal cycle timing, and sustainable aviation fuel compatibility upgrade requirements. Industry-specific inputs incorporated Pratt & Whitney GTF and CFM International LEAP output schedules, alongside CAAC C919 certification progress.
Forecasts assume regulatory continuity in FAA Part 33, EASA CS-E, and CAAC type certification pathways; material policy shifts in fire-resistance specifications or sustainable aviation fuel blending mandates would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Gas Turbine Upgrade for Performance Enhancement Market