
 Gas Turbine Upgrade for Performance Enhancement Market | 2026-2036
Gas Turbine Upgrade for Performance Enhancement Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Turbine Upgrade for Performance Enhancement Market Analysis
The United States is rewriting competitive dynamics for gas turbine upgrades through its massive installed base of combined-cycle plants built during the 1990s and 2000s. GE Vernova leverages its OEM service agreements to dominate the aftermarket for heavy-duty frame turbines. Siemens Energy competes through its comprehensive component replacement programs targeting F-class and H-class units. Mitsubishi Heavy Industries anchors its position in Asia through long-term service contracts with Japanese and Southeast Asian utilities.
Gas turbine upgrade for performance enhancement encompasses hardware modifications, control system modernization, and combustion optimization applied to existing turbomachinery to restore or exceed original design output, heat rate, and emissions performance. Typical interventions include replacement of degraded hot gas path components with advanced superalloy designs, retrofit of digital control architectures, and implementation of inlet air cooling or fogging systems to recover lost capacity. Component replacement and efficiency improvement categories command the deepest margin pools due to material intensity and specialized labor requirements. Control system upgrade demand is accelerating fastest as utilities seek AI-enabled diagnostics and remote monitoring capabilities to reduce forced outage rates.
EPA New Source Performance Standards and the EU F-Gas Regulation shape upgrade specifications by mandating lower NOx and greenhouse gas intensity from modified units. The Federal Energy Regulatory Commission's interconnection rules in the United States and national grid codes across Europe determine whether upgraded turbines qualify for capacity payments and priority dispatch. Stakeholders must monitor evolving carbon border adjustment mechanisms and hydrogen blending mandates that could render unmodified gas turbines economically stranded within a single regulatory cycle.
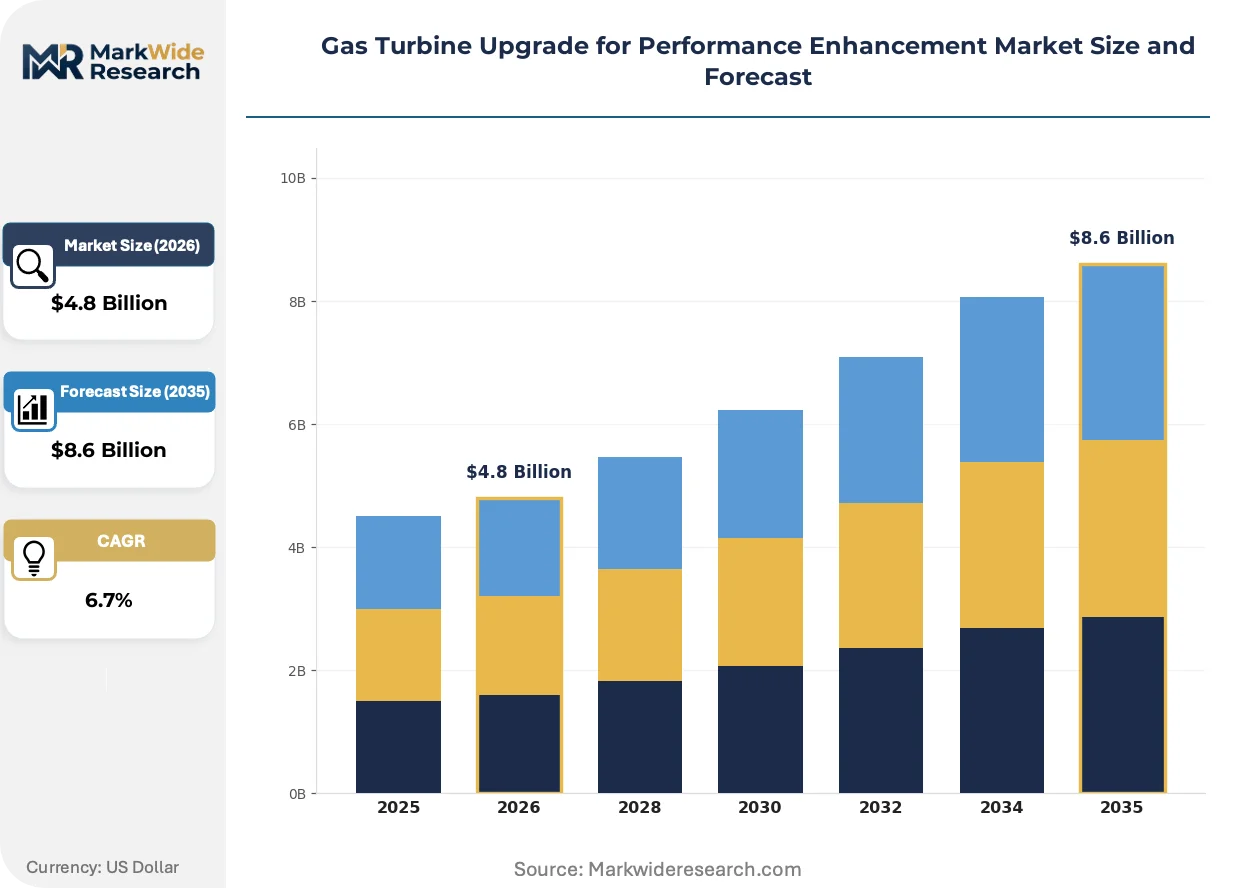
Market Dynamics
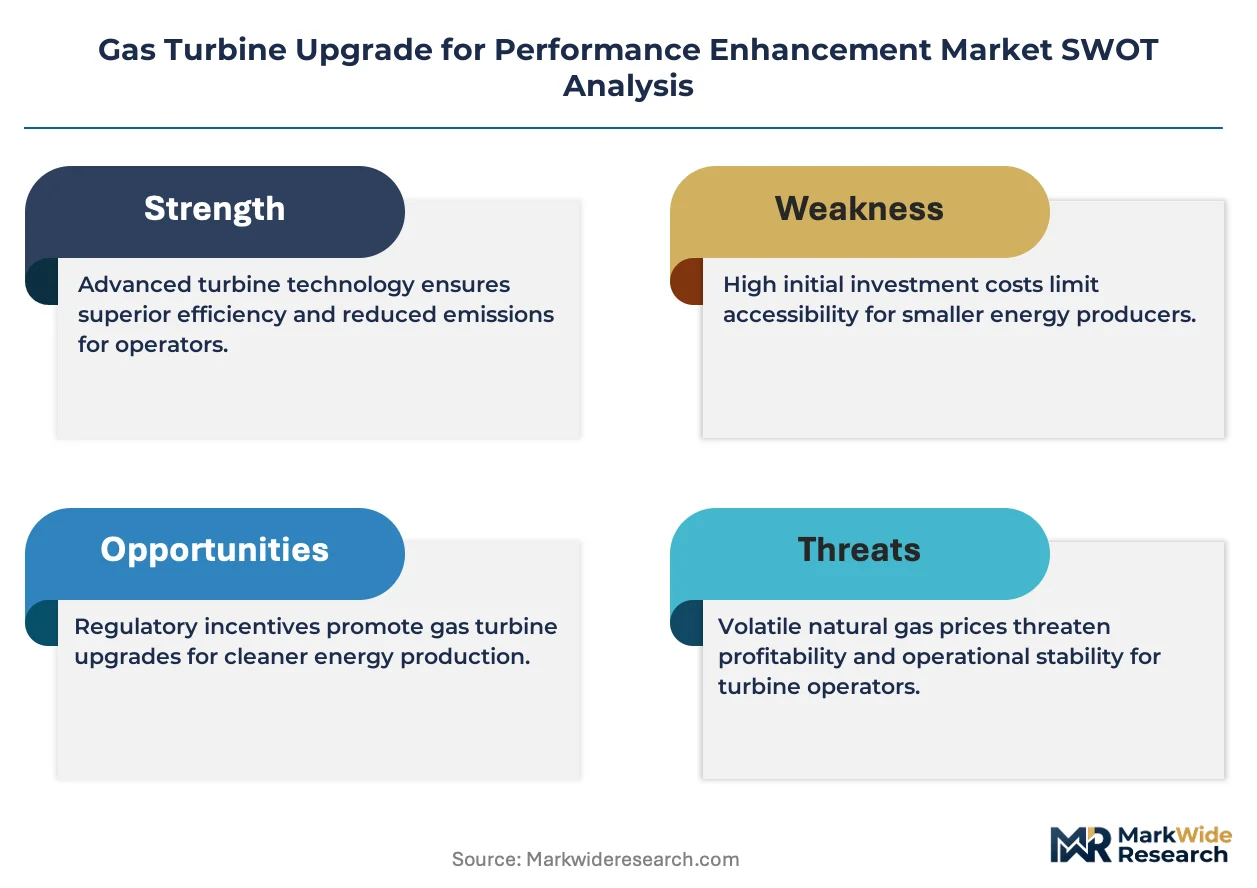
Stricter emissions mandates from the EPA and EU F-Gas Regulation are forcing utilities to choose between costly retrofits and premature asset retirement, compressing decision timelines for fleet managers.
Growth Catalysts
- EPA New Source Performance Standards:These rules mandate NOx reductions from modified units, compelling US power utilities to invest in low-NOx combustion retrofits and digital control architectures.
- Hot gas path component degradation:Aging F-class and H-class turbines in combined-cycle plants require superalloy replacement cycles, creating recurring hardware demand from installed base expansion.
- India:State-run generation companies face political pressure to maximize output from existing assets without greenfield construction, concentrating upgrade demand in this geography.
Market Restraints
- Superalloy supply concentration:Specialized nickel-based alloys for hot section components depend on limited foundry capacity in the United States and Germany, creating input bottlenecks.
- Carbon border adjustment mechanisms:Emerging EU trade policies threaten to strand unmodified gas turbines economically within a single regulatory cycle, chilling investment.
- Renewable substitution:Utility-scale solar and battery storage are capturing incremental capacity additions, reducing the relative attractiveness of turbine life extension projects.
Strategic Opportunities
- Hydrogen blending mandates:EU decarbonization frameworks are creating demand for combustion system modifications capable of handling elevated hydrogen concentrations in fuel supply.
- AI-enabled diagnostics:Convergence of machine learning algorithms with digital twin technology opens remote monitoring service models for utilities seeking to reduce forced outage rates.
- Southeast Asia:Japanese utilities are extending long-term service contracts into Vietnam and Thailand, transferring technical capabilities to underpenetrated markets.
Industry Challenges
- Specialized welding technicians:Hot gas path repairs require Inconel and cobalt alloy expertise that exceeds standard power plant maintenance crew capabilities.
- Control system integration:Retrofitting digital architectures onto legacy analog turbine governors creates commissioning delays and interoperability failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Turbine Upgrade for Performance Enhancement Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Upgrade Type: Performance Tuning, Control System Upgrade, Component Replacement, Efficiency Improvement Application: Power Generation, Oil & Gas, Marine, Aerospace End User: Utilities, Industrial Facilities, Research Institutions, Governmental Agencies Technology: Advanced Sensors, AI Optimization, Additive Manufacturing, Hybrid Solutions |
| Companies Covered | GE Vernova, Mee Industries, General Electric, B&B-AGEMA GmbH, Industrial Turbine Systems, Siemens Energy, Centrax Industries, MAN Energy Solutions, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Turbine Upgrade for Performance Enhancement Market Emerging Trajectories
Additive manufacturing of superalloy turbine blades is collapsing lead times for replacement hot gas path components. Digital twin platforms are compressing maintenance intervals through predictive analytics. Procurement patterns are fragmenting as utilities unbundle OEM service agreements.
Directed energy deposition and powder bed fusion techniques are collapsing traditional casting timelines for first-stage buckets and nozzles. Siemens Energy and GE Vernova field teams are adopting these processes for emergency repairs. The technology is collapsing spare parts inventory requirements and enabling just-in-time component production.
The EU F-Gas Regulation is tightening greenhouse gas intensity thresholds for modified turbomachinery. Equipment owners must now document emissions performance improvements to qualify for operating permits. Combined-cycle operators in Germany and the Netherlands are responding with inlet air cooling retrofits and advanced sealing packages.
Long-term service agreements are fragmenting as utilities seek competitive bidding for major inspections. Independent service providers are capturing scope previously reserved for OEM channels. This unbundling is most visible in the United States, where merchant generators face merchant power price volatility and seek to minimize fixed costs.
Gas Turbine Upgrade for Performance Enhancement Market Segmentation
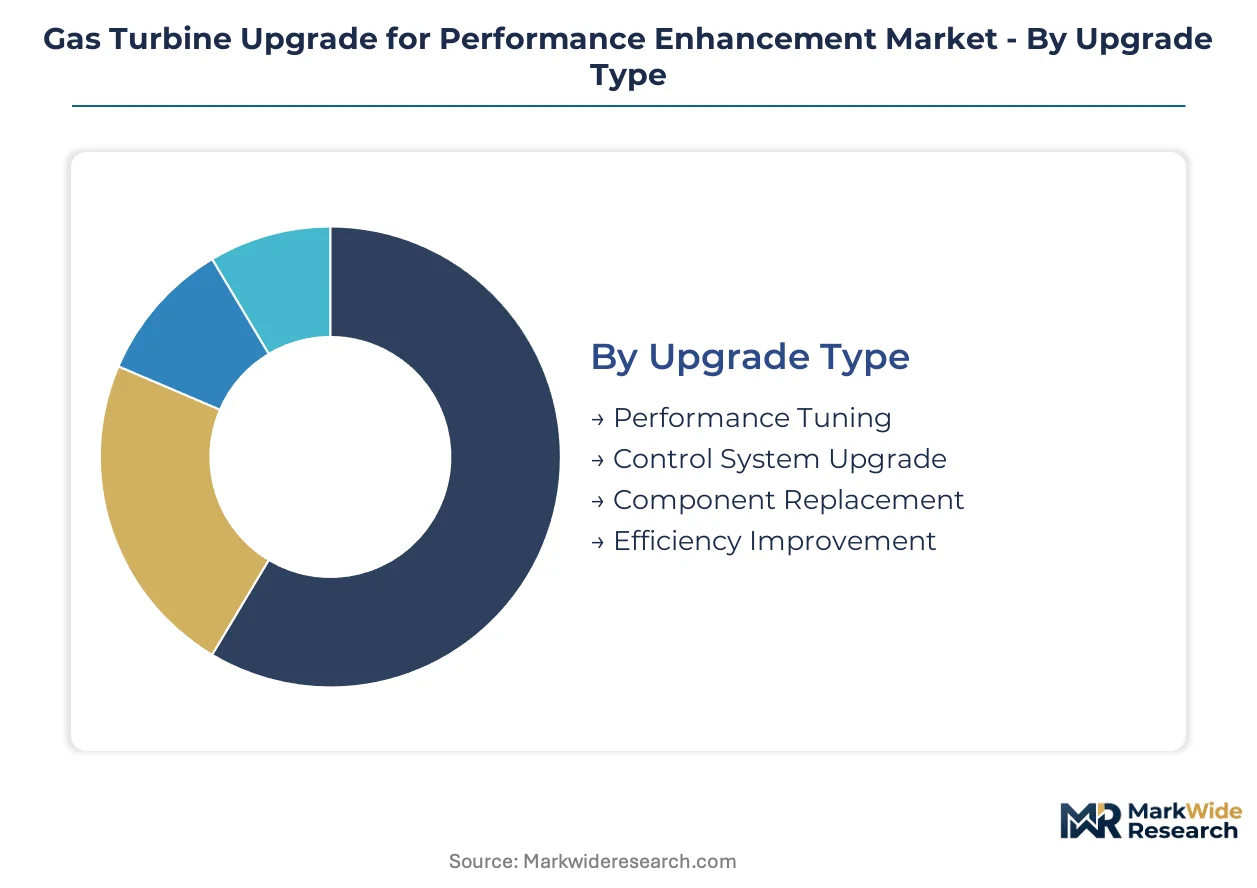
Segmentation reveals distinct upgrade economics across turbine vintages and operational profiles. Upgrade type and application drive fundamentally different margin structures and procurement behaviors.
Upgrade Type:
Mature hardware interventions dominate current revenue, while digital and additive technologies emerge as growth vectors.
- Component Replacement:Hot gas path hardware swaps using advanced superalloy designs restore degraded output and heat rate in aging F-class and H-class units. Demand concentrates in United States combined-cycle plants facing EPA emissions deadlines, with utilities prioritizing superalloy bucket and nozzle replacement over full unit retirement.
- Efficiency Improvement:Inlet air cooling systems and advanced sealing packages recover lost capacity and reduce fuel consumption. Indian state-run generation companies deploy these retrofits to maximize output from installed base without greenfield construction, driven by political pressure to avoid new capital expenditure.
- Control System Upgrade:Digital architecture retrofits enable AI-enabled diagnostics and remote monitoring capabilities.
- Performance Tuning:Combustion optimization adjustments restore design specifications without major hardware intervention.
Component Replacement handles the majority of throughput; Efficiency Improvement is climbing the fastest on share.
Application:
Power generation anchors installed base volume, while oil and gas applications command premium pricing for uptime-critical deployments.
- Power Generation:Combined-cycle and simple-cycle plants require life extension to bridge renewable intermittency. German and Dutch operators respond to EU F-Gas Regulation with inlet cooling and sealing retrofits to qualify for operating permits.
- Oil & Gas:LNG trains and pipeline compression stations prioritize reliability over efficiency gains. Offshore platforms in Southeast Asia extend maintenance intervals through predictive analytics, transferring Japanese utility service contract models to underpenetrated markets.
- Marine:Naval and commercial vessel propulsion systems face distinct classification society requirements.
- Aerospace:Derivative industrial turbines derived from aviation platforms require specialized overhaul protocols.
Power Generation captures the deepest revenue pool; Oil & Gas delivers the highest margin per installed megawatt.
End User:
Procurement sophistication varies sharply between regulated utilities and merchant industrial operators.
- Utilities:Regulated power companies with long-term service agreements now unbundle OEM contracts for competitive bidding. United States merchant generators facing power price volatility minimize fixed costs through fragmented procurement.
- Industrial Facilities:Cogeneration and captive power operators prioritize heat rate improvements over emissions compliance.
- Governmental Agencies:Defense and strategic reserve installations mandate domestic content and security-cleared technicians.
- Research Institutions:University and national laboratory test beds drive early adoption of hydrogen blending combustion modifications.
Utilities dominate contract value; Industrial Facilities show the steepest expansion trajectory as distributed generation spreads.
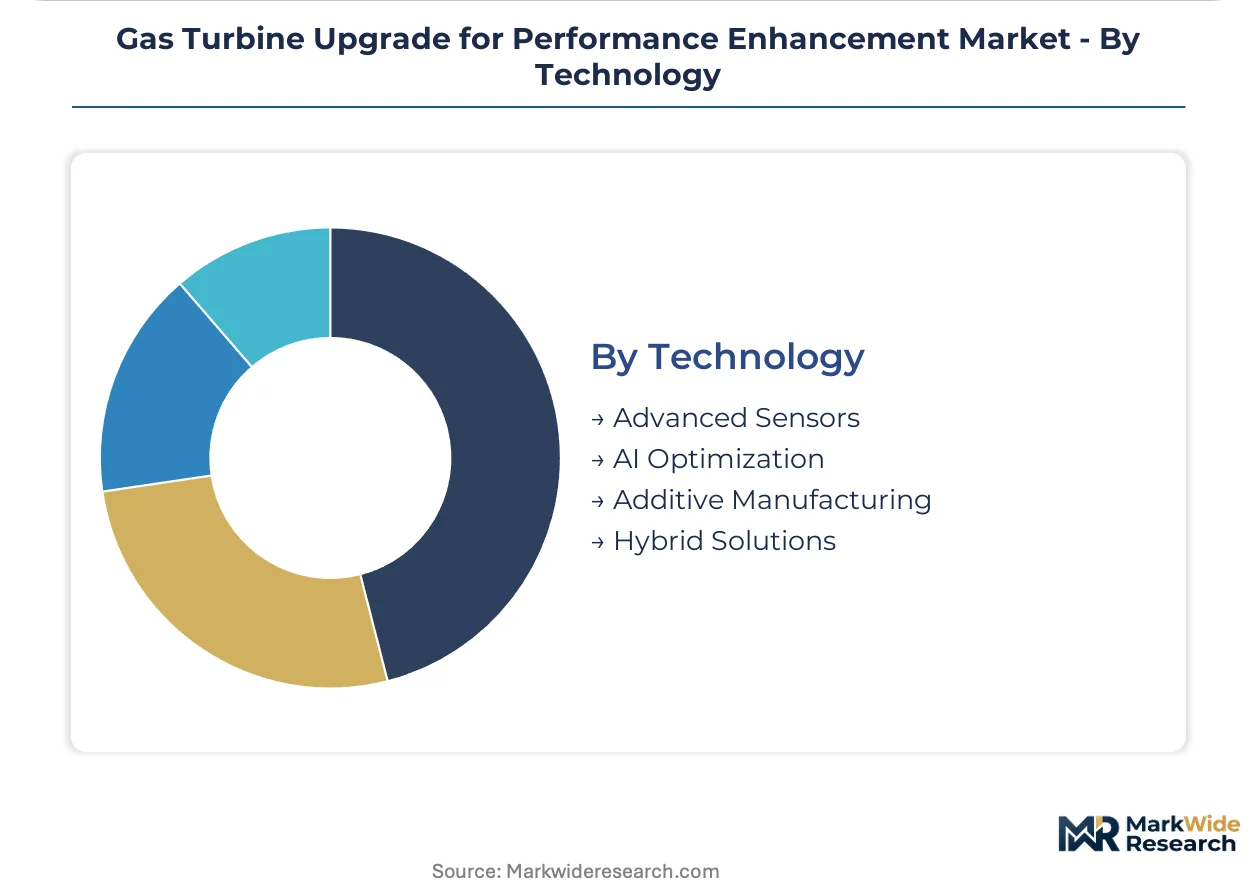
Technology:
Digital and advanced manufacturing technologies are displacing conventional repair methodologies.
- AI Optimization:Machine learning algorithms integrated with digital twin platforms compress maintenance intervals through predictive analytics. Remote monitoring service models reduce forced outage rates for utilities seeking operational cost reduction.
- Additive Manufacturing:Directed energy deposition and powder bed fusion collapse casting timelines for first-stage buckets and nozzles. Emergency repairs now deploy just-in-time component production, collapsing spare parts inventory requirements.
- Advanced Sensors:Distributed temperature and vibration monitoring enable condition-based maintenance.
- Hybrid Solutions:Combined digital and hardware interventions address multiple degradation modes simultaneously.
AI Optimization leads adoption velocity; Additive Manufacturing is gaining share fastest as foundry bottlenecks persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA New Source Performance Standards anchor demand in the United States, while parallel regulatory frameworks in Europe and Asia-Pacific create differentiated upgrade specifications across national markets.
United States
Combined-cycle plants built during the 1990s and 2000s require life extension to meet FERC interconnection rules and qualify for capacity payments. EPA mandates on NOx emissions compel utilities toward low-NOx combustion retrofits and digital control architectures. Texas and California host the densest concentrations of merchant generators unbundling OEM service agreements for competitive bidding.
Germany
Combined-cycle operators respond to EU F-Gas Regulation tightening greenhouse gas intensity thresholds for modified turbomachinery. Documentation requirements for emissions performance improvements drive inlet air cooling retrofits and advanced sealing packages. The Ruhr industrial corridor and Bavarian power clusters concentrate upgrade demand from utilities seeking operating permit compliance.
India
State-run generation companies face political pressure to maximize output from installed F-class and H-class assets without greenfield construction. Central Electricity Authority guidelines shape technical specifications for efficiency-focused hardware retrofits. Maharashtra and Gujarat host the largest concentrations of aging turbine fleets requiring superalloy component replacement cycles.
Japan
Utilities extend long-term service contract models developed domestically into Southeast Asian markets through technical capability transfers. METI decarbonization frameworks accelerate demand for hydrogen-ready combustion modifications. The Kanto and Kansai industrial belts anchor domestic upgrade demand while serving as export hubs for Vietnamese and Thai power projects.
Netherlands
Gas turbine operators navigate EU F-Gas Regulation permit requirements through inlet cooling and sealing retrofits that document measurable emissions reductions. National grid codes determine priority dispatch eligibility for upgraded units. The Rotterdam-Antwerp industrial cluster concentrates demand from petrochemical cogeneration operators seeking heat rate improvements.
Gas Turbine Upgrade for Performance Enhancement Market Vendor Landscape
OEM incumbents and independent service providers split the market along the fault line of long-term service agreement unbundling. The vendor base concentrates around three strategic archetypes: original equipment manufacturers leveraging installed base lock-in, independent specialists capturing inspection scope through competitive bidding, and additive manufacturing innovators collapsing spare parts lead times. Competitive moves center on technology licensing for hydrogen-ready combustion systems and backward integration into superalloy foundry capacity to bypass supply bottlenecks.
Within the OEM tier, GE Vernova and Siemens Energy occupy positions defined by comprehensive component replacement programs and digital architecture retrofit capabilities. Mitsubishi Heavy Industries anchors the Asia-Pacific vector through technical service contract extensions. Among European-based specialists, B&B-AGEMA GmbH exemplifies the independent service provider archetype capturing scope from fragmented procurement patterns. MAN Energy Solutions represents the industrial turbomachinery crossover segment applying marine and oil-gas expertise to power generation upgrades.
| Leading Market Players |
|---|
| GE Vernova |
| Mee Industries |
| General Electric |
| B&B-AGEMA GmbH |
| Industrial Turbine Systems |
| Siemens Energy |
| Centrax Industries |
| MAN Energy Solutions |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Superalloy supply concentration in United States and German foundries dictates both margin compression in component replacement tiers and the geographic clustering of upgrade service providers. EPA emissions deadlines and EU F-Gas Regulation compliance windows compress procurement timelines, amplifying pricing power for holders of certified hot gas path inventory while forcing utilities toward longer-term service contracts.
Pricing Analysis
Geographic price spreads widen between North American and Asian upgrade markets, with United States combined-cycle operators absorbing 15-25% premiums for EPA-compliant combustion hardware. Three-tier pricing structure across premium OEM service agreements, independent specialist bids, and emergency repair rates reflects certification grade and after-sales bundling intensity. Cost compression in standard-tier efficiency retrofits is intensifying because Indian state-run generators unbundle contracts for competitive bidding. Merchant generators in Texas and California exhibit highest price sensitivity due to power price volatility, while Japanese utilities show lowest sensitivity under long-term service contract lock-in.
Supply Chain Analysis
Specialized foundry capacity at Precision Castparts and Howmet Aerospace anchors superalloy component supply, with directed energy deposition service bureaus emerging as secondary sources. Hot gas path hardware draws from United States, Germany, and Japan; digital control architectures source from Taiwan and South Korea; specialized welding consumables feed from United States and Sweden. Single-source vulnerability concentrates in first-stage bucket and nozzle castings for F-class and H-class turbines. Distribution runs through OEM direct channels, independent service provider networks, and emergency repair logistics hubs positioned near combined-cycle plant clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas turbine upgrade market sits in a replacement cycle upswing driven by 1990s-2000s combined-cycle fleet maturation, creating favorable conditions for hardware-intensive service strategies over the next decade.
For Market Incumbents: Pre-empt independent service provider encroachment by backward integration into additive manufacturing capacity for emergency superalloy component production. Lock in superalloy foundry offtake agreements to secure input supply against nickel price volatility and limited United States-Germany casting capacity. Capture hydrogen-ready combustion modification intellectual property before EU blending mandates accelerate. For New Entrants and Emerging Players: Southeast Asian underpenetration in Vietnam and Thailand offers white-space capture through technical capability transfers from Japanese utility service contract models. Target efficiency improvement retrofits for Indian state-run generators facing political pressure to maximize installed base output without greenfield construction. Lead with AI-enabled remote monitoring service models that reduce forced outage rates for merchant generators unbundling OEM agreements. For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors additive manufacturing innovators and hydrogen-ready combustion technology holders. Long-term viability hinges on positioning for successive regulatory tightening across EPA, EU F-Gas, and emerging carbon border adjustment mechanisms. Watch for hydrogen blending mandate acceleration as the inflection signal that revalues combustion modification intellectual property.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Foundry Capacity | Secures supply of Inconel and cobalt alloys for hot gas path repairs against United States-Germany capacity constraints. |
| Hydrogen-Ready Combustion System Licensing | Positions upgrade portfolios for EU decarbonization mandates and METI hydrogen blending frameworks in Japan. |
| AI-Enabled Remote Monitoring Platform Launch | Captures recurring revenue from utilities seeking predictive analytics to reduce forced outage rates. |
| Southeast Asia Service Contract Extension | Transfers Japanese utility technical capabilities into Vietnamese and Thai power markets through long-term agreements. |
| Additive Manufacturing Emergency Repair Capability | Collapses spare parts inventory requirements through just-in-time production of first-stage buckets and nozzles. |
Methodological Framework
The analysis maps component replacement, efficiency improvement, control system upgrade, and performance tuning segments, each validated through utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Primary interviews with fleet managers at United States merchant generators and state-run Indian generation companies combined with secondary validation from EIA data, IEA reports, FERC filings, and EPA emissions compliance databases. Bottom-up installed base enumeration and top-down regulatory mandate impact assessment were triangulated to establish upgrade volume estimates.
Assumptions held fixed include current EPA New Source Performance Standards stringency and EU F-Gas Regulation greenhouse gas intensity thresholds; variables tested included hydrogen blending mandate acceleration rates and superalloy supply bottleneck severity. The forecast framework models upgrade type, application, end user, and technology dimensions across the projection horizon. CAGRs were derived from segment-level replacement cycle timing and regulatory deadline clustering. Forecast inputs incorporated combined-cycle plant vintage distribution and regional emissions compliance cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing specialists or hydrogen combustion technology disruptors would shift outcomes. Forecasts reflect assumptions about regulatory implementation timelines and superalloy supply elasticity. Cross-checking against FERC interconnection queue data and EPA emissions compliance tracking systems is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
General Aviation Engines Market