
 Aircraft Turbine Engine Market | 2026-2036
Aircraft Turbine Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Turbine Engine Market Outlook
OEM-direct procurement channels is fragmenting as airlines and lessors diversify sourcing through independent MRO networks and parts brokers. Pratt & Whitney leverages its geared turbofan platform to sustain aftermarket revenue streams across installed fleets. General Electric Company anchors wide-body engine deliveries through long-term service agreements with global carriers. Rolls-Royce plc competes on ultra-high-thrust segments for next-generation twin-aisle programs.
An aircraft turbine engine converts thermal energy from fuel combustion into mechanical shaft power through successive compressor, combustor, and turbine stages, typically operating at pressure ratios exceeding 40:1 in modern high-bypass designs. Its primary purpose is to generate thrust for propulsion or shaft power for auxiliary systems across fixed-wing and rotary-wing platforms. Turbofan configurations dominate commercial transport due to superior fuel efficiency and noise suppression, while turboprop architectures retain structural importance in regional connectivity and short-field operations. Military aviation applications favor turbojet and low-bypass turbofan designs optimized for supersonic performance and combat maneuverability.
The FAA and EASA enforce stringent airworthiness and emissions certification standards that dictate engine architecture choices and retrofit timelines for fleet operators. EPA regulations on aircraft greenhouse gas emissions, aligned with ICAO Annex 16 Volume IV, constrain new engine development pathways and sustain retrofit demand for existing powerplants. The EU Green Deal and CSRD disclosure requirements extend compliance obligations through supply chain tiers, compelling OEMs to document lifecycle carbon intensity. Stakeholders must monitor sustainable aviation fuel certification progress and countervailing tariff structures on precision-cast components.
Market Dynamics
The aircraft turbine engine sector faces intensifying pressure from ICAO's Carbon Offsetting and Reduction Scheme for International Aviation, which mandates emissions performance thresholds that force fleet operators toward next-generation powerplant architectures and accelerate retirement timelines for older engine generations.
Growth Catalysts
- Narrow-body fleet expansion:Commercial carriers in China and India are scaling single-aisle aircraft orders to capture rebounding passenger traffic volumes. This concentrates procurement demand around high-bypass turbofan designs optimized for short-to-medium haul economics.
- ICAO Annex 16 Volume IV:The EPA's alignment with international aircraft greenhouse gas standards creates compliance-driven replacement cycles. Operators must retrofit or retire engines that fail to meet nitrogen oxide and particulate matter limits.
- Geared turbofan architectures:Pratt & Whitney's power-dense transmission systems deliver double-digit fuel efficiency gains over conventional direct-drive designs. Airlines prioritize these powerplants for new narrow-body deliveries despite higher upfront acquisition costs.
Market Restraints
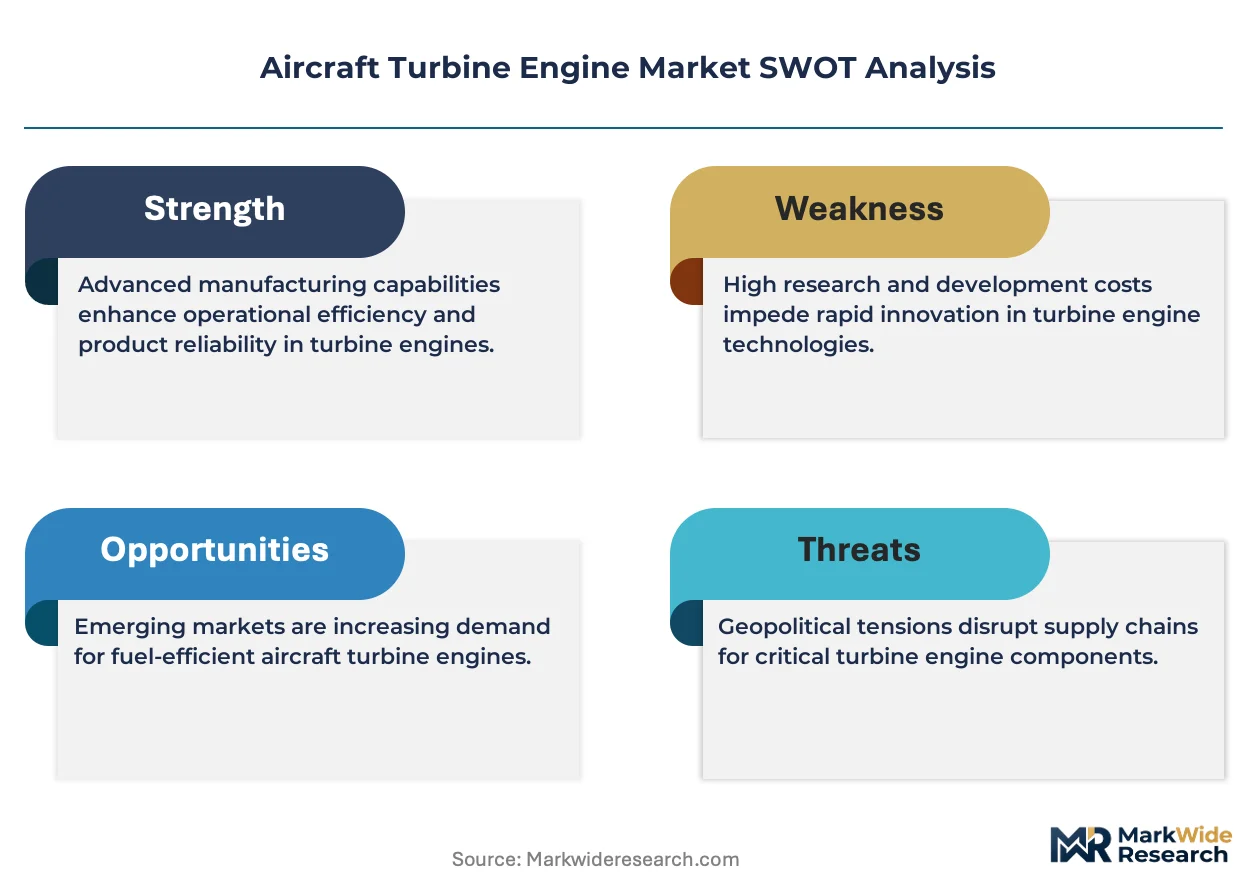
- Superalloy supply concentration:Precision-cast turbine blades depend on nickel-based alloys sourced through a concentrated supplier base in the United States and Germany. Input cost volatility in specialty metals compresses OEM margins and extends lead times.
- Certification timeline friction:FAA and EASA airworthiness validation for new engine programs requires extensive test-cell hours and flight envelope demonstration. Regulatory friction delays revenue recognition by three to five years from design freeze.
- Hybrid-electric substitution threat:Regional aviation segments below fifty-seat capacity face displacement from battery-hybrid propulsion systems under development. Turboprop architectures in sub-1,500 nautical mile routes confront long-term demand erosion.
Strategic Opportunities
- Sustainable aviation fuel certification:The ASTM D7566 standard for synthetic paraffinic kerosene creates aftermarket retrofit demand. Engine OEMs can capture service revenue through combustion system modifications that enable higher SAF blend ratios.
- India MRO infrastructure gap:The country's maintenance capacity lags fleet growth, creating white space for independent service providers. Third-party overhaul facilities can displace OEM-captive networks in the fastest-growing aviation market.
- Digital twin convergence:Physics-based modeling fused with flight-data analytics enables predictive maintenance contracts. Airlines in Germany and Singapore are piloting these outcome-based agreements to optimize engine-on-wing time.
Industry Challenges
- Specialized technician scarcity:Advanced repair processes for single-crystal turbine components require metallurgical expertise concentrated among aging workforces in the United States and United Kingdom. Training pipeline gaps threaten MRO throughput capacity.
- Legacy fleet integration complexity:New engine control software architectures must interface with aging airframe systems dating to the 1990s. Certification of these mixed-vintage integrations consumes disproportionate engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Turbine Engine Market |
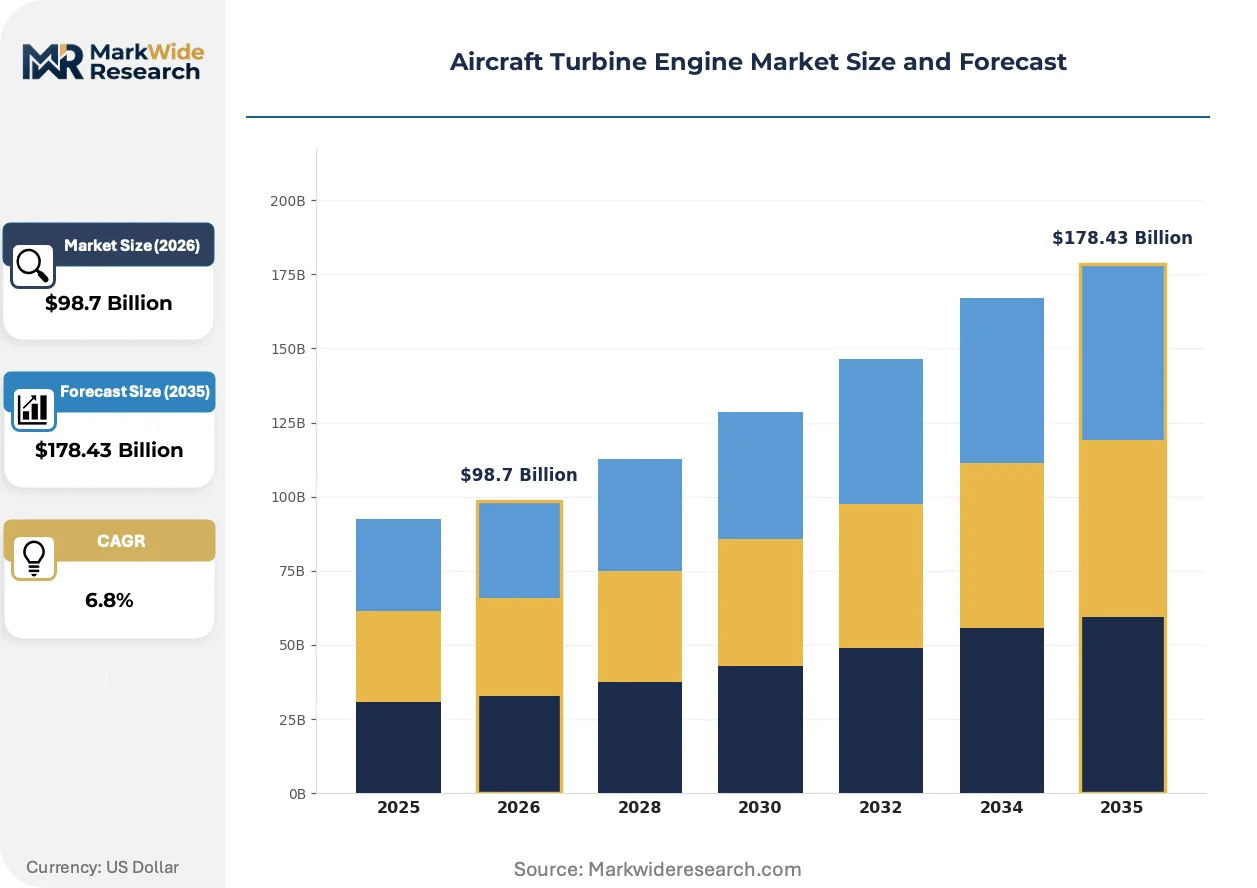
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbojet, Turbofan, Turboprop, Turboshaft Application: Civil Aviation, Military Aviation, Commercial Transport, Business Aviation End User: Airlines, Military Forces, Aircraft Manufacturers, Maintenance Providers Fuel Type: Aviation Fuel, Biofuel, Synthetic Fuel, Others |
| Companies Covered | CFM International, General Electric Company, Pratt & Whitney, Rolls-Royce plc, Safran, MTU Aero Engines, Honeywell International Inc., Rostec State Corporation, Lycoming Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Turbine Engine Market Strategic Shifts
Propulsion architecture decisions are increasingly dictated by lifecycle carbon accounting rather than thrust-to-weight optimization alone, forcing simultaneous advances in combustion efficiency, materials science, and digital monitoring infrastructure.
Ceramic matrix composites are migrating from exhaust nozzle applications to high-pressure turbine shrouds and combustor liners. These silicon carbide-reinforced materials withstand temperatures three hundred degrees Celsius above nickel superalloy limits. Narrow-body engine programs at Airbus and Boeing suppliers are adopting CMC components to reduce cooling airflow requirements and improve thermal efficiency.
REACH restrictions on hexavalent chromium surface treatments are compelling coating technology transitions across European supply chains. The ECHA authorization list blocks traditional corrosion protection processes for compressor and turbine hardware. German and French engine component suppliers are accelerating plasma-sprayed aluminum alternatives and vapor-deposition techniques to maintain export eligibility.
Power-by-the-hour contracts are fragmenting as lessors and low-cost carriers demand unbundled maintenance options. Traditional bundled service agreements that wrapped spares, labor, and technical support into per-flight-hour fees face displacement from itemized procurement. Southeast Asian budget airlines are driving this shift, negotiating direct component purchases and third-party labor separately to reduce total cost of ownership.
Aircraft Turbine Engine Market Segmentation
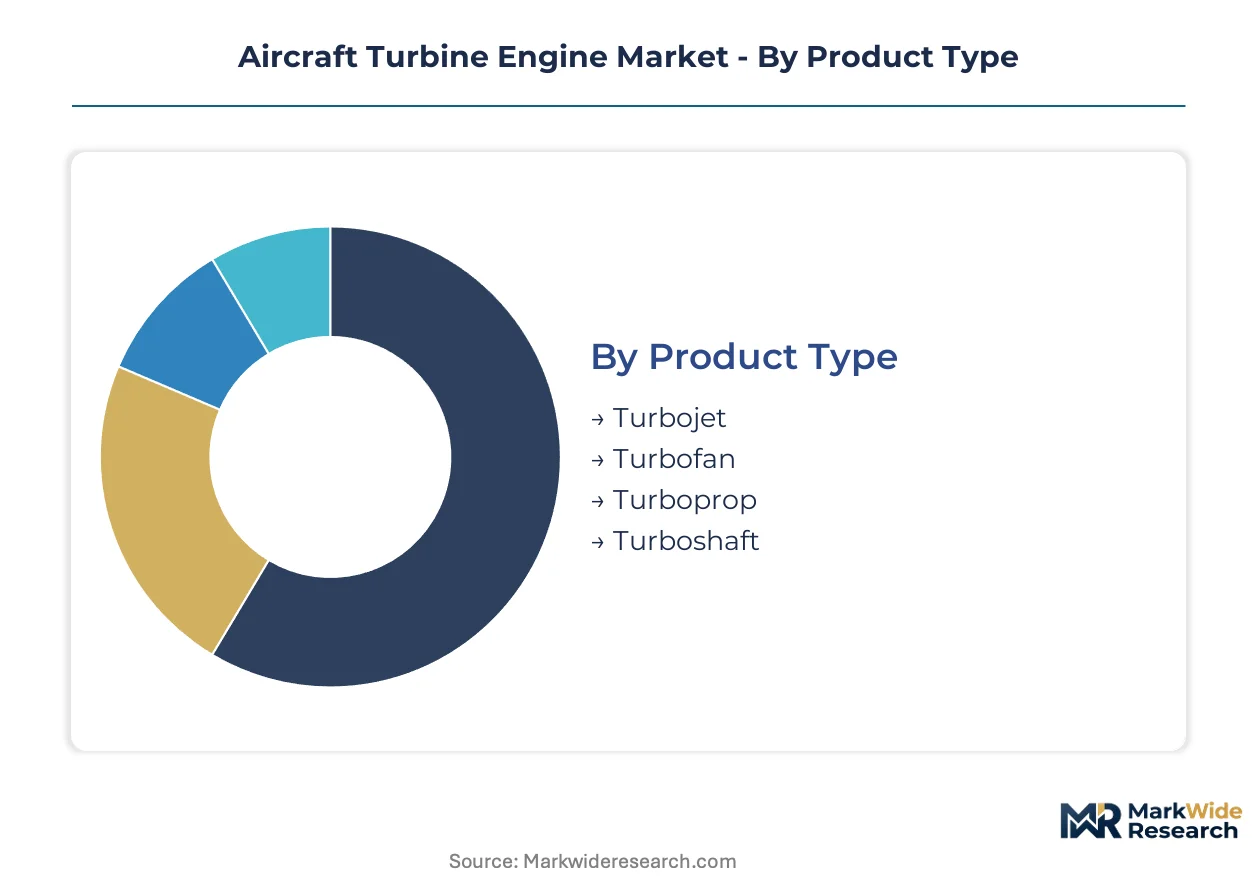
Engine architecture choices cascade through fleet economics, maintenance infrastructure, and regulatory compliance pathways. Segmentation reveals how propulsion technology maps to operational requirements across fixed-wing and rotary-wing platforms.
Product Type:
Cost tier separation across propulsion architectures determines capital deployment patterns and aftermarket revenue longevity for OEMs and service networks.
- Turbofan:High-bypass configurations dominate commercial transport with pressure ratios exceeding 40:1 in modern designs. Demand concentrates in narrow-body fleet expansions across China and India, where airlines prioritize fuel efficiency gains over upfront acquisition premiums.
- Turboprop:Gas turbine powerplants driving propellers retain structural importance in regional connectivity below 1,500 nautical miles. Short-field operations in Southeast Asia and sub-Saharan Africa sustain procurement volumes despite hybrid-electric substitution threats.
- Turbojet:Pure jet thrust generation without bypass airflow serves supersonic military applications and legacy combat aircraft retrofits.
- Turboshaft:Shaft-power delivery optimized for helicopter main rotors and auxiliary power units across rotary-wing fleets.
Turbofan holds installed capacity. Turboprop is rotating up the share rankings in regional connectivity segments.
Application:
Operational intensity and duty cycles vary dramatically across mission profiles, dictating engine life management and overhaul scheduling.
- Commercial Transport:Scheduled airline operations accumulate high flight hours with predictable load factors. Narrow-body deployments in India and China concentrate procurement around geared turbofan architectures certified to ICAO Annex 16 Volume IV emissions thresholds.
- Military Aviation:Combat maneuverability requirements prioritize thrust-to-weight ratios over thermal efficiency. Turbojet and low-bypass turbofan designs serve fighter programs where supersonic performance dictates architecture selection.
- Civil Aviation:General aviation and utility operations span diverse power requirements from single-engine trainers to agricultural aircraft.
- Business Aviation:Corporate jet fleets demand compact high-thrust engines with rapid spool-up characteristics for altitude flexibility.
Commercial Transport anchors volume procurement. Military Aviation is climbing the fastest in technology development intensity.
End User:
Customer type determines procurement channel structure, from OEM-direct fleet agreements to fragmented third-party maintenance sourcing.
- Airlines:Network carriers and low-cost operators negotiate power-by-the-hour contracts or unbundled component procurement. Southeast Asian budget airlines are driving itemized maintenance agreements to reduce total cost of ownership.
- Aircraft Manufacturers:Airframe OEMs at Airbus and Boeing source propulsion systems through long-term sole-source agreements with engine primes.
- Military Forces:Defense procurement agencies specify mission-tailored performance requirements with sovereign maintenance infrastructure obligations.
- Maintenance Providers:Independent MRO networks and parts brokers are fragmenting traditional OEM-captive aftermarket channels.
Airlines hold installed capacity. Maintenance Providers are gaining share fastest in aftermarket revenue capture.
Fuel Type:
Energy source certification status determines retrofit eligibility and emissions compliance pathways across existing fleet powerplants.
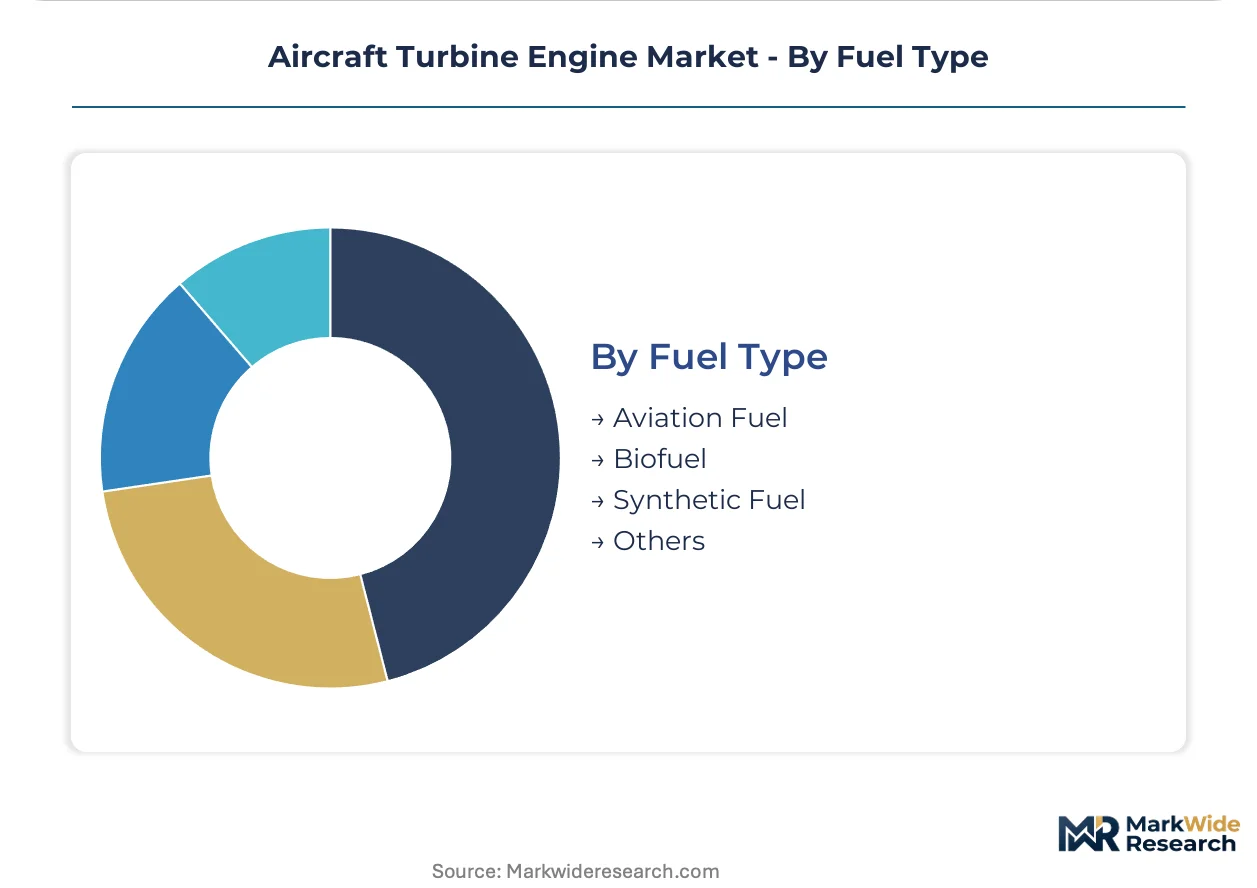
- Aviation Fuel:Conventional Jet A and Jet A-1 kerosene formulations remain the baseline for turbine engine certification and warranty coverage.
- Biofuel:Hydroprocessed esters and fatty acids meeting ASTM D7566 standards enable drop-in compatibility with existing combustion hardware.
- Synthetic Fuel:Fischer-Tropsch and power-to-liquid paraffinic kerosene variants require combustion system modifications for higher blend ratios.
- Others:Emerging alcohol-to-jet and sugar-to-jet pathways await full certification for commercial deployment.
Aviation Fuel holds installed capacity. Synthetic Fuel is expanding most quickly in certification pipeline investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ICAO's Carbon Offsetting and Reduction Scheme for International Aviation is reshaping procurement priorities across national aviation authorities. Fleet operators in major markets face accelerated replacement timelines for powerplants that fail emissions thresholds. This regulatory pressure concentrates investment in three distinct geographies where OEM infrastructure and MRO capacity anchor regional demand patterns.
United States
The FAA enforces airworthiness standards that extend certification timelines for new engine programs. EPA regulations on aircraft greenhouse gas emissions align with ICAO Annex 16 Volume IV, forcing domestic carriers toward fuel-efficient turbofan architectures. Connecticut and Ohio host precision-cast turbine blade foundries where specialty alloy supply chains face input cost volatility.
China
Commercial carriers are scaling narrow-body fleet orders to capture rebounding domestic passenger traffic. The Civil Aviation Administration of China implements emissions performance thresholds that accelerate retirement of older engine generations. Shanghai and Xi'an anchor MRO infrastructure development where maintenance capacity lags behind fleet expansion rates.
Germany
EASA certification requirements and EU Green Deal disclosure obligations extend compliance through supply chain tiers. REACH restrictions on hexavalent chromium surface treatments compel coating technology transitions for compressor hardware. Munich and Hamburg concentrate engine component suppliers accelerating plasma-sprayed aluminum alternatives for export eligibility.
India
Low-cost carriers drive unbundled maintenance agreements to reduce total cost of ownership across expanding single-aisle deployments. The Directorate General of Civil Aviation enforces airworthiness standards that dictate retrofit timelines for existing powerplants. Delhi and Mumbai face MRO infrastructure gaps where independent service providers can displace OEM-captive networks.
United Kingdom
Defense procurement agencies specify mission-tailored performance requirements with sovereign maintenance infrastructure obligations. The Civil Aviation Authority enforces stringent emissions certification standards that constrain new engine development pathways. Derby and Bristol host metallurgical expertise concentrated among aging workforces where training pipeline gaps threaten repair throughput capacity.
Aircraft Turbine Engine Market Competitive Environment
On the supply side, the industry is consolidated around a tight oligopoly of integrated propulsion system providers. Three strategic archetypes dominate competitive positioning: full-stack OEMs controlling design-through-service lifecycles, specialist component suppliers capturing niche material science applications, and state-affiliated entities serving sovereign defense requirements. Dominant competitive moves include long-term sole-source agreements with airframe manufacturers and geographic expansion of MRO networks into underserved growth markets.
Within the full-stack OEM tier, General Electric Company and Pratt & Whitney exemplify integrated propulsion providers anchoring wide-body and narrow-body fleet deliveries respectively. Rolls-Royce plc occupies a position on ultra-high-thrust segments for next-generation twin-aisle programs. CFM International represents the joint-venture archetype combining complementary manufacturing capabilities across national boundaries. These three anchors illustrate how competitive positioning depends on architectural specialization rather than scale alone.
| Leading Market Players |
|---|
| CFM International |
| General Electric Company |
| Pratt & Whitney |
| Rolls-Royce plc |
| Safran |
| MTU Aero Engines |
| Honeywell International Inc. |
| Rostec State Corporation |
| Lycoming Engines |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on precision-cast nickel superalloy suppliers in the United States and Germany compresses OEM margins and dictates pricing tier spreads across aftermarket and new-engine procurement channels. This concentration forces tiered pricing structures that separate FAA-certified new production from overhaul-eligible surplus inventory, while simultaneously shaping dual-sourcing imperatives in supply chain design.
Pricing Analysis
Certification level creates the primary spread between new-production turbofan engines and overhaul-eligible powerplants. Pricing stratifies across premium OEM-direct fleet agreements, standard independent MRO channel procurement, and economy surplus parts brokerage. Cost compression in the economy tier intensifies as airlines unbundle maintenance packages to reduce total cost of ownership. Low-cost carriers in Southeast Asia exhibit highest price sensitivity, while network carriers prioritizing engine-on-wing time accept premium positioning.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates supply chain risk planning for precision-cast turbine components. Manufacturing concentration centers on Connecticut, Ohio, and Bavaria for nickel-based superalloy foundries, with ceramic matrix composite production scaling in South Carolina and Toulouse. The supply chain draws from specialty alloy feedstock, single-crystal casting capacity, and plasma-spray coating infrastructure. Distribution runs through OEM-captive networks, independent MRO facilities, and parts broker clearinghouses serving lessor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICAO's Carbon Offsetting and Reduction Scheme for International Aviation creates a regulatory inflection that accelerates fleet replacement cycles and expands addressable market for fuel-efficient architectures. This disruption concentrates strategic value in emissions-compliant powerplant portfolios and retrofit-capable service networks.
For Market Incumbents: Build switching-cost moats through long-term service agreements that embed predictive maintenance analytics and SAF-compatible combustion system upgrades. Deepen backward integration into ceramic matrix composite production to secure thermal efficiency advantages against hybrid-electric substitution threats. Anchor capacity in India to capture MRO infrastructure gaps before independent providers consolidate market share. For New Entrants and Emerging Players: Pursue white-space opportunities in third-party MRO networks serving India's expanding narrow-body fleet, where maintenance capacity lags aircraft deliveries by structural margins. Target independent parts brokerage for geared turbofan components as Pratt & Whitney's installed base ages into overhaul-intensive cycles. Establish go-to-market positioning through unbundled component procurement contracts that displace traditional power-by-the-hour bundling. For Investors and Strategic Acquirers: EPA alignment with ICAO Annex 16 Volume IV reshapes the acquisition landscape toward emissions-compliant engine portfolios and SAF-certification capabilities. Long-term viability favors targets with established FAA-EASA dual certification pathways and digital twin infrastructure for predictive maintenance contracting. Monitor ASTM D7566 SAF blend ratio approvals as the signal indicating retrofit demand inflection and aftermarket revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Matrix Composite Scale-Up | CMC migration into high-pressure turbine shrouds enables thermal efficiency gains exceeding nickel superalloy limits. |
| SAF Combustion System Certification | ASTM D7566-compliant modifications capture aftermarket retrofit demand from emissions-driven fleet operators. |
| India MRO Infrastructure Expansion | Independent overhaul facilities displace OEM-captive networks in the fastest-growing narrow-body aviation market. |
| Digital Twin Predictive Maintenance | Physics-based modeling fused with flight-data analytics optimizes engine-on-wing time for airline customers. |
| Geared Turbofan Aftermarket Capture | Power-dense transmission systems entering overhaul cycles sustain long-term service revenue streams. |
Study Parameters
Desk research of FAA type certificate databases, EASA certification filings, and ICAO emissions compliance registries preceded structured interviews with fleet procurement directors, MRO operations executives, and engine program managers at tier-one suppliers. Secondary validation drew from OEM annual disclosures, airline fleet planning documents, and specialty metals trade flow analysis. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Assumptions held fixed include regulatory compliance timelines for ICAO Annex 16 Volume IV, SAF certification pathways under ASTM D7566, and narrow-body fleet expansion rates in China and India. Variables modeled encompass hybrid-electric substitution penetration in regional segments, superalloy input cost volatility, and technician training pipeline throughput. The analytical framework segmented by engine architecture, application intensity, end-user procurement channel, and fuel certification status. CAGRs derived from installed base growth, retirement-replacement ratios, and aftermarket revenue intensity per flight hour.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price trajectories, sovereign aviation subsidy policies, or trade tariff structures on precision-cast components would shift the trajectory. Forecasts reflect these assumptions with explicit acknowledgment that regulatory acceleration or SAF infrastructure delays could compress or extend replacement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
America Aircraft Engines Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Aircraft Ignition System Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Piston Engine Aircraft Market
Aircraft Engine Systems and Services
Gas Turbine Service Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market