
 Turboprop Engine Market | 2026-2036
Turboprop Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Turboprop Engine Market Analysis
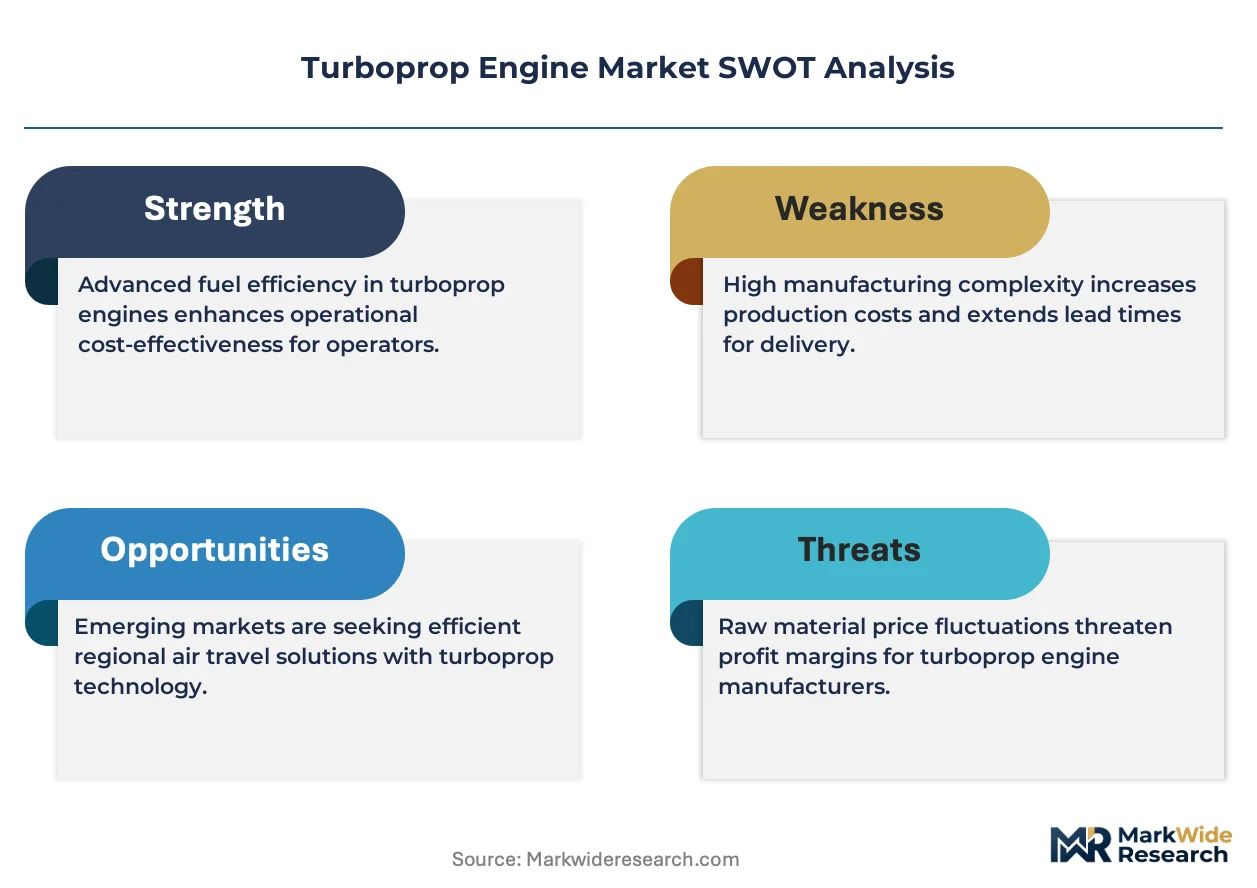
Power-by-the-hour leasing and asset-light operating models is reconfiguring how regional carriers access turboprop capacity without bearing full capital burdens. Pratt & Whitney Canada leverages its dominant PT6 franchise to sustain aftermarket revenue streams across decades of installed base. GE Aerospace anchors its position through integrated digital monitoring systems that reduce unscheduled maintenance for fleet operators.
A turboprop engine combines a gas turbine core with a reduction gearbox driving a propeller, typically operating at power ranges from 500 to over 5,000 shaft horsepower and achieving peak thermal efficiency at altitudes below 25,000 feet. Its primary commercial purpose is delivering superior fuel economy and runway performance for short-haul and low-density routes where jet speeds provide no operational advantage. The single-stage turbine architecture leads in unit volume for regional transport applications, while dual-stage configurations capture premium positioning in military trainer programs requiring higher altitude capability. Variable-pitch propeller technology dominates margin pools as integration complexity with full-authority digital engine controls commands pricing premiums over fixed-pitch alternatives.
The FAA and EASA impose stringent certification standards under Part 33 and CS-E respectively, governing turbine engine endurance, containment, and emissions thresholds that dictate product development timelines and market entry costs. ICAO Annex 16 noise standards and the EU Green Deal aviation emissions framework are accelerating manufacturer investment in hybrid-electric turboprop architectures and sustainable aviation fuel compatibility. Stakeholders must monitor how regulatory divergence between FAA and EASA certification pathways for novel propulsion concepts affects platform development economics and fleet standardization decisions.
Market Dynamics
ICAO Annex 16 noise standards and the EU Green Deal aviation emissions framework are compressing product development cycles and forcing manufacturers toward hybrid-electric architectures and sustainable aviation fuel compatibility before 2030.
Growth Catalysts
- Archipelagic Route Economics:Indonesia's geography creates structural demand for turboprop efficiency over jet alternatives on sub-500 nautical mile sectors where fuel burn differentials dominate operating costs.
- Power-by-the-Hour Leasing:Asset-light operating models allow regional carriers to access turboprop capacity without full capital burden, expanding addressable fleet operator base beyond balance-sheet-strong incumbents.
- FAA Part 33 Certification Pathways:Streamlined supplemental type certificate processes for engine upgrades enable faster technology insertion into existing installed bases, accelerating aftermarket revenue capture.
Market Restraints
- Turbine Blade Alloy Concentration:Single-source supply of nickel-based superalloys from concentrated metallurgical processors creates input cost volatility and delivery risk for hot section components.
- Jet Bridge Infrastructure Bias:Airport capital planning prioritizes jet-compatible gate configurations, forcing turboprop operators into remote stand positions that degrade passenger experience and operational efficiency.
- Speed-Altitude Performance Ceiling:Fixed-geometry propeller systems impose hard limits on cruise efficiency above 25,000 feet, excluding turboprops from contested airspace optimization and longer sector economics.
Strategic Opportunities
- Hybrid-Electric Convergence:Integration of battery-electric boost systems with conventional gas turbine cores opens new mission profiles for 19-50 seat aircraft on sub-300 mile routes with zero-emission terminal operations.
- Southeast Asian Fleet Renewal:Aging Fokker 50 and ATR 42-300 retirements in Vietnam, Philippines, and Myanmar create replacement demand for next-generation turboprop platforms with 15% fuel efficiency improvement.
- Sustainable Aviation Fuel Mandates:EU Green Deal aviation emissions frameworks and ReFuelEU Aviation regulations create regulatory tailwind for turboprop OEMs whose powerplants achieve higher SAF blend compatibility than high-bypass turbofans.
Industry Challenges
- Full-Authority Digital Engine Control Integration:Variable-pitch propeller systems demand specialized software engineering talent scarce in legacy mechanical hydromechanical control supply chains, extending development timelines.
- Dual Certification Burden:Divergent FAA Part 33 and EASA CS-E validation requirements for novel propulsion architectures force redundant test campaigns, inflating market entry costs by 20-40%.
- Legacy Fleet Interoperability:Ground support equipment and maintenance training infrastructure locked into PT6 and TPE331 architectures creates switching friction for new engine entrants.
Report Scope
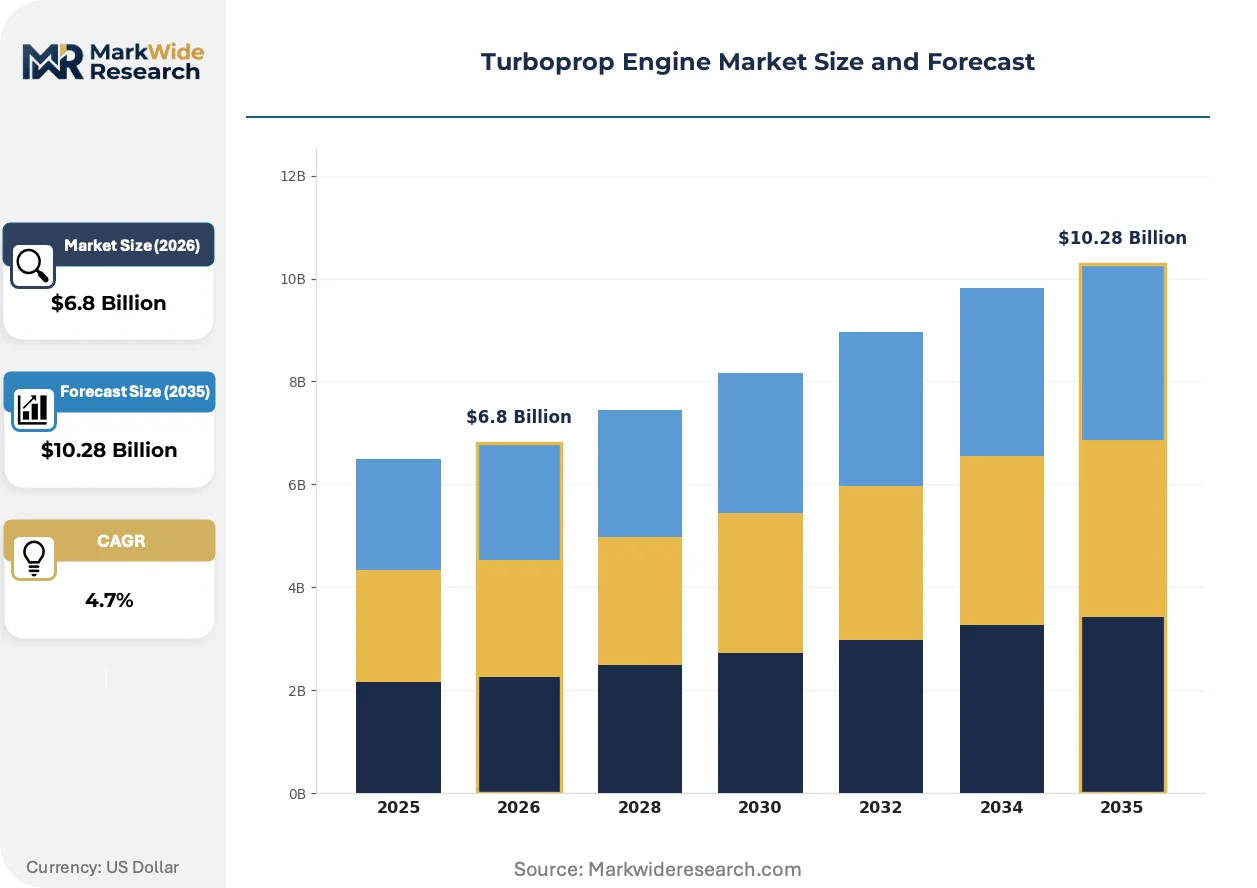
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turboprop Engine Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PT6, TPE331, PW127, A320 Engine End User: Commercial Aviation, Military, General Aviation, Cargo Application: Regional Transport, Training, Agricultural Aviation, Air Ambulance Technology: Single-Stage Turbine, Dual-Stage Turbine, Variable-Pitch Propeller, Fixed-Pitch Propeller |
| Companies Covered | Honeywell International, Lockheed Martin, Pratt & Whitney Canada, IHI Corporation, Rotax Aircraft Engines, GE Aerospace, Rolls-Royce, PBS Aerospace, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turboprop Engine Market Emerging Trajectories
Propulsion architecture is hybridizing across multiple technology fronts simultaneously, with electric assist systems, advanced thermodynamic cycles, and digital monitoring converging to redefine performance benchmarks and aftermarket economics for regional aviation.
Hybrid-electric turboprop propulsion is hybridizing gas turbine cores with battery-electric boost modules to enable 30-50% fuel reduction on climb segments. Regional carriers in Scandinavia and the Pacific Northwest are piloting retrofit configurations for existing 19-seat airframes. This convergence is compressing the competitive window for pure-turbine architectures below 1,000 shaft horsepower.
EU Green Deal aviation emissions frameworks and ReFuelEU Aviation mandates are forcing engine manufacturers to redesign fuel system architectures for 100% sustainable aviation fuel compatibility by 2030. Hot section coatings and elastomeric seals require reformulation to prevent degradation from aromatic content variation. Turboprop OEMs with earlier SAF certification timelines are capturing preferred supplier status with European lessors.
Regional carriers are unbundling engine maintenance from airframe leases, creating direct contractual relationships with OEM aftermarket networks. This disintermediation of traditional lessor bundled service packages concentrates fleet data access with engine manufacturers. Indonesia and the Philippines exhibit the fastest migration toward this model as archipelagic operators prioritize uptime guarantees over capital cost minimization.
Turboprop Engine Market Segmentation
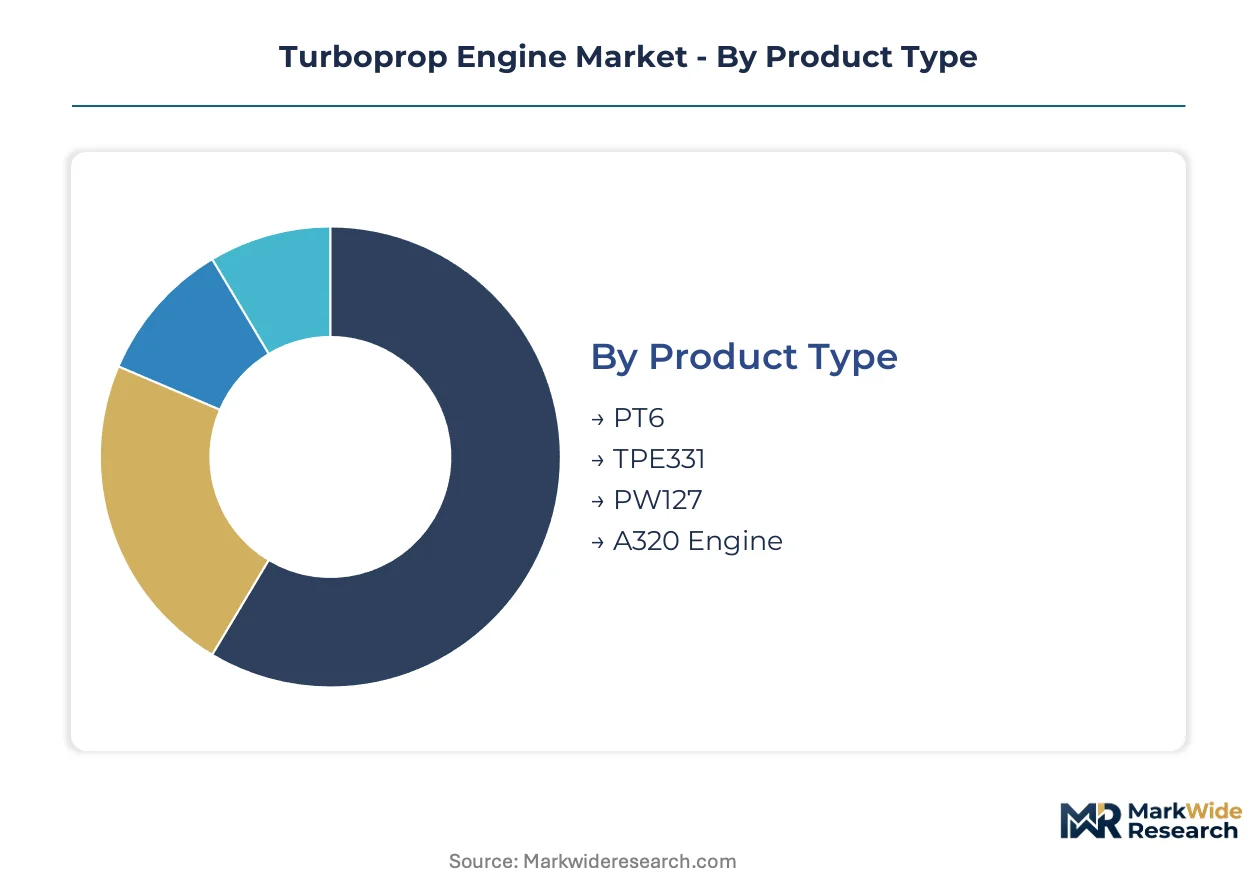
Turboprop engine segmentation reveals how powerplant architecture, operator economics, and mission profiles intersect to determine procurement priorities. Manufacturers configure product portfolios across these dimensions to capture aftermarket lifetime value and fleet standardization benefits.
Product Type:
Cost tier stratification across engine families reflects installed base longevity, parts commonality, and aftermarket service network density.
- PT6:Pratt & Whitney Canada's single-shaft turboprop dominates regional transport with 500-1,940 shaft horsepower range and reverse-flow combustor design. Indonesia's archipelagic carriers standardize on PT6A-60/67 series for ATR 42/72 fleets, leveraging power-by-the-hour contracts that shift maintenance risk to OEM service networks.
- TPE331:Honeywell's direct-drive architecture eliminates reduction gearbox weight for agricultural and special-mission applications. Myanmar's aging Fokker 50 operators face replacement decisions as Garrett legacy support contracts expire, creating conversion opportunities to newer PT6 or PW127 alternatives.
- PW127:Pratt & Whitney Canada's integrated propeller system targets 50-seat regional aircraft with 2,750 shaft horsepower output and six-blade composite propeller.
- A320 Engine:Derivative turboprop adaptations for narrow-body conversion programs serve cargo operators seeking runway performance advantages over pure-jet alternatives.
PT6 commands the established base. The steepest expansion runs through PW127 as ATR fleet renewals concentrate in Southeast Asia.
End User:
Application context determines procurement specifications, with commercial operators prioritizing fuel efficiency and military buyers emphasizing altitude performance.
- Commercial Aviation:Regional airlines operating 30-78 seat aircraft constitute the volume anchor, with Indonesian carriers like Garuda Indonesia's Citilink subsidiary driving ATR 72-600 deliveries. FAA Part 33 certification requirements and EASA CS-E validation create dual regulatory burden for new platform entry.
- Military:Trainer programs and maritime patrol missions demand dual-stage turbine architectures for high-altitude capability. The Philippines' ongoing fleet modernization prioritizes turboprop platforms for archipelagic sovereignty patrols where jet fuel logistics constrain operational reach.
- General Aviation:Owner-operated aircraft and fractional ownership programs concentrate demand in 500-1,000 shaft horsepower single-engine configurations.
- Cargo:Express freight operators exploit turboprop runway performance for secondary airport access, with dedicated freighter conversions of passenger airframes.
Commercial Aviation holds the revenue concentration. Cargo is climbing the fastest as e-commerce logistics reshape regional air freight networks.
Application:
Mission profile dictates engine specification, with stage length, payload, and field performance requirements filtering available architectures.
- Regional Transport:Scheduled passenger service on 200-500 nautical mile sectors exploits turboprop fuel burn advantages below jet crossover ranges. Vietnam's expanding domestic network favors ATR 72 operations from short-runway airports at Da Lat and Con Dao.
- Training:Military pilot instruction programs require dual-stage turbines for spin recovery and high-altitude aerobatics. Thailand's air force trainer procurement evaluates turboprop platforms against jet alternatives for cost-per-flight-hour economics.
- Agricultural Aviation:Low-altitude crop-dusting missions prioritize power-to-weight ratio and rapid throttle response for terrain avoidance.
- Air Ambulance:Medical evacuation configurations demand rapid engine start and reliability certification for single-pilot IFR operations.
Regional Transport anchors fleet volumes. Air Ambulance is gaining share fastest as healthcare infrastructure investment extends aeromedical reach in island nations.
Technology:
Thermodynamic cycle architecture and propeller integration determine efficiency trade-offs across altitude and speed envelopes.
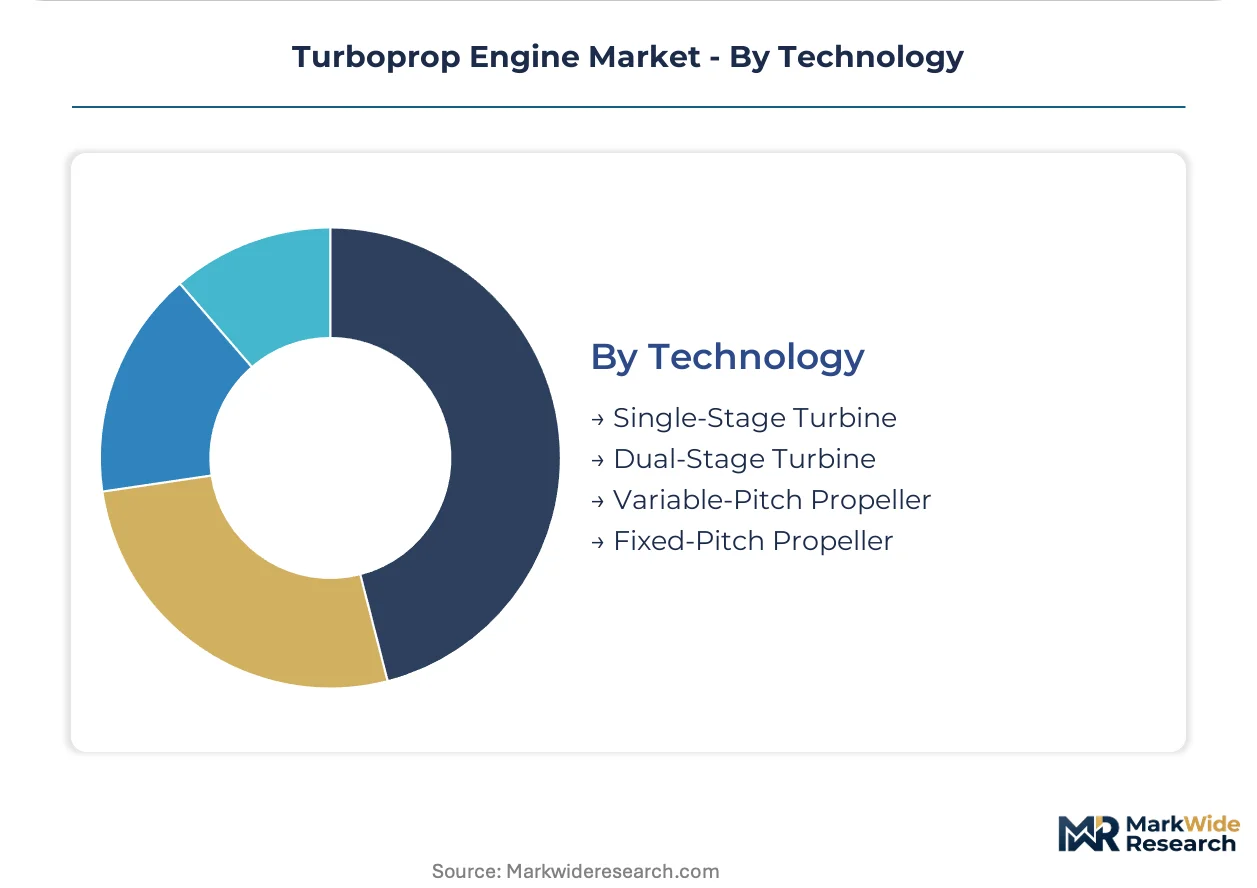
- Single-Stage Turbine:Axial-centrifugal compressor designs dominate commercial regional transport with simplified maintenance and lower parts count. Indonesian MRO providers concentrate capability on PT6 single-stage architectures, creating path dependency for fleet renewal decisions.
- Variable-Pitch Propeller:Full-authority digital engine control integration enables constant-speed operation across flight phases, optimizing propeller efficiency for climb, cruise, and descent profiles. EASA certification timelines for new FADEC software releases constrain technology insertion rates.
- Dual-Stage Turbine:Two-spool configurations extract additional work from exhaust gases for high-altitude military applications.
- Fixed-Pitch Propeller:Mechanical simplicity serves cost-constrained training and agricultural markets where altitude variation is limited.
Single-Stage Turbine retains the installed base dominance. Variable-Pitch Propeller shows the steepest expansion trajectory as digital control integration commands pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across turboprop engine markets. Indonesia and the Philippines import complete powerplants while building MRO capabilities. Canada and the United States maintain trade surpluses through Pratt & Whitney Canada and GE Aerospace production networks.
Indonesia
Archipelagic route structures at Garuda Indonesia's Citilink subsidiary drive ATR 72-600 fleet expansion. The Directorate General of Civil Aviation enforces ICAO Annex 16 noise compliance timelines that accelerate fleet renewal decisions. Batam island hosts expanding MRO clusters where PT6 overhaul capability concentrates among local joint ventures.
United States
General aviation manufacturing in Wichita and Wichita-adjacent corridors sustains demand for 500-1,000 shaft horsepower configurations. FAA Part 33 certification pathways enable streamlined supplemental type certificates for engine upgrades. The Dallas-Fort Worth aerospace corridor anchors aftermarket service network density for North American operators.
Canada
Pratt & Whitney Canada's Longueuil headquarters anchors PT6 production serving global regional airline fleets. Transport Canada certification alignment with FAA Part 33 reduces dual validation burdens for North American market entry. Montreal's aerospace cluster concentrates turboprop propulsion engineering talent and digital control system development.
Philippines
Aging Fokker 50 retirements create replacement demand for next-generation turboprop platforms across Cebu Pacific's regional subsidiary. The Civil Aviation Authority of the Philippines implements ICAO-aligned emissions monitoring that favors fuel-efficient architectures. Clark Freeport Zone hosts emerging MRO investments targeting archipelagic operator uptime requirements.
France
Safran's Toulouse operations support ATR aircraft propulsion integration for European regional carriers. EASA CS-E validation requirements and EU Green Deal aviation emissions frameworks accelerate SAF-compatible engine development. The Occitanie aerospace cluster concentrates composite propeller manufacturing and full-authority digital engine control software engineering.
Turboprop Engine Market Vendor Landscape
On the supply side, the industry is consolidated around a handful of integrated propulsion system architects with decades-long installed base lock-in. Pratt & Whitney Canada and GE Aerospace anchor the commercial regional transport segment through differentiated approaches to aftermarket capture. Honeywell International and Rolls-Royce occupy specialized niches in military trainer and maritime patrol applications. Competitive moves center on power-by-the-hour contract expansion and hybrid-electric architecture partnerships rather than direct platform competition.
Within the established-engine archetype, Pratt & Whitney Canada and GE Aerospace exemplify divergent strategies for sustaining aftermarket revenue across multi-decade fleet lifecycles. Honeywell International occupies a position in legacy platform support where Garrett-era TPE331 architectures create conversion opportunities. Safran represents the European propulsion integration specialist competing through ATR airframe partnerships rather than standalone engine sales.
| Leading Market Players |
|---|
| Honeywell International |
| Lockheed Martin |
| Pratt & Whitney Canada |
| IHI Corporation |
| Rotax Aircraft Engines |
| GE Aerospace |
| Rolls-Royce |
| PBS Aerospace |
| Safran |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on nickel-based superalloy suppliers for hot section turbine blades dictates both pricing tier spreads and supply chain shape across the turboprop engine market. Input cost volatility from concentrated metallurgical processors cascades through OEM pricing structures while forcing manufacturers toward long-term offtake arrangements that reshape procurement relationships.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the turboprop engine market. Certification grade under EASA CS-E and FAA Part 33 pathways drives price differentiation alongside volume scale for fleet operators. Cost compression in the economy tier is intensifying because archipelagic carriers in Indonesia and the Philippines prioritize capital cost minimization over performance specifications. Regional airlines with power-by-the-hour contracts exhibit the least price sensitivity, while owner-operated agricultural operators demonstrate acute sensitivity to upfront engine acquisition costs.
Supply Chain Analysis
Specialized foundries in the United States, Canada, and France hold concentrated capacity for precision-cast turbine blades and reduction gearbox housings. Manufacturing draws from nickel-based superalloys, titanium alloys, and composite propeller resins as critical raw material inputs. Single-source vulnerability for hot section coatings creates exposure to aromatic content variations from sustainable aviation fuel mandates. Distribution runs through OEM-direct service networks and authorized MRO joint ventures in Southeast Asian archipelagic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fleet operators as regional carrier consolidation in Southeast Asia concentrates procurement leverage. Fleet standardization decisions by Indonesian and Philippine operators now dictate platform viability more than manufacturer R&D investment cycles.
For Market Incumbents: Build installed base lock-in through power-by-the-hour contract expansion across ATR fleet renewals in Vietnam and Myanmar. Defensive moves center on PT6 architecture backward integration into hot section component manufacturing and Transport Canada-FAA harmonized certification investments that raise rival market entry costs. Hybrid-electric architecture partnerships with battery system specialists address emerging substitute technology threats from pure-electric regional aircraft programs. For New Entrants and Emerging Players: Mid-market cargo conversion programs in the United States represent the most penetrable entry point for turboprop engine alternatives. Agricultural aviation operators in Brazil and Australia seeking Garrett TPE331 replacements offer secondary white-space opportunity. Go-to-market positioning through aftermarket parts commonality claims and accelerated EASA CS-E validation timelines captures fleet operator attention. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors hybrid-electric propulsion specialists with established airframe partnerships. Long-term viability over the coming decade hinges on SAF compatibility certification timelines and archipelagic operator fleet data access. Acquisition target archetypes include digital engine control software firms and composite propeller manufacturers. Watch for ICAO Annex 16 noise standard revision announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Architecture Partnership | GE Aerospace battery integration agreements with Scandinavian regional carriers validate propulsion convergence roadmaps. |
| SAF Compatibility Certification | Pratt & Whitney Canada 100% sustainable aviation fuel approval secures preferred supplier status with EU lessors under ReFuelEU mandates. |
| Power-by-the-Hour Contract Expansion | Indonesian MRO joint ventures in Batam concentrate fleet data access and aftermarket revenue capture with archipelagic operators. |
| Digital Engine Control Integration | Safran FADEC software development in Toulouse commands pricing premiums over mechanical hydromechanical alternatives. |
| Regional MRO Capability Buildout | Clark Freeport Zone investments target Philippine archipelagic operator uptime requirements and reduce OEM service network dependency. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regional airline fleet managers, MRO facility directors, and propulsion system procurement leads at lessor networks. Secondary validation drew from FAA Part 33 certification filings, EASA CS-E validation databases, Transport Canada type certificate records, and ICAO Annex 16 noise compliance documentation. Bottom-up fleet operator demand modeling triangulated against top-down OEM production and aftermarket revenue disclosures.
Calibration across the projection horizon employed multi-segment growth modeling across powerplant architecture, end-use application, and regional regulatory cluster dimensions. CAGRs were derived from installed base retirement schedules, fleet renewal order backlogs, and hybrid-electric technology insertion timelines. Industry-specific inputs included archipelagic route frequency data from Indonesian and Philippine civil aviation authorities and sustainable aviation fuel blend mandate implementation trajectories under EU Green Deal frameworks.
Practitioners should monitor ICAO noise standard revision timelines and nickel superalloy supply contract renegotiations for early signals of forecast revision. Assumptions underlying projections reflect current regulatory compliance deadlines and fleet operator power-by-the-hour adoption curves. Quarterly review of ATR delivery schedules and Southeast Asian MRO joint venture formation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Rocket Propulsion Market
Aircraft Engine Systems and Services
Aircraft Lubricant Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Helicopter Engine Market
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Angle of Attack Sensor Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Nacelle Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
General Aviation Engines Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market