
 Commercial Aircraft Turbine Blades and Vanes Market | 2026-2036
Commercial Aircraft Turbine Blades and Vanes Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Turbine Blades and Vanes Market Insights
REACH is rebalancing the cost-of-entry calculus for European suppliers of nickel-based superalloy castings. Precision Castparts Corp. leverages captive vacuum investment casting capacity across multiple US sites to sustain margin control on complex airfoil geometries. MTU Aero Engines AG anchors its competitive position through deep specialization in low-pressure turbine module assembly for both Airbus and Boeing platforms.
Commercial Aircraft Turbine Blades and Vanes are precision-engineered hot-section components cast from nickel-based superalloys or titanium aluminides, typically operating at gas-path temperatures exceeding metal melting points through internal cooling channels and ceramic thermal barrier coatings. Their primary purpose is converting thermal energy from combusted fuel into rotational mechanical work that drives compressors and fan sections. Single crystal blades command the dominant share of OEM value pools due to their elimination of grain boundaries and superior creep resistance at extreme temperatures. Ceramic matrix composites represent the fastest-growing material technology segment as airframers pursue weight reduction targets and extended on-wing intervals.
FAA airworthiness directives, EASA certification specifications, and EPA engine emissions standards collectively dictate alloy compositions, coating chemistries, and repair interval documentation requirements across the supplier base. These frameworks compel manufacturers to maintain dual-certified production lines and traceable metallurgical records for every serialized casting. Stakeholders must monitor how ICAO carbon offset mechanisms and emerging sustainable aviation fuel compatibility standards redirect R&D spending toward combustion system architectures that tolerate higher peak temperatures without degrading blade and vane life.
Market Dynamics
Narrowbody fleet renewal programs across Asia-Pacific carriers are compressing procurement cycles for high-pressure turbine components while FAA and EASA emissions mandates force simultaneous material recertification.
Growth Catalysts
- FAA emissions mandates:Tightening NOx and particulate standards force OEMs to redesign combustion architectures, accelerating replacement demand for thermal barrier-coated airfoils that tolerate higher peak temperatures without creep degradation.
- Ceramic matrix composites:CMC vane platforms cut component weight by one-third versus nickel superalloys, enabling extended on-wing intervals that reduce airline MRO spend and align with airframer fuel burn targets.
- China's MRO hub expansion:Domestic narrowbody final assembly lines at Tianjin and Zhoushan localize blade sourcing requirements, creating captive demand for precision-cast high-pressure components within the country's expanding repair network.
Market Restraints
- Rhenium supply concentration:Over 80% of global rhenium output derives from Chilean copper-molybdenum byproduct recovery, exposing single-crystal superalloy casters to geopolitical disruption and price volatility in strategic alloying elements.
- Dual-certified production lines:FAA and EASA maintain non-harmonized qualification pathways for thermal barrier coating chemistries, forcing suppliers to duplicate metallurgical testing and documentation systems for identical part numbers.
- Electron beam physical vapor deposition:EB-PVD coating chambers require 18-24 month lead times for capital equipment, constraining capacity expansion for yttria-stabilized zirconia topcoats that protect rotating airfoils from oxidation.
Strategic Opportunities
- India's PLI scheme for aerospace:Production-linked incentives for precision manufacturing attract foreign casting houses to establish vacuum investment foundries serving both domestic narrowbody programs and export MRO contracts.
- Additive repair of tip sections:Directed energy deposition restores eroded blade geometries without full component replacement, opening service revenue streams at overhaul shops previously limited to coating reapplication.
- Sustainable aviation fuel compatibility:Higher combustion temperatures from SAF blends accelerate thermal barrier coating degradation, expanding addressable market for next-generation ceramic topcoats with improved thermal gradient resistance.
Industry Challenges
- Single-crystal solidification technicians:Bridgman furnace operation and grain selector alignment require tacit expertise accumulated over decades, with retirement waves at US and European foundries outpacing apprenticeship pipeline replenishment.
- Traceable metallurgical records:FAA airworthiness directives mandate serialized documentation of every casting's thermal history and chemical composition, forcing legacy suppliers to digitize paper-based quality systems spanning thirty-plus years of production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Turbine Blades and Vanes Market |
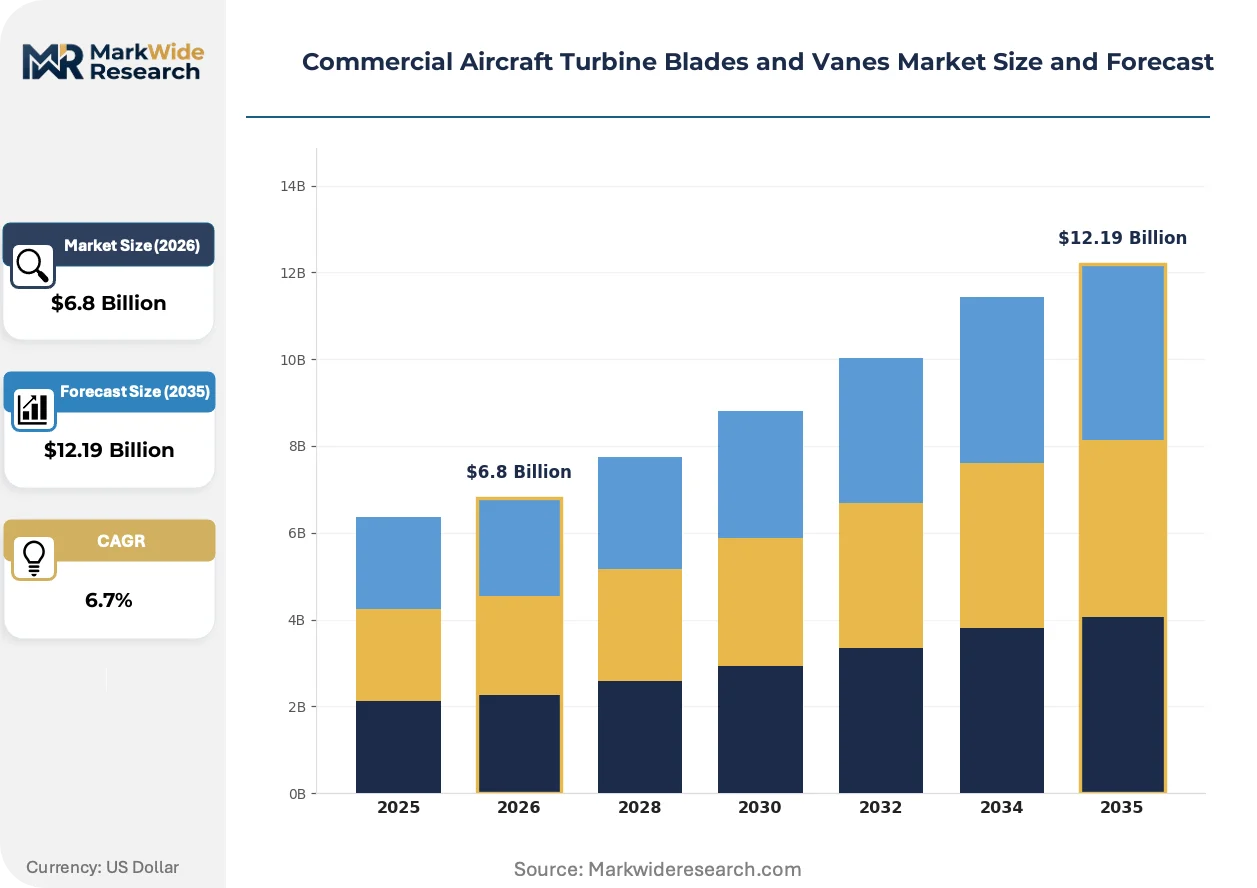
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal Blades, Directionally Solidified Vanes, Coated Blades, Metal Matrix Composites, Ceramic Matrix Composites Material Technology: Nickel-Based Superalloys, Titanium Aluminides, Thermal Barrier Coatings, Ceramic Coatings, Solid Solution Alloys Application: High-Pressure Turbines, Low-Pressure Turbines, Combustor Liners, Compressor Sections, Exhaust Systems End User Industry: Airline Operators, Maintenance Repair Organizations, Aircraft Manufacturers, Defense Contractors, Leasing Companies |
| Companies Covered | GKN Aerospace Limited, MTU Aero Engines AG, Precision Castparts Corp., Kawasaki Heavy Industries, Ltd., Carpenter Technology Corporation, GE Aviation, Pratt & Whitney, Siemens Energy AG, Rolls-Royce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Turbine Blades and Vanes Market Trends and Innovations
Additive manufacturing is penetrating repair networks while thermal barrier coating architectures evolve toward multilayer environmental barrier systems. Demand-side procurement patterns are consolidating around airframer-direct contracts.
Environmental barrier coatings are unifying the previously separate functions of oxidation protection and thermal insulation in a single ceramic layer stack. GE Aerospace and Pratt & Whitney are qualifying EBC systems for next-generation turbine vanes exposed to moist combustion environments. This unification eliminates the weight penalty of legacy dual-layer coatings while extending component life in high-humidity operational profiles.
REACH is restricting hexavalent chromium in conversion coating chemistries used for bond coat surface preparation. European suppliers must reformulate pretreatment processes for thermal barrier adhesion layers without carcinogenic chrome species. Nickel-based superalloy casters in Germany and France are accelerating plasma electrolytic oxidation trials to maintain EASA certification timelines.
Power-by-the-hour contracts are compressing supplier-airline relationships into airframer-mediated frameworks. Airlines now procure blade and vane replacements through OEM material repair agreements rather than independent MRO channel sourcing. This consolidation is most advanced among LCC fleets in Southeast Asia operating under standardized narrowbody maintenance programs.
Commercial Aircraft Turbine Blades and Vanes Market Segmentation
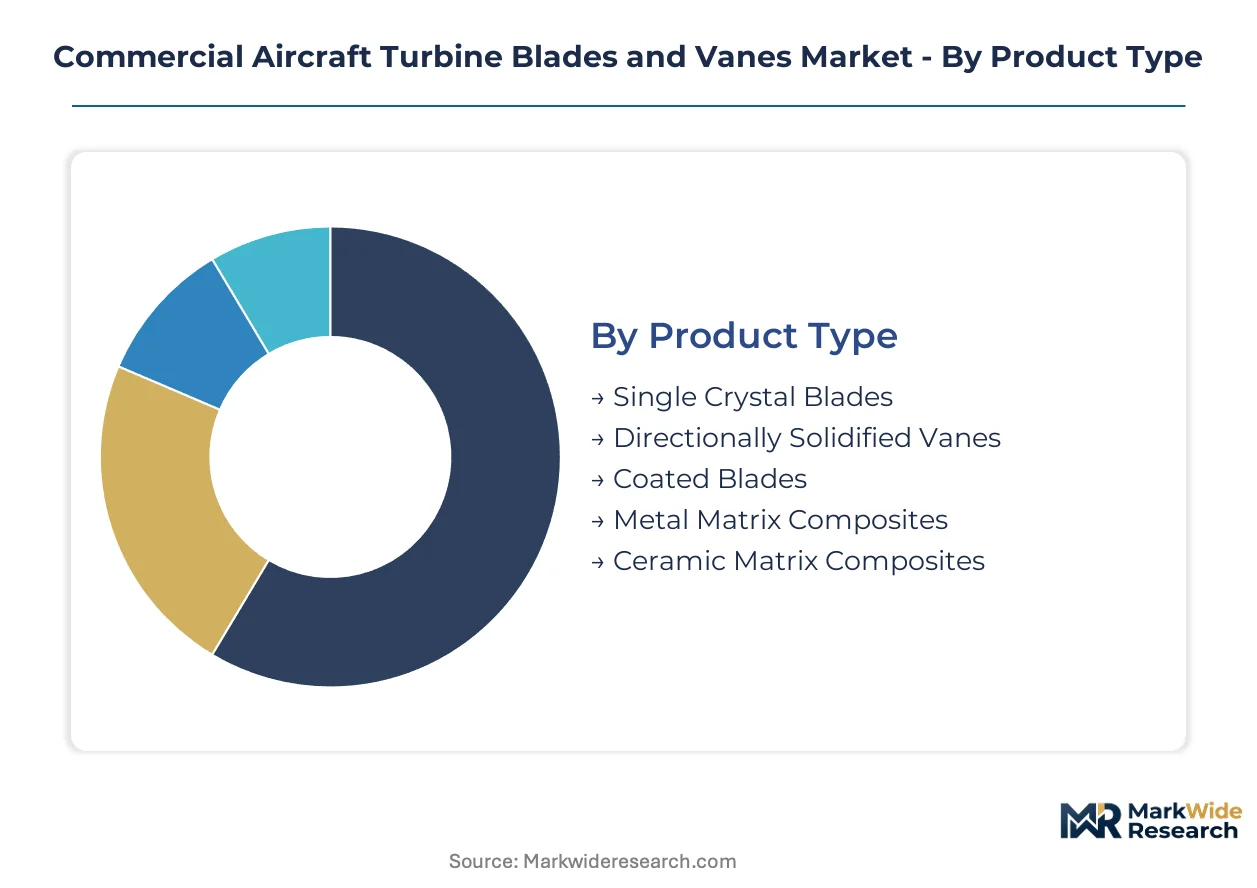
Segmentation in the Commercial Aircraft Turbine Blades and Vanes Market reveals how material science investments, thermal management requirements, and procurement channel structures fragment value capture across the supply chain. Each dimension exposes different competitive moats: casting complexity, coating intellectual property, or airframer-direct contract leverage.
Product Type:
Volume concentration sits with legacy castings, while premium economics accrue to single-crystal architectures and ceramic matrix innovations that extend on-wing intervals.
- Single Crystal Blades:Elimination of grain boundaries through Bridgman furnace solidification delivers superior creep resistance at gas-path temperatures exceeding metal melting points. Demand concentrates in high-pressure turbine stages of next-generation narrowbody engines, where FAA emissions mandates force higher peak operating temperatures without life degradation. Airlines operating under power-by-the-hour contracts prioritize these components for reduced shop visit frequency.
- Ceramic Matrix Composites:Silicon carbide fiber-reinforced ceramic matrices cut component weight by one-third versus nickel superalloys while maintaining structural integrity at extreme thermal gradients. GE Aerospace and Pratt & Whitney are qualifying CMC vane platforms for moist combustion environments, with China's domestic narrowbody programs accelerating localized sourcing requirements.
- Directionally Solidified Vanes:Columnar grain structures align along the primary stress axis, balancing cost against performance in intermediate-pressure turbine stages.
- Coated Blades:Dual-layer thermal barrier systems combine metallic bond coats with yttria-stabilized zirconia topcoats for oxidation protection.
- Metal Matrix Composites:Discontinuous ceramic reinforcement in aluminum or titanium matrices serves lower-temperature compressor applications.
Today's leader: Single Crystal Blades. Tomorrow's challenger: Ceramic Matrix Composites.
Material Technology:
Cost tier stratification separates commodity nickel alloys from specialized intermetallics and advanced ceramic systems that command qualification premiums.
- Nickel-Based Superalloys:Gamma-prime strengthened alloys with rhenium and ruthenium additions dominate rotating airfoil applications through precipitation hardening mechanisms. Precision Castparts Corp. leverages captive vacuum investment casting capacity across multiple US sites to sustain margin control on these complex geometries. REACH restrictions on hexavalent chromium are forcing European suppliers to reformulate conversion coating chemistries for bond coat adhesion.
- Thermal Barrier Coatings:Multilayer ceramic systems with graded compositional transitions manage thermal gradients between hot gas paths and cooled metal substrates. EB-PVD coating chambers require 18-24 month lead times for capital equipment, constraining capacity expansion for yttria-stabilized zirconia topcoats. Environmental barrier coatings are unifying oxidation protection and thermal insulation functions in next-generation architectures.
- Titanium Aluminides:Intermetallic compounds offering density advantages for low-pressure turbine blades in geared turbofan architectures.
- Ceramic Coatings:Plasma-sprayed or EB-PVD deposited zirconia-based systems for stationary vane platforms.
- Solid Solution Alloys:Cobalt-based or iron-nickel systems for lower-temperature structural applications.
Procurement gravity centers on nickel superalloys. Technology transition favors thermal barrier coating innovations.
Application:
Customer type differentiation separates OEM new-build demand from aftermarket replacement cycles with divergent margin structures and technical specifications.
- High-Pressure Turbines:First-stage blades and vanes encounter the most severe thermal and mechanical loading, requiring single-crystal castings with intricate internal cooling channels. Narrowbody fleet renewal programs across Asia-Pacific carriers are compressing procurement cycles for these components. MTU Aero Engines AG anchors its competitive position through deep specialization in high-pressure module assembly for both Airbus and Boeing platforms.
- Low-Pressure Turbines:Larger-diameter airfoils operating at reduced temperatures prioritize weight reduction and aerodynamic efficiency over creep resistance. Ceramic matrix composite vane platforms are gaining traction here for extended on-wing intervals that reduce airline MRO spend.
- Combustor Liners:Segmented heat shields and transition ducts managing flame temperature non-uniformity.
- Compressor Sections:Titanium or steel alloy stators and rotors in sub-combustion temperature regimes.
- Exhaust Systems:Mixer nozzles and thrust reverser components with lower thermal protection requirements.
High-pressure turbines command current value pools. Low-pressure turbines offer the steepest expansion trajectory through material substitution.
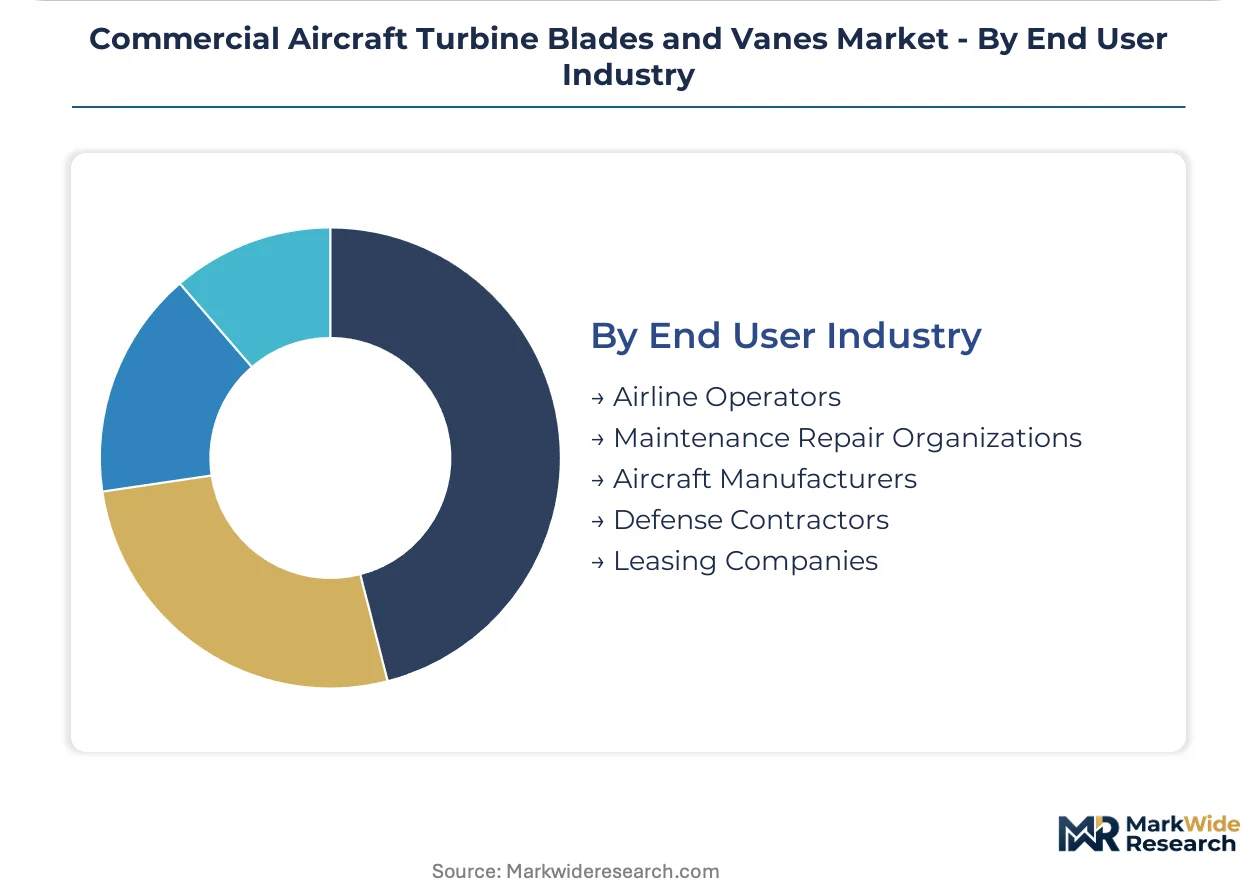
End User Industry:
Supply concentration dictates margin capture, with airframer-direct contracts displacing independent MRO channels under consolidated procurement frameworks.
- Aircraft Manufacturers:Boeing and Airbus specify blade and vane architectures through engine OEM partnerships, controlling design authority and qualification pathways. Power-by-the-hour contracts are compressing supplier-airline relationships into airframer-mediated frameworks. Airlines now procure replacements through OEM material repair agreements rather than independent sourcing.
- Maintenance Repair Organizations:Independent overhaul shops face margin pressure as airframers consolidate aftermarket channels, though additive repair of tip sections opens service revenue streams previously limited to coating reapplication.
- Airline Operators:Fleet managers optimizing life-cycle cost through power-by-the-hour or fixed-price maintenance agreements.
- Defense Contractors:Military engine programs with specialized performance and survivability requirements.
- Leasing Companies:Asset owners specifying maintenance reserves and redelivery condition standards.
Aircraft manufacturers control design specification. MRO networks are adapting to repair technology displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized foundry technicians and metallurgical engineers concentrate in industrial corridors spanning Connecticut, Bavaria, and the Midlands, anchoring precision casting capabilities that supply turbine airfoils to engine OEMs worldwide.
United States
Narrowbody fleet renewal programs at Southwest Airlines and United Airlines drive procurement of high-pressure turbine components from domestic suppliers. FAA airworthiness directives mandate serialized documentation of thermal history for every casting, compelling Hartford-area foundries to digitize legacy quality systems. Precision Castparts Corp. leverages captive vacuum investment casting capacity across multiple sites in the Pacific Northwest to sustain margin control on complex airfoil geometries.
Germany
REACH restrictions on hexavalent chromium force nickel-based superalloy casters to reformulate conversion coating chemistries for thermal barrier adhesion layers. MTU Aero Engines AG anchors its competitive position through deep specialization in low-pressure turbine module assembly for Airbus platforms. The Munich-Stuttgart industrial corridor hosts concentrated EB-PVD coating capacity serving both domestic engine programs and export contracts.
United Kingdom
Power-by-the-hour contracts compress supplier-airline relationships into airframer-mediated frameworks that favor established Midlands foundries. Rolls-Royce qualification pathways for single-crystal castings maintain stringent grain selector alignment standards that preserve technical moats. Derby-area precision casting houses supply high-pressure turbine vanes for next-generation widebody engines under EASA certification timelines.
China
Domestic narrowbody final assembly lines at Tianjin and Zhoushan localize blade sourcing requirements within the country's expanding MRO hub network. SAMR quality standards for aerospace castings tighten traceability requirements for superalloy compositions used in rotating airfoils. Xi'an and Chengdu precision manufacturing clusters attract foreign joint ventures seeking access to COMAC supply chain qualification pathways.
Japan
Kawasaki Heavy Industries maintains integrated casting-to-assembly capabilities for low-pressure turbine modules serving both domestic and export engine programs. METI production-linked incentives support vacuum investment foundry modernization in the Nagoya industrial zone. Osaka-area ceramic matrix composite research institutes collaborate with engine OEMs on next-generation vane platform qualification for moist combustion environments.
Commercial Aircraft Turbine Blades and Vanes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for contract leverage across the turbine airfoil value chain. The supplier base fragments across three tiers: integrated engine OEMs with captive casting capacity, independent Tier-1 precision foundries, and specialized coating houses. Strategic differentiation centers on Bridgman furnace throughput, thermal barrier coating intellectual property, and airframer-direct contract relationships. Capacity expansion and technology licensing represent the dominant competitive moves as qualification timelines stretch beyond thirty-six months for new casting geometries.
Among integrated engine OEMs with captive supply chains, GE Aviation and Pratt & Whitney exemplify the vertical control archetype through in-house casting and coating capabilities. Precision Castparts Corp. occupies a distinctive position as a dedicated precision foundry serving multiple engine platforms without airframer ownership. MTU Aero Engines AG represents the module-assembly specialist model, concentrating competitive position in low-pressure turbine integration rather than raw casting output.
| Leading Market Players |
|---|
| GKN Aerospace Limited |
| MTU Aero Engines AG |
| Precision Castparts Corp. |
| Kawasaki Heavy Industries, Ltd. |
| Carpenter Technology Corporation |
| GE Aviation |
| Pratt & Whitney |
| Siemens Energy AG |
| Rolls-Royce |
| Others |
Pricing and Supply Chain Analysis
Rhenium spot volatility from Chilean copper-molybdenum byproduct streams cascades through single-crystal superalloy casting economics, compressing margins at independent foundries while integrated engine OEMs absorb input shocks through captive vacuum investment capacity.
Pricing Analysis
Power-by-the-hour versus transactional component sales splits procurement economics between bundled service contracts and spot replacement orders. Pricing stratifies across airframer-direct qualification tiers, single-crystal premium castings, and commodity directionally solidified vanes. Cost compression in independent MRO channels is intensifying because airframers consolidate aftermarket sourcing through OEM material repair agreements. Low-cost carriers operating standardized narrowbody fleets exhibit highest price sensitivity; integrated engine OEMs with captive supply chains demonstrate lowest.
Supply Chain Analysis
Bridgman furnace operators in Connecticut, Bavaria, and the English Midlands face accelerating retirement waves that constrain single-crystal solidification throughput. Supply concentrates in the United States, Germany, and China for precision vacuum investment casting, with Japan and the United Kingdom anchoring specialized coating capacity. The network draws from Chilean rhenium, Australian ruthenium, and Chinese yttrium for superalloy and thermal barrier formulations. Single-source vulnerability in EB-PVD coating chamber manufacturing creates eighteen-to-twenty-four-month capacity expansion bottlenecks. Distribution runs through airframer-qualified Tier-1 foundries to engine OEM assembly lines, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic matrix composite weight reduction and extended on-wing intervals are shifting value capture toward premium-tier material substitutions, expanding addressable margins for qualified suppliers.
For Market Incumbents: Extend environmental barrier coating qualification timelines to lock in next-generation thermal management architectures before REACH restrictions on hexavalent chromium force European competitor reformulation. Deepen backward integration into silicon carbide fiber production to secure CMC vane platform supply chains against Japanese research institute licensing leverage. Consolidate airframer-direct contract relationships through power-by-the-hour participation to displace independent MRO channel access. For New Entrants and Emerging Players: Capture India's PLI scheme for aerospace precision manufacturing by establishing vacuum investment foundries serving COMAC supply chain qualification pathways and export MRO contracts. Target additive repair of high-pressure turbine blade tip sections, where directed energy deposition restores eroded geometries without full component replacement. Pursue joint venture structures with established EB-PVD coating houses to bypass capital equipment lead time barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where Bridgman furnace technical expertise concentrates in aging workforce cohorts without apprenticeship pipeline replenishment. Five-to-ten-year viability favors acquisitions of Midlands and Connecticut foundries with intact grain selector alignment capabilities and digitized metallurgical record systems. Watch for SAF compatibility mandates accelerating thermal barrier coating degradation rates as the signal for next-generation ceramic topcoat demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Barrier Coating Qualification | GE Aerospace and Pratt & Whitney unification of oxidation protection and thermal insulation extends component life in humid combustion environments. |
| Ceramic Matrix Composite Vane Platform Deployment | Silicon carbide fiber-reinforced matrices cut weight by one-third versus nickel superalloys, enabling extended on-wing intervals. |
| EB-PVD Coating Capacity Expansion | Yttria-stabilized zirconia topcoat throughput constraints from eighteen-to-twenty-four-month equipment lead times favor early-mover capital commitment. |
| Additive Repair Technology Integration | Directed energy deposition of blade tip sections opens service revenue streams at overhaul shops beyond coating reapplication. |
| REACH-Compliant Conversion Coating Reformulation | Plasma electrolytic oxidation trials at German and French foundries maintain EASA certification without hexavalent chromium. |
Research Methodology
Direct dialogue with precision foundry operations directors, thermal barrier coating R&D leads, engine OEM procurement managers, and airline fleet maintenance planners grounded qualitative assessment. Secondary validation drew from FAA airworthiness directive filings, EASA certification specification updates, EPA engine emissions standards, and customs trade data for rhenium and ruthenium import flows. Bottom-up segment sizing triangulated against top-down OEM production forecasts across the analysis window.
Installed base projections and replacement cycle modeling generated volume and value estimates across single-crystal blades, ceramic matrix composites, directionally solidified vanes, and coated blade architectures. Segmentation dimensions captured material technology tier, turbine stage application, and procurement channel structure. CAGRs derived from fitted growth curves incorporating narrowbody fleet renewal schedules, emissions mandate compliance timelines, and MRO hub localization patterns.
SAF combustion temperature compatibility, rhenium supply disruption, and Bridgman furnace technician retirement rates are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market