
 Embedded Structural Health Monitoring Networks for Aircraft Skins Market | 2026-2036
Embedded Structural Health Monitoring Networks for Aircraft Skins Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Structural Health Monitoring Networks for Aircraft Skins Market Insights
Asset-light sensor-network leasing is narrowing the competitive field for smaller MRO providers seeking embedded health-monitoring capabilities. Safran leverages its integrated avionics platform to bundle skin-monitoring hardware with flight-data services. TE Connectivity anchors its position through proprietary connector and harness architectures that withstand fuselage flex cycles. HBK FiberSensing specializes in fiber Bragg grating interrogators calibrated for composite-wing strain mapping.
Embedded structural health monitoring networks for aircraft skins comprise distributed arrays of strain, acoustic, and vibration sensors laminated or bonded into fuselage and wing structures, typically operating at sampling rates between 1 kHz and 50 kHz to capture fatigue-crack initiation and impact events. These networks transmit processed damage indicators to ground-based analytics platforms, enabling condition-based maintenance that replaces fixed-interval inspections. Fiber optic sensors lead installed base volume due to electromagnetic immunity and multiplexing density, while machine learning analytics represents the fastest-expanding technology segment as airlines seek automated damage-classification tools. Piezoelectric sensors occupy a mature niche in acoustic-emission crack detection, though margin pools are shifting toward integrated wireless-communication modules that eliminate harness weight.
FAA airworthiness directives and EASA certification memoranda on composite damage tolerance are mandating redundant sensing pathways for next-generation narrowbody programs. The EU AI Act and forthcoming machine-learning audit standards will impose traceability requirements on automated damage-prediction algorithms deployed in European-registered fleets. Stakeholders must decide whether to develop proprietary analytics stacks or partner with established aerospace software houses before regulatory compliance timelines harden.
Market Dynamics
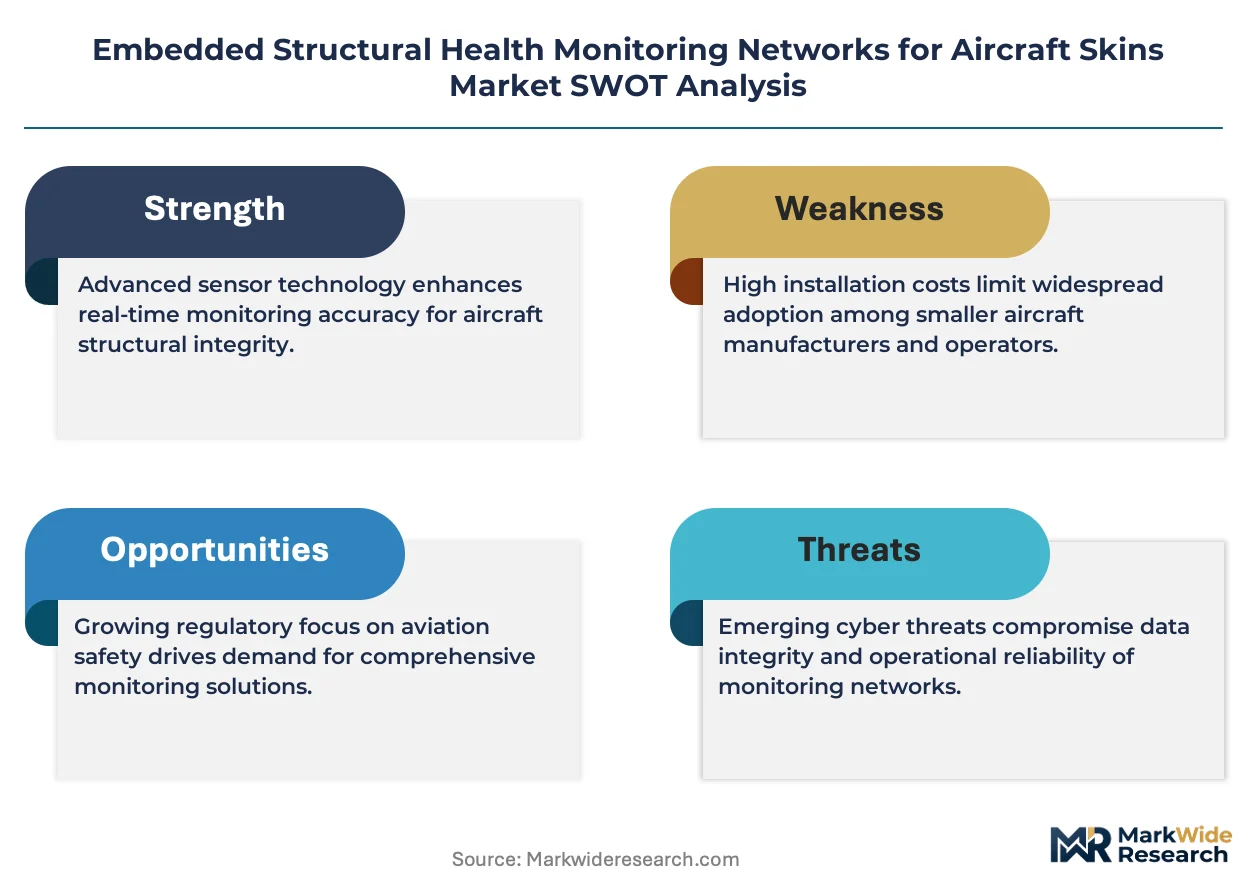
FAA airworthiness directives on aging aircraft integrity are compressing inspection cycles and forcing fleet operators toward continuous sensor-based monitoring rather than periodic manual checks.
Growth Catalysts
- Composite Damage Tolerance Mandates:EASA certification memoranda now require redundant sensing pathways for next-generation narrowbody programs, compelling airframers to embed fiber optic networks during manufacturing.
- Condition-Based Maintenance Economics:Military and commercial fleet operators calculate that unscheduled maintenance reductions justify upfront sensor-network capital expenditure across Boeing and Airbus platforms.
- Machine Learning Analytics:Airlines seek automated damage-classification tools that process strain and acoustic data without ground-crew interpretation, accelerating adoption of integrated hardware-software bundles.
Market Restraints
- Electromagnetic Certification Costs:Piezoelectric sensor networks require extensive shielding validation for fuel-vapor zones, inflating non-recurring engineering for each aircraft type.
- Fiber Optic Interrogator Concentration:Specialized interrogator manufacturing concentrates among a handful of European and North American suppliers, creating single-source vulnerability for multiplexed sensing architectures.
- Wireless Harness Substitution Threat:Integrated wireless-communication modules eliminate cable weight but introduce latency and power-draw tradeoffs that limit sampling rates below 10 kHz for critical crack-detection applications.
Strategic Opportunities
- Asset-Light Leasing Models:Smaller MRO providers can access embedded health-monitoring capabilities through sensor-network leasing rather than capital purchase, narrowing the competitive field against integrated primes.
- EU AI Act Traceability Requirements:Automated damage-prediction algorithms deployed in European-registered fleets must demonstrate audit trails, creating partnership demand between hardware vendors and established aerospace software houses.
- Machine Learning-Edge Computing Convergence:Onboard processing of fiber Bragg grating data reduces telemetry bandwidth requirements and enables real-time alert generation during flight operations.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Strain-mapping calibration requires engineers fluent in both composite mechanics and optical physics, a skill intersection with limited university pipeline output.
- Legacy Aircraft Retrofit Complexity:Bonding sensor arrays to existing aluminum fuselage structures demands structural repair manual amendments and supplemental type certificate timelines that stretch 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Structural Health Monitoring Networks for Aircraft Skins Market |
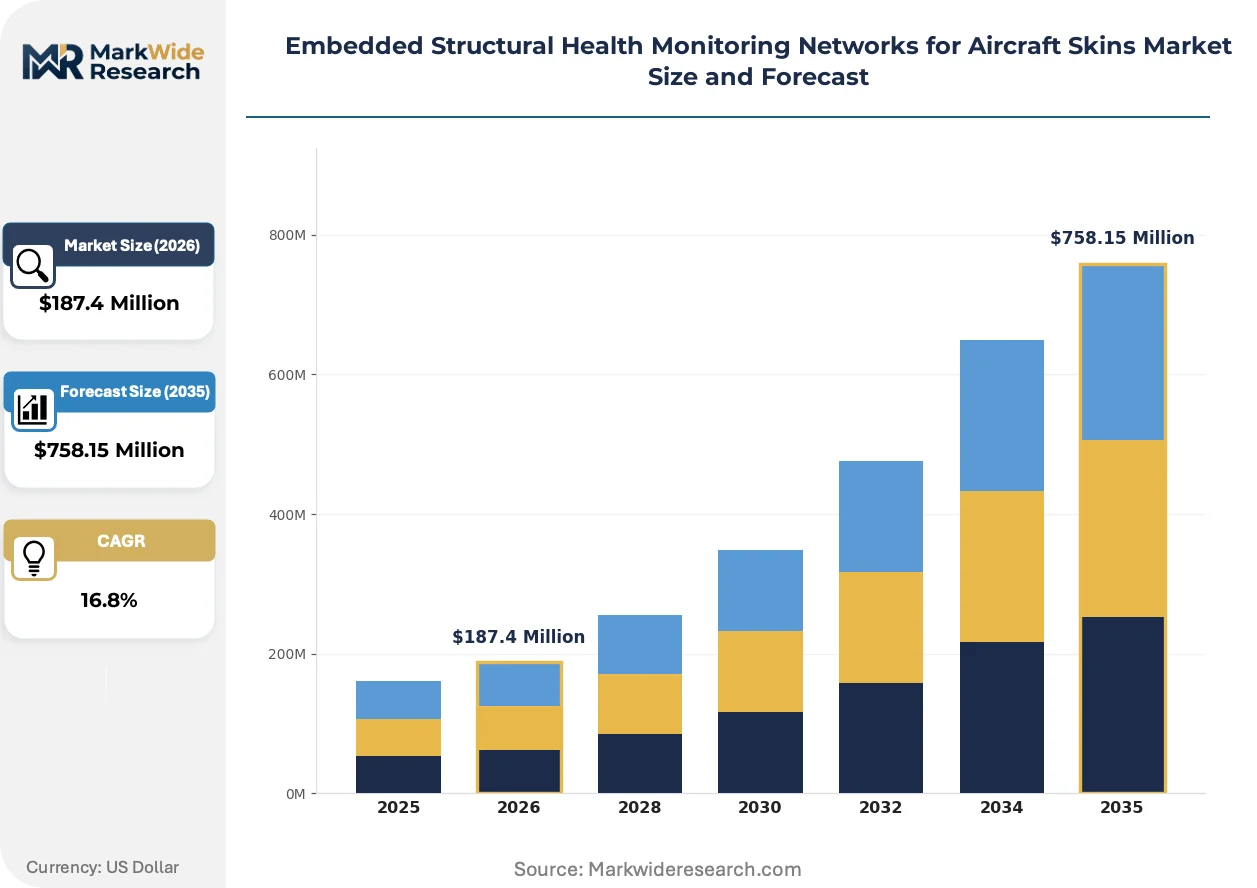
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Sensors, Piezoelectric Sensors, Ultrasonic Sensors, Capacitive Sensors, MEMS Sensors Technology: Wireless Communication, Data Acquisition, Signal Processing, Distributed Sensing, Machine Learning Analytics Application: Fatigue Monitoring, Crack Detection, Impact Damage Assessment, Corrosion Monitoring, Delamination Sensing End User: Aircraft Manufacturers, MRO Providers, Aerospace Research Centers, Component Suppliers |
| Companies Covered | Safran, TE Connectivity, HBK FiberSensing, PhotonFirst, Luna Innovations, Acellent Technologies, Metis Design Corporation, National Instruments, Fibotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Structural Health Monitoring Networks for Aircraft Skins Market Trends and Innovations
Machine learning analytics is compressing damage-classification timelines from hours to seconds, while regulatory mandates harden around automated decision traceability and electromagnetic immunity standards.
Fiber optic sensing architectures are digitizing structural health data capture across composite wing and fuselage applications. Airlines operating Airbus A350 and Boeing 787 fleets are retrofitting these networks at accelerated pace to satisfy damage-tolerance documentation requirements. The technology is digitizing maintenance record-keeping by replacing manual ultrasonic inspection logs with continuous, timestamped strain histories stored in blockchain-anchored databases.
The EU AI Act imposes algorithmic audit standards on automated damage-prediction systems deployed in European-registered aircraft. Industrial consequence includes mandatory documentation of training data provenance and decision-boundary transparency for neural networks classifying crack severity. Narrowbody programs with European type certificates are responding by segregating safety-critical damage assessments from probabilistic wear-estimation functions.
Buying patterns among defense primes are rotating toward performance-based logistics contracts that bundle sensor hardware with predictive analytics subscriptions. Traditional component vendors face disintermediation as Safran and TE Connectivity capture multi-year service revenue alongside initial equipment sales. This shift is most visible in United States Air Force tanker and mobility fleet modernization programs, where total availability contracts now specify minimum structural monitoring coverage as a deliverable.
Embedded Structural Health Monitoring Networks for Aircraft Skins Market Segmentation
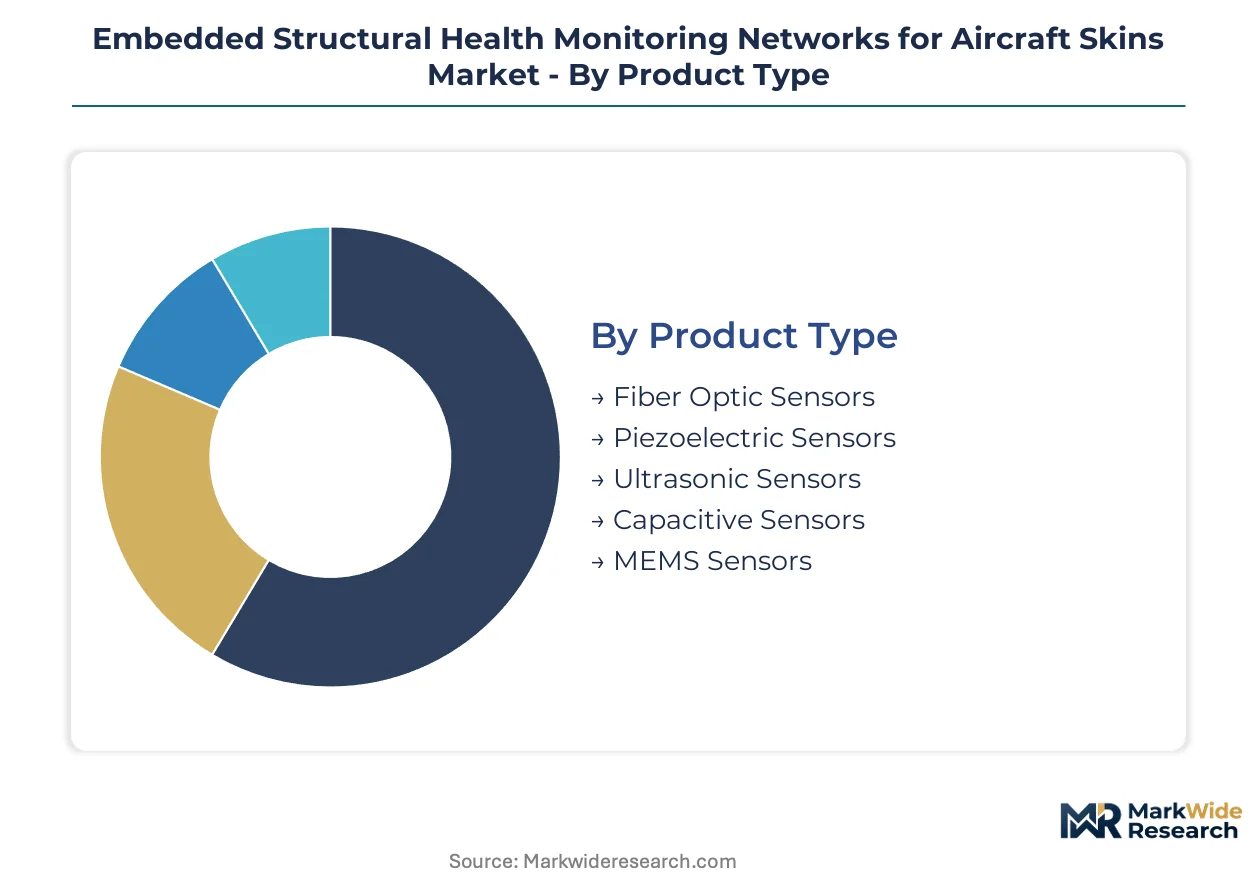
Segmentation reveals how sensor modalities, processing architectures, and damage-detection applications partition procurement budgets across airframe production and aftermarket retrofit programs. Each dimension carries distinct certification pathways and margin structures that shape vendor positioning.
Product Type:
Mature electromagnetic-immune technologies dominate installed base volume while emerging solid-state architectures challenge interrogator cost structures.
- Fiber Optic Sensors:Fiber Bragg grating arrays laminated into composite wing skins measure strain through wavelength-shift detection, achieving multiplexing densities exceeding 100 sensors per fiber. Airbus A350 and Boeing 787 production lines specify these networks for damage-tolerance documentation mandated by FAA and EASA certification memoranda.
- Piezoelectric Sensors:Lead zirconate titanate wafers bonded to aluminum fuselage structures detect acoustic emissions from fatigue-crack propagation, operating at sampling rates up to 50 kHz. Military tanker modernization programs in the United States favor these sensors for fuel-vapor-zone applications where electromagnetic immunity is secondary to bandwidth.
- Ultrasonic Sensors:Pulse-echo transducers embedded during manufacturing provide thickness-loss mapping for corrosion monitoring in maritime patrol aircraft.
- Capacitive Sensors:Micro-gap electrodes measure dielectric changes from moisture ingress in sandwich composite structures.
- MEMS Sensors:Silicon-based accelerometer arrays enable vibration-based delamination detection at interrogator costs below fiber optic alternatives.
Fiber optic sensors handle the majority of throughput in new narrowbody programs; MEMS sensors are gaining share fastest through retrofit applications.
Technology:
Cost tier separation runs from hardware-centric modules to software-intensive analytics stacks with recurring revenue profiles.
- Machine Learning Analytics:Neural networks trained on strain and acoustic datasets classify damage severity without ground-crew interpretation, compressing assessment timelines from hours to seconds. EU AI Act traceability requirements are forcing European-registered operators toward documented training-data provenance and decision-boundary transparency.
- Wireless Communication:Integrated radio modules eliminate harness weight from sensor networks but introduce latency tradeoffs that limit sampling rates below 10 kHz for critical crack-detection channels. Defense primes in the United States specify these architectures for unmanned aerial vehicle applications where mass reduction dominates reliability margins.
- Data Acquisition:Multi-channel digitizers with 24-bit resolution capture fiber Bragg grating spectra at kilohertz rates for fatigue-cycle counting.
- Signal Processing:Edge-computing architectures enable onboard damage localization without telemetry bandwidth consumption.
- Distributed Sensing:Optical frequency-domain reflectometry provides continuous strain mapping along single fibers exceeding 50 meters in length.
Machine learning analytics commands premium pricing tiers; wireless communication modules are expanding most quickly through military retrofit budgets.
Application:
Volume concentrates in scheduled-inspection replacement while emerging use cases address previously undetectable damage modes.
- Fatigue Monitoring:Continuous strain-cycle counting at wing root and fuselage crown locations replaces fixed-interval eddy-current inspections, enabling condition-based maintenance economics that justify sensor-network capital expenditure. Commercial fleet operators calculate unscheduled maintenance reductions across Boeing and Airbus platforms.
- Crack Detection:Acoustic emission processing from piezoelectric arrays identifies fatigue-crack initiation before visual detectability thresholds, satisfying FAA airworthiness directives on aging aircraft integrity. United States-based MRO providers retrofit these capabilities to extend supplemental type certificate timelines.
- Impact Damage Assessment:Real-time event detection from hail and foreign object debris enables immediate flight-crew alerting.
- Corrosion Monitoring:Electrochemical impedance spectroscopy tracks moisture ingress in lap joints and sealant failures.
- Delamination Sensing:Guided wave propagation analysis identifies composite ply separations in sandwich structures.
Fatigue monitoring captures the largest share of airline procurement; impact damage assessment is climbing the fastest as composite skin prevalence expands.
End User:
Customer type determines integration depth, from factory-embedded specifications to aftermarket retrofit complexity.
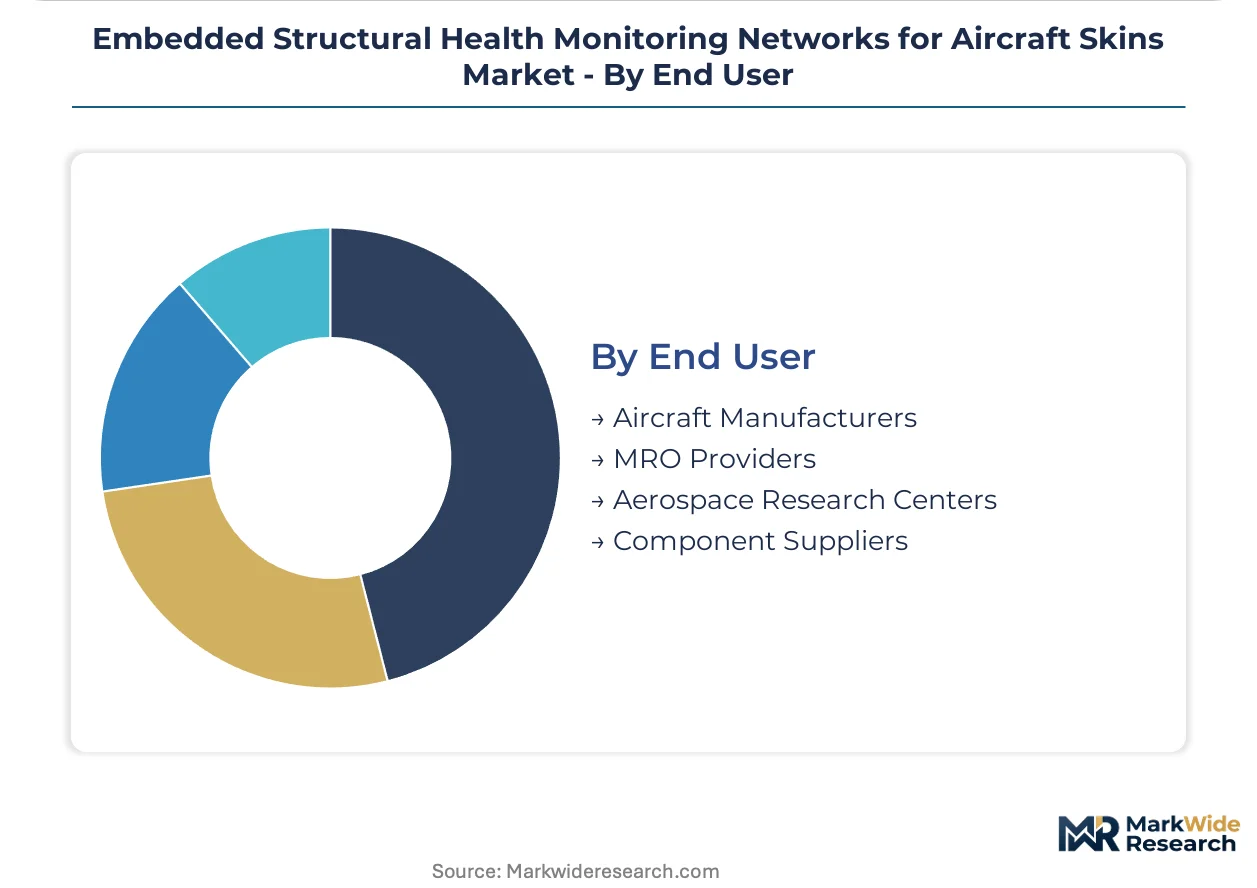
- Aircraft Manufacturers:Boeing and Airbus production lines embed fiber optic networks during composite layup and curing processes, locking sensor architectures into structural repair manuals and airworthiness certification baselines. Factory integration eliminates 18-36 month supplemental type certificate timelines required for retrofit installations.
- MRO Providers:Maintenance organizations pursue asset-light sensor-network leasing models to access embedded health-monitoring capabilities without capital purchase, narrowing competitive gaps against integrated primes. Smaller United States-based providers target regional jet and cargo-conversion fleets with accelerated retrofit programs.
- Aerospace Research Centers:NASA and university laboratories validate multiphysics simulation tools for strain-mapping calibration.
- Component Suppliers:Tier-2 vendors integrate sensing capabilities into control surfaces and engine nacelles for upstream differentiation.
Aircraft manufacturers specify the majority of embedded volume; MRO providers are expanding fastest through performance-based logistics contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives and EASA certification memoranda on composite damage tolerance are accelerating sensor-network mandates across major aviation jurisdictions. Military and commercial fleet operators in concentrated aerospace clusters are expanding adoption of continuous skin-monitoring systems to reduce unscheduled maintenance.
United States
Boeing production lines in Washington State and defense prime operations in Texas drive embedded fiber optic specifications for next-generation narrowbody programs. FAA airworthiness directives on aging aircraft integrity compress inspection cycles and mandate redundant sensing pathways for damage-tolerance compliance. The Seattle-Tacoma aerospace corridor concentrates interrogator manufacturing and MRO retrofit capabilities for both commercial and military tanker fleets.
France
Safran's integrated avionics platform bundles skin-monitoring hardware with flight-data services for Airbus A350 production in Toulouse. EASA certification memoranda require redundant sensing architectures that European-registered operators must satisfy through documented training-data provenance. The Occitanie aerospace cluster anchors composite-wing manufacturing where fiber Bragg grating networks laminate during curing processes.
Germany
HBK FiberSensing's fiber Bragg grating interrogators serve strain-mapping calibration demands from Hamburg and Munich-based composite specialists. The EU AI Act imposes algorithmic audit standards on automated damage-prediction systems deployed in European-registered aircraft. Bavaria's precision optics manufacturing corridor supplies multiplexed sensing architectures for next-generation narrowbody programs.
United Kingdom
BAE Systems and Rolls-Royce operations in Lancashire and Bristol drive defense retrofit programs for aging military transport fleets. EASA certification memoranda on composite damage tolerance extend to UK-registered aircraft through retained EU aviation law frameworks. The Southwest England aerospace cluster specializes in supplemental type certificate timelines for legacy aluminum fuselage bonding applications.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries embed sensor networks during regional jet manufacturing in Nagoya and Gifu prefectures. METI industrial policy supports condition-based maintenance economics through performance-based logistics contract structures. The Chubu aerospace manufacturing belt concentrates MEMS sensor production for vibration-based delamination detection in composite sandwich structures.
Embedded Structural Health Monitoring Networks for Aircraft Skins Market Competitive Landscape
Channel-controlling players compete with product-specialist players across interrogator hardware, sensor arrays, and analytics software tiers. Consolidation concentrates among European and North American suppliers of fiber optic interrogators, creating single-source vulnerability for multiplexed sensing architectures. Three archetypes dominate: integrated avionics platforms bundling hardware with flight-data services, connector and harness specialists leveraging proprietary architectures, and fiber optic sensing pure-plays focused on strain-mapping calibration. M&A activity targets machine learning analytics capabilities, while strategic partnerships address EU AI Act traceability requirements for automated damage-prediction algorithms.
Within the integrated platform tier, Safran and TE Connectivity occupy positions that span hardware manufacturing through multi-year service revenue capture. HBK FiberSensing exemplifies the fiber optic sensing specialist archetype, anchoring interrogator production calibrated for composite-wing applications. These three companies represent distinct competitive vectors: bundled avionics-flight-data ecosystems, proprietary connector-harness architectures withstand fuselage flex cycles, and dedicated fiber Bragg grating expertise for strain-mapping calibration.
| Leading Market Players |
|---|
| Safran |
| TE Connectivity |
| HBK FiberSensing |
| PhotonFirst |
| Luna Innovations |
| Acellent Technologies |
| Metis Design Corporation |
| National Instruments |
| Fibotex |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on European and North American fiber optic interrogator suppliers compresses pricing power for multiplexed sensing architectures while simultaneously forcing tiered procurement strategies that separate premium-certified from standard-grade sensor networks. FAA airworthiness directive compliance timelines and EASA certification memoranda create regulatory chokepoints that extend lead times for damage-tolerance-grade hardware, widening spreads between factory-embedded specifications and aftermarket retrofit alternatives.
Pricing Analysis
Certification level (FAA-grade and EASA-compliant) creates the primary spread between premium factory-embedded networks and standard aftermarket retrofit configurations. The dominant pricing structure runs through performance-based logistics contracts that bundle sensor hardware with predictive analytics subscriptions, displacing per-unit transactional models. Price differentiation rests on electromagnetic immunity validation for fuel-vapor zones and machine learning audit documentation for EU AI Act compliance. Cost compression in standard-grade piezoelectric arrays is intensifying because wireless communication modules eliminate harness weight at lower interrogator expense. Military fleet operators demonstrate the least price sensitivity due to total availability contract structures, while smaller MRO providers leasing sensor networks exhibit acute cost consciousness.
Supply Chain Analysis
Tariff exposure between the United States and European Union member states dominates supply chain risk for fiber Bragg grating interrogators and specialized connector architectures. Geographic supply concentration centers on Germany, France, and the United States for precision optics manufacturing and avionics integration capabilities. Raw material dependencies draw from rare-earth-doped optical fibers, lead zirconate titanate wafers, and aerospace-grade epoxy bonding agents. Single-source vulnerability persists for multiplexed sensing interrogators calibrated to composite-wing strain specifications. Distribution runs through airframer production line specifications and defense prime performance-based logistics contracts, with aftermarket MRO channels expanding through asset-light leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded structural health monitoring networks for aircraft skins constitute a defensive-moat market where regulatory entrenchment through FAA airworthiness directives and EASA certification memoranda creates substantial switching costs for fleet operators. Network effects consolidate around integrated avionics platforms that bundle hardware with multi-year analytics subscriptions.
For Market Incumbents: Entrench position through exclusive flight-data service bundling that locks airframers into structural repair manual baselines, while acquiring machine learning analytics capabilities to satisfy EU AI Act traceability mandates before compliance timelines harden. Vertical integration into proprietary connector-harness architectures withstands fuselage flex cycles and eliminates third-party vulnerability. Capacity addition in the Seattle-Tacoma aerospace corridor captures Boeing and defense prime retrofit demand.
For New Entrants and Emerging Players: Pursue white-space opportunities in regional jet and cargo-conversion fleet retrofits where supplemental type certificate complexity has deterred integrated primes. Underpenetrated segments include vibration-based delamination detection for composite sandwich structures using MEMS sensor arrays at interrogator costs below fiber optic alternatives. Target Japan's Chubu aerospace manufacturing belt through partnerships with Mitsubishi Heavy Industries and Kawasaki Heavy Industries for regional jet embedded specifications.
For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors fiber optic sensing pure-plays with established EASA calibration relationships and documented training-data provenance. Long-term viability across the analysis window hinges on algorithmic audit capability for automated damage-prediction systems. Acquisition target archetypes include machine learning analytics specialists with aerospace software house partnerships. The signal to watch is performance-based logistics contract penetration rates among United States Air Force tanker and mobility fleet modernization programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Analytics Acquisition | EU AI Act traceability mandates require documented training-data provenance for neural networks classifying crack severity. |
| Performance-Based Logistics Contracting | United States Air Force tanker programs specify minimum structural monitoring coverage as a contract deliverable. |
| Fiber Bragg Grating Interrogator Capacity Expansion | Boeing 787 and Airbus A350 production lines embed these networks during composite curing processes. |
| Wireless Communication Module Development | Defense primes specify these architectures for unmanned aerial vehicle applications where mass reduction dominates. |
| EU Regulatory Compliance Partnership | EASA certification memoranda require redundant sensing pathways with algorithmic audit documentation. |
Research Methodology
The analysis maps fiber optic sensor networks, piezoelectric acoustic arrays, machine learning analytics platforms, and wireless communication modules, each validated through primary interviews with airframe platform engineers, MRO retrofit program managers, defense prime procurement officers, and fiber optic interrogator manufacturing directors. Secondary validation draws from FAA airworthiness directive filings, EASA certification memoranda, SEC 10-K disclosures from listed avionics suppliers, and customs records for aerospace-grade optical fiber imports. Bottom-up triangulation across sensor installation counts and top-down reconciliation against airframe production schedules ensure cross-verified volume estimates.
Assumptions held fixed include continued enforcement of FAA aging aircraft integrity mandates and EASA composite damage tolerance requirements throughout the projection horizon, while fuel price volatility and defense budget allocation shifts were treated as scenario variables. Segmentation dimensions modeled encompass sensor modality, processing architecture, damage-detection application, and end-user integration depth. CAGRs derive from regression analysis of historical fleet retrofit penetration rates and forward projection of narrowbody program sensor specifications. Industry-specific forecast inputs include Boeing and Airbus delivery schedules and United States Air Force tanker modernization program timelines.
Sensitivities concentrate around EU AI Act implementation timelines for algorithmic audit standards and fiber optic interrogator manufacturing concentration risk. Forecasts reflect assumptions about regulatory mandate continuity and composite airframe production mix. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aviation Analytics Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market