
 Free Fall Sensor Market | 2026-2036
Free Fall Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Free Fall Sensor Market Foresight
A capital-intensity divergence between MEMS foundry owners and fabless design houses is rotating competitive advantage toward players with in-house fabrication. Bosch Sensortec leverages captive wafer capacity to sustain margin control across automotive safety programs. STMicroelectronics anchors European supply through its dedicated MEMS production lines in Italy and France. Analog Devices competes on precision calibration, differentiating its portfolio for aerospace-grade applications.
Free fall sensors detect abrupt acceleration changes typically exceeding 3 g within milliseconds, using piezoelectric or capacitive transduction to trigger protective mechanisms in hard drives, vehicle restraint systems, and industrial machinery. The devices primarily serve to prevent mechanical damage or bodily injury by initiating countermeasures before impact occurs. Combination sensors integrating accelerometer and gyroscope functions capture the fastest expansion as end users demand six-axis detection in compact packages. Wireless sensors remain nascent but occupy emerging margin pools in predictive maintenance deployments where cabling constraints limit traditional architectures.
FDA scrutiny of wearable fall-detection devices and NHTSA crashworthiness protocols directly shape sensor accuracy requirements and validation burdens for suppliers targeting health monitoring and automotive channels. ISO 26262 functional safety standards and IEC 61508 industrial safety frameworks mandate fault-tolerant designs that extend development cycles but create barriers against unqualified entrants. Stakeholders must monitor evolving FAA certification criteria for drone parachute systems and emerging EU AI Act implications for autonomous fall-response algorithms.
Market Dynamics
MEMS miniaturization is compressing package sizes while multiplying axis counts, forcing suppliers to recalibrate fabrication economics and validation protocols simultaneously.
Growth Catalysts
- ISO 26262 Functional Safety Mandates:Automotive OEMs in Germany and Japan now require fault-tolerant sensor architectures for occupant restraint systems, pulling multi-axis units into standard safety bundles.
- Predictive Maintenance Adoption:Industrial machinery operators deploy wireless free fall sensors to monitor crane loads and conveyor systems where cabling failures previously blinded monitoring systems.
- Drone Parachute Certification:FAA criteria for commercial UAV emergency recovery systems mandate millisecond-response detection, opening dedicated procurement channels for aerospace-grade suppliers.
Market Restraints
- Wafer Supply Concentration:MEMS foundry capacity clusters in Taiwan and select European nodes, exposing fabless design houses to allocation shocks during automotive demand surges.
- Piezoelectric Material Volatility:Lead zirconate titanate and specialized ceramic substrates face price swings tied to rare earth processing bottlenecks in Chinese refining corridors.
- Optical Motion Capture Substitution:Camera-based fall detection in controlled industrial environments eliminates sensor hardware entirely, threatening unit volume in factory automation segments.
Strategic Opportunities
- EU AI Act Compliance Services:Autonomous fall-response algorithms in wearable health monitors require documented decision transparency, creating adjacent revenue streams for validation tooling.
- India Industrial Safety Enforcement:State-level factory inspectorates are mandating machine guarding upgrades, opening first-mover positioning for sensor suppliers with localized calibration labs.
- Accelerometer-Gyroscope Fusion:Six-axis combination sensors capture design wins in compact automotive modules where discrete component counts previously blocked integration.
Industry Challenges
- ISO 26262 Certification Timelines:Automotive safety qualification cycles extend 18-24 months, freezing product roadmaps and delaying revenue recognition for new entrants.
- Multi-Physics Simulation Talent:MEMS design requires simultaneous mastery of mechanical, electrical, and thermal modeling, with qualified engineers concentrated at established IDMs.
- Legacy Hard Drive Channel Erosion:Solid-state storage displacement collapses the original high-volume application for free fall sensors, forcing portfolio pivots toward automotive and industrial verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free Fall Sensor Market |
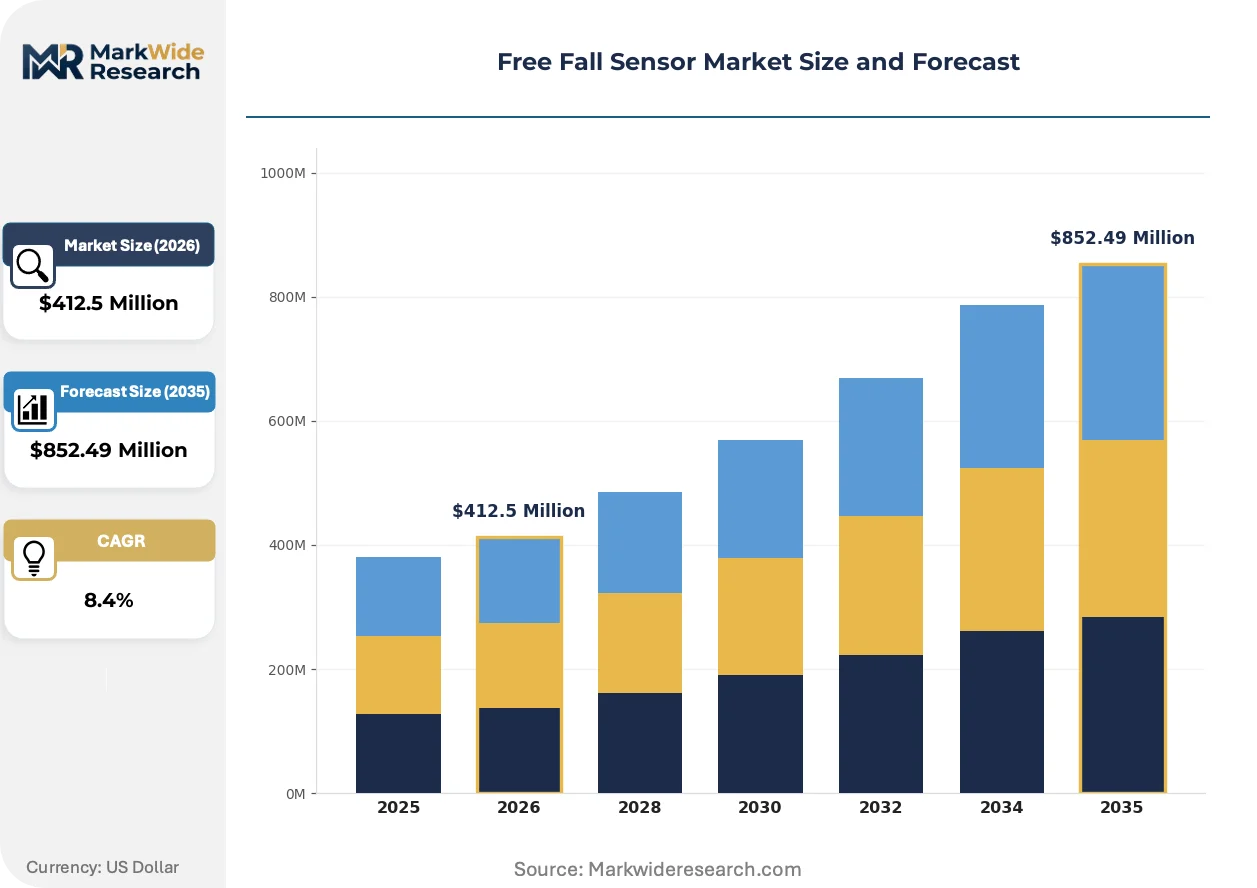
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Accelerometer, Gyroscope, Combination Sensor, Magnetometer Technology: Microelectromechanical Systems, Digital Sensors, Analog Sensors, Wireless Sensors Application: Automotive Safety, Aerospace, Industrial Equipment, Consumer Electronics End User: Manufacturers, Research Institutions, Component Suppliers, Transportation Providers |
| Companies Covered | TE Connectivity, Bosch Sensortec, STMicroelectronics, NXP Semiconductors, Analog Devices, Honeywell, Murata, Broadcom, InvenSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free Fall Sensor Market Shifts & Advancements
Convergence between functional safety mandates and edge computing architectures is redrawing sensor specifications, validation burdens, and supplier qualification pathways across end-use verticals.
Capacitive MEMS transduction is decomposing the traditional dominance of piezoelectric architectures in automotive safety modules. Tier 1 suppliers in Stuttgart and Detroit are adopting capacitive designs for their superior temperature stability and self-test capabilities. The technology is decomposing legacy supply relationships as foundries with CMOS-compatible processes capture design wins from specialized ceramic houses.
EU AI Act algorithmic transparency requirements are forcing wearable health monitor suppliers to document sensor fusion decision pathways. Device manufacturers targeting European markets must now maintain audit trails for fall-detection trigger logic, extending software validation cycles by 30-40 percent. Health technology procurement teams in France and Germany are prioritizing suppliers with pre-certified documentation packages.
Direct OEM contracting is displacing distribution-layer sensor procurement in high-reliability automotive programs. Bosch, Continental, and Denso are establishing dedicated supplier development programs with MEMS houses, bypassing traditional component distributors. This pattern concentrates most visibly in German automotive clusters where just-in-sequence delivery mandates favor captive supplier relationships over merchant market flexibility.
Free Fall Sensor Market Segmentation
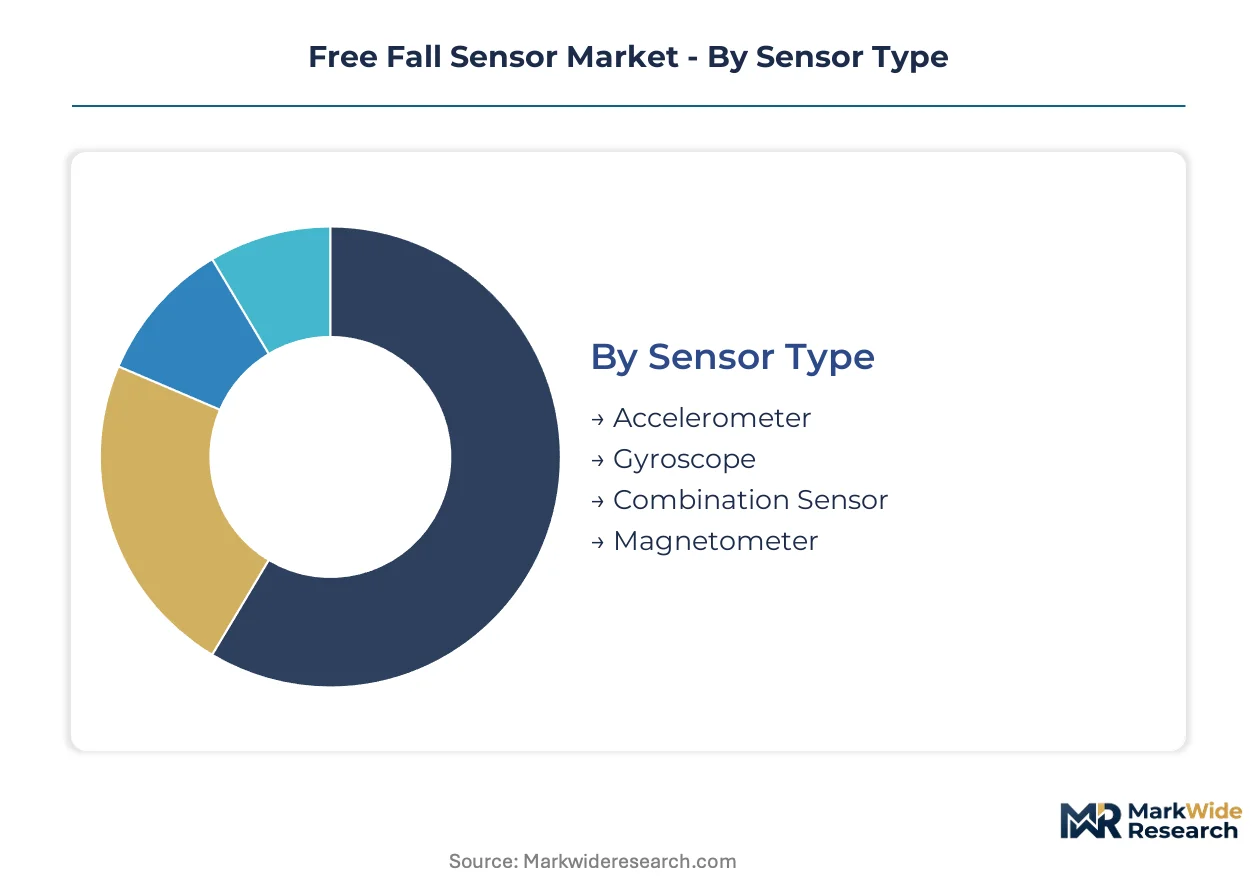
Free fall sensor procurement patterns diverge sharply across technical specifications and end-use requirements. Automotive safety programs demand fault-tolerant architectures with ISO 26262 certification, while industrial deployments prioritize wireless connectivity for retrofit flexibility. Understanding margin concentration within each dimension enables suppliers to allocate R&D resources against the highest-return opportunities.
Sensor Type:
Premium pricing accrues to multi-axis units that reduce component counts and simplify system integration for Tier 1 automotive suppliers.
- Accelerometer:Single-axis piezoelectric or capacitive designs detect linear acceleration thresholds exceeding 3 g. German and Japanese OEMs embed these in airbag deployment modules where millisecond response times determine occupant survival rates. Legacy hard drive protection applications are contracting as solid-state storage displaces mechanical media.
- Combination Sensor:Six-axis packages fuse accelerometer and gyroscope functions in compact MEMS dies. Stuttgart-based safety system integrators specify these for rollover detection and electronic stability control where spatial orientation data reduces false triggers. The format commands price premiums of 40-60 percent over discrete alternatives.
- Gyroscope:Angular rate sensors complement linear detection in drone parachute recovery systems.
- Magnetometer:Magnetic field sensing adds heading reference for navigation-augmented fall detection.
The dominant share belongs to Accelerometer, while Combination Sensor is closing the gap fastest.
Technology:
Manufacturing scale and capital intensity separate captive foundry operators from fabless competitors seeking wafer allocation.
- Microelectromechanical Systems:Silicon-based bulk and surface micromachining enable sub-millimeter feature sizes with wafer-level packaging. Italian and French production lines at STMicroelectronics anchor European supply security for automotive programs. MEMS processes require dedicated equipment sets that lock in 15-20 year depreciation cycles.
- Wireless Sensors:Battery-powered units with Bluetooth Low Energy or proprietary RF protocols eliminate cabling in crane load monitoring and conveyor belt applications. Predictive maintenance adopters in German manufacturing clusters are trialing mesh network deployments where wiring failures previously blinded monitoring systems. The segment climbs fastest as industrial IoT architectures mature.
- Digital Sensors:On-die ADC integration simplifies host processor interfaces.
- Analog Sensors:Continuous voltage output suits legacy industrial control systems.
MEMS fabrication commands the largest revenue pool, though Wireless Sensors expand most quickly in industrial retrofit channels.
Application:
Regulatory mandates and liability exposure create divergent pricing power across end-use verticals.
- Automotive Safety:Occupant restraint systems, rollover detection, and pedestrian protection modules require ASIL-D rated components under ISO 26262. NHTSA crashworthiness protocols and KBA type approval processes in Germany extend qualification timelines to 18-24 months. OEMs in Detroit and Stuttgart are consolidating supplier bases to three qualified MEMS houses per program.
- Industrial Equipment:Machine guarding, crane load monitoring, and conveyor safety systems deploy free fall detection for personnel protection. Indian state factory inspectorates are mandating upgrades that open first-mover positioning for suppliers with localized calibration capabilities. The application gains share as enforcement tightens in emerging manufacturing economies.
- Aerospace:FAA certification criteria for commercial UAV parachute systems specify millisecond-response detection thresholds.
- Consumer Electronics:Wearable fall-detection devices face FDA scrutiny of algorithmic performance claims.
Automotive Safety retains the dominant position, while Industrial Equipment scales fastest on regulatory enforcement tailwinds.
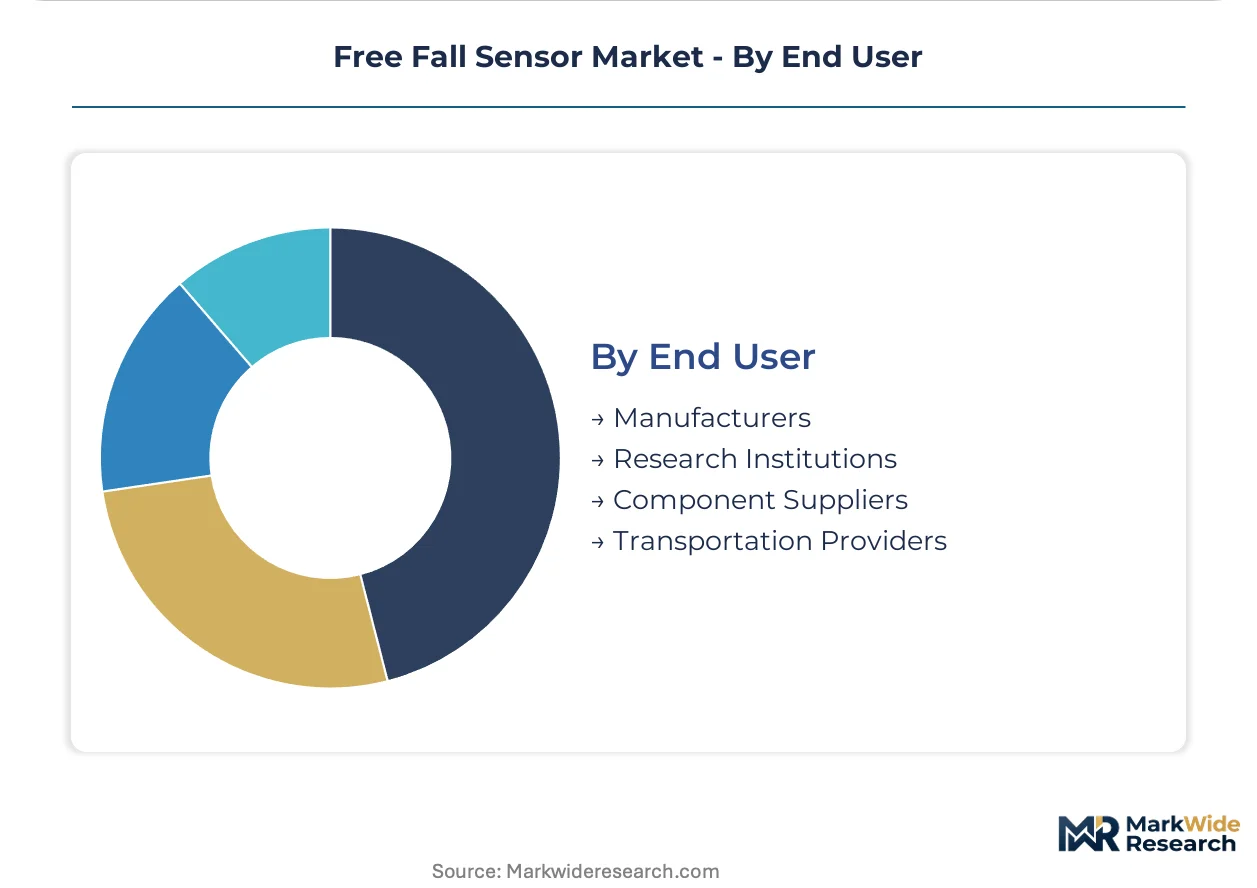
End User:
Procurement sophistication and volume concentration determine supplier relationship structures.
- Manufacturers:Tier 1 automotive suppliers and industrial machinery builders specify sensors at the system design stage. Bosch, Continental, and Denso are establishing dedicated supplier development programs that bypass traditional distribution. Direct contracting concentrates in German automotive clusters where just-in-sequence delivery mandates favor captive relationships.
- Component Suppliers:Module houses and subsystem integrators aggregate demand across multiple OEM programs. These intermediaries maintain buffer inventory and provide value-added calibration services. Their procurement patterns stabilize volume forecasts for MEMS foundries.
- Research Institutions:University and national laboratory procurement focuses on specialized specifications.
- Transportation Providers:Fleet operators and logistics companies deploy sensors for cargo protection.
Manufacturers control the largest procurement volume, while Component Suppliers are consolidating fastest through distributor bypass trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs embed multi-axis sensors in occupant restraint bundles, while Indian factory inspectorates mandate machine guarding upgrades. Japanese precision manufacturers prioritize gyroscope fusion for rollover detection. This consumption-mix differential shapes regional procurement patterns and supplier qualification pathways.
United States
NHTSA crashworthiness protocols and FAA drone parachute certification drive demand for millisecond-response detection systems. Detroit-based safety system integrators consolidate supplier bases to three qualified MEMS houses per automotive program. Tier 1 suppliers establish dedicated development relationships that bypass traditional distribution channels.
Germany
Stuttgart automotive clusters require ISO 26262 ASIL-D rated components for electronic stability control and pedestrian protection modules. KBA type approval processes extend qualification timelines to 18-24 months, freezing product roadmaps for new entrants. Just-in-sequence delivery mandates favor captive supplier relationships over merchant market flexibility.
Japan
METI industrial safety frameworks and precision manufacturing standards shape sensor accuracy requirements for robotics and automated machinery. Nagoya-based automotive suppliers specify six-axis combination sensors for rollover detection applications. Domestic MEMS foundries anchor supply security through dedicated production lines.
India
State-level factory inspectorates mandate machine guarding upgrades in Maharashtra and Gujarat manufacturing corridors. BIS certification requirements for industrial safety equipment create first-mover positioning for suppliers with localized calibration capabilities. Pune and Ahmedabad industrial zones drive procurement volume for crane load monitoring systems.
China
MIIT standards for industrial IoT architectures accelerate wireless sensor deployment in smart factory retrofits. GB standards for machinery safety equipment tighten enforcement in Yangtze River Delta manufacturing hubs. Shenzhen and Shanghai electronics clusters concentrate demand for compact MEMS packages in consumer drone applications.
Free Fall Sensor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operators commanding margin control against fabless design houses seeking wafer allocation. The structure stratifies between MEMS fabrication owners with 15-20 year equipment depreciation cycles and module integrators aggregating demand across multiple OEM programs. Two strategic archetypes dominate: vertically integrated IDMs with in-house wafer capacity, and fabless specialists competing on precision calibration. Capacity expansion and direct OEM contracting represent the dominant competitive moves, as automotive Tier 1 suppliers bypass distribution layers entirely.
Within the integrated fabrication tier, Bosch Sensortec and STMicroelectronics exemplify the captive foundry model, leveraging dedicated production lines to sustain supply security for automotive safety programs. Analog Devices occupies a position among precision calibration specialists, differentiating through aerospace-grade validation capabilities. These three anchors span German, European, and US geographic origins respectively, reflecting the regional clustering of MEMS expertise and automotive OEM procurement power.
| Leading Market Players |
|---|
| TE Connectivity |
| Bosch Sensortec |
| STMicroelectronics |
| NXP Semiconductors |
| Analog Devices |
| Honeywell |
| Murata |
| Broadcom |
| InvenSense |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with MEMS foundries lock in wafer access for automotive safety programs while fixing unit costs across ISO 26262 qualification cycles. German Tier 1 suppliers in Stuttgart clusters leverage these structures to neutralize spot-market volatility in silicon substrates.
Pricing Analysis
Contract-based long-term offtake dominates procurement for ASIL-D certified components, with price differentiation anchored in ISO 26262 certification tier and captive foundry access. Premium-mid-economy pricing separates fault-tolerant automotive modules from standard industrial units. Cost compression in consumer-grade accelerometers intensifies as solid-state storage erodes legacy hard drive volumes. Industrial machinery buyers exhibit highest price sensitivity, while aerospace-grade purchasers prioritize traceability over unit economics.
Supply Chain Analysis
Taiwan and France anchor MEMS wafer fabrication for automotive and industrial programs respectively. Silicon wafers, specialized ceramic substrates for piezoelectric transduction, and CMOS-compatible packaging materials constitute core input dependencies. Single-source vulnerability concentrates in Taiwanese foundry nodes during automotive demand surges. Distribution runs through direct OEM contracting in German automotive clusters, bypassing traditional component distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-as-a-service and validation documentation packages expand faster than hardware unit sales as EU AI Act transparency mandates create recurring revenue layers for algorithmic audit trails.
For Market Incumbents: Shield automotive safety margins by deepening captive foundry utilization in Italian and French production nodes against fabless competitors facing allocation shocks. Accelerate ISO 26262 pre-certification investments to compress 18-24 month qualification timelines before NHTSA protocols tighten further. For New Entrants and Emerging Players: Lead with wireless sensor architectures in Indian industrial corridors where state factory inspectorates mandate machine guarding upgrades without established supplier relationships. Target crane load monitoring and conveyor safety systems in Maharashtra and Gujarat manufacturing zones through localized calibration partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision calibration specialists with aerospace-grade validation capabilities over undifferentiated module integrators. Long-term viability hinges on algorithmic transparency service attach rates in European health monitoring channels. Watch FAA drone parachute certification timelines as inflection signal for aerospace-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Expansion | Italian and French production lines at STMicroelectronics anchor European supply security for ASIL-D automotive programs. |
| ISO 26262 Pre-Certification Investment | Early qualification commitment compresses 18-24 month timelines before KBA type approval processes extend further. |
| Algorithmic Validation Service Launch | EU AI Act documentation packages capture recurring revenue from wearable health monitor suppliers in France and Germany. |
| Localized Calibration Lab Buildout | Indian state inspectorates in Maharashtra and Gujarat favor suppliers with BIS-certified regional testing capabilities. |
| Direct OEM Supplier Development Program | Bosch, Continental, and Denso partnerships bypass distribution layers in Stuttgart just-in-sequence delivery corridors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with MEMS design engineers, Tier 1 automotive procurement directors, industrial safety compliance officers, and FAA certification specialists; alongside secondary validation through SEC semiconductor filings, NHTSA crashworthiness databases, ISO 26262 registrar records, and EU AI Act implementation guidance. Bottom-up sensor unit demand modeling triangulated against top-down automotive production forecasts and industrial safety equipment import data.
Across the projection horizon, the analytical framework segmented volume and value outputs by sensor type, certification tier, end-use vertical, and regional regulatory cluster. CAGRs derived from historical MEMS pricing trajectories, automotive safety content per vehicle trends, and wireless industrial IoT deployment curves. Forecast inputs incorporated ISO 26262 qualification pipeline visibility and FAA drone parachute certification schedule indicators.
The analysis sits within stated boundaries; outcomes outside sustained automotive safety mandate enforcement or stable rare earth ceramic substrate supply would require recalibration. Forecasts reflect documented assumptions regarding MEMS foundry capacity expansion timelines and EU AI Act implementation pacing. Recalibration cycles align with material shifts in NHTSA protocol revisions or Indian state-level factory inspection enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market