
 Aerospace Superalloys Market | 2026-2036
Aerospace Superalloys Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Superalloys Market Analysis
Defense procurement is shifting toward sixth-generation fighter platforms and hypersonic systems that demand superalloys with superior creep resistance. Carpenter Technology Corporation sustains leadership in premium vacuum-melted alloys for rotating components. Precision Castparts Corp. dominates investment casting of directionally solidified turbine blades for commercial turbofans. Haynes International specializes in cobalt-based formulations that withstand extreme thermal cycling in afterburner sections.
Aerospace superalloys are high-performance metallic systems, predominantly nickel-based with chromium, cobalt, and refractory element additions, engineered to retain mechanical integrity above 80 percent of their melting temperature. Vacuum induction melting followed by vacuum arc remelting eliminates trace impurities critical for fatigue-limited rotating hardware. Nickel-based alloys command the dominant margin pool due to their entrenched position in high-pressure turbine disks and blades. Alloy powder forms are gaining traction as additive manufacturing penetrates legacy forging supply chains for complex vanes and structural brackets. Forged parts remain the volume anchor for large-diameter engine casings and compressor rotors where directional grain structure governs service life.
FAA airworthiness directives and EASA certification standards dictate minimum creep-rupture life and thermomechanical fatigue thresholds for commercial engine superalloy components. EPA emissions regulations indirectly shape demand by forcing higher combustion temperatures that only advanced single-crystal superalloys can tolerate. MRO Services and defense contractors must track how REACH substance restrictions and emerging EU Green Deal material passport requirements affect alloy chemistry and supplier qualification timelines.
Market Dynamics
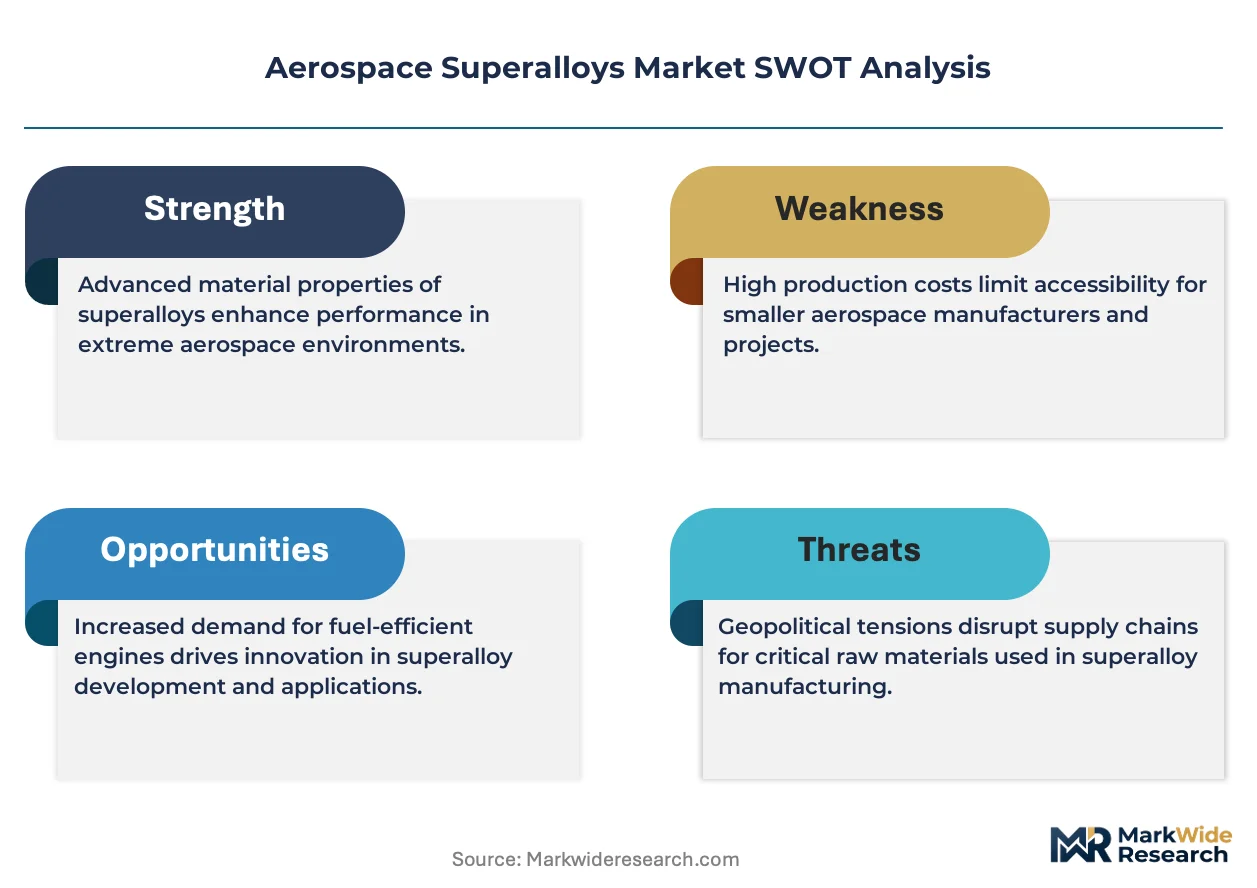
The aerospace superalloys sector is experiencing acute supply tension as single-crystal casting capacity concentrates among a handful of qualified foundries while next-generation engine programs accelerate qualification timelines. This structural squeeze between concentrated upstream supply and dispersed downstream demand is forcing OEMs to lock in multi-year offtake agreements earlier in development cycles.
Growth Catalysts
- Next-Generation Propulsion:Sixth-generation fighter and adaptive-cycle commercial engine programs demand nickel-based superalloys with enhanced creep resistance above 1,100°C. These platforms are accelerating qualification cycles for advanced single-crystal formulations.
- REACH Compliance:The EU's Green Deal material passport requirements are favoring superalloy suppliers with closed-loop recycling capabilities and verified carbon footprint documentation across the supply chain.
- Additive Manufacturing:Powder-bed fusion and directed energy deposition processes are penetrating legacy forging supply chains for complex turbine vanes and structural brackets, expanding addressable component geometries.
Market Restraints
- Rhenium Supply Concentration:Over 80 percent of global rhenium extraction occurs in Chile and Kazakhstan, creating acute price volatility for third-generation single-crystal alloys requiring this refractory element.
- Vacuum Melting Bottleneck:Triple-melt capacity (VIM-VAR-ESR) for rotating disk alloys concentrates in the United States, Germany, and Japan, limiting new entrant qualification pathways.
- Ceramic Matrix Substitution:Silicon carbide-silicon carbide composites are displacing superalloys in selected static hot-section components above 1,200°C, compressing addressable market for conventional castings.
Strategic Opportunities
- India Defense Localization:The country's PLI scheme for aerospace components is creating captive demand for indigenized superalloy melting and casting capacity to supply domestic fighter engine programs.
- Hydrogen Combustion Adaptation:Emerging hydrogen-fired turbine architectures require modified superalloy chemistries resistant to high-temperature steam oxidation, opening formulation development white space.
- Digital Twin Integration:Physics-based remaining-life prediction models are converging with sensor-embedded engine hardware, enabling predictive MRO scheduling and expanding aftermarket alloy demand.
Industry Challenges
- Master Melter Shortage:The specialized workforce capable of controlling vacuum arc remelting solidification microstructure is aging out faster than training pipelines can replenish.
- FAA-EASA Divergence:Emerging differences in certification data package requirements for powder metallurgy superalloys are forcing dual-track qualification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Superalloys Market |
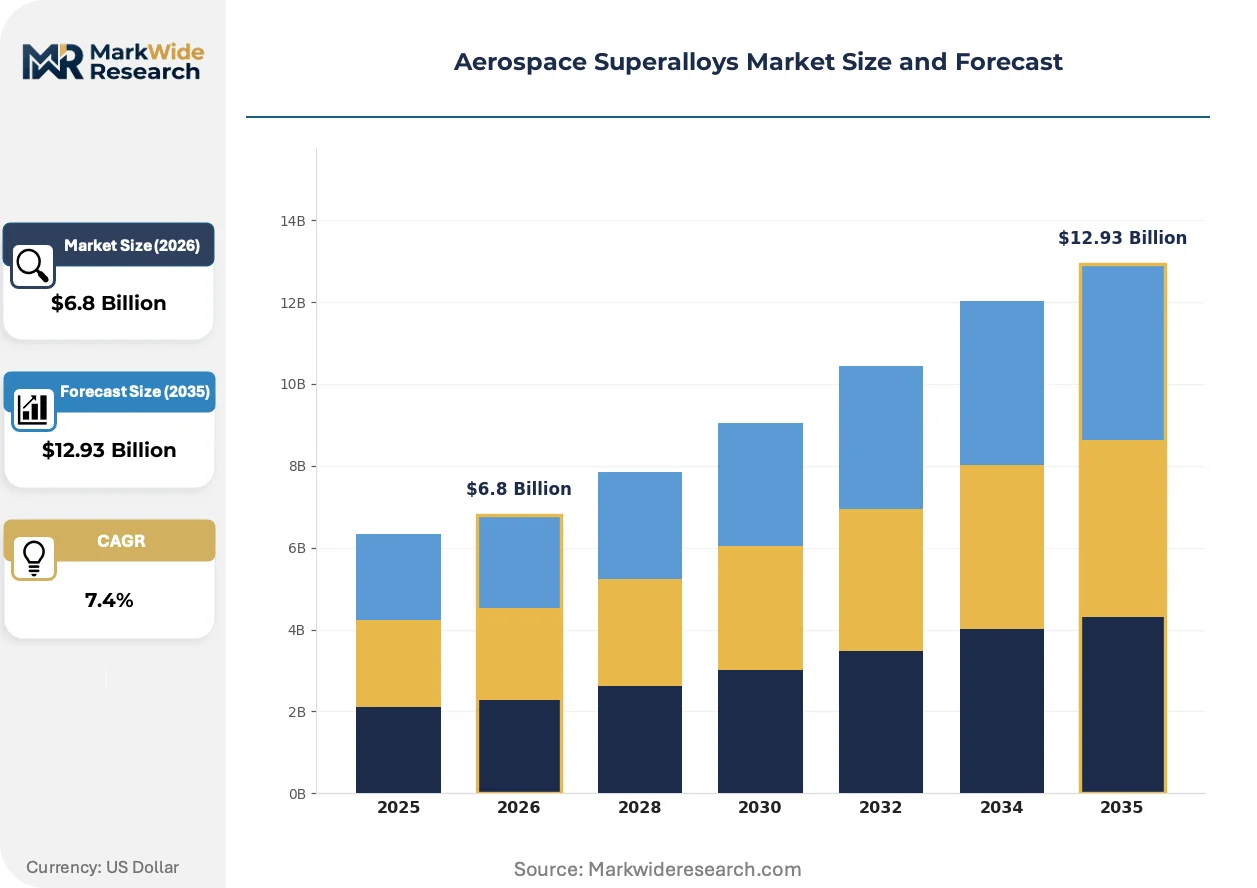
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nickel-Based, Cobalt-Based, Iron-Based, Titanium-Based Application: Jet Engines, Turbines, Structural Components, Heat Exchangers Form: Alloy Powder, Sheet, Bar, Forged Parts End User: Aerospace Manufacturers, Defense Contractors, MRO Services, Research Institutions |
| Companies Covered | Allegheny Technologies Incorporated (ATI), Carpenter Technology Corporation, Haynes International, Precision Castparts Corp., Special Metals Corporation, Doncasters Group, Cannon-Muskegon, Arconic, thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Superalloys Market Emerging Trajectories
Computational materials science is compressing traditional alloy development timelines from decades to years, while sustainability mandates are rewriting supplier qualification criteria. These forces are converging to reshape competitive positioning around digital capabilities and circular material flows.
High-entropy alloy coatings deposited via plasma-transferred arc welding are unifying oxidation protection and thermal barrier functions previously served by separate ceramic topcoats and metallic bond coats. Pratt & Whitney and Rolls-Royce are integrating these systems into next-generation high-pressure turbine airfoils. This unification is eliminating thermal expansion mismatch failures and reducing component count in the hottest engine sections.
REACH substance restrictions and the EU Green Deal material passport framework are mandating full supply chain disclosure of alloy chemistry and recycling content for aerospace components entering European service. The ECHA is expanding candidate list scrutiny on cobalt and chromium compounds critical to superalloy formulations. European MRO providers are responding by qualifying alternative chemistries and securing certified scrap recycling streams to maintain compliance margins.
Long-term offtake contracting is displacing spot procurement for critical rotating components as OEMs seek to lock in single-crystal casting capacity. Safran and GE Aerospace are negotiating decade-spanning agreements directly with qualified foundries, bypassing traditional distributor channels. This pattern is most visible in the United States and France, where defense and commercial engine production lines are competing for the same constrained supplier base.
Aerospace Superalloys Market Segmentation
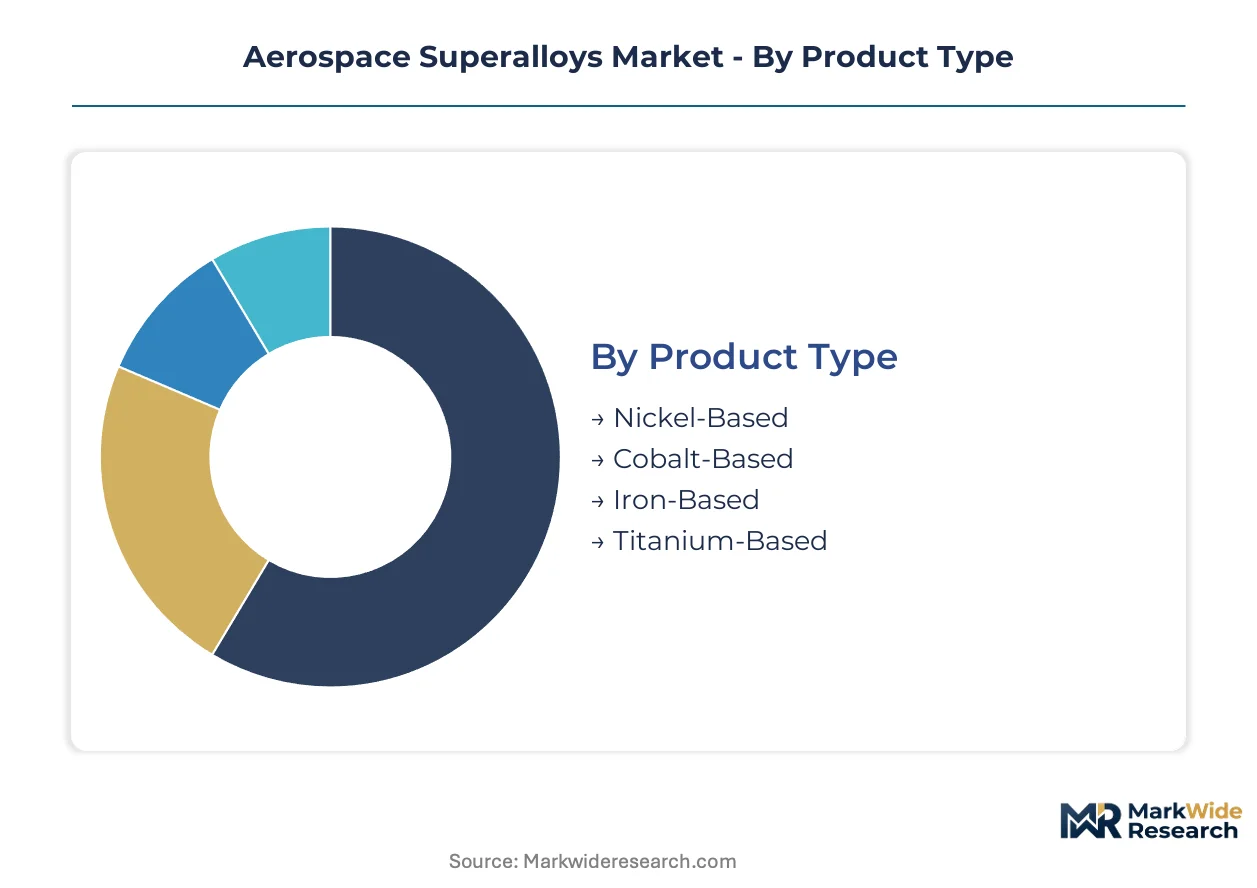
Superalloy procurement decisions hinge on precise matching of thermal-mechanical properties to component-specific duty cycles. Segmentation reveals how material form and chemistry align with distinct value chains across propulsion systems and airframe structures.
Product Type:
Material chemistry dictates service temperature ceilings, oxidation resistance, and manufacturing compatibility across hot-section applications.
- Nickel-Based:These alloys incorporate chromium, cobalt, and refractory elements to retain tensile strength above 80 percent of melting temperature. Demand concentrates in high-pressure turbine disks and single-crystal blades for next-generation jet engines, where FAA and EASA certification thresholds mandate proven creep-rupture performance. Nickel-based formulations command the dominant margin pool due to entrenched OEM qualification pathways.
- Cobalt-Based:Haynes International and specialty suppliers engineer these systems for extreme thermal cycling in afterburner sections and combustor liners. Procurement from defense contractors in the United States and Germany is intensifying as sixth-generation fighter programs specify superior hot corrosion resistance. Cobalt's face-centered cubic structure provides exceptional wear characteristics where thermal gradients exceed nickel alloy limits.
- Iron-Based:Lower-cost alternatives for intermediate-temperature compressor casings and non-rotating hardware where density reduction outweighs absolute thermal performance.
- Titanium-Based:Intermediate-weight solutions for fan frames and cold-section components requiring specific strength advantages below 600°C service thresholds.
Nickel-based alloys lead on scale; cobalt-based alloys lead on momentum in defense procurement cycles.
Application:
Component location within propulsion and airframe systems determines alloy specification, thermal barrier requirements, and qualification rigor.
- Jet Engines:Hot-section rotating hardware demands vacuum-melted nickel superalloys with verified fatigue life. China, the United States, and Germany are concentrating procurement for single-crystal turbine blades as adaptive-cycle commercial engines and military propulsion systems advance simultaneously.
- Turbines:Land-based and auxiliary power units utilize directionally solidified castings and wrought disk alloys with shorter qualification cycles than flight-critical hardware. Industrial gas turbine OEMs in Germany and Japan are locking in multi-year offtake agreements for forged rotor components.
- Structural Components:Landing gear, engine mounts, and airframe attachments employ precipitation-hardened nickel alloys where high specific strength and corrosion resistance converge.
- Heat Exchangers:Compact recuperators and precoolers in emerging hydrogen combustion architectures require modified chemistries resistant to high-temperature steam oxidation.
Jet engines dominate absolute alloy consumption; heat exchangers are climbing fastest as hydrogen propulsion architectures mature.
Form:
Manufacturing process selection governs grain structure, defect tolerance, and geometric complexity achievable for each component class.
- Alloy Powder:Gas-atomized feedstocks enable powder-bed fusion and directed energy deposition for complex turbine vanes and structural brackets. Additive manufacturing penetration is expanding addressable geometries beyond legacy forging constraints.
- Forged Parts:Large-diameter engine casings and compressor rotors require directional grain structure control through isothermal and conventional forging. These remain the volume anchor where ingot metallurgy and deformation processing ensure structural integrity.
- Sheet:Thin-gauge rolled product for combustor liners and afterburner flaps requiring thermal fatigue resistance in planar configurations.
- Bar:Round and rectangular mill products for machined rotating components where billet conversion yields favorable radial grain flow.
Forged parts anchor current procurement volumes; alloy powder is gaining share fastest as qualification timelines for additive hardware compress.
End User:
Customer category shapes specification stringency, contract duration, and aftermarket service requirements.
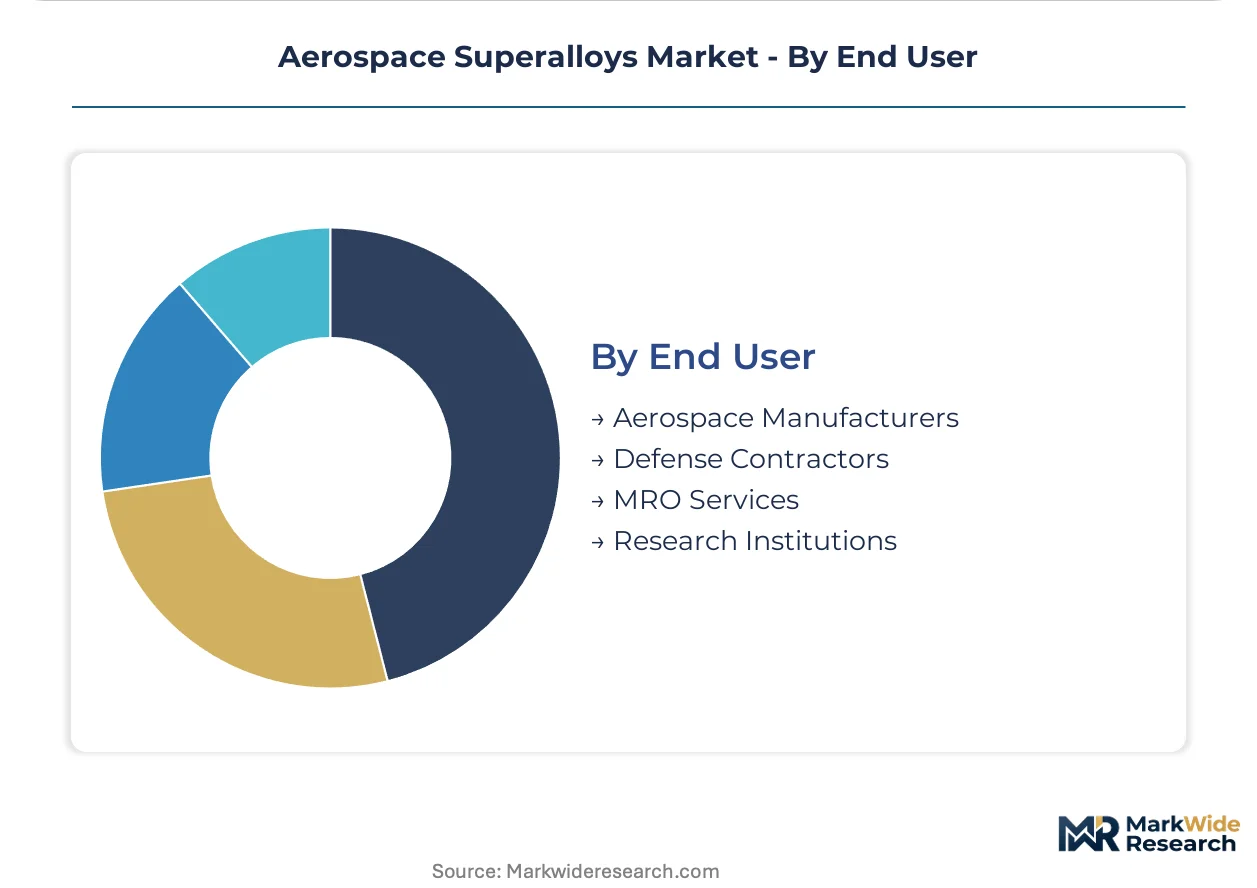
- Aerospace Manufacturers:Pratt & Whitney, Rolls-Royce, and Safran specify proprietary alloy grades with multi-decade qualification heritage. These OEMs negotiate decade-spanning offtake agreements directly with qualified foundries, bypassing traditional distribution channels.
- Defense Contractors:Sixth-generation fighter and hypersonic system programs demand superalloys with superior creep resistance above 1,100°C. Procurement in the United States prioritizes domestic vacuum melting capacity per DOD supply chain security directives.
- MRO Services:Overhaul providers track REACH substance restrictions and emerging EU Green Deal material passport requirements affecting alloy chemistry and supplier qualification timelines. Digital twin integration is enabling predictive remaining-life scheduling.
- Research Institutions:National laboratories and university programs drive computational materials science applications that compress traditional alloy development timelines.
Aerospace manufacturers command procurement scale; defense contractors are expanding fastest as hypersonic and next-generation fighter programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cincinnati-Wright Patterson corridor concentrates the most sophisticated vacuum-melting infrastructure for rotating disk alloys. Defense procurement from next-generation fighter programs and adaptive-cycle commercial engine development are reshaping capacity allocation across qualified foundries.
United States
Pratt & Whitney and GE Aerospace drive single-crystal blade demand for adaptive-cycle engines. FAA certification thresholds for creep-rupture performance govern supplier qualification timelines. The Cincinnati-Dayton corridor hosts concentrated vacuum arc remelting capacity serving both commercial and defense propulsion systems.
China
Domestic fighter engine programs and C919 narrowbody production are accelerating indigenized superalloy melting investment. MIIT industrial policy prioritizes closed-loop rhenium recovery to reduce import dependence. Shenyang and Xi'an aerospace clusters are expanding directional solidification foundry capacity for turbine blade production.
Germany
MTU Aero Engines and industrial gas turbine OEMs lock in multi-year offtake agreements for forged rotor components. REACH substance restrictions on cobalt compounds are forcing qualification of alternative chemistries. The Munich-Stuttgart axis concentrates precision investment casting for high-pressure turbine hardware.
France
Safran's LEAP and next-generation military engine programs concentrate procurement for single-crystal superalloys. EASA certification standards for powder metallurgy hardware diverge from FAA data package requirements. The Paris-Saclay cluster integrates computational materials science with foundry process development.
India
The PLI scheme for aerospace components is creating captive demand for indigenized superalloy capacity to supply Kaveri fighter engine development. BIS standards for aerospace materials are aligning with EASA technical specifications. Hyderabad and Bangalore defense corridors are qualifying vacuum induction melting for rotating disk alloys.
Aerospace Superalloys Market Vendor Landscape
Long-term offtake contracting dominates the current landscape as OEMs bypass traditional distribution channels to secure constrained foundry capacity. The supplier base concentrates around three qualified tiers: integrated primary melters with captive forging, specialized investment casting foundries, and emerging additive manufacturing powder suppliers. Strategic archetypes include vacuum-melting specialists with multi-decade OEM qualification heritage and regional champions serving defense localization mandates. Capacity expansion and backward integration into rhenium recovery represent the dominant competitive moves.
Among US-based integrated suppliers, Carpenter Technology Corporation and Precision Castparts Corp. exemplify the vacuum-melting specialist archetype with entrenched positions in rotating component supply chains. Haynes International occupies a distinct position within cobalt-based formulation expertise for extreme thermal cycling applications. These three anchors demonstrate how qualification heritage and metallurgical process control create defensive moats against new entrant competition.
| Leading Market Players |
|---|
| Allegheny Technologies Incorporated (ATI) |
| Carpenter Technology Corporation |
| Haynes International |
| Precision Castparts Corp. |
| Special Metals Corporation |
| Doncasters Group |
| Cannon-Muskegon |
| Arconic |
| thyssenkrupp AG |
| Others |
Supply Flow & Price Mechanics
Rhenium spot price volatility cascades through aerospace superalloy supply chains into three distinct procurement tiers: premium single-crystal formulations for rotating turbine hardware, standard vacuum-melted alloys for structural components, and economy-grade wrought products for non-critical applications. This commodity-driven stratification concentrates pricing power among integrated melters with captive rhenium recovery while squeezing margin pools for distributors lacking backward integration.
Pricing Analysis
Input-cost pass-through from Chilean and Kazakh rhenium extraction dominates alloy pricing dynamics. Three-tier pricing structure across premium single-crystal, standard directionally-solidified, and economy wrought grades differentiates by certification tier and thermal performance threshold. Pricing pressure stems from REACH compliance costs and EASA material passport documentation requirements. Defense contractors exhibit lowest price sensitivity due to DOD supply chain security mandates, while industrial gas turbine OEMs negotiate hardest on volume contracts.
Supply Chain Analysis
Direct-to-OEM channels handle Pratt & Whitney and GE Aerospace demand for rotating disk alloys, bypassing traditional metal distribution. Supply concentrates in the United States, Germany, and Japan for triple-melt capacity, with China expanding domestic vacuum induction infrastructure. The chain draws from Chilean rhenium, South African chromium, and Russian nickel feedstocks. Single-source vulnerability around master melter expertise creates acute qualification risk. Distribution runs through decade-spanning offtake agreements rather than spot procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace superalloys market compounds steadily as next-generation propulsion programs sustain multi-decade demand visibility against constrained casting capacity. FAA and EASA certification timelines create defensive moats that protect incumbent returns.
For Market Incumbents: Acquire rhenium recovery assets to secure refractory element supply against Chilean and Kazakh concentration risk. Expand directional solidification foundry capacity in the Cincinnati-Dayton corridor to capture sixth-generation fighter and adaptive-cycle commercial engine demand. Lock in multi-decade offtake agreements before emerging EU Green Deal material passport requirements reshape supplier qualification criteria.
For New Entrants and Emerging Players: Enter via additive manufacturing powder supply for complex turbine vanes and structural brackets where legacy forging constraints limit incumbent response. Target India's PLI scheme aerospace corridors in Hyderabad and Bangalore, where domestic Kaveri fighter engine programs create captive demand for qualified vacuum melting capacity. Pursue EASA technical specification alignment as the fastest pathway to European MRO service qualification.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized investment casting foundries holding active FAA and EASA approvals for single-crystal hardware. Long-term viability hinges on decade-spanning OEM relationships and master melter workforce depth. Watch for hydrogen combustion architecture announcements from Pratt & Whitney and Rolls-Royce as the inflection signal for modified superalloy chemistry demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rhenium Recovery | Captive supply of Chilean-extracted refractory elements secures third-generation single-crystal alloy production. |
| Long-term Supply Agreement | Decade-spanning offtake contracts with Safran and GE Aerospace lock in constrained foundry capacity. |
| Green Manufacturing Transition | Closed-loop recycling capabilities satisfy EU Green Deal material passport requirements for European service. |
| Capacity Expansion | Directional solidification foundry buildout in the Cincinnati-Wright Patterson corridor serves defense procurement. |
| Joint Venture | Technology partnerships with national laboratories compress computational materials science development timelines. |
Methodological Framework
Bottom-up jet engine and turbine modeling reconciled against top-down vacuum melting capacity tracking forms the analytical core of this study. Primary interviews with superalloy procurement executives at Pratt & Whitney, Rolls-Royce, and Safran; master melter technical leads at qualified foundries; defense contractor materials engineers; and MRO service qualification managers combined with secondary validation from FAA airworthiness directives, EASA certification standards, EPA emissions filings, and SEC 10-K disclosures from Carpenter Technology and Haynes International. Top-down and bottom-up triangulation ensured segment-level consistency.
Historical trendline analysis of nickel-based superalloy consumption across commercial turbofan, military propulsion, and industrial gas turbine applications established baseline growth patterns. The projection framework segments by material chemistry, component application, manufacturing form, and end-user category, with CAGRs derived from engine program delivery schedules and OEM capacity announcements. Forecast inputs include adaptive-cycle engine development timelines, sixth-generation fighter procurement cycles, and hydrogen combustion architecture maturation curves.
Inputs from FAA certification databases and EASA type certificate records were available through the study window; gaps in proprietary OEM alloy specification data introduce uncertainty bands around single-crystal blade demand forecasts. Periodic stress-testing of base assumptions against REACH substance restriction expansions and rhenium supply disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market