
 Power Grid Primary and Secondary Fusion Equipment Market | 2026-2036
Power Grid Primary and Secondary Fusion Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Power Grid Primary and Secondary Fusion Equipment Market Insights
Renewable energy integration is restructuring utility procurement priorities for primary and secondary fusion equipment. Siemens leverages its digital grid portfolio to anchor European utility contracts. ABB competes through high-voltage direct current expertise in offshore wind interconnection projects. General Electric sustains manufacturing scale across transformer and switchgear lines for North American infrastructure renewal.
Power grid primary and secondary fusion equipment encompasses circuit-interrupting and voltage-transformation apparatus rated from distribution-level kilovolts through extra-high-voltage classes, employing SF6 or vacuum insulation media with microprocessor-based protection coordination. This equipment enables fault isolation, load transfer, and voltage regulation across meshed transmission and radial distribution architectures. Circuit breakers and switchgear command the dominant share of capital allocation due to their criticality in fault-clearing speed and arc-quenching reliability. Protection relays represent the fastest-expanding category as IEC 61850-process-bus architectures displace hardwired copper interfaces. Transformers remain margin-dense where amorphous core materials and vegetable-based insulating oils command technical premiums.
IEC 61850, IEEE C37.90, and GB/T 14285 collectively dictate interoperability, electromagnetic immunity, and protection-logic standards that determine product certification and market access across Europe, North America, and China. China's SAMR enforces GB standards for grid equipment while India's CEA mandates centralized testing protocols for interconnection compatibility. Stakeholders must monitor evolving F-Gas Regulation phase-down timelines in Europe and China's dual carbon policy stringency to calibrate insulation technology roadmaps and regional manufacturing commitments.
Market Dynamics
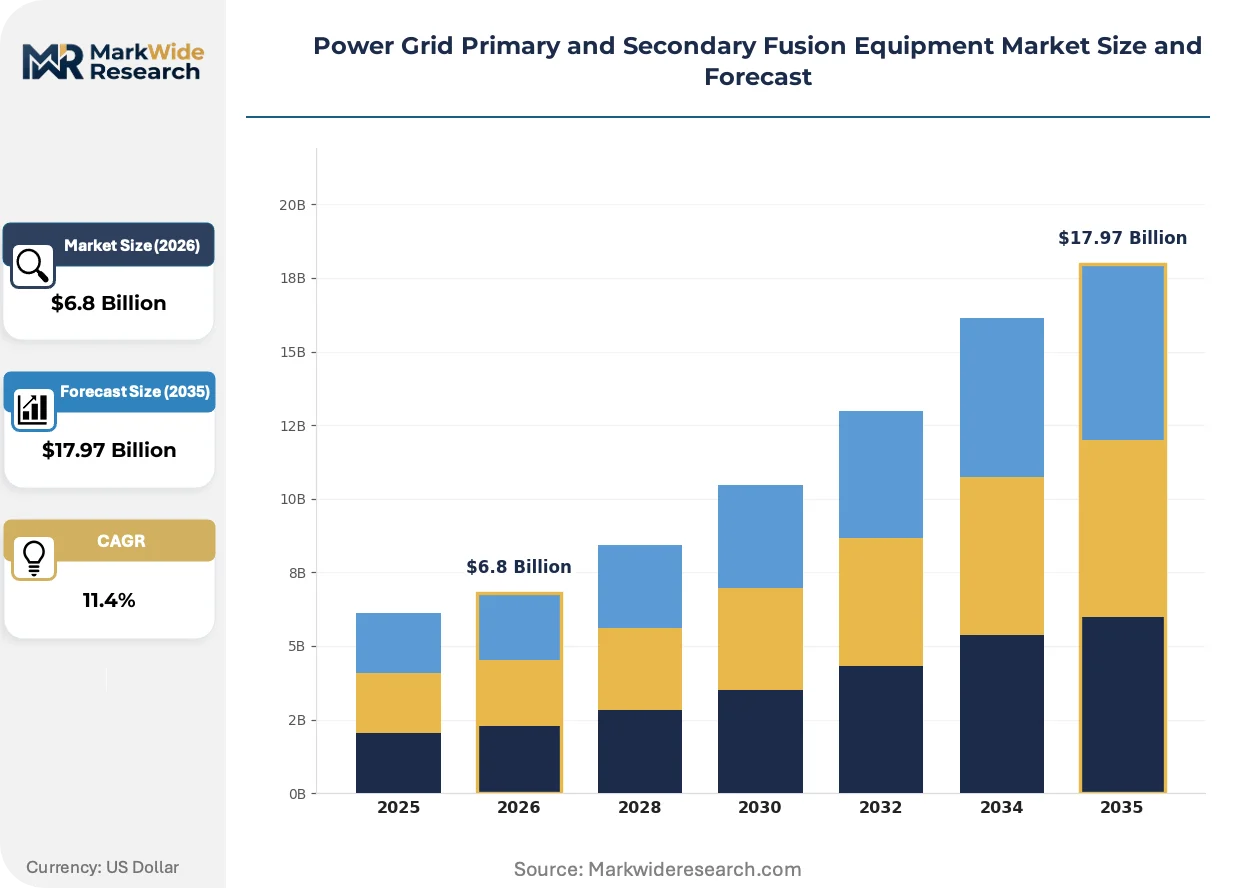
Ultra-high voltage transmission buildouts in China and IEC 61850 digitalization mandates are restructuring procurement priorities for fusion equipment across transmission and distribution utilities.
Growth Catalysts
- Ultra-High Voltage Buildouts:China's State Grid Corporation drives demand for 1,100 kV class transformers and switchgear through trans-regional power transmission corridors connecting western generation bases to eastern load centers.
- IEC 61850 Process Bus Architecture:Hardwired copper interfaces between protection relays and circuit breakers are yielding to Ethernet-based sampled value networks, accelerating replacement cycles in European and North American substations.
- Vegetable-Based Insulating Oils:Ester fluids derived from rapeseed and soybean crops are penetrating transformer specifications where fire safety and biodegradability requirements tighten environmental compliance.
Market Restraints
- SF6 Gas Phase-Down:Europe's F-Gas Regulation imposes stringent quotas on sulfur hexafluoride, forcing manufacturers to accelerate vacuum interrupter and clean air insulation development without mature supply chains.
- Grain-Oriented Electrical Steel Concentration:Transformer core material supply concentrates among Japanese and South Korean metallurgical producers, exposing procurement costs to capacity constraints and trade flow disruptions.
- Amorphous Metal Casting Limitations:Distribution transformer efficiency gains from amorphous alloy cores remain supply-constrained by limited ribbon casting furnace capacity and specialized annealing expertise.
Strategic Opportunities
- Digital Twin Integration:Real-time thermal and dissolved gas analysis models for power transformers enable predictive maintenance contracts and asset performance guarantees for utility fleet operators.
- India's Green Energy Corridors:The country's Central Electricity Authority mandates standardized testing protocols for renewable interconnection equipment, opening procurement windows for IEC-certified switchgear and protection systems.
- Modular Mobile Substations:Compact skid-mounted transformer and switchgear assemblies address emergency restoration and temporary load growth in disaster-prone regions and mining extraction sites.
Industry Challenges
- IEC 61850 Engineering Expertise Scarcity:System configuration description file engineering and sampled value network commissioning require specialized substation automation skills that utility workforces and contractor pools lack at scale.
- Legacy Electromechanical Relay Obsolescence:Utilities face complex migration pathways from static protection schemes to microprocessor-based platforms, demanding staged cutover strategies that maintain fault coverage during transition periods.
- Multi-Vendor Interoperability Certification:Client-server conformance testing across protection relay, merging unit, and circuit breaker intelligent electronic devices from different suppliers extends project timelines and integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Grid Primary and Secondary Fusion Equipment Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Circuit Breakers, Transformers, Switchgear, Protection Relays Operation Mode: Manual, Automatic, Semi-Automatic, Remote-Controlled End User: Utilities, Industrial Facilities, Commercial Complexes, Government Agencies Installation Type: Onshore, Offshore, Underground, Above Ground |
| Companies Covered | Siemens, ABB, General Electric, Toshiba, Nari Technology, XJ Electric, Henan Pinggao Electric, Schneider Electric, Shanghai Holystar Information Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Grid Primary and Secondary Fusion Equipment Market Trends and Innovations
Digital substation architectures and sustainable insulation chemistries are converging to redefine equipment specifications, testing protocols, and lifecycle service models across transmission and distribution networks.
Digital twin platforms for power transformers aggregate dissolved gas analysis, load tap changer operation counts, and thermal imaging data into predictive degradation models. European transmission system operators deploy these systems to extend asset life and defer capital replacement. This capability is decentralizing maintenance decision-making from centralized asset management departments to regional operations centers with direct field visibility.
Europe's F-Gas Regulation mandates an 80 percent reduction in SF6 emissions by 2030 from 2014 baselines, accelerating vacuum interrupter development for high-voltage circuit breakers above 72.5 kV. Manufacturers must redesign arc quenching chambers and operating mechanisms while maintaining fault-clearing speed performance. German and French utilities now specify SF6-free alternatives in tender documents, compressing market access for conventional gas-insulated switchgear.
Performance-based service contracts for switchgear and transformer fleets are displacing traditional time-based maintenance schedules. Nordic distribution utilities lead this transition, linking contractor payments to availability guarantees and fault interruption reliability metrics rather than prescribed inspection frequencies. This restructuring concentrates risk with equipment manufacturers and specialized service providers while transferring operational accountability away from utility maintenance departments.
Power Grid Primary and Secondary Fusion Equipment Market Segmentation
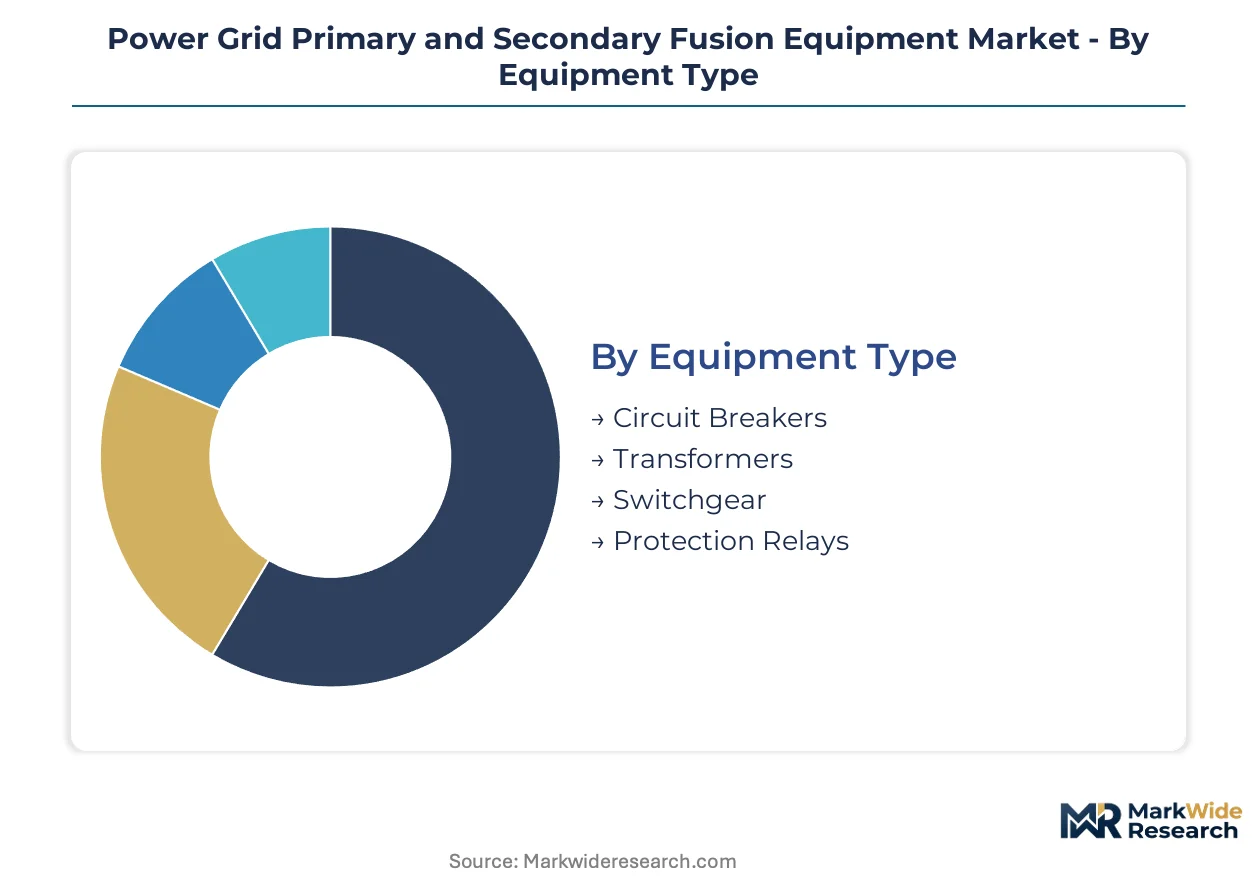
Equipment classification in power grid fusion systems determines procurement specifications, lifecycle cost models, and interoperability requirements across transmission and distribution networks. Segmentation reveals where capital concentrates and which technology trajectories command premium pricing.
Equipment Type:
Circuit breakers and switchgear anchor volume procurement, while protection relays capture the steepest technology premium expansion.
- Circuit Breakers:These fault-interrupting devices employ SF6 or vacuum arc-quenching media rated from distribution-level kilovolts through ultra-high-voltage classes. State Grid Corporation specifications for 1,100 kV corridors in China concentrate demand for gas-insulated designs, though Europe's F-Gas Regulation accelerates vacuum alternative development.
- Transformers:Voltage-transformation apparatus spans power and distribution classes with core materials ranging from grain-oriented electrical steel to amorphous alloys. Vegetable-based ester insulating fluids penetrate specifications where fire safety and biodegradability tighten environmental compliance.
- Switchgear:Metal-enclosed assemblies integrate circuit breakers, disconnectors, and earthing switches for fault isolation and load transfer.
- Protection Relays:Microprocessor-based devices coordinate fault detection and clearing logic through IEC 61850 process bus architectures.
Today's leader: Circuit Breakers. Tomorrow's challenger: Protection Relays.
Operation Mode:
Automation intensity correlates directly with grid modernization investment cycles and workforce availability constraints.
- Automatic:Self-acting protection and reclosure systems eliminate human response latency during fault events. Nordic distribution utilities specify these for remote substations where travel time to site exceeds acceptable outage duration, linking contractor payments to availability guarantees rather than inspection frequency.
- Remote-Controlled:SCADA-integrated operation enables centralized dispatch control across geographically dispersed assets. India's Green Energy Corridor mandates standardized protocols for renewable interconnection, opening procurement windows for remotely operable switchgear and protection systems.
- Manual:Direct operator intervention for switching operations and maintenance isolation.
- Semi-Automatic:Hybrid modes requiring local initiation with automated sequence completion.
Automatic systems dominate new installations. Remote-Controlled architectures gain fastest in distributed generation integration zones.
End User:
Utility procurement scales dwarf industrial volume, though commercial and government segments exhibit distinct specification patterns.
- Utilities:Transmission and distribution operators specify equipment for meshed network architectures and radial distribution feeders. North American utilities expand grid modernization investments, prioritizing IEC 61850 digitalization and digital twin integration for predictive maintenance contracts.
- Industrial Facilities:Manufacturing and extraction sites demand ruggedized equipment for high-fault-current environments. Mining operations specify modular mobile substations for temporary load growth and emergency restoration in disaster-prone regions.
- Commercial Complexes:Data centers and medical campuses prioritize compact underground installations with fire-resistant insulation.
- Government Agencies:Military and critical infrastructure operators mandate hardened specifications for electromagnetic immunity and physical security.
Utilities command procurement scale. Industrial Facilities expand fastest in resource extraction and manufacturing reshoring zones.
Installation Type:
Physical deployment configuration determines environmental protection ratings, thermal management design, and civil engineering cost structures.
- Above Ground:Conventional open-air substations with exposed buswork and free-air cooling dominate established transmission corridors. State Grid Corporation's trans-regional power transmission buildouts in western China concentrate demand for these cost-optimized configurations.
- Underground:Urban land scarcity and aesthetic constraints drive compact GIS installations in dense European and Asian metropolitan zones. German and French utilities now specify SF6-free alternatives in tender documents, compressing market access for conventional gas-insulated designs.
- Onshore:Terrestrial installations across standard elevation and seismic conditions.
- Offshore:Platform-mounted equipment for wind farm interconnection and subsea cable termination.
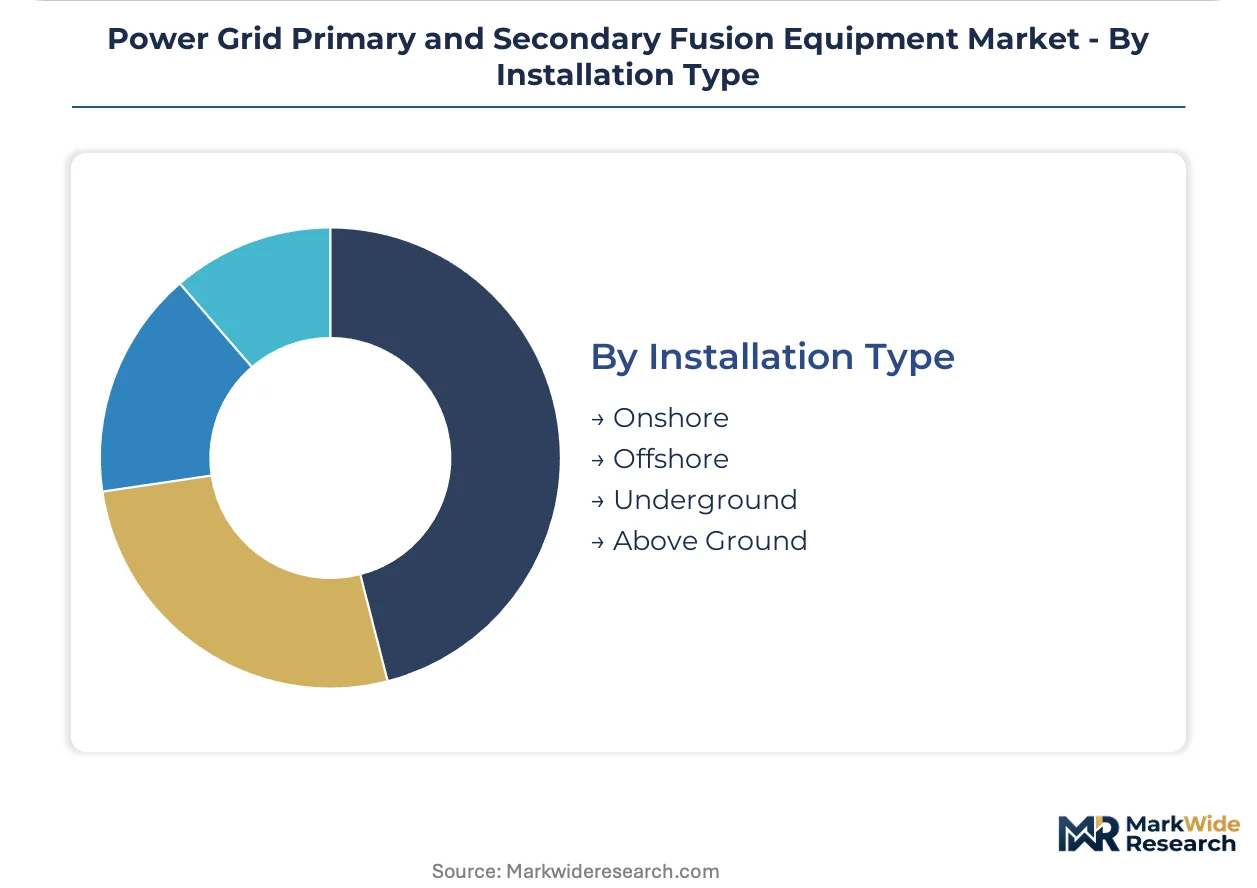
Above Ground retains cost advantage. Underground configurations expand most quickly in urban densification corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers relocate to jurisdictions with lower compliance costs for SF6 phase-down timelines and carbon border adjustments. China's dual carbon policy and Europe's F-Gas Regulation create divergent cost structures that influence equipment sourcing decisions.
China
State Grid Corporation's 1,100 kV ultra-high voltage corridors drive transformer and switchgear procurement at unmatched scale. SAMR enforces GB standards for grid equipment certification while MEE implements dual carbon targets that accelerate clean air insulation development. XJ Electric and Henan Pinggao Electric anchor production clusters in Henan province serving western generation-to-eastern load transmission buildouts.
Germany
Transmission system operators specify SF6-free alternatives in tender documents under F-Gas Regulation mandates. ECHA oversees chemical compliance for ester-based insulating fluids penetrating transformer specifications. Industrial concentrations in Bavaria and North Rhine-Westphalia host Siemens digital grid engineering centers developing IEC 61850 process bus architectures.
United States
FERC grid modernization incentives accelerate utility procurement of digital substation equipment across Texas and California independent system operator territories. EPA monitors SF6 emissions from existing gas-insulated installations while IRA provisions support transformer efficiency upgrades. Manufacturing activity concentrates in the Midwest electrical steel corridor serving North American infrastructure renewal cycles.
India
CEA-mandated standardized testing protocols for Green Energy Corridor renewable interconnection equipment open procurement windows for IEC-certified switchgear. BIS certification requirements govern domestic manufacturing while state transmission utilities in Maharashtra and Gujarat expand high-voltage substation capacity. Domestic producers Nari Technology and regional fabricators scale assembly operations to meet localization targets.
Japan
METI directs grid resilience investments following regional supply disruptions, prioritizing seismic-resistant transformer specifications. JIS standards govern interoperability with legacy protection systems while utilities in the Kanto and Kansai regions deploy digital twin platforms for predictive maintenance. Toshiba anchors domestic manufacturing alongside specialized suppliers serving island grid architecture requirements.
Power Grid Primary and Secondary Fusion Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical conglomerates commanding transmission-level procurement and regional fabricators capturing distribution-tier volume. The vendor base organizes around three archetypes: full-spectrum grid solution providers, component-specialized manufacturers, and state-affiliated national champions. Consolidation pressure intensifies as digitalization requirements favor players with embedded software capabilities. Dominant competitive moves include backward integration into core material supply and strategic partnerships for IEC 61850 engineering expertise.
Among European-based full-spectrum providers, Siemens and ABB exemplify the integrated archetype spanning protection systems through high-voltage switchgear. General Electric occupies a position representing North American manufacturing scale across transformer and circuit breaker lines. Chinese state-affiliated champions including Nari Technology and XJ Electric sit within the national champion tier, leveraging domestic ultra-high voltage demand to anchor regional procurement relationships.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| General Electric |
| Toshiba |
| Nari Technology |
| XJ Electric |
| Henan Pinggao Electric |
| Schneider Electric |
| Shanghai Holystar Information Technology |
| Others |
Pricing and Supply Chain Analysis
Performance-tier bifurcation between IEC 61850-certified digital substation equipment and legacy electromechanical systems manifests in both pricing premiums and supply chain configurations. Siemens and ABB command 15-25% price premiums for process-bus architectures while procurement officers at State Grid Corporation and European transmission operators absorb longer lead times for certified components.
Pricing Analysis
Distributor margins of 12-18% for circuit breakers and switchgear compress to 6-10% for bulk utility contracts direct from manufacturers. Pricing stratifies across premium, standard, and economy tiers where amorphous core transformers and vegetable-based ester fluids capture technical premiums against grain-oriented steel designs. Cost compression in vacuum interrupter development intensifies as Europe's F-Gas Regulation accelerates SF6-free alternatives. Industrial facilities exhibit highest price sensitivity due to project-based procurement cycles, while transmission utilities prioritize availability guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean producers of grain-oriented electrical steel for transformer cores. Manufacturing concentrates in China, Germany, and the United States for high-voltage switchgear assemblies. Raw material dependencies include copper buswork, SF6 or vacuum interrupter tubes, and amorphous metal ribbon. Tariff exposure on electrical steel imports from Asia threatens cost structures for North American transformer producers. Distribution runs through authorized distributors for smaller utilities and direct OEM relationships for national transmission operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers locate production in jurisdictions with delayed SF6 phase-down timelines to supply equipment to Europe's constrained market. The 80% F-Gas Regulation reduction mandate creates divergent cost structures between German compliance-heavy production and Chinese or Indian manufacturing alternatives.
For Market Incumbents: Deepen backward integration into amorphous metal casting capacity to secure transformer core material supply against Japanese and South Korean concentration. Fortify IEC 61850 engineering expertise through captive training programs or acquisition of specialized substation automation consultancies to address workforce scarcity threatening project timelines. For New Entrants and Emerging Players: Enter via modular mobile substation segments serving mining operations and disaster-prone regions where incumbent coverage remains thin. Target India's Green Energy Corridor procurement windows where CEA-mandated standardized testing protocols level the certification playing field against established European suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where digitalization requirements favor players with embedded software capabilities over hardware-only manufacturers. Long-term viability hinges on IEC 61850 process bus architecture competence and clean air insulation technology portfolios. Acquisition target archetype: mid-cap specialists with SAMR certification for Chinese ultra-high voltage corridors. Signal to watch: F-Gas Regulation quota tightening accelerating vacuum interrupter demand beyond current manufacturing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Materials | Captive amorphous metal casting secures transformer efficiency gains against supply-constrained ribbon furnace capacity. |
| IEC 61850 Engineering Capability Buildout | Process bus commissioning expertise addresses utility workforce gaps and accelerates digital substation deployment timelines. |
| SF6-Free Product Line Development | Vacuum interrupter and clean air insulation designs unlock German and French tender access under F-Gas Regulation mandates. |
| Digital Twin Platform Integration | Predictive maintenance contracts for transformer fleets transfer operational risk from utilities to equipment manufacturers. |
| Modular Mobile Substation Manufacturing | Compact skid-mounted assemblies serve emergency restoration and temporary load growth in mining and disaster-prone regions. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down transformer and switchgear production tracking forms the analytical core of this study. Primary interviews with transmission planning officers, distribution asset managers, EPC contractors, and protection system integrators were validated against secondary sources including FERC filings, EIA infrastructure databases, State Grid Corporation tender announcements, and IEC standardization committee documentation. Triangulation across these inputs ensures segmentation integrity across equipment type, operation mode, and end-user categories.
Input-output matrices map transformer core material flows, circuit breaker manufacturing capacity, and protection relay shipment volumes to derive segment-level expansion rates across the projection horizon. Segmentation dimensions modeled include voltage class tier, insulation medium type, automation architecture, and regional regulatory framework. CAGRs were computed from installed base replacement cycles and greenfield transmission corridor development pipelines. Forecast inputs incorporate SAMR certification timelines, F-Gas Regulation quota trajectories, and grain-oriented electrical steel trade flow patterns.
Inputs from utility procurement databases and manufacturer shipment records were available through the study window; gaps in real-time project cancellation data and subsidy program modification timing introduce uncertainty bands around capacity addition assumptions. Forecasts reflect documented assumptions regarding IEC 61850 adoption velocity and SF6 alternative technology maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
SCR Power Controller Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Deaerators Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Industrial Power Transmission Drive Belts Market