
 Wind Power Fastener Market | 2026-2036
Wind Power Fastener Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Fastener Market Analysis
Project finance structures with long-term power purchase agreements are reshaping capital deployment across wind installations, lowering barriers for independent developers and altering procurement timelines for component suppliers. Vestas Wind Systems leverages its integrated supply chain to control fastener specifications across turbine platforms. Siemens Gamesa Renewable Energy anchors European offshore demand through direct OEM relationships with certified fastener vendors. Goldwind dominates domestic sourcing in China, where captive supply networks reduce import dependency for critical bolting systems.
Wind power fasteners are high-strength mechanical joining elements, typically manufactured from alloyed carbon steel or duplex stainless steel with tensile ratings exceeding 1,000 MPa, designed to withstand cyclic loading, salt corrosion, and thermal expansion in rotating machinery and steel tower structures. Bolts command the largest product volume share due to their load-bearing function in tower flanges and nacelle frames, though stainless steel variants are gaining share as offshore salt exposure intensifies material performance requirements. Turbine assembly and tower construction represent the primary application channels, with blade attachment emerging as a higher-margin segment as longer blades impose stricter fatigue-resistance specifications on root-fastening hardware.
FDA standards for material traceability intersect with ISO 898-1 mechanical property classifications to govern fastener acceptance in regulated wind energy projects, while the EU Green Deal's embedded carbon requirements are pressuring mills to document emissions across steel production. China's GB standards and MIIT industrial policy directives enforce domestic content ratios that redirect procurement toward local fastener manufacturers. Stakeholders must monitor evolving certification protocols for hydrogen embrittlement resistance as turbine OEMs extend design life expectations beyond twenty-five years.
Market Dynamics
Offshore wind turbine scaling is compressing fastener procurement cycles as tower OEMs demand corrosion-resistant bolting systems certified for 25-year design life in salt-laden environments.
Growth Catalysts
- EU Green Deal embedded carbon mandates:Steel mills must document production emissions, redirecting procurement toward European fastener vendors with verified supply chain transparency.
- China's MIIT localization directives:Domestic content ratios enforce captive sourcing for multi-megawatt turbine assembly, building indigenous bolting capacity.
- Stainless steel bolting adoption:Duplex grades with superior chloride resistance are displacing carbon steel variants in North Sea and Baltic offshore installations.
Market Restraints
- Alloy steel price volatility:Nickel and molybdenum input costs swing with commodity cycles, squeezing margin structures for precision-forged fasteners.
- European supply concentration:Certified fastener vendors cluster in Germany and Scandinavia, creating geographic dependency for offshore project developers.
- Hydrogen embrittlement susceptibility:High-strength grades above 1,200 MPa face performance degradation in cathodic protection zones, limiting material selection.
Strategic Opportunities
- Floating offshore wind platforms:Dynamic mooring systems require fatigue-resistant fastening hardware with motion-compensated load distribution.
- Blade root attachment specialization:Longer carbon fiber blades impose stricter torque specifications, creating premium tier for certified root-bolt suppliers.
- India's CEA renewable purchase obligations:State-level mandates for wind capacity are building procurement demand for ISO-certified structural bolting.
Industry Challenges
- ISO 898-1 fatigue testing backlog:Certification laboratories face 18-month queues for mechanical property validation, delaying product qualification.
- Heat treatment skill scarcity:Specialized furnace operators capable of achieving precise through-hardness in large-diameter bolts remain concentrated in mature manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Fastener Market |
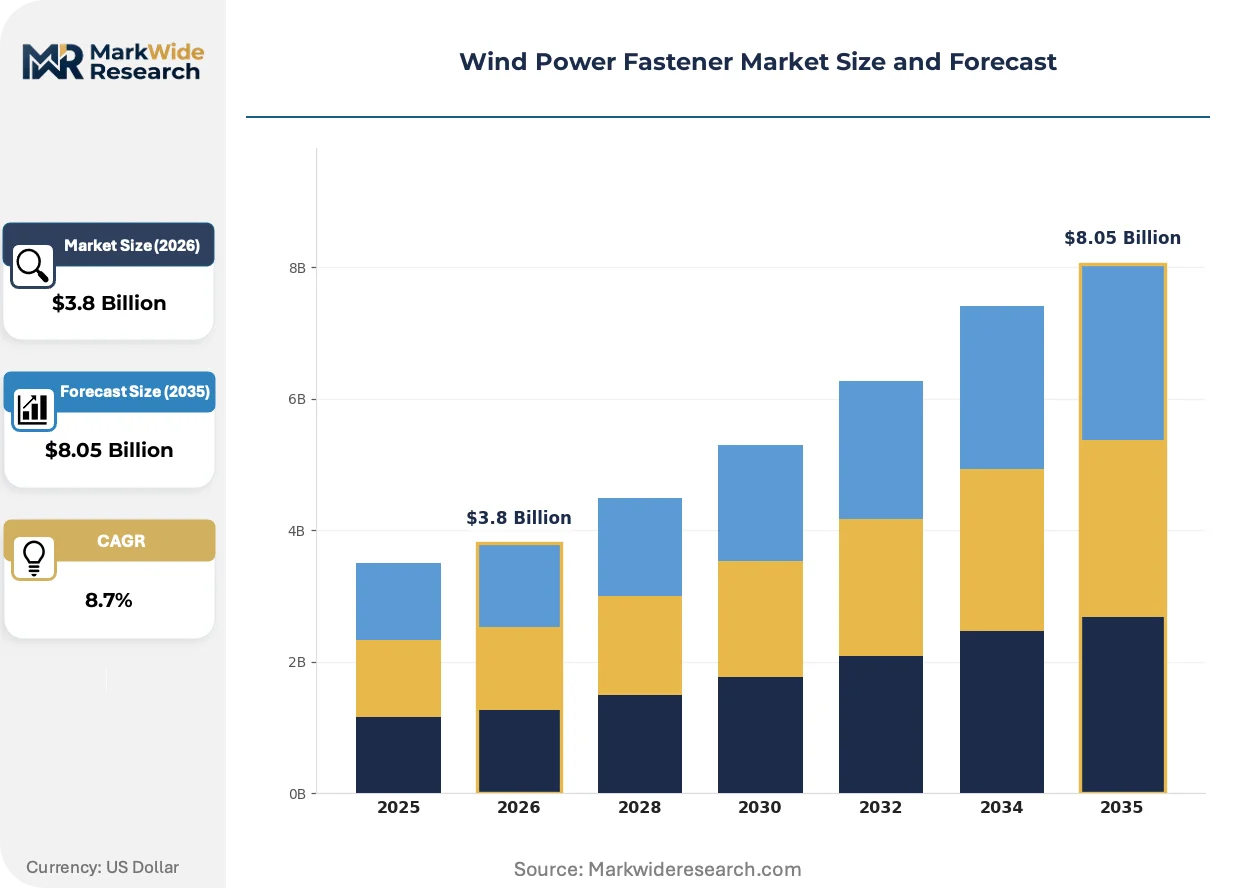
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Screws Material: Stainless Steel, Carbon Steel, Aluminum, Nylon Application: Turbine Assembly, Tower Construction, Blade Attachment, Generator Mounting End User: OEMs, Wind Farm Developers, Maintenance Services, Contractors |
| Companies Covered | Goldwind, Nordex, Siemens Gamesa Renewable Energy, Envision Energy, Mingyang Smart Energy, Vestas Wind Systems, All-Pro Fasteners, Suzlon Group, General Electric Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Fastener Market Emerging Trajectories
Fastener engineering is converging with materials science and digital traceability, reshaping how turbine OEMs specify, source, and monitor structural joining hardware across project lifecycles.
Coating technology is hybridizing as plasma-electrolytic oxidation layers combine with organic topcoats to deliver 5,000-hour salt spray resistance without hexavalent chromium. Offshore developers in Denmark and the Netherlands specify these duplex systems for monopile flange connections. The approach is compressing maintenance intervals while satisfying REACH chemical restrictions.
EU Green Deal carbon accounting rules now require documented emissions across steel melt-to-finish production. Fastener vendors serving German and French offshore auctions must submit Environmental Product Declarations verified against EN 15804. Mills in Sweden and Finland leverage hydropower-fed electric arc furnaces to meet these thresholds, securing preferential supplier status with Vestas and Siemens Gamesa.
Buyer consolidation among independent power producers is compressing vendor qualification timelines. Developers with multi-gigawatt pipelines now mandate single-source fastener agreements spanning tower, nacelle, and blade hardware. This pattern concentrates procurement leverage with tier-one suppliers capable of integrated logistics and bonded inventory programs at port-side staging yards in Qingdao and Esbjerg.
Wind Power Fastener Market Segmentation
Wind power fastener procurement varies sharply by installation phase, environmental exposure, and contracting structure. Material selection and certification grade determine supplier eligibility across offshore and onshore project tiers.
Product Type:
Cost tier determines procurement volume and margin structure, with heavy-duty flanged hardware commanding premium pricing against standardized small-diameter fasteners.
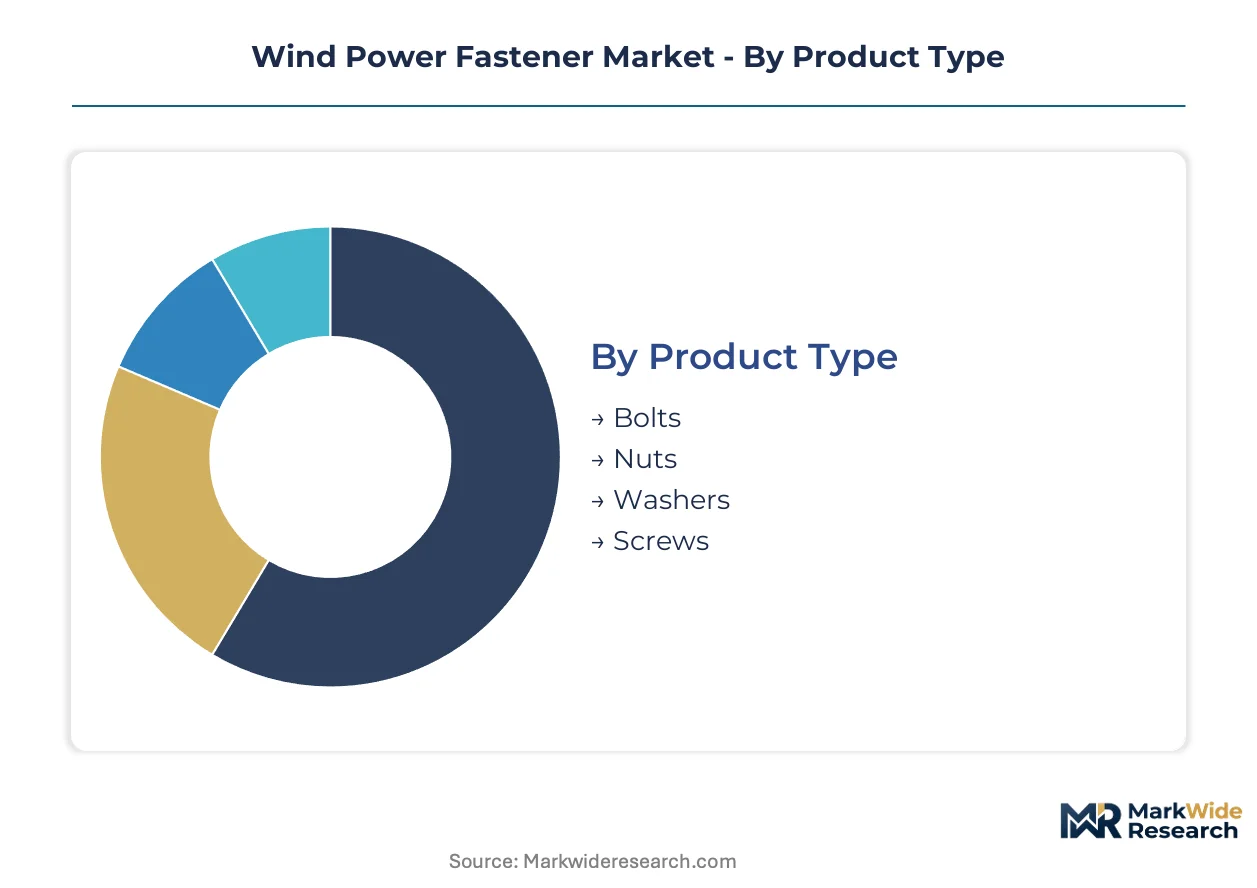
- Bolts:High-tensile alloy steel fasteners rated above 1,000 MPa dominate tower flange and nacelle frame connections. Offshore developers in Denmark specify duplex stainless grades for monopile joints exposed to North Sea salt spray.
- Nuts:Precision-forged hex and flange nuts mate with bolts in preloaded tension assemblies. Chinese tower fabricators source heavy hex patterns domestically under MIIT localization directives.
- Washers:Hardened flat and beveled washers distribute clamping loads across flange faces. Direct tension indicators are gaining specification for bolted joint verification.
- Screws:Thread-forming and machine screws secure electrical enclosures and secondary brackets. Volume concentrates in nacelle assembly lines.
Bolts hold installed capacity. Washers are rotating up the share rankings as joint integrity verification tightens.
Material:
Application severity dictates metallurgical grade, with salt exposure and cyclic loading forcing upgrades from standard carbon grades.
- Stainless Steel:Duplex and super-duplex grades deliver chloride resistance for 25-year offshore design life. Baltic Sea developers specify SAF 2507 for submerged bolting zones.
- Carbon Steel:Quenched and tempered alloy grades dominate onshore towers where atmospheric corrosion remains manageable. Surface treatments extend service intervals.
- Aluminum:Lightweight alloys reduce nacelle mass in pitch system hardware. Specialized applications in blade root adapters.
- Nylon:Insulating polymers isolate galvanic couples between dissimilar metals. Limited to electrical isolation and temporary fixturing.
Carbon Steel holds installed capacity. Stainless Steel is rotating up the share rankings.
Application:
Customer type concentration varies by project phase, with EPC contractors driving tower construction volume and OEMs controlling turbine assembly specifications.
- Turbine Assembly:Nacelle and drivetrain bolting demands precision torque control and documented preload. Vestas and Siemens Gamesa enforce vendor qualification protocols.
- Tower Construction:Tubular steel sections require circumferential flange bolting in 100+ connection points per tower. Chinese fabricators localize supply through captive fastener subsidiaries.
- Blade Attachment:Root bolt arrays transfer aerodynamic loads into the hub. Longer carbon fiber blades impose stricter fatigue specifications on threaded hardware.
- Generator Mounting:Resilient fastener systems isolate drivetrain vibration. Specialized elastomeric washers complement metallic bolting.
Tower Construction holds installed capacity. Blade Attachment is rotating up the share rankings.
End User:
Supply concentration clusters with OEMs and major developers, compressing vendor margins while extending contract duration.
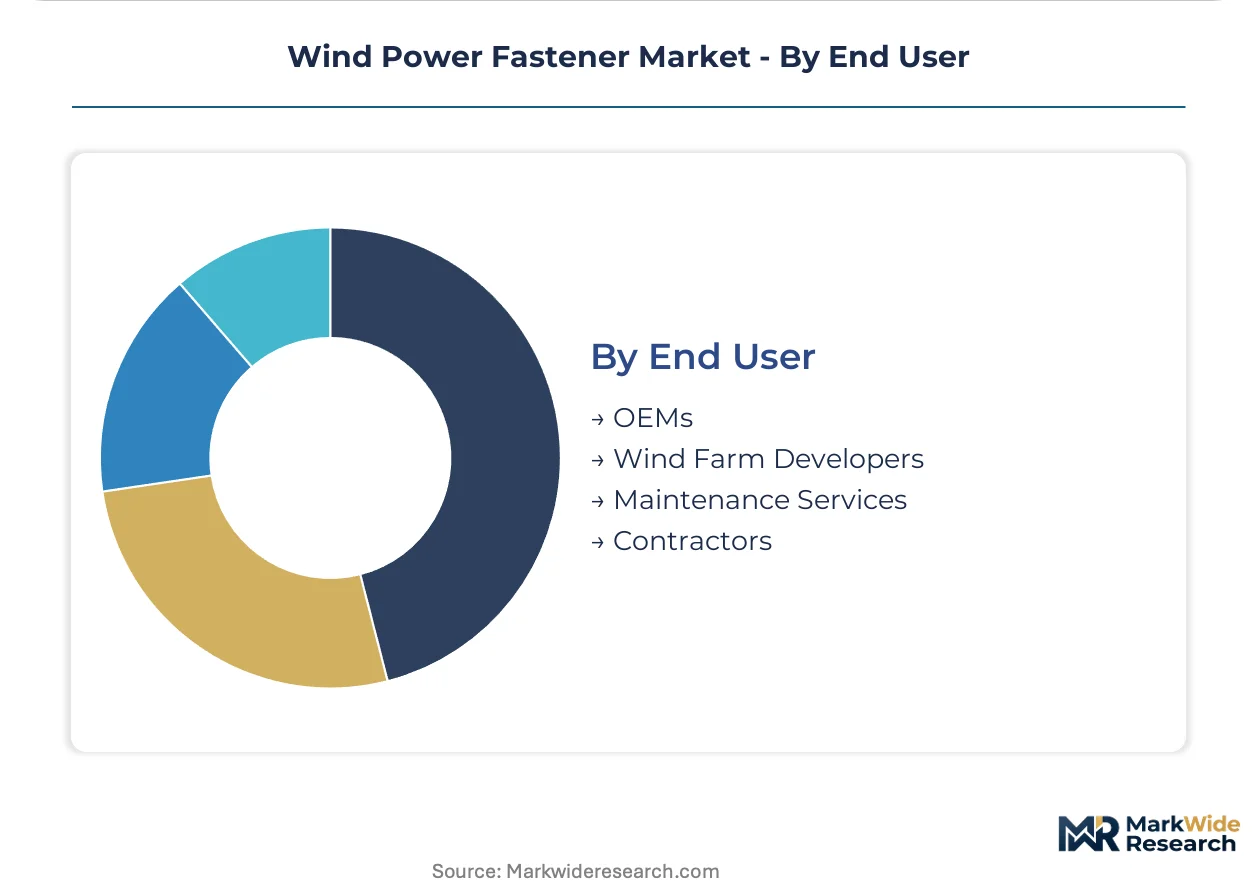
- OEMs:Turbine manufacturers specify fastener grades across platform generations. Direct sourcing agreements lock in volume with tier-one forgers.
- Wind Farm Developers:Independent power producers negotiate frame agreements covering multi-gigawatt pipelines. Procurement leverage concentrates with Danish and German utilities.
- Maintenance Services:Retrofit and replacement demand follows installed base aging. Specialized torque service providers carry bonded fastener inventory.
- Contractors:EPC firms execute civil and electrical installation with project-specific bolting packages. Local sourcing requirements vary by permitting jurisdiction.
OEMs hold installed capacity. Wind Farm Developers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fastener trade flows tilt toward import dependency in offshore wind clusters while manufacturing capacity concentrates in steel-producing regions with forged-component expertise. Export competitiveness hinges on alloy steel pricing, certification laboratory proximity, and port logistics for tower staging.
China
Domestic OEMs and tower fabricators drive procurement volume for multi-megawatt units under MIIT localization directives. GB standards enforce domestic content ratios that redirect supply chains toward indigenous bolting manufacturers. The Yangtze River Delta cluster hosts captive fastener subsidiaries serving Goldwind and Envision Energy assembly lines.
Germany
North Sea offshore auctions generate demand for duplex stainless fasteners certified to 25-year design life. EU Green Deal embedded carbon mandates require Environmental Product Declarations verified against EN 15804. The Port of Esbjerg in neighboring Denmark serves as the staging hub for German offshore projects, concentrating bonded inventory with tier-one suppliers.
United States
Independent power producers with multi-gigawatt pipelines negotiate frame agreements spanning tower, nacelle, and blade hardware. The Inflation Reduction Act production tax credits accelerate project finance structures with long-term power purchase agreements. Gulf Coast fabrication yards in Texas and Louisiana localize supply chains for onshore utility-scale installations.
India
State-level renewable purchase obligations under CEA directives build procurement demand for ISO-certified structural bolting. Wind capacity additions concentrate in Gujarat and Tamil Nadu, where EPC contractors execute civil installation with project-specific bolting packages. Domestic tower fabricators are qualifying local fastener vendors to reduce import dependency.
Denmark
Offshore developers specify plasma-electrolytic oxidation coatings for monopile flange connections in North Sea salt spray environments. REACH chemical restrictions accelerate displacement of hexavalent chromium surface treatments. Copenhagen-based procurement teams enforce single-source fastener agreements across Vestas turbine platforms.
Wind Power Fastener Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in forged-alloy and surface-treatment niches. The vendor base separates into three strata: turbine OEMs with captive fastener specifications, certified forging houses serving offshore certification requirements, and regional distributors holding bonded inventory at port-side staging yards. Strategic moves center on backward integration into heat-treatment capacity and geographic expansion toward emerging wind markets in India and Vietnam.
Among turbine OEMs with integrated supply chain control, Vestas Wind Systems and Siemens Gamesa Renewable Energy exemplify the platform-dominant archetype, while Goldwind occupies a parallel position within China's domestic market structure. These entities anchor procurement leverage through direct vendor qualification protocols and multi-year volume commitments.
| Leading Market Players |
|---|
| Goldwind |
| Nordex |
| Siemens Gamesa Renewable Energy |
| Envision Energy |
| Mingyang Smart Energy |
| Vestas Wind Systems |
| All-Pro Fasteners |
| Suzlon Group |
| General Electric Renewable Energy |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese fastener forging capacity is compressing export pricing for carbon steel tower bolts while tightening margins for European duplex stainless suppliers serving North Sea offshore clusters. This utilization asymmetry between regions is forcing procurement managers to rebalance supplier portfolios across certification tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume across multi-gigawatt turbine platforms. Price differentiation hinges on ISO 898-1 fatigue certification grade and embedded carbon documentation under EU Green Deal mandates. Cost compression in carbon steel bolting is intensifying because Chinese MIIT localization directives have expanded domestic forging capacity. Independent power producers with frame agreements show lowest price sensitivity, while EPC contractors executing single projects exhibit highest sensitivity to spot alloy steel movements.
Supply Chain Analysis
Alloy steel feedstock draws from electric arc furnace mills in Sweden, Germany, and China, with nickel and molybdenum alloying elements sourced from mining operations in Indonesia and Chile. Raw material dependencies center on high-purity scrap metal, specialized quenching oils, and plasma-electrolytic oxidation coating chemicals. Single-source vulnerability concentrates in certified heat treatment furnaces located in Germany and Scandinavia. Distribution runs through bonded inventory programs at port-side staging yards in Esbjerg, Qingdao, and Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind power fastener procurement is evolving into a service-attach opportunity as torque verification and preload monitoring contracts expand faster than hardware shipments. Recurring-revenue layers around joint integrity assurance are capturing margin pools that hardware-only vendors cannot access.
For Market Incumbents: Entrench platform dominance by acquiring captive heat treatment capacity in Baltic coastal zones to secure 25-year certification pipelines. Lock in direct sourcing agreements with Vestas and Siemens Gamesa that bundle hardware with digital preload monitoring services. Defend against emerging Chinese fastener exporters by accelerating EN 15804 Environmental Product Declaration coverage across European mill networks. For New Entrants and Emerging Players: Pursue blade root attachment specialization where longer carbon fiber platforms impose unmet fatigue-resistance specifications on threaded hardware. India's CEA renewable purchase obligations create the most penetrable geography for ISO-certified structural bolting. Lead with torque-service bundling rather than commodity bolt pricing to bypass entrenched forging relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fastener vendors with integrated preload monitoring and bonded inventory logistics. Long-term viability favors acquisition targets possessing both EN 15804 carbon transparency and port-side staging infrastructure. The signal to watch is acceleration in floating offshore wind platform procurement, which demands fatigue-resistant hardware with motion-compensated load distribution capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Secures 25-year certification capacity for offshore duplex stainless orders. |
| Environmental Product Declaration Program | Unlocks preferential supplier status under EU Green Deal embedded carbon rules. |
| Blade Root Attachment Specialization | Captures premium tier as longer carbon fiber blades tighten fatigue specifications. |
| Port-Side Bonded Inventory Expansion | Compresses procurement cycles for independent power producers with multi-gigawatt pipelines. |
| Digital Preload Monitoring Service Launch | Converts transactional hardware sales into recurring torque verification contracts. |
Methodological Framework
Initial hypotheses were tested against primary input from turbine OEM procurement directors, EPC contractor project managers, fastener forging plant engineers, and offshore wind farm developers and refined through secondary validation against customs trade data, SEC filings from listed turbine manufacturers, IEA renewable energy reports, and FERC interconnection queues. Bottom-up volume estimates from individual project pipelines were triangulated against top-down capacity forecasts from national renewable energy auction results.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, material grade, application phase, and end-user contracting structure. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansion timelines and auction award volumes. Industry-specific forecast inputs included MIIT localization directive implementation schedules and EU Green Deal carbon accounting phase-in dates.
Macroeconomic conditions sit as an overlay; deviation in alloy steel commodity indices, offshore wind auction clearing prices, or cathodic protection zone engineering standards would shift the trajectory. Cross-checking against IEA offshore wind capacity forecasts and national renewable energy auction databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Portable Power Station Market
Power Equipment
Clean Steam Separator Market
Power Equipment
United States Power Rental Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Levant Power Cable Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Japan Power EPC Market
Power Equipment
Wind Turbine Maintenance Market