
 Thailand Power EPC Market | 2026-2036
Thailand Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Power EPC Market Analytics
Thailand's enhanced Power Development Plan is expanding the cost-of-entry calculus for foreign EPC contractors by mandating local content thresholds and technology transfer provisions. Siemens Energy AG leverages its gas turbine manufacturing footprint in Asia to sustain competitive positioning for combined cycle projects. B.Grimm Power Public Company Limited anchors its domestic market share through integrated development and operational capabilities across multiple provinces. Mitsubishi Hitachi Power Systems differentiates through advanced-class gas turbine technology leadership and long-term service agreements.
Power EPC encompasses the full-scope engineering, procurement, and construction of electricity generation infrastructure, typically involving equipment specification, civil works, installation of turbines or photovoltaic arrays, and grid interconnection systems rated from distribution-level voltages to 500 kV transmission. The primary purpose centers on delivering turnkey generation assets that meet dispatch reliability targets and environmental permits for utility and industrial offtakers. Construction services dominate value capture across the service type dimension, while solar technology within the technology segment shows the fastest growth trajectory as feed-in tariffs and corporate power purchase agreements reshape project pipelines. Mega projects command disproportionate margin pools due to complexity premiums and extended contract durations, though medium-scale distributed generation is gaining share as industrial users seek energy cost hedging.
The Energy Regulatory Commission of Thailand governs licensing and tariff structures, while the Ministry of Energy's Department of Alternative Energy Development and Efficiency administers renewable energy standards and incentive eligibility. These frameworks shape contractor qualification requirements, local partnership mandates, and technology selection criteria for grid-connected assets. Stakeholders must monitor regulatory deliberations on capacity market mechanisms and carbon pricing proposals that would alter project economics and EPC contract structuring.
Market Dynamics
Thailand's revised Power Development Plan is restructuring contractor qualification thresholds through local content mandates and technology transfer requirements that favor established regional players with existing manufacturing footprints.
Growth Catalysts
- Eastern Economic Corridor expansion:Industrial estates in Rayong, Chonburi, and Chachoengsao are commissioning captive power plants to offset grid reliability risks for petrochemical and automotive manufacturing clusters.
- Feed-in tariff revisions:The Ministry of Energy's adjusted renewable energy incentives are redirecting EPC portfolios toward solar photovoltaic and gas-fired combined cycle installations with faster permitting timelines.
- Combined cycle technology maturation:Advanced-class gas turbines with higher efficiency ratings are reducing lifecycle cost calculations for utility-scale developers evaluating baseload alternatives.
Market Restraints
- Specialized equipment import dependency:Heavy gas turbines and high-voltage transformers concentrate supply among Japanese and German original equipment manufacturers, exposing projects to currency volatility and extended lead times.
- Local content floor costs:Domestic manufacturing thresholds for steel fabrication and civil works inflate project budgets compared to regional competitors with shallower localization requirements.
- Grid interconnection queuing:The Energy Regulatory Commission's transmission upgrade backlog delays commercial operation dates for completed generation assets in the Central region.
Strategic Opportunities
- Industrial estate microgrids:Eastern seaboard manufacturing parks are soliciting distributed generation EPC contracts with islanding capability to insure against transmission instability.
- Battery energy storage integration:Hybrid solar-plus-storage configurations are opening new EPC scopes as the Department of Alternative Energy Development and Efficiency relaxes standalone storage licensing barriers.
- Long-term service agreement bundling:Contractors with operational capabilities can capture recurring revenue streams by wrapping construction contracts with multi-year operations and maintenance provisions.
Industry Challenges
- Commissioning engineer scarcity:Specialized talent for gas turbine alignment and high-voltage switching system testing commands premium wages that compress project margins.
- Environmental permit timelines:Environmental Impact Assessment approvals for coal-adjacent fuel sources extend development cycles and tie up working capital.
- Legacy grid synchronization:New generation assets must integrate with aging 115 kV and 230 kV infrastructure requiring custom protection relay configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Power EPC Market |
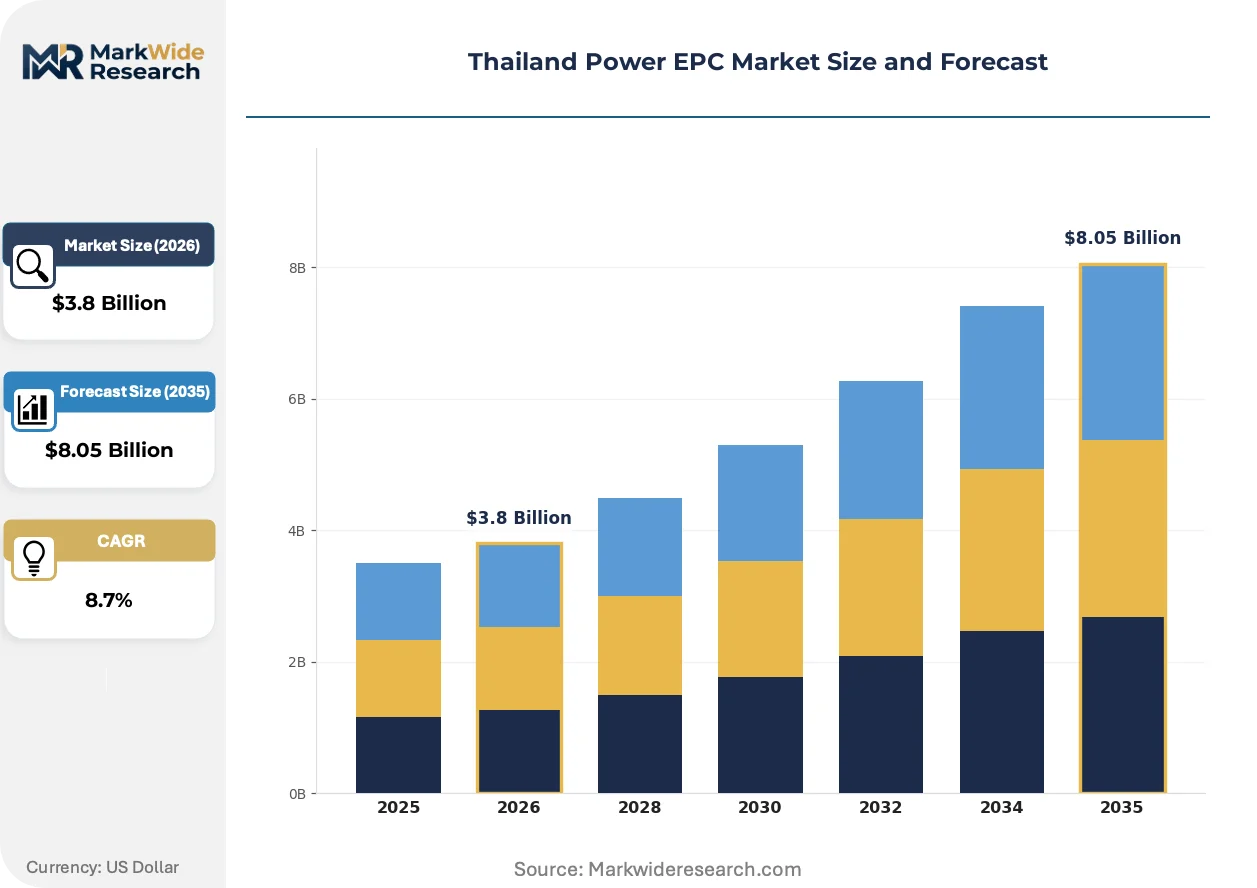
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Procurement, Project Management, Engineering End User: Utilities, Government, Industrial, Commercial Technology: Solar, Wind, Hydro, Thermal Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Black & Veatch Corporation, Siemens Energy AG, Mitsubishi Hitachi Power Systems, B.Grimm Power Public Company Limited, Thai Jurong Engineering Limited, General Electric Company, Pöyry PLC, Sino-Thai Engineering & Construction PCL, Marubeni Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Power EPC Market Evolving Landscape
Digital twin modeling and modular construction methods are compressing project delivery schedules while predictive maintenance platforms are reshaping post-construction value capture for EPC contractors.
Modular skid-mounted combined cycle packages are overtaking field-erected configurations for mid-scale industrial applications. Petrochemical developers in Map Ta Phut and Laem Chabang are specifying factory-integrated turbine and heat recovery steam generator assemblies to reduce on-site labor exposure. This standardization is compressing mechanical completion timelines and reducing weather-related construction risk.
The Energy Regulatory Commission's capacity market mechanism deliberations are forcing developers to restructure offtake agreements. Proposed availability-based payments would reward dispatchable generation over intermittent sources, altering technology selection criteria for upcoming auction rounds. Gas-fired EPC contractors are positioning advanced-class turbines to capture these reliability premiums.
Corporate power purchase agreements are displacing traditional utility-tariff contracting for industrial offtakers. Automotive assemblers in the Eastern Economic Corridor are negotiating direct renewable energy supply contracts that transfer development risk to EPC-backed project companies. This channel shift concentrates procurement authority within sustainability and treasury functions rather than plant engineering departments.
Thailand Power EPC Market Segmentation
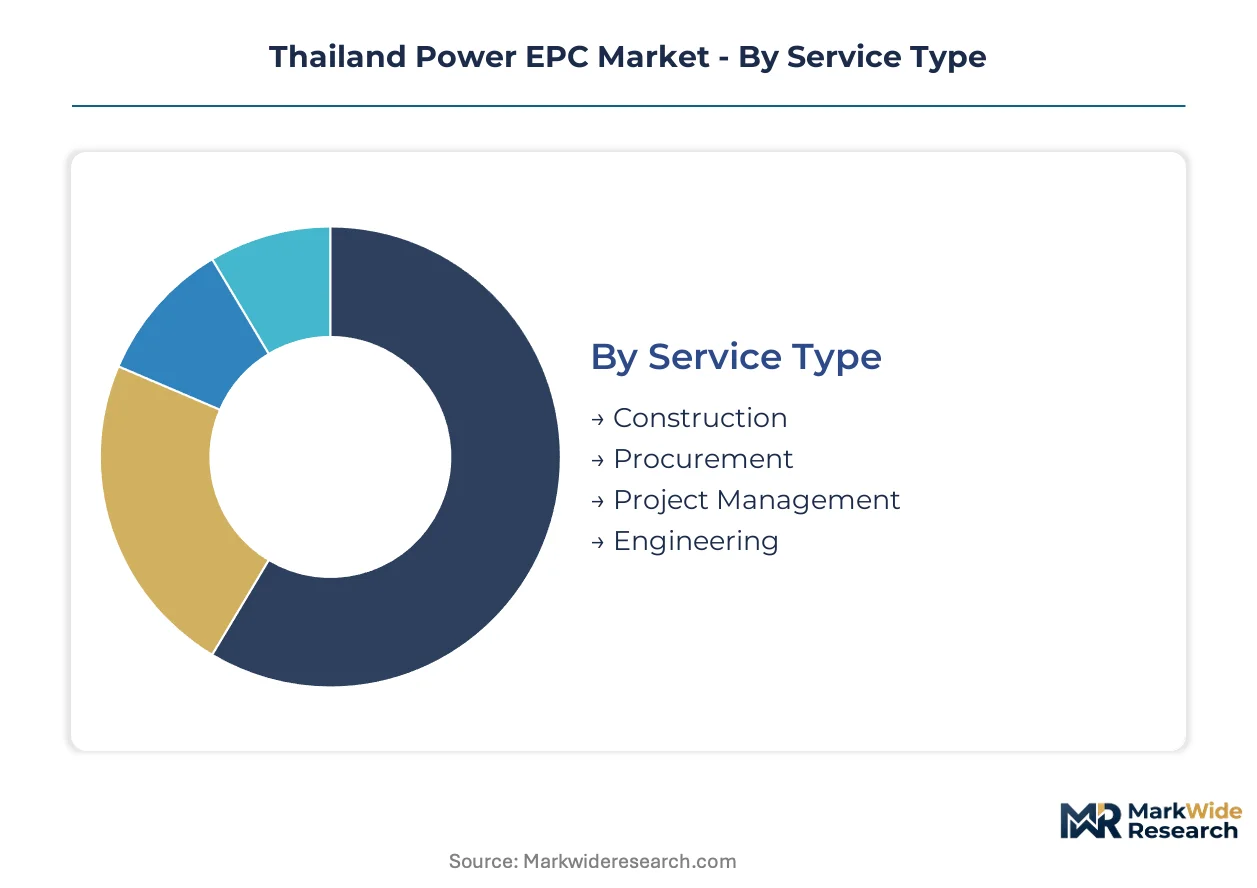
Thailand's Power EPC market segments reflect distinct procurement behaviors across utility-scale developers, industrial captives, and distributed commercial offtakers. Contractor qualification requirements and technology risk profiles vary sharply by segment, reshaping competitive positioning.
Service Type:
Contract value capture depends on scope bundling and risk transfer allocation between developer and contractor.
- Construction:Civil works, equipment installation, and mechanical completion dominate project budgets. Eastern Economic Corridor industrial estates are expanding turnkey construction contracts for captive gas-fired plants as grid reliability concerns mount.
- Procurement:Long-lead equipment specification and vendor management for gas turbines, transformers, and photovoltaic modules. Currency volatility on Japanese and German OEM imports is compressing margins for procurement-only scopes.
- Project Management:Schedule coordination across multi-contractor environments and interface risk allocation.
- Engineering:Front-end design, grid interconnection studies, and environmental permitting support.
Construction leads on scale; Procurement leads on momentum as equipment localization mandates deepen.
End User:
Offtaker creditworthiness and dispatch priority shape contract terms and technology selection.
- Utilities:State-owned generators and independent power producers procuring grid-connected baseload assets. The Electricity Generating Authority of Thailand and regional IPPs are advancing combined cycle tenders under revised Power Development Plan capacity auctions.
- Industrial:Petrochemical, automotive, and electronics manufacturers in Rayong and Chonburi seeking captive generation. Manufacturing clusters are specifying island-capable microgrids to hedge against transmission instability.
- Government:Provincial administrations and state enterprises developing distributed renewable assets.
- Commercial:Shopping centers, hospitals, and data centers procuring behind-the-meter solar installations.
Industrial offtakers are expanding most quickly; Utilities retain the deepest project pipelines.
Technology:
Permitting velocity and fuel cost trajectories are redirecting developer portfolios across generation sources.
- Solar:Ground-mount utility arrays and rooftop distributed generation with accelerating storage hybridization. Corporate power purchase agreements from Eastern Economic Corridor automotive assemblers are concentrating demand for solar-plus-battery configurations.
- Thermal:Gas-fired combined cycle and reciprocating engine plants for industrial captives and grid firming. Advanced-class gas turbines with higher efficiency ratings are reducing lifecycle cost calculations for Map Ta Phut petrochemical developers.
- Wind:Onshore installations in southern provinces with constrained transmission access.
- Hydro:Small run-of-river developments and existing asset rehabilitation.
Thermal dominates contracted capacity; Solar climbs the fastest on feed-in tariff and corporate PPA momentum.
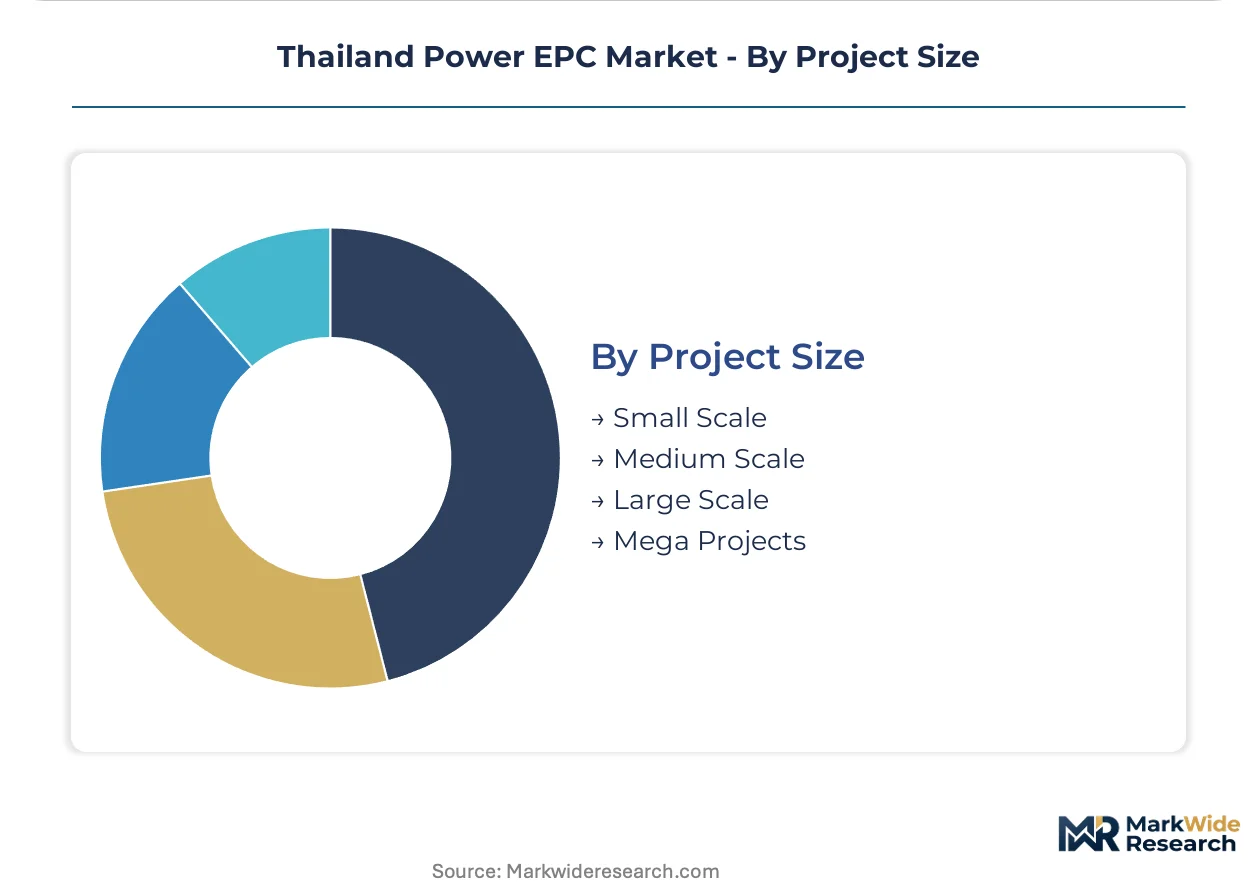
Project Size:
Capital deployment thresholds and risk concentration determine contractor specialization and margin structure.
- Mega Projects:Utility-scale combined cycle and large solar farms exceeding 500 MW requiring multi-year execution. Complexity premiums and extended contract durations attract integrated EPC consortia with balance sheet capacity.
- Large Scale:Grid-connected assets between 100-500 MW with standardized equipment packages. Regional contractors with gas turbine service experience are capturing share in this tier.
- Medium Scale:Industrial captive plants and commercial solar installations from 10-100 MW. Distributed generation is gaining share as energy cost hedging motivates direct procurement.
- Small Scale:Behind-the-meter commercial solar and rural electrification assets under 10 MW.
Mega Projects concentrate margin pools; Medium Scale is gaining share fastest on industrial estate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Bangkok and the Eastern Economic Corridor anchor Thailand's Power EPC capacity, with specialized commissioning engineers commanding premium wages across Rayong and Chonburi industrial zones.
Eastern Economic Corridor
Petrochemical and automotive manufacturing clusters in Rayong and Chonburi are expanding captive power plant procurement as grid reliability concerns mount. The Ministry of Energy's revised Power Development Plan mandates local content thresholds for contractors operating in this zone. Map Ta Phut and Laem Chabang industrial estates are specifying island-capable microgrids to insure against transmission instability.
Central Region
Utility-scale combined cycle tenders from the Electricity Generating Authority of Thailand concentrate demand in Bangkok metropolitan and surrounding provinces. The Energy Regulatory Commission governs licensing and tariff structures that shape contractor qualification requirements. Grid interconnection queuing delays commercial operation dates for completed generation assets throughout this region.
Northeastern Region
Solar photovoltaic ground-mount arrays are advancing across Khon Kaen and Udon Thani provinces under adjusted renewable energy feed-in tariffs. The Department of Alternative Energy Development and Efficiency administers incentive eligibility and licensing barriers for hybrid solar-plus-storage configurations. Provincial administrations are developing distributed renewable assets to reduce transmission dependency.
Southern Region
Onshore wind installations in Nakhon Si Thammarat and Songkhla face constrained transmission access requiring custom grid interconnection studies. The Energy Regulatory Commission's transmission upgrade backlog particularly affects commercial operation timelines in this zone. Small run-of-river hydro developments and existing asset rehabilitation projects populate the project pipeline.
Northern Region
Industrial estates in Chiang Mai and Lamphun are evaluating behind-the-meter solar installations for electronics manufacturing facilities. Corporate power purchase agreements from automotive component suppliers are transferring development risk to EPC-backed project companies. The Department of Alternative Energy Development and Efficiency's relaxed standalone storage licensing is opening new EPC scopes for battery energy storage integration.
Thailand Power EPC Market Competitive Landscape
The competitive structure tilts toward integrated regional players with established manufacturing footprints and long-term service capabilities. Market concentration favors contractors possessing both gas turbine technology access and domestic operational platforms. Three archetypes dominate: multinational OEM-backed EPC consortia, Thai-Japanese joint ventures with localized fabrication capacity, and domestic integrated developers with provincial operational reach. Competitive moves center on bundling construction contracts with multi-year operations and maintenance provisions, and securing technology transfer partnerships to satisfy local content mandates.
Within the multinational OEM tier, Siemens Energy AG and Mitsubishi Hitachi Power Systems exemplify technology-led positioning anchored by gas turbine manufacturing presence in Asia. B.Grimm Power Public Company Limited occupies a distinctive position as a domestic integrated developer with operational capabilities across multiple provinces. These three entities represent the spectrum from foreign technology access to domestic market anchoring, with each archetype responding differently to the Power Development Plan's localization requirements and the Eastern Economic Corridor's captive power demand surge.
| Leading Market Players |
|---|
| Black & Veatch Corporation |
| Siemens Energy AG |
| Mitsubishi Hitachi Power Systems |
| B.Grimm Power Public Company Limited |
| Thai Jurong Engineering Limited |
| General Electric Company |
| Pöyry PLC |
| Sino-Thai Engineering & Construction PCL |
| Marubeni Corporation |
| Others |
Value Network & Pricing Analysis
Advanced-class gas turbine efficiency premiums bifurcate contractor margins between technology-integrated consortia and procurement-only service providers, with the former capturing lifecycle value through bundled construction and long-term service agreements while the latter face compression from currency volatility on Japanese and German OEM imports.
Pricing Analysis
Bundled EPC contracts with multi-year operations and maintenance provisions command pricing premiums against unbundled construction-only scopes. Price differentiation hinges on local content compliance thresholds and technology transfer certification tiers. Cost compression in procurement-only segments is intensifying because currency exposure on heavy gas turbine imports erodes fixed-fee margins. Industrial captive offtakers in the Eastern Economic Corridor exhibit highest price sensitivity, while utility-scale developers prioritize dispatch reliability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for gas turbine refurbishment and heat recovery steam generator component remanufacturing anchor aftermarket revenue streams for established OEM-backed contractors. Heavy gas turbines and high-voltage transformers draw from concentrated manufacturing bases in Japan and Germany. Supply chain risk centers on single-source vulnerability for advanced-class turbine blade castings. Distribution runs through Bangkok-based engineering procurement centers to Rayong and Chonburi industrial estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
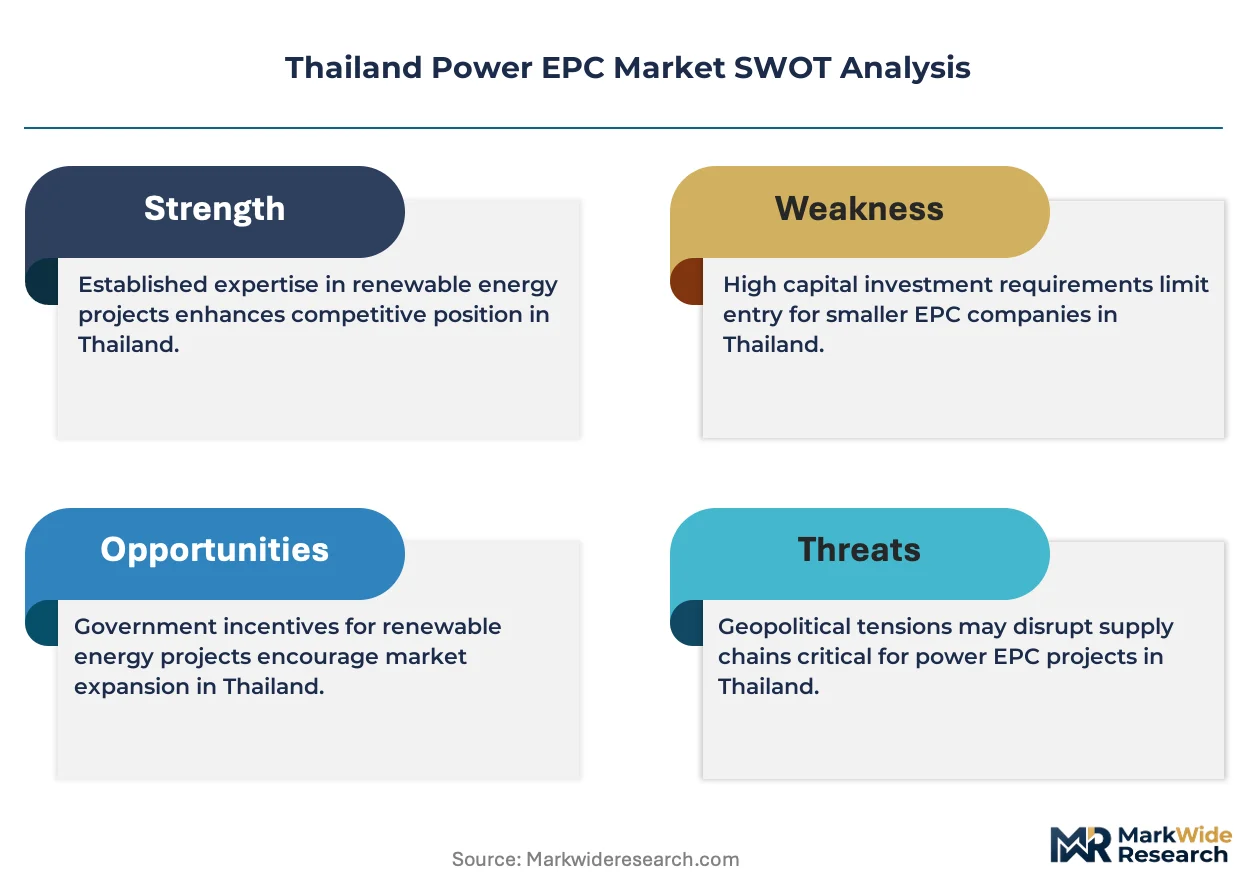
Thailand's Power EPC market represents a late-cycle quality story as Eastern Economic Corridor manufacturing clusters shift procurement criteria from lowest-bid construction toward island-capable microgrid specifications with guaranteed availability terms.
For Market Incumbents: Extend operational platform coverage across provincial industrial zones to preempt emerging Thai-Japanese joint ventures from capturing medium-scale captive plant contracts. Deepen backward integration into localized steel fabrication capacity to satisfy Power Development Plan content mandates. Anchor technology transfer partnerships with METI-registered Japanese OEMs to defend gas turbine access against Siemens Energy AG's regional manufacturing footprint. For New Entrants and Emerging Players: Enter via battery energy storage integration scopes as the Department of Alternative Energy Development and Efficiency relaxes standalone licensing barriers. Target northeastern solar-plus-storage hybrid configurations where transmission constraints create premium pricing for dispatchable renewable assets. Pursue corporate power purchase agreement origination partnerships with Eastern Economic Corridor automotive assemblers to bypass utility tariff channel congestion. For Investors and Strategic Acquirers: Consolidation pressure builds where commissioning engineer scarcity compresses project margins for mid-tier contractors lacking operational service platforms. Long-term viability favors integrated developers with provincial O&M reach and technology licensing access. Watch the Energy Regulatory Commission's capacity market mechanism deliberations as the inflection signal—availability-based payment structures would revalue dispatchable generation asset portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Secures gas turbine access for local content compliance under Power Development Plan mandates. |
| Long-term Service Agreement Bundling | Captures recurring revenue from Electricity Generating Authority of Thailand utility-scale assets. |
| Provincial O&M Platform Expansion | Builds captive customer lock-in across Rayong and Chonburi industrial estate clusters. |
| Battery Storage Integration Capability | Opens hybrid solar-plus-storage scopes as Department of Alternative Energy Development and Efficiency relaxes licensing. |
| Local Content Manufacturing Investment | Satisfies Ministry of Energy thresholds for Eastern Economic Corridor project eligibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against Electricity Generating Authority of Thailand tender disclosures, Energy Regulatory Commission licensing records, and Ministry of Energy policy circulars. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic demand modeling.
Comparable-period anchoring established historical reference baselines across the projection horizon, with analytical frameworks segmenting by fuel source, generation capacity tier, project scale, and regional grid type. CAGRs were derived from trend extrapolation calibrated to announced Power Development Plan capacity auction schedules and feed-in tariff revision timelines.
Inputs from regulatory filings and project development databases were available through the study window; gaps in proprietary EPC contract margin disclosures introduce uncertainty bands around competitive positioning assessments. Practitioners should monitor Energy Regulatory Commission capacity market mechanism deliberations and carbon pricing proposals for early signals of technology selection priority shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Europe Power Rental Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Portable Power Station Market
Power Equipment
Air Preheater Market
Power Equipment
Levant Power Cable Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Process Air Heater Market
Power Equipment
Brazil Power EPC Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Global Power Supply Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
France Power EPC Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Power Equipment Testing Market