
 Asia-Pacific Thermal Energy Storage Market | 2026-2036
Asia-Pacific Thermal Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermal Energy Storage Market Analytics
Software-defined thermal dispatch is consolidating how storage assets monetize flexibility across Asia-Pacific grids. Trane Technologies leverages its building automation stack to integrate ice storage with real-time utility pricing in Japanese commercial towers. Abengoa SA anchors its position through concentrated solar power molten salt expertise transferred to Chinese joint ventures. EnergyNest competes with modular concrete-based sensible heat blocks designed for industrial steam buffering in South Korean petrochemical complexes.
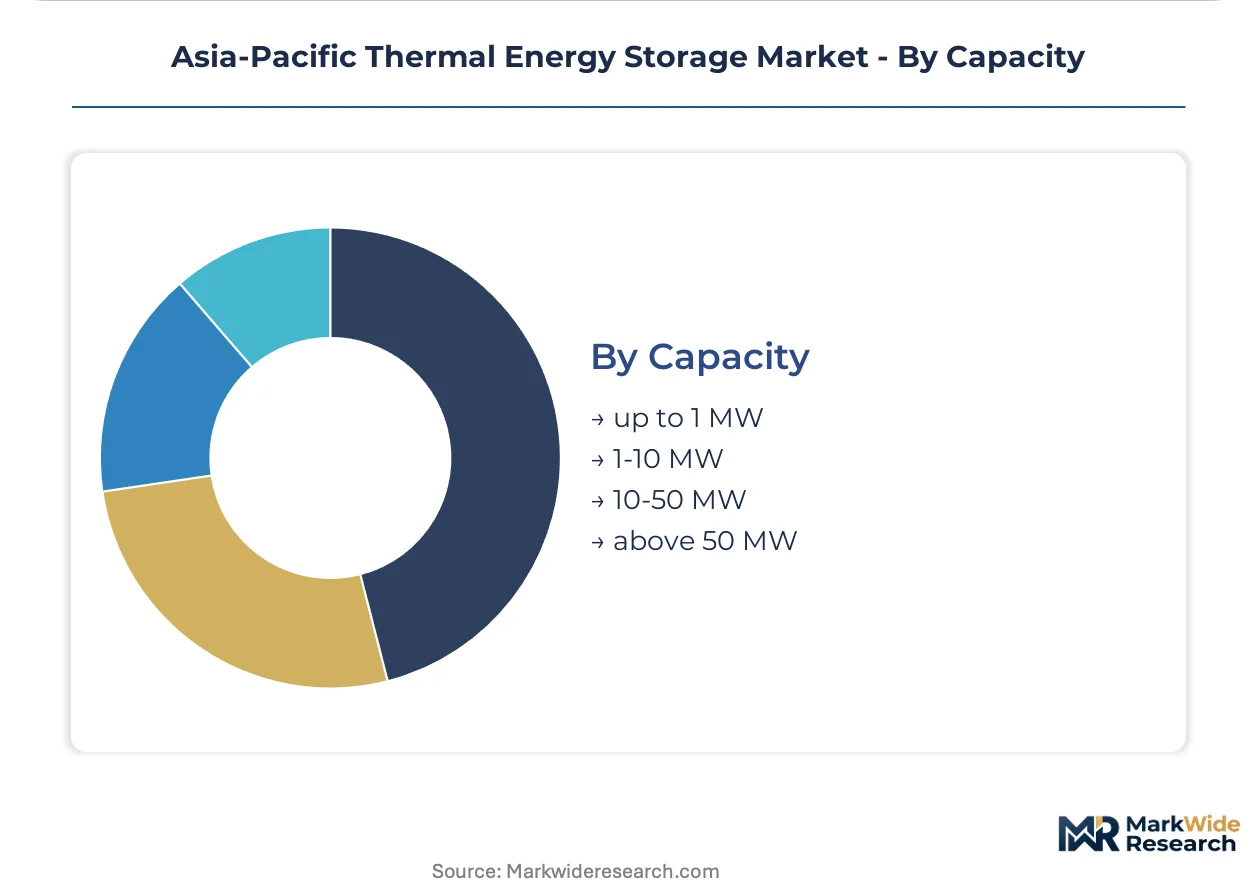
Asia-Pacific Thermal Energy Storage encompasses systems that capture thermal energy in materials such as molten salts, phase change media, or pressurized water for later discharge, typically operating between 150°C and 565°C in commercial configurations. These systems primarily enable renewable energy integration and peak shaving for district heating networks and industrial process heat. Sensible heat storage dominates installed capacity due to lower material costs and mature tank engineering, while phase change materials represent the fastest-expanding segment as Chinese manufacturers refine paraffin and salt hydrate encapsulation for building HVAC applications. The 10-50 MW capacity bracket captures the strongest margin pool, serving utility-scale renewable pairing where engineering complexity deters commoditized competition.
China's MIIT enforces industrial energy intensity standards that mandate waste heat recovery in steel and cement plants, directly expanding molten salt storage procurement. Japan's METI supports thermal battery demonstrations through green innovation funding, while South Korea's KEMCO building codes now require thermal storage in large commercial developments above specified floor areas. Stakeholders must monitor how China's SAMR standardization of thermochemical storage safety protocols reshapes technology licensing requirements across the region.
Market Dynamics
China's MIIT energy intensity mandates are forcing steel and cement plants to deploy molten salt storage for waste heat recovery, compressing deployment timelines across eastern China's industrial corridor while reshaping vendor qualification requirements.
Growth Catalysts
- Molten salt integration:District heating networks in South Korea and Japan are expanding procurement of salt-based systems for peak shaving and renewable pairing.
- MIIT mandates:China's industrial energy efficiency standards mandate waste heat recovery in heavy industry, directly expanding thermochemical storage R&D budgets.
- KEMCO building codes:South Korea now requires thermal storage installations in commercial developments above specified floor areas.
Market Restraints
- Input cost volatility:Nitrate salt prices fluctuate with fertilizer market cycles, squeezing margins for molten salt tank fabricators.
- Technical limitation:Phase change materials above 300°C suffer from thermal cycling degradation, limiting deployment in high-temperature industrial process heat.
- Regulatory friction:China's SAMR has yet to finalize thermochemical storage safety protocols, freezing licensing timelines for novel reactor designs.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian industrial zones in Vietnam and Indonesia lack district heating infrastructure but present greenfield opportunities for distributed ice storage in food processing.
- Technology convergence:Integration of building automation stacks with ice-based HVAC systems is opening real-time utility pricing arbitrage in Japanese commercial towers.
- Regulatory tailwind:Japan's METI green innovation funding supports thermal battery demonstrations, subsidizing pilot deployments in prefectural smart city programs.
Industry Challenges
- Skill gap:Molten salt system engineering requires heat transfer fluid specialists scarce across Asia-Pacific engineering consultancies.
- Capex intensity:Large-scale sensible heat tanks for steel plant integration demand 10-15 year payback horizons, straining industrial balance sheets.
- Standardization delays:Absence of unified JIS-GB interface standards complicates cross-border equipment sourcing between Japan and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermal Energy Storage Market |
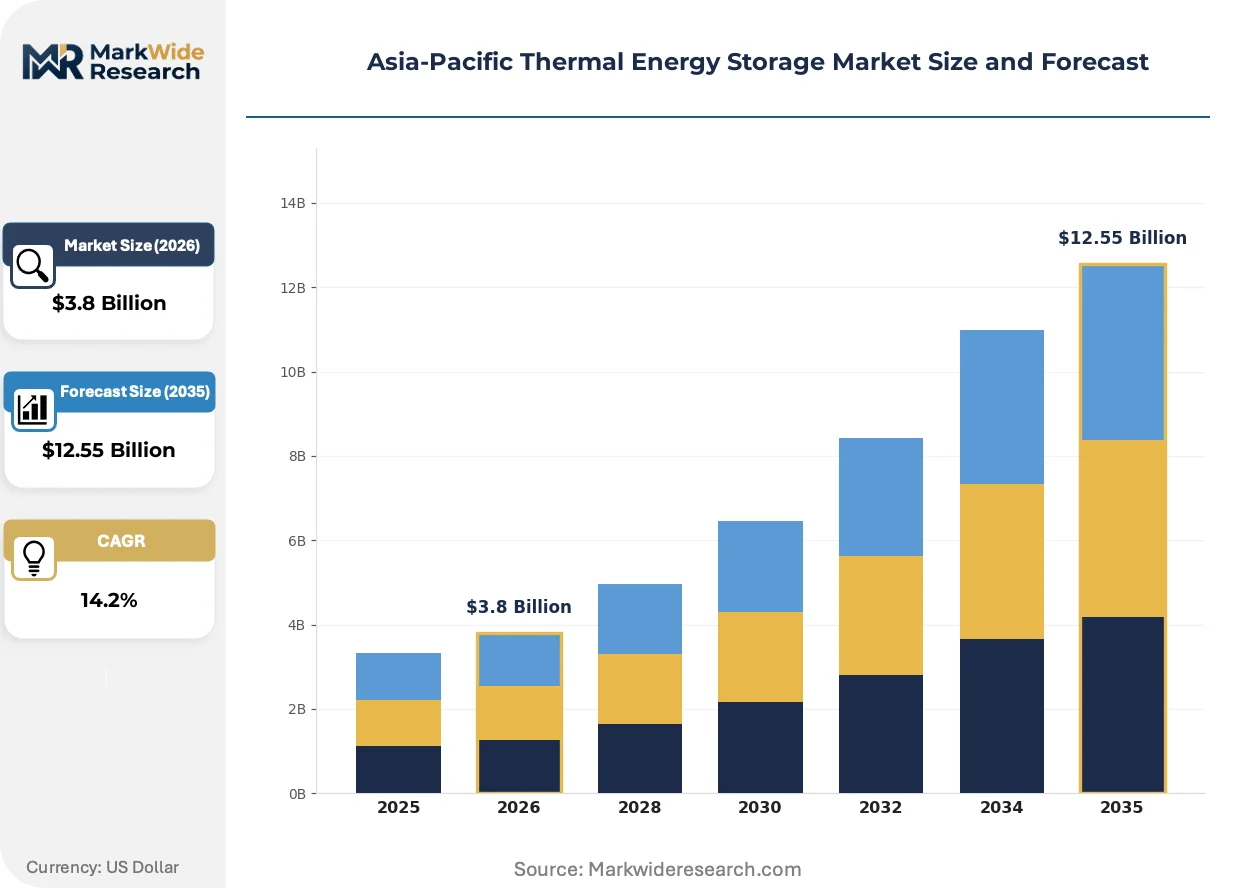
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: sensible heat storage, latent heat storage, thermochemical storage, phase change materials End User: commercial buildings, industrial facilities, district heating, utility companies Application: renewable energy integration, peak shaving, load shifting, uninterrupted power supply Capacity: up to 1 MW, 1-10 MW, 10-50 MW, above 50 MW |
| Companies Covered | Trane Technologies, Burns & McDonnell Consultants Inc, Baltimore Aircoil Co, Acciona SA, Abengoa SA, EVAPCO Inc, MAN Energy Solutions SE, EnergyNest, Sunamp Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermal Energy Storage Market Evolving Landscape
Software-defined dispatch architectures are compressing how thermal storage assets monetize grid flexibility, with automation layers now determining competitive positioning more than hardware specifications alone.
Modular concrete-based sensible heat blocks are consolidating industrial steam buffering applications. South Korean petrochemical complexes are adopting these systems for batch process thermal management. The technology is consolidating vendor margins by reducing on-site welding requirements and enabling factory-quality control.
China's dual carbon goals and MIIT efficiency mandates are accelerating thermochemical storage R&D. Steel plants in Hebei province must recover waste heat or face production quotas. Equipment suppliers are responding with salt-hydrate reactor designs tailored to blast furnace off-gas temperatures.
Japanese commercial real estate buyers now prioritize ice storage systems with real-time utility pricing integration. Building operators in Tokyo and Osaka are displacing conventional chiller-only HVAC with hybrid configurations. This preference shift is most visible in Class A office towers seeking green building certifications under CASBEE standards.
Asia-Pacific Thermal Energy Storage Market Segmentation
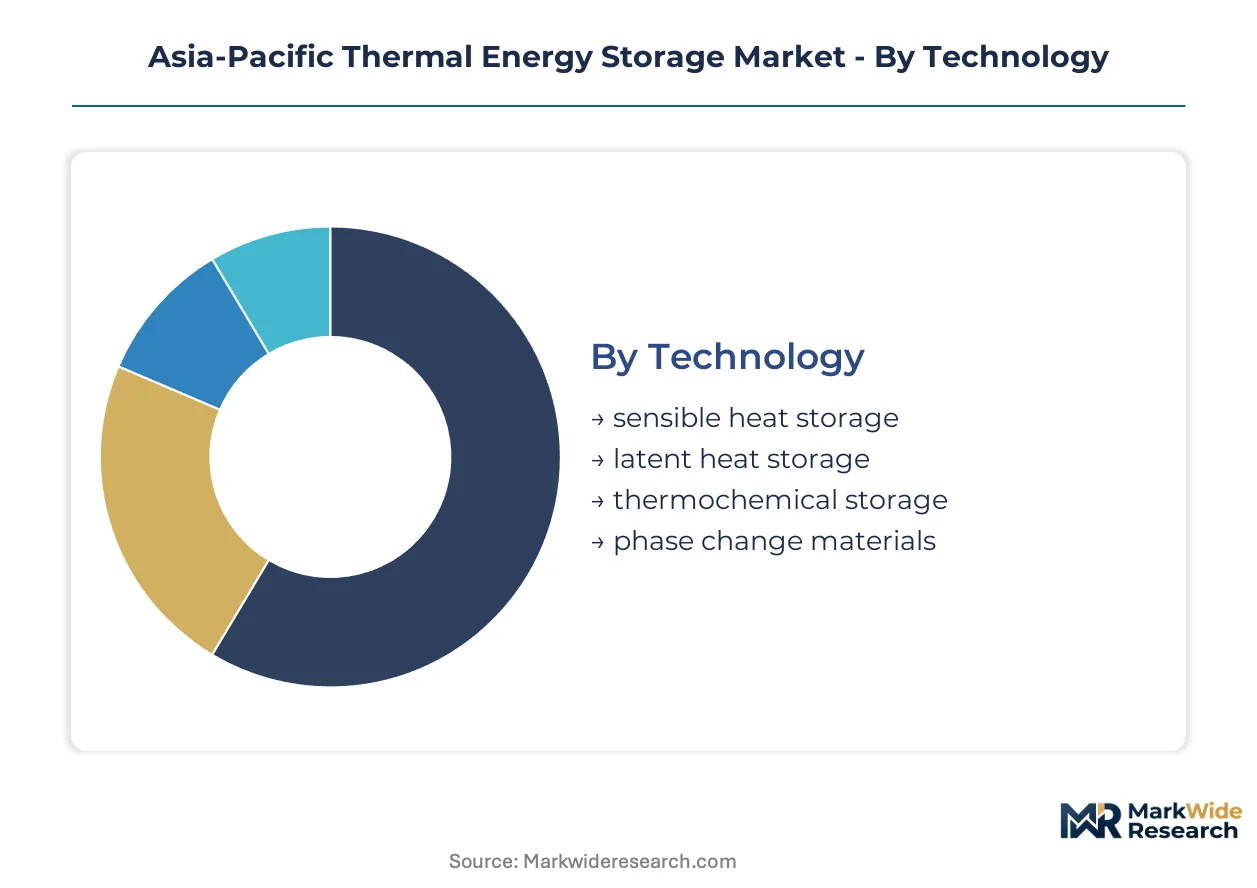
Thermal energy storage procurement patterns diverge sharply across technology maturity curves and end-use thermal profiles. Vendors must align product architectures with the specific temperature ranges, discharge durations, and automation requirements that dominate each segment.
Technology:
Supply concentration in tank fabrication and heat transfer fluid engineering favors established sensible heat systems, while emerging categories struggle with qualified installer networks.
- Sensible heat storage:Water, molten salts, or concrete store thermal energy through temperature change without phase transition. China's steel plants in Hebei province deploy large tanks for blast furnace off-gas recovery under MIIT mandates.
- Latent heat storage:Phase change materials absorb and release heat at constant temperature during solid-liquid transitions. Japanese commercial towers favor ice-based systems for HVAC load shifting under KEMCO building codes.
- Thermochemical storage:Reversible chemical reactions enable higher energy density than sensible systems. China's SAMR safety protocol delays are freezing licensing for novel reactor designs.
- Phase change materials:Encapsulated paraffin and salt hydrates target building integration. Chinese manufacturers are refining encapsulation techniques for CASBEE-certified developments.
Sensible heat storage absorbs the bulk of installed capacity; phase change materials are expanding most quickly.
End User:
Customer procurement sophistication varies from standardized building code compliance to complex industrial process integration requiring custom engineering.
- Commercial buildings:Office towers and retail complexes deploy ice storage and smaller sensible systems for HVAC optimization. Tokyo Class A properties prioritize real-time utility pricing arbitrage through building automation integration.
- Industrial facilities:Steel, cement, and chemical plants require high-temperature storage for process heat management. South Korean petrochemical complexes adopt modular concrete blocks for batch process thermal buffering.
- District heating:Centralized networks in South Korea and Japan procure molten salt systems for renewable pairing and peak shaving.
- Utility companies:Grid operators deploy large-scale storage for renewable firming and frequency regulation services.
Industrial facilities command the highest project values; commercial buildings are climbing the fastest as KEMCO and METI mandates expand addressable floor space.
Application:
Revenue concentration tracks regulatory incentive structures, with waste heat recovery mandates and renewable integration targets directing procurement flows.
- Renewable energy integration:Storage pairs with solar thermal and CSP plants to dispatch heat when irradiance is unavailable. Chinese joint ventures leverage transferred molten salt expertise for concentrated solar power projects.
- Peak shaving:Thermal storage displaces peak electricity demand for cooling or heating. Japanese commercial towers use ice storage to reduce afternoon grid strain during summer demand spikes.
- Load shifting:Time-of-use arbitrage moves thermal energy consumption to off-peak rate periods.
- Uninterrupted power supply:Critical facilities maintain thermal services during grid outages through stored energy discharge.
Renewable energy integration captures the largest project pipeline; peak shaving is gaining share fastest as real-time pricing spreads across Japanese and South Korean grids.
Capacity:
Engineering complexity and margin structures stratify sharply across size brackets, with mid-scale systems avoiding both commoditized small-unit competition and extended payback periods of gigawatt-hour projects.
- Up to 1 MW:Distributed systems serve individual commercial buildings and small industrial processes. Standardized units from Chinese manufacturers dominate this price-sensitive bracket.
- 1-10 MW:Campus-scale and medium industrial applications require semi-custom engineering. South Korean petrochemical facilities populate this range with modular concrete block installations.
- 10-50 MW:Utility-scale renewable pairing and large district heating networks concentrate procurement. Engineering complexity deters commoditized competition, preserving vendor margins.
- Above 50 MW:Gigawatt-hour sensible heat tanks for steel plant integration demand decade-plus payback horizons. China's eastern industrial corridor hosts these capital-intensive deployments.
The 10-50 MW bracket commands the strongest margin pool; above 50 MW projects are climbing the fastest as MIIT waste heat mandates force steel sector compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of molten salt storage tanks and heat transfer fluids consumed across Asia-Pacific, while Japan and South Korea absorb premium-priced systems for district heating and commercial building integration.
China
Steel plants in Hebei province deploy gigawatt-hour sensible heat tanks to comply with MIIT waste heat recovery mandates. SAMR's pending thermochemical storage safety protocols are freezing licensing timelines for novel reactor designs. The Yangtze River Delta hosts concentrated manufacturing of phase change material encapsulation for building HVAC applications.
Japan
Tokyo Class A office towers prioritize ice storage systems with real-time utility pricing arbitrage through building automation integration. METI green innovation funding subsidizes thermal battery demonstrations in prefectural smart city programs. The Kansai region around Osaka exhibits strongest commercial deployment as CASBEE certification requirements tighten.
South Korea
Petrochemical complexes in the Busan-Ulsan corridor adopt modular concrete-based sensible heat blocks for batch process thermal management. KEMCO building codes now mandate thermal storage installations in commercial developments above specified floor areas. Seoul Capital Area concentrates district heating network procurement of molten salt systems for peak shaving.
Australia
Remote mining operations in Western Australia pilot concentrated solar power with molten salt storage for diesel displacement. The national renewable energy agency supports feasibility studies for industrial process heat applications. Queensland's sugar processing facilities represent emerging demand for distributed ice storage in food processing.
Vietnam
Industrial zones in northern provinces lack district heating infrastructure but present greenfield opportunities for distributed thermal storage. Foreign equipment suppliers establish local assembly partnerships to serve food processing and textile manufacturing. Ho Chi Minh City periphery hosts early commercial building deployments as electricity tariffs introduce time-of-use structures.
Asia-Pacific Thermal Energy Storage Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific thermal energy storage landscape. Tank fabricators and molten salt suppliers dominate project economics through material sourcing control, while system integrators capture margins through software-defined dispatch architectures. Three archetypes prevail: integrated industrial conglomerates with captive heat transfer fluid production; specialized storage technology developers licensing reactor designs; and building automation vendors extending HVAC stacks into thermal storage control. Capacity expansion and strategic technology licensing represent the dominant competitive moves as vendors position for MIIT-mandated industrial deployments.
Among European-Spanish specialists, Abengoa SA and Acciona SA occupy positions anchored in concentrated solar power molten salt expertise transferred to Chinese joint ventures. Trane Technologies exemplifies the building automation extension archetype, leveraging its control systems footprint in Japanese commercial towers. EnergyNest represents the modular industrial storage tier with concrete-based sensible heat block designs. These three entities illustrate how geographic origin and legacy capability domains stratify competitive positioning across technology segments.
| Leading Market Players |
|---|
| Trane Technologies |
| Burns & McDonnell Consultants Inc |
| Baltimore Aircoil Co |
| Acciona SA |
| Abengoa SA |
| EVAPCO Inc |
| MAN Energy Solutions SE |
| EnergyNest |
| Sunamp Ltd |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between MIIT-mandated industrial systems and KEMCO-compliant commercial installations manifests in both pricing premiums and supply chain sourcing strategies across Asia-Pacific. Premium-tier molten salt tanks for steel plant integration command engineering-qualified fabricator premiums, while commodity-grade ice storage units for building HVAC flow through standardized Chinese manufacturing channels.
Pricing Analysis
Margin tightening in commercial building systems reflects nitrate salt price volatility tracking fertilizer market cycles. Project-based long-term contracting dominates industrial procurement, with price differentiation anchored in heat transfer fluid certification grade and on-site welding complexity. Cost-down pressure on sub-1 MW distributed units accelerates as Chinese manufacturers scale encapsulation techniques. District heating networks exhibit lowest price sensitivity due to renewable pairing mandates; food processing buyers in Southeast Asia show highest elasticity.
Supply Chain Analysis
Direct-to-industrial-plant channels handle hyperscale steel sector demand, while distribution runs through building automation integrators for commercial HVAC applications. Supply concentrates in China's Yangtze River Delta for tank fabrication and Hebei province for heat transfer fluid production, with South Korean petrochemical complexes drawing from domestic modular concrete block specialists. Raw material dependencies rest on Chilean nitrate salts, Australian concrete aggregates, and Japanese heat transfer fluid formulations. Single-source vulnerability in qualified molten salt engineering talent constrains project execution timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive heat transfer fluid production represents the decisive competitive lever as MIIT mandates compress deployment timelines and vendor qualification requirements tighten across eastern China's industrial corridor.
For Market Incumbents: Anchor market position through backward integration into nitrate salt refining and heat transfer fluid formulation to offset fertilizer market cyclicality. Defend against modular concrete block substitutes by embedding software-defined dispatch layers that automation-first competitors cannot replicate. Prioritize SAMR pre-certification engineering for thermochemical reactor designs ahead of protocol finalization. For New Entrants and Emerging Players: Australian mining diesel displacement projects present the most penetrable buyer archetype for concentrated solar power molten salt pilots, with remote operations seeking ESG-compliant baseload alternatives. Vietnamese food processing facilities in northern industrial zones offer greenfield distributed ice storage opportunities absent incumbent district heating infrastructure. Lead with local assembly partnerships rather than equipment import to circumvent tariff exposure and accelerate commissioning timelines. For Investors and Strategic Acquirers: Re-rating potential sits with building automation-thermal storage convergence plays given KEMCO mandate expansion and real-time pricing arbitrage monetization across Japanese commercial towers. Long-term viability favors asset-light system integrators over capital-heavy tank fabricators as software layers capture margin migration. Watch for SAMR thermochemical safety protocol publication as licensing inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Transfer Fluids | Captive nitrate salt supply insulates margins from fertilizer market cyclicality affecting molten salt tank fabricators. |
| Software-Defined Dispatch Layer Development | Real-time utility pricing arbitrage capabilities differentiate building automation vendors in KEMCO-mandated Japanese commercial towers. |
| Joint Venture with Chinese Steel Sector | MIIT waste heat recovery mandates in Hebei province create captive demand for gigawatt-hour sensible heat tank deployments. |
| Technology Licensing to Southeast Asian Assemblers | Local manufacturing partnerships circumvent logistics chokepoints for Vietnamese and Indonesian food processing ice storage demand. |
| Green Certification Program Alignment | CASBEE and METI green innovation funding qualification unlocks subsidized pilot deployment capital in Japanese prefectural smart city programs. |
Research Methodology
Document review covered MIIT industrial energy intensity standards, KEMCO building code amendments, METI green innovation funding disclosures, and SAMR thermochemical storage draft protocols, complemented by interviews with molten salt system engineering directors, district heating network procurement officers, building automation integration specialists, and steel plant energy managers. Secondary validation drew from China customs trade data, Japan Iron and Steel Federation production statistics, South Korean petrochemical facility EPC contractor disclosures, and IEA technology roadmaps. Bottom-up project pipeline aggregation and top-down regulatory mandate sizing were triangulated to constrain forecast variance.
Installed capacity and revenue outputs trace to segment-level modeling across technology type, end-user vertical, application purpose, and capacity tier, with cross-validation against engineering firm order backlogs and equipment manufacturer shipment disclosures. CAGRs derive from regression against historical deployment velocity and policy mandate acceleration curves. Forecast inputs incorporate MIIT compliance timeline assumptions, nitrate salt price trajectory scenarios, and qualified installer network expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR protocol finalization timing, thermochemical reactor licensing velocity, and Southeast Asian electricity tariff restructuring progress. Assumptions reflect documented regulatory commitments and disclosed project pipelines. Periodic stress-testing of base assumptions against MIIT enforcement intensity and KEMCO code expansion scope is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Thermal Recovery Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Southeast Asia Thermal Power Market